
 Global Cakes Market | 2026-2036
Global Cakes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cakes Market Analysis
Market Context
Single-serve and mini-portion bundling is recalibrating how consumers purchase cakes across retail and foodservice channels. Grupo Bimbo leverages its continental manufacturing footprint to dominate mass-market shelf-stable lines in the Americas. Yamazaki Baking anchors premium Japanese-style offerings across Asian markets. Mondelez International competes through controlled distribution in convenience and travel retail globally.
Technical Definition and Structural Segments
Cakes denote chemically leavened baked goods combining wheat or alternative flours, sweeteners, fats, and eggs, then aerated through creaming or foaming before oven setting; they serve celebratory, snacking, and dessert occasions across retail and institutional channels. Layer cake and cheesecake segments concentrate margin pools in premium gifting and foodservice dessert menus, while cupcakes sustain volume through portability and portion control appeal. Wheat flour formulations still occupy the bulk of production scale, though almond flour alternatives are gaining traction among health-conscious consumers.
Regulatory Framework
EU F-Gas Regulation and REACH compliance shape industrial bakery equipment procurement and ingredient sourcing across European production facilities. FDA nutrition labeling rules and USDA organic certification standards govern product claims and market access in the United States. Stakeholders must monitor evolving front-of-pack labeling requirements and sugar taxation regimes as these frameworks increasingly determine permissible formulations and competitive positioning.
Market Dynamics
Clean-label reformulation mandates across the European Union are compressing formulation flexibility and forcing accelerated R&D cycles in industrial cake production. Sugar reduction targets set by EFSA and corresponding front-of-pack labeling requirements in multiple jurisdictions are reshaping competitive positioning.
Growth Catalysts
- EU Sugar Reduction Targets:Mandatory reformulation timelines under the EU Farm to Fork Strategy are pulling investment into alternative sweetener systems and fiber enrichment technologies across European manufacturing facilities.
- Single-Serve Portion Bundling:Foodservice operators in the United States are adopting mini-portion formats for dessert menus, expanding addressable occasions beyond traditional celebration events.
- Almond Flour Alternatives:Health-conscious consumer segments in Germany are driving adoption of wheat-free formulations, creating premium price realization in free-from product lines.
Market Restraints
- Egg Price Volatility:Avian influenza outbreaks and feed grain cost fluctuations are destabilizing input cost structures for sponge and chiffon cake categories dependent on egg aeration.
- REACH Compliance Burden:Chemical safety documentation requirements for processing aids and emulsifiers are extending procurement timelines and narrowing supplier pools for European producers.
- Plant-Based Fat Limitations:Technical performance gaps in creaming and mouthfeel replication are constraining complete butter replacement in premium layer cake applications.
Strategic Opportunities
- Chinese Tier-2 Cities:Underpenetrated bakery retail infrastructure in Chengdu and Hangzhou offers first-mover positioning for localized premium cake formats adapted to regional taste preferences.
- USDA Organic Certification:Accelerating organic claim penetration in United States retail channels is creating margin expansion potential for certified clean-label cake lines.
- Direct-to-Consumer Subscription:Frozen cake delivery models are bypassing traditional retail slotting constraints and capturing recurring revenue in United Kingdom metropolitan markets.
Industry Challenges
- Artisan Skill Scarcity:Industrial bakeries face recruitment gaps in laminated dough and decorative finishing expertise as experienced craftspeople exit the workforce without pipeline replacement.
- Legacy Equipment Retrofit Costs:Depositor and oven control system upgrades required for allergen segregation and clean-in-place protocols are compressing capital deployment flexibility at mid-scale facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cakes Market |
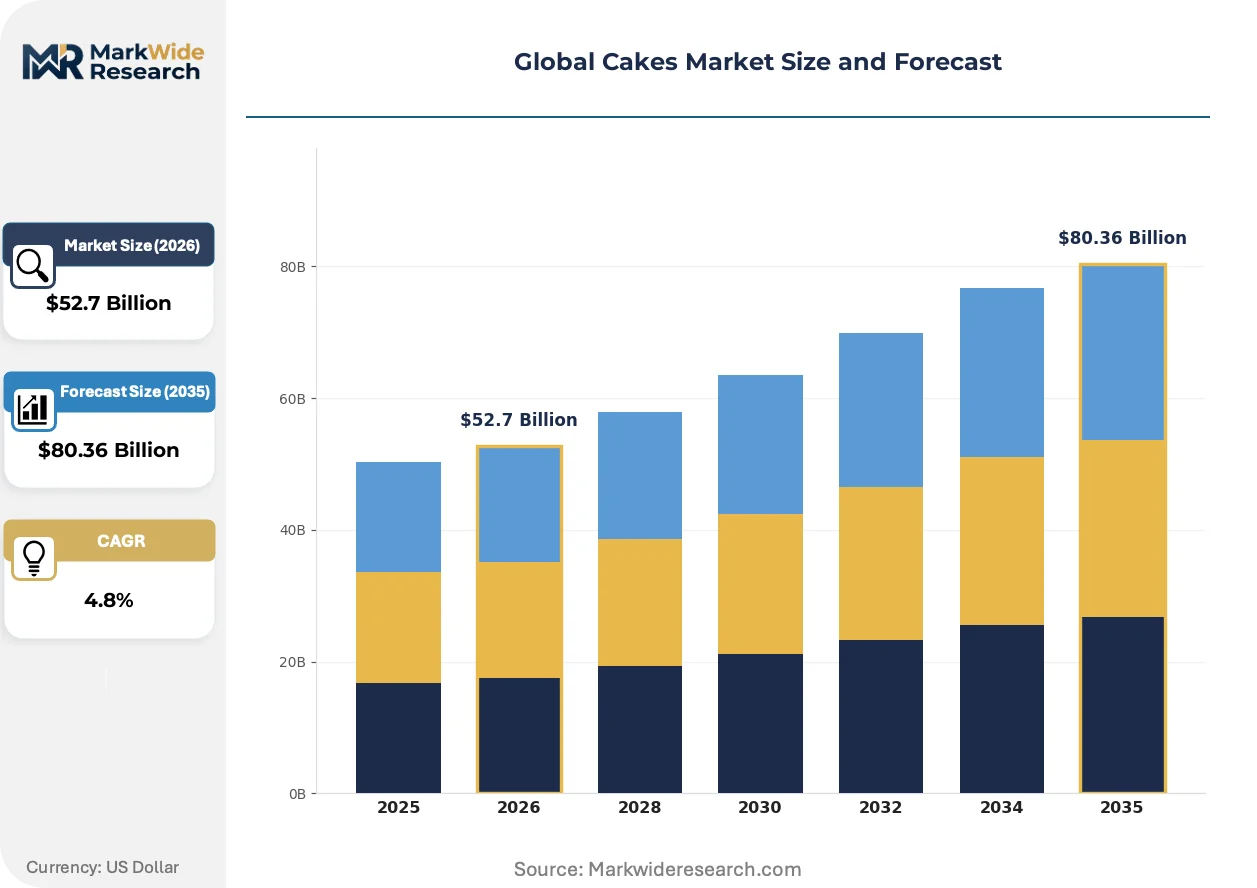
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Layer Cake, Cupcake, Pound Cake, Cheesecake Ingredient Type: Wheat Flour, Almond Flour, Cocoa Powder, Sugar Distribution Channel: Online Retail, Supermarket, Bakery Shop, Foodservice Customer Segment: Children, Adults, Health-conscious Consumers, Occasional Buyers |
| Companies Covered | Grupo Bimbo, Mondelez International, McKee Foods, Hostess Brands, Yamazaki Baking, Finsbury Food Group, General Mills, Britannia Industries, Campbell Soup Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cakes Market Emerging Trajectories
Digital manufacturing integration and alternative protein formulation are converging to compress production cycle times while expanding permissible ingredient palettes. These shifts are redrawing technical capability requirements across the value chain.
Vision-guided robotic decorating systems are automating intricate finishing operations previously requiring manual artistry. Large-scale industrial bakeries in Germany are deploying these systems for consistent lace-pattern execution on celebration cakes. This technology is automating quality standardization while reducing labor dependency in high-mix production environments.
EFSA's evolving guidance on novel food ingredients is accelerating approval pathways for cultivated egg proteins and precision-fermented dairy alternatives. European manufacturers are reformulating classic recipes around these inputs to preempt supply volatility. Cheesecake and mousse cake segments are most affected, with pilot lines already operational in Netherlands and Denmark facilities.
Buyers in United States foodservice channels are consolidating procurement around approved supplier lists with verified sustainability credentials. Distributor intermediaries are losing volume to direct manufacturer relationships as institutional buyers demand chain-of-custody documentation. This pattern is most visible in K-12 and healthcare feeding segments where federal nutrition compliance requirements intersect with ESG reporting obligations.
Global Cakes Market Segmentation
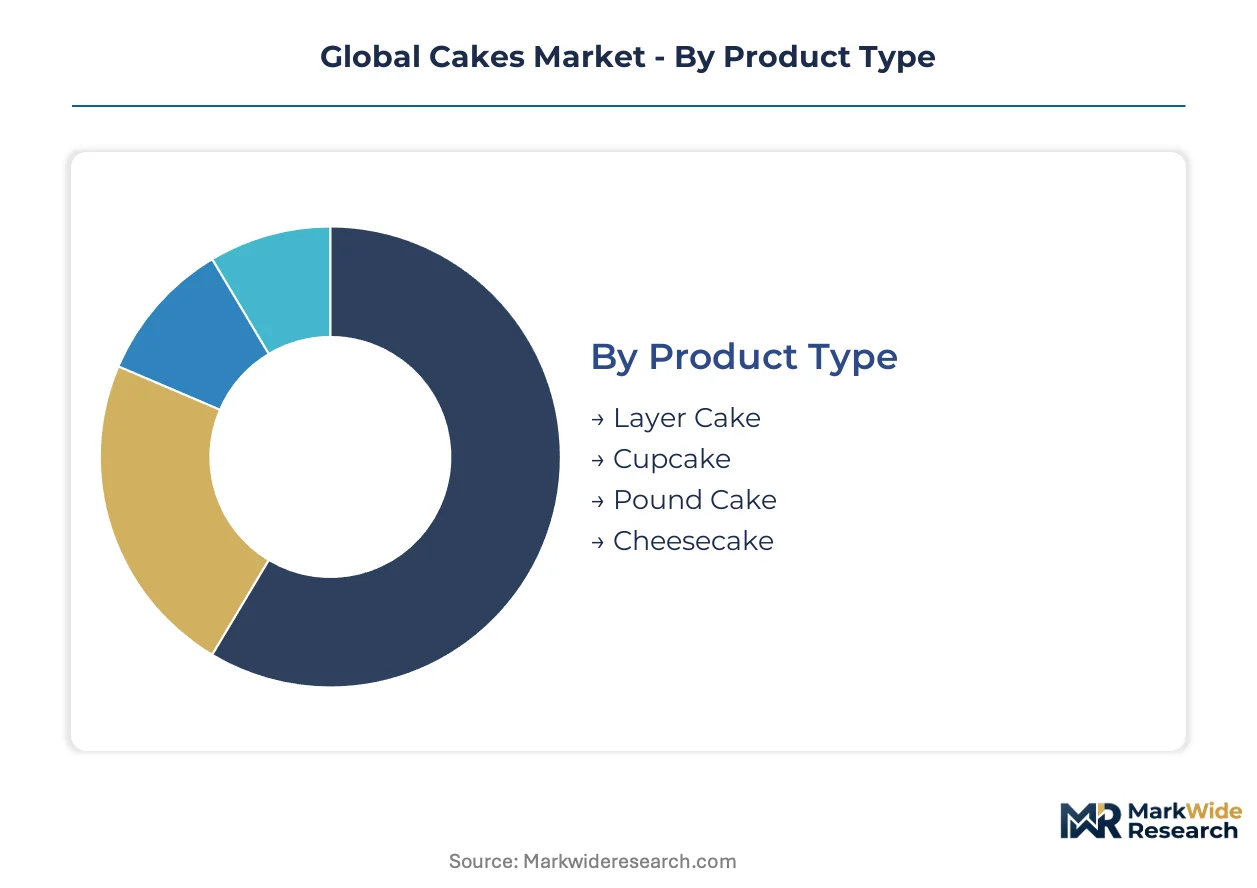
Cake manufacturers configure product portfolios across four intersecting dimensions that determine pricing power and channel access. Technical specifications in ingredient and format choices now drive margin differentiation more than traditional brand equity.
Product Type:
Structural format determines aeration method, shelf stability, and occasion targeting across retail and foodservice deployment.
- Layer Cake:Multi-tiered constructions with buttercream or fondant finishes dominate premium gifting and wedding catering segments. United States foodservice channels concentrate demand for customized celebration formats with extended lead times.
- Cheesecake:Dense, unbaked or baked curd formulations command refrigerated distribution infrastructure. German retail channels show accelerating preference for portion-controlled mini-cheesecakes in convenience formats.
- Cupcake:Individual-portion cakes with decorative frosting sustain volume through grab-and-go retail placement and school catering contracts.
- Pound Cake:Butter-dense, close-grained traditional recipes serve coffee accompaniment occasions and private-label retail lines with extended ambient shelf life.
Mature deployment sits with Pound Cake in mass-market retail. Newer deployment is concentrated in Cheesecake for premium convenience channels.
Ingredient Type:
Raw material specifications now determine clean-label positioning and regulatory compliance pathways across manufacturing geographies.
- Wheat Flour:Standard protein content hard wheat formulations still anchor industrial scale production for cost-sensitive retail tiers. China and United States milling infrastructure supports continental supply security for this base ingredient.
- Almond Flour:Blanched and unblanched nut meal alternatives enable gluten-free and low-carbohydrate claims. German health-conscious consumer segments drive premium price realization despite input cost volatility.
- Cocoa Powder:Natural and alkalized chocolate bases define indulgence positioning in dessert cake categories.
- Sugar:Sucrose and alternative sweetener systems face reformulation pressure under EFSA reduction targets and front-of-pack labeling requirements.
Volume concentration remains with Wheat Flour for mainstream production. Margin expansion is concentrating in Almond Flour for free-from specialty lines.
Distribution Channel:
Channel selection determines temperature control requirements, shelf placement economics, and direct consumer relationship depth.
- Foodservice:Institutional and restaurant dessert menus concentrate demand for thaw-and-serve frozen formats and custom celebration cakes. United States K-12 and healthcare feeding segments consolidate procurement around approved supplier lists with verified sustainability credentials.
- Online Retail:Direct-to-consumer frozen cake delivery models bypass traditional retail slotting constraints. United Kingdom metropolitan markets show recurring revenue capture through subscription configurations.
- Supermarket:Mass-market retail shelf space competition drives private-label penetration and promotional intensity in ambient cake categories.
- Bakery Shop:Artisan and chain bakery counters sustain freshness claims through short distribution cycles and localized production.
Traditional volume flows through Supermarket. Channel investment is accelerating in Online Retail for recurring revenue models.
Customer Segment:
Demographic and behavioral targeting shapes formulation intensity, portion architecture, and marketing communication strategy.
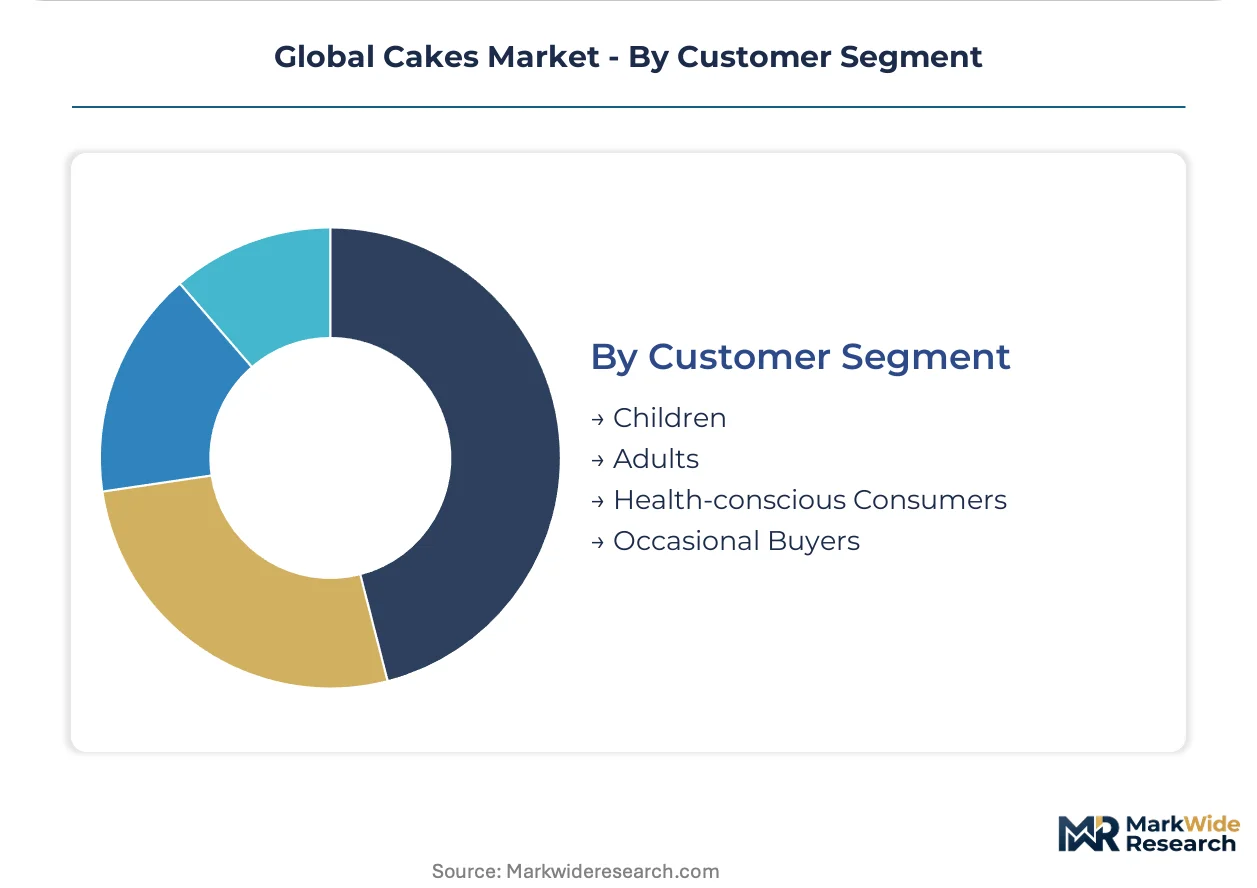
- Health-conscious Consumers:Macro-nutrient tracking and ingredient transparency demands drive reformulation toward reduced sugar, alternative flours, and clean-label emulsifier systems. EFSA guidance on novel ingredients accelerates approval pathways for fiber enrichment technologies targeting this segment.
- Adults:Gifting and personal indulgence occasions support premium pricing for celebration formats and portion-controlled dessert cakes.
- Children:School-compliant formulations and character-licensed decorations sustain volume in retail novelty categories.
- Occasional Buyers:Seasonal and event-driven purchase patterns concentrate in holiday-themed and limited-edition product launches.
Established revenue bases serve Adults for celebration occasions. Segment expansion is climbing fastest in Health-conscious Consumers for daily snacking repositioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany, China, and the United States while consumption patterns diverge across retail and foodservice channels. Regulatory frameworks in the European Union and FDA jurisdictions reshape formulation requirements. Industrial bakery infrastructure concentrates in specific metropolitan zones with cold-chain advantages.
United States
Foodservice operators drive single-serve portion bundling for dessert menus, expanding occasions beyond traditional celebrations. FDA nutrition labeling rules and USDA organic certification standards govern product claims and market access. K-12 and healthcare feeding segments in metropolitan corridors consolidate procurement around approved supplier lists with verified sustainability credentials.
China
Rising middle-class consumption and Western-style bakery adoption fuel demand for premium celebration formats. The country's national food safety regulator enforces GB standards for additive usage and labeling compliance. Tier-2 cities including Chengdu and Hangzhou present underpenetrated retail infrastructure for localized premium cake formats.
Germany
Health-conscious consumer segments accelerate adoption of almond flour alternatives and wheat-free formulations. EFSA sugar reduction targets and EU Farm to Fork Strategy mandates compress formulation flexibility. Industrial bakeries in Bavaria deploy vision-guided robotic decorating systems for consistent quality standardization in high-mix production environments.
United Kingdom
Direct-to-consumer frozen cake delivery models capture recurring revenue through subscription configurations in metropolitan markets. REACH compliance requirements for processing aids extend procurement timelines for European producers. London-based foodservice distributors face volume displacement as institutional buyers demand direct manufacturer relationships with chain-of-custody documentation.
Japan
Premium Japanese-style offerings anchor demand across Asian markets through portion-controlled elegance and seasonal limited editions. METI standards and JIS certification requirements shape equipment procurement and quality protocols. Yamazaki Baking's production footprint in the Kanto region exemplifies continental manufacturing scale for specialized formats.
Global Cakes Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across mass-market shelf-stable and premium refrigerated segments. The vendor base organizes around three strategic archetypes: continental-scale manufacturers with backward-integrated flour milling, regional specialists in celebration and gifting formats, and private-label contractors serving retail channel consolidation. Dominant competitive moves include capacity expansion in almond flour processing capabilities and strategic partnerships with precision-fermented ingredient suppliers.
Within the diversified conglomerate tier, Grupo Bimbo and Mondelez International exemplify scale-driven positioning across Americas and global convenience retail respectively. Yamazaki Baking occupies a position representing premium Asian-format specialization. Among focused specialists, Finsbury Food Group and McKee Foods exemplify regional celebration and snacking archetypes. Britannia Industries anchors emerging-market penetration capabilities. These named entities represent structural positioning rather than specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Grupo Bimbo |
| Mondelez International |
| McKee Foods |
| Hostess Brands |
| Yamazaki Baking |
| Finsbury Food Group |
| General Mills |
| Britannia Industries |
| Campbell Soup Company |
| Others |
Supply Flow & Price Mechanics
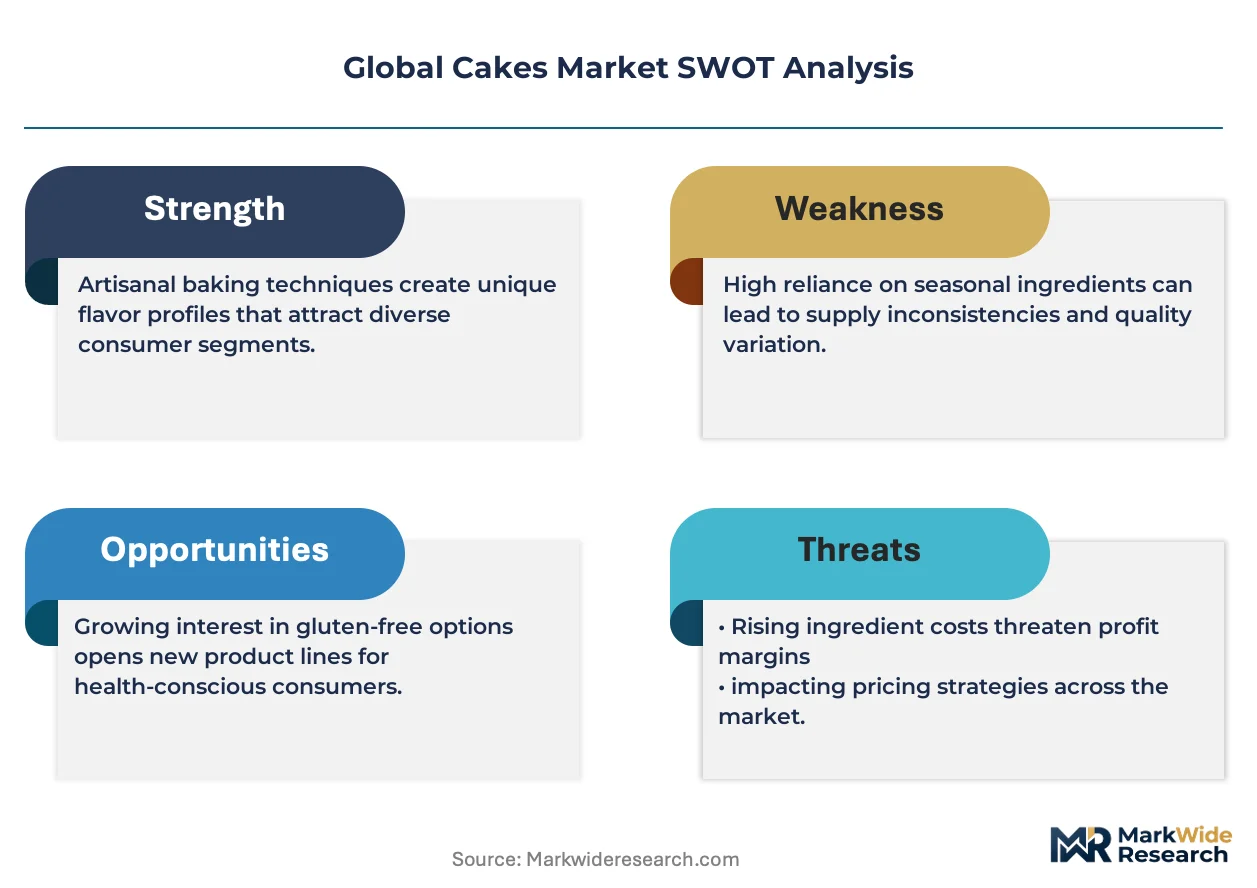
Clean-label certification tiers separate premium celebration cakes from commodity ambient lines, with EU Farm to Fork compliance costs and almond flour input volatility widening the spread between validated organic SKUs and standard formulations. This bifurcation manifests in divergent procurement strategies: premium manufacturers captive-source specialty flours and precision-fermented dairy alternatives, while mass-market players optimize wheat flour and egg supply contracts against avian influenza risk.
Pricing Analysis
Margin tightening in mass-market shelf-stable tiers reflects egg price volatility and promotional intensity in supermarket channels. Three-tier pricing structure across premium, standard, and economy levels tracks ingredient certification grade and customization depth. Cost-down pressure on economy lines accelerates because private-label penetration concentrates buyer power. School catering contracts and K-12 feeding segments exhibit highest price sensitivity; wedding catering and direct-to-consumer gifting show lowest.
Supply Chain Analysis
Freight cost differentials between refrigerated and ambient distribution networks favor regional production clustering over continental sourcing for cheesecake and mousse formats. Manufacturing gravity centers on Germany, China, and the United States for wheat flour milling infrastructure and equipment supplier density. Raw material portfolios draw from egg markets vulnerable to avian influenza, almond flour subject to California drought cycles, and butterfat tethered to dairy commodity swings. Single-source vulnerability concentrates in precision-fermented dairy alternatives where European pilot facilities dominate early capacity. Distribution runs through foodservice broadliners losing volume to direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive position in cakes hinges on backward integration into alternative protein and specialty flour processing, with first-movers capturing margin expansion as EFSA novel food pathways mature.
For Market Incumbents: Hedge egg supply volatility through cultivated protein partnerships and dual-sourcing from precision-fermented dairy pilots in Netherlands and Denmark facilities. Defend channel position by consolidating direct relationships with K-12 and healthcare institutional buyers around verified sustainability credentials and chain-of-custody documentation. For New Entrants and Emerging Players: Direct-to-consumer subscription routes in United Kingdom metropolitan markets bypass retail slotting fees and capture recurring revenue through frozen cake delivery models. Target underpenetrated Tier-2 Chinese cities including Chengdu and Hangzhou with localized premium formats adapted to regional taste preferences, leveraging digital marketing for brand building without legacy distributor overhead. For Investors and Strategic Acquirers: Re-rating potential sits with almond flour processing specialists given EU sugar reduction mandates and German health-conscious consumer acceleration. Long-term viability favors facilities with clean-label certification infrastructure and robotic decorating capability. Watch EFSA approval velocity for cultivated egg proteins as inflection indicator for input cost structure transformation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Almond Flour Milling | Captures margin expansion in German free-from specialty lines amid input cost volatility. |
| Precision-Fermented Dairy Partnership | Preempts butterfat supply risk in premium layer cake applications through EFSA-aligned novel ingredient pathways. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting constraints and builds recurring revenue in United Kingdom metropolitan corridors. |
| Vision-Guided Robotic Decorating Deployment | Automates quality standardization in Bavarian high-mix production environments amid artisan skill scarcity. |
| USDA Organic Certification Investment | Unlocks margin expansion in United States retail channels where clean-label claims accelerate penetration. |
Methodological Framework
Document review covered FDA nutrition labeling guidance, EFSA novel food approvals, EU Farm to Fork Strategy implementation documents, and customs trade data, complemented by interviews with plant managers at industrial bakery facilities, procurement leads at foodservice distributors, category buyers at supermarket chains, and regulatory affairs specialists. Secondary validation drew from SEC filings of diversified baked goods conglomerates, Nielsen retail audit data, and equipment manufacturer technical specifications. Bottom-up volume modeling triangulated against top-down market sizing across ingredient type and distribution channel dimensions.
Cross-referencing historical production capacity expansion patterns against panel input from manufacturing executives informed CAGR derivation across the analysis window. Segmentation modeling incorporated product type, ingredient specification, distribution channel, and customer behavioral archetype dimensions. Forecast inputs included EFSA reformulation timeline enforcement, avian influenza outbreak frequency, and cold-chain infrastructure development trajectories in target geographies.
Inputs from regulatory filings and trade databases were available through the study window; gaps in real-time egg commodity pricing and precision-fermented ingredient capacity announcements introduce uncertainty bands around input cost assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Asia-Pacific Frozen Bakery Market
Bakery Products
Frozen Bakery Additives Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
GCC Bakery Products Market
Bakery Products
Malted Rye Flour Market
Bakery Products
Par-Baked Bread Market
Bakery Products
North America Fortified Bakery Products Market
Bakery Products
Cream Cheese Frosting Market
Bakery Products
Low Fat Muffin Market
Bakery Products
Cakes and Pastries Market
Bakery Products
Middle East and Africa Bakery Products Market
Bakery Products
Oman Frozen Bakery Products Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Latin America Frozen Bakery Market
Bakery Products
North America Par Baked Bread Market