
 Low Fat Bran Muffins Market | 2026-2036
Low Fat Bran Muffins Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Bran Muffins Market Analytics
The convenience-oriented professional segment is recalibrating morning consumption habits toward portable, nutritionally dense bakery options. Kellogg's leverages its cereal-bakery crossover expertise to anchor shelf presence in mass retail channels. General Mills sustains R&D intensity around fiber-forward formulations that compete with emerging artisan brands. Bob's Red Mill specializes in whole-grain ingredient supply, extending its influence upstream into branded finished goods.
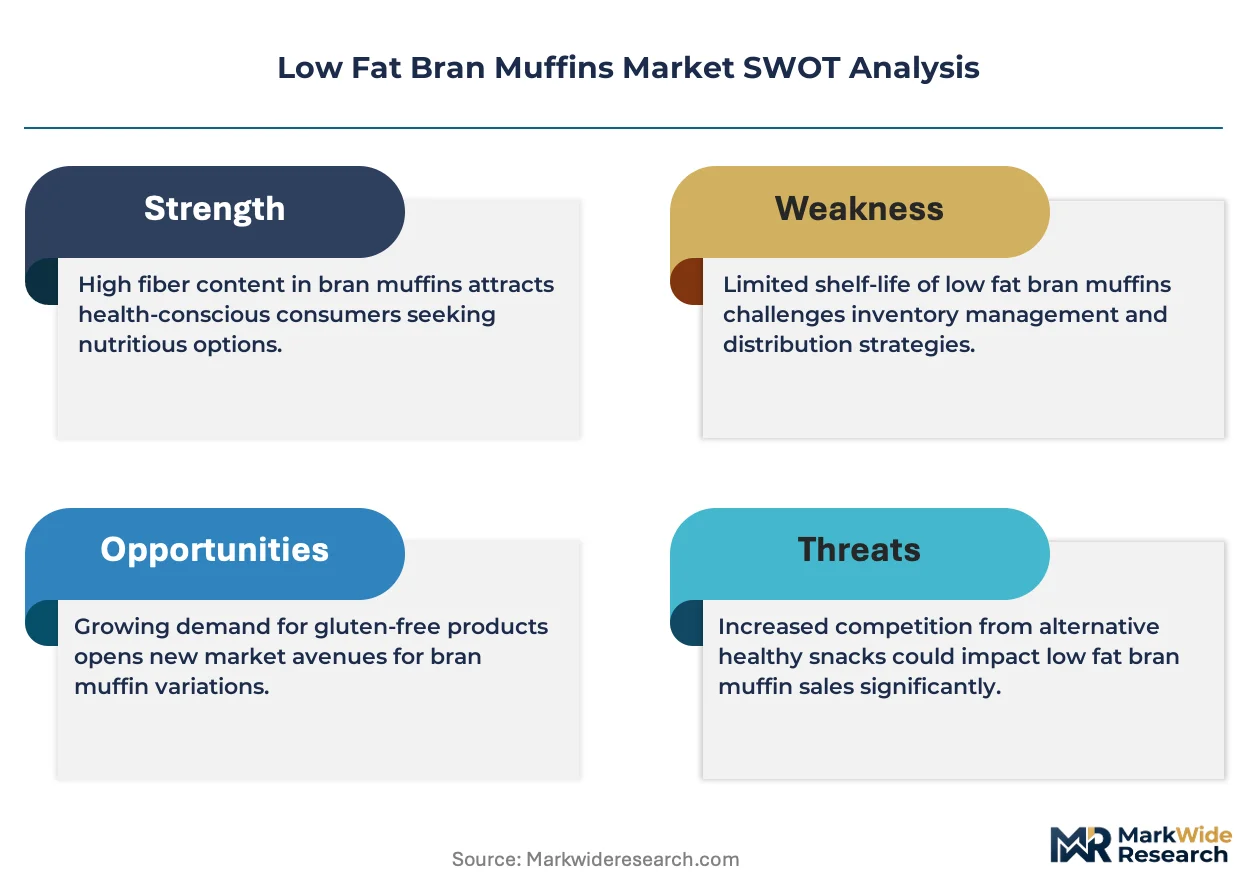
Low fat bran muffins combine wheat bran, reduced-fat dairy or oil substitutes, and leavening agents baked to a moisture specification typically below 45 percent, delivering standardized fiber content for dietary management and on-the-go meal replacement. Gluten-free and organic product types command premium positioning as margin pools concentrate in allergen-controlled and certified-clean supply chains. Supermarkets and online retailers dominate volume throughput, while health food stores capture higher per-unit economics through curated assortment and dietitian endorsement.
The FDA governs nutrition labeling and health claims under the Nutrition Labeling and Education Act, directly constraining fat-content assertions and fiber-quantification methods. USDA organic certification and state-level cottage-food regulations create layered compliance thresholds that shape market access for regional entrants. Stakeholders must monitor evolving whole-grain definition standards and clean-label enforcement intensity to align formulation pipelines with shifting compliance baselines.
Market Dynamics
Clean-label reformulation mandates from the FDA and USDA are compressing formulation cycles while whole-grain fortification standards force ingredient sourcing recalibration across the supply base.
Growth Catalysts
- FDA Whole-Grain Definition Standards:Updated serving-size guidance expands permissible fiber claims, enabling broader shelf placement in conventional grocery.
- Urban Coastal Professionals:Dense concentrations in Boston, Seattle, and San Francisco generate sustained demand for portable breakfast alternatives with validated nutritional density.
- Enzymatic Fat-Replacement Technology:Lipase-modified starch systems improve moisture retention without hydrogenated oils, extending shelf stability in mass retail distribution.
Market Restraints
- Wheat Bran Input Volatility:Drought cycles in North American grain belts create price instability for the primary fiber source, compressing margin predictability for mid-tier producers.
- USDA Organic Certification Lag:Three-year transition requirements for conventional acreage constrain rapid scaling of certified-clean supply chains.
- Refrigerated Protein Bar Substitution:Chilled snacking alternatives with comparable macronutrient profiles capture overlapping convenience-oriented occasions.
Strategic Opportunities
- Texas and Florida Suburban Expansion:Underserved metro corridors outside traditional coastal strongholds present white-space for specialty grocery penetration.
- Direct-to-Office Subscription Models:Employer-sponsored wellness programs create captive demand channels bypassing conventional retail markup structures.
- IRA-Aligned Sustainable Packaging Incentives:Federal bio-based material credits offset compostable wrapper cost premiums for early adopters.
Industry Challenges
- Clean-Label Sensory Validation:Removing artificial preservatives while maintaining 45-day ambient shelf life demands accelerated stability testing protocols.
- Multi-State Cottage-Food Compliance:Fragmented home-kitchen licensing rules across California, New York, and Illinois create regulatory friction for regional artisan entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Bran Muffins Market |
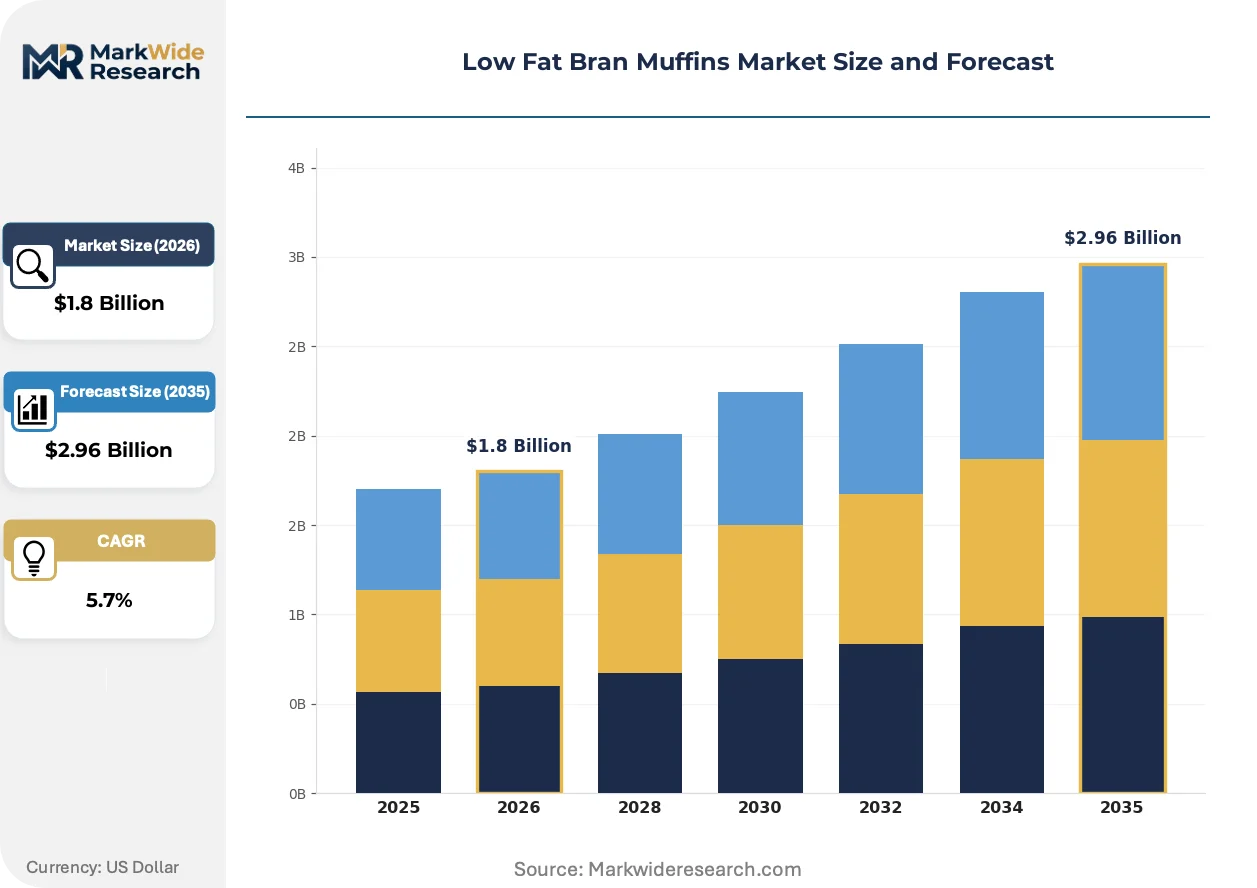
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free, Whole Grain, Sugar-Free, Organic Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Cafés Consumer Type: Health-Conscious Individuals, Diabetics, Athletes, Busy Professionals Packaging Type: Boxed, Individually Wrapped, Bulk, Eco-Friendly |
| Companies Covered | Kellogg's, General Mills, Post Holdings, Central Market, King Kullen, Bob's Red Mill, King Arthur Baking, Hostess Brands, Entenmann's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Bran Muffins Market Evolving Landscape
Reformulation science and distribution model compression are converging to redefine how fiber-forward bakery reaches convenience-seeking consumers.
Soluble fiber prebiotic enrichment is absorbing into mainstream formulations as brands seek dual-function positioning. Health-conscious millennials in metropolitan markets adopt these variants at accelerated rates. The technology is absorbing margin pressure from premium positioning by justifying price tiers through digestive health claims.
USDA Bioengineered Food Disclosure Standards now mandate explicit labeling for ingredients derived from gene-edited crops. Industrial bakers reformulating with CRISPR-modified wheat face reformulation timelines compressed by compliance deadlines. The standard most affects mass-market producers reliant on commodity grain supply chains.
Subscription-based replenishment models are displacing impulse purchase patterns in household pantry management. Direct-to-consumer channels capture recurring revenue from suburban families seeking predictable breakfast inventory. This behavioral shift concentrates in California and Pacific Northwest markets with established e-commerce grocery infrastructure.
Low Fat Bran Muffins Market Segmentation
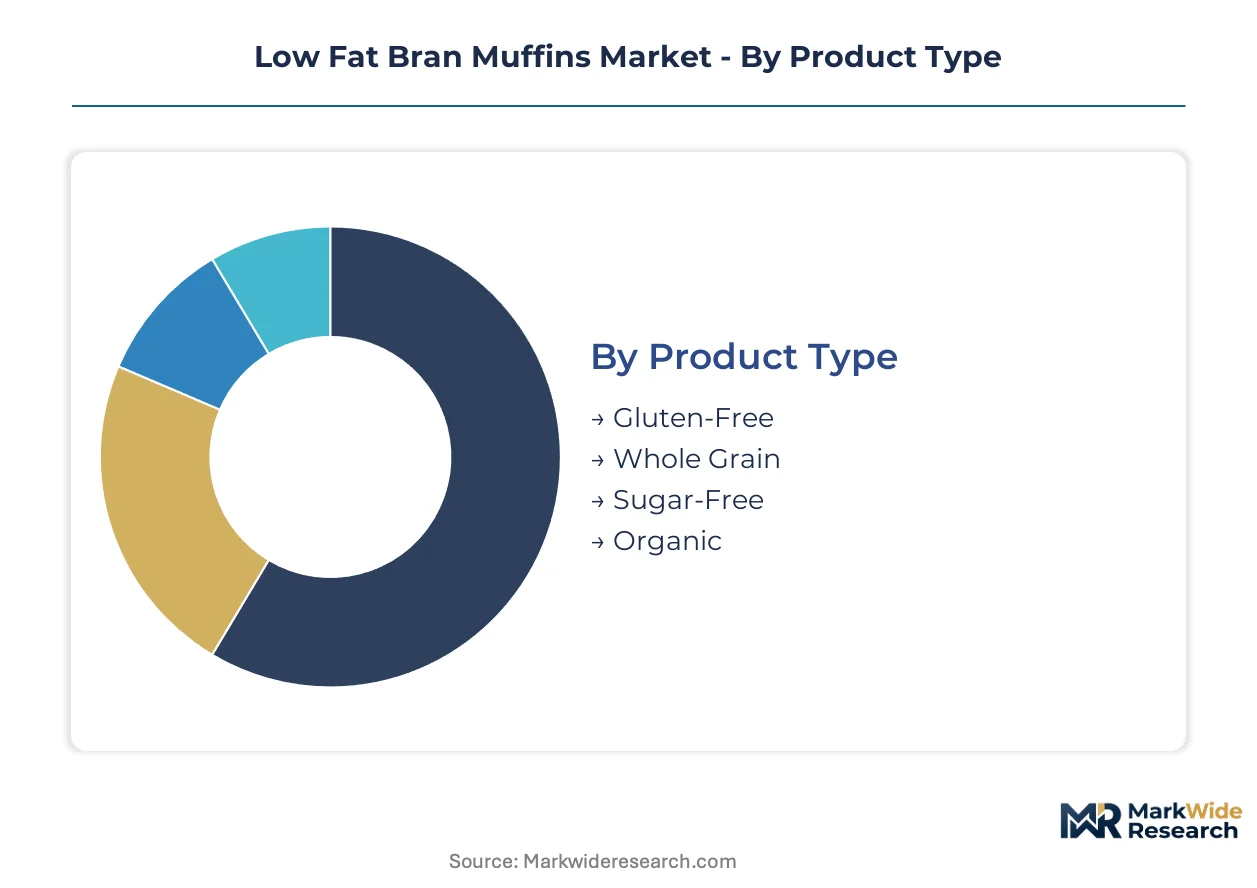
Segmentation in low fat bran muffins reveals how formulation specialization and channel strategy determine margin capture. Manufacturers must align product architecture with distinct consumption occasions and regulatory thresholds across each dimension.
Product Type:
Standalone specialty formulations command premium positioning through certification layers, while embedded functional variants integrate into broader dietary management protocols.
- Gluten-Free:Formulations replace wheat bran with rice, oat, or almond fiber bases to achieve under 20ppm gluten thresholds. Demand clusters in celiac-diagnosed households across Massachusetts and California, where specialty grocery density supports price premiums. The segment absorbs formulation cost inflation through medical-necessity positioning.
- Whole Grain:Products maintain ≥51% whole grain content by weight per FDA guidance, leveraging intact bran and germ for fiber density. Urban coastal professionals in Seattle and Boston sustain volume through validated nutritional claims on packaging. This segment anchors conventional grocery shelf placement.
- Sugar-Free:Monk fruit and allulose sweetener systems replace sucrose for glycemic management applications.
- Organic:USDA-certified supply chains command three-year transition premiums and segregated handling infrastructure.
Volume placements concentrate in Whole Grain; the faster expansion belongs to Gluten-Free.
Distribution Channel:
Channel selection determines margin structure through markup layering and inventory velocity trade-offs.
- Supermarkets:Mass retail chains like Kroger and Safeway drive case-volume throughput with centralized distribution and promotional slotting fees. Health-conscious suburban families in Texas and Florida generate recurring basket attachments alongside conventional grocery trips. This channel compresses per-unit margins while maximizing household penetration.
- Health Food Stores:Curated assortments with dietitian endorsement capture 40-60% price premiums over mass retail. Dense concentrations in Pacific Northwest co-ops and Northeast natural foods chains sustain higher per-unit economics through educated consumer bases. The segment justifies shelf space through margin contribution rather than velocity.
- Online Retailers:Amazon and Thrive Market enable subscription replenishment with predictive inventory algorithms.
- Cafés:Foodservice placement in grab-and-go bakery cases targets morning commuter occasions.
Supermarkets dominate absolute volume; Health Food Stores deliver the steepest margin expansion trajectory.
Consumer Type:
User segmentation maps functional need states to formulation intensity and purchase frequency patterns.
- Health-Conscious Individuals:Wellness-motivated buyers prioritize clean-label ingredient panels and third-party certifications over price sensitivity. This cohort concentrates in coastal metropolitan markets with established organic grocery infrastructure and drives repeat purchase through brand loyalty programs.
- Diabetics:Glycemic management requirements mandate low-glycemic carbohydrate profiles and precise fiber-to-sugar ratios. Endocrinologist recommendations and diabetes educator endorsements validate purchase decisions in this clinically guided segment.
- Athletes:Pre-workout carbohydrate loading and post-training recovery occasions demand portable, macronutrient-quantified formats.
- Busy Professionals:Convenience-seeking office workers substitute sit-down breakfasts with shelf-stable, individually portioned options.
Health-Conscious Individuals anchor baseline demand; Busy Professionals are expanding most quickly as hybrid work patterns normalize.
Packaging Type:
Packaging configuration directly determines shelf-life extension, portion control, and sustainability credentialing.
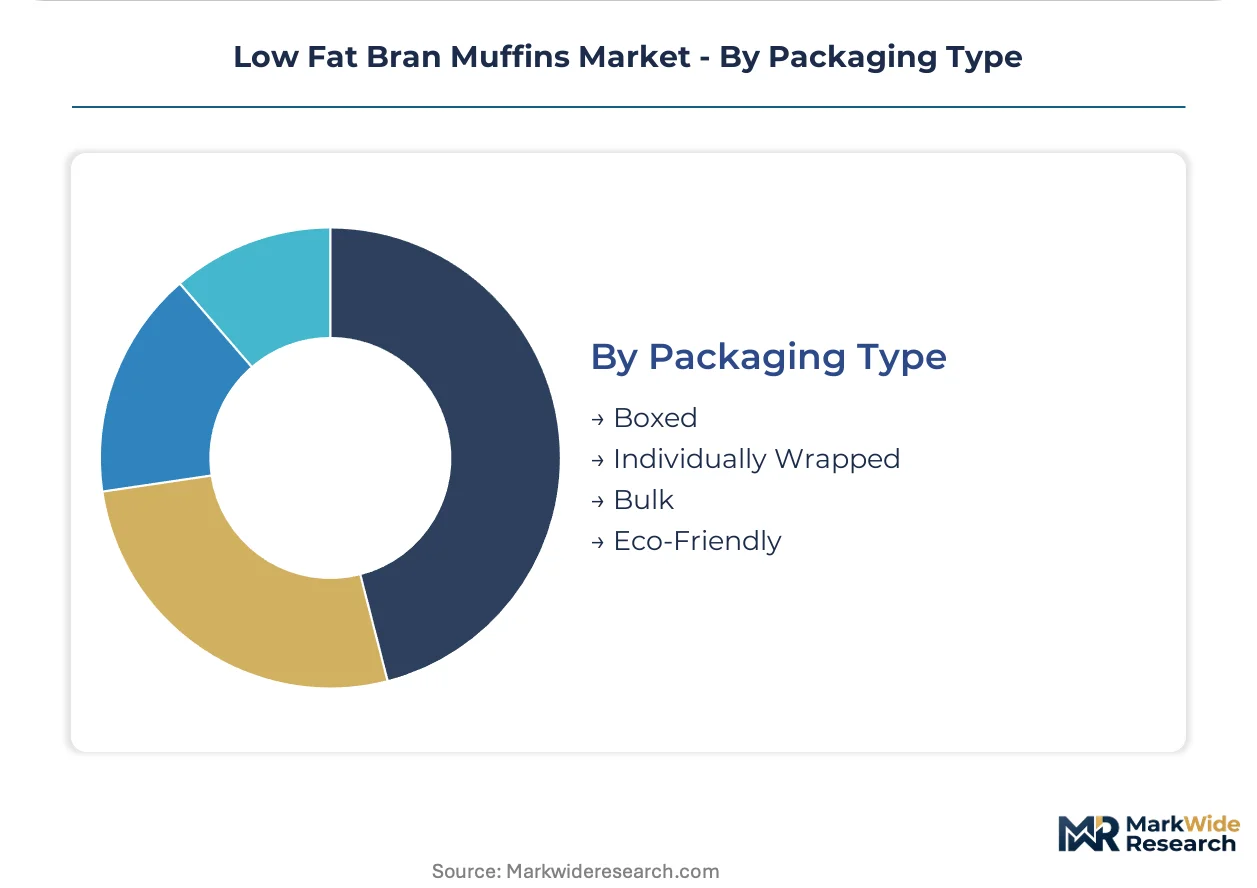
- Boxed:Multi-count corrugated packaging serves pantry-stocking households with 30-45 day ambient stability requirements. Suburban families in Florida and Texas metro corridors favor this format for predictable breakfast inventory management and unit-cost efficiency.
- Individually Wrapped:Single-serve flow-wrapped portions enable foodservice placement and on-the-go consumption without resealing. Urban professionals in San Francisco and New York sustain demand through commuter-friendly portability and contamination control.
- Bulk:Unpackaged bakery case offerings reduce per-unit material costs for in-store bakery programs.
- Eco-Friendly:Compostable cellulose and PLA wrappers align with IRA-aligned federal bio-based material incentives.
Boxed formats dominate household penetration; Eco-Friendly packaging gains share fastest among millennial and Gen Z purchaser cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in distressed urban corridors concentrate production incentives for low-fat bran muffin manufacturers seeking FDA-compliant facility upgrades. Tax-advantaged development areas in Baltimore, Detroit, and Cleveland anchor regional baking clusters with accelerated depreciation schedules for clean-label equipment investments.
United States
Urban coastal professionals in Boston, Seattle, and San Francisco sustain premium demand for portable, fiber-dense breakfast alternatives. FDA whole-grain definition standards expand permissible fiber claims, enabling broader conventional grocery shelf placement. The Pacific Northwest corridor concentrates artisan brands leveraging regional organic supply chains through Portland and Eugene distribution hubs.
Canada
Health-conscious consumers in Toronto and Vancouver drive demand for reduced-fat bakery with validated nutritional labeling. Health Canada nutrition labeling regulations constrain fat-content assertions and mandate bilingual packaging standards. The Greater Toronto Area hosts contract manufacturing capacity serving cross-border supermarket private-label programs.
United Kingdom
Clean-label reformulation pressures from EFSA guidance reshape fiber-forward product development for British retailers. The UK Food Standards Agency enforces strict allergen labeling thresholds that complicate gluten-free bran muffin production. London and Manchester metropolitan markets concentrate demand for on-the-go breakfast alternatives among finance and technology sector workers.
Germany
Bio-certified organic demand in Berlin and Munich sustains premium positioning for USDA-equivalent EU organic bakery. ECHA chemical safety standards influence emulsifier and preservative selection in industrial formulations. The Baden-Württemberg region anchors whole-grain ingredient processing infrastructure supplying Central European baking operations.
Australia
Sports nutrition positioning drives athlete-targeted bran muffin variants in Sydney and Melbourne fitness-oriented retail channels. FSANZ food standards govern health claim substantiation for fiber and reduced-fat assertions. The Melbourne metropolitan area concentrates specialty grocery penetration with dietitian-curated breakfast assortment programs.
Low Fat Bran Muffins Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with mass-market retail channels consolidating around cereal-bakery crossover portfolios while artisan segments fragment across regional clean-label entrants. The vendor base organizes into three archetypes: legacy breakfast conglomerates with R&D scale, whole-grain ingredient suppliers extending downstream, and regional cottage-food operators exploiting direct-to-consumer channels. Dominant competitive moves include strategic partnerships between ingredient suppliers and finished-goods brands, plus geographic expansion into underserved suburban corridors bypassing traditional coastal strongholds.
Within the legacy breakfast conglomerate tier, Kellogg's and General Mills exemplify scale-driven market presence through cereal-bakery crossover expertise and fiber-forward formulation pipelines. Bob's Red Mill occupies a distinct upstream-to-downstream position, anchoring whole-grain ingredient supply influence while extending branded finished-goods reach. These three entities represent contrasting strategic postures: mass-retail shelf dominance, R&D-intensive product development, and supply-chain-integrated specialty positioning.
| Leading Market Players |
|---|
| Kellogg's |
| General Mills |
| Post Holdings |
| Central Market |
| King Kullen |
| Bob's Red Mill |
| King Arthur Baking |
| Hostess Brands |
| Entenmann's |
| Others |
Value Network & Pricing Analysis
Captive sourcing of North American wheat bran anchors cost predictability for mid-tier producers while creating pricing leverage for vertically integrated operators with in-house milling capacity. The three-year USDA organic transition requirement forces committed investment before premium price realization, compressing working capital cycles for entrants against established players with certified acreage already under cultivation.
Pricing Analysis
Short lead-time premiums concentrate in health food store channels where rapid replenishment of fast-moving SKUs justifies 15-25% markups over supermarket baselines. Three-tier pricing structure across certified-organic, whole-grain conventional, and economy private-label tiers separates buyers by certification tolerance and brand loyalty intensity. Pricing pressure stems from refrigerated protein bar substitution in convenience occasions, eroding impulse purchase frequency. Health-conscious individuals show lowest price sensitivity; suburban families in Texas and Florida exhibit highest elasticity, trading down to private-label during promotional windows.
Supply Chain Analysis
Dual-sourcing mandates from mass retail buyers require qualification of at least two wheat bran suppliers per production facility, fragmenting procurement across North American grain belts and Australian organic operations. Primary inputs include wheat bran, enzymatic fat-replacement starches, and monk fruit sweetener systems. Tariff exposure on Australian organic wheat concentrates risk for premium-tier producers dependent on segregated certified supply. Distribution runs through centralized bakery networks serving supermarket distribution centers, with direct-to-consumer channels bypassing traditional wholesale markup layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA whole-grain definition standards function as a cost-of-compliance moat, advantaging incumbent R&D budgets against artisan entrants lacking accelerated stability testing infrastructure. The regulation's fiber-quantification precision demands laboratory investment that fragments competitive viability across scale tiers.
For Market Incumbents: Anchor shelf position through cereal-bakery crossover brand extension into fiber-forward formats, exploiting existing retail slotting relationships. Defend against refrigerated protein bar substitution by accelerating enzymatic fat-replacement R&D to match clean-label shelf-life claims. Prioritize backward integration into certified organic wheat sourcing to capture margin compression from three-year transition premiums.
For New Entrants and Emerging Players: Enter via direct-to-office subscription models targeting employer wellness programs, bypassing conventional retail slotting fee barriers. White-space concentrates in Texas and Florida suburban corridors where specialty grocery penetration lags coastal density. Lead with eco-friendly packaging credentials to capture IRA-aligned federal bio-based material credits and millennial purchaser preference.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by legacy breakfast conglomerates seeking clean-label portfolio augmentation. Long-term viability favors supply-chain-integrated specialists with captive organic acreage and health food store channel density. Watch FDA enforcement intensity on whole-grain claim substantiation as inflection signal for compliance-cost recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | FDA fiber-quantification compliance enables broader conventional grocery shelf placement for reformulated SKUs. |
| Direct-to-Consumer Subscription Launch | Amazon and Thrive Market algorithms capture recurring revenue from suburban pantry-stocking households. |
| Organic Supply Chain Integration | USDA three-year transition requirements favor early acreage commitment before certified-premium price realization. |
| Sustainable Packaging Transition | IRA bio-based material credits offset compostable wrapper cost premiums for first-mover brands. |
| Suburban Geographic Expansion | Texas and Florida metro corridors present white-space for specialty grocery penetration outside coastal strongholds. |
Research Methodology
Multi-period observation of wheat bran input pricing, enzymatic fat-replacement adoption curves, and clean-label SKU velocity anchored the trend analysis, supplemented by interviews with bakery R&D directors, supermarket category buyers, health food store procurement managers, and FDA regulatory affairs consultants. Secondary validation drew from USDA organic certification databases, FDA whole-grain guidance documents, Nielsen retail audit data, and SEC 10-K filings of publicly traded breakfast conglomerates. Bottom-up SKU-level velocity modeling triangulated against top-down category value estimates.
Input-output matrices mapped wheat bran supply fluctuations, enzymatic technology adoption rates, and channel shift patterns across the projection horizon. Segmentation dimensions included product type (gluten-free, whole grain, sugar-free, organic), distribution channel (supermarkets, health food stores, online retailers, cafés), consumer archetype (health-conscious individuals, diabetics, athletes, busy professionals), and packaging configuration. CAGRs derived from regression-weighted historical velocity trends applied to projected household penetration curves in identified growth corridors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under drought-induced wheat bran price spikes or accelerated FDA clean-label enforcement timelines. Deviation in refrigerated protein bar substitution rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Pizza Dough Balls Market
Bakery Products
Middle East and Africa Bakery Products Market
Bakery Products
Vegan Donuts Market
Bakery Products
Ready-To-Finish Bakery Products Market
Bakery Products
Global Rice Cakes Market
Bakery Products
Europe Zwieback Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
Vegan Baking Mix Market
Bakery Products
Bread Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
Packaged Bread Market
Bakery Products
Asia-Pacific Baked Food and Cereals Market
Bakery Products
Bread Mix Market
Bakery Products
North America Par Baked Bread Market
Bakery Products
Bakery Fats Market
Bakery Products
Healthy Biscuits Market