
 Cake Base Discs Market | 2026-2036
Cake Base Discs Market Size, Share, and Industry Trends Forecast 2026-2036
Cake Base Discs Market Outlook
ISO 22000 food safety certification is reorganizing competitive access in the Cake Base Discs Market, filtering out suppliers lacking verified hazard controls. Puratos Group leverages its European manufacturing footprint to sustain consistent supply to artisan bakeries. CSM Bakery Solutions anchors its position through deep channel relationships with commercial bakery chains. Wilton Brands LLC competes by specializing in decorative presentation formats for home baking segments.
Cake base discs are rigid support platforms, typically manufactured from food-grade cardboard, corrugated fiberboard, or coated paperboard composites, engineered to bear layered cake loads without sagging or moisture penetration during transport and display. Round configurations dominate commercial bakery procurement due to standardization in wedding and celebration cake formats, while custom shapes command premium positioning in boutique catering channels. Cardboard materials lead volume shipments across the 8-inch and 10-inch size brackets, though plastic alternatives are gaining traction in refrigerated display applications where moisture resistance outweighs sustainability preferences.
The EU Packaging and Packaging Waste Regulation and FDA food contact substance requirements shape material selection and migration testing protocols for cross-border suppliers. BIS certification in India and FSSAI compliance standards further segment market access for exporters targeting Asia-Pacific food service channels. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate innovation cycles to align procurement with pending material restriction timelines.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing material choice windows for cake base disc manufacturers, forcing accelerated substrate transitions before pending restriction timelines activate.
Growth Catalysts
- Artisan bakery expansion:Premium cardboard bases are penetrating independent bakery chains across France and Germany as celebration cake formats standardize on rigid support platforms.
- ISO 22000 certification requirements:Food safety verification is filtering supplier access, creating competitive moats for hazard-control-compliant manufacturers in cross-border trade.
- Coated paperboard innovation:Moisture-resistant composites are displacing conventional cardboard in refrigerated display applications where transport durability outweighs cost sensitivity.
Market Restraints
- Pulp fiber cost volatility:Food-grade cardboard input prices fluctuate with Nordic pulp supply cycles, compressing margin buffers for mid-tier converters.
- Western European supply concentration:Production gravity centers on Benelux and northern France, exposing buyers to single-region disruption risk.
- Plastic substitution threat:Polypropylene alternatives are capturing share in cold-chain bakery segments where moisture resistance trumps sustainability positioning.
Strategic Opportunities
- Extended producer responsibility frameworks:The EU Green Deal's packaging circularity mandates will advantage suppliers with closed-loop fiber recovery systems.
- Specialty cake segment white space:Custom-shaped bases for boutique catering channels command premium positioning with limited current supplier penetration.
- Home baking channel digitization:Direct-to-consumer platforms are opening new distribution pathways for decorative presentation formats outside traditional bakery procurement.
Industry Challenges
- Migration testing complexity:FDA food contact substance protocols and EFSA compliance requirements demand dual-certification investment for transatlantic suppliers.
- Legacy equipment retrofit costs:Coating line upgrades for moisture-barrier paperboard require capital deployment that strains smaller converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cake Base Discs Market |
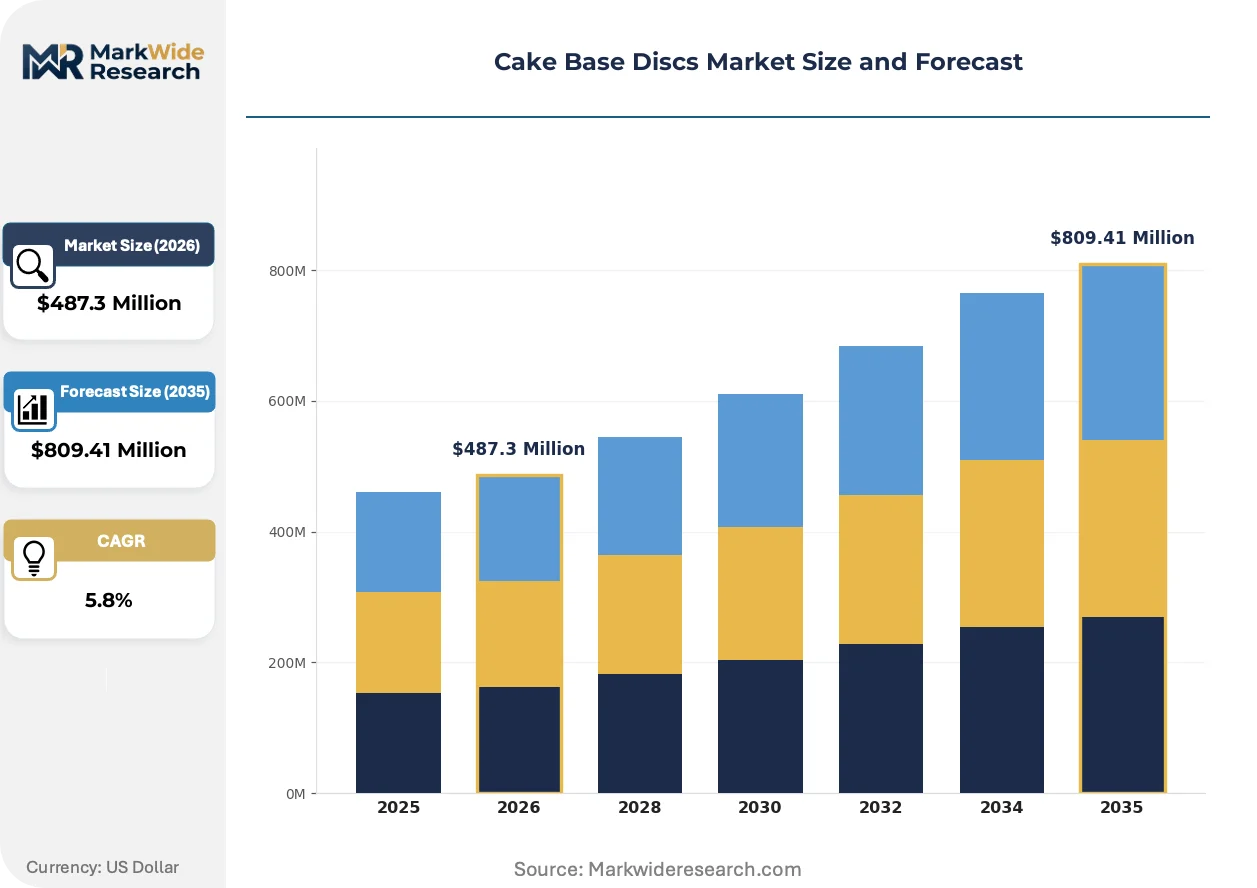
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round, Square, Rectangular, Custom Shapes Material: Cardboard, Plastic, Wood, Metal Size: 6 inch, 8 inch, 10 inch, 12 inch End User: Bakeries, Restaurants, Catering Services, Home Bakers |
| Companies Covered | Rich Products Corporation, General Mills, Wilton Brands LLC, DecoPac, Mondelez International, Cargill, Oetker Group, CSM Bakery Solutions, Puratos Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cake Base Discs Market Strategic Shifts
Active substrate engineering and regulatory compression are reshaping competitive positioning in cake base disc manufacturing, with material science advances running ahead of compliance framework adaptation.
Barrier-coated corrugated fiberboard is miniaturizing the performance gap between cardboard and plastic alternatives in refrigerated applications. Commercial bakery chains in Germany are piloting these composites for wedding cake transport. The technology is miniaturizing moisture penetration rates to sub-5% thresholds previously requiring petroleum-based substrates.
REACH substance restrictions are eliminating certain wax coatings from food-contact applications in the European Union. Manufacturers must reformulate barrier layers using bio-based alternatives before 2027 sunset dates. Wedding and celebration cake segments are accelerating qualification timelines to avoid supply interruption.
Consolidated procurement by artisan bakery cooperatives is compressing supplier negotiation cycles from annual to quarterly rhythms. Independent French bakery chains are pooling volume commitments to extract tiered pricing concessions. This concentration is most visible in Paris and Lyon metropolitan clusters where specialty cake demand density supports shared logistics infrastructure.
Cake Base Discs Market Segmentation
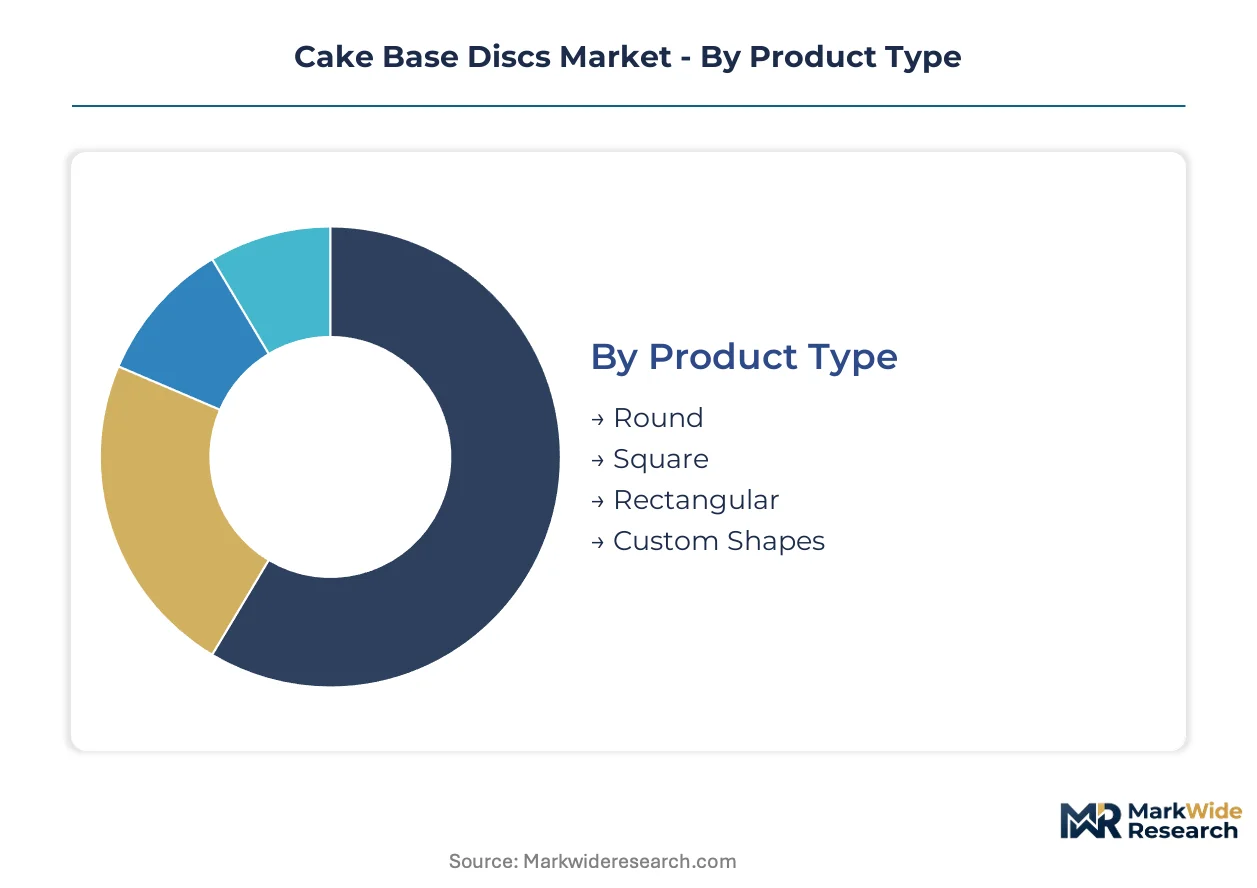
Cake base disc procurement patterns diverge sharply across channel types, with artisan bakeries prioritizing standardized round formats while catering services drive custom shape development. Channel-specific requirements around transport durability, presentation aesthetics, and regulatory compliance create distinct segment performance profiles.
Product Type:
Round formats dominate commercial bakery procurement through wholesale distributors, while custom shapes flow primarily through boutique catering channels and direct-to-specialty-retail pathways.
- Round:Engineered from food-grade corrugated fiberboard with moisture-resistant coatings, these standardized platforms bear layered cake loads without sagging during refrigerated transport. French and German artisan bakery chains concentrate procurement in the 8-inch and 10-inch brackets for wedding and celebration cake formats. ISO 22000 certification requirements are filtering supplier access for this high-volume segment.
- Custom Shapes:Laser-cut or die-pressed configurations including hexagons, hearts, and tiered asymmetrical designs command premium positioning in boutique catering channels. Paris and Lyon metropolitan clusters show concentrated demand density where specialty cake presentation differentiates catering procurement decisions.
- Square:Rigid support platforms optimized for sheet cake derivatives and modernist dessert architecture, penetrating commercial bakery chains through consolidated cooperative purchasing.
- Rectangular:Standardized formats for slab cakes and corporate event catering, with volume concentration in Benelux production corridors serving cross-border distribution.
By volume, Round leads. By growth pace, Custom Shapes is climbing the fastest.
Material:
Cost tier stratification separates premium coated composites from economy-grade uncoated cardboard, with plastic alternatives capturing cold-chain segments where performance outweighs sustainability premiums.
- Cardboard:Food-grade paperboard composites with barrier coatings dominate 8-inch and 10-inch shipments through wholesale bakery supply channels. REACH substance restrictions are forcing accelerated reformulation of wax-based moisture barriers before sunset deadlines.
- Plastic:Polypropylene and PET alternatives penetrate refrigerated display applications where sub-5% moisture penetration thresholds outweigh circularity preferences. German commercial bakery chains pilot these substrates for wedding cake transport durability.
- Wood:Premium hardwood and bamboo platforms serve upscale catering presentation requirements with natural aesthetic positioning.
- Metal:Reusable aluminum and stainless steel bases target high-volume commercial bakery operations with extended lifecycle economics.
Cardboard commands the volume lead. Plastic is gaining share fastest in cold-chain segments.
Size:
Application-driven procurement patterns concentrate 8-inch and 10-inch formats in celebration cake segments, while 6-inch and 12-inch brackets serve diverging use cases across home baking and institutional catering.
- 8 inch:The standard wedding cake tier format, manufactured from coated corrugated fiberboard with reinforced load-bearing cores. French artisan bakery expansion drives concentrated demand through Paris metropolitan procurement cooperatives.
- 10 inch:Base tier and single-layer celebration cake standard, with volume flowing through German commercial bakery chains and independent French bakery networks.
- 6 inch:Individual dessert and home baking segment format, penetrating direct-to-consumer channels through specialty kitchenware retail.
- 12 inch:Institutional catering and large-format event standard, with procurement concentrated in Benelux production hubs serving cross-border foodservice distributors.
Eight-inch formats anchor volume. Ten-inch formats show the steepest expansion trajectory in artisan bakery channels.
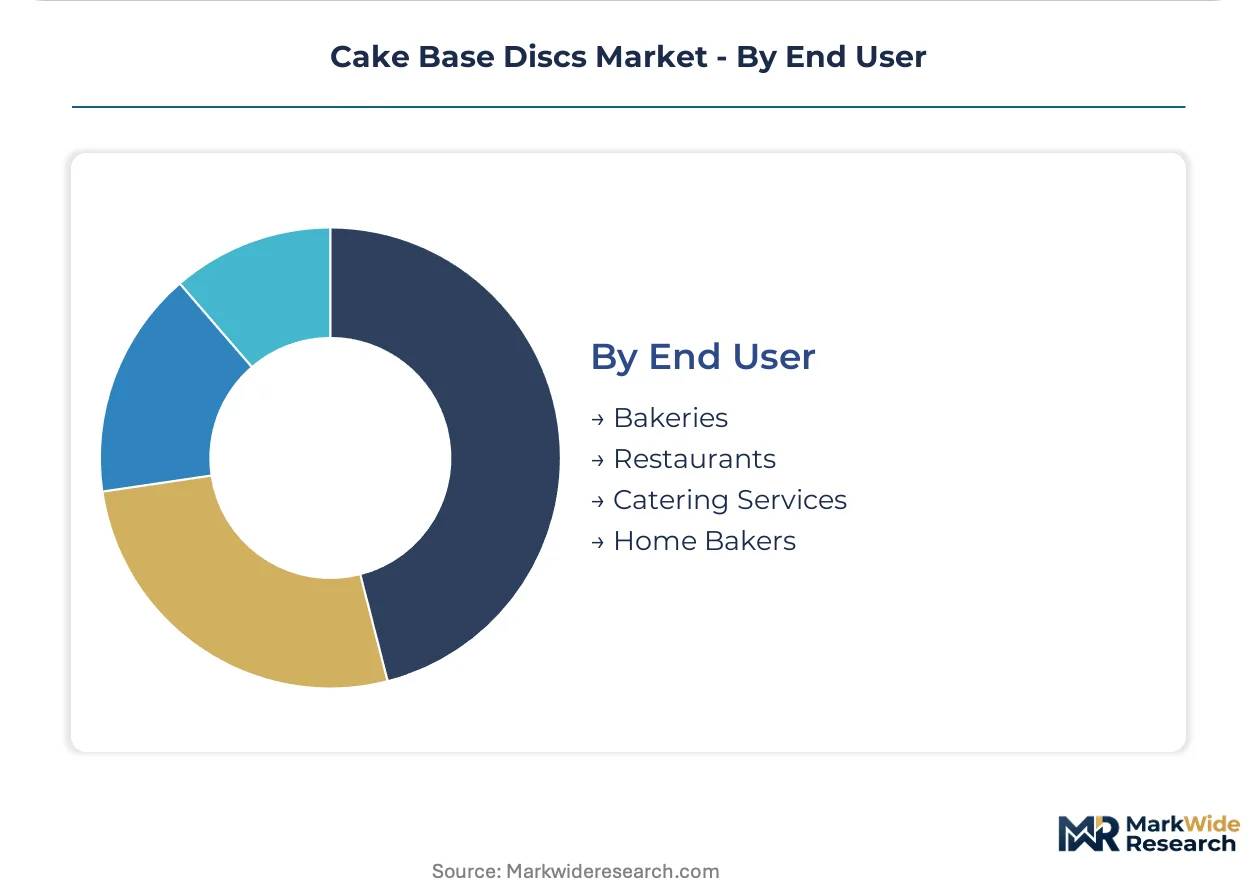
End User:
Customer type determines certification requirements and channel access, with commercial bakeries demanding ISO 22000 verification while home baking segments prioritize decorative presentation features.
- Bakeries:Artisan and commercial bakery chains require food-grade cardboard with verified hazard controls and EFSA-compliant migration testing. German and French procurement cooperatives are compressing negotiation cycles to quarterly rhythms.
- Catering Services:Boutique catering channels drive custom shape development with premium positioning for event presentation differentiation.
- Restaurants:Dessert program procurement concentrates in mid-tier coated paperboard for plated presentation durability.
- Home Bakers:Decorative presentation formats penetrate direct-to-consumer platforms outside traditional bakery procurement channels.
Bakeries dominate volume. Catering Services is expanding most quickly in custom shape premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Packaging and Packaging Waste Regulation deadlines are compressing substrate transition timelines for cake base disc manufacturers across Western Europe. Artisan bakery expansion in France and Germany is driving premium cardboard demand for celebration cake formats. Production gravity concentrates in Benelux and northern France corridors serving cross-border distribution networks.
France
Paris and Lyon metropolitan clusters anchor specialty cake demand density for boutique catering channels. ANSM enforces food contact substance compliance alongside REACH substance restrictions on wax-based coatings. Île-de-France procurement cooperatives compress supplier negotiation cycles to quarterly rhythms for independent bakery chains.
Germany
Commercial bakery chains pilot barrier-coated corrugated fiberboard for wedding cake transport durability in refrigerated applications. KBA oversees packaging safety standards while EFSA migration testing protocols filter cross-border supplier access. Bavaria and North Rhine-Westphalia production hubs serve centralized procurement for artisan bakery cooperatives.
United States
Home baking segments drive decorative presentation format demand through direct-to-consumer kitchenware channels. FDA food contact substance requirements shape material selection and migration testing protocols for imported substrates. Midwest and Northeast corridor distribution centers handle wholesale bakery supply chain consolidation.
India
FSSAI compliance standards segment market access for exporters targeting food service channels in tier-one metropolitan markets. BIS certification mandates filter supplier qualification for commercial bakery procurement. Maharashtra and Karnataka industrial corridors concentrate converter capacity serving domestic bakery chain expansion.
United Kingdom
Artisan bakery chains standardize on 8-inch and 10-inch round formats for celebration cake tiers across London and Southeast England. FSA food contact material regulations align with EU REACH frameworks during post-transition regulatory alignment. Midlands manufacturing clusters supply coated paperboard composites to cross-channel distributors.
Cake Base Discs Market Competitive Environment
Listed leaders compete with private specialists across certification tiers and channel access dimensions. The vendor base stratifies between scale-driven converters serving commercial bakery chains and boutique fabricators targeting custom shape premiums. Three archetypes dominate: ISO 22000-certified integrated manufacturers, regional coating specialists with barrier innovation capabilities, and decorative presentation format designers for home baking channels. Competitive moves concentrate on coating line upgrades for moisture-resistant substrates and cooperative procurement consolidation to extract volume pricing concessions.
Among the named players, Puratos Group and CSM Bakery Solutions exemplify the integrated manufacturer archetype with European production footprints serving artisan bakery networks. Wilton Brands LLC occupies a position within the decorative presentation tier targeting home baking digitization. Rich Products Corporation and General Mills represent scale-driven food conglomerates with bakery supply channel leverage. These company names illustrate competitive positioning patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Rich Products Corporation |
| General Mills |
| Wilton Brands LLC |
| DecoPac |
| Mondelez International |
| Cargill |
| Oetker Group |
| CSM Bakery Solutions |
| Puratos Group |
| Others |
Value Chain & Pricing Dynamics
Barrier-coated corrugated fiberboard displacing conventional wax-coated cardboard in refrigerated display applications simultaneously redraws procurement geography toward Benelux coating specialists and compresses margin buffers for Nordic pulp-dependent converters. This substrate transition concentrates pricing power with integrated manufacturers possessing in-house barrier innovation capabilities while fragmenting negotiation leverage among legacy uncoated cardboard suppliers facing REACH substance restriction deadlines.
Pricing Analysis
Certification level creates the primary spread across the Cake Base Discs Market, with ISO 22000-verified hazard controls commanding premium positioning over uncertified alternatives. Three-tier pricing structure separates food-grade coated composites from standard corrugated fiberboard and economy uncoated grades. Cost compression in mid-tier segments is intensifying because pulp fiber input volatility erodes converter margins. Commercial bakery chains exhibit lowest price sensitivity due to cooperative volume consolidation, while independent artisan bakeries negotiate quarterly for tiered concessions.
Supply Chain Analysis
Belgium, the Netherlands, and northern France anchor coated paperboard production for cross-border distribution into German and French bakery networks. Manufacturing draws from Nordic pulp supply cycles, bio-based barrier coating inputs, and specialized lamination equipment. Single-region concentration exposes buyers to disruption risk from Benelux logistics chokepoints or regulatory enforcement actions. Distribution runs through wholesale bakery supply cooperatives consolidating procurement for artisan chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents in the Cake Base Discs Market face urgent substitution defense against polypropylene alternatives capturing cold-chain bakery segments. The threat trajectory demands preemptive positioning before plastic performance gaps narrow further.
For Market Incumbents: Shield core cardboard volumes by accelerating bio-based barrier coating qualification ahead of REACH sunset deadlines. Prioritize backward integration into pulp sourcing to dampen Nordic supply cycle exposure. Secure exclusive supply agreements with Paris and Lyon procurement cooperatives before quarterly negotiation rhythms harden.
For New Entrants and Emerging Players: Anchor in custom shape fabrication for boutique catering channels where laser-cut precision commands premium positioning with limited incumbent penetration. Target direct-to-consumer kitchenware platforms for decorative presentation formats outside traditional wholesale bakery procurement. Lead with moisture-resistant composite innovation for home baking digitization.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed coating specialists possessing barrier innovation capabilities but lacking channel scale. Five-to-ten year viability hinges on circular fiber recovery system deployment aligning with extended producer responsibility frameworks. Monitor EU Packaging and Packaging Waste Regulation enforcement intensity as inflection signal for substrate transition velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Line Upgrade | REACH-compliant bio-based formulations secure continued EU market access for wedding cake tiers. |
| Cooperative Procurement Consolidation | Quarterly volume commitments extract tiered pricing from mid-tier converters in Paris clusters. |
| Direct-to-Consumer Platform Launch | Decorative presentation formats bypass wholesale bakery channels for home baking digitization. |
| Circular Fiber Recovery Partnership | Closed-loop systems align with EU Green Deal packaging circularity mandates for competitive advantage. |
| Custom Shape Fabrication Capacity | Laser-cut precision capabilities penetrate boutique catering white space in Lyon metropolitan demand. |
Study Parameters
Desk research of EU regulatory filings, food contact substance compliance databases, and Nordic pulp trade statistics preceded structured interviews with coating line engineers, artisan bakery procurement managers, wholesale distribution channel heads, and regulatory affairs specialists at packaging converters. Primary fieldwork across Benelux and northern France production corridors validated substrate transition timelines and cooperative purchasing consolidation patterns. Secondary triangulation incorporated customs data, FEFCO industry statistics, and EFSA migration testing protocols. Bottom-up volume estimates from individual converter capacity and top-down demand aggregation from bakery chain procurement data were reconciled through iterative cross-checking.
Variance decomposition across the projection horizon isolates segment-specific growth contributions from material substitution effects, regulatory compliance cost pass-through, and channel digitization velocity. Modeled dimensions span product type, material substrate, size bracket, and end-user channel, with additional stratification by certification tier and geographic production cluster. CAGRs were derived from normalized baseline penetration rates and elasticity-adjusted demand response functions. Key forecast inputs include REACH substance restriction implementation schedules and artisan bakery cooperative formation rates in French metropolitan markets.
Material uncertainties — pulp fiber cost volatility, regulatory enforcement intensity variations, and plastic substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about barrier coating adoption curves and cooperative procurement consolidation trajectories. Recalibration cycles align with material shifts in EU packaging waste regulation deadlines and substrate innovation qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Gluten-Free Baking Mixes Market
Bakery Products
North America Fortified Bakery Products Market
Bakery Products
Bread Crumbs Market
Bakery Products
Frosting, Toppings, and Decorations Market
Bakery Products
Vegan Certified Cake Mixes Market
Bakery Products
Dough Conveyor Market
Bakery Products
Sourdough Market
Bakery Products
Gluten-Free Bakery Premixes Market
Bakery Products
Specialty Bakery Market
Bakery Products
Low Calorie Flour Market
Bakery Products
Bread Improver Market
Bakery Products
Europe Sourdough Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
Oman Frozen Bakery Products Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Middle East and Africa Bakery Products Market