
 Roast to Order Coffee Market | 2026-2036
Roast to Order Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Roast to Order Coffee Market Analytics
Small-batch roaster capacity across the Pacific Northwest is rebalancing toward direct-to-consumer fulfillment models. Starbucks leverages its vertical integration from sourcing to retail to maintain freshness guarantees at scale. Blue Bottle Coffee sustains a premium position through exacting roast-to-ship timelines. Intelligentsia specializes in single-origin transparency protocols that anchor its wholesale relationships with independent cafés.
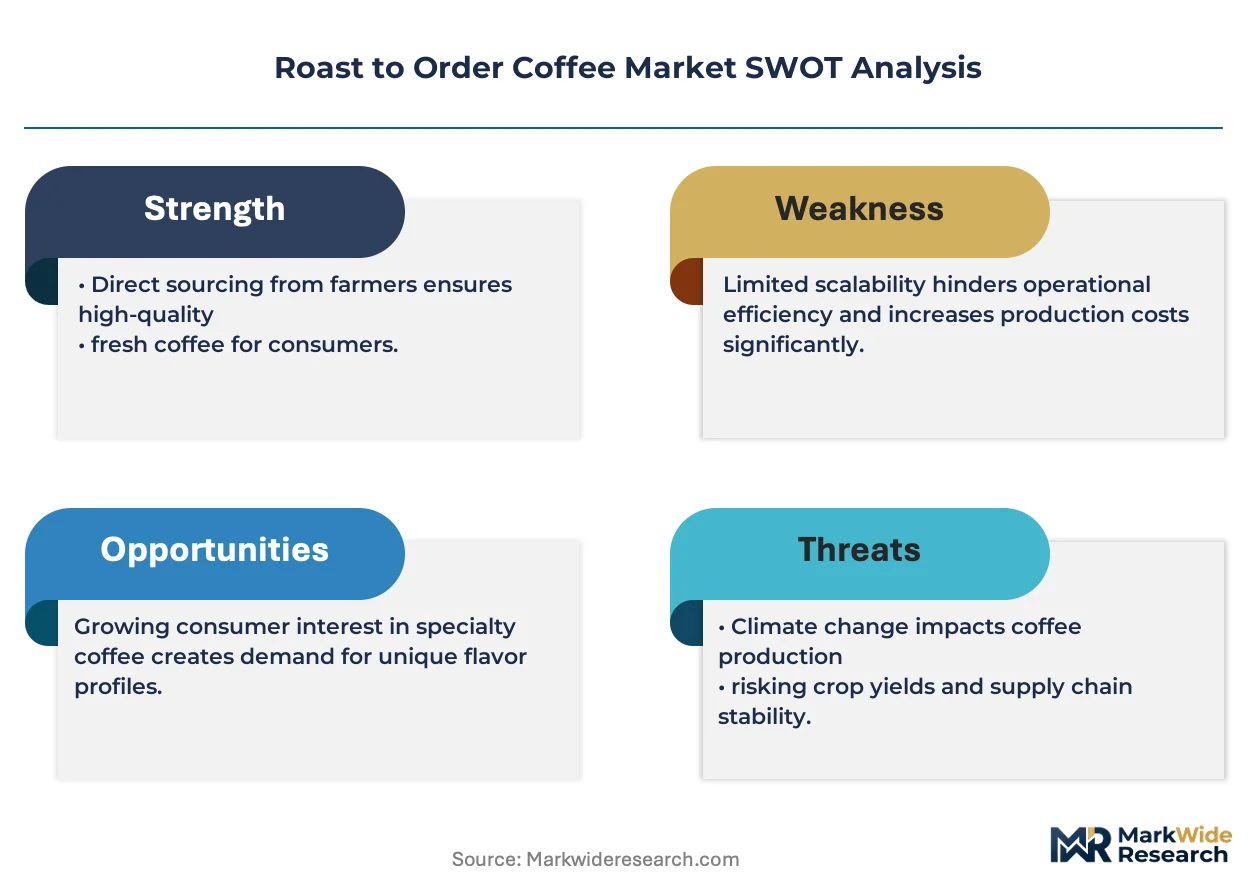
Roast to order coffee denotes beans roasted only after purchase confirmation, typically within 24-72 hours of fulfillment, preserving volatile aromatic compounds that degrade within 14 days of roasting. The primary commercial purpose centers on delivering peak flavor freshness that pre-packaged retail coffee cannot replicate. Whole beans command the dominant margin pool among product types, while pods represent the fastest-growing format as convenience-oriented households adopt compatible systems. Office catering channels are expanding fastest among customer types, though retail consumers still occupy the largest volume position.
FDA food safety regulations govern roasting facility standards and labeling requirements across the United States, while USDA organic certification shapes premium pricing tiers for certified roasters. The EU Green Deal's deforestation-free regulation and REACH chemical standards constrain European import sourcing and packaging material selection. Stakeholders must monitor how evolving carbon disclosure rules and single-use packaging bans in multiple jurisdictions will reshape fulfillment economics and last-mile delivery formats.
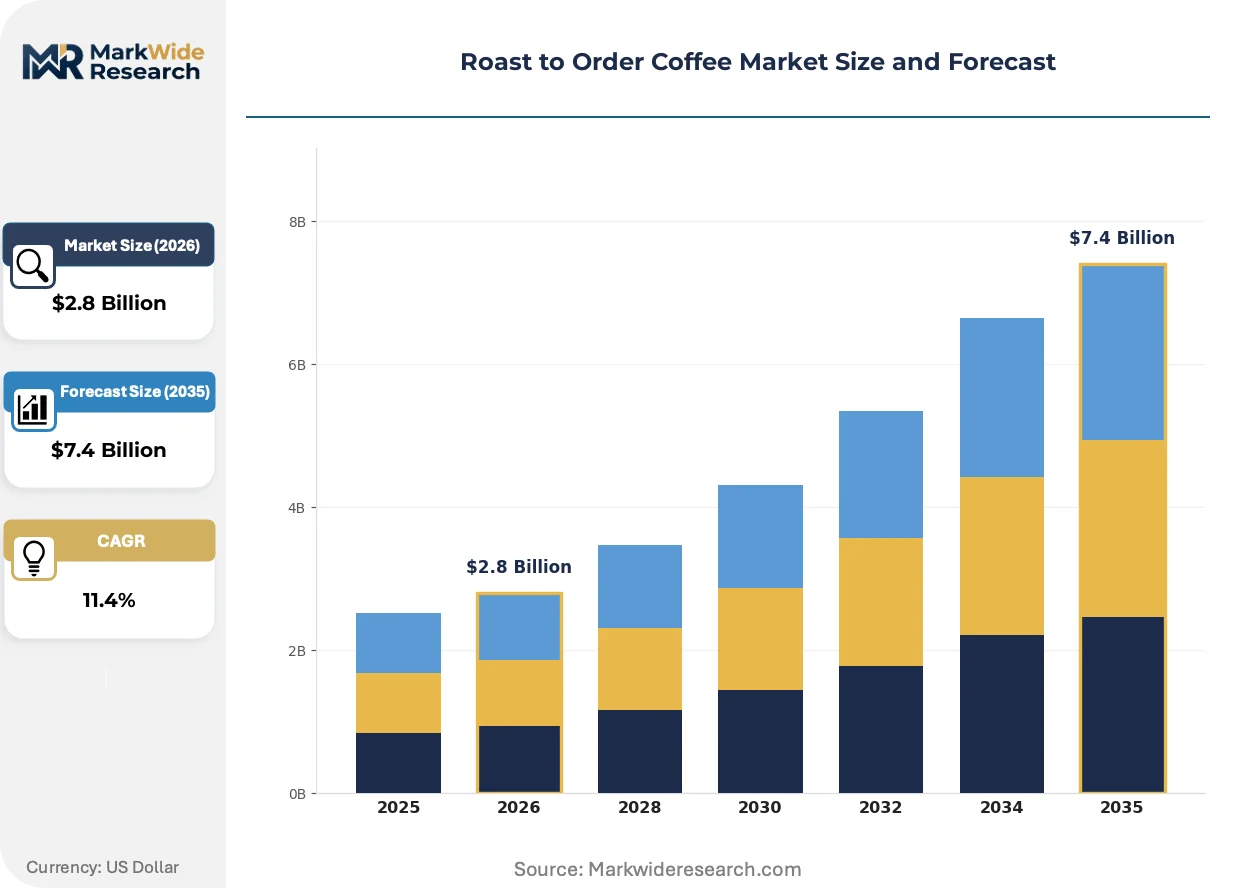
Market Dynamics
The EU Green Deal's deforestation-free supply chain mandates are forcing European roasters to rebuild sourcing protocols from origin to port, while Pacific Northwest urban clusters and Southern California micro-roasters accelerate direct-to-consumer fulfillment models that compress roast-to-door timelines.
Growth Catalysts
- Regulatory transparency mandates:The EU Green Deal's deforestation-free regulation requires batch-level traceability from farm to roaster, creating competitive advantage for operators with established origin relationships and blockchain-enabled provenance systems.
- Office catering channel expansion:Corporate food service providers across the United States are replacing commodity coffee contracts with roast-to-order programs that justify per-cup premiums through freshness guarantees and employee retention metrics.
- Pod format technology maturation:Compostable and aluminum-compatible pod systems are unlocking convenience-oriented households previously excluded by whole-bean preparation requirements, expanding addressable market depth.
Market Restraints
- Green coffee price volatility:Arabica futures on the Intercontinental Exchange subject small-batch roasters to margin compression that pre-packaged retail competitors hedge through forward contracts and inventory depth.
- Origin supply concentration:Brazilian and Colombian harvest disruptions from climate-induced flowering irregularities concentrate risk for roasters dependent on single-origin transparency protocols as a competitive differentiator.
- Last-mile freshness degradation:Volatile aromatic compound half-life of 14 days creates irreducible delivery window constraints that exclude rural and exurban geographies from economically viable service.
Strategic Opportunities
- Underpenetrated Southern California exurbs:Riverside and San Bernardino counties exhibit roast-to-order penetration gaps of 40-60% below Los Angeles basin levels, presenting first-mover expansion terrain for regional operators.
- USDA organic certification premium capture:Certified organic roast-to-order commands 25-35% price premiums in Pacific Northwest urban clusters, with certification backlogs creating temporary supply scarcity for qualified operators.
- Micro-fulfillment automation convergence:Integration of small-batch roasting equipment with automated packaging and dispatch systems enables 2-hour delivery windows in dense metropolitan cores.
Industry Challenges
- Roastmaster talent scarcity:Small-batch roasting requires sensory calibration skills developed over 3-5 years, with Pacific Northwest labor markets exhibiting vacancy rates exceeding specialty coffee industry averages.
- Multi-jurisdiction packaging compliance:Simultaneous adherence to FDA food contact substance regulations, California Proposition 65 labeling, and emerging single-use packaging bans fragments packaging procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roast to Order Coffee Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Beans, Ground Coffee, Pods, Instant Coffee Customer Type: Retail Consumers, Coffee Shops, Restaurants, Office Catering Distribution Channel: Online, Specialty Stores, Supermarkets, Direct Sales Roasting Level: Light Roast, Medium Roast, Dark Roast, Flavored |
| Companies Covered | Starbucks, Blue Bottle Coffee, Stumptown Coffee Roasters, Peet's Coffee, Driftaway Coffee, Verve Coffee Roasters, Wonderstate Coffee, Tony's Coffee, Intelligentsia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roast to Order Coffee Market Evolving Landscape
Electrification of roasting equipment, deforestation-free sourcing mandates, and direct-to-consumer fulfillment automation are converging to reshape capital deployment and competitive positioning across the value chain.
Fluid-bed electric roasting technology is electrifying thermal energy delivery in small-batch operations, replacing natural gas combustion systems with precision-controlled hot air streams. Artisan roasters in Portland and Seattle are adopting electric systems at 15-20% annual replacement rates. This technology is electrifying location flexibility by eliminating venting infrastructure requirements and enabling roasting operations in mixed-use retail spaces previously excluded by fire code restrictions.
REACH chemical standards and the EU Green Deal's deforestation-free regulation are tightening material and origin compliance burdens simultaneously. European roasters must now document that packaging adhesives and inks meet Substance of Very High Concern thresholds while proving coffee origins exclude deforested lands post-December 2020. German and Dutch import operations are responding by consolidating supplier relationships and investing in third-party audit infrastructure that smaller competitors cannot replicate.
Subscription-based replenishment models are displacing episodic retail purchasing among high-frequency coffee consumers. Direct-to-consumer channels are capturing volume previously routed through specialty grocery and café retail, with Southern California households showing highest adoption of flexible-frequency delivery algorithms. This behavioral shift concentrates most visibly in dual-income professional households across San Diego and Orange County metro areas.
Roast to Order Coffee Market Segmentation
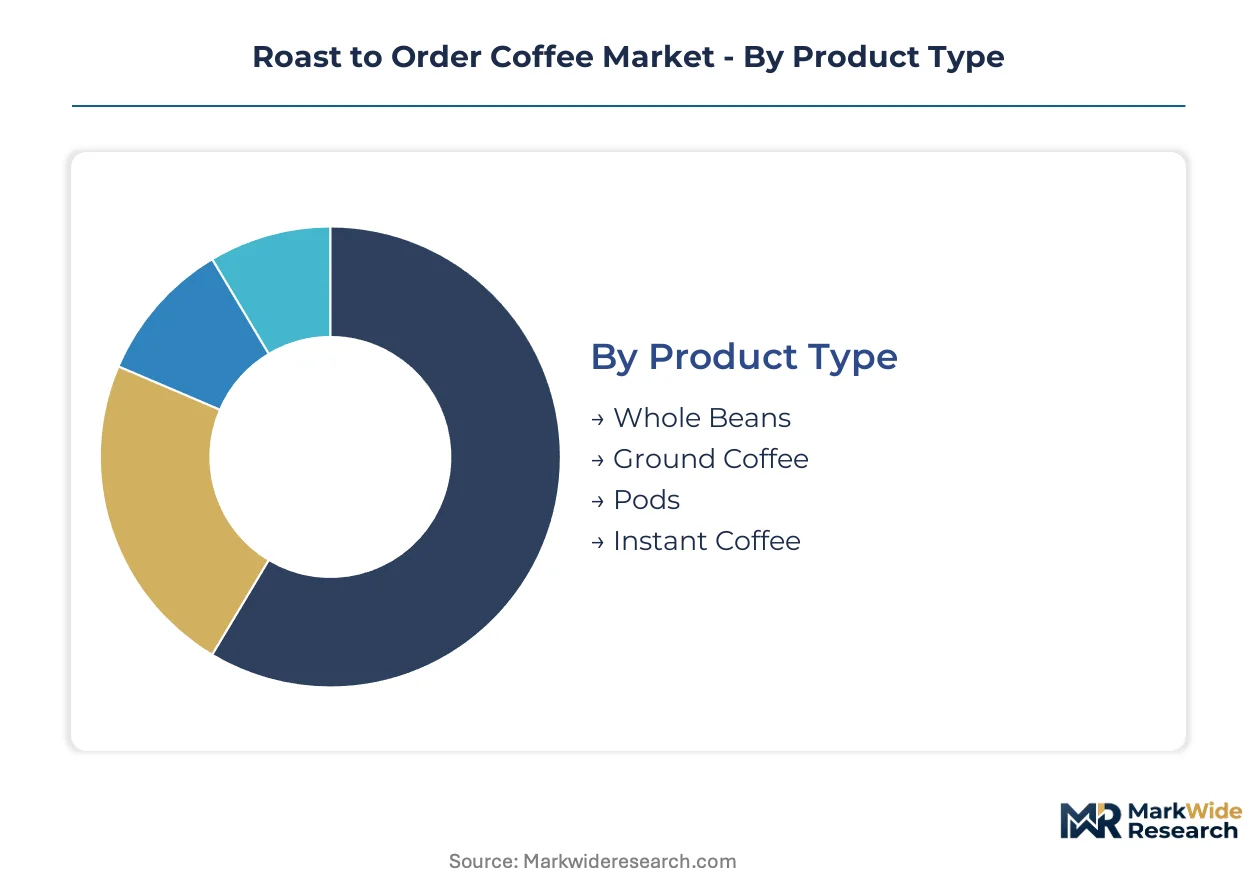
Roast-to-order operators configure production capacity around distinct consumption rituals and fulfillment constraints. Each segment demands different roast-to-ship timelines, packaging formats, and origin transparency protocols that reshape margin economics across the value chain.
Product Type:
Equipment upgrade cycles and packaging automation investments are rebalancing capacity allocation across physical formats, with whole-bean infrastructure requiring longer capital recovery horizons than pod-compatible systems.
- Whole Beans:Unprocessed roasted kernels preserve volatile aromatic compounds for 14 days post-roast, commanding premium positioning in Pacific Northwest urban clusters where sensory calibration drives repeat purchase. Independent cafés in Portland and Seattle anchor wholesale demand through single-origin transparency requirements.
- Pods:Pre-portioned aluminum or compostable capsules enable 2-hour fulfillment windows in dense metropolitan cores, with Southern California dual-income households adopting flexible-frequency replenishment algorithms fastest. Compostable systems unlock regulatory compliance in jurisdictions with emerging single-use packaging bans.
- Ground Coffee:Pre-milled format accelerates preparation for convenience-oriented segments, though accelerated oxidation limits roast-to-consumption windows.
- Instant Coffee:Soluble extract format occupies economy positioning, with minimal roast-to-order penetration due to extended shelf stability requirements.
Whole Beans sits at the top of the volume ranking, with Pods climbing the fastest.
Customer Type:
Procurement patterns diverge sharply between episodic retail purchasing and contracted corporate replenishment, with office catering channels demanding batch-level traceability documentation that retail consumers rarely request.
- Office Catering:Corporate food service providers across the United States are replacing commodity contracts with freshness-guaranteed programs, using employee retention metrics to justify per-cup premiums. San Diego and Orange County metro areas exhibit highest adoption of algorithmic replenishment scheduling.
- Coffee Shops:Independent cafés in the Pacific Northwest require roast-to-ship timelines under 72 hours to maintain single-origin transparency protocols that differentiate their retail proposition.
- Retail Consumers:Direct-to-capture volume concentrates in dual-income professional households, with subscription models displacing specialty grocery purchasing.
- Restaurants:Fine-dining establishments leverage origin documentation for menu storytelling, though volume per outlet remains below café and office channels.
Retail Consumers capture the largest absolute volume, while Office Catering gains share fastest through contract consolidation.
Distribution Channel:
Last-mile configuration determines freshness degradation exposure, with online fulfillment compressing roast-to-door timelines through micro-fulfillment automation in dense urban cores.
- Online:Direct-to-consumer platforms enable subscription-based replenishment with flexible-frequency algorithms, capturing volume previously routed through specialty grocery. Riverside and San Bernardino counties present expansion terrain with penetration gaps below Los Angeles basin levels.
- Direct Sales:Roaster-owned retail locations in mixed-use spaces exploit electric roasting technology to eliminate venting infrastructure requirements and enable on-site production.
- Specialty Stores:Curated retail environments emphasize sensory education and origin storytelling, supporting premium positioning.
- Supermarkets:Mass retail channel carries pre-packaged inventory with extended shelf life, limiting roast-to-order penetration due to freshness guarantee requirements.
Online leads channel volume, with Direct Sales expanding most quickly through retail-production integration.
Roasting Level:
Consumer palate evolution and third-wave coffee education are shifting demand toward lighter roast profiles that preserve origin-specific terroir characteristics, requiring recalibration of roasting equipment thermal profiles.
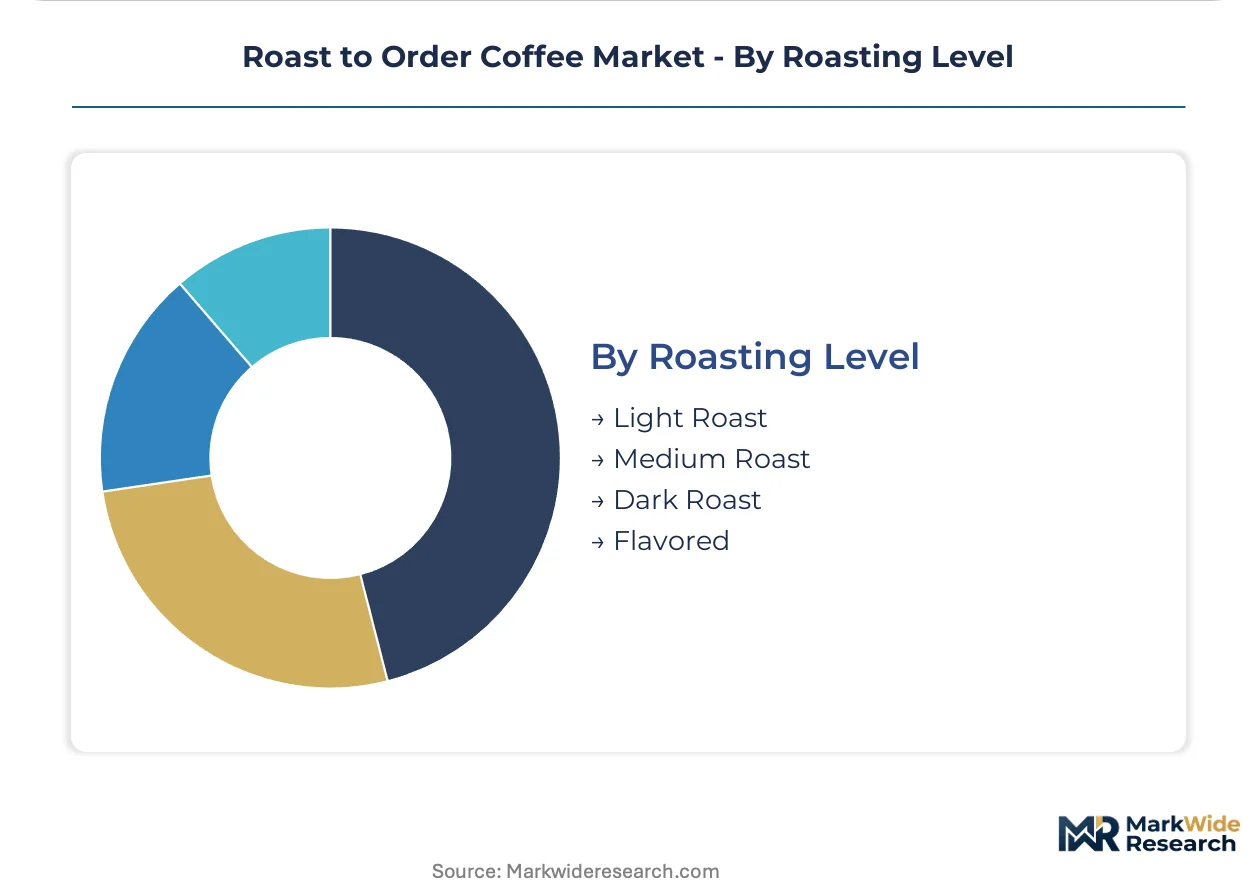
- Light Roast:Shortest roasting duration preserves acidic brightness and floral aromatics, dominating specialty café procurement in Seattle and Portland where sensory differentiation commands wholesale premiums.
- Medium Roast:Balanced development appeals to convenience-oriented households seeking approachable flavor profiles without preparation complexity.
- Dark Roast:Extended Maillard reaction produces bittersweet chocolate and caramel notes, retaining loyalty among traditional consumption segments.
- Flavored:Post-roast additive processing enables seasonal and novelty positioning, though volatile compound stability challenges freshness guarantees.
Light Roast holds the top volume position, with Medium Roast climbing fastest as convenience-oriented households enter the category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as European compliance costs push small-batch capacity toward North American markets with lighter traceability burdens. Roasters are relocating roasting operations to jurisdictions where FDA food safety standards impose lower documentation overhead than EU Green Deal deforestation-free mandates.
United States
Dual-income professional households in Southern California and the Pacific Northwest drive subscription adoption, with San Diego and Orange County metros showing highest algorithmic replenishment rates. FDA food safety regulations govern facility standards while USDA organic certification commands 25-35% price premiums in Seattle and Portland urban clusters. Micro-fulfillment automation in Los Angeles basin enables 2-hour delivery windows that Riverside and San Bernardino exurbs have yet to match.
Germany
Corporate food service providers in Berlin and Hamburg are replacing commodity contracts with freshness-guaranteed office catering programs. REACH chemical standards and EU Green Deal deforestation-free regulations force batch-level traceability documentation from farm to port. German import operations are consolidating supplier relationships and investing in third-party audit infrastructure that smaller competitors cannot replicate.
United Kingdom
Independent cafés in London and Manchester require roast-to-ship timelines under 72 hours to maintain single-origin transparency protocols. The UK's post-EU regulatory framework retains REACH-aligned chemical standards while diverging on deforestation enforcement timelines. Roasters in Bristol and Glasgow are adopting electric fluid-bed roasting technology to eliminate venting infrastructure and enable mixed-use retail production spaces.
Netherlands
Rotterdam port operations serve as European entry points for green coffee subject to EU Green Deal origin verification requirements. Dutch roasters face simultaneous compliance with REACH Substance of Very High Concern thresholds for packaging adhesives and deforestation-free land use documentation. Amsterdam specialty cafés are accelerating direct-to-consumer fulfillment models that compress roast-to-door timelines below 48 hours.
Japan
Convenience-oriented households in Tokyo and Osaka are adopting pod-compatible systems with compostable capsules that satisfy emerging single-use packaging restrictions. METI energy efficiency standards are accelerating electric roasting equipment adoption in small-batch operations. Third-wave coffee education in Fukuoka and Sapporo is shifting demand toward light roast profiles that preserve origin-specific terroir characteristics.
Roast to Order Coffee Market Competitive Landscape
Pacific Northwest producers anchor the premium freshness tier; Southern California specialists hold convenience-oriented subscription share. The vendor base separates into three structural tiers: vertically integrated giants with captive sourcing networks, mid-scale regional roasters with direct-to-consumer automation, and micro-roasters with retail-production integration. Competitive moves concentrate on micro-fulfillment automation deployment and USDA organic certification backlog capture.
Within the vertically integrated tier, Starbucks exemplifies scale-driven freshness guarantees through captive sourcing-to-retail control. Blue Bottle Coffee and Intelligentsia occupy positions defined by exacting roast-to-ship timelines and single-origin transparency protocols respectively. These three anchors demonstrate how backward integration into green coffee procurement and roasting capacity ownership separate premium positioning from commodity competition.
| Leading Market Players |
|---|
| Starbucks |
| Blue Bottle Coffee |
| Stumptown Coffee Roasters |
| Peet's Coffee |
| Driftaway Coffee |
| Verve Coffee Roasters |
| Wonderstate Coffee |
| Tony's Coffee |
| Intelligentsia |
| Others |
Value Network & Pricing Analysis
Certification-ladder divergence between USDA organic and conventional tiers manifests in both Pacific Northwest premium capture and sourcing protocol complexity. EU Green Deal deforestation-free mandates impose documentation overhead that compresses margins for European operators while creating arbitrage opportunities for North American roasters with lighter traceability burdens.
Pricing Analysis
Direct-to-consumer channels bypass distributor markups that wholesale café relationships absorb, enabling roast-to-order operators to retain 25-35% organic certification premiums in Seattle and Portland urban clusters. Three-tier pricing structure across premium single-origin, standard blended, and economy private-label levels differentiates by origin transparency depth and roast-to-ship velocity. Pricing pressure stems from Arabica futures volatility on the Intercontinental Exchange, which small-batch roasters cannot hedge like pre-packaged retail competitors. Office catering buyers exhibit lowest price sensitivity due to employee retention justification metrics, while supermarket procurement teams demand volume discounts that erode freshness guarantees.
Supply Chain Analysis
Direct-to-roaster channels from Brazilian and Colombian origin markets handle specialty-grade Arabica procurement for transparency-protocol operators, with Ethiopian and Guatemalan micro-lots serving single-origin differentiation. Green coffee sourcing draws from harvests vulnerable to climate-induced flowering irregularities, while compostable pod packaging feeds from EU REACH-compliant adhesive suppliers. Supply chain risk centers on single-origin concentration for roasters dependent on farm-level traceability as competitive positioning. Distribution runs through micro-fulfillment nodes in Los Angeles basin and Pacific Northwest urban cores, with electric roasting equipment enabling mixed-use retail production spaces previously excluded by venting infrastructure requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in roast-to-order coffee rests on electrification-driven facility cost reduction and algorithmic subscription retention that lengthens customer lifetime value. Premium-tier shift toward light-roast single-origin protocols commands wholesale pricing power with independent cafés.
For Market Incumbents: Deepen backward integration into green coffee procurement to secure origin relationships before EU Green Deal consolidation accelerates. Invest in electric fluid-bed roasting capacity in Portland and Seattle to eliminate venting infrastructure costs and accelerate mixed-use retail deployment. Capture USDA organic certification backlog scarcity before qualified competitor supply catches Pacific Northwest demand. For New Entrants and Emerging Players: Corporate food service providers in San Diego and Orange County metros represent the most penetrable channel, with algorithmic replenishment scheduling adoption outpacing Los Angeles basin saturation. Target Riverside and San Bernardino exurbs where roast-to-order penetration gaps of 40-60% below basin levels create first-mover terrain. Launch with compostable pod-compatible systems that satisfy emerging single-use packaging restrictions while unlocking convenience-oriented household expansion. For Investors and Strategic Acquirers: Consolidation pressure builds where EU Green Deal compliance costs exceed smaller European roaster capital reserves, creating distressed acquisition opportunities with established origin audit infrastructure. Mid-scale regional operators with direct-to-consumer automation and captive subscription algorithms present the strongest long-term viability framing. Watch electric roasting equipment adoption rates as inflection indicator for location-flexibility competitive advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Automation Deployment | Enables 2-hour delivery windows in Los Angeles basin through roasting-packaging-dispatch integration. |
| USDA Organic Certification Investment | Captures 25-35% price premiums in Seattle and Portland while creating temporary supply scarcity. |
| Electric Roasting Equipment Conversion | Eliminates venting infrastructure requirements and enables mixed-use retail production spaces in dense urban cores. |
| Deforestation-Free Sourcing Protocol | Satisfies EU Green Deal batch-level traceability mandates that reshape European competitive positioning. |
| Subscription Algorithm Development | Retains dual-income professional households in Southern California through flexible-frequency replenishment scheduling. |
Research Methodology
Direct dialogue with roastmaster operators, specialty café procurement managers, corporate food service directors, and green coffee import specialists grounded qualitative findings in operational practice. Secondary validation drew from FDA food safety guidance documents, USDA organic certification databases, EU Green Deal regulatory filings, and Intercontinental Exchange Arabica futures data. Bottom-up volume estimates from roasting equipment capacity and subscription platform transaction patterns triangulated against top-down category spending benchmarks from retail audit sources.
Bottom-up modeling aggregated individual roaster capacity, subscription cohort retention curves, and channel mix assumptions across the projection horizon. Segmentation dimensions included product type, customer archetype, distribution channel, and roasting level, with regional regulatory clusters capturing EU Green Deal, FDA, and METI compliance variations. CAGRs derived from fitted growth curves applied to base-year volume estimates, with electric equipment replacement rates and pod format adoption curves serving as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Arabica price volatility, climate-induced origin harvest disruption, and single-use packaging ban jurisdictional expansion. Outputs reflect documented assumptions regarding subscription retention algorithms and electrification capital deployment timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
United Arab Emirates Coffee Roaster Market
Coffee
Drip Coffee Machine Market
Coffee
Espresso Powder Market
Coffee
Coffee Cherry Market
Coffee
Nitrogenated Coffee Market
Coffee
Coffee Syrup Market
Coffee
Portable Espresso Machines Market
Coffee
Coffee Bottle Market
Coffee
Thailand Coffee and Tea Capsules Market
Coffee
India Coffee Roaster Market
Coffee
GCC Instant Coffee Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Germany Coffee Market
Coffee
Asia Pacific Coffee Market
Coffee
Japan Coffee and Tea Capsules Market
Coffee
North America Specialty Coffee Market