
 Qatar Bakery Product Market | 2026-2036
Qatar Bakery Product Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Bakery Product Market Analytics
Qatar's Ministry of Public Health food safety modernization is pivoting bakery manufacturers toward reformulated recipes and cleaner-label portfolios. Qbake leverages its captive flour milling capacity to sustain cost advantages across bread and pastry lines. Yasmeen Sweets differentiates through heritage positioning in Arabic confectionery and celebration cakes. Mondelez International anchors the premium biscuit and snacking segment through controlled modern trade shelf space.
Qatar bakery products comprise wheat-based and alternative-grain formulations produced through mechanical mixing, fermentation, baking, and post-bake finishing processes, serving daily consumption, ceremonial, and food service needs. Breads dominate volume throughput given staple consumption patterns, while pastries capture widening margin pools from café culture proliferation. Eco-friendly packaging is accelerating fastest among packaging type categories as retail chains impose plastic-reduction mandates on suppliers.
MOHAP enforces HACCP-aligned facility licensing and periodic ingredient traceability audits that elevate compliance costs for smaller bakeries. The Qatar Standards body mandates nutritional labeling and shelf-life validation that favor centralized production over artisan micro-bakeries. Stakeholders must monitor how upcoming municipal sustainability targets reshape packaging procurement rules and production site energy requirements.
Market Dynamics
Qatar's hospitality procurement transformation is restructuring bakery demand as hotel and food service operators consolidate supplier relationships toward centralized production capable of meeting volume and compliance thresholds simultaneously.
Growth Catalysts
- Tourism Infrastructure Expansion:New hotel and entertainment venue construction across Lusail and The Pearl is generating institutional procurement contracts for artisan and convenience bakery categories. Food service operators prioritize suppliers with HACCP-aligned certifications.
- MOHAP Nutritional Labeling Mandates:Mandatory shelf-life validation and ingredient disclosure requirements are accelerating consolidation toward industrial-scale bakeries with laboratory testing capabilities and centralized quality systems.
- Flour Milling Integration:Captive wheat processing capacity within major production groups is compressing input cost volatility and securing supply continuity for bread and pastry lines.
Market Restraints
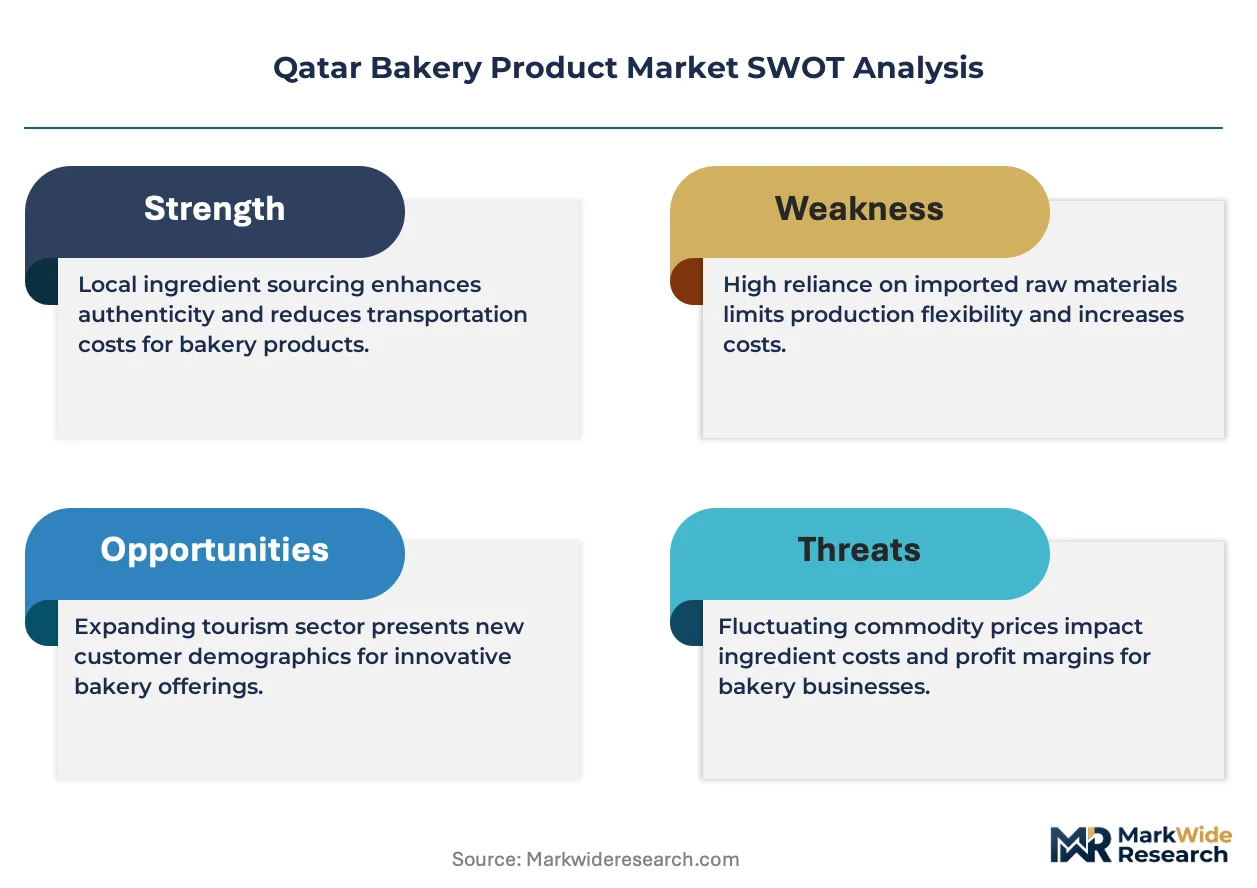
- Import Dependency for Specialty Ingredients:Premium chocolate, dried fruits, and functional additives rely on European and Asian suppliers, exposing margins to freight rate fluctuations and currency shifts.
- Energy-Intensive Production Costs:Industrial ovens and climate-controlled fermentation rooms consume substantial electricity, with tariff structures from Kahramaa directly affecting unit economics at scale.
- Limited Domestic Wheat Cultivation:Qatar's arid climate necessitates near-total reliance on imported grain, constraining backward integration opportunities and creating price pass-through exposure to Black Sea and Australian harvest cycles.
Strategic Opportunities
- Al Wakrah Industrial Zone Expansion:Underutilized logistics and production space south of Doha offers relocation potential for bakeries seeking larger facilities with improved port and highway connectivity.
- Eco-Friendly Packaging Transition:Retail chains including Lulu and Carrefour Qatar are imposing plastic-reduction procurement rules, creating first-mover advantage for suppliers with compostable or fiber-based packaging solutions.
- Heritage Positioning in Arabic Confectionery:Celebration cake and date-based product segments remain underdeveloped relative to European-style offerings, presenting differentiation space through localized formulation and cultural narrative.
Industry Challenges
- Skilled Artisan Labor Scarcity:Traditional Arabic pastry techniques and laminated dough craftsmanship require specialized training, with limited local culinary education pathways forcing reliance on expatriate recruitment.
- Compliance Timeline Compression:MOHAP facility licensing and periodic traceability audit cycles demand dedicated quality personnel and documentation systems that strain smaller operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Bakery Product Market |
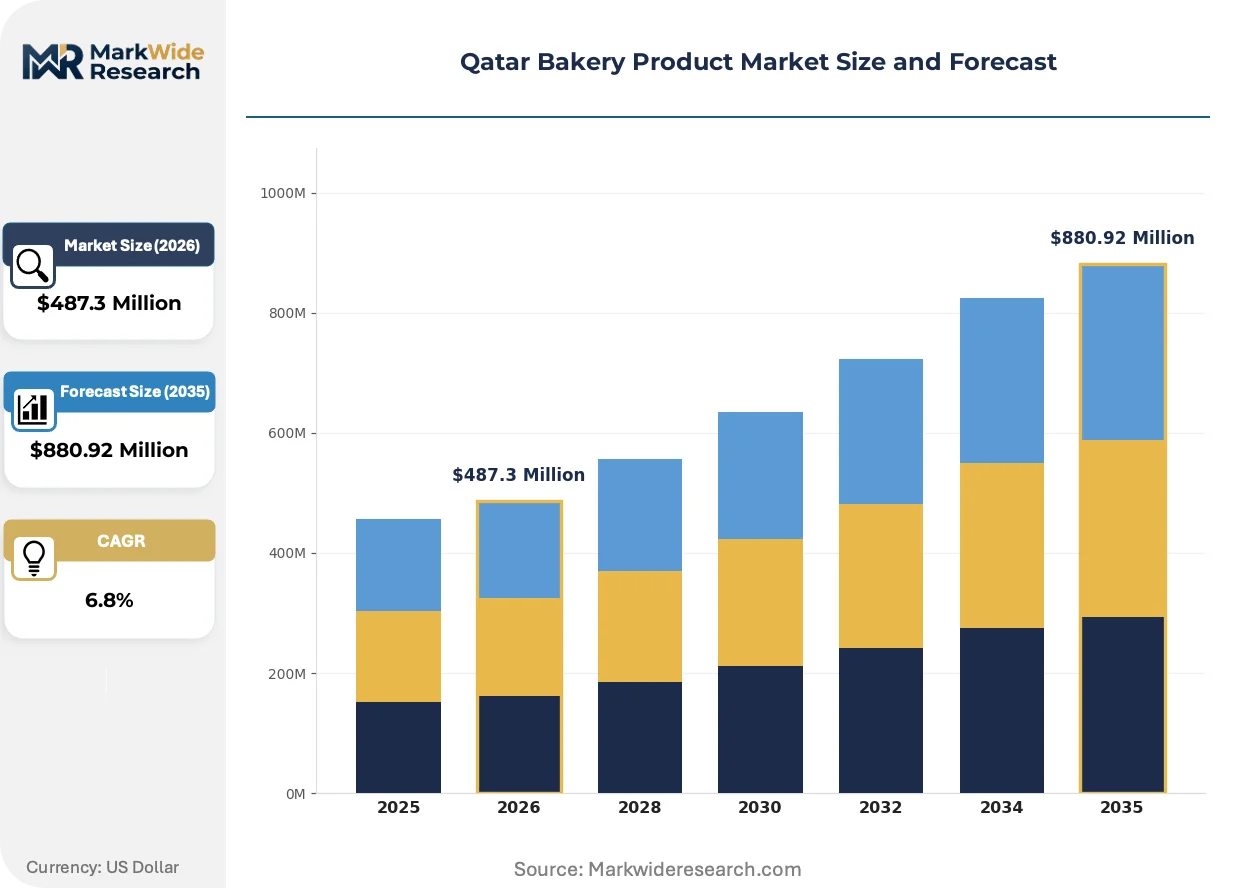
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Pastries, Cakes, Confectionery Distribution Channel: Supermarkets, Online Retail, Grocery Stores, Specialty Shops End User: Households, Restaurants, Cafes, Catering Services Packaging Type: Bags, Boxes, Trays, Eco-friendly Packaging |
| Companies Covered | Wadia Group, Ummsaid Bakery, Korean Bakeries WLL, IFFCO, Valeo Foods Group, Yasmeen Sweets, Kellanov, Qbake (Qatar Flour Mills Co.), Mondelez International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Bakery Product Market Evolving Landscape
Production technology and procurement specifications are converging to reshape how bakery products reach Qatari consumers, with regulatory pressure and channel evolution acting as simultaneous accelerants.
Automated dough handling and continuous mixing systems are decentralizing production geography within Qatar's bakery sector. Industrial equipment suppliers are deploying modular lines that reduce minimum efficient scale, enabling medium-capacity facilities in Al Rayyan and Umm Salal to compete with Doha-centric operations. This compression of scale economics is fragmenting supply concentration and creating regional distribution nodes closer to retail endpoints.
MOHAP's alignment with Codex Alimentarius standards for food additive limits and contaminant thresholds is elevating reformulation requirements across bread and biscuit categories. Manufacturers must validate alternative emulsifiers and preservatives to maintain shelf stability under stricter maximum residue limits. Premium positioned brands are responding fastest, using compliance as a marketing differentiator in modern trade channels.
Café culture proliferation is altering consumption occasion patterns and procurement specifications for pastries and portion-controlled items. Food service buyers are unbundling frozen dough supply from finished goods, investing in in-store baking capabilities to emphasize freshness signaling. This channel shift is most visible in Doha's West Bay and Msheireb districts, where hospitality operators prioritize thaw-and-bake solutions over fully finished deliveries.
Qatar Bakery Product Market Segmentation
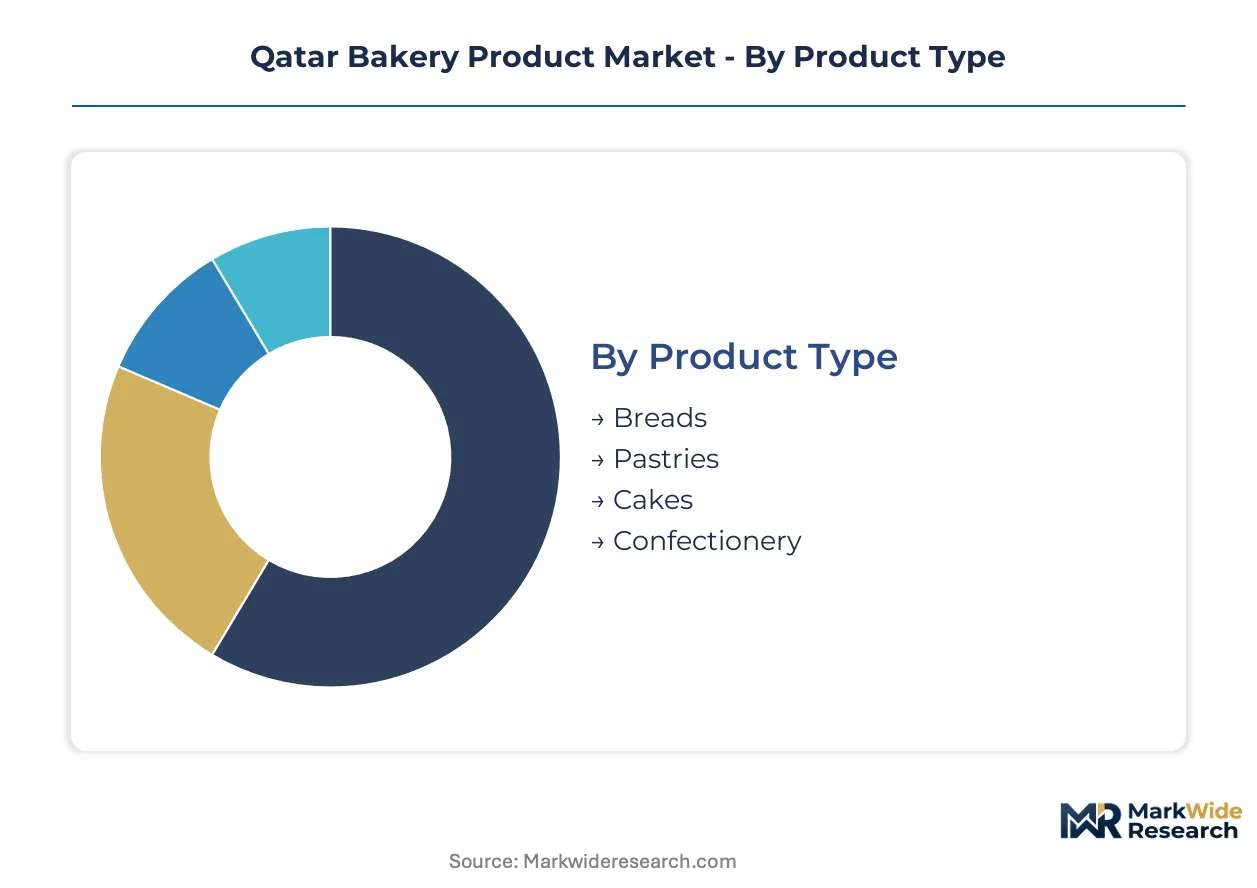
Qatar's bakery product segmentation reveals how procurement specifications diverge across hospitality, retail, and household channels. Understanding these splits enables suppliers to align production scale and compliance investments with actual demand concentration.
Product Type:
Households prioritize daily staple availability and price stability, while hospitality operators weight consistency and shelf-life validation more heavily.
- Breads:Wheat-based loaves and flatbreads dominate production throughput given Qatar's reliance on imported grain. Daily consumption patterns in Doha and Al Rayyan sustain high-volume contracts with centralized industrial bakeries holding HACCP-aligned certifications.
- Pastries:Croissants, danishes, and laminated dough items capture widening margin pools from café culture proliferation in West Bay and Msheireb. Food service buyers increasingly specify thaw-and-bake formats to emphasize freshness signaling.
- Cakes:Celebration and ceremonial segments concentrate demand around Ramadan and wedding seasons, with heritage positioning in Arabic confectionery gaining traction against European-style offerings.
- Confectionery:Biscuits and snacking items anchor modern trade shelf space, with premium positioning dependent on controlled distribution through Carrefour Qatar and Lulu hypermarkets.
Volume sits with Breads; growth tilts toward Pastries.
Distribution Channel:
Channel selection directly determines packaging specifications and compliance documentation requirements for bakery suppliers.
- Supermarkets:Carrefour Qatar and Lulu impose plastic-reduction procurement mandates that favor suppliers with compostable packaging solutions. Nutritional labeling validation and shelf-life documentation are non-negotiable entry requirements.
- Online Retail:Delivery platforms prioritize portion-controlled and ambient-stable formats suited to last-mile logistics in Doha's dense residential zones. Packaging integrity during summer heat exposure remains a technical constraint.
- Grocery Stores:Neighborhood retailers in Al Wakrah and Umm Salal concentrate bread and basic pastry demand, with price sensitivity limiting premium product penetration.
- Specialty Shops:Artisan micro-bakeries in The Pearl and Souq Waqif precincts emphasize heritage narrative and in-store production visibility, though MOHAP compliance costs constrain expansion.
Supermarkets command volume throughput; Online Retail is climbing the fastest.
End User:
End-use segmentation separates commodity procurement from specification-driven contract opportunities.
- Households:Daily bread consumption drives staple purchasing with limited brand loyalty, though nutritional awareness is shifting preferences toward cleaner-label portfolios.
- Restaurants:Hotel and fine-dining operators in Lusail and The Pearl consolidate supplier relationships toward centralized production capable of meeting volume and compliance thresholds simultaneously.
- Cafes:Thaw-and-bake solutions are displacing fully finished deliveries as operators invest in in-store baking capabilities for freshness differentiation.
- Catering Services:Large-scale event provision around sports and entertainment venues demands batch consistency and traceability documentation for MOHAP audit readiness.
Households absorb baseline volume; Cafes are gaining share fastest.
Packaging Type:
Packaging procurement is reshaping supplier qualification criteria as retail chains enforce sustainability mandates.
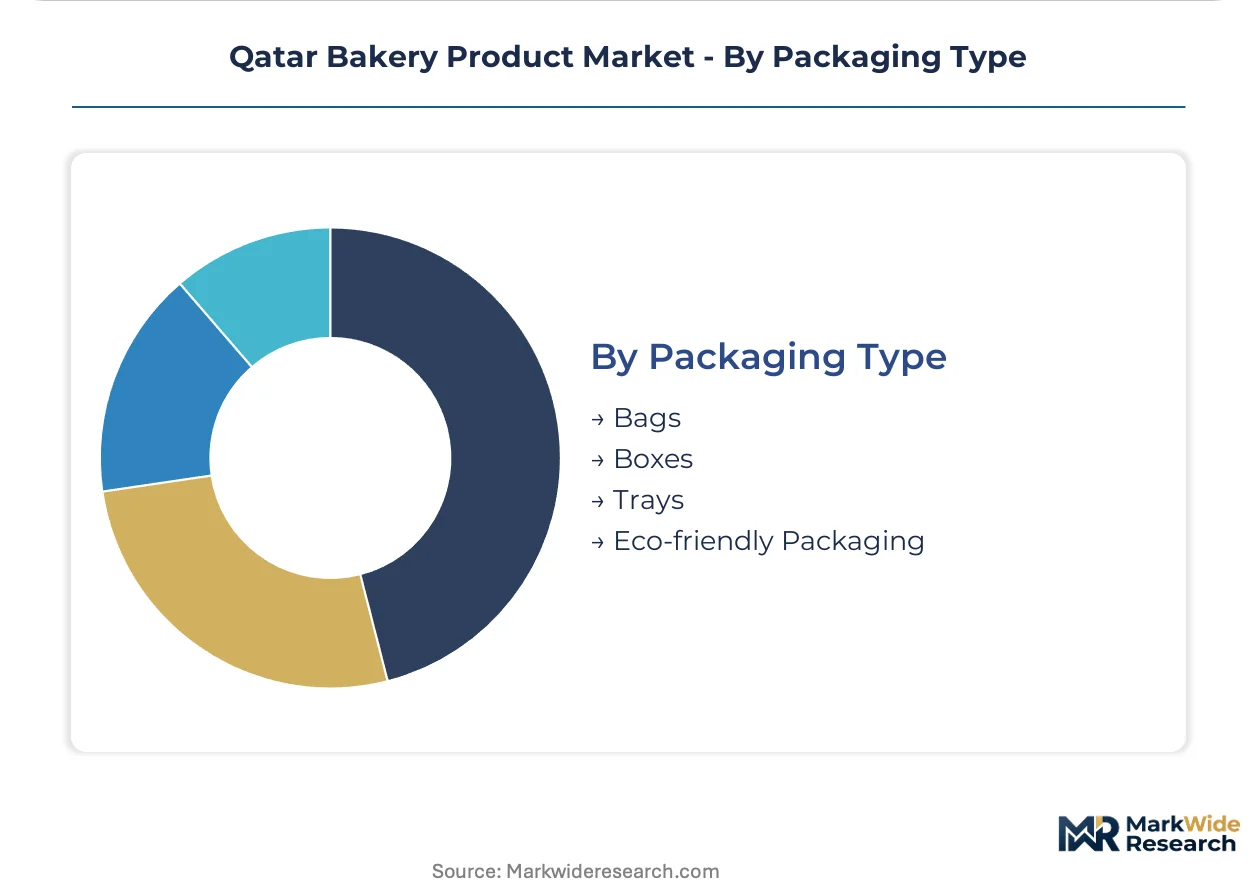
- Bags:Polyethylene and paper-based bread bags remain standard for high-volume retail distribution, though thickness reductions are accelerating under retailer pressure.
- Boxes:Rigid packaging for cakes and premium confectionery requires structural integrity for display aesthetics in modern trade environments.
- Trays:Vacuum-formed and pressed pulp formats serve pastry and portion-controlled items, with fiber-based alternatives gaining preference in hospitality procurement.
- Eco-friendly Packaging:Compostable films and molded fiber solutions are expanding most quickly as Lulu and Carrefour Qatar impose plastic-reduction timelines on supplier contracts.
Conventional formats hold current volume; Eco-friendly Packaging shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Doha and its surrounding industrial zones concentrate Qatar's bakery production capacity, with Al Wakrah and Umm Salal emerging as secondary nodes for regional distribution.
Doha Metropolitan Area
West Bay and Msheireb hospitality clusters drive demand for thaw-and-bake pastry solutions and premium confectionery. MOHAP enforces HACCP-aligned facility licensing that favors centralized bakeries with laboratory testing capabilities. Industrial bakeries in Doha's food manufacturing districts supply volume bread contracts to Lulu and Carrefour Qatar under strict nutritional labeling mandates.
Al Wakrah Industrial Zone
Underutilized logistics space south of Doha attracts bakeries seeking larger facilities with improved port connectivity for specialty ingredient imports. The zone offers relocation potential for operations needing expanded cold storage and highway distribution access. Manufacturers here serve growing retail demand in southern Doha residential corridors.
Umm Salal
Neighborhood grocery retailers in this northern municipality concentrate basic bread and pastry demand with pronounced price sensitivity. Local distributors route lower-margin staple products through independent stores competing on proximity rather than premium positioning. The area functions as a volume absorption zone for standardized bakery outputs.
Lusail Development
New hotel and entertainment venue construction generates institutional procurement contracts for artisan and convenience bakery categories. Food service operators in this emerging district prioritize suppliers with validated shelf-life documentation and batch traceability systems. The development extends hospitality-driven demand northward from central Doha.
The Pearl and Al Daayen
High-end residential and tourism precincts sustain specialty shop demand for heritage-positioned Arabic confectionery and celebration cakes. Artisan micro-bakeries emphasize in-store production visibility, though MOHAP compliance costs constrain expansion beyond niche positioning. Ramadan and wedding seasons concentrate ceremonial purchasing in these affluent catchments.
Qatar Bakery Product Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance capability and channel access. The market structures around three tiers: flour-integrated industrial groups with captive milling, international brand licensors controlling modern trade shelf space, and heritage-positioned local specialists in ceremonial segments. Consolidation pressures favor centralized production with laboratory testing and traceability documentation. Strategic moves cluster toward packaging sustainability transitions and hospitality procurement consolidation.
Within the integrated-production tier, Qbake anchors cost-advantaged positioning through captive flour milling capacity. Yasmeen Sweets exemplifies heritage-driven differentiation in Arabic confectionery and celebration cake segments. Mondelez International occupies the premium biscuit and snacking vector through controlled modern trade distribution. These three represent distinct competitive archetypes: upstream-integrated volume producer, culturally anchored specialty player, and multinational brand licensor.
| Leading Market Players |
|---|
| Wadia Group |
| Ummsaid Bakery |
| Korean Bakeries WLL |
| IFFCO |
| Valeo Foods Group |
| Yasmeen Sweets |
| Kellanov |
| Qbake (Qatar Flour Mills Co.) |
| Mondelez International |
| Others |
Value Network & Pricing Analysis
Hospitality procurement consolidation in Lusail and The Pearl is compressing supplier margins toward contract-based pricing with volume-commitment tiers. This buyer concentration rewards industrial-scale bakeries with captive flour milling and laboratory testing capabilities, while artisan micro-bakeries face exclusion from institutional contracts.
Pricing Analysis
Outcome-based pricing tied to shelf-life validation and batch consistency anchors hospitality procurement contracts. Pricing stratifies across premium heritage-positioned confectionery, standard industrial bread lines, and economy grocery-store staples. Cost compression in economy tiers is intensifying because of energy tariff pressure from Kahramaa and wheat import price volatility. Households in Umm Salal and Al Wakrah show highest price sensitivity, while hotel operators in West Bay prioritize compliance documentation over unit cost.
Supply Chain Analysis
HACCP-aligned facility licensing and MOHAP traceability audits are gating supplier qualification, favoring centralized production with in-house quality systems. Wheat sourcing draws from Australia, Ukraine, and Canada, with near-total import dependency constraining backward integration. Specialty ingredients—premium chocolate, dried fruits, functional additives—feed from European and Asian suppliers, exposing margins to freight rate fluctuations. Distribution runs through Doha-centric industrial zones with emerging nodes in Al Wakrah for southern corridor coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's bakery sector is becoming a vertical-integration race as flour milling capacity and captive cold storage emerge as decisive cost levers. Players securing upstream control over wheat processing and downstream control over hospitality distribution are consolidating procurement relationships fastest.
For Market Incumbents: Cement cost advantages by expanding captive milling capacity and securing long-term wheat supply agreements with Black Sea and Australian exporters. Defend against artisan competitors by investing in automated dough handling systems that reduce per-unit labor costs while maintaining MOHAP compliance documentation. Channel control through direct contracts with Lusail hotel operators represents the critical defensive perimeter.
For New Entrants and Emerging Players: Heritage-positioned Arabic confectionery in The Pearl and Al Daayen offers the most penetrable white space, with celebration cake demand concentrated around Ramadan and wedding seasons. Target thaw-and-bake pastry supply to café operators in Msheireb and West Bay seeking freshness differentiation without in-house laminated dough expertise. A go-to-market angle emphasizing compostable packaging compliance ahead of Lulu and Carrefour Qatar mandates unlocks modern trade shelf access.
For Investors and Strategic Acquirers: The window for entry favors industrial-scale bakeries with laboratory testing capabilities and HACCP-aligned certifications that hospitality procurement consolidation is screening for. Long-term viability hinges on exposure to tourism infrastructure expansion rather than household staple commoditization. Watch for municipal sustainability targets tightening packaging procurement rules as the signal for accelerated eco-friendly transition investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flour Milling | Captive wheat processing compresses input cost volatility for Qbake and integrated groups. |
| Eco-Friendly Packaging Transition | Compostable solutions unlock Lulu and Carrefour Qatar procurement contracts ahead of plastic-reduction deadlines. |
| Hospitality Distribution Consolidation | Direct contracts with Lusail hotel operators secure volume throughput and compliance-premium pricing. |
| Heritage Brand Positioning | Arabic confectionery narrative differentiation protects margin pools in The Pearl and Al Daayen catchments. |
| Automated Production Scale-Up | Modular dough handling lines enable Al Rayyan and Umm Salal facilities to compete with Doha-centric operations. |
Research Methodology
Document review covered Qatar Standards nutritional labeling protocols, MOHAP HACCP facility licensing requirements, and customs trade data on wheat and specialty ingredient imports, complemented by interviews with industrial bakery operations managers, hospitality procurement directors at Lusail hotel developments, retail category buyers at Lulu and Carrefour Qatar, and flour milling supply chain planners. Secondary validation drew from Kahramaa electricity tariff disclosures, tourism infrastructure project databases, and Codex Alimentarius additive limit standards. Bottom-up production capacity assessments and top-down hospitality procurement spend estimates were triangulated to anchor market sizing.
Segmentation outputs across product type, distribution channel, end user, and packaging format were modeled over the projection horizon using elasticity-adjusted volume projections and value-per-unit assumptions derived from channel-specific margin structures. CAGRs were computed from log-linear trend fitting across the analysis window, with growth rates stress-tested against Qatar's tourism arrival forecasts and food service operator expansion timelines. Wheat import price volatility and energy tariff trajectories served as key sensitivity inputs.
Revisions become necessary when MOHAP implements stricter contaminant thresholds or when municipal sustainability mandates accelerate packaging procurement rule changes. Forecasts reflect assumptions about continued hospitality infrastructure investment and stable Black Sea wheat supply corridors. A model refresh is warranted upon material change in Kahramaa industrial electricity tariff structures or Qatar's grain import sourcing patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Gluten-Free Bakery Premixes Market
Bakery Products
Pastries Market
Bakery Products
Diabetic Bakery Products Market
Bakery Products
Low Calorie Flour Market
Bakery Products
Bakery Emulsions Market
Bakery Products
Gluten-Free Bread Market
Bakery Products
Low Fat Bran Muffins Market
Bakery Products
Low-Calorie Pie Market
Bakery Products
Baking Mix, Base and Concentrate Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
Europe Sweet Biscuits Market
Bakery Products
Frozen Bakery Products Market
Bakery Products
Bakers Yeast Market
Bakery Products
US Retail Packaged Bread Market
Bakery Products
United States Cookies Market
Bakery Products
Bread Market