
 Bakers Yeast Market | 2026-2036
Bakers Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Bakers Yeast Market Analysis
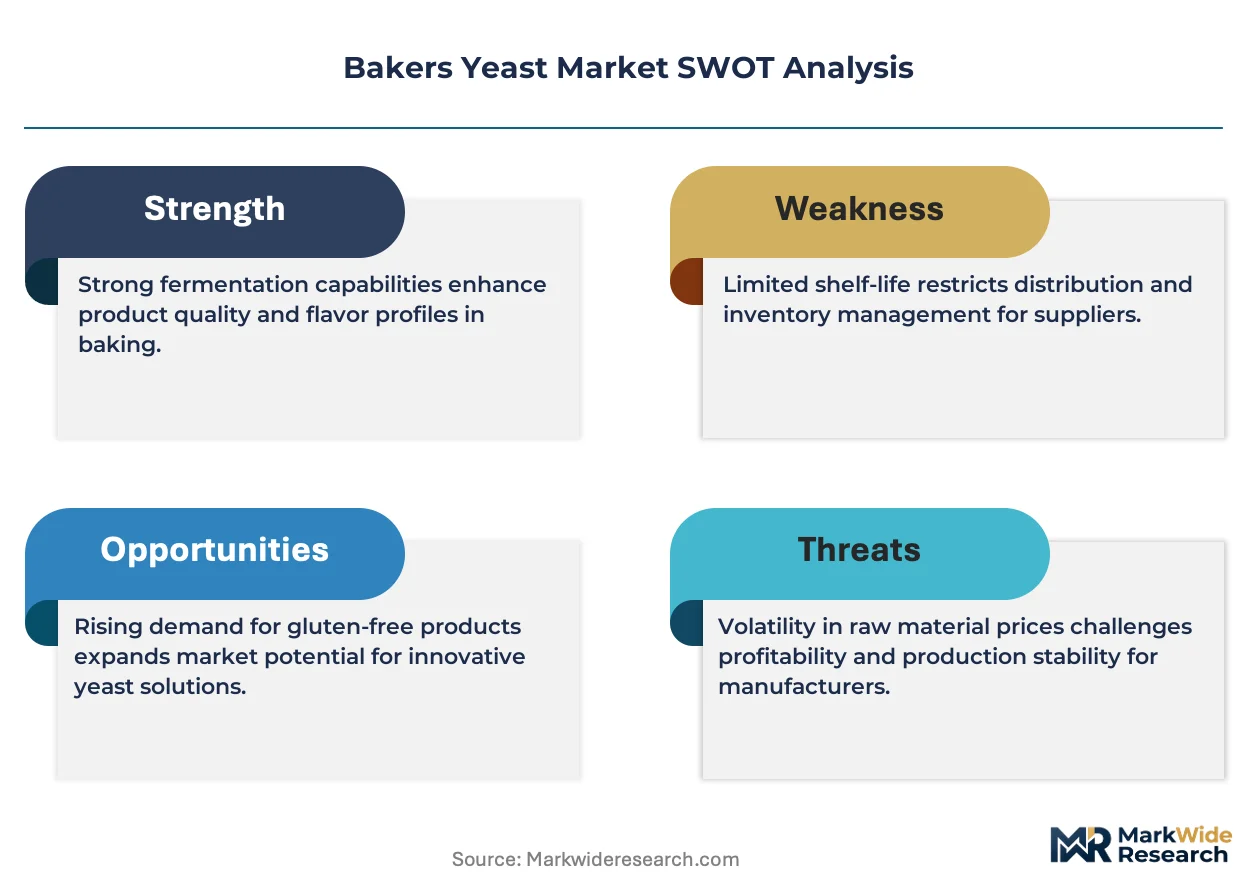
Subscription-based technical service and fermentation optimization support is hardening into a core revenue layer alongside commodity yeast sales. Lesaffre International leverages its global strain libraries to anchor long-term supply contracts with industrial bakeries. AngelYeast Co., Ltd. competes through backward integration into molasses sourcing and captive biotech R&D facilities. Lallemand Inc. specializes in temperature-tolerant strains that reduce refrigeration costs for food service distributors.
Bakers yeast comprises living Saccharomyces cerevisiae cells cultivated through aerobic fermentation on molasses or beet sugar substrates, typically containing 27-33% protein by dry weight and functioning primarily as a biological leavening agent that converts fermentable sugars into carbon dioxide and ethanol. Instant yeast formulations command widening preference among commercial bakeries due to faster activation times and reduced proofing labor, while fresh yeast retains dominance in European artisan channels where tradition governs procurement specifications. Nutritional yeast applications in plant-based food service are expanding fastest within the application matrix, though baking itself still occupies the largest margin pool across end-user categories.
EU F-Gas Regulation and REACH compliance frameworks constrain refrigerant choices and chemical inputs in European fermentation facilities, while FDA food safety standards govern strain purity and allergen labeling for US-imported products. EFSA novel food assessments now delay commercialization of genetically optimized yeast strains in continental Europe. Stakeholders must monitor evolving carbon accounting rules for biological manufacturing, as scope emissions disclosures begin penetrating yeast procurement tenders from multinational bakery groups.
Market Dynamics
EU F-Gas Regulation compliance costs are forcing fermentation facility operators across Germany, France, and Italy to accelerate capital deployment into energy-efficient cooling systems, compressing operating margins while reshaping competitive positioning between legacy and upgraded production assets.
Growth Catalysts
- Artisan bakery chain expansion:North American specialty retailers are scaling fresh yeast procurement for in-store baking programs, creating dedicated supply lanes from Lower Saxony fermentation clusters.
- Instant yeast activation speed:Commercial bakeries are adopting fast-acting dry formulations that reduce proofing labor hours and enable continuous production scheduling.
- REACH chemical input frameworks:ECHA compliance requirements are accelerating substitution toward bio-based fermentation nutrients, opening procurement contracts for certified sustainable molasses suppliers.
Market Restraints
- Molasses price volatility:Sugar beet harvest fluctuations in France and Germany create input cost instability that compresses margin predictability for strain cultivation operations.
- Fresh yeast cold chain fragility:Temperature excursion risks during last-mile distribution limit geographic reach from centralized EU production hubs to distant markets.
- Genetic strain modification delays:EFSA novel food assessment timelines extend commercialization pathways for optimized Saccharomyces cerevisiae variants by 18-36 months versus conventional breeding.
Strategic Opportunities
- Plant-based food service penetration:Nutritional yeast applications in vegan cheese and seasoning blends are opening specialty ingredient channels beyond traditional baking.
- Carbon accounting integration:Scope 3 emissions disclosure requirements from multinational bakery groups are creating premium contract tiers for verified low-carbon strain production.
- Subscription technical services:Fermentation optimization support contracts are hardening into recurring revenue layers alongside commodity yeast volume sales.
Industry Challenges
- Specialized fermentation engineering talent:Aerobic bioprocess optimization expertise remains concentrated among legacy European operators, constraining facility expansion timelines.
- Legacy refrigeration asset stranding:F-Gas phasedown schedules force accelerated capex cycles for cooling system retrofits before residual equipment value recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakers Yeast Market |
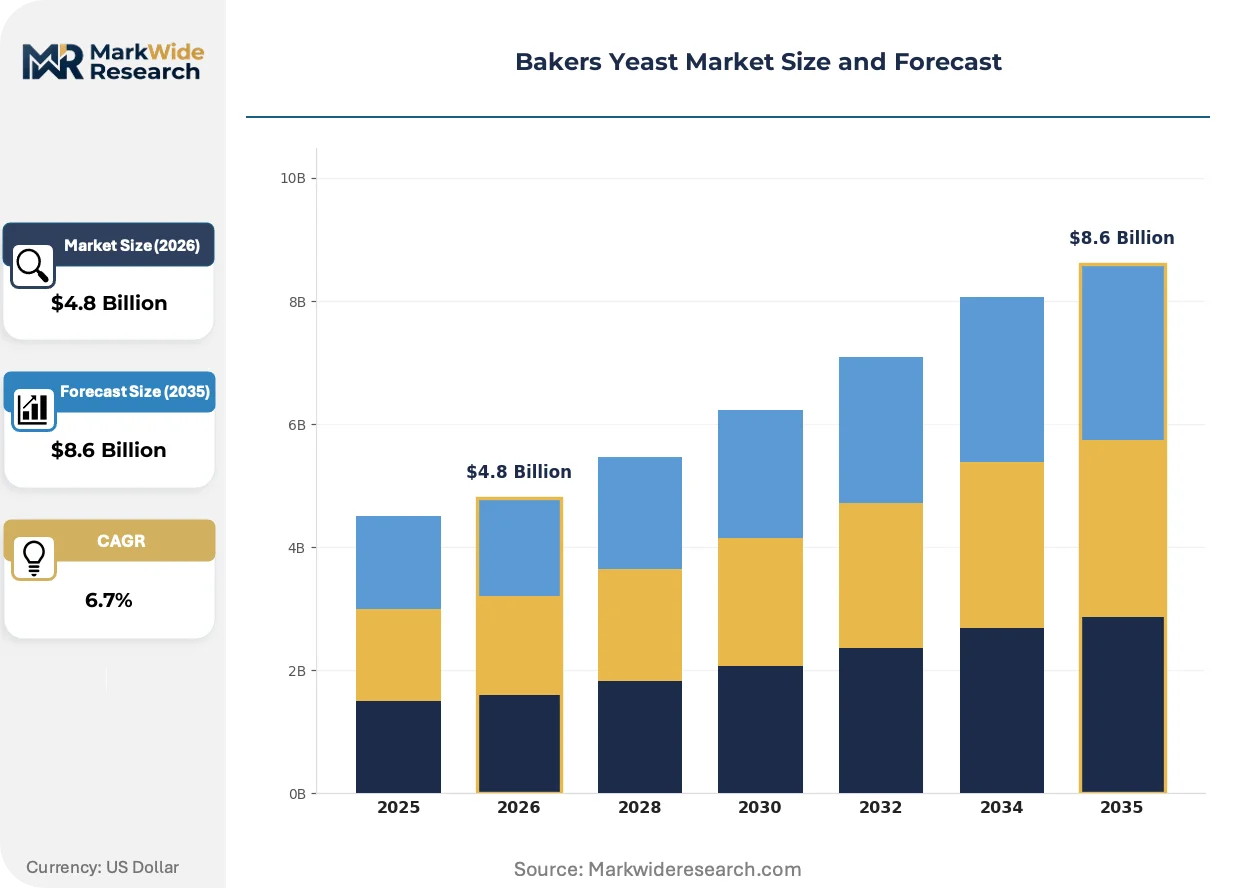
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Dry Yeast, Instant Yeast, Fresh Yeast, Nutritional Yeast Application: Baking, Brewing, Fermentation, Animal Feed Packaging Type: Bulk Packaging, Sachets, Tubs, Jars End User: Bakery, Food Service, Retail, Home Bakers |
| Companies Covered | Associated British Foods plc, Lesaffre International, AngelYeast Co., Ltd., Lallemand Inc., ADM, AB Mauri, Pak Group, Nisshin Seifun Group Inc., Leiber, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakers Yeast Market Emerging Trajectories
Temperature-tolerant strain development and digital fermentation monitoring are converging to reshape production economics, while regulatory carbon accounting and buyer procurement centralization are rewriting contract structures across the value chain.
Continuous fermentation monitoring systems using dissolved oxygen and pH sensors are absorbing variability in molasses substrate quality, enabling real-time nutrient dosing adjustments that stabilize cell density yields. Industrial bakeries in Germany and the Netherlands are deploying these systems fastest, compressing batch-to-batch performance variance that previously required conservative over-formulation.
EU F-Gas Regulation phasedown schedules are mandating refrigerant transitions from hydrofluorocarbons to ammonia or CO2 cascade systems in fermentation facilities, adding 15-25% to cooling infrastructure capital intensity. Lower Saxony production clusters are responding through shared utility investments that distribute retrofit costs across multiple strain production lines.
Consolidated procurement by multinational bakery groups is displacing fragmented distributor relationships with direct long-term supply contracts tied to carbon intensity disclosures. This concentration is most visible in Germany, where industrial baking cooperatives are negotiating three to five-year agreements that embed technical service obligations and fermentation optimization support.
Bakers Yeast Market Segmentation
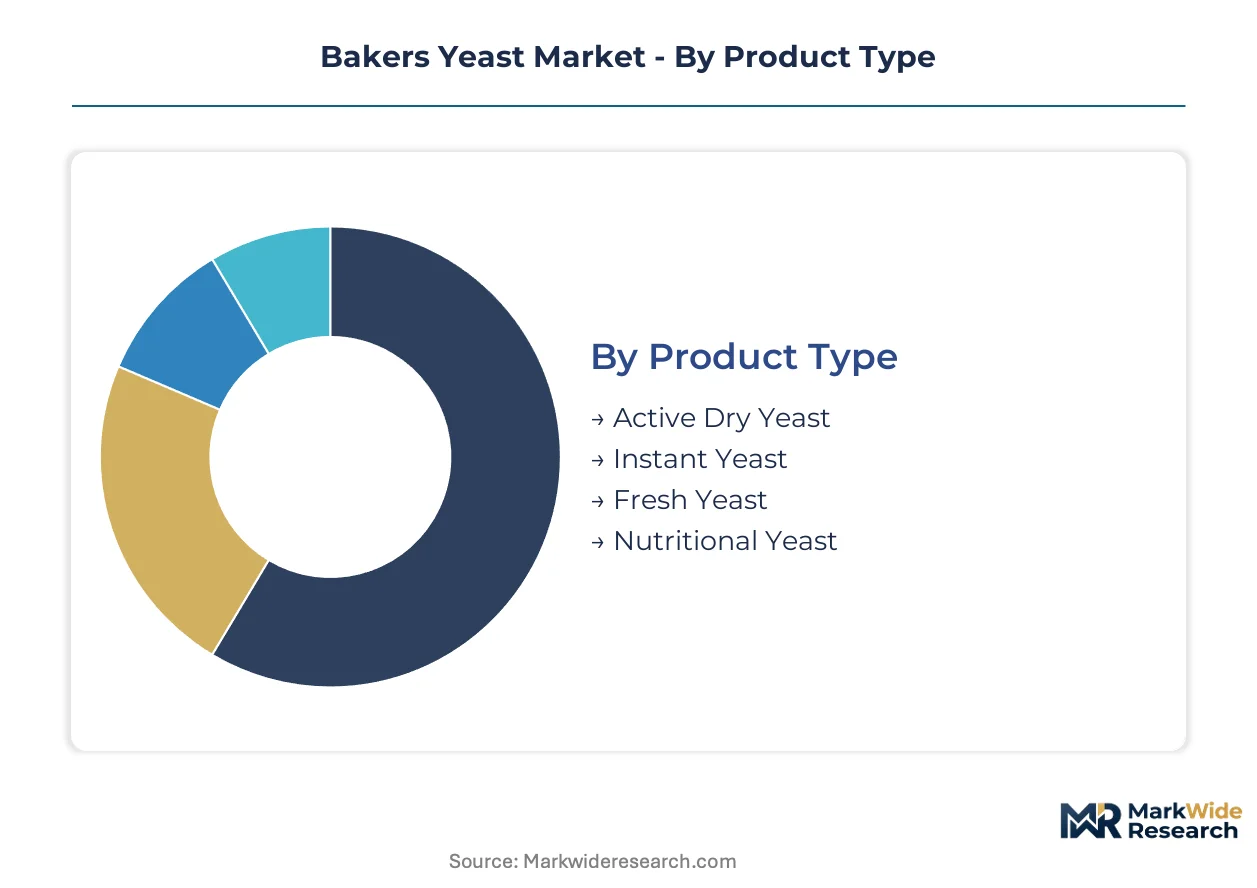
Yeast form factor determines supply chain architecture, with dry variants enabling centralized production and extended distribution reach while fresh formats anchor regional fermentation clusters. Procurement specifications diver sharply between industrial bakeries optimizing labor efficiency and artisan channels preserving traditional activation protocols.
Product Type:
Active dry and instant formulations function as standalone inputs requiring only rehydration, while fresh yeast demands embedded cold chain infrastructure throughout distribution.
- Instant Yeast:Fast-acting granules with porous structure enable direct incorporation into flour without pre-hydration. Commercial bakeries in Germany and the Netherlands are standardizing procurement around this format to compress proofing cycles and enable continuous production scheduling.
- Fresh Yeast:Living Saccharomyces cerevisiae cells in compressed cake form containing 70% moisture content. Artisan bakery chains across North America are expanding dedicated supply lanes from Lower Saxony fermentation clusters to support in-store baking programs.
- Active Dry Yeast:Dehydrated dormant cells requiring warm water activation before use, favored by home bakers and small-scale retail operations.
- Nutritional Yeast:Inactivated whole-cell preparations valued for umami flavor profiles and B-vitamin fortification in plant-based food service applications.
Instant yeast leads volumes today; nutritional yeast is gaining share fastest.
Application:
Cost tier separation distinguishes commodity leavening from premium specialty fermentation where strain purity commands price multiples.
- Baking:Biological leavening in bread, pastry, and viennoiserie production consumes the largest production volume. Industrial baking cooperatives in Germany are negotiating multi-year supply contracts embedding carbon intensity disclosures and technical service obligations.
- Brewing:Saccharomyces cerevisiae strains selected for specific ester profiles and attenuation characteristics. Craft brewery proliferation in Bavaria is stimulating demand for temperature-tolerant variants that reduce refrigeration energy.
- Fermentation:Bioethanol production and industrial biotechnology applications utilizing yeast as biocatalysts for chemical synthesis.
- Animal Feed:Single-cell protein supplementation in livestock nutrition, particularly in regions facing soybean meal supply constraints.
Baking dominates value capture; brewing applications are climbing the fastest.
Packaging Type:
Volume scale dictates format selection, with bulk serving industrial procurement and unitized formats addressing fragmented retail channels.
- Bulk Packaging:Industrial totes and fiber drums containing 20-500kg for commercial bakery direct procurement. Lower Saxony production clusters distribute via tanker to large-scale baking facilities.
- Sachets:Hermetically sealed foil pouches preserving viability for 12-24 months. Retail penetration in France and Italy favors this format for household pantry stability.
- Tubs:Refrigerated containers for fresh yeast distribution with limited shelf life.
- Jars:Glass or PET containers targeting premium positioning in specialty food retail.
Bulk packaging leads volumes today; sachets are expanding most quickly.
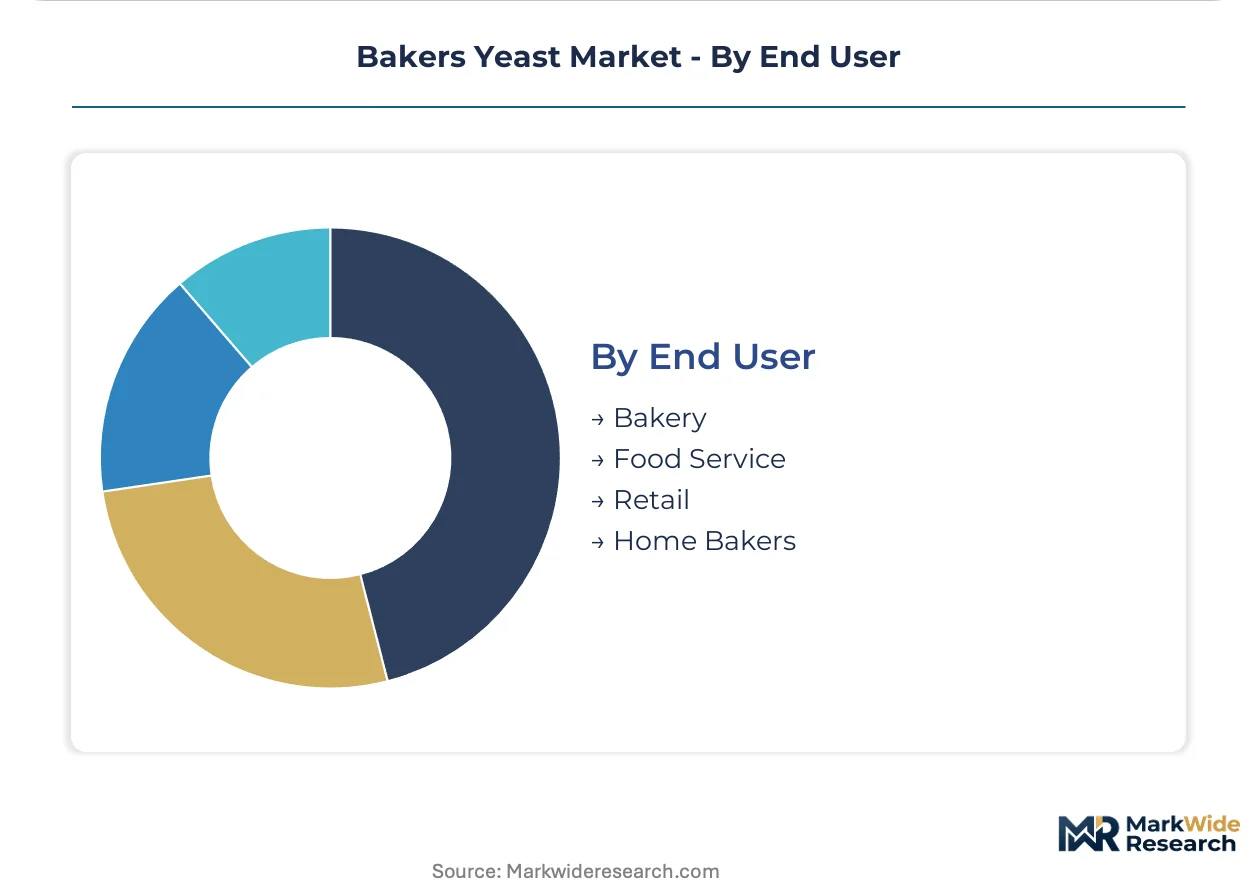
End User:
Customer type fragmentation separates specification-driven industrial procurement from price-sensitive retail consumption.
- Bakery:Industrial and artisan baking operations with strain-specific fermentation protocols. EU F-Gas Regulation compliance costs are reshaping supplier selection toward energy-efficient production assets.
- Food Service:Restaurant chains and institutional catering requiring consistent activation performance. Temperature-tolerant strains from specialized suppliers reduce distributor refrigeration burdens.
- Retail:Supermarket and specialty store channels serving home baking enthusiasts.
- Home Bakers:Individual consumers purchasing through e-commerce and conventional grocery.
Bakery end users lead volumes today; food service is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between jurisdictions are redirecting fermentation capacity investments toward regions with phased compliance timelines. Manufacturers are relocating production assets to exploit gaps in carbon accounting enforcement and refrigerant transition schedules.
Germany
Industrial baking cooperatives in Lower Saxony and Bavaria anchor continental supply contracts for fresh yeast strains. EU F-Gas Regulation compliance costs are accelerating shared utility investments across fermentation clusters to distribute cooling infrastructure retrofits. ECHA REACH frameworks constrain chemical inputs while redirecting procurement toward bio-based fermentation nutrients.
United States
Artisan bakery chains are expanding dedicated procurement lanes for in-store baking programs using European-sourced fresh yeast. FDA food safety standards govern strain purity and allergen labeling for imported products. Temperature-tolerant strain demand from food service distributors is reducing refrigeration burdens across distribution networks.
France
Sugar beet harvest fluctuations in northern growing regions create input cost instability for molasses-dependent cultivation operations. ANSM and national agricultural regulators oversee biotech strain assessments alongside EFSA novel food evaluation timelines. Industrial baking facilities in Île-de-France and Hauts-de-France negotiate multi-year supply contracts embedding carbon intensity disclosures.
China
Domestic fermentation capacity is expanding to serve industrial baking growth in eastern coastal provinces. MIIT and SAMR standards govern food-grade bioprocess equipment and strain quality certification. Molasses sourcing from domestic sugar processing centers in Guangxi and Yunnan supports captive yeast production for regional bakery chains.
Netherlands
Commercial bakeries are standardizing procurement around instant yeast formats to compress proofing cycles and enable continuous production scheduling. National environmental agencies enforce EU Green Deal carbon accounting rules that penetrate procurement tenders from multinational bakery groups. Rotterdam and Amsterdam distribution hubs facilitate re-export of fermentation products to Nordic markets.
Bakers Yeast Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated procurement by multinational bakery groups displacing fragmented distributor relationships. The vendor base organizes around three strategic archetypes: global strain library operators, backward-integrated molasses processors, and temperature-tolerant specialty developers. Dominant competitive moves include direct long-term supply contract negotiations and fermentation optimization support subscriptions that harden into recurring revenue layers.
Among European-anchored specialists, Lesaffre International and Lallemand Inc. exemplify divergent positioning archetypes within the branded tier, while AngelYeast Co., Ltd. represents the Asia-Pacific integrated model with captive upstream sourcing. Associated British Foods plc occupies a position spanning both ingredient supply and downstream bakery retail, creating internal demand visibility that informs strain development priorities. These three anchors collectively illustrate how geographic origin and structural integration shape competitive differentiation without requiring uniform strategic postures.
| Leading Market Players |
|---|
| Associated British Foods plc |
| Lesaffre International |
| AngelYeast Co., Ltd. |
| Lallemand Inc. |
| ADM |
| AB Mauri |
| Pak Group |
| Nisshin Seifun Group Inc. |
| Leiber |
| Others |
Supply Flow & Price Mechanics
Consolidated procurement by multinational bakery groups is forcing suppliers toward direct long-term contracts with embedded technical service obligations, compressing distributor margins while rewarding strain producers with captive fermentation optimization capabilities.
Pricing Analysis
Distributor margin layers have compressed as industrial baking cooperatives negotiate direct supply agreements with Lower Saxony fermentation clusters. Three-tier pricing structure across premium certified strains, standard commercial grades, and economy bulk formats separates carbon-verified production from conventional output. Pricing pressure stems from molasses input cost volatility in French and German sugar beet regions. Small-scale retail channels exhibit highest price sensitivity, while industrial bakeries prioritize activation consistency over unit cost.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised fresh yeast cakes create specialized cold chain recovery networks, with expired product diverted to animal feed processors rather than landfill. Supply concentrates in Germany, France, and China, with Lower Saxony anchoring continental fresh yeast distribution. Raw material dependencies center on sugar beet molasses, nitrogen sources, and phosphate nutrients. Single-source vulnerability runs through concentrated European sugar beet harvests. Distribution runs through shared utility investments across fermentation clusters that distribute cooling infrastructure costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with artisan bakery chains and carbon-conscious multinational procurement driving specification premiums for verified low-carbon strain production.
For Market Incumbents: Acquire fermentation optimization engineering talent pools to defend technical service revenue layers against commodity price erosion. Threats from backward-integrated molasses processors in Asia-Pacific require accelerated captive biotech R&D facility deployment. Priority lever rests on shared utility investments across Lower Saxony production clusters that distribute EU F-Gas Regulation compliance costs. For New Entrants and Emerging Players: Launch via plant-based food service channels targeting nutritional yeast applications in vegan cheese and seasoning blends. White-space opportunity concentrates in temperature-tolerant strain development for food service distributors seeking refrigeration cost reduction. Most penetrable segment spans North American artisan bakery chains expanding in-store baking programs with European-sourced fresh yeast supply lanes. For Investors and Strategic Acquirers: Asymmetric upside sits with backward-integrated specialists controlling captive molasses sourcing and in-house strain development capabilities. Long-term viability over the projection horizon favors operators with verified carbon accounting systems embedded in procurement tenders. Signal to watch involves scope emissions disclosure requirements penetrating multinational bakery group supply contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Sourcing | Captive supply from Guangxi and Yunnan processing centers stabilizes input cost volatility for strain cultivation. |
| Energy-Efficient Cooling Infrastructure Deployment | Shared utility investments across Lower Saxony clusters distribute EU F-Gas Regulation compliance retrofit costs. |
| Temperature-Tolerant Strain Development | Lallemand Inc. specialization reduces refrigeration burdens for food service distributors across distribution networks. |
| Carbon Accounting System Integration | Verified low-carbon production credentials unlock premium contract tiers from multinational bakery procurement. |
| Subscription Technical Service Launch | Fermentation optimization support contracts harden into recurring revenue alongside commodity yeast volume sales. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation facility operators, industrial bakery procurement leads, molasses supply specialists, and ECHA regulatory affairs consultants with secondary validation from EU F-Gas Regulation filings, REACH compliance databases, EFSA novel food assessment records, and customs trade data for yeast product categories. Bottom-up strain production estimates and top-down baking industry consumption models were triangulated against cross-referenced sources.
Historical reference periods anchored volume and value trajectories across the analysis window, with segmentation dimensions spanning yeast form factor, application category, packaging format, and end-user type alongside carbon intensity certification tier. CAGRs were derived from fitted growth curves incorporating molasses price index movements, artisan bakery chain expansion rates, and regulatory compliance cost absorption patterns across production geographies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sugar beet harvest disruption scenarios and EFSA novel food assessment timeline extensions. Practitioners should monitor scope emissions disclosure penetration in multinational bakery procurement tenders and F-Gas phasedown schedule acceleration signals for early indicators of contract structure shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Low Calorie Muffins Market
Bakery Products
Ice Cream Cake Market
Bakery Products
Gluten-Free Bakery Market
Bakery Products
Biscuit Mixes Market
Bakery Products
Low Fat Oatmeal Cookies Market
Bakery Products
Gulf Cooperation Council Frozen Bakery Products Market
Bakery Products
Waffle Market
Bakery Products
Low Fat Chocolate Cake Market
Bakery Products
Packaged Bread Market
Bakery Products
Sourdough Market
Bakery Products
Global Cakes Market
Bakery Products
Southeast Asia Bakery Products Market
Bakery Products
Bread Mix Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
Pastry Margarine Market
Bakery Products
Vegan Certified Cake Mixes Market