
 Fondant Market | 2026-2036
Fondant Market Size, Share, and Industry Trends Forecast 2026-2036
Fondant Market Intelligence
Modular fondant kits combining base pastes with color and flavor sachets is repositioning purchase decisions toward customizable at-home baking experiences. Satin Ice dominates North American specialty retail channels with consistent roll-out consistency. Bakels Pettinice leverages its Australian manufacturing base to supply Asia-Pacific wholesale bakery networks. Puratos Group anchors European artisan bakery demand through technical service partnerships with professional pastry chefs.
Fondant is a sugar-based confectionery paste composed of sucrose, glucose syrup, and water, mechanically worked to a pliable, dough-like consistency that sets firm yet sliceable when applied to cakes and pastries. Its primary commercial purpose is to create smooth, decorable surfaces that accept color, texture, and three-dimensional modeling. Ready-to-use fondant leads volume sales through supermarket and online retail channels, while pourable fondant commands premium positioning in high-throughput commercial bakeries where labor efficiency determines margin. Rolled fondant sustains the fastest growth trajectory among home bakers and small catering services seeking professional-grade finishes without specialized equipment.
FDA food additive regulations and EU Regulation 1333/2008 on food enzymes constrain hydrocolloid and stabilizer selections in fondant formulations, directly elevating R&D costs for cross-border suppliers. ISO 22000 and FSSC 22000 certification requirements from major retail chains further filter market access, favoring vertically integrated manufacturers with in-house quality laboratories. Stakeholders must monitor evolving titanium dioxide restrictions under EFSA reassessment protocols, as reformulation timelines will separate compliant suppliers from inventory-stranded competitors.
Market Dynamics
Clean-label ingredient mandates under EU Regulation 1169/2011 and evolving FDA labeling standards are forcing reformulation across the entire fondant supply chain, compressing margins for manufacturers dependent on synthetic hydrocolloids and artificial colorants.
Growth Catalysts
- Artisan Wedding Cake Segment:Premium rolled fondant demand concentrates in high-end celebration markets where visual finish commands pricing power. Professional pastry chefs in the United States and Germany drive specification authority.
- EU Regulation 1333/2008:Food enzyme frameworks are accelerating enzyme-modified starch adoption in fondant formulations, creating compliant texture alternatives to traditional gelatin-based stabilizers.
- Modular At-Home Kits:Base paste-plus-sachet systems are democratizing professional-grade cake decoration for home bakers without specialized equipment investment.
Market Restraints
- Sugar Price Volatility:Sucrose and glucose syrup input costs fluctuate with commodity sugar markets, squeezing margin predictability for volume producers serving supermarket channels.
- Titanium Dioxide Regulatory Uncertainty:EFSA reassessment protocols under ongoing review threaten inventory positions for suppliers using E171 whitening agents, forcing premature reformulation cycles.
- Supply Concentration Risk:Asia-Pacific hydrocolloid sourcing dependence creates exposure to shipping corridor disruptions and the country's national food safety regulator enforcement variations.
Strategic Opportunities
- Plant-Based Colorant Convergence:Spirulina-derived blues and beetroot reds are electrifying clean-label positioning for premium tier products targeting health-conscious celebration buyers.
- Specialty Retail Channel Expansion:Online direct-to-consumer platforms in the United Kingdom bypass traditional wholesale bakery distribution, capturing full margin from enthusiast segments.
- FSSC 22000 Certification Arbitrage:Vertically integrated manufacturers with in-house quality laboratories are capturing shelf space from uncertified competitors as major retail chains harden supplier qualification requirements.
Industry Challenges
- Pastry Chef Talent Pipeline:Professional fondant application skills concentrate in aging demographic cohorts, constraining throughput capacity for high-end catering services.
- Cross-Border Reformulation Timelines:Simultaneous compliance with FDA food additive regulations and EU enzyme restrictions fragments R&D resource allocation for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fondant Market |
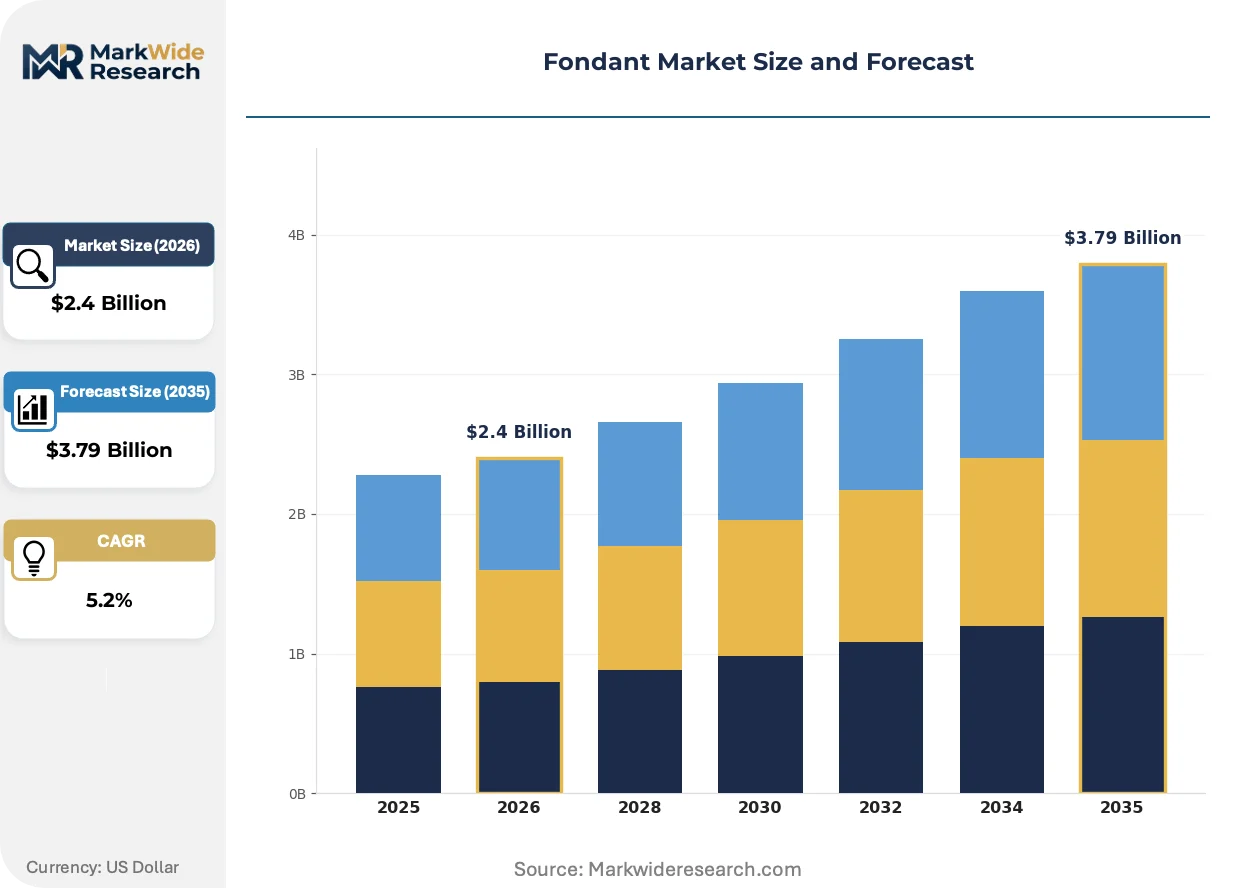
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Use Fondant, Rolled Fondant, Pourable Fondant, Modeling Chocolate Application: Cakes, Cupcakes, Cookies, Pastries Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesalers End User: Bakers, Home Bakers, Catering Services, Professional Pastry Chefs |
| Companies Covered | FondX, Bakels Pettinice, Satin Ice, Puratos Group, JF Renshaw, Wilton, Dawn Food Products, Saracino, Fat Daddio’s, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fondant Market Strategic Shifts & Innovations
Formulation chemistry and distribution architecture are undergoing parallel transformation as regulatory pressure intersects with amateur baker empowerment. Three developments are restructuring competitive positioning.
Enzyme-modified starch systems are electrifying texture engineering in rolled fondant production, replacing traditional gelatin-based stabilizers with plant-derived alternatives that maintain pliability without animal-derived inputs. Mid-sized commercial bakeries in Germany are adopting these systems fastest, driven by vegan-label certification requirements. The technology is compressing supplier differentiation around clean-label credentials rather than performance specifications alone.
EFSA titanium dioxide reassessment protocols are forcing premature reformulation investments across European manufacturing footprints, eliminating E171 from whitening formulations before formal bans take effect. Suppliers with captive R&D facilities are accelerating natural mineral alternatives to market. Premium positioning tiers absorb these cost escalations most effectively, while economy segments face margin compression.
Subscription-based modular fondant kits are rotating demand toward recurring revenue models, displacing one-time retail purchases with curated monthly deliveries targeting home baking enthusiasts. Specialty online channels in the United States and United Kingdom are capturing this behavioral shift fastest. Celebration segment buyers demonstrate highest lifetime value under this model, with wedding-planning cohorts showing strongest retention metrics.
Fondant Market Segmentation
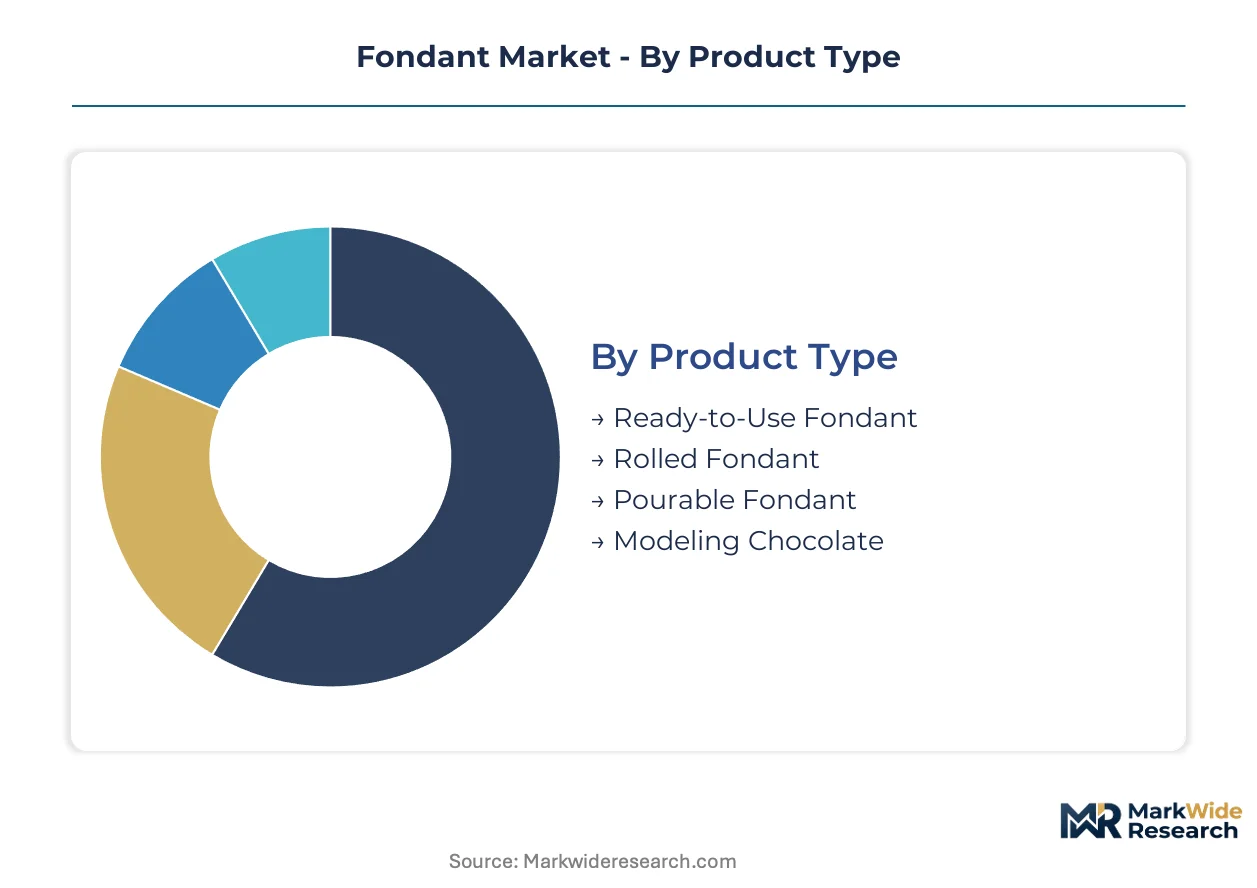
Fondant formulation chemistry and distribution architecture create distinct margin profiles across product tiers. Understanding capital deployment requirements and customer workflow integration separates high-return segments from commodity exposure.
Product Type:
Capital intensity concentrates in manufacturing equipment for texture engineering and stabilizer integration, with rolled fondant requiring the most sophisticated sheeting and conditioning lines.
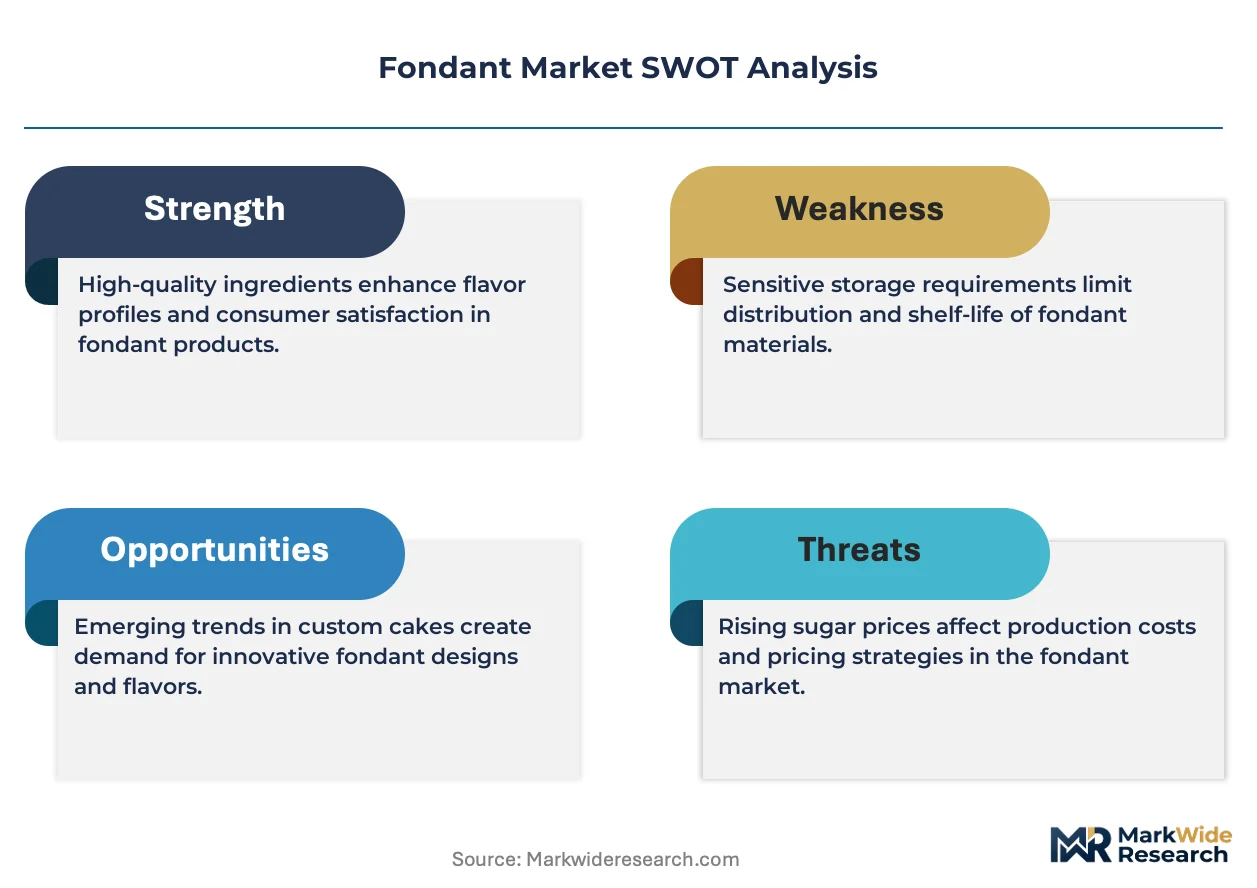
- Rolled Fondant:Sucrose-glucose syrup matrices mechanically worked to pliable dough consistency, setting firm yet sliceable. Demand concentrates in the United States and Germany where wedding cake artisans command premium pricing for professional-grade finishes. Clean-label stabilizer mandates under EU Regulation 1333/2008 are accelerating enzyme-modified starch adoption, elevating R&D spend for compliant formulations.
- Ready-to-Use Fondant:Pre-conditioned pastes packaged for immediate application without specialized equipment. Supermarket and online retail channels in the United Kingdom drive volume, though margin compression from synthetic hydrocolloid reformulation pressures profitability.
- Pourable Fondant:Low-viscosity coatings for automated bakery lines requiring minimal labor intervention.
- Modeling Chocolate:Chocolate-based pliable paste for three-dimensional sculpting applications in celebration segments.
Most installed capacity flows through ready-to-use fondant. Expansion is steepest in rolled fondant.
Application:
Workflow complexity and decoration surface area determine equipment and skill requirements, with tiered celebration cakes demanding the most specialized labor inputs.
- Cakes:Multi-tier celebration and wedding applications requiring smooth fondant coverage over irregular surfaces. Professional pastry chefs in the United States and Germany specify rolled fondant for high-value commissions where visual finish determines pricing power. EFSA titanium dioxide reassessment protocols are forcing premature reformulation of whitening formulations.
- Cupcakes:Individual portion formats suitable for mass production and home baker experimentation. Modular fondant kits through online retail channels in the United Kingdom are capturing enthusiast demand.
- Cookies:Flat surface applications with lower technical barriers to entry.
- Pastries:Laminated dough integration requiring moisture-resistant fondant specifications.
Cake applications absorb the highest absolute spend per unit. Cupcake decoration is climbing the fastest among home baking segments.
Distribution Channel:
Certification requirements and margin capture potential vary sharply by channel, with specialty retail demanding FSSC 22000 compliance while direct-to-consumer bypasses wholesale intermediaries.
- Online Retail:Direct-to-consumer platforms enabling subscription-based modular kit models. The United States and United Kingdom demonstrate strongest adoption of curated monthly deliveries targeting wedding-planning cohorts with highest lifetime value metrics.
- Specialty Stores:Professional supply outlets serving pastry chefs with technical consultation and consistent roll-out specifications.
- Supermarkets:Mass-market ready-to-use fondant facing sugar price volatility exposure.
- Wholesalers:Bulk supply to commercial bakeries with volume-dependent pricing structures.
Specialty stores move the highest-margin formulations. Online retail is gaining share fastest through enthusiast subscription models.
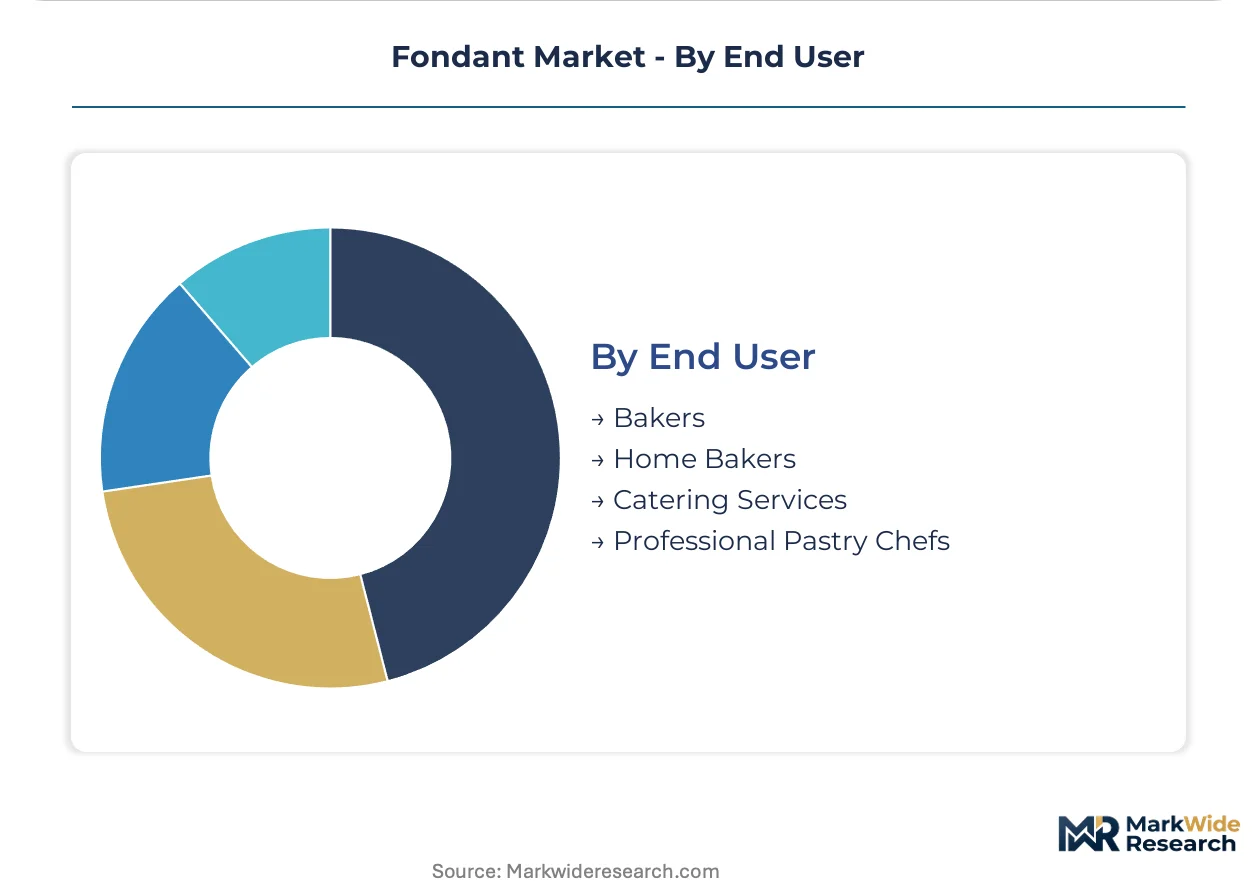
End User:
Skill concentration and equipment access create distinct purchasing patterns, with professional credentialing determining specification authority in premium tiers.
- Professional Pastry Chefs:Specification authorities in high-end celebration markets with formal training in fondant application techniques. Aging demographic cohorts in Germany and the United States constrain throughput capacity for premium catering services.
- Home Bakers:Enthusiast segment driving modular kit adoption without specialized equipment investment.
- Catering Services:Volume purchasers balancing labor efficiency against finish quality requirements.
- Bakers:Commercial operations prioritizing pourable fondant for throughput optimization.
Professional pastry chefs command the highest per-unit spend. Home bakers are expanding most quickly through democratized kit formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fondant manufacturing originated in French and Belgian confectionery traditions during the 19th century, with industrial scaling following post-war mechanization in Germany and the United States. Contemporary demand patterns reflect this dual heritage, with premium artisan applications concentrated in Western European markets and volume production anchored in North American retail channels.
United States
Wedding cake artisans in California and New York Metro drive specification authority for premium rolled fondant, commanding premium pricing for celebration commissions. FDA food additive regulations constrain hydrocolloid selections, elevating compliance costs for cross-border suppliers. Specialty retail channels in Los Angeles and Brooklyn capture enthusiast demand through subscription-based modular kit models.
Germany
Professional pastry chef density in Bavaria and North Rhine-Westphalia sustains Europe's most sophisticated fondant application market, with artisan bakeries specifying enzyme-modified starch formulations. EU Regulation 1333/2008 on food enzymes accelerates plant-based stabilizer adoption, compressing margins for gelatin-dependent suppliers. Stuttgart's technical service partnerships anchor Puratos Group's European market development.
United Kingdom
Online direct-to-consumer platforms in London and Southeast England bypass traditional wholesale intermediaries, capturing full margin from home baking enthusiasts. EU Regulation 1169/2011 clean-label mandates force reformulation of synthetic colorant-dependent inventories. Birmingham's specialty bakery supply cluster serves catering services balancing labor efficiency against finish quality requirements.
Australia
Wholesale bakery networks across New South Wales and Victoria source rolled fondant from Asia-Pacific manufacturing bases, with Melbourne's commercial baking sector prioritizing pourable formulations for throughput optimization. The country's national food safety regulator enforces FSSC 22000 certification requirements that filter market access. Sydney's specialty retail expansion targets wedding-planning cohorts through curated monthly delivery models.
France
Traditional pâtisserie preservation in Île-de-France and Auvergne-Rhône-Alpes sustains artisan fondant demand for celebration applications, with Lyon-based pastry schools maintaining technical skill pipelines. EFSA titanium dioxide reassessment protocols threaten E171-dependent whitening formulations, forcing premature reformulation cycles. Parisian luxury catering services absorb cost escalations through premium positioning tiers.
Fondant Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification and distribution channel dimensions, with FSSC 22000 compliance separating qualified suppliers from retail-stranded competitors. The vendor base clusters around three strategic archetypes: vertically integrated manufacturers with captive R&D facilities, regional specialists leveraging geographic proximity to bakery networks, and brand-licensed consumer goods conglomerates serving supermarket channels. Capacity expansion and portfolio diversification toward clean-label formulations represent the dominant competitive moves as regulatory deadlines compress reformulation timelines.
Among North American specialty retail anchors, Satin Ice and Wilton occupy positions within the brand-recognition tier, while Bakels Pettinice exemplifies Asia-Pacific wholesale network specialists. Puratos Group anchors European artisan bakery demand through technical service partnerships. These named entities represent archetype differentiation rather than exhaustive market coverage, with each occupying distinct positions across premium-standard-economy pricing stratification.
| Leading Market Players |
|---|
| FondX |
| Bakels Pettinice |
| Satin Ice |
| Puratos Group |
| JF Renshaw |
| Wilton |
| Dawn Food Products |
| Saracino |
| Fat Daddio's |
| Others |
Cost & Logistics Intelligence
Captive in-house production of enzyme-modified starch stabilizers anchors both supply security and premium pricing power for European fondant manufacturers facing EU Regulation 1333/2008 compliance deadlines. This backward integration into plant-based texture engineering separates certified suppliers from competitors stranded with gelatin-dependent inventories and reformulation cost overruns.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by FSSC 22000 certification grade and clean-label ingredient status. Price differentiation hinges on stabilizer technology tier and retail channel access, with specialty stores commanding 40-60% premiums over supermarket channels. Cost compression in economy-tier ready-to-use fondant is intensifying because of sucrose price volatility and synthetic hydrocolloid reformulation mandates. Home bakers through online subscription models demonstrate lowest price sensitivity, while commercial bakeries purchasing through wholesale channels exhibit highest elasticity.
Supply Chain Analysis
Sucrose and glucose syrup supply rests on Brazilian and Thai sugarcane processors, with EU beet sugar refineries providing regional coverage for German and French manufacturers. Hydrocolloid sourcing draws from Philippines seaweed farming operations and Indian guar processing facilities, creating Asia-Pacific dependency for texture-critical inputs. Single-source vulnerability concentrates in titanium dioxide alternatives development, where natural mineral whitening suppliers face EFSA-driven demand surges they cannot immediately fulfill. Distribution runs through specialty retail and online direct-to-consumer platforms for premium tiers, while supermarket and wholesale channels handle volume ready-to-use formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in enzyme-modified starch adoption and subscription-based modular kit models, with clean-label certification investments yielding pricing power that outpaces input cost inflation.
For Market Incumbents: Anchor defensible positioning through captive R&D facilities accelerating EFSA-compliant titanium dioxide alternatives to market ahead of formal bans. Deepen backward integration into plant-based stabilizer supply chains to isolate margin from hydrocolloid price volatility and Asia-Pacific shipping corridor disruptions. Control specialty retail channel shelf space by hardening FSSC 22000 certification moats that uncertified competitors cannot breach within reformulation timelines. For New Entrants and Emerging Players: Direct-to-consumer online platforms offer the most penetrable route for modular fondant kit subscription models targeting wedding-planning cohorts in the United States and United Kingdom. White-space exists in plant-based colorant convergence, specifically spirulina-derived blue formulations where incumbent R&D pipelines lag enthusiast demand. Pursue technical service partnerships with aging professional pastry chef demographics in Germany to capture specification authority before talent pipeline constraints intensify. For Investors and Strategic Acquirers: Roll-up economics work for mid-sized European manufacturers with in-house quality laboratories because certification requirements from major retail chains are filtering uncertified competitors from shelf access. Long-term viability favors targets with demonstrated enzyme-modified starch formulation capabilities and established technical service relationships with professional pastry networks. Watch EFSA titanium dioxide reassessment protocol finalization as the inflection signal separating reformulation-ready portfolios from inventory-stranded positions.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | EU Regulation 1333/2008 compliance separates certified suppliers from stranded inventory positions. |
| Subscription-Based Modular Kit Launch | Online direct-to-consumer platforms in the United States capture highest lifetime value from wedding-planning cohorts. |
| Technical Service Partnership Expansion | Puratos Group's Stuttgart partnerships demonstrate how chef specification authority converts to premium pricing power. |
| Backward Integration into Stabilizer Supply | In-house enzyme-modified starch production isolates margins from Philippines seaweed farming price volatility. |
| Specialty Retail Channel Certification Arbitrage | FSSC 22000 compliance captures shelf space as major retail chains harden supplier qualification requirements. |
Research Approach
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region's professional pastry chef networks and specialty bakery supply channels. The approach combines structured interviews with head pastry chefs at high-end catering services, procurement leads at wholesale bakery distributors, R&D directors at vertically integrated manufacturers, and category buyers at specialty retail chains, validated against secondary sources including FDA food additive guidance documents, EFSA scientific opinions, FSSC 22000 certification registries, and customs trade data on sucrose and hydrocolloid imports. Bottom-up segment sizing triangulates against top-down market value estimates.
Granularity-level modeling operates at product type, application, distribution channel, and end-user dimensions, with additional disaggregation by clean-label certification status and stabilizer technology tier. CAGRs derive from segment-level growth trajectory analysis incorporating regulatory deadline impacts, subscription model adoption curves, and professional pastry chef demographic projections. Industry-specific forecast inputs include EFSA titanium dioxide reassessment timeline assumptions and enzyme-modified starch technology diffusion rates across German commercial bakeries.
The model assumes a particular technology adoption path for plant-based stabilizer systems; alternative pathways involving accelerated gelatin replacement would alter the outlook for incumbent formulation portfolios. Forecasts reflect assumptions about regulatory enforcement consistency, shipping corridor stability, and professional skill pipeline continuity. Material deviation in EFSA protocol finalization or Asia-Pacific hydrocolloid supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Flatbread Market
Bakery Products
Marzipan Market
Bakery Products
Healthy Biscuits Market
Bakery Products
No-Fat Cake Market
Bakery Products
Dough Whitener Market
Bakery Products
North America Par Baked Bread Market
Bakery Products
Cake Concentrate Market
Bakery Products
Layer Cake Mixes Market
Bakery Products
Specialty Bakery Market
Bakery Products
Southeast Asia Bakery Products Market
Bakery Products
Wedding Cakes Market
Bakery Products
Instant Cake Emulsifier Market
Bakery Products
Baking Mix, Base and Concentrate Market
Bakery Products
Low Calorie Rice Cake Market
Bakery Products
Pastry Premixes Market
Bakery Products
Batter and Breader Premixes Market