
 Diabetic Bakery Products Market | 2026-2036
Diabetic Bakery Products Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetic Bakery Products Market Outlook
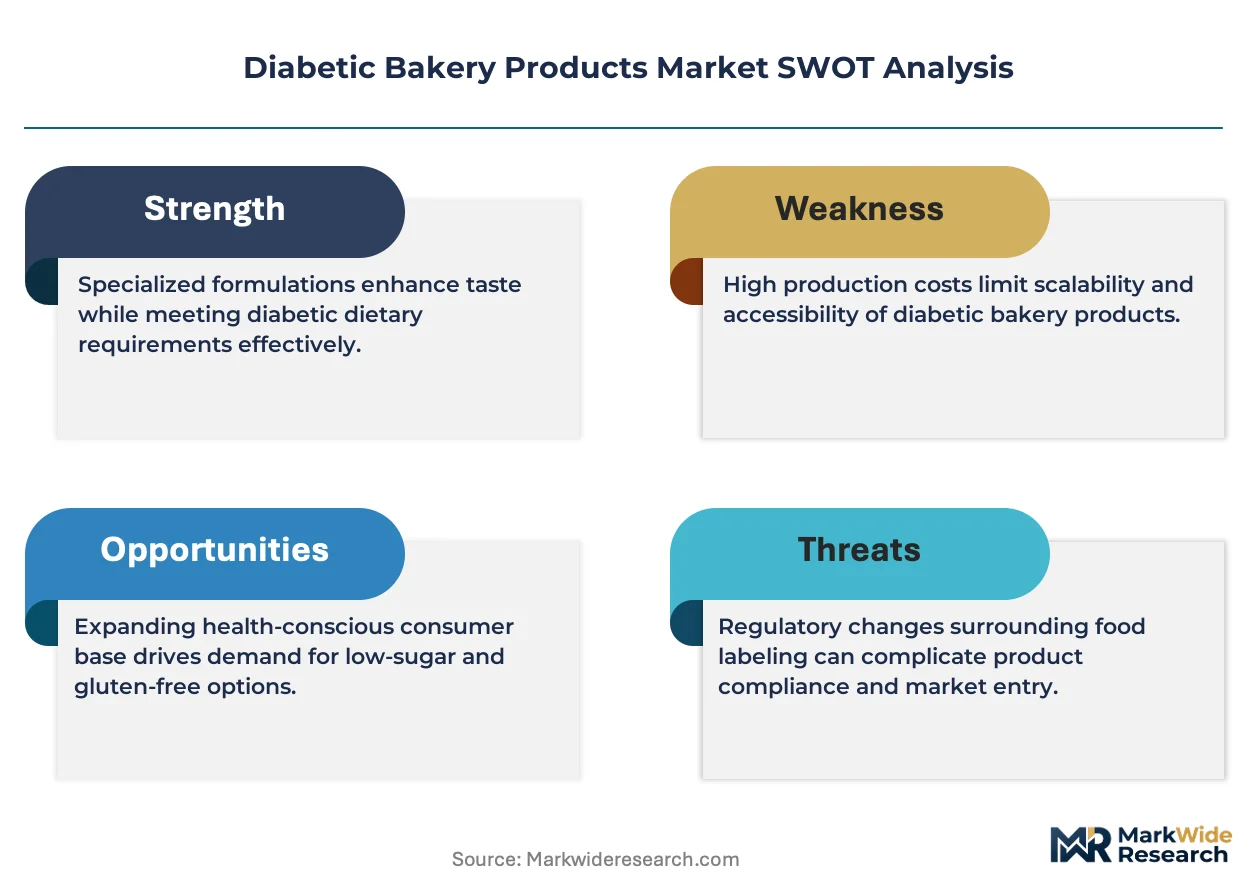
ISO 22000 certification is unwinding the competitive landscape for diabetic bakery entrants, raising food safety management thresholds that smaller regional bakers struggle to meet. Mondelez International leverages its global distribution infrastructure to anchor shelf presence across European retail chains. Britannia Industries Limited specializes in whole-grain and fiber-enriched formulations tailored to South Asian palates and glycemic profiles.
Diabetic bakery products are baked goods reformulated with sugar substitutes, alternative flours, and soluble fiber additives to achieve lower glycemic index values, typically below 55 on the GI scale, while maintaining structural integrity through modified starch and protein-stabilized emulsions. Their primary commercial purpose is to provide safe indulgence options for insulin-resistant consumers without triggering postprandial glucose spikes. The breads and cookies categories dominate current volume, while cakes command premium positioning due to complex fat-replacement chemistry and shorter freshness windows. Sugar substitutes and natural sweeteners represent the fastest-growing ingredient segment as monk fruit and allulose displace legacy polyols in clean-label formulations.
FDA nutrition labeling rules and EFSA health claim protocols jointly govern permissible glycemic assertions, forcing reformulation investments that favor scaled manufacturers with dedicated R&D labs. India's FSSAI is tightening standards for sugar-free claims, adding compliance layers for exporters targeting its diabetic population. Stakeholders must monitor evolving sweetener approval pipelines and regional glycemic-index testing requirements to anticipate which formulation investments will retain market access.
Market Dynamics
Glycemic-index certification requirements from EFSA, Japan's Consumer Affairs Agency, and Health Canada are forcing manufacturers to rebuild formulation pipelines around validated low-GI testing protocols, compressing time-to-market for new diabetic bakery SKUs.
Growth Catalysts
- Clean-label sweetener pipelines:Monk fruit and allulose approvals are accelerating in the US and Japan, displacing legacy polyols in premium diabetic cookie formulations.
- Hospital cafeteria procurement mandates:German and Canadian healthcare facilities now specify certified low-GI bakery options for inpatient diabetes management programs.
- Aging population density in urban corridors:Tokyo, Toronto, and Berlin exhibit overlapping diabetes prevalence and health-conscious consumption patterns that support specialty bakery expansion.
Market Restraints
- Allulose supply concentration:North American production bottlenecks limit scalable access for European and Asian formulators seeking clean-label positioning.
- EFSA health claim friction:The agency's strict glycemic-index substantiation protocols delay product launches by 12-18 months for manufacturers lacking dedicated clinical testing budgets.
- Modified starch cost volatility:Tapioca and resistant wheat starch prices fluctuate with Brazilian and Australian harvest cycles, squeezing margin structures for mid-tier producers.
Strategic Opportunities
- Indian FSSAI compliance arbitrage:Early alignment with tightening sugar-free claim standards positions exporters for first-mover advantage in India's underserved diabetic bakery segment.
- Direct-to-patient subscription channels:Specialized e-commerce platforms for chronic disease management bypass retail slotting fees and capture recurring revenue from insulin-resistant consumers.
- Fiber-protein emulsion convergence:Combining soluble oat fiber with pea protein stabilizers enables texture parity with conventional cakes while meeting EFSA low-GI thresholds.
Industry Challenges
- ISO 22000 certification timelines:Smaller regional bakers face 8-12 month food safety management system implementation periods that delay contract eligibility with major retail chains.
- Cross-functional formulation expertise:The intersection of glycemic science, bakery process engineering, and regulatory affairs creates acute talent scarcity in European and North American R&D hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetic Bakery Products Market |
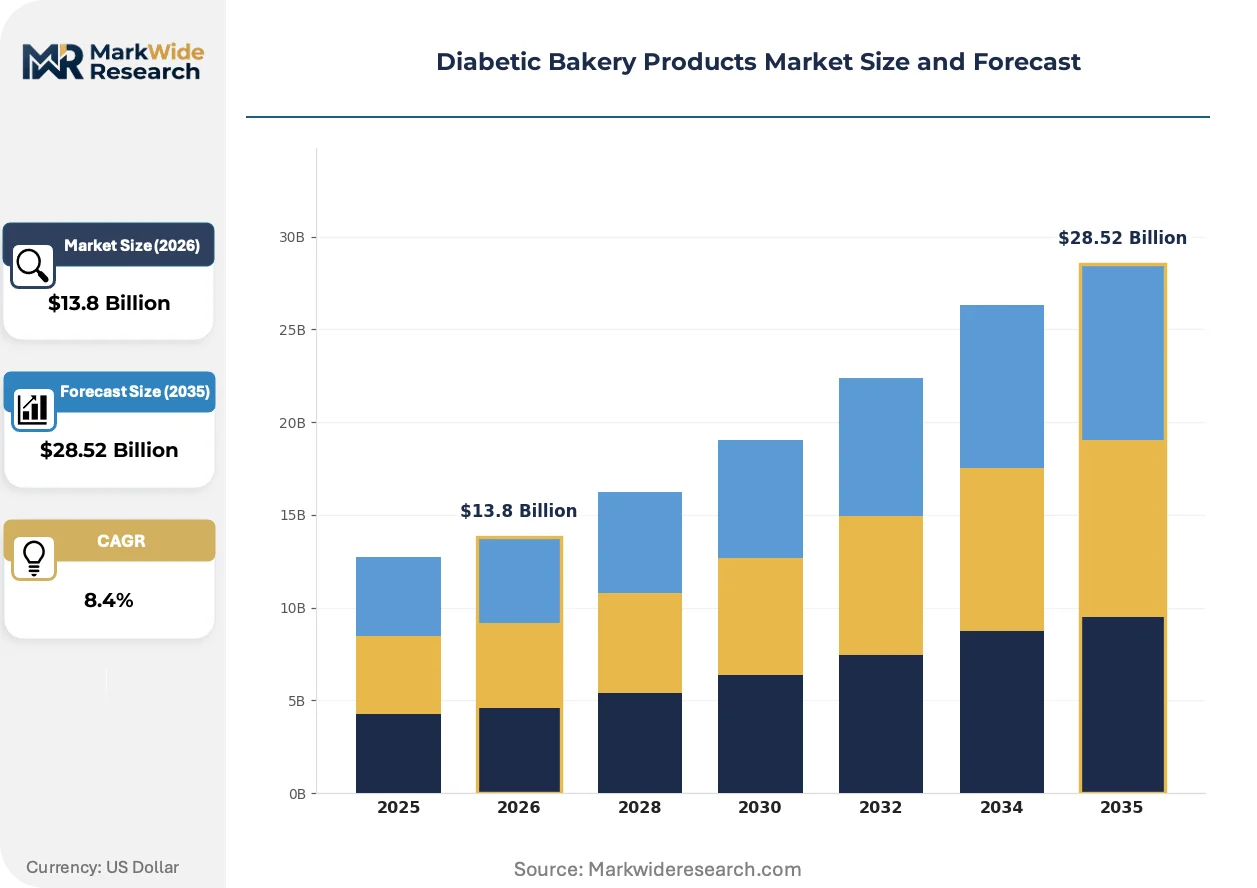
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Cookies, Muffins, Cakes Ingredient Type: Whole Grain, Sugar Substitutes, Fiber Enrichments, Natural Sweeteners Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Bakeries End User: Individuals, Hospitals, Cafes, Fitness Centers |
| Companies Covered | Britannia Industries Limited, Dunkin' Donuts, Grupo Bimbo, Nestle, United Biscuits, Mondelez International, Barilla Holding, Kellogg, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetic Bakery Products Market Strategic Shifts
Formulation science and distribution architecture are undergoing parallel reinvention as clean-label mandates collide with precision nutrition expectations, reshaping how diabetic bakery products reach insulin-resistant consumers.
Allulose-based sweetening systems are bifurcating the diabetic bakery landscape. This rare sugar delivers 70% sucrose sweetness with negligible glycemic impact and superior Maillard browning versus polyols. Premium European and North American specialty bakeries have accelerated adoption since 2023. The technology is bifurcating competitive positioning: manufacturers with secured allulose supply chains command clean-label shelf space while polyol-dependent competitors retreat to value-tier positioning.
EFSA's evolving health claim protocols for glycemic response are tightening permissible marketing language across the European Union. Manufacturers must now commission clinical trials demonstrating sub-55 GI values to retain premium pricing authority. Cake and pastry categories face the steepest compliance burden due to complex fat-replacement chemistry requirements, driving consolidation toward scaled players with captive testing facilities.
Urban aging clusters are reconfiguring distribution priorities for diabetic bakery producers. Specialty retailers in Tokyo's Setagaya ward and Toronto's North York district now allocate expanded refrigerated sections to certified low-GI SKUs. Direct partnerships with endocrinology clinics and diabetes education centers are displacing conventional wholesale bakery routes in these high-prevalence corridors, capturing patients at diagnosis touchpoints.
Diabetic Bakery Products Market Segmentation
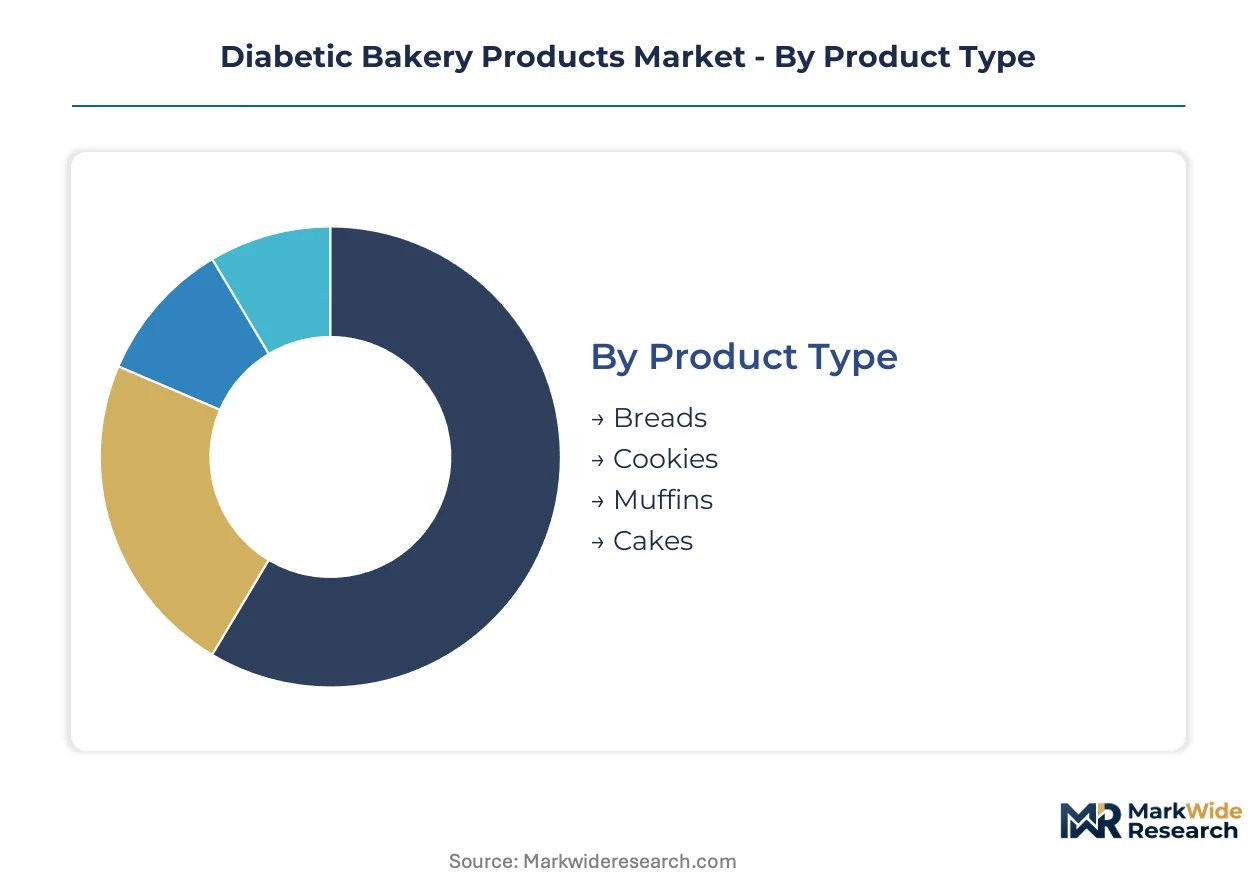
Diabetic bakery segmentation reflects divergent formulation complexity and regulatory exposure across product formats. Channel and ingredient splits reveal where clean-label premiums command pricing power versus commodity substitution.
Product Type:
Breads dominate domestic production in Germany and Japan due to shorter freshness windows and hospital procurement localization. Cakes and cookies travel further through export channels, with North American specialty retailers sourcing premium decorated cakes from scaled European manufacturers.
- Breads:Sourdough and sprouted grain formulations achieve sub-55 glycemic index values through extended fermentation and resistant starch enrichment. German hospital cafeterias in Berlin and Munich now mandate certified low-GI bread options for inpatient diabetes management programs, creating concentrated demand corridors.
- Cookies:Allulose-sweetened variants displace legacy polyol formulations in premium positioning, with monk fruit blends capturing clean-label shelf space in Japanese convenience retail. The category's longer shelf stability enables cross-border e-commerce fulfillment from North American production hubs.
- Muffins:Single-serve portions align with fitness center grab-and-go procurement in Toronto and Tokyo urban clusters.
- Cakes:Complex fat-replacement chemistry using pea protein emulsions and soluble oat fiber drives premium tier separation; EFSA health claim substantiation requirements favor scaled manufacturers with captive clinical testing facilities.
Breads hold the largest share; momentum sits with cookies as allulose supply chains mature.
Ingredient Type:
Cost tier separation runs deepest in this category, with natural sweeteners commanding 3-4x polyol pricing and fiber enrichments sitting at mid-tier positioning.
- Sugar Substitutes:Erythritol and xylitol remain volume leaders in value-tier products across Indian and Southeast Asian markets where FSSAI sugar-free claim enforcement remains less stringent than EFSA protocols.
- Natural Sweeteners:Monk fruit extract and allulose achieve clean-label positioning in premium North American and European retail, with Japanese Consumer Affairs Agency approvals accelerating adoption in Tokyo-area specialty bakeries. Supply concentration in North American allulose production creates procurement bottlenecks for European formulators.
- Whole Grain:Resistant wheat and sprouted barley flours anchor South Asian formulations tailored to regional glycemic profiles.
- Fiber Enrichments:Soluble oat and chicory root inclusions enable texture parity in reduced-fat cakes while meeting Health Canada fiber claim thresholds.
Sugar substitutes retain volume dominance; natural sweeteners are climbing the fastest as regulatory approvals expand.
Distribution Channel:
Volume concentration favors supermarkets, but margin structure inverts toward direct and specialty channels where certification premiums stick.
- Supermarkets:Mass retail chains in Germany and Canada allocate refrigerated sections to certified low-GI SKUs, with slotting fees favoring ISO 22000-certified manufacturers.
- Specialty Bakeries:Tokyo's Setagaya ward and Toronto's North York district exhibit expanded low-GI bakery counters; direct partnerships with endocrinology clinics displace conventional wholesale routes in these high-diabetes-prevalence corridors.
- Online Retail:Subscription platforms for chronic disease management bypass retail slotting fees and capture recurring revenue from insulin-resistant consumers.
- Health Food Stores:Pharmacist-staffed chains in Berlin and Vancouver provide glycemic-index counseling that drives conversion for premium-priced formulations.
Supermarkets capture the greatest volume; specialty bakeries are expanding most quickly through clinic partnerships.
End User:
Application maturity separates institutional procurement—with its mandated certification requirements—from discretionary individual purchase.
- Individuals:Aging urban populations in Berlin, Tokyo, and Toronto drive repeat purchase through direct-to-patient subscription models.
- Hospitals:German and Canadian healthcare facilities specify certified low-GI bakery options; procurement mandates require documented glycemic-index testing from EFSA-aligned protocols.
- Cafes:Third-wave coffee chains in Toronto and Berlin add low-GI pastry options to capture health-conscious demographics.
- Fitness Centers:Post-workout recovery positioning drives muffin and protein-enriched cookie placement in Tokyo and Vancouver gym retail.
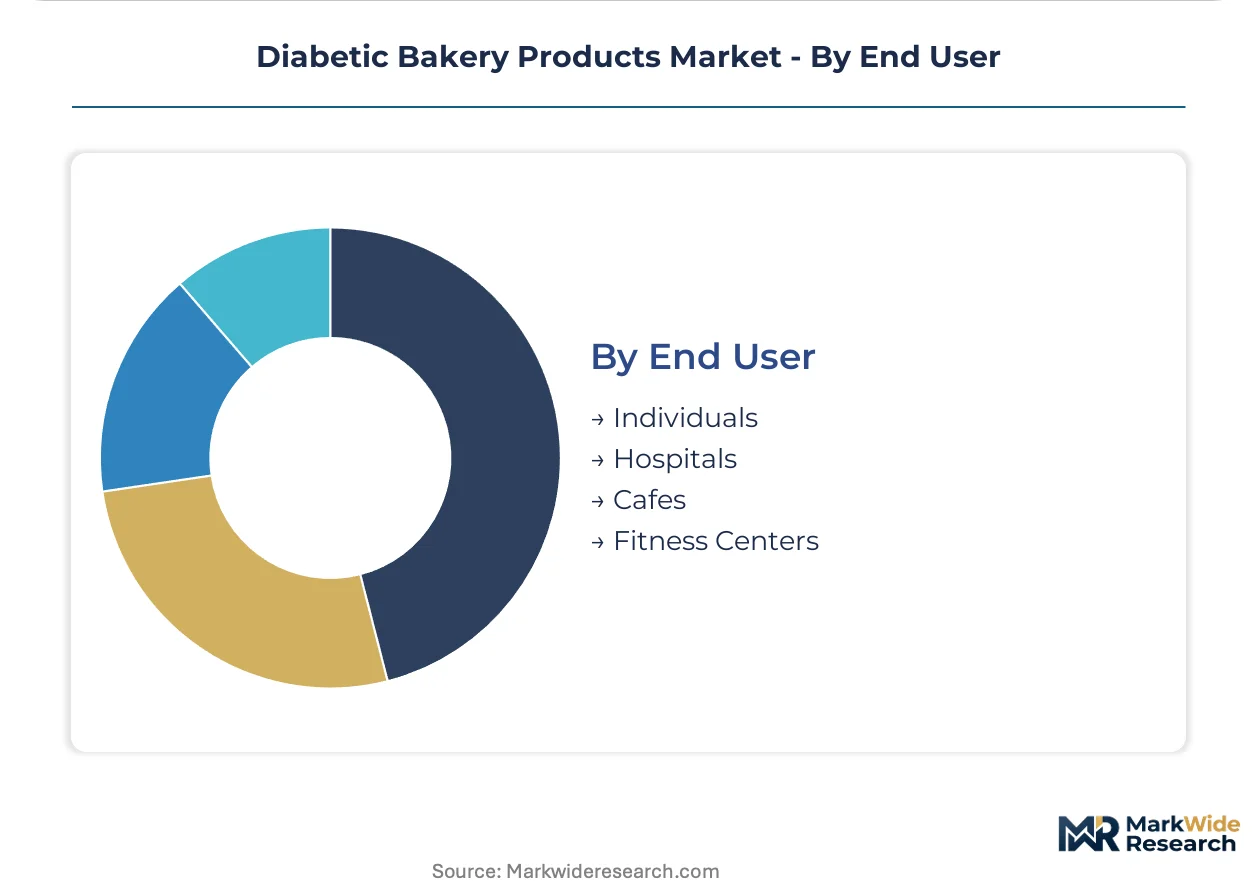
Individuals represent the largest addressable base; hospitals are gaining share fastest through procurement mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glycemic-index certification mandates from EFSA, Japan's Consumer Affairs Agency, and Health Canada are restructuring diabetic bakery supply chains across concentrated urban corridors where diabetes prevalence intersects with aging demographics.
Germany
Hospital cafeteria procurement mandates in Berlin and Munich now require documented low-GI testing aligned with EFSA protocols. The country's national food safety regulator enforces strict health claim substantiation that delays product launches by 12-18 months. Bavaria's specialty bakery cluster around Munich anchors domestic production of certified diabetic breads for inpatient diabetes management programs.
Japan
Tokyo's Setagaya ward exhibits expanded refrigerated sections for certified low-GI SKUs in specialty retail. The Consumer Affairs Agency accelerated monk fruit and allulose approvals since 2023, displacing legacy polyol formulations. Kansai's Osaka-based bakery network partners directly with endocrinology clinics to capture patients at diagnosis touchpoints.
Canada
Healthcare facilities in Toronto and Vancouver specify certified low-GI bakery options for institutional procurement. Health Canada's fiber claim thresholds and glycemic-index labeling requirements favor manufacturers with dedicated clinical testing budgets. Ontario's Greater Toronto Area concentrates demand from overlapping diabetes prevalence and health-conscious aging populations in North York district.
United States
FDA nutrition labeling rules govern permissible glycemic assertions while allulose supply concentration creates procurement bottlenecks for clean-label formulators. The agency's rare sugar approval pipeline enabled premium cookie reformulations displacing polyol-dependent competitors. California's Bay Area and Pacific Northwest metro clusters drive direct-to-patient subscription channel growth for chronic disease management platforms.
India
FSSAI tightening of sugar-free claim standards adds compliance layers for exporters targeting the country's diabetic population. Britannia Industries Limited specializes in whole-grain formulations tailored to South Asian palates and glycemic profiles. Maharashtra's Mumbai-Pune corridor anchors domestic production of fiber-enriched diabetic bakery products for urban health-conscious consumers.
Diabetic Bakery Products Market Competitive Environment
Player mix skews toward multinational packaged food conglomerates with captive distribution infrastructure and regional specialists with formulation expertise tailored to local glycemic profiles. Scale advantages concentrate in European and North American markets where ISO 22000 certification requirements and EFSA health claim protocols favor dedicated R&D investment. Three archetypes dominate: global snack conglomerates leveraging retail shelf presence, regional bakery specialists with clean-label supply chain control, and healthcare-channel direct distributors bypassing conventional wholesale routes. Competitive moves center on strategic partnerships with endocrinology clinics and portfolio diversification into allulose-based premium tiers.
Within the multinational conglomerate tier, Mondelez International and Nestlé occupy positions defined by global distribution infrastructure and European retail chain penetration. Britannia Industries Limited exemplifies the regional specialist archetype through South Asian market focus. Grupo Bimbo represents scale-driven bakery manufacturing with geographic diversification across multiple certification jurisdictions.
| Leading Market Players |
|---|
| Britannia Industries Limited |
| Dunkin' Donuts |
| Grupo Bimbo |
| Nestle |
| United Biscuits |
| Mondelez International |
| Barilla Holding |
| Kellogg |
| General Mills |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at North American allulose production facilities shapes both supply concentration and price floors for clean-label diabetic bakery tiers. Manufacturers with captive sweetener supply command premium shelf positioning while polyol-dependent competitors absorb margin compression from Brazilian tapioca starch volatility.
Pricing Analysis
Certification level creates the primary spread between diabetic bakery tiers, with ISO 22000-validated SKUs capturing 40-60% premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects glycemic-index substantiation investment, brand heritage, and after-sales clinical support bundling. Cost compression in the economy tier intensifies because Indian and Southeast Asian FSSAI enforcement gaps enable polyol formulations to undercut clean-label alternatives. Hospital procurement committees exhibit lowest price sensitivity due to mandated low-GI compliance, while individual consumers through mass retail show highest elasticity.
Supply Chain Analysis
North America anchors allulose production capacity while Brazil and Australia supply modified starch feedstocks for texture stabilization. European formulators draw from Asian monk fruit extract pipelines and regional resistant wheat starch mills. Single-source vulnerability concentrates in rare sugar manufacturing, where production bottlenecks limit scalable access for clean-label expansion. Distribution runs through hybrid models: direct-to-patient subscription platforms capture recurring revenue while ISO-certified manufacturers penetrate hospital procurement through dedicated clinical sales forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-patient subscription services for chronic disease management expand faster than conventional retail bakery SKUs, attaching recurring revenue to diagnostic touchpoints and bypassing slotting fee structures.
For Market Incumbents: Compound shelf presence through EFSA-aligned glycemic-index certification investments that delay rival launches by 12-18 months. Deepen backward integration into allulose supply chains to secure clean-label positioning as North American production bottlenecks intensify. Defend against regional specialists by acquiring clinic partnership networks in Tokyo and Toronto urban corridors. For New Entrants and Emerging Players: FSSAI fast-track compliance for sugar-free claims opens first-mover positioning in India's underserved diabetic bakery segment. Target Maharashtra's Mumbai-Pune corridor through whole-grain formulations tailored to South Asian glycemic profiles. Capture hospital cafeteria procurement in German secondary cities where incumbent coverage remains thin. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-patient subscription platforms with endocrinology clinic partnerships. Long-term viability favors scaled manufacturers with captive clinical testing facilities and multi-jurisdiction certification portfolios. Monitor allulose supply contract renewals as inflection indicator for clean-label competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Glycemic-Index Certification Investment | Clinical validation protocols delay rival launches and anchor premium pricing authority in European retail. |
| Allulose Supply Chain Backward Integration | Captive rare sugar production secures clean-label positioning as North American bottlenecks constrain competitors. |
| Direct-to-Patient Subscription Platform Launch | Recurring revenue attachment at diabetes diagnosis touchpoints bypasses conventional retail slotting structures. |
| Endocrinology Clinic Partnership Network | Prescriptive channel access in Tokyo and Toronto corridors displaces wholesale bakery distribution routes. |
| Indian FSSAI Compliance-First Market Entry | Early alignment with tightening sugar-free standards positions exporters for underserved diabetic population access. |
Study Parameters
A spread of perspectives from R&D formulation scientists, hospital procurement managers, retail category buyers, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with bakery process engineers and glycemic-index testing laboratory directors alongside secondary validation through EFSA health claim registers, FDA nutrition labeling guidance documents, and FSSAI sugar-free claim standards. Customs records for alternative sweetener imports and Health Canada fiber claim thresholds provided trade-flow triangulation. Bottom-up SKU-level modeling and top-down category sizing were reconciled across data sources.
Segmentation dimensions modeled include product format complexity, sweetener technology tier, distribution channel certification requirements, and regional regulatory cluster stringency. CAGRs were derived from volume trajectory analysis across the projection horizon, with growth rate assumptions stress-tested against hospital procurement mandate expansion timelines and clean-label sweetener approval pipelines. Industry-specific forecast inputs incorporated modified starch cost volatility patterns and glycemic-index testing capacity constraints at EFSA-aligned laboratories.
Underlying assumptions cover sustained regulatory enforcement of low-GI labeling requirements, with deviation risk concentrated in allulose supply expansion timelines and FSSAI claim standard implementation pacing. Forecasts reflect these conditions without claiming predictive certainty. Recalibration cycles align with material shifts in rare sugar production capacity and glycemic-index certification protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Ready-To-Finish Bakery Products Market
Bakery Products
Instant Cake Gel Market
Bakery Products
Teaseed Cake Market
Bakery Products
Bread Improver Market
Bakery Products
GCC Bakery Products Market
Bakery Products
Organic Bread Flour Market
Bakery Products
Oman Frozen Bakery Products Market
Bakery Products
Frozen Bakery Additives Market
Bakery Products
South America Bakery Products Market
Bakery Products
Healthy Biscuits Market
Bakery Products
Yeastless Dough Market
Bakery Products
Ice Cream Cake Market
Bakery Products
North America Bakery Products Market
Bakery Products
Banana Bread Market
Bakery Products
Global Cake Mix Market
Bakery Products
Bakery Emulsions Market