
 Asia-Pacific Machine Control System Market | 2026-2036
Asia-Pacific Machine Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Machine Control System Market Outlook
Integration of artificial intelligence into real-time kinematic positioning is reshaping how machine control systems coordinate earthmoving and precision agriculture workflows. Trimble Inc. leverages deep R&D investment in GNSS-inertial fusion to sustain technology leadership across Japanese construction automation projects. Topcon Corporation anchors its competitive position through specialized optical and laser-based machine guidance systems for Korean infrastructure contractors. Hexagon competes aggressively by extending its sensor-to-software portfolio into autonomous mining operations across Western Australia and Indonesia.
Asia-Pacific machine control systems encompass hardware-software platforms that fuse satellite positioning, inertial measurement, and hydraulic actuation to automate blade, bucket, and boom movements within three-centimeter accuracy tolerances. These systems primarily serve to eliminate manual staking, reduce material overages, and compress project timelines in civil engineering and resource extraction. Programmable logic controllers occupy the mature core of the product stack, with stable replacement cycles across Japanese automotive stamping lines. IoT solutions represent the fastest-expanding technology dimension, as cloud-connected telematics modules enable predictive maintenance for Chinese excavator fleets. Process automation applications concentrate the largest margin pools, particularly in Australian iron ore operations where downtime costs exceed thousands of dollars per hour.
Japan's Ministry of Economy, Trade and Industry enforces JIS standards that mandate electromagnetic compatibility and functional safety certifications for construction automation equipment, elevating compliance costs for non-domestic suppliers. China's Ministry of Industry and Information Technology administers GB standards and dual carbon implementation rules that compel machine control vendors to optimize energy consumption algorithms in electrified heavy equipment. India's Bureau of Indian Standards and Central Electricity Authority jointly shape product approval pathways for automation systems deployed in power infrastructure projects. Stakeholders must monitor how divergent certification timelines across these three regulatory regimes affect platform standardization strategies and regional go-to-market sequencing.
Market Dynamics
China's dual carbon goals are forcing electrification retrofits across heavy machinery fleets, compressing replacement cycles for hydraulic control architectures and accelerating vendor R&D budgets toward energy-efficient actuation systems.
Growth Catalysts
- India's earthmoving equipment modernization:Bureau of Indian Standards certification pathways for automation systems in power infrastructure are unlocking public sector procurement at scale.
- GNSS-inertial fusion technology:Real-time kinematic positioning with AI-enhanced sensor fusion is eliminating manual staking workflows in Japanese construction automation.
- Western Australian iron ore automation:Downtime economics exceeding thousands of dollars per hour are compelling autonomous mining investments with predictive maintenance modules.
Market Restraints
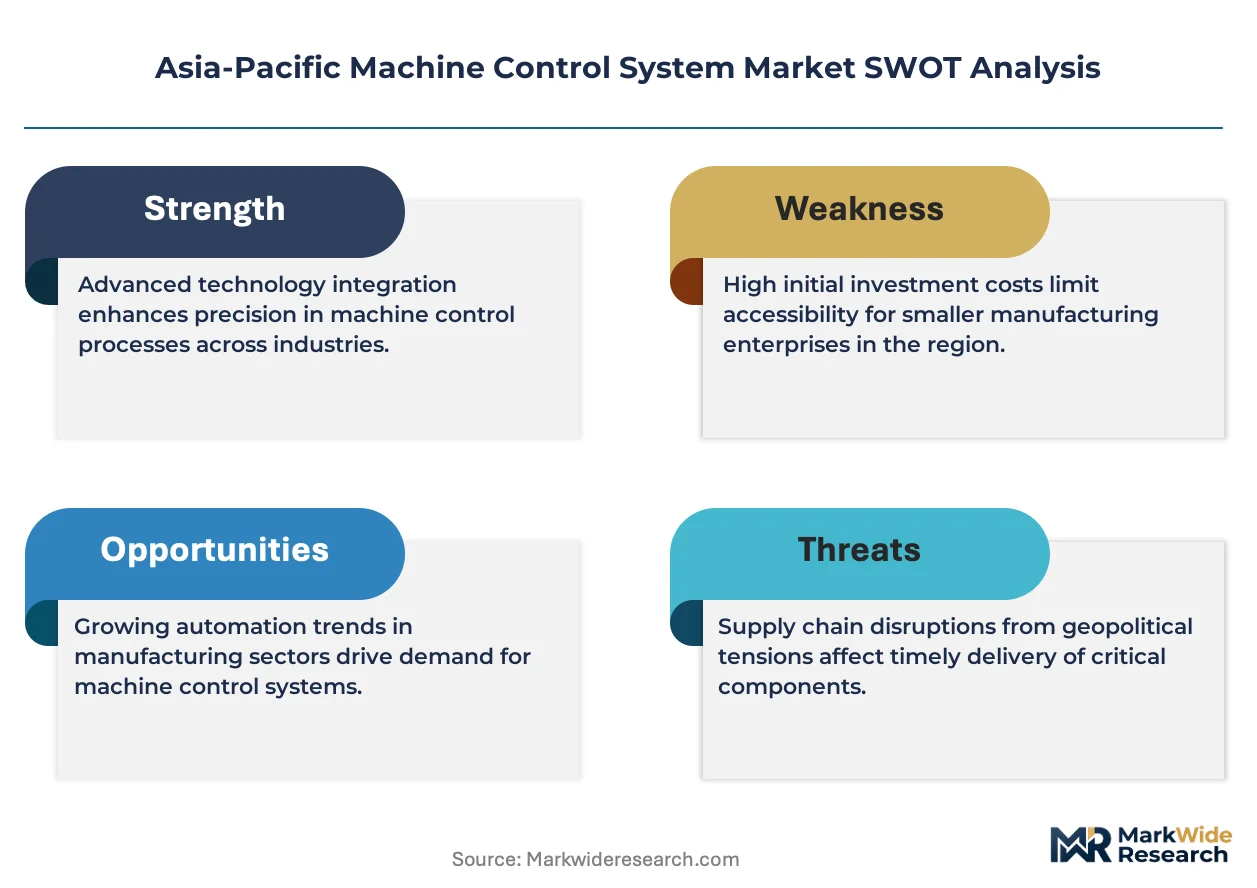
- Sensor supply concentration:High-precision inertial measurement units concentrate among a limited set of qualified suppliers, creating input bottlenecks for regional system integrators.
- JIS certification costs:Japan's Ministry of Economy, Trade and Industry electromagnetic compatibility mandates elevate compliance expenditures for non-domestic equipment vendors.
- Optical guidance substitution:Laser-based machine guidance systems in Korean infrastructure projects compete directly with satellite-dependent architectures in GPS-denied environments.
Strategic Opportunities
- Indonesian autonomous mining:Sensor-to-software portfolio extensions into unmanned haulage operations present white space for integrated platform providers.
- Cloud-connected telematics:IoT modules enabling fleet-wide predictive maintenance are penetrating Chinese excavator markets faster than traditional PLC replacement cycles.
- MIIT energy algorithms:China's Ministry of Industry and Information Technology dual carbon implementation rules create regulatory tailwinds for electrified control system optimization.
Industry Challenges
- Functional safety certification timelines:Divergent approval pathways across Japan's METI, China's MIIT, and India's BIS/CEA regimes complicate platform standardization strategies.
- Legacy hydraulic integration:Retrofitting electrified actuation into existing earthmoving fleets requires bespoke engineering that stretches deployment timelines and technical service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Machine Control System Market |
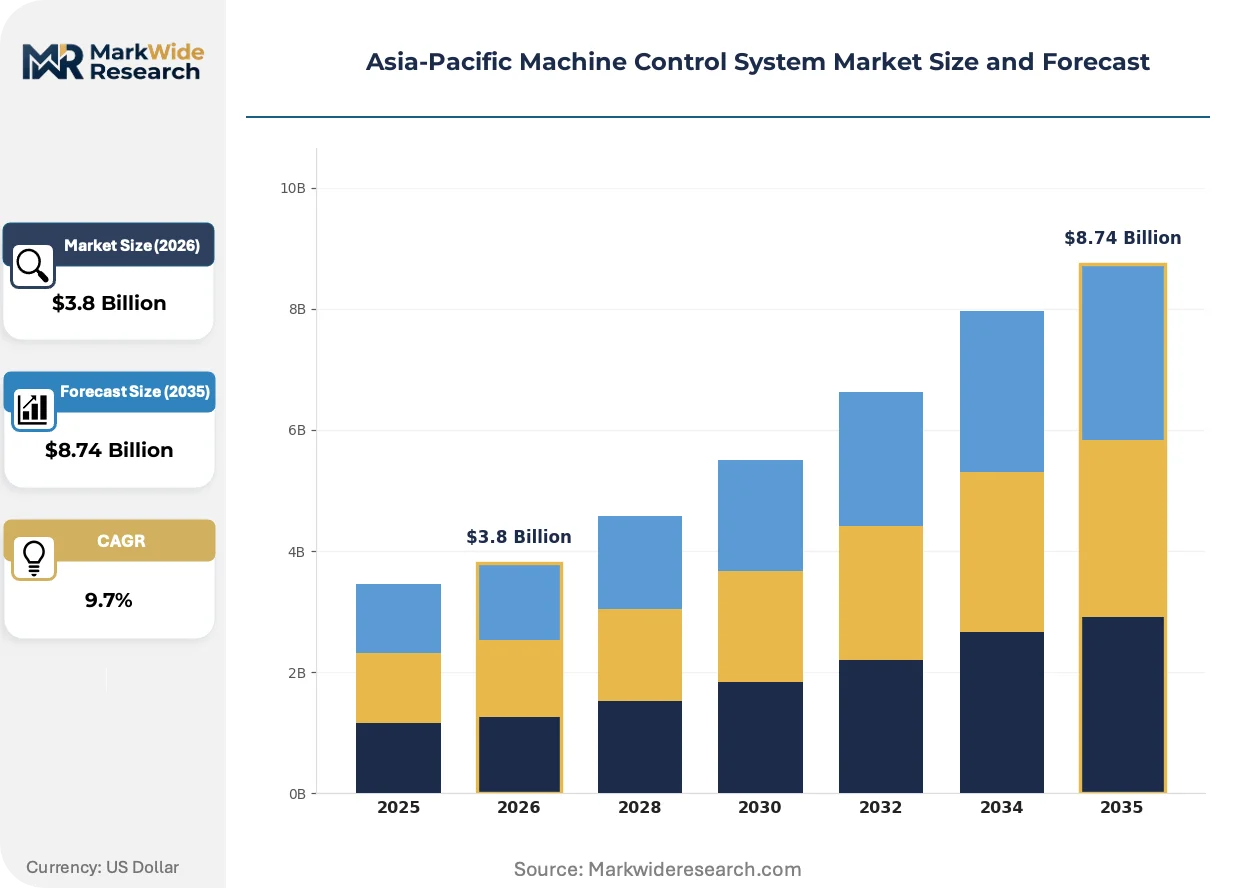
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable Logic Controllers, Distributed Control Systems, Supervisory Control and Data Acquisition, Human-Machine Interface Technology: Embedded Systems, Cloud Computing, IoT Solutions, Artificial Intelligence End User: Manufacturing, Oil & Gas, Automotive, Construction Application: Process Automation, Robotics, Motion Control, Asset Management |
| Companies Covered | Trimble Inc., Topcon Corporation, Hexagon, MOBA Mobile Automation AG, ABB, Schneider Electric SE, Komatsu Ltd, Leica Geosystems AG, Hemisphere GNSS Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Machine Control System Market Strategic Shifts
Artificial intelligence integration is compressing the accuracy-to-cost ratio for machine guidance, enabling three-centimeter tolerances to propagate beyond premium civil engineering into mid-market construction segments.
AI-enhanced real-time kinematic positioning is rendering obsolete manual blade and bucket control in Southeast Asian construction fleets. Korean and Japanese contractors are adopting autonomous grade control systems at replacement-cycle velocity rather than waiting for full fleet turnover. The structural consequence is collapsing demand for traditional survey staking services and compressing project timeline risk premiums.
China's MIIT dual carbon implementation rules mandate energy consumption optimization algorithms in electrified heavy equipment control architectures. This regulatory pressure is accelerating vendor investment in regenerative hydraulic systems and motor-inverter integration. Construction and mining equipment categories face the steepest compliance curves, with domestic Chinese manufacturers adapting faster than import-dependent competitors.
Equipment-as-a-service contracting is displacing outright ownership for machine control systems in Australian iron ore and Indonesian coal operations. Mining contractors now prefer bundled hardware-software-maintenance agreements that transfer obsolescence risk to vendors. This shift is most visible in Western Australia, where autonomous haulage downtime costs have made outcome-based pricing the default procurement mode for new fleet deployments.
Asia-Pacific Machine Control System Market Segmentation
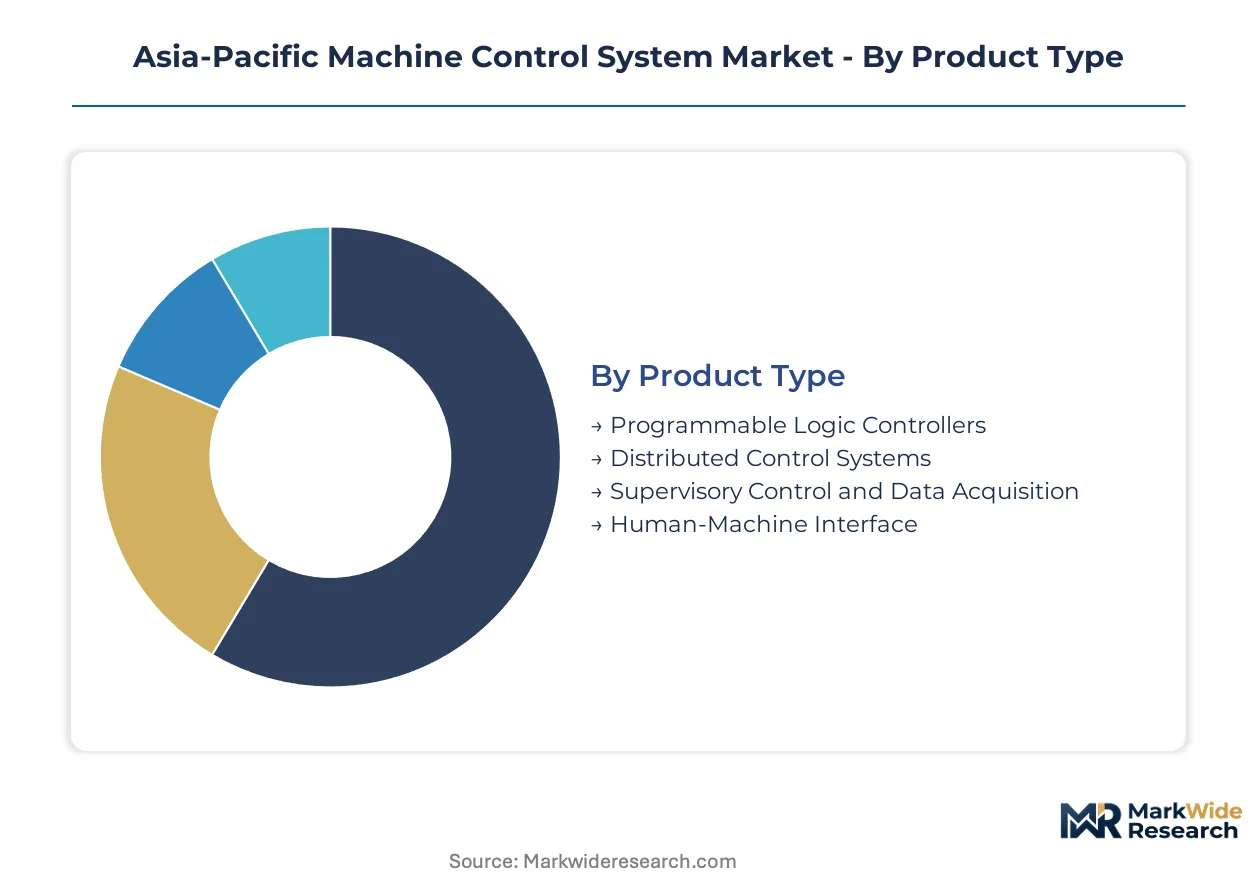
Machine control system architectures in Asia-Pacific diverge sharply across deployment contexts, from Japanese automotive stamping lines requiring deterministic PLC cycles to Australian mining operations demanding cloud-orchestrated autonomous haulage. Segmentation reveals how vendor R&D budgets allocate across hardware-software boundaries and which regulatory regimes shape certification requirements for each product category.
Product Type:
Use-case spectrum spans legacy factory floors through distributed mineral processing networks, with each architecture imposing distinct latency tolerances and safety integrity levels.
- Programmable Logic Controllers:Deterministic control hardware executes millisecond-precision logic sequences for discrete manufacturing operations. Japanese automotive stamping lines maintain stable replacement cycles here, though electrification retrofits under China's MIIT dual carbon rules are compressing traditional upgrade timelines.
- Distributed Control Systems:Decentralized process control architectures coordinate continuous operations across geographically spread production nodes. Australian iron ore beneficiation plants and Indonesian LNG facilities concentrate demand, driven by uptime economics where hourly downtime costs exceed thousands of dollars.
- Supervisory Control and Data Acquisition:Layered monitoring systems aggregate field-level telemetry for centralized visualization and alarm management.
- Human-Machine Interface:Operator-facing visualization platforms translate machine states into actionable control inputs.
The dominant share belongs to Programmable Logic Controllers, while Distributed Control Systems is closing the gap fastest.
Technology:
Cost tier stratification separates capital-intensive embedded hardware from subscription-weighted cloud services, with integration complexity escalating at the intersection.
- Embedded Systems:Dedicated microprocessor architectures execute real-time control loops with hard deterministic guarantees. Korean semiconductor packaging lines and Indian power infrastructure projects anchor procurement, constrained by high-precision inertial measurement unit supply bottlenecks among qualified vendors.
- IoT Solutions:Cloud-connected telematics modules stream operational data for predictive maintenance algorithms. Chinese excavator fleets are penetrating this category faster than traditional PLC replacement cycles, driven by MIIT-mandated energy consumption optimization requirements.
- Cloud Computing:Remote computational resources host simulation, optimization, and fleet orchestration workloads.
- Artificial Intelligence:Machine learning inference engines enhance sensor fusion and autonomous decision-making.
Embedded Systems commands the largest installed base, though IoT Solutions is expanding most quickly as electrified fleet retrofits accelerate across the region.
End User:
Application maturity varies dramatically, with process industries exhibiting stable replacement patterns while construction automation undergoes technology disruption.
- Manufacturing:Discrete and process production facilities deploy machine control for quality consistency and throughput maximization. Japanese automotive and electronics contract manufacturers sustain the core revenue pool, with JIS electromagnetic compatibility certification acting as a non-domestic vendor barrier.
- Construction:Earthmoving and precision grading operations adopt automated blade and bucket control to eliminate manual staking. Southeast Asian fleet expansion and India's Bureau of Indian Standards certification pathways for power infrastructure automation are unlocking public sector procurement at scale.
- Oil & Gas:Upstream extraction and downstream refining operations depend on safety-instrumented control systems.
- Automotive:Stamping, welding, and final assembly lines require synchronized multi-axis motion control.
Manufacturing retains the deepest penetration, yet Construction is gaining share fastest as AI-enhanced GNSS-inertial fusion displaces traditional survey workflows.
Application:
Margin concentration follows downtime exposure, with continuous process industries commanding premium pricing against discrete automation.
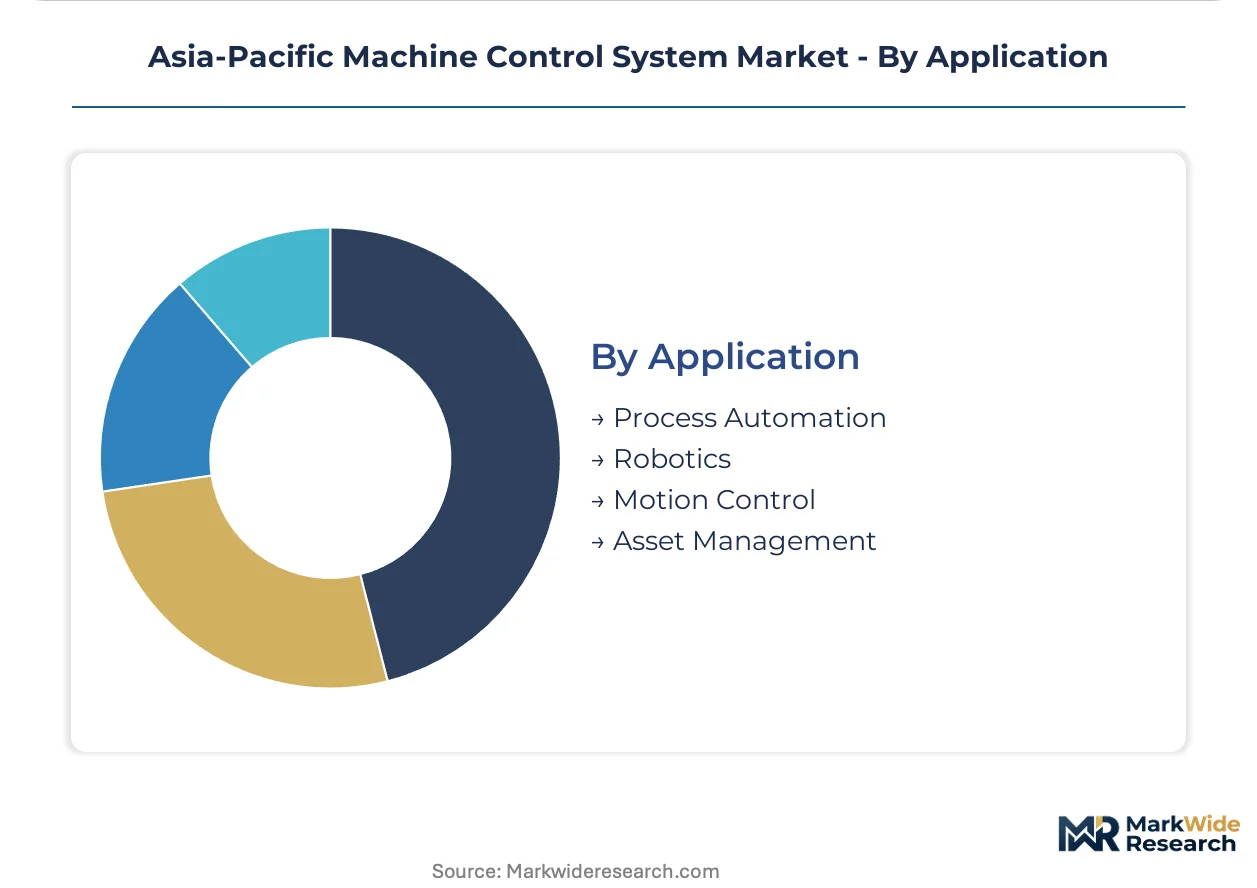
- Process Automation:Closed-loop control of continuous manufacturing and resource extraction operations. Australian iron ore and Indonesian coal mining concentrate the largest margin pools, where autonomous haulage downtime economics have made outcome-based equipment contracting the default procurement mode.
- Robotics:Coordinated multi-axis motion control for manipulator arms and autonomous vehicles. Korean infrastructure contractors and Japanese construction automation projects are adopting autonomous grade control systems at replacement-cycle velocity rather than awaiting full fleet turnover.
- Motion Control:Precision positioning of mechanical axes for tooling and material handling.
- Asset Management:Lifecycle optimization of equipment through condition monitoring and predictive analytics.
Process Automation captures the highest value per installed node, while Robotics is climbing the fastest as autonomous grade control propagates beyond premium civil engineering into mid-market construction segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese machine control system exports flow primarily into Southeast Asian construction automation projects, while Australian mining technology procurement draws heavily from European sensor-to-software portfolios. This trade-flow pattern shapes competitive positioning across the Asia-Pacific region.
China
Electrified heavy equipment retrofits and excavator fleet telematics dominate procurement priorities under MIIT dual carbon implementation rules. GB standards compliance now mandates energy consumption optimization algorithms in all new control architectures. Yangtze River Delta construction equipment manufacturers are accelerating domestic sourcing of GNSS-inertial fusion modules to reduce import dependency.
Japan
Automotive stamping line automation and precision agriculture systems sustain replacement-cycle demand for PLC-based architectures. METI enforces JIS electromagnetic compatibility and functional safety certifications that elevate compliance costs for non-domestic equipment vendors. Kanto region electronics contract manufacturers are integrating AI-enhanced sensor fusion into existing production lines without full system overhaul.
India
Earthmoving equipment modernization and power infrastructure automation unlock public sector procurement at scale through Bureau of Indian Standards certification pathways. Central Electricity Authority joint approvals shape deployment timelines for grid-connected control systems. Maharashtra and Gujarat construction hubs are adopting automated grade control systems for highway and dam projects ahead of monsoon construction windows.
Australia
Autonomous mining operations and iron ore beneficiation plants concentrate demand for distributed control systems with predictive maintenance modules. TGA-equivalent functional safety requirements apply to autonomous haulage deployments in Western Australia. Pilbara region mining contractors have shifted to equipment-as-a-service contracting that transfers obsolescence risk to system vendors.
South Korea
Infrastructure contractors and semiconductor packaging lines drive parallel demand for optical guidance systems and embedded control hardware. Korean industrial automation standards align with international IEC frameworks while maintaining domestic certification preferences. Busan-Ulsan manufacturing corridor specialists are deploying laser-based machine guidance in GPS-denied tunneling environments.
Asia-Pacific Machine Control System Market Competitive Environment
Channel-controlling players compete with product-specialist players across hardware-software boundaries, creating a tiered market structure where scale advantages concentrate in mining automation while construction segments fragment across regional system integrators. The vendor base separates into three archetypes: sensor-to-software platform providers, GNSS-inertial fusion technology specialists, and legacy PLC distributors with retrofit capabilities. Dominant competitive moves include strategic partnerships for certification pathway navigation and portfolio diversification into electrified actuation systems.
Among North American and European technology providers, Trimble Inc., Topcon Corporation, and Hexagon occupy positions that exemplify the platform-provider archetype. Trimble represents the GNSS-inertial fusion specialist with deep R&D positioning in construction automation. Topcon anchors the optical and laser-based guidance segment for infrastructure contractors. Hexagon sits within the sensor-to-software integration tier with mining automation portfolio extensions. These three entities demonstrate how geographic origin and technology heritage shape competitive positioning without requiring identical go-to-market structures.
| Leading Market Players |
|---|
| Trimble Inc. |
| Topcon Corporation |
| Hexagon |
| MOBA Mobile Automation AG |
| ABB |
| Schneider Electric SE |
| Komatsu Ltd |
| Leica Geosystems AG |
| Hemisphere GNSS Inc |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in high-precision inertial measurement unit fabrication across Japan and South Korea is tightening supplier pricing power while compressing margin buffers for regional system integrators bidding on Australian mining automation contracts.
Pricing Analysis
Current-generation GNSS-inertial fusion modules command substantial premiums against prior-generation optical guidance systems and emerging next-generation AI-enhanced sensor platforms. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified architectures for Japanese automotive lines from uncertified imports and domestically produced Chinese alternatives under GB standards. Pricing pressure stems from MIIT-mandated energy consumption optimization requirements that force R&D cost absorption. Mid-market construction segments in Southeast Asia exhibit highest price sensitivity, while Australian iron ore operators prioritize uptime economics over unit cost.
Supply Chain Analysis
Tariff exposure between China and key technology-exporting nations dominates supply chain risk planning for machine control system vendors. Component fabrication concentrates in Japan, South Korea, and Taiwan, with final assembly drawing from Chinese Yangtze River Delta capacity. High-precision inertial measurement units, specialized optical encoders, and motor-inverter assemblies anchor critical input dependencies. Single-source vulnerability around qualified IMU suppliers creates procurement bottlenecks for non-domestic vendors. Distribution runs through authorized system integrator networks in construction segments and direct OEM relationships in mining automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting around sensor-to-software integration as equipment-as-a-service contracting transfers obsolescence risk from mining operators to vendors, collapsing traditional hardware-software boundary pricing.
For Market Incumbents: Build certification moats through accelerated JIS and GB standard pre-approval investments ahead of competitor entry timelines. Deepen backward integration into inertial measurement unit supply through captive production partnerships with Korean semiconductor fabricators. Channel control through exclusive distribution agreements with Australian mining contractors defends against emerging sensor-to-software platform entrants. For New Entrants and Emerging Players: Mid-market earthmoving contractors in Indonesia and Vietnam represent the most penetrable entry point for cloud-connected telematics modules bypassing legacy PLC replacement cycles. Target Indian Bureau of Indian Standards certification pathways for power infrastructure automation as a regulatory-fast-track wedge. Go-to-market execution through equipment rental fleet partnerships transfers customer acquisition cost to channel partners. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across IoT-enabled predictive maintenance sub-segments as subscription revenue streams displace hardware-heavy business models. Acquisition target archetypes include specialized optical guidance firms with Korean infrastructure contractor relationships and domestic Chinese vendors with MIIT compliance pre-certification. Monitor equipment-as-a-service contract penetration rates in Western Australian iron ore as the signal for platform economics tipping point.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-to-Software Platform Integration | Unifies GNSS-inertial fusion with cloud telemetry for Australian autonomous mining operations. |
| MIIT Dual Carbon Compliance Investment | Positions vendors for GB standards certification in Chinese electrified heavy equipment procurement. |
| Backward Integration into IMU Supply | Reduces single-source dependency for Japanese automotive stamping line automation vendors. |
| Equipment-as-a-Service Contracting | Transfers obsolescence risk to vendors in Western Australian iron ore outcome-based pricing. |
| Strategic Partnership with System Integrators | Accelerates JIS certification pathway navigation for non-domestic construction automation entrants. |
Study Parameters
Desk research of customs trade databases, SEC filings from automation technology providers, and GB standards documentation preceded structured interviews with mining operations managers, construction fleet procurement directors, OEM platform engineers, and aftermarket service heads. Primary fieldwork across Japan, China, India, and Australia validated secondary estimates of replacement cycle timing and certification pathway duration. Bottom-up unit economics modeling triangulated against top-down market sizing from equipment production data.
Assumption sets held fixed regulatory implementation timelines across METI, MIIT, and BIS regimes while varying electrification retrofit penetration rates and equipment-as-a-service adoption curves across the projection horizon. Segmentation dimensions modeled include product architecture type, technology tier, end-use industry vertical, application maturity, and regional regulatory cluster. CAGRs derived from weighted average of historical replacement cycle analysis and forward-looking procurement survey data. Industry-specific forecast inputs incorporated iron ore spot price volatility effects on Australian mining automation capex and monsoon construction window timing for Indian earthmoving equipment deployment.
Macroeconomic conditions sit as an overlay; deviation in Chinese construction fixed-asset investment, Australian mining commodity prices, or yen-yuan exchange rate volatility would shift the trajectory. Forecasts reflect documented assumptions around certification timeline convergence and electrification retrofit cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Electric Vehicle (EV) Sensor Market
Sensors and Controls
Gesture Control Market
Sensors and Controls
Global Fluid Management and Visualization Systems Market
Sensors and Controls
Air Particle Monitor System Market
Sensors and Controls
Antenna Transducer and Radome Market
Sensors and Controls
Thin Film Sensor Market
Sensors and Controls
High-End Accelerometer Market
Sensors and Controls
Laser Sensor Market
Sensors and Controls
Smart Temperature Management Market
Sensors and Controls
US Digital Thermometer Market
Sensors and Controls
Asia-Pacific Nano Radiation Sensors Market
Sensors and Controls
Middle-East and Africa Nanosensors Market
Sensors and Controls
Electromagnetic Tracking Systems Market
Sensors and Controls
Europe Touch Sensor Market
Sensors and Controls
Wireless Temperature Sensor Market
Sensors and Controls
Piezoelectric Materials Market