
 Photoresist Removal Market | 2026-2036
Photoresist Removal Market Size, Share, and Industry Trends Forecast 2026-2036
Photoresist Removal Market Insights
East Asian specialty chemical producers is rebalancing capacity toward semiconductor-grade formulations as advanced lithography nodes multiply stripping steps per wafer. Fujifilm Corporation leverages its integrated position in both photoresist and removal chemistries to capture value across process sequences. DuPont de Nemours, Inc. sustains R&D intensity in low-particulate aqueous formulations for sub-7nm applications. Entegris, Inc. dominates contamination-controlled fluid handling systems that pair with removal chemistries in high-volume fabs.
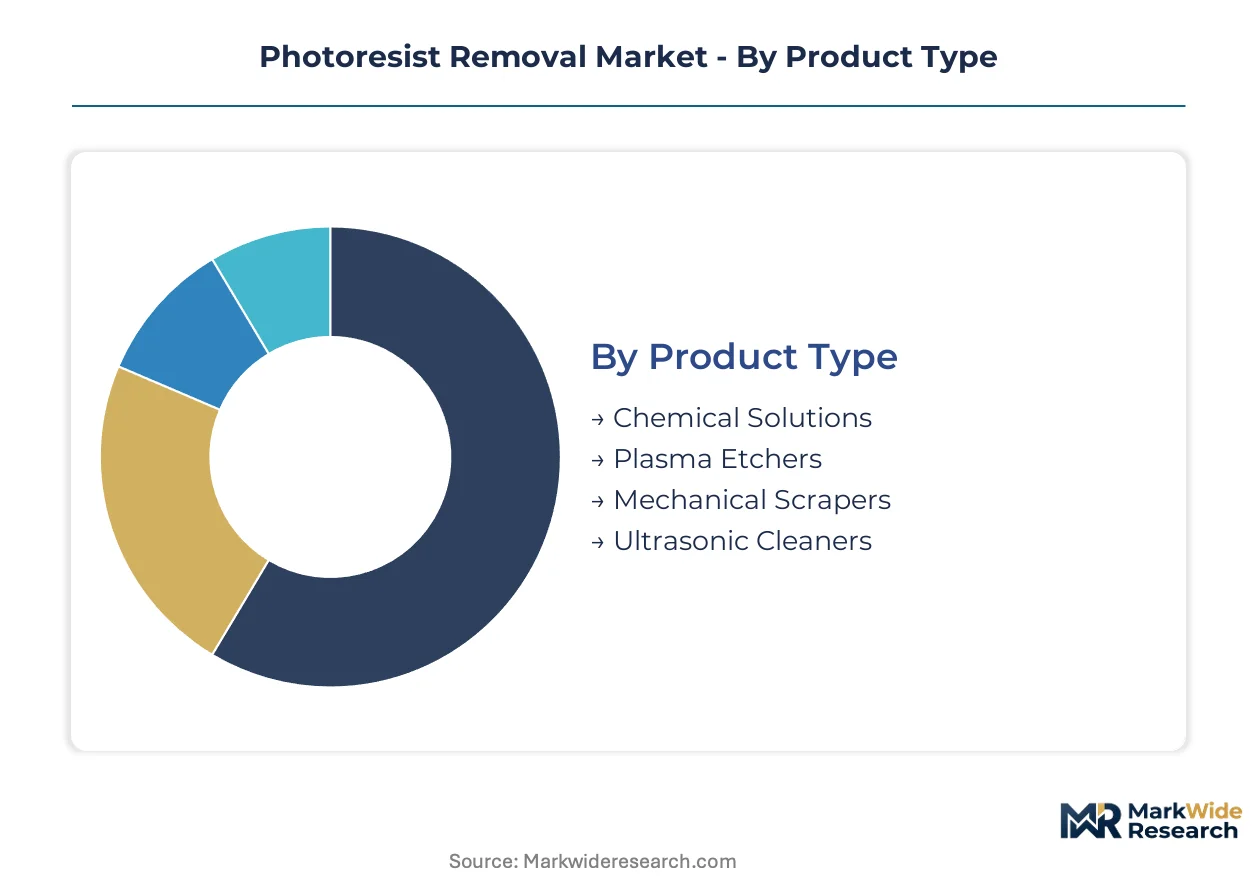
Photoresist removal encompasses the selective dissolution or ablation of light-sensitive polymer masks from wafer surfaces following pattern transfer, typically requiring controlled pH, temperature, and metallic ion thresholds below parts-per-billion levels to prevent device contamination. Chemical Solutions remains the largest product category by volume, though Plasma Etchers claims the fastest structural expansion as dry stripping displaces solvent baths at critical layers. Wet Processes still anchors mainstream logic and memory production, while Hybrid Techniques capture margin pools in advanced packaging where sequential wet-dry protocols reduce substrate damage.
EPA enforcement of effluent limitations under the Clean Water Act constrains solvent-based discharge from US fabs, while REACH registration requirements in Europe restrict certain amine-based strippers from cross-border supply. Japan's METI chemical management guidelines and South Korea's K-REACH parallel frameworks add compliance layers for multinational suppliers. Stakeholders must monitor regulatory divergence between jurisdictions as it fragments formulation portfolios and reshapes regional supply qualifications.
Market Dynamics
Advanced node lithography at Taiwan Semiconductor Manufacturing and Samsung Foundry multiplies stripping cycles per wafer from single-digit to double-digit steps, concentrating chemical demand in East Asian fabrication corridors while forcing chemistry suppliers to certify formulations at parts-per-trillion contamination thresholds.
Growth Catalysts
- Sub-7nm Ramp:Logic foundries in Taiwan and South Korea now require three to five photoresist removal steps per critical layer, expanding solvent and plasma chemistry consumption per wafer processed.
- REACH Substitution Mandate:ECHA restrictions on N-Methyl-2-pyrrolidone and glycol ether solvents are accelerating qualification of aqueous and plasma-based alternatives in European-bound supply chains.
- Advanced Packaging Proliferation:Hybrid wet-dry stripping protocols for 3D-IC and fan-out wafer-level packaging are creating incremental chemistry demand beyond traditional front-end applications.
Market Restraints
- Fluorinated Solvent Cost Volatility:Perfluorinated compound feedstock prices fluctuate with refrigerant market dynamics, compressing margins on plasma etcher consumables.
- East Asian Supply Concentration:Over 70% of high-purity chemical production capacity resides in Japan and South Korea, creating geographic vulnerability for non-regional fabs.
- Sub-3nm Technical Ceiling:Plasma damage to fragile low-k dielectric materials at advanced nodes limits dry stripping penetration at certain metallization layers.
Strategic Opportunities
- US Fab Buildout:CHIPS Act incentives for Arizona and Texas semiconductor manufacturing are creating greenfield demand for domestic chemical qualification and blending capacity.
- Carbon-Neutral Chemistry:EU Green Deal carbon border adjustments favor suppliers with renewable feedstock sourcing and closed-loop solvent recovery systems.
- Single-Wafer Processing Convergence:Integration of point-of-use chemical blending with plasma strip modules enables real-time formulation adjustment for heterogeneous integration applications.
Industry Challenges
- Metrology Talent Scarcity:Parts-per-trillion contamination analysis requires specialized mass spectrometry expertise that outpaces current semiconductor technician training pipelines.
- Multi-Jurisdiction Certification Lag:Simultaneous EPA, ECHA, METI, and K-REACH registration timelines extend new formulation commercialization by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photoresist Removal Market |
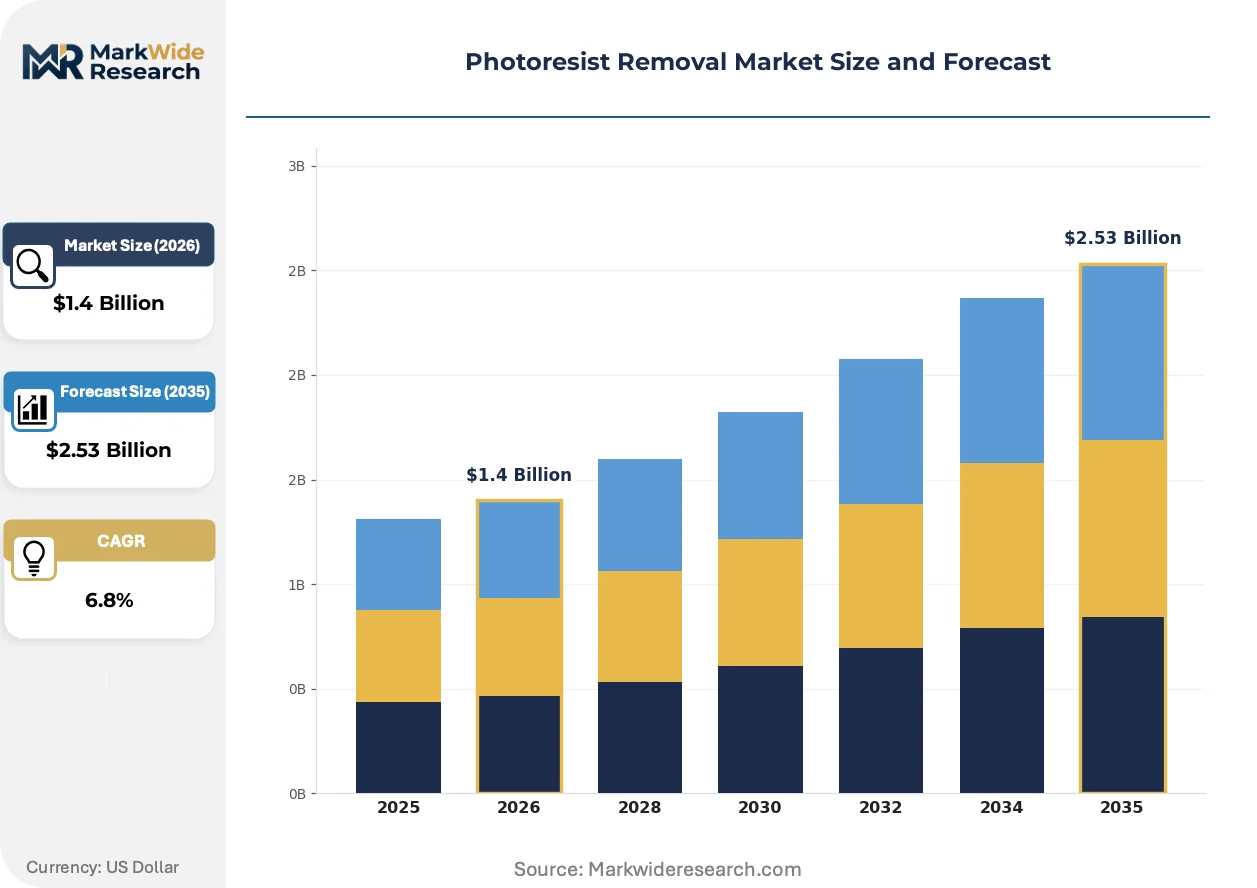
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Solutions, Plasma Etchers, Mechanical Scrapers, Ultrasonic Cleaners Technology: Wet Processes, Dry Processes, Hybrid Techniques, Laser-Based Application: Semiconductor Manufacturing, Flat Panel Display, Microelectromechanical Systems, Printed Circuit Boards End User: Foundries, Integrated Device Manufacturers, Electronics Manufacturers, Universities |
| Companies Covered | Fujifilm Corporation, Mitsubishi Gas Chemical, DuPont de Nemours, Inc., Avantor, Inc., Shin-Etsu Chemical Co., Ltd., Tokyo Ohka Kogyo Co., Ltd., Entegris, Inc., Sumitomo Chemical Co., Ltd., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photoresist Removal Market Trends and Innovations
Photoresist removal technology is bifurcating between extreme purity aqueous formulations for critical layers and high-throughput plasma systems for non-critical stacks, with hybrid protocols emerging at packaging nodes where substrate damage tolerance is lowest.
Supercritical carbon dioxide cleaning is absorbing niche applications in MEMS and photonics manufacturing where aqueous chemistries risk stiction or corrosion of released mechanical structures. Analog Devices and Bosch Sensortec have piloted scCO2 modules for accelerometer wafer processing. The technology is absorbing margin pools previously captured by specialized solvent formulations in damage-sensitive device categories.
EPA effluent guidelines under the Clean Water Act are tightening discharge limits for nitrogen-bearing organic compounds from wet stripping operations, forcing US-based fabs to install on-site wastewater treatment or switch to zero-liquid-discharge chemistries. Semiconductor facilities in Arizona and Oregon face the most stringent upcoming limits and are accelerating plasma etcher adoption for layers where process latitude permits.
Consolidated procurement through equipment-chemistry bundling contracts is displacing standalone chemical purchasing at leading-edge fabs. Applied Materials and Lam Research now specify qualified chemistry suppliers within tool service agreements, capturing multi-year volume commitments. Taiwan and South Korea display the most advanced bundling penetration, with foundries negotiating total-cost-per-wafer metrics rather than per-liter chemical pricing.
Photoresist Removal Market Segmentation
Photoresist removal technologies fragment across wet, dry, and hybrid modalities that trade off throughput against damage sensitivity at each node. Chemistry purity specifications and equipment integration requirements create distinct procurement pools that rarely overlap within single fabs.
Product Type:
Product classification centers on the physical mechanism of resist dissolution or ablation, with chemistry and equipment suppliers occupying fundamentally different margin structures.
- Chemical Solutions:Aqueous and solvent-based formulations dominate volume, requiring parts-per-trillion metallic ion control for sub-7nm layers. Taiwan Semiconductor Manufacturing and Samsung Foundry concentrate procurement through consolidated chemical management contracts that bundle formulation supply with waste handling services.
- Plasma Etchers:Dry stripping systems displace solvent baths at critical metallization layers where aqueous chemistries risk dielectric damage. South Korea's Pyeongtaek complex and Taiwan's Hsinchu corridor are installing high-density plasma modules to reduce liquid effluent volumes under tightening EPA and ECHA discharge limits.
- Mechanical Scrapers:Physical removal via brush or pad contact addresses thick-film resists in packaging applications where chemical selectivity is limited. Bosch Sensortec employs mechanical clearing for MEMS cavity structures where liquid entrapment would cause stiction failures.
- Ultrasonic Cleaners:Megasonic agitation accelerates aqueous chemistry penetration in high-aspect-ratio features. Analog Devices utilizes these systems for photonics waveguide processing where acoustic cavitation outperforms static immersion.
Chemical Solutions leads on scale; Plasma Etchers leads on momentum.
Technology:
Process modality selection hinges on substrate damage tolerance and contamination thresholds rather than unit economics alone.
- Wet Processes:Solvent and aqueous baths remain the workhorse for logic and memory production, with formulation suppliers certifying chemistries at Taiwan Semiconductor Manufacturing and Intel's Arizona facilities. EPA effluent guidelines under the Clean Water Act are forcing US fabs toward closed-loop solvent recovery or zero-liquid-discharge alternatives.
- Dry Processes:Oxygen-based plasma stripping eliminates liquid waste streams entirely, gaining share at layers where low-k dielectric damage is manageable. Samsung Foundry has qualified downstream microwave plasma systems for non-critical stack removal in Pyeongtaek.
- Hybrid Techniques:Sequential wet-dry protocols minimize substrate damage in 3D-IC and fan-out wafer-level packaging. ASE Group and Amkor Technology deploy hybrid sequences for silicon interposer cleaning where pure plasma would crack fragile dielectrics.
- Laser-Based:Excimer laser ablation addresses niche photoresist removal in photonics and MEMS where thermal budget constraints prohibit plasma exposure. Coherent supplies UV laser modules for silicon photonics foundries in Rochester, New York.
Wet Processes anchors mainstream volume; Hybrid Techniques climbs the fastest.
Application:
End-use application determines purity grade, throughput requirements, and regulatory exposure for removal chemistry suppliers.
- Semiconductor Manufacturing:Logic and memory fabs consume the highest-purity formulations, with Taiwan and South Korea foundries specifying parts-per-trillion contamination thresholds. Advanced node ramp at Samsung and TSMC multiplies stripping steps per wafer from single-digit to double-digit cycles.
- Flat Panel Display:Large-area substrate processing favors high-throughput spray tools over immersion baths. BOE Technology and TCL CSOT in China operate wet strip lines for Gen 10.5 OLED fabs with chemistry volumes an order of magnitude above semiconductor equivalents.
- Microelectromechanical Systems:Released mechanical structures demand damage-free removal without stiction or corrosion. Bosch Sensortec and STMicroelectronics utilize supercritical CO2 and specialized aqueous chemistries for accelerometer and gyroscope wafer processing.
- Printed Circuit Boards:Lower purity requirements and higher throughput tolerances define this segment, with chemistry costs dominating equipment depreciation in procurement decisions. Unimicron and Zhen Ding Technology in Taiwan operate high-volume wet strip lines for HDI substrate manufacturing.
Semiconductor Manufacturing leads on specification intensity; MEMS gains share fastest.
End User:
Customer type shapes procurement modality, with foundries consolidating volumes and IDMs maintaining captive formulation development.
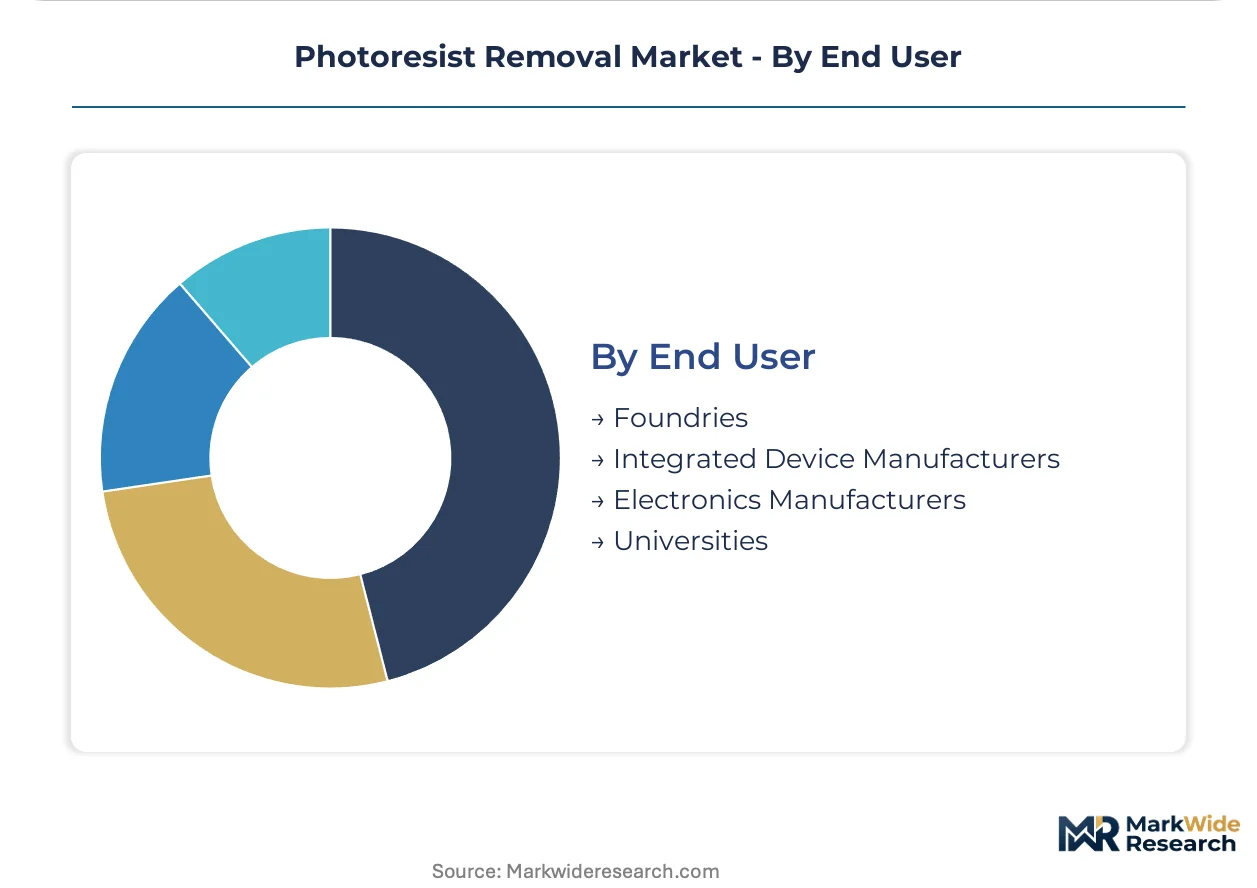
- Foundries:Taiwan Semiconductor Manufacturing, Samsung Foundry, and GlobalFoundries negotiate total-cost-per-wafer contracts that bundle chemistry supply with equipment service agreements. Lam Research and Applied Materials specify qualified suppliers within tool maintenance contracts, locking out standalone chemical vendors.
- Integrated Device Manufacturers:Intel, Texas Instruments, and Analog Devices maintain in-house formulation development for proprietary process flows. Intel's Arizona and Oregon facilities operate dedicated chemical blending operations to protect process intellectual property.
- Electronics Manufacturers:Assembly and test houses purchase removal chemistries for rework and failure analysis applications. Foxconn and Jabil operate distributed chemical inventories across multiple geographies with less stringent purity requirements than front-end fabs.
- Universities:Research institutions procure small-batch formulations for process development and academic fabrication facilities. Stanford Nanofabrication Facility and IMEC in Belgium represent concentrated demand pockets for experimental chemistries.
Foundries lead on procurement scale; IDMs lead on captive technology control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan commands higher stripping step density per wafer than Germany, yet both jurisdictions face tightening discharge constraints that reshape chemistry procurement. The geographic distribution of photoresist removal demand tracks advanced lithography clusters, with regulatory divergence forcing formulation portfolio fragmentation across supply chains.
United States
Intel's Arizona and Oregon fabs drive aqueous chemistry demand for sub-7nm production, while EPA effluent guidelines under the Clean Water Act tighten nitrogen-bearing organic compound discharge limits. CHIPS Act incentives accelerate domestic chemical blending capacity buildout in Phoenix and Hillsboro corridors.
South Korea
Samsung Foundry's Pyeongtaek complex multiplies plasma etcher installations to reduce liquid waste volumes under K-REACH registration requirements. The Seoul Capital Area anchors high-density plasma module adoption for non-critical stack removal at advanced memory fabs.
Japan
Shin-Etsu Chemical and Tokyo Ohka Kogyo supply semiconductor-grade formulations under METI chemical management guidelines that parallel European REACH frameworks. The Kyushu and Tohoku regions concentrate specialty chemical production capacity serving East Asian fabrication demand.
Taiwan
Taiwan Semiconductor Manufacturing consolidates procurement through total-cost-per-wafer contracts bundling chemistry with waste handling services. The Hsinchu Science Park corridor specifies parts-per-trillion contamination thresholds for wet process formulations at leading-edge foundries.
Germany
Merck KGaA operates formulation development for European-bound supply chains under ECHA restrictions on N-Methyl-2-pyrrolidone and glycol ether solvents. The Frankfurt-Rhine-Main region houses aqueous alternative qualification labs serving EU Green Deal carbon border adjustment compliance.
Photoresist Removal Market Competitive Landscape
Japanese producers anchor one tier; American specialists hold equipment-chemistry integration positions. The vendor base separates into consolidated chemical formulators and contamination-controlled fluid handling system suppliers. Three archetypes dominate: integrated resist-removal chemistry providers, standalone high-purity solvent blenders, and equipment-embedded solution bundlers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as fabs consolidate procurement through multi-year service agreements.
Within the integrated chemistry tier, Fujifilm Corporation and DuPont de Nemours, Inc. exemplify backward control across process sequences. Entegris, Inc. occupies a distinct position in contamination-controlled fluid handling systems that pair with removal chemistries in high-volume fabrication environments. These three entities represent the dominant competitive anchors across the formulation-to-delivery value chain.
| Leading Market Players |
|---|
| Fujifilm Corporation |
| Mitsubishi Gas Chemical |
| DuPont de Nemours, Inc. |
| Avantor, Inc. |
| Shin-Etsu Chemical Co., Ltd. |
| Tokyo Ohka Kogyo Co., Ltd. |
| Entegris, Inc. |
| Sumitomo Chemical Co., Ltd. |
| Merck KGaA |
| Others |
Pricing and Supply Chain Analysis
Parts-per-trillion contamination analysts in Japan and South Korea command wage premiums that widen pricing spreads between semiconductor-grade and industrial-grade photoresist removal chemistries. Labor-cost differentials between these specialized fabrication corridors and emerging chemical blending regions in Arizona and Texas directly feed three-tier pricing stratification across premium, standard, and economy formulation levels.
Pricing Analysis
Capacity additions in Arizona and Texas are reshaping price floors for aqueous formulations serving domestic foundry demand. Pricing stratifies across premium, standard, and economy tiers based on metallic ion certification thresholds and bundled waste-handling service inclusion. Cost compression in standard-grade solvent blends is intensifying because South Korean suppliers are qualifying lower-purity alternatives for non-critical layers. Memory foundries exhibit the highest price sensitivity due to wafer-thin margins, while leading-edge logic fabs prioritize contamination control over unit cost.
Supply Chain Analysis
Specialized chemical engineering talent shortages in Japan and South Korea constrain formulation plant expansion timelines. Supply concentrates in Japan, South Korea, and Germany for high-purity N-Methyl-2-pyrrolidone alternatives and aqueous stripping chemistries. Production draws from fluorinated compound feedstocks, electronic-grade solvents, and precision filtration membranes. Single-source vulnerability pervades plasma etcher consumables where perfluorinated compound supply rests on refrigerant market dynamics. Distribution runs through consolidated chemical management contracts that bundle formulation supply with point-of-use fluid handling systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA REACH restrictions on N-Methyl-2-pyrrolidone and glycol ether solvents are accelerating demand for aqueous and plasma-based alternatives across European-bound supply chains.
For Market Incumbents: To counter bundling contracts that lock equipment-chemistry procurement at Taiwan and South Korea foundries, incumbents should deepen backward integration into point-of-use filtration systems and expand captive blending capacity in Phoenix and Hillsboro corridors. Certification investment at parts-per-trillion thresholds remains essential for maintaining premium-tier positioning. For New Entrants and Emerging Players: Begin with supercritical carbon dioxide cleaning modules for MEMS and photonics applications where aqueous chemistries risk stiction failures. The most penetrable segment sits in damage-sensitive device categories previously served by specialized solvent formulations. A go-to-market angle anchored to zero-liquid-discharge compliance offers differentiation against incumbent wet chemistry portfolios. For Investors and Strategic Acquirers: Equipment-integrated solution bundlers are the most active acquirer in this space, seeking contamination-controlled fluid handling capabilities to pair with removal chemistries. Long-term viability hinges on qualification timelines compressing below eighteen months for multi-jurisdiction registration. The signal to watch is EPA effluent guideline enforcement intensity in Arizona and Oregon fabs as a proxy for plasma etcher adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | New blending facilities in Phoenix and Hillsboro corridors address CHIPS Act domestic sourcing mandates for Intel fabs. |
| Backward Integration | Formulation suppliers acquiring point-of-use filtration capabilities capture value previously lost to Entegris fluid handling systems. |
| Green Manufacturing Transition | Closed-loop solvent recovery systems qualify for EU Green Deal carbon border adjustment preferences at Merck KGaA. |
| Long-term Supply Agreement | Total-cost-per-wafer contracts bundling chemistry with waste handling lock out standalone vendors at TSMC. |
| Joint Venture | Equipment-chemistry partnerships between Applied Materials and qualified suppliers consolidate procurement at Samsung Pyeongtaek. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged plant managers at chemical blending facilities, procurement leads at Taiwan and South Korea foundries, distribution channel partners in East Asian fabrication corridors, and technical R&D directors developing aqueous alternatives. Secondary validation drew from EPA effluent filings, ECHA REACH registration databases, METI chemical management guidelines, and SEC 10-K disclosures from listed suppliers. Bottom-up formulation demand estimates and top-down equipment shipment data were cross-referenced for triangulation.
Segment-weighting approaches assigned differential growth coefficients across wet processes, dry processes, hybrid techniques, and laser-based modalities. The analytical framework modeled chemistry grade tier, end-use application, equipment integration depth, and regional regulatory cluster across the projection horizon. CAGRs were derived from stripping step intensity curves at named foundries and plasma etcher installation trajectories. Forecast inputs included node migration timelines and multi-jurisdiction certification lag distributions.
Several conditions sit outside the modeled scope, including unforeseen raw material disruptions, abrupt regulatory harmonization between EPA and ECHA frameworks, and breakthrough dry stripping technologies eliminating wet chemistry at sub-3nm layers. Forecasts reflect documented assumptions about foundry capacity ramp schedules and substitution elasticity for restricted solvents. Practitioners should monitor K-REACH enforcement intensity and Arizona fab construction permits for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Epitaxial Wafer Market
Semiconductor Fabrication
Diamond Semiconductor Substrates Market
Semiconductor Fabrication
Gan Substrate and Gan Wafer Market
Semiconductor Fabrication
Solar Grade Wafer Market
Semiconductor Fabrication
Manual Wafer Aligner Market
Semiconductor Fabrication
Etchant for FPD Market
Semiconductor Fabrication
Additive Manufacturing in Semiconductor Market
Semiconductor Fabrication
North America Atomic Layer Deposition Market
Semiconductor Fabrication
Thin Layer Deposition Market
Semiconductor Fabrication
Etching Machine Market
Semiconductor Fabrication
Semiconductor Logistics Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
Solar Ingot Wafer Market
Semiconductor Fabrication
Ion Implantation Machine Market
Semiconductor Fabrication
Semiconductor Foundry Market