
 Solar Glass Market | 2026-2036
Solar Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Glass Market Intelligence
China's massive expansion of solar glass production capacity is narrowing the cost gap between standard and high-transparency anti-reflective glass. Leading Chinese producers like Xinyi Solar Holdings Ltd. and Flat Glass Group Co., Ltd. leverage immense manufacturing scale to control global supply chains. In contrast, European manufacturer Saint-Gobain specializes in high-performance glass for specialized architectural and BIPV applications. AGC Inc. competes through technological innovation in coatings and material science.
Solar glass is an iron-oxide-reduced silicate glass engineered for maximum light transmittance, typically exceeding 91%. Its primary function is to protect photovoltaic cells from environmental factors while ensuring optimal solar energy absorption for electricity generation. Anti-Reflective Glass represents the dominant product type, essential for efficiency gains in standard photovoltaic panels. The emergence of Bifacial technology is creating new demand for highly durable, transparent backsheets and front glass combinations.
Regulatory frameworks like the EU Green Deal and the US Inflation Reduction Act (IRA) directly stimulate demand through subsidies and local content requirements. In China, national GB standards dictate the quality and performance benchmarks for glass used in domestic and export-oriented solar modules. Stakeholders must now decide how to balance the benefits of concentrated, low-cost Chinese supply against the policy-driven incentives for regionalized manufacturing in North America and Europe.
Market Dynamics
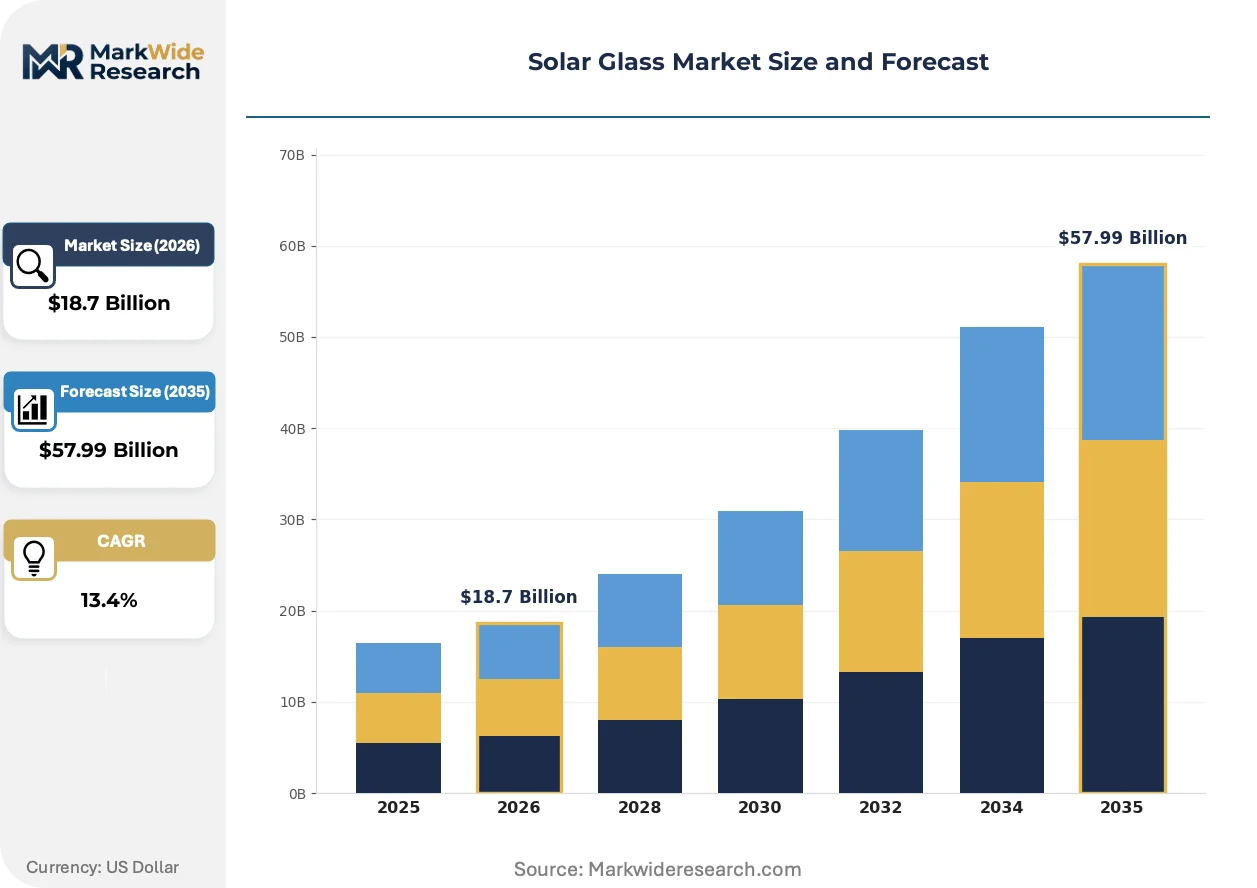
The solar glass market is defined by a central tension: immense, low-cost production capacity in China versus policy-driven efforts in the US and Europe to re-shore manufacturing and secure regional supply chains.
Growth Catalysts
- Government Incentives:The US IRA and EU Green Deal use subsidies to accelerate solar project deployment, increasing demand for solar glass.
- Bifacial Technology:Growing adoption of bifacial modules requires glass for both front and back surfaces, increasing material volume per panel.
- Architectural Integration:The expansion of Building Integrated Photovoltaics (BIPV) into building facades creates a new, high-value market for specialized glass.
Market Restraints
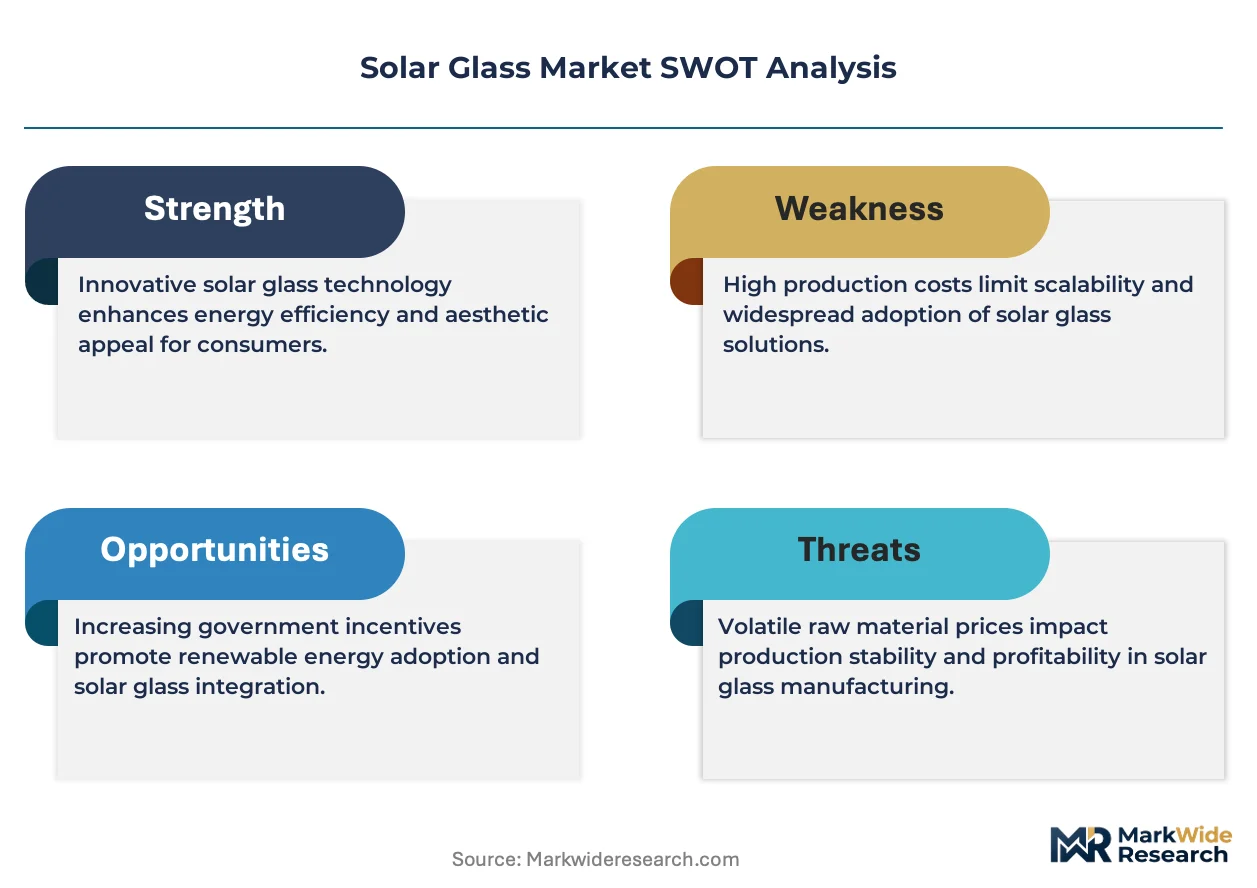
- Raw Material Costs:Volatile pricing for inputs like low-iron silica sand and soda ash creates instability in manufacturing cost structures.
- Geographic Concentration:Heavy dependence on production hubs in China exposes the global supply chain to geopolitical and trade-related disruption risks.
- Logistical Complexity:The fragility and weight of large glass sheets result in high transport costs and breakage risks, complicating global distribution.
Strategic Opportunities
- New Regional Manufacturing:India's PLI scheme and the US IRA incentivize new solar glass plants to serve domestic module assembly operations.
- Advanced Coatings Development:Innovations in self-cleaning or anti-soiling coatings offer a path to product differentiation and improved energy yield.
- Vehicle Integration:The emerging Vehicle Integrated Photovoltaics (VIPV) market presents an opportunity for lightweight, durable, custom-shaped solar glass in automotive applications.
Industry Challenges
- Capital Intensity:Building new float glass production lines requires immense upfront capital and long construction timelines, creating high barriers to entry.
- Regulatory Compliance:Navigating disparate benchmarks like China's GB standards and EU CE marking adds complexity and cost for global exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Glass Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $57.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Anti-Reflective Glass, Tinted Glass, Heat-Strengthened Glass Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial, Building-Integrated Photovoltaics Application: Photovoltaic Panels, Building Integrated Systems, Solar Thermal Systems, Concentrated Solar Power, Solar Greenhouses End User: Energy Producers, Construction Companies, Utility Providers, Agricultural Installers, Commercial Developers |
| Companies Covered | Xinyi Solar Holdings Ltd., Flat Glass Group Co., Ltd., IRICO Group New Energy Co., Ltd., AGC Inc., Saint-Gobain, CSG Holding Co. Ltd., Jin Jing Group, Guangdong Golden Glass Technologies, Nippon Sheet Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Glass Market Strategic Shifts & Innovations
Efficiency imperatives and supply chain diversification are shaping product development. Technology is focused on maximizing light transmission, while policy frameworks are encouraging manufacturing regionalization to mitigate geopolitical risks.
Product design for solar glass now centers on advanced anti-reflective (AR) coatings to boost output. PV module manufacturers universally adopt these coatings to gain crucial efficiency points. The industry is migrating from standard single-sided coatings toward double-sided applications for bifacial panels and complex multi-layer coatings for premium products.
Legislation like the US Inflation Reduction Act (IRA) is altering supply chain strategies. The act's production tax credits for domestic components stimulate onshoring of the value chain. Consequently, North America is seeing new investment in solar glass facilities to serve local module assemblers.
Buyer criteria are expanding beyond cost-per-watt to include supply chain resilience and embodied carbon. Procurement for large projects now weighs the risks of concentrated sourcing and the carbon footprint of logistics. This shift is most visible in Europe, where frameworks like the CSRD influence purchasing.
Solar Glass Market Segmentation
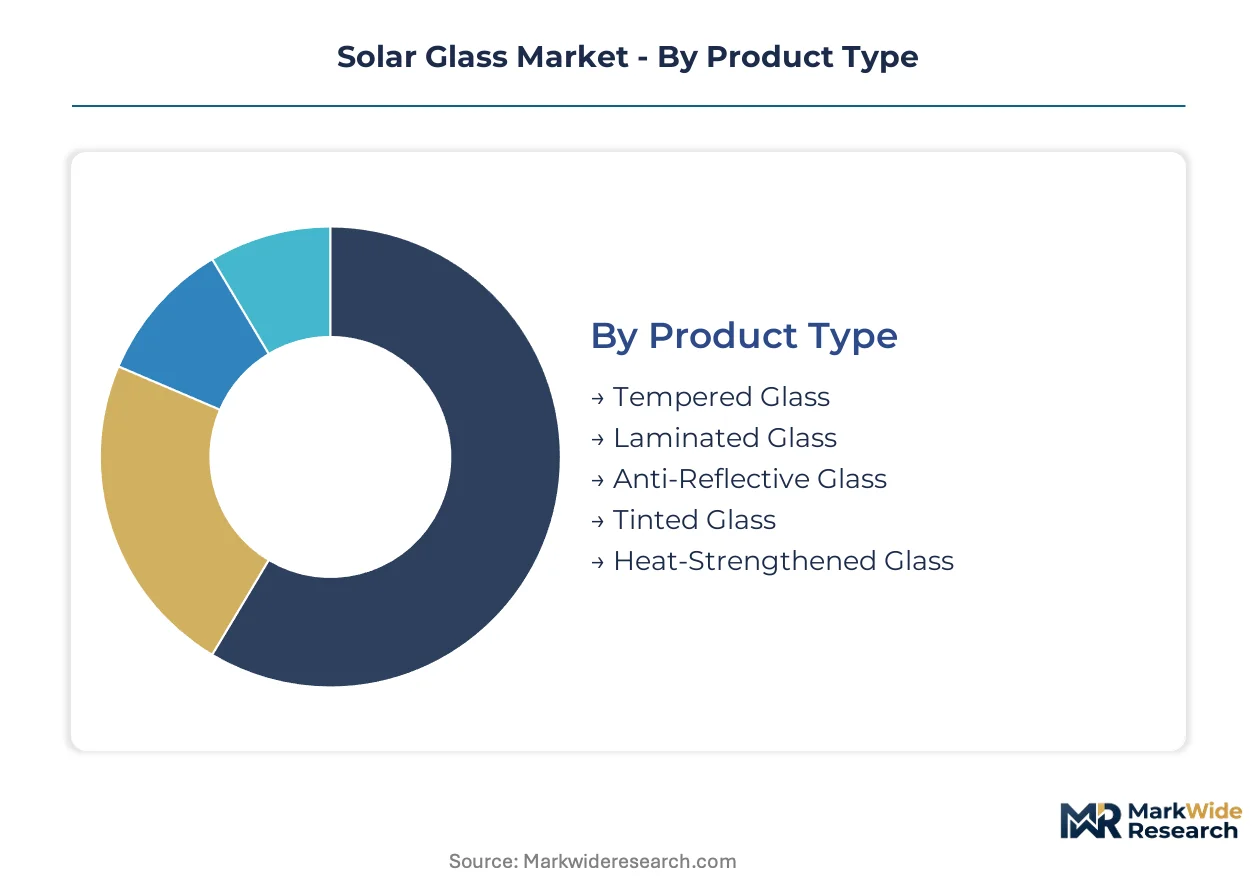
The solar glass market segments reflect distinct material properties and diverse end-use requirements. Understanding these categories is critical for manufacturers to align product development with evolving market demands. Each segment addresses specific performance criteria, influencing overall system efficiency and durability in various solar applications.
Product Type:
The after-sales-service intensity for solar glass varies significantly across product types, driven by performance requirements and installation complexity.
- Anti-Reflective Glass:This glass features specialized coatings that minimize light reflection, maximizing solar transmittance to the PV cells. Demand concentrates in standard photovoltaic panels across China and Europe, driven by efficiency imperatives and competitive module pricing.
- Laminated Glass:Comprising multiple glass layers bonded with an interlayer, laminated glass offers enhanced durability and safety against impact and environmental stresses. Its adoption is accelerating in Building Integrated Photovoltaics (BIPV) applications in Germany, requiring robust architectural integration.
- Tempered Glass:This thermally treated glass provides increased strength and resistance to breakage, commonly used as a protective front sheet for solar modules.
- Tinted Glass:Tinted solar glass reduces glare and provides aesthetic benefits, finding niche applications in architectural solar installations.
- Heat-Strengthened Glass:Offering intermediate strength between annealed and tempered glass, it provides improved thermal shock resistance for specific solar thermal systems.
Anti-Reflective Glass holds the largest share; momentum sits with Laminated Glass.
Technology:
Technology segmentation highlights how glass properties are tailored to specific solar energy conversion methods and their application environments.
- Bifacial:Bifacial technology utilizes glass on both the front and back of the module, capturing sunlight from both sides to increase energy yield. This technology sees strong demand in utility-scale solar farms in the US, driven by land-use efficiency and IRA incentives.
- Building-Integrated Photovoltaics:BIPV integrates solar glass directly into building envelopes, serving as both a structural and energy-generating component. European construction projects, particularly in France and the Netherlands, are driving demand for aesthetic and functional BIPV glass.
- Monocrystalline:This technology uses high-purity silicon cells, requiring high-transparency glass to maximize the efficiency of individual cells.
- Polycrystalline:Polycrystalline cells are cost-effective, and the glass for these modules balances performance with manufacturing economics.
- Thin-Film:Thin-film modules are flexible and lightweight, necessitating specialized glass that accommodates their unique material properties and installation methods.
Thin-Film technology shows consistent adoption, while Bifacial technology is expanding most quickly.
Application:
The application segments delineate where solar glass is deployed, reflecting diverse customer types and market needs.
- Photovoltaic Panels:This segment encompasses glass used in conventional solar panels for electricity generation in residential, commercial, and utility-scale installations. Demand is globally widespread, with China dominating production volume for standard modules.
- Building Integrated Systems:BIPV applications integrate solar glass directly into building materials like facades, roofs, and windows. European architectural firms and developers are key customers, prioritizing aesthetics and energy efficiency.
- Solar Thermal Systems:Solar thermal systems use glass to capture solar energy for heating water or air, primarily in residential and commercial buildings.
- Concentrated Solar Power:CSP plants employ specialized glass mirrors to focus sunlight onto a receiver, generating high temperatures for electricity production.
- Solar Greenhouses:Greenhouses utilize solar glass optimized for light transmission and thermal regulation, enabling crop cultivation with integrated energy generation.
Photovoltaic Panels applications command the largest market volume; Building Integrated Systems are demonstrating significant growth.
End User:
End user segmentation reveals the primary purchasers and beneficiaries of solar glass products, influencing procurement strategies and product specifications.
- Energy Producers:These entities, including independent power producers and utility companies, procure solar glass for large-scale solar farms. Their procurement decisions heavily prioritize cost-per-watt and long-term durability for projects in the US and India.
- Construction Companies:Construction firms integrate solar glass into new building projects and renovations, particularly for BIPV installations. European construction regulations and green building standards drive their demand for specialized glass.
- Utility Providers:Utility companies invest in solar glass for grid-scale solar power generation, often through direct ownership or power purchase agreements.
- Agricultural Installers:These installers deploy solar glass in agricultural settings for applications like solar greenhouses and irrigation systems.
- Commercial Developers:Commercial developers incorporate solar glass into office buildings, retail centers, and industrial facilities, balancing energy generation with architectural design.
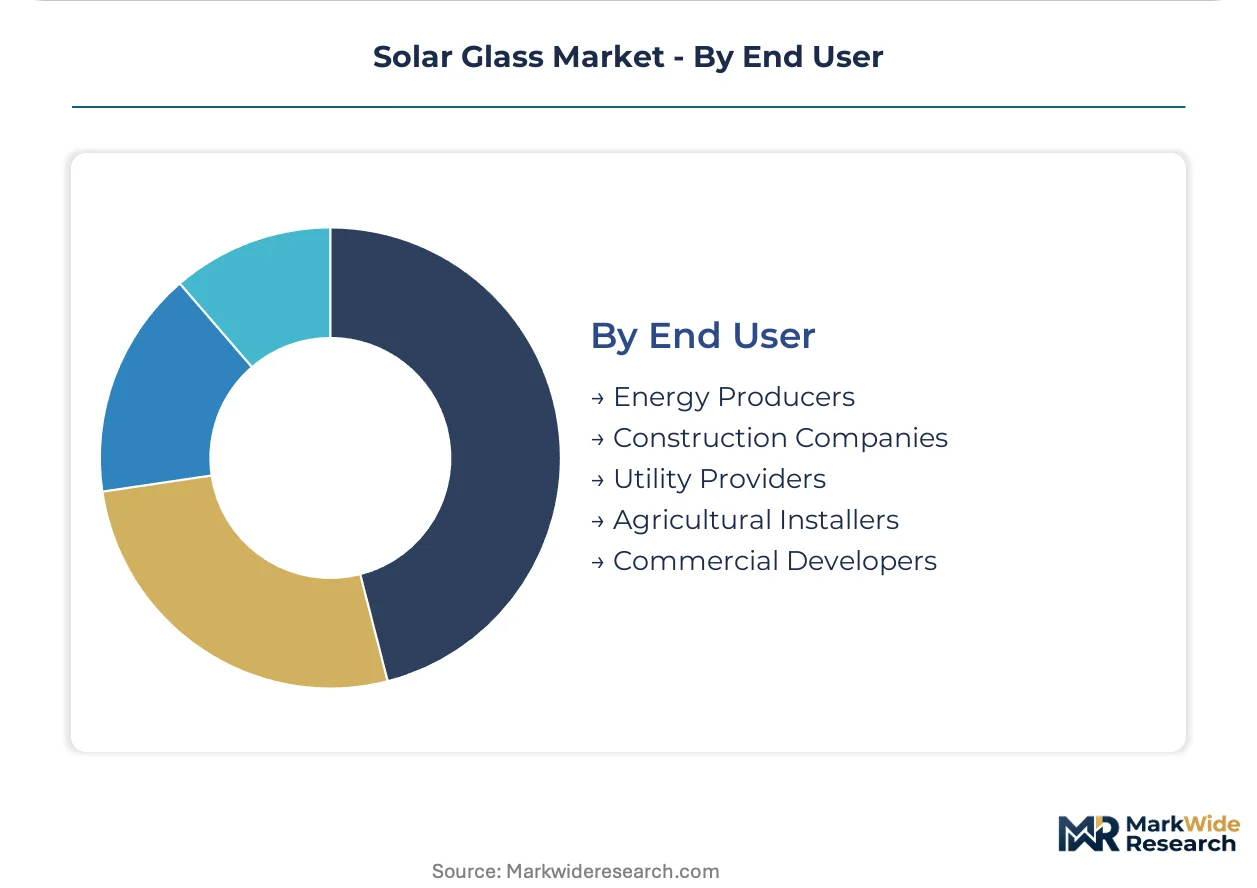
Energy Producers represent the foundational demand base, with Commercial Developers exhibiting increasing procurement activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration in China defines the global solar glass landscape, driving down costs and influencing market dynamics. However, policy incentives in other regions are fostering localized production and diversifying supply chains. This creates regional centers for both manufacturing and specialized application demand.
China
Domestic demand for photovoltaic panels drives immense solar glass production capacity in China. The national dual carbon goals provide significant policy support for solar component manufacturing. Production capacity for specialized solar glass concentrates within key industrial provinces like Jiangsu and Anhui, serving both domestic and export markets.
United States
Demand for utility-scale solar farms and residential installations is accelerating in the United States. The US Inflation Reduction Act (IRA) directly stimulates demand through production tax credits and local content requirements. New solar glass facilities are emerging in states like Georgia and Ohio to serve domestic module assembly operations.
Germany
Building Integrated Photovoltaics (BIPV) applications show strong growth in Germany, driven by green building standards. The EU Green Deal and CE marking regulations influence product specifications and demand. Architectural firms in urban centers like Berlin and Munich prioritize aesthetic and functional BIPV glass solutions.
India
India's solar energy targets are increasing demand for photovoltaic panels and associated glass components. The PLI scheme incentivizes new solar glass plants to serve domestic module assembly operations. Manufacturing hubs are developing in states like Gujarat and Rajasthan, supported by government initiatives.
Japan
Technological innovation in coatings and material science characterizes the Japanese solar glass market. Demand for monocrystalline modules requires high-transparency glass to maximize efficiency. Companies in regions like Kanto are focused on advanced anti-reflective coatings and specialized glass for high-performance applications.
Solar Glass Market Key Industry Players
Scale producers and specialized innovators split the solar glass market, creating a dynamic competitive environment. Large Chinese manufacturers leverage immense scale for cost leadership, while European and Japanese firms focus on high-performance niches. Dominant competitive moves include capacity expansion and advanced coatings development.
Within the scale-driven manufacturing tier, China-based Xinyi Solar Holdings Ltd. and Flat Glass Group Co., Ltd. exemplify the immense production capabilities. These companies anchor global supply chains through their vast operational footprint. European manufacturer Saint-Gobain occupies a position within specialized architectural and BIPV applications, representing a focus on high-performance glass solutions.
| Leading Market Players |
|---|
| Xinyi Solar Holdings Ltd. |
| Flat Glass Group Co., Ltd. |
| IRICO Group New Energy Co., Ltd. |
| AGC Inc. |
| Saint-Gobain |
| CSG Holding Co. Ltd. |
| Jin Jing Group |
| Guangdong Golden Glass Technologies |
| Nippon Sheet Glass |
| Others |
Cost & Logistics Intelligence
Chinese overcapacity in solar glass production exerts significant downward pressure on global pricing. This high utilization rate influences both supplier behavior and the overall pricing posture across the industry.
Pricing Analysis
GB standards dictate the pricing tier structure for solar glass, especially for export products from China, where the dominant pricing model involves per-unit transactional contracts influenced by long-term offtake agreements. Price differentiation stems from quality grade, specifically high-transparency anti-reflective coatings versus standard glass, and significant geographic delivery costs. Downward pricing pressure primarily originates from immense Chinese manufacturing scale and intense competition. Energy Producers exhibit the highest price sensitivity, prioritizing cost-per-watt, while BIPV application developers prioritize specialized performance.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common, particularly with large-scale Chinese producers. Geographic supply concentration centers heavily on China, with emerging regional hubs in India and the United States. The industry draws from key raw materials like low-iron silica sand and soda ash; geopolitical and trade-related disruption risks represent a structural vulnerability. Distribution runs through direct sales channels to PV module manufacturers and specialized distributors for BIPV applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar glass market represents a high-growth disruption, driven by the rapid expansion of Bifacial technology across utility-scale installations. This technological inflection point is reshaping demand for specialized glass products.
For Market Incumbents: Build regional manufacturing moats in North America and India to mitigate geopolitical risks and leverage IRA and PLI incentives. Invest heavily in advanced coatings R&D, focusing on multi-layer anti-reflective and self-cleaning technologies to differentiate against commodity glass. This strategy counters the threat of concentrated, low-cost Chinese supply and strengthens supply chain resilience. Pursue strategic partnerships with local module assemblers, integrating into their value chains.
For New Entrants and Emerging Players: Build out niche capabilities in specialized glass, targeting high-value applications like Building Integrated Photovoltaics (BIPV) in Europe and Vehicle Integrated Photovoltaics (VIPV). The BIPV segment, particularly in Germany and France, offers penetrable market entry due to its emphasis on aesthetics and customized solutions. Focus on a performance-based value proposition, emphasizing unique material properties and advanced functionalities like anti-soiling coatings.
For Investors and Strategic Acquirers: Long-term, this sits as an essential component play because solar glass underpins the global energy transition, with demand tied directly to renewable energy buildout. Target specialized technology providers with strong IP in advanced coatings or unique BIPV integration solutions. Also consider regional manufacturing assets in incentivized geographies like the US or India. A key signal to watch is the sustained ramp-up and cost-competitiveness of non-Chinese solar glass production.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Capacity Expansion | New facilities in the US and India diversify supply chains and leverage local content requirements. |
| Advanced Coatings R&D | Developing multi-layer anti-reflective coatings boosts module efficiency for PV manufacturers. |
| BIPV Product Development | Tailored aesthetic and functional glass solutions capture high-value architectural project demand. |
| Supply Chain Digitization | Implementing IoT and AI improves logistics efficiency and reduces breakage risks for fragile glass. |
| Sustainable Manufacturing Processes | Reducing embodied carbon in production aligns with EU Green Deal and CSRD procurement criteria. |
Research Approach
Operator-level perspectives from R&D directors, procurement leads, BIPV architects, and utility project managers anchored the qualitative base. This primary research, conducted through targeted interviews, was rigorously validated against secondary data sources. Secondary sources included company SEC filings, trade association reports, and government energy agency publications. Bottom-up and top-down triangulation ensured data consistency across all market segments.
Scenario-bracketing established market projection boundaries, accounting for policy and technology adoption rates. The analytical framework modeled product type, technology, application, end user, and regional policy frameworks. Compound Annual Growth Rates derived from historical data, expert consensus, and projected market shifts. Solar panel deployment targets and BIPV project pipelines served as critical forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese scale producers or new regional entrants would shift outcomes. Forecasts reflect assumptions of geopolitical stability and raw material supply. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
China Green Building Materials Market
Green Building Materials
Non-Residential Green Building Market
Green Building Materials
Eco-Friendly Bitumen Market
Green Building Materials
Global Green Walls Market
Green Building Materials
Asia Pacific Green Cement Market
Green Building Materials
APAC Green Buildings Market
Green Building Materials
Green Building Materials Market
Green Building Materials
GCC Green Cement Market
Green Building Materials
Energy Efficient Window and Door Market
Green Building Materials
Solar Windows Market
Green Building Materials
Solar Frames Market
Green Building Materials
Green Concrete Market
Green Building Materials
Sustainable and Green Building Materials Market
Green Building Materials
Green Roof Market
Green Building Materials
Green Silica Market
Green Building Materials
Green Cement Market