
 Green Coatings Market | 2026-2036
Green Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Green Coatings Market Intelligence
Direct-to-contractor sales channels for architectural applications are fragmenting as digital platforms and specialized distributors gain share from traditional retail. This shift challenges established players like The Sherwin-Williams Company, which leverages its extensive network of company-operated stores. In contrast, BASF SE competes on material science innovation, supplying advanced biobased raw materials to other formulators. PPG Industries Inc. differentiates through its strong position in high-performance coatings for the aerospace and marine sectors.
Green coatings are surface treatments formulated to minimize environmental and health impacts, often characterized by low-to-zero volatile organic compound (VOC) content or the use of renewable, biobased materials. Their primary purpose is to provide protective and decorative finishes while complying with stringent environmental standards. Waterborne formulations dominate the market due to their performance and regulatory compliance, while powder coatings represent a high-growth category in industrial applications. Within technology segments, the development of advanced biobased resins and low-VOC systems is attracting significant R&D investment.
Regulatory frameworks are a primary market catalyst, with the European Union's REACH directive and US EPA regulations setting strict limits on VOCs in paints and coatings. In China, the Ministry of Ecology and Environment (MEE) enforces similar standards as part of its dual carbon goals, mandating the use of environmentally friendly products. Stakeholders must now decide whether to invest in captive production of biobased resins or secure long-term supply agreements to ensure formulation consistency and cost control.
Market Dynamics
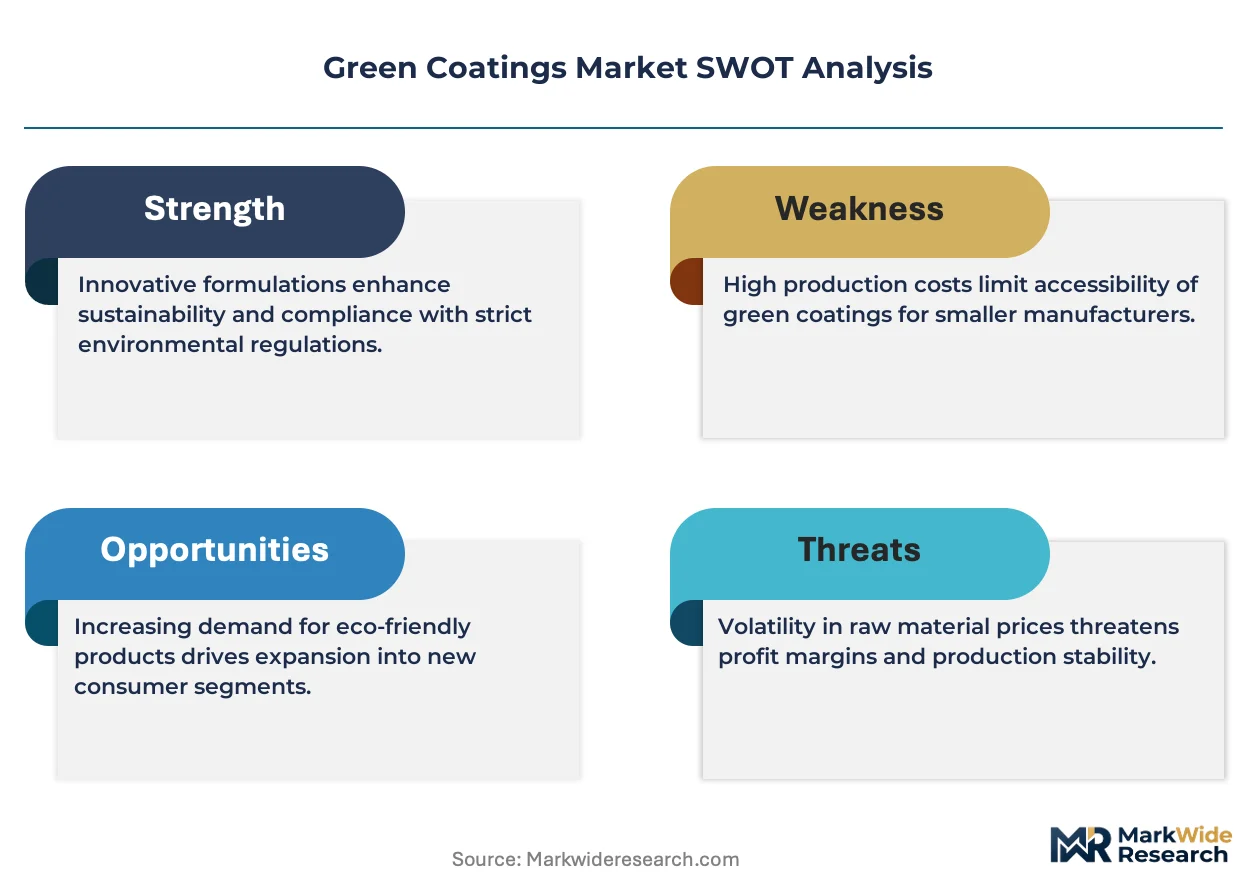
The central tension shaping the green coatings market is the conflict between stringent, globally fragmented VOC regulations and the technical challenge of achieving performance parity. This dynamic forces formulators to balance compliance-driven material substitution with end-user demands for durability and application efficiency.
Growth Catalysts
- Regulatory Mandates:The EU's REACH directive and similar rules from the US EPA and China's MEE create non-negotiable demand for low-VOC architectural and industrial coatings, acting as a primary market driver.
- Green Building Standards:The proliferation of certifications like LEED and BREEAM compels architects and builders to specify products with low-to-zero VOC content, directly stimulating demand in new construction and renovation projects.
- Biobased Material Innovation:Advances in converting renewable feedstocks like corn, soy, and plant oils into viable biobased resins and solvents expand the formulation toolkit, enabling higher performance in green coatings.
Market Restraints
- Cost Disparity:Key biobased raw materials, such as epoxies and polyols derived from plant sources, often carry a significant price premium over their petrochemical equivalents, hindering adoption in cost-sensitive applications.
- Performance Gaps:Certain waterborne and powder coatings still exhibit limitations in adhesion, cure time, and corrosion resistance compared to traditional solvent-borne systems, restricting their use in demanding industrial environments.
- Supply Chain Volatility:The supply of agricultural feedstocks for biobased resins is subject to crop cycles, weather events, and competition from the food industry, introducing price and availability risks for formulators.
Strategic Opportunities
- Emerging Market Penetration:Rapid urbanization and nascent environmental regulations in Southeast Asia and Latin America present significant expansion opportunities for formulators of cost-effective, compliant waterborne architectural paints.
- High-Performance Niches:Developing biobased or zero-VOC coatings for specialized sectors like aerospace interiors, marine applications, and electric vehicle components opens new, high-margin revenue streams.
- Functional Additives Integration:Incorporating functionalities such as self-cleaning, anti-microbial, or thermal insulation properties into green coating formulations creates strong product differentiation and value-added potential.
Industry Challenges
- Formulation Expertise Scarcity:A persistent shortage of chemists and material scientists skilled in reformulating coatings to meet lower VOC targets while maintaining performance attributes creates a significant operational bottleneck.
- Regulatory Fragmentation:Navigating the complex and often diverging environmental and chemical safety standards across the US, EU, and China increases the cost and timeline for product development and certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Coatings Market |
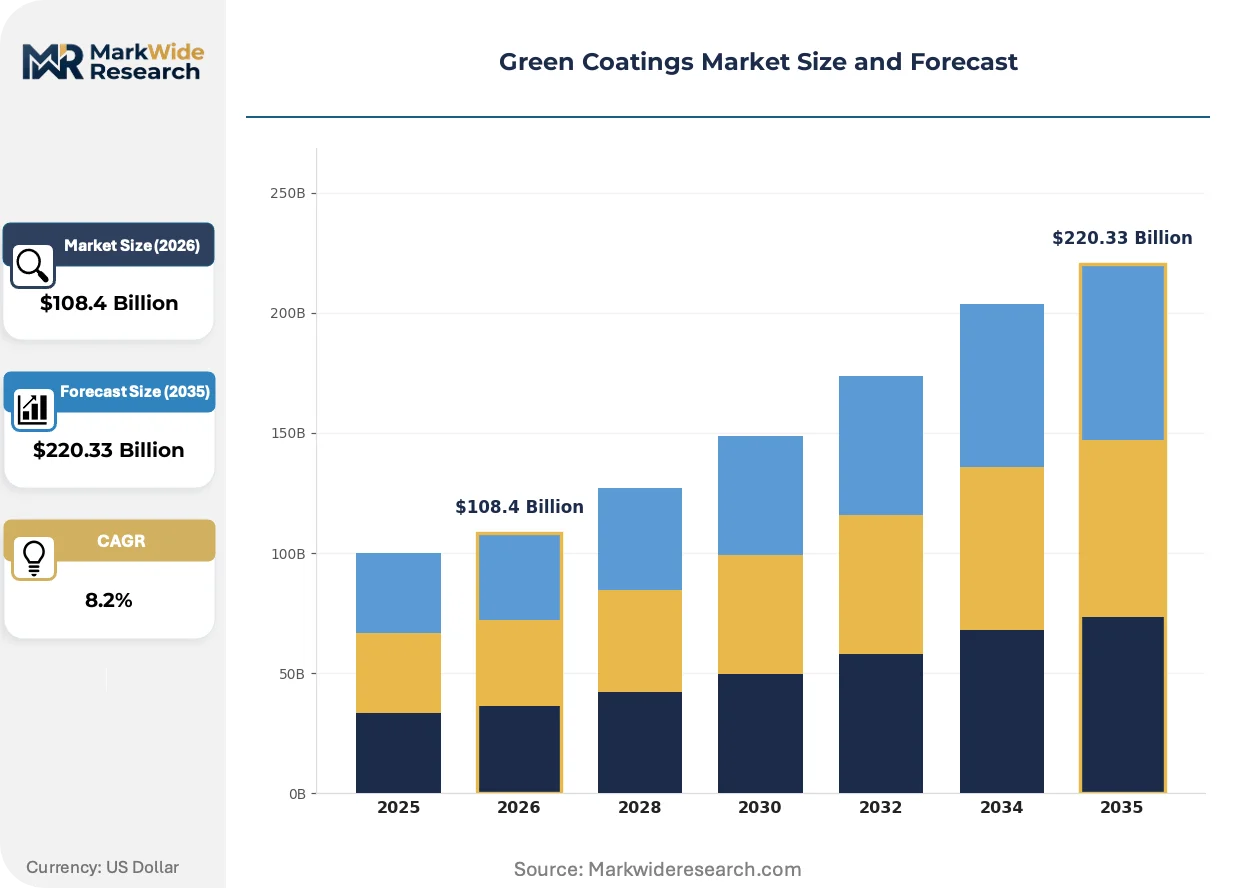
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $220.33 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterborne, Powder, UV Curable, Silicone, Solvent-Free Technology: Biobased, Nanotechnology, Low-VOC, Infrared, Photocatalytic Application: Architectural, Marine, Aerospace, Electronics, Packaging End User: Construction Contractors, OEM Manufacturers, Electronic Assemblers, Packaging Producers |
| Companies Covered | Axalta Coating Systems, LLC, Nippon Paint Holdings Co., Ltd., AkzoNobel N.V., Asian Paints Limited, Jotun A/S, The Sherwin-Williams Company, BASF SE, Kansai Paint Co., Ltd., PPG Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Coatings Market Strategic Shifts & Innovations
The competitive landscape is being reshaped by the dual forces of material circularity and the digitalization of formulation science. These trends are moving the industry beyond simple VOC reduction toward a more holistic lifecycle approach to environmental impact, favoring innovation in both chemistry and process technology.
Formulation simulation software represents a pivotal technological shift. These AI-driven platforms allow researchers to model the properties of new biobased resins and predict their performance characteristics without physical prototyping. Chemical and coatings formulators are increasingly adopting these tools to shorten development timelines for new products. This technology is virtualizing key aspects of the traditional R&D process, reducing material waste and accelerating the market entry of next-generation green coatings.
Product stewardship regulations are expanding beyond manufacturing to encompass the entire product lifecycle. The EU's Corporate Sustainability Reporting Directive (CSRD), for example, requires companies to disclose comprehensive data on their products' environmental footprint, including raw material sourcing and end-of-life impact. The industrial coatings segment is most affected, as it must now provide extensive documentation to customers in sectors like automotive and machinery who are subject to these reporting rules.
A notable behavioral shift is occurring as large-scale architectural and construction firms move toward specifying integrated coating systems over individual products. This disrupts the traditional channel of selling paints, primers, and sealers separately. Buyers now favor single-source suppliers that can guarantee compatibility and performance across all layers, a trend most visible in major commercial construction projects in North America and Europe.
Green Coatings Market Segmentation
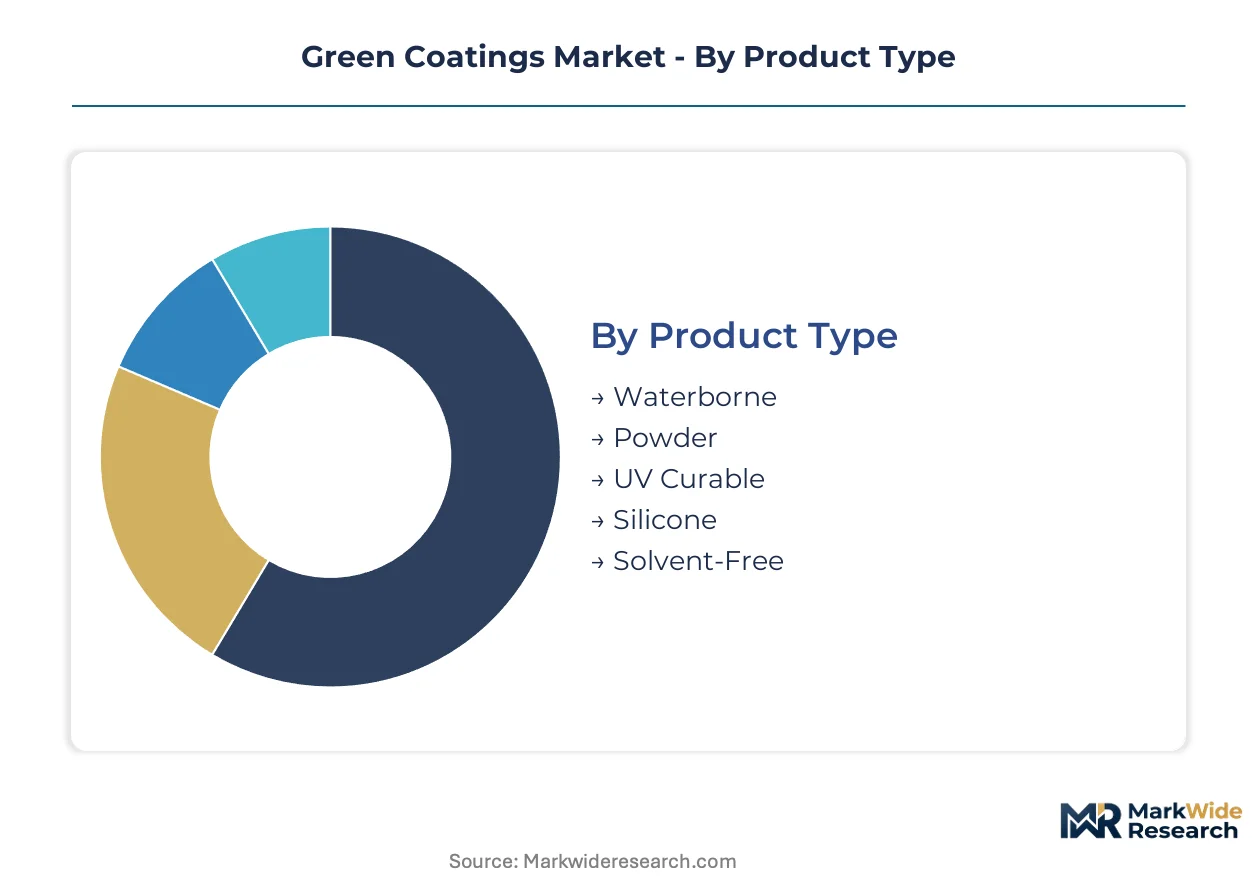
Segmentation within the green coatings market reveals critical distinctions in formulation, performance, and regulatory compliance. Analyzing these segments helps stakeholders understand where innovation is concentrating and where demand drivers are strongest. This granular view informs strategic investment and product development decisions.
Product Type:
The chemical composition of green coatings defines their performance characteristics and environmental footprint.
- Waterborne:Waterborne formulations utilize water as the primary solvent, significantly reducing volatile organic compound (VOC) emissions. Regulatory mandates from the US EPA and the EU's REACH directive drive demand for these coatings in architectural applications.
- Powder:Powder coatings consist of finely ground polymer resins and pigments applied electrostatically, offering zero VOC content and high durability. Industrial sectors like automotive and appliance manufacturing increasingly adopt powder systems for their efficiency and environmental benefits.
- UV Curable:UV curable coatings harden rapidly under ultraviolet light, offering high-performance finishes for electronics and packaging.
- Silicone:Silicone-based coatings provide excellent weather resistance and flexibility, finding use in demanding exterior applications.
- Solvent-Free:Solvent-free formulations eliminate traditional organic solvents, improving worker safety and environmental profiles across various industrial uses.
Waterborne coatings hold significant installed capacity. Powder coatings are rotating up the share rankings.
Technology:
The underlying scientific principles differentiate how green coating technologies deliver environmental benefits and enhanced functionality.
- Biobased:Biobased technologies integrate renewable feedstocks like plant oils and agricultural waste into resin and solvent production. Significant R&D investment focuses on developing these materials to reduce reliance on petrochemicals and enhance circularity.
- Low-VOC:Low-VOC technologies formulate coatings with minimal volatile organic compound content, directly addressing air quality regulations. Architectural and construction firms prioritize these systems to meet green building standards like LEED in North America.
- Nanotechnology:Nanotechnology incorporates nanoscale particles to enhance properties like scratch resistance and self-cleaning in green coatings.
- Infrared:Infrared curing technologies accelerate the drying process for industrial coatings, improving energy efficiency and throughput.
- Photocatalytic:Photocatalytic coatings use light to break down pollutants, offering air purification and self-cleaning capabilities for exterior surfaces.
Biobased innovations are expanding most quickly. Low-VOC formulations underpin the majority of current green coating sales.
Application:
End-use sectors dictate specific performance requirements and regulatory compliance needs for green coatings.
- Architectural:Architectural applications encompass paints and coatings for residential, commercial, and institutional buildings, forming the largest market segment. Stringent VOC limits from the US EPA and EU's REACH directive significantly influence product development for these uses.
- Aerospace:Aerospace coatings demand extreme durability, corrosion resistance, and lightweight properties for aircraft exteriors and interiors. Formulators develop high-performance, low-VOC systems to meet strict safety and environmental standards from regulators like the FAA.
- Marine:Marine coatings protect ships and offshore structures from corrosion and fouling, with growing demand for environmentally friendly antifouling solutions.
- Electronics:Electronics coatings provide insulation and protection for circuit boards and components, requiring specialized low-VOC and UV-curable formulations.
- Packaging:Packaging coatings enhance barrier properties and aesthetics for food and consumer goods, with a focus on biobased and recyclable options.
Architectural uses dominate overall green coatings sales. Aerospace and marine applications present emerging high-margin opportunities.
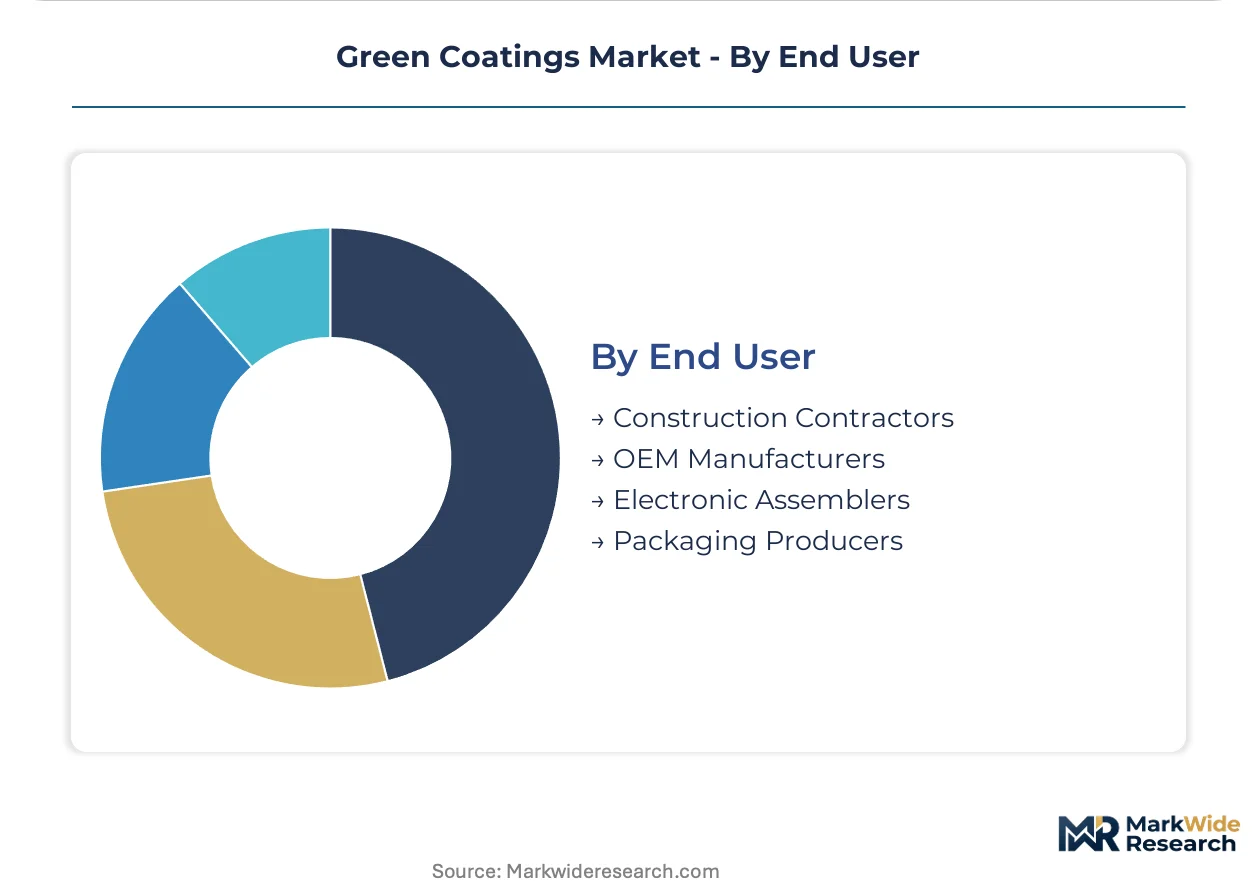
End User:
The procurement patterns and specific needs of end-user groups shape the distribution channels and product specifications for green coatings.
- Construction Contractors:Construction contractors purchase green coatings for new builds and renovation projects, driven by green building certifications and local regulations. Their procurement often involves direct-to-contractor sales channels and bulk volumes for large-scale commercial sites.
- OEM Manufacturers:OEM manufacturers integrate green coatings into their production lines for products like appliances, automotive parts, and industrial machinery. They require consistent performance, supply chain reliability, and specific application properties for high-volume manufacturing processes.
- Electronic Assemblers:Electronic assemblers utilize specialized green coatings for circuit board protection and component encapsulation, prioritizing low-VOC and fast-curing properties.
- Packaging Producers:Packaging producers apply green coatings to enhance product shelf life and appeal, increasingly seeking biobased and sustainable options for consumer goods.
Construction contractors represent the largest volume purchasers. OEM manufacturers demand the strictest product specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Major shipping lanes and industrial corridors facilitate the distribution of raw materials and finished products for green coatings. These critical infrastructure networks underpin regional market dynamics across various applications. Regulatory frameworks and local demand patterns shape specific country-level growth trajectories.
China
China's extensive high-speed rail network supports the distribution of green coatings for vast green building projects. The Ministry of Ecology and Environment (MEE) enforces strict standards, including dual carbon goals, driving demand for compliant products. The Yangtze River Delta region, a major manufacturing hub, adopts industrial powder coatings.
United States
The United States' interstate highway system connects major construction markets, facilitating architectural green coatings supply. US EPA regulations and LEED standards mandate low-VOC products across commercial and residential sectors. California's stringent environmental policies accelerate the adoption of advanced waterborne formulations.
Germany
Germany's highly developed port infrastructure enables efficient import and export of specialized green coating raw materials. The European Union's REACH directive significantly influences formulation choices for industrial and automotive coatings. The Rhine-Ruhr industrial region leads in developing and applying high-performance solvent-free systems.
India
India's growing network of national highways supports green coatings delivery to rapidly expanding urban centers. The Bureau of Indian Standards (BIS) promotes eco-friendly product certifications, encouraging sustainable construction practices. The Mumbai-Pune industrial belt is a focal point for new manufacturing facilities adopting compliant finishes.
Brazil
Brazil's extensive road network connects major agricultural regions with burgeoning industrial and construction sites. Local environmental agencies increasingly enforce regulations reducing VOC emissions from paints and coatings. São Paulo state, an economic powerhouse, exhibits strong demand for waterborne architectural solutions in new developments.
Green Coatings Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with established global players and specialized innovators coexisting. The market shows a blend of consolidation at the top and fragmentation within niche segments, particularly for specialized green formulations. Strategic archetypes include large-scale integrators, material science innovators, and high-performance specialists. Companies are pursuing strategic partnerships, focused R&D investments, and portfolio diversification to navigate regulatory complexities and meet evolving demand.
On the premium-tier vector, The Sherwin-Williams Company exemplifies a market leader leveraging an extensive direct-to-contractor network for architectural applications across North America. BASF SE, a German chemical giant, anchors the material science innovation segment, supplying advanced biobased raw materials to other formulators globally. PPG Industries Inc. occupies a position as a high-performance specialist, differentiating through its strong presence in demanding aerospace and marine sectors. These companies represent distinct strategic approaches and play pivotal roles in shaping the future of green coatings.
| Leading Market Players |
|---|
| Axalta Coating Systems, LLC |
| Nippon Paint Holdings Co., Ltd. |
| AkzoNobel N.V. |
| Asian Paints Limited |
| Jotun A/S |
| The Sherwin-Williams Company |
| BASF SE |
| Kansai Paint Co., Ltd. |
| PPG Industries Inc. |
| Others |
Cost & Logistics Intelligence
Commodity volatility, particularly for biobased raw materials, determines both pricing tier spreads and the overall green coatings supply chain shape. This volatility influences formulators' investment decisions in captive production versus long-term supply agreements. It also impacts the cost competitiveness of green formulations against traditional petrochemical-based options.
Pricing Analysis
Contract-based long-term offtake agreements, often with volume discounts, characterize the green coatings market. Price differentiation stems from biobased content certifications and guaranteed performance attributes for specialized applications. Pricing pressure stems from the rising cost of petrochemical feedstocks, which impacts solvent-borne alternatives. Construction contractors represent the most price-sensitive buyer segment, while aerospace and marine OEMs prioritize performance over cost.
Supply Chain Analysis
Large chemical companies like BASF SE hold significant contract manufacturing capacity for advanced biobased raw materials. The supply chain for green coatings concentrates in China, Germany, and the United States. Raw material dependencies include petrochemical derivatives, plant oils, and specialized resins for high-performance systems. Agricultural feedstock price volatility for biobased materials presents a structural supply chain risk. Distribution runs through a fragmented network of direct-to-contractor channels and specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The green coatings market presents a fragmentation opportunity, driven by the demand-side shift towards specifying integrated coating systems by large architectural firms.
For Market Incumbents:Entrench existing market share by investing in captive production of advanced biobased resins to ensure supply consistency. Strengthen direct-to-contractor networks, especially in architectural applications, to counter digital platform displacement. Pursue certification investments in new low-VOC and zero-VOC formulations to meet evolving regulatory standards. Develop full system solutions rather than individual products to secure integrated project specifications.
For New Entrants and Emerging Players:Build out specialized capabilities in high-performance niches, such as aerospace interiors or electric vehicle components, where margins are higher. Target cost-effective waterborne solutions for emerging markets in Southeast Asia, leveraging rapid urbanization trends. A go-to-market angle involves partnering with architectural firms to co-develop and specify integrated green coating systems. Focus on functional additives integration to create strong product differentiation.
For Investors and Strategic Acquirers:The market sits at a growth phase that favors material science innovators with proprietary biobased technologies. Strong regulatory tailwinds ensure sustained demand over the next decade, enhancing long-term viability. Acquisition targets should include biobased resin developers or formulation simulation software providers. Quarterly review of new regulatory mandates and biobased material cost trends is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Secures raw material supply for growing low-VOC and biobased demand. |
| Green Manufacturing Transition | Reduces operational environmental footprint and improves brand perception. |
| Long-term Supply Agreement | Ensures consistent access to specialized biobased raw materials. |
| Product Launch | Introduces differentiated functional green coatings for specific applications. |
| Joint Venture | Accelerates R&D in advanced biobased resins and low-VOC systems. |
Research Approach
Initial hypotheses were tested against primary input from R&D chemists, procurement leads, regulatory affairs specialists, and architectural specifiers, and refined through iterative feedback. This involved combining in-depth interviews with validation against secondary sources like EU REACH documentation, US EPA reports, China MEE standards, and corporate sustainability reports. Bottom-up market sizing was triangulated with top-down validation to ensure accuracy.
Demand-supply-balance framing informed the analytical framework across the modeling period, projecting market evolution. Segmentation dimensions modeled included product type, technology, application, end user, and regional regulatory stringency. Compound annual growth rates were derived from historical trends, projected regulatory impacts, and anticipated technological adoption curves. Key industry-specific forecast inputs included VOC emission limits and biobased material prices.
Stress conditions across global commodity prices, regulatory enforcement timelines, and R&D breakthroughs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory stability and technological progress. Quarterly review of new regulatory mandates and biobased material cost trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Green Waterproofing Products Market
Green Building Materials
Green Rebar Market
Green Building Materials
Europe Green Cement Market
Green Building Materials
Solar Glass Market
Green Building Materials
Eco-Friendly Tiles Market
Green Building Materials
Sustainable and Green Building Materials Market
Green Building Materials
Solar Windows Market
Green Building Materials
United States Green Cement Market
Green Building Materials
Global Green Walls Market
Green Building Materials
Artificial Green Wall Market
Green Building Materials
Eco Flooring Market
Green Building Materials
Sustainable Construction Market
Green Building Materials
APAC Green Buildings Market
Green Building Materials
Energy Efficient Window and Door Market
Green Building Materials
Solar Frames Market
Green Building Materials
North America Green Buildings Market