
 Energy Efficient Window and Door Market | 2026-2036
Energy Efficient Window and Door Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Efficient Window and Door Market Insights
Polyvinyl chloride framing is rebalancing toward fiberglass and composite cores as thermal performance thresholds tighten. Andersen Windows leverages captive pultrusion capacity to control fiberglass supply. Pella sustains R&D intensity across its Iowa engineering campus. Marvin anchors premium wood-clad positioning in coastal Northeast markets.
Energy efficient windows and doors are building envelope components engineered to minimize thermal transmittance, typically achieving U-Factors below 0.25 Btu/hr路ft虏路掳F through multi-cavity glazing, warm-edge spacers, and thermally broken frames. Their primary purpose is to reduce HVAC load while maintaining daylighting and structural integrity. Vinyl Windows still occupies the largest volume tier across North American residential channels. Triple Glazing is displacing double-pane configurations in Northern European renovation pipelines. Commercial Buildings application commands elevated margin pools due to specification complexity and energy consultant involvement.
EPA ENERGY STAR certification, EU Ecodesign requirements, and California Title 24 building standards collectively tighten minimum performance thresholds and restrict market access for non-compliant products. The EU Green Deal renovation wave and US IRA efficiency tax credits are channeling public capital toward deep retrofit programs. Stakeholders must monitor how regional U-Factor mandates diverge and whether supply chains for warm-edge spacer technology can match specification velocity.
Market Dynamics
Building energy codes are tightening thermal transmittance thresholds faster than frame and glazing supply chains can adapt, forcing simultaneous retooling across vinyl extrusion, fiberglass pultrusion, and warm-edge spacer manufacturing.
Growth Catalysts
- EU Green Deal renovation wave:Deep retrofit mandates across Germany, France, and Poland are accelerating triple-glazed window replacement in post-war housing stocks.
- US IRA efficiency tax credits:The Inflation Reduction Act channels homeowner subsidies toward ENERGY STAR-certified window upgrades in mature single-family markets.
- Warm-edge spacer technology:Swiss and Austrian component suppliers are scaling silicone-based thermal break production to meet Northern European U-Factor mandates.
Market Restraints
- Argon and krypton gas supply concentration:Inert gas fills for triple glazing depend on Ukrainian and Russian industrial gas infrastructure, creating fill-rate volatility.
- Fiberglass raw material cost structure:E-glass roving and resin systems track petrochemical indices, compressing margin on thermally broken frame assemblies.
- Technical limitation in historic renovation:Thin-profile triple glazing exceeds sightline constraints of pre-1940s steel window frames, restricting deep retrofit penetration.
Strategic Opportunities
- Underpenetrated geography:Italy and Spain retain high shares of single-pane glazing in rental housing, creating latent replacement demand as EU Ecodesign enforcement tightens.
- Technology convergence:Electrochromic glazing integration with building management systems is opening premium commercial specification channels.
- Regulatory tailwind:California Title 24's 2025 thermal envelope standards will mandate net-zero-ready fenestration in new residential construction.
Industry Challenges
- Warm-edge spacer fabrication skill gap:Automated spacer bending and desiccant filling require technician training pipelines that vocational programs have not scaled.
- Triple glazing certification timeline:NFRC simulated energy performance ratings extend product development cycles by eight to fourteen months.
- Legacy window removal logistics:Deconstruction and landfill diversion requirements in Massachusetts and Vermont add project management complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Efficient Window and Door Market |
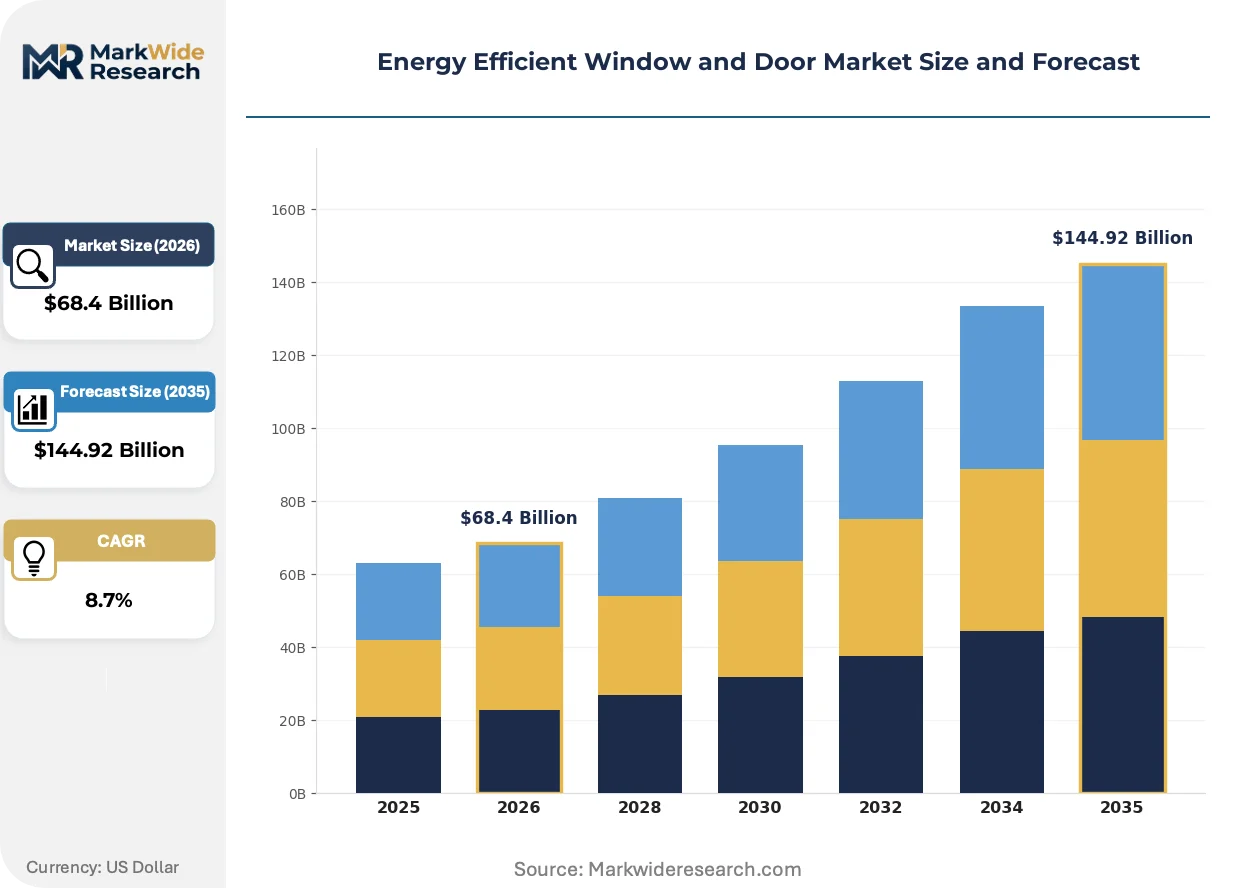
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl Windows, Aluminum Doors, Wood Frames, Fiberglass Windows, Composite Doors Technology: Low-E Glass, Double Glazing, Triple Glazing, Insulated Frames, Solar Control Coatings Application: New Construction, Renovation Projects, Commercial Buildings, Educational Facilities, Hospitality Structures End User: Contractors, Architects, Property Developers, Facility Managers, Energy Consultants |
| Companies Covered | Andersen Windows, Pella, JELD-WEN, Marvin, REHAU, Milgard, Ply Gem, Therma-Tru Doors, Fenesta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Efficient Window and Door Market Trends and Innovations
Vacuum-insulated glazing and thermoplastic composite frames are compressing the performance gap between residential retrofit feasibility and passive house standards. Material science advances and regulatory precision are converging to redefine cost-thermal trade-offs.
Vacuum-insulated glazing (VIG) is consolidating its position in high-density urban renovation where triple-pane unit thickness exceeds existing frame rebates. London and New York multifamily developers specify VIG for heritage facade retention. The technology is consolidating supplier R&D investment away from incremental spacer improvements toward evacuated cavity systems.
The EU F-Gas Regulation is phasing down hydrofluorocarbon blowing agents used in polyurethane thermal breaks and insulated frame cores. Spanish and Portuguese window fabricators face reformulation deadlines for polyamide strips and foam-in-place gaskets. The regulation is compressing formulation timelines for frame system suppliers serving Mediterranean export markets.
Performance-based procurement is displacing unit-cost bidding in German and Austrian social housing tenders. Energy consultants now specify whole-window U-Factor and g-value targets rather than generic product categories. This shift is visible in Vienna and Hamburg where housing associations bundle window replacement with HVAC system downsizing.
Energy Efficient Window and Door Market Segmentation
Energy efficient window and door procurement follows distinct technical and commercial logics across building types and stakeholder groups. Specification requirements diverge sharply between thermal performance mandates for new construction versus aesthetic constraints in historic renovation.
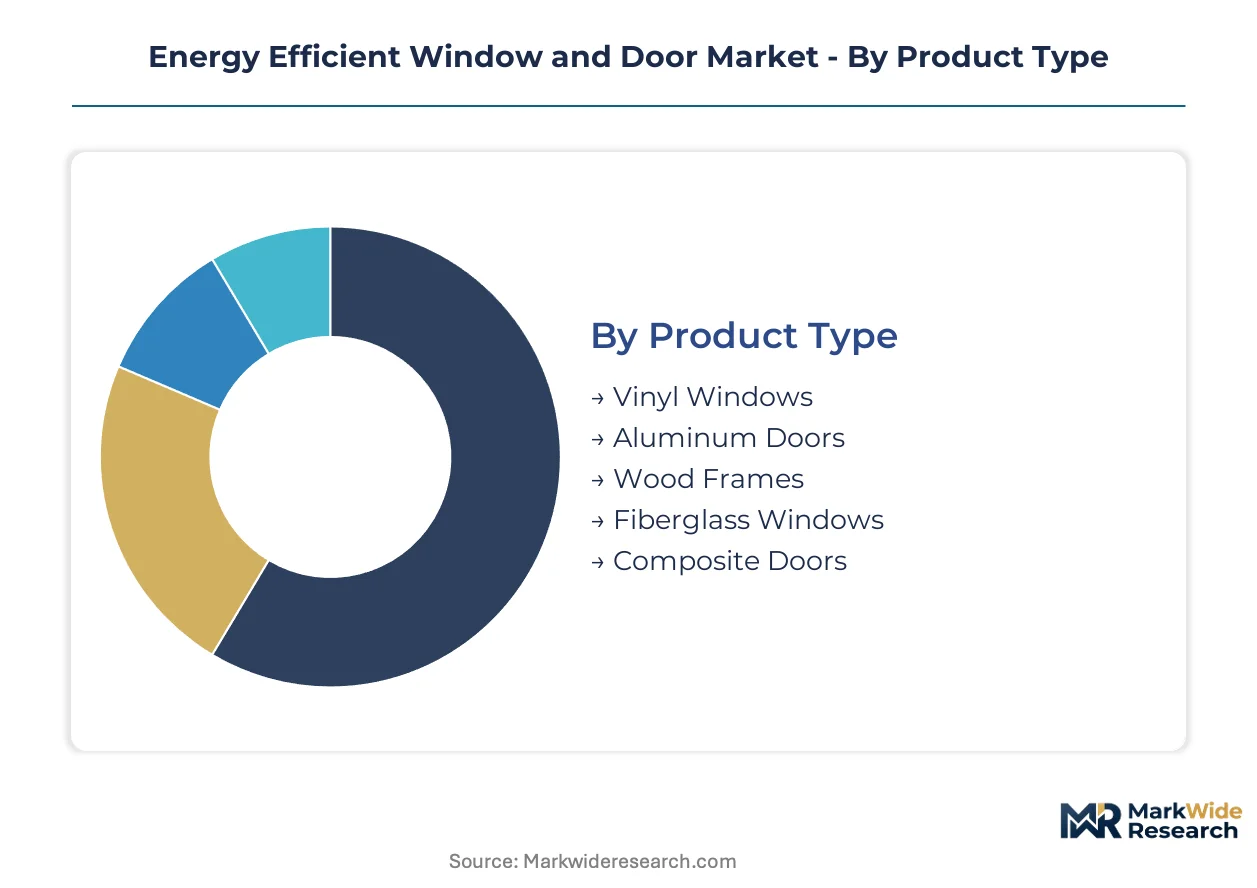
Product Type:
Buyer selection hinges on thermal performance thresholds relative to installed cost and maintenance burden across climate zones.
- Vinyl Windows:Multi-chamber extruded PVC frames with welded corners dominate volume procurement in North American residential replacement channels. Demand concentrates in US Midwest and Southeast single-family retrofits where cost sensitivity outweighs premium material preferences.
- Fiberglass Windows:Pultruded glass-fiber reinforced profiles achieve superior thermal expansion coefficients and structural rigidity for large-format glazing. German and Austrian fabricators specify these for passive house-certified multifamily developments where frame U-Factors must fall below 0.8 W/m虏K.
- Aluminum Doors:Thermally broken extrusions with polyamide strips serve commercial entrance systems requiring slimmer sightlines than vinyl or fiberglass allow.
- Wood Frames:Solid timber or engineered lumber with aluminum exterior cladding retains premium positioning in heritage districts and coastal Northeast US markets.
- Composite Doors:Hybrid constructions combining insulating foam cores with fiberglass or steel facings address security and thermal requirements in mid-market residential entry applications.
Vinyl Windows leads on scale; Fiberglass Windows leads on momentum as EU Ecodesign enforcement tightens.
Technology:
Glazing configuration and coating selection determine whether assemblies meet jurisdiction-specific U-Factor mandates.
- Triple Glazing:Three lites separated by warm-edge spacers and gas-filled cavities achieve center-of-glass U-Factors approaching 0.15 Btu/hr路ft虏路掳F. Northern European renovation pipelines specify these for post-war housing stocks as Germany and Poland implement deep retrofit subsidies.
- Low-E Glass:Sputtered silver or tin oxide coatings reflect infrared radiation while transmitting visible light. US ENERGY STAR certification thresholds effectively mandate these coatings across all climate zones except southern Florida.
- Double Glazing:Two-lite configurations with argon fill retain dominant share in cost-constrained replacement markets and mild climate new construction.
- Insulated Frames:Polyurethane foam or aerogel-filled profiles reduce linear thermal transmittance at the frame edge.
- Solar Control Coatings:Spectrally selective layers managing solar heat gain coefficient serve commercial facades in cooling-dominated climates.
Double Glazing retains volume leadership; Triple Glazing gains share fastest where EU Green Deal funding penetrates.
Application:
Project delivery method and specification authority shape procurement channels and margin structures.
- Renovation Projects:Existing building envelope upgrades involve field measurement, custom fabrication, and disruption management. Demand clusters in Germany, France, and UK social housing programs targeting pre-1990 building stocks with single-pane glazing.
- Commercial Buildings:Office and retail specifications involve energy consultants, facade engineers, and building management system integration. These projects command elevated margins due to performance guarantees and commissioning requirements.
- New Construction:Production homebuilders and multifamily developers specify standard sizes with volume pricing.
- Educational Facilities:K-12 and university projects prioritize durability and acoustic performance alongside thermal metrics.
- Hospitality Structures:Hotels and resorts balance energy performance with guest comfort and brand aesthetic requirements.
New Construction dominates unit volumes; Renovation Projects commands steepest expansion trajectory as building stock ages and retrofit incentives proliferate.
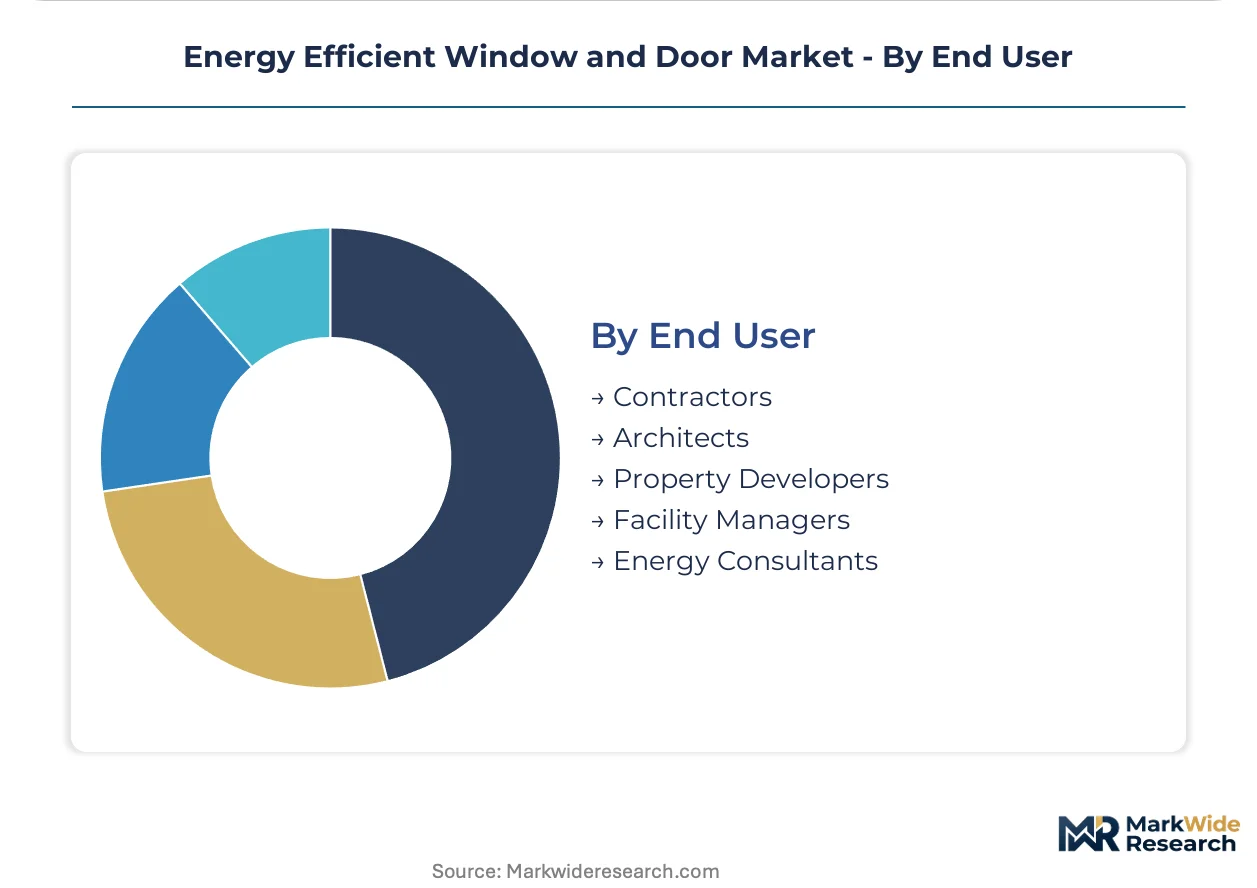
End User:
Technical sophistication and specification authority vary dramatically across the value chain.
- Energy Consultants:Third-party analysts specify whole-building U-Factor targets and g-value requirements in German and Austrian social housing tenders. These stakeholders displace generic product categories with performance-based procurement.
- Property Developers:Multifamily and commercial project sponsors balance first cost against operational expense reductions and green building certification premiums.
- Contractors:Installation firms influence substitution decisions based on lead time, fabrication tolerance, and crew familiarity.
- Architects:Design professionals specify aesthetic and performance criteria but often delegate technical glazing selection to specialized consultants.
- Facility Managers:Building operations staff drive replacement decisions based on energy cost escalation and occupant comfort complaints.
Contractors transact highest unit volumes; Energy Consultants gain influence fastest as performance-based procurement spreads beyond German-speaking markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr corridor anchors European fenestration manufacturing, with triple-glazed production scaling to meet EU Green Deal renovation mandates across Northern Europe and North American coastal markets.
Germany
Deep retrofit subsidies in post-war social housing stocks drive triple-glazed procurement volumes. The EU Ecodesign Directive enforces progressively lower U-Factor thresholds through 2030. Fabrication clusters in Bavaria and North Rhine-Westphalia supply passive house-certified assemblies for Austrian and Swiss export markets.
United States
IRA efficiency tax credits channel homeowner investment toward ENERGY STAR-certified replacements in mature single-family markets. EPA certification thresholds effectively mandate Low-E coatings across all climate zones except southern Florida. Andersen Windows and Pella anchor production capacity in Minnesota and Iowa for Midwest and Northeast distribution.
China
Dual carbon goals accelerate building envelope efficiency standards in tier-one cities. The Ministry of Ecology and Environment tightens energy codes for commercial construction in Beijing-Tianjin-Hebei and Yangtze River Delta clusters. Domestic fabricators scale warm-edge spacer production to reduce import dependence from Swiss and Austrian suppliers.
United Kingdom
Social housing decarbonization programs target pre-1990 building stocks with single-pane glazing. Building Regulations Part L revisions mandate net-zero-ready fenestration in new residential construction from 2025. London multifamily developers specify vacuum-insulated glazing for heritage facade retention where triple-pane thickness exceeds existing frame rebates.
Poland
EU cohesion funds finance window replacement in communist-era panel housing districts. The National Reconstruction Plan channels subsidies toward building envelope upgrades in Krakow and Warsaw metropolitan areas. Local fabricators expand warm-edge spacer bending capacity to meet German and Austrian component import demand.
Energy Efficient Window and Door Market Competitive Landscape
Global majors compete with regional champions across thermal performance certification and local fabrication proximity. The market structure consolidates around vertically integrated frame manufacturers with captive glass processing, while specialist component suppliers concentrate in Swiss and Austrian warm-edge spacer technology. Three archetypes dominate: North American residential replacement specialists, European passive house fabricators, and Asian cost-optimized volume producers. Capacity expansion and backward integration into fiberglass pultrusion represent the primary competitive vectors.
Among North American residential specialists, Andersen Windows, Pella, and Marvin occupy positions across premium and mid-market tiers. Andersen Windows exemplifies vertical control through captive fiberglass supply chains. Pella represents sustained engineering investment in Iowa-based product development. Marvin anchors wood-clad positioning in coastal Northeast markets where salt exposure drives material selection.
| Leading Market Players |
|---|
| Andersen Windows |
| Pella |
| JELD-WEN |
| Marvin |
| REHAU |
| Milgard |
| Ply Gem |
| Therma-Tru Doors |
| Fenesta |
| Others |
Pricing and Supply Chain Analysis
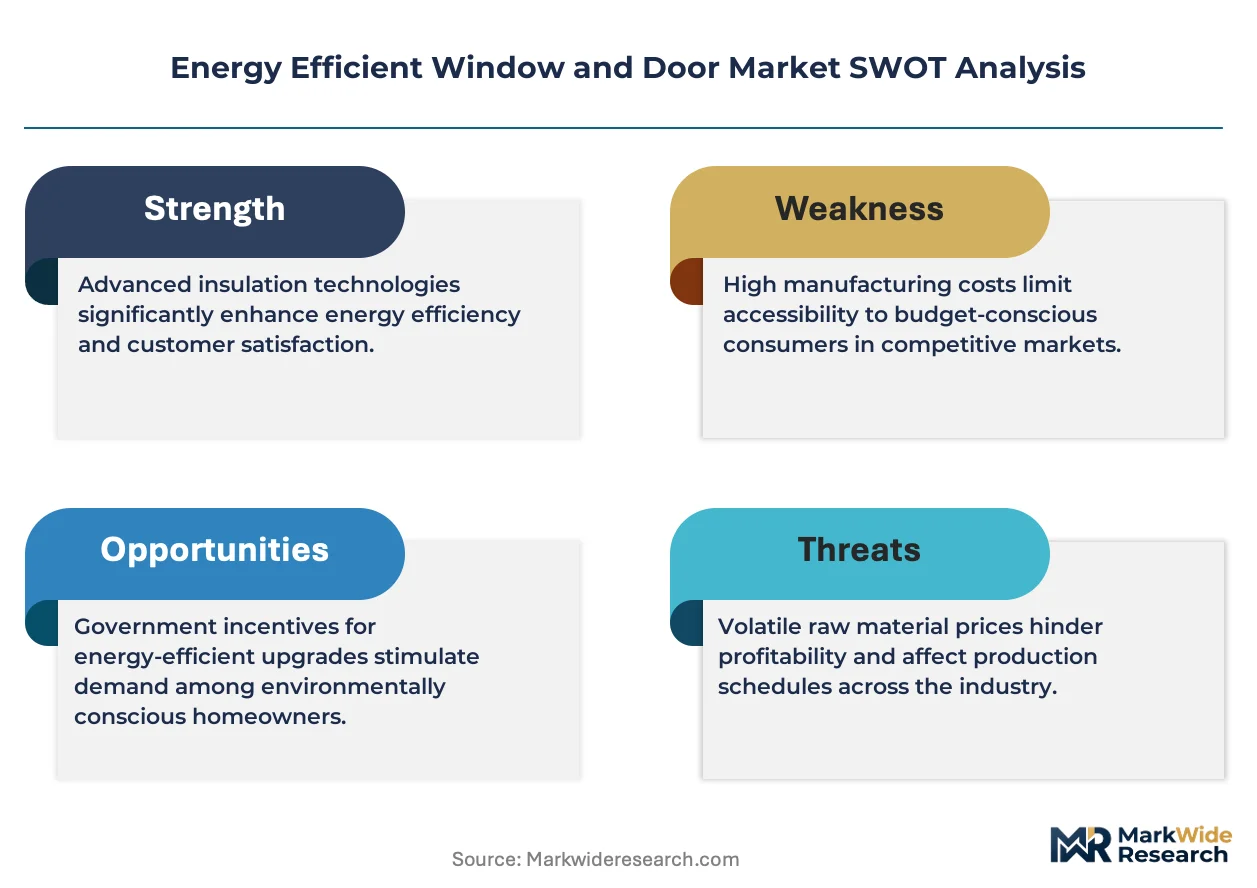
EU Ecodesign enforcement tightening U-Factor thresholds below 0.8 W/m²K is forcing fabricators to retool toward triple-glazed assemblies and warm-edge spacer systems, compressing margins on legacy double-pane lines while premium-tier pricing captures performance-certified volumes.
Pricing Analysis
Input-cost pass-through from E-glass roving and petrochemical resin indices is compressing margins on thermally broken fiberglass frames, while argon and krypton gas fill volatility from Eastern European supply concentration adds further cost uncertainty. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and thermal performance tier, with passive house-certified assemblies commanding substantial premiums over ENERGY STAR baseline products. Pricing pressure stems from vinyl extrusion overcapacity in North American residential replacement channels, where cost compression is intensifying due to buyer consolidation among production homebuilders. Contractors in Midwest and Southeast US markets exhibit highest price sensitivity, while German and Austrian social housing associations prioritize whole-window U-Factor performance over unit cost.
Supply Chain Analysis
Workforce availability constraints in Bavaria and North Rhine-Westphalia fabrication clusters are limiting warm-edge spacer bending capacity expansion, even as demand from Polish and Austrian export markets accelerates. Supply concentrates in Germany, China, and the United States, with Swiss and Austrian component suppliers anchoring thermal break technology for Northern European passive house specifications. Raw material dependencies rest on Ukrainian and Russian industrial gas infrastructure for inert fills, E-glass roving from Chinese and European smelters, and polyamide thermal break strips from German and Austrian polymer specialists. Single-source vulnerability in noble gas supply creates fill-rate volatility for triple-glazed production. Distribution runs through regional fabricator networks with direct-to-contractor channels dominating North American residential replacement, while European markets favor specification-through-consultant models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through backward integration into fiberglass pultrusion and warm-edge spacer production, capturing value that currently flows to Austrian and Swiss component suppliers while premium-tier positioning in passive house certification commands pricing power.
For Market Incumbents: Anchor defensive positioning through captive supply of fiberglass profiles and warm-edge spacer technology, insulating against Austrian and Swiss component supplier pricing power while building installation service capabilities to capture renovation project margins threatened by contractor consolidation. Capacity addition in Poland and Bavaria addresses EU Green Deal demand proximity, while NFRC certification investment extends product development timelines that smaller competitors cannot match. For New Entrants and Emerging Players: Begin with vacuum-insulated glazing technology for high-density urban renovation where triple-pane thickness exceeds existing frame rebates, targeting London and New York multifamily developers facing heritage facade constraints. Italy and Spain present the most penetrable geographies, with high shares of single-pane glazing in rental housing and tightening EU Ecodesign enforcement creating latent replacement demand. A specification-through-energy-consultant go-to-market angle aligns with performance-based procurement spreading from German-speaking markets. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap fabricators possessing warm-edge spacer bending capability and passive house certification infrastructure, as these technical assets face scarcity amid EU renovation wave acceleration. Long-term viability hinges on regulatory enforcement durability and supply chain localization trends favoring regional production over Asian import dependence. Watch NFRC certification timeline compression and Massachusetts deconstruction mandate expansion as inflection indicators for technical capability premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiberglass Pultrusion | Captures margin from E-glass roving cost volatility while securing supply for thermally broken frame production. |
| Warm-Edge Spacer Manufacturing Scale-Up | Addresses technician skill gaps constraining Northern European triple-glazed output and Austrian import dependence. |
| Vacuum-Insulated Glazing Product Launch | Opens heritage renovation channels in London and New York where triple-pane thickness exceeds existing rebates. |
| Installation Service Capability Buildout | Captures renovation project margins and addresses Massachusetts and Vermont deconstruction logistics requirements. |
| Passive House Certification Investment | Secures specification in German and Austrian social housing tenders using performance-based procurement criteria. |
Research Methodology
Bottom-up residential and commercial construction modeling reconciled against top-down frame and glazing production tracking forms the analytical core, combining primary interviews with window fabricator procurement directors, energy consultant specification leads, contractor installation firms, and warm-edge spacer component suppliers with secondary validation from EPA ENERGY STAR certification databases, EU Ecodesign directive implementation reports, and NFRC simulated energy performance ratings.
Input-output matrices mapping E-glass roving and resin consumption to pultruded frame output, cross-referenced with ENERGY STAR and passive house certification volumes across the projection horizon, underpin segment-level demand estimation. Segmentation dimensions modeled include product type, glazing technology, application channel, and end-user specification authority, with CAGRs derived from regression analysis against building permit flows and retrofit incentive appropriations. Argon and krypton gas supply concentration and EU F-Gas Regulation phase-down timelines inform supply-side constraint modeling.
Several conditions sit outside the modeled scope, including geopolitical disruption to Ukrainian and Russian industrial gas infrastructure, abrupt relaxation of EU or US state-level building energy codes, and breakthrough displacement of triple glazing by electrochromic or vacuum-insulated alternatives. Forecasts reflect assumptions around regulatory enforcement continuity and supply chain localization trends. Material deviation in noble gas supply stability or NFRC certification timeline compression warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Green Waterproofing Products Market
Green Building Materials
Outdoor Flooring Market
Green Building Materials
Green Cement and Concrete Market
Green Building Materials
GCC Green Cement Market
Green Building Materials
Sustainable and Green Building Materials Market
Green Building Materials
Eco Flooring Market
Green Building Materials
Artificial Green Wall Market
Green Building Materials
Solar Windows Market
Green Building Materials
Green Cement Market
Green Building Materials
Green Silica Market
Green Building Materials
Green Building Materials Market
Green Building Materials
Global Green Walls Market
Green Building Materials
Solar Frames Market
Green Building Materials
Green Rebar Market
Green Building Materials
Asia Pacific Green Cement Market
Green Building Materials
Green Roof Market