
 APAC Green Buildings Market | 2026-2036
APAC Green Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Green Buildings Market Insights
Net-zero-ready specifications are reorganizing procurement priorities across the APAC green buildings landscape. Shimizu Corporation leverages its integrated design-build platform to deliver high-performance envelopes across Japanese commercial towers. Taisei Corporation anchors its competitive position through advanced seismic-resistant sustainable structures. CapitaLand Limited differentiates via deep exposure to Singapore's premium certified office stock.
Green buildings integrate energy-efficient systems, low-carbon materials, and smart controls to minimize operational emissions and resource consumption across the building lifecycle. These structures typically target sub-50 kWh per square meter annual energy intensity while maintaining indoor environmental quality standards. Commercial certification programs including LEED and Green Star command premium leasing spreads across major APAC financial districts. Smart Lighting and Energy Management Systems represent the fastest-expanding technology clusters as owners prioritize operational carbon reduction. Sustainable Wood and Concrete Alternatives are gaining specification share as embodied carbon accounting tightens across supply chains.
China's MEE enforces dual carbon compliance timelines that reshape new construction permitting across provincial markets. Australia's NABERS and Green Star frameworks mandate disclosure-driven performance upgrades in existing building stock. Singapore's BCA Green Mark program sets mandatory efficiency thresholds for commercial developments above specified floor areas. Stakeholders must track how certification convergence between national schemes and international standards affects cross-border project financing and tenant covenant requirements.
Market Dynamics
Dual carbon compliance timelines across China are compressing permitting windows for new commercial construction, forcing developers to pre-certify net-zero performance before breaking ground. This regulatory velocity is cascading through Southeast Asian markets as regional investors demand comparable environmental accountability.
Growth Catalysts
- NABERS disclosure mandates:Australia's performance-based rating system requires existing commercial stock to publish operational energy intensity, creating refurbishment demand across Sydney and Melbourne office towers.
- Smart building controls:IoT-enabled energy management systems reduce HVAC loads through predictive occupancy algorithms, with Singapore's BCA Green Mark program accelerating specification in premium developments.
- Urban corridor density:Jakarta, Bangkok, and Ho Chi Minh City concentrate new Grade A supply where land scarcity justifies vertical construction with integrated sustainability systems.
Market Restraints
- Low-carbon material premiums:Mass timber and geopolymer concrete carry 15-40% cost premiums over conventional steel and Portland cement, compressing developer margins on fixed-price contracts.
- Certification fragmentation:Divergent pathways between LEED, Green Star, and national schemes force project teams to pursue multiple parallel assessments, extending design timelines.
- Grid infrastructure lag:Vietnam and Indonesia's transmission networks cannot reliably support all-electric building systems in secondary cities, limiting electrification strategies.
Strategic Opportunities
- Philippines commercial retrofits:Manila's aging office stock lacks basic efficiency systems, creating first-mover advantage for performance contracting models tied to NABERS-equivalent ratings.
- Green bond financing:Certification-linked debt instruments from Singapore and Hong Kong exchanges reduce capital costs for projects meeting specified envelope performance thresholds.
- AI-driven commissioning:Machine learning platforms that optimize building startup sequences are penetrating Japanese and Korean markets where precision energy targeting commands tenant premiums.
Industry Challenges
- Commissioning agent scarcity:Qualified professionals who can verify integrated system performance across MEP and envelope domains remain concentrated in Tokyo, Sydney, and Singapore.
- Embodied carbon accounting:Supply chain data gaps for steel, aluminum, and glass prevent accurate lifecycle assessments required by emerging procurement clauses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Green Buildings Market |
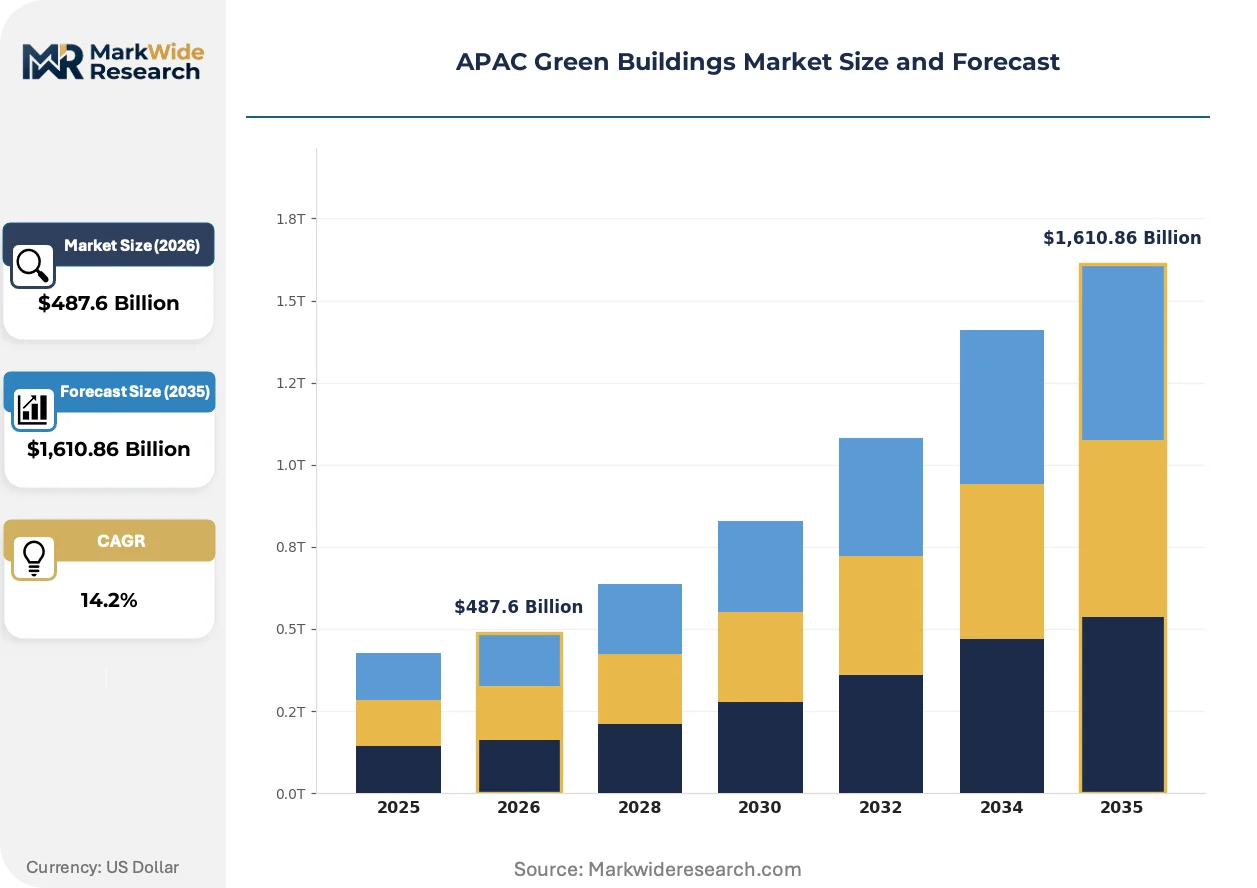
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,610.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Building Type: Residential, Commercial, Industrial, Institutional Technology: Solar Panels, Energy Management Systems, HVAC Systems, Smart Lighting Material: Recycled Materials, Sustainable Wood, Green Insulation, Concrete Alternatives Certification: LEED, BREEAM, Green Star, NABERS |
| Companies Covered | Shimizu Corporation, Taisei Corporation, Kajima Corporation, Obayashi Corporation, Lendlease Group, Swire Properties, CapitaLand Limited, City Developments Limited, Gamuda Land, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Green Buildings Market Trends and Innovations
Performance simulation tools and prefabricated envelope systems are compressing design-to-occupancy cycles across major APAC commercial developments. These innovations reshape how developers balance capital efficiency against operational carbon commitments.
High-performance facade systems incorporating electrochromic glazing and automated shading are bifurcating the specification landscape. Premium office developers in Singapore and Sydney are mandating dynamic envelope controls to hit sub-50 kWh per square meter targets. This technology is compressing the performance gap between speculative and trophy assets, forcing mid-tier projects to justify higher rents through measurable efficiency gains.
China's MEE enforcement of dual carbon compliance timelines is tightening new construction permitting across provincial markets. Developers must now submit operational energy models before receiving occupancy certificates, shifting design risk earlier in project cycles. Guangdong and Jiangsu provinces are responding fastest, with local design institutes building dedicated net-zero simulation teams.
Tenant covenant structures now embed sustainability performance clauses that trigger rent adjustments based on actual metered consumption. Singapore's institutional investors are pioneering green lease templates that transfer operational efficiency risk to building operators. This behavioral shift is most visible in Sydney's CBD, where major financial services tenants refuse space lacking disclosed NABERS ratings above specified thresholds.
APAC Green Buildings Market Segmentation
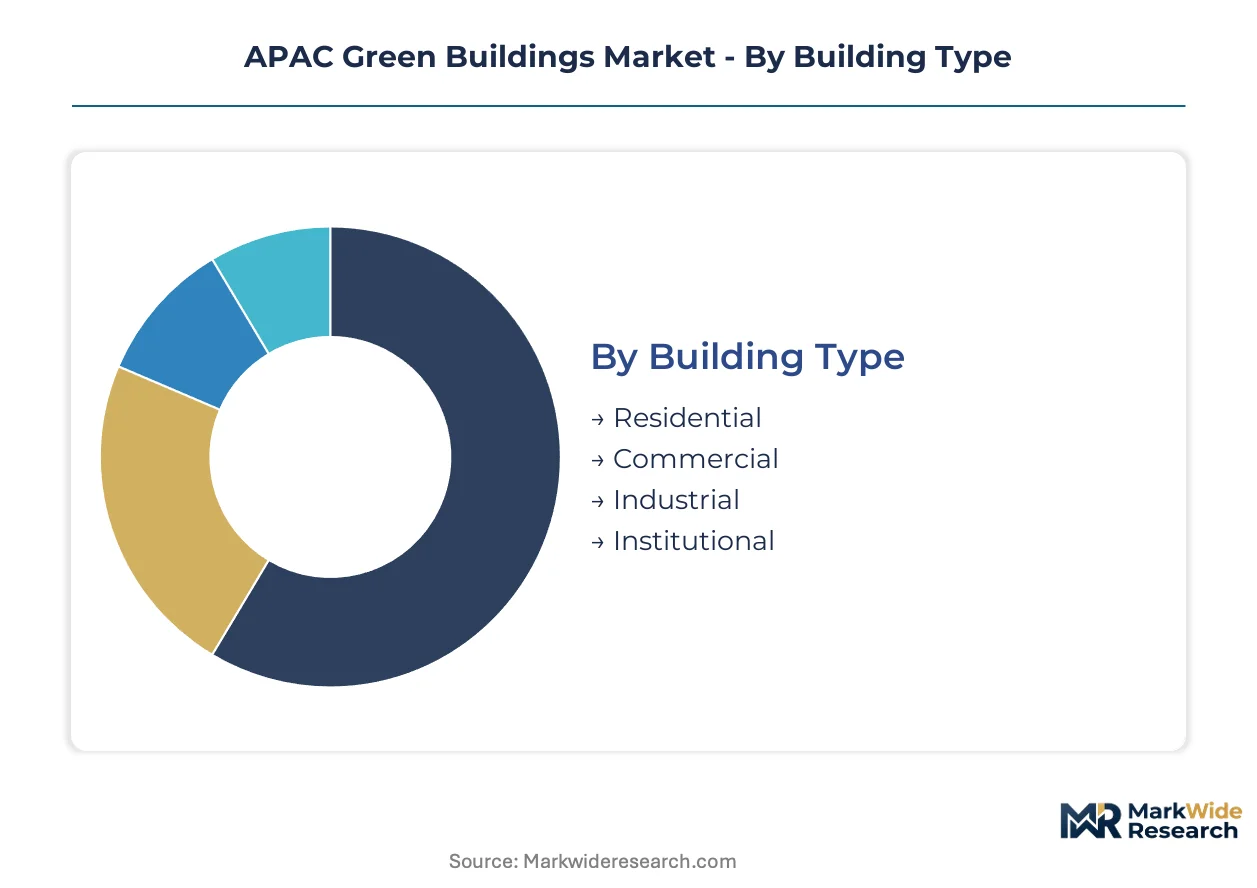
Segmentation reveals how procurement priorities diverge across building lifecycles in the APAC green buildings market. Certification requirements and material specifications cascade differently through residential towers in Ho Chi Minh City versus commercial developments in Sydney.
Building Type:
Channel flows split sharply between owner-occupied institutional projects and speculative commercial developments, with distinct financing structures governing each pathway.
- Residential:High-rise towers in Jakarta and Bangkok integrate solar thermal and rainwater harvesting as baseline amenities. Developer competition for green financing concentrates demand in premium condominium segments where BCA Green Mark and LEED certifications command resale premiums.
- Commercial:Grade A office stock in Singapore and Sydney anchors net-zero leasing spreads. NABERS disclosure mandates and green lease templates now require sub-50 kWh per square meter performance guarantees before institutional capital deploys.
- Industrial:Warehouse and logistics facilities prioritize rooftop solar arrays and high-efficiency envelope systems to offset cooling loads across Southeast Asian distribution corridors.
- Institutional:Government and healthcare buildings in China face MEE-mandated dual carbon compliance timelines, with provincial design institutes pre-certifying operational energy models prior to occupancy permits.
Commercial dominates installed base. Residential is where expansion concentrates.
Technology:
Cost tiers separate mature building systems from emerging digital infrastructure, with integration complexity driving specification decisions.
- Energy Management Systems:IoT-enabled platforms with predictive occupancy algorithms reduce HVAC loads across Singapore's premium developments. BCA Green Mark program acceleration and tenant covenant structures demanding metered performance verification are concentrating procurement in integrated system architectures.
- Smart Lighting:LED networks with daylight harvesting and automated controls achieve 40-60% lighting energy reduction. Deployment concentrates in Sydney and Melbourne office retrofits where NABERS rating improvements directly affect asset valuations.
- Solar Panels:Rooftop photovoltaic systems with battery storage integration satisfy on-site renewable generation requirements across China's provincial construction permitting.
- HVAC Systems:Variable refrigerant flow and geothermal exchange systems address tropical cooling demands in Bangkok and Jakarta high-rises.
Energy Management Systems command the steepest expansion trajectory. HVAC Systems retain the largest installed footprint.
Material:
Volume concentration in mass timber and low-carbon concrete alternatives reflects embodied carbon accounting tightening across supply chains.
- Concrete Alternatives:Geopolymer and alkali-activated binders reduce Portland cement content by 50-80%. Cost premiums of 15-40% over conventional concrete compress margins on fixed-price contracts, limiting adoption to trophy assets in Sydney and Singapore.
- Sustainable Wood:Cross-laminated timber and glulam systems sequester carbon while enabling rapid prefabricated construction. Japanese commercial developers leverage domestic forestry certification to meet METI procurement guidelines.
- Recycled Materials:Steel with high scrap content and reclaimed aggregates satisfy circular economy clauses in Australian Green Star assessments.
- Green Insulation:Cellulose, sheep wool, and aerogel products address thermal bridging in high-performance envelopes across temperate Australian and Japanese markets.
Concrete Alternatives attract development-stage investment. Sustainable Wood scales most quickly in Japan and Australia.
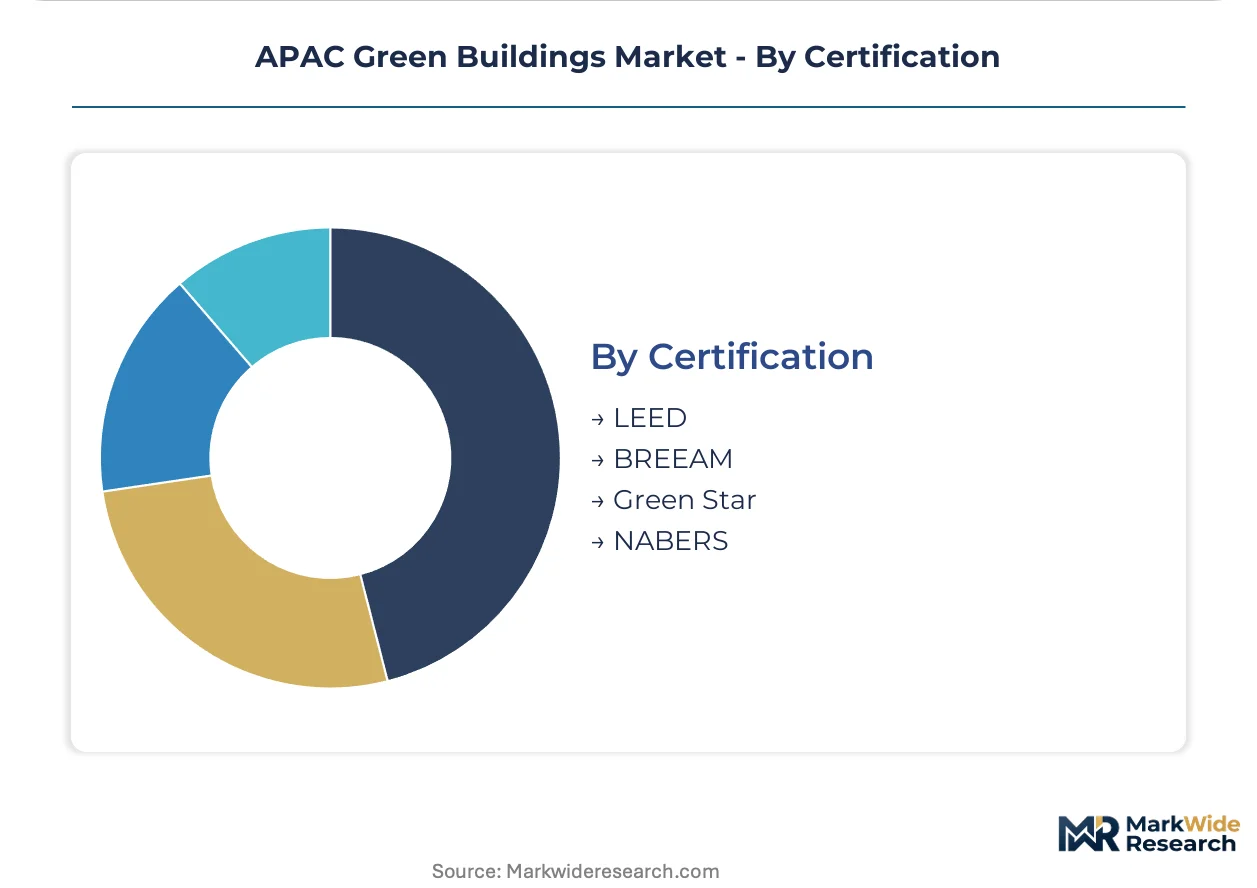
Certification:
Geography determines scheme selection, with national programs converging toward international standards for cross-border financing.
- LEED:USGBC's global framework dominates multinational tenant requirements across APAC financial districts. Premium leasing spreads in Singapore and Hong Kong justify dual-certification strategies alongside national schemes.
- NABERS:Australia's performance-based rating mandates operational energy disclosure for existing commercial stock. Sydney and Melbourne office towers face refurbishment pressure to maintain investment-grade ratings above specified thresholds.
- Green Star:GBCA's holistic framework integrates embodied carbon and health criteria, with version upgrades tightening material procurement requirements.
- BREEAM:UK-originated scheme retains niche presence in Hong Kong and Singapore developments targeting European institutional investors.
NABERS dominates Australian operational performance verification. LEED spans the widest cross-border project financing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital flows into green building development across APAC increasingly favor net-zero-certified assets, with Singapore, Australia, and China importing design expertise while exporting financing structures to Southeast Asian emerging markets.
China
Provincial construction permitting now requires operational energy models before occupancy certificates, with Guangdong and Jiangsu provinces building dedicated net-zero simulation teams. MEE enforces dual carbon compliance timelines that compress development windows. Shanghai and Shenzhen commercial towers anchor the largest certified stock in the region.
Australia
NABERS disclosure mandates force Sydney and Melbourne office towers into performance-based refurbishment cycles to maintain investment-grade ratings. Green Star framework upgrades tighten material procurement requirements. Sydney CBD institutional investors now refuse capital deployment without sub-50 kWh per square meter performance guarantees.
Singapore
BCA Green Mark program mandates efficiency thresholds for commercial developments above specified floor areas, accelerating smart building controls specification. Green lease templates transfer operational efficiency risk to building operators. Marina Bay and Raffles Place financial districts command premium leasing spreads for dual-certified assets.
Japan
METI procurement guidelines drive cross-laminated timber adoption in commercial developments, with domestic forestry certification enabling rapid prefabricated construction. Tokyo's design institutes concentrate qualified commissioning agents for integrated MEP and envelope verification. Osaka and Nagoya towers integrate advanced seismic-resistant sustainable structures.
Vietnam
Ho Chi Minh City Grade A supply concentrates new vertical construction with integrated sustainability systems, though grid infrastructure lag limits full electrification strategies. Green bond financing from regional exchanges reduces capital costs for envelope performance thresholds. District 2 and Thu Thiem new urban areas anchor certified commercial development.
APAC Green Buildings Market Competitive Landscape
Concentration sits with integrated design-build platforms and premium certified office developers across the region. Japanese general contractors anchor high-performance envelope delivery through captive engineering capabilities. Australian and Singaporean property groups differentiate via certification depth and green lease structuring. Competitive moves center on strategic partnerships for low-carbon material sourcing and geographic expansion into Southeast Asian urban corridors.
Within the integrated contractor tier, Shimizu Corporation and Taisei Corporation represent archetypes of seismic-resistant sustainable construction platforms. CapitaLand Limited occupies a position exemplifying deep exposure to premium certified office stock. These three entities anchor the competitive spectrum from engineering-led delivery to asset-heavy development models across Tokyo, Singapore, and Sydney markets.
| Leading Market Players |
|---|
| Shimizu Corporation |
| Taisei Corporation |
| Kajima Corporation |
| Obayashi Corporation |
| Lendlease Group |
| Swire Properties |
| CapitaLand Limited |
| City Developments Limited |
| Gamuda Land |
| Others |
Pricing and Supply Chain Analysis
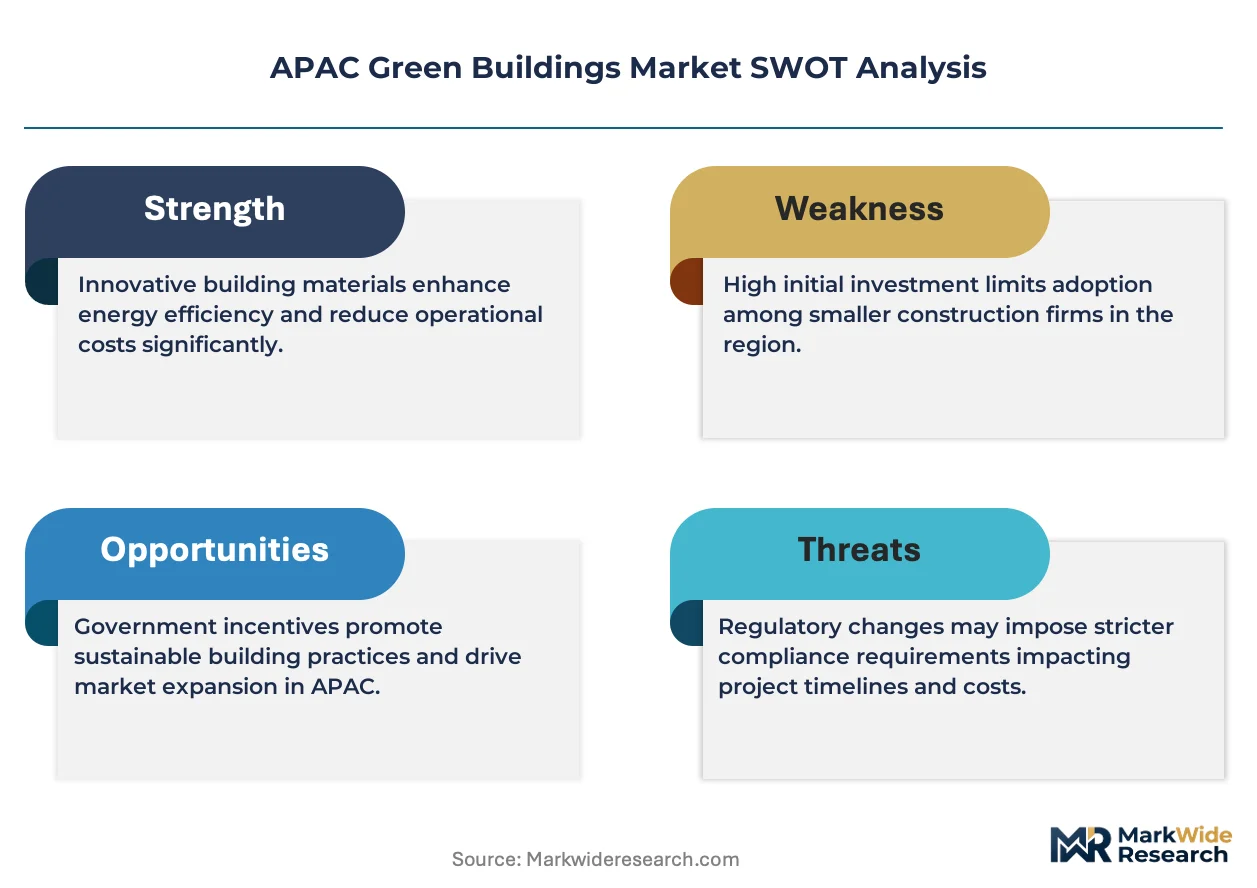
BCA Green Mark certification thresholds in Singapore gate both supplier qualification and price differentiation simultaneously, compressing procurement timelines for envelope systems while segmenting developer margins across certified and uncertified project tiers. This regulatory architecture concentrates pricing power with integrated design-build platforms that can pre-certify performance before construction mobilization.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across APAC green building developments. Pricing stratifies across premium, standard, and economy tiers based on certification depth and envelope performance guarantees. Cost compression in mid-tier commercial segments is intensifying because fixed-price contracts absorb low-carbon material premiums. Speculative developers exhibit highest price sensitivity; institutional owner-occupiers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Malacca Strait transit routes underwrite material flows for Southeast Asian construction corridors. Manufacturing concentrates in China, Japan, and South Korea for electrochromic glazing and smart building controls. Raw material dependencies include cross-laminated timber from certified Australian and Japanese forestry, geopolymer binders from regional cement producers, and high-performance glass from South Korean float lines. Single-source vulnerability sits with seismic-resistant structural components from Japanese engineering specialists. Distribution runs through integrated contractor channels with captive fabrication facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
APAC green buildings are approaching a platform-economics inflection as BCA Green Mark, NABERS, and LEED data interoperability enables portfolio-level performance benchmarking across institutional asset managers.
For Market Incumbents: Secure commissioning agent capacity in Tokyo, Sydney, and Singapore before talent scarcity forces wage inflation across verification services. Backward integration into low-carbon concrete supply hedges against 15-40% material premiums compressing margins on fixed-price contracts. Certification convergence between national schemes and international standards threatens competitive positioning for single-scheme specialists. For New Entrants and Emerging Players: Differentiate on AI-driven commissioning platforms that optimize building startup sequences, penetrating Japanese and Korean markets where precision energy targeting commands tenant premiums. Manila's aging office stock offers lowest penetration for performance contracting models tied to NABERS-equivalent ratings. Green bond financing access from Singapore and Hong Kong exchanges provides capital cost advantage for envelope performance threshold compliance. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across net-zero commercial retrofits as operational energy model pre-certification extends design timelines before revenue recognition. Acquisition targets should concentrate on integrated design-build platforms with captive engineering capabilities spanning MEP and envelope domains. Watch for NABERS disclosure mandate expansion beyond Australia as the signal indicating regional performance-based regulation adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Convergence Investment | Pursuing dual BCA Green Mark and LEED pathways secures multinational tenant requirements across Singapore financial districts. |
| Commissioning Agent Capacity Buildout | Tokyo and Sydney talent acquisition addresses scarcity constraining integrated MEP and envelope verification timelines. |
| Low-Carbon Material Backward Integration | In-house geopolymer concrete production hedges 15-40% cost premiums over conventional Portland cement. |
| AI-Driven Commissioning Platform Launch | Machine learning startup optimization penetrates Japanese markets where precision energy targeting commands rent premiums. |
| Green Bond Financing Access | Singapore and Hong Kong exchange certification-linked debt reduces capital costs for envelope performance thresholds. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with building developers, commissioning agents, sustainability consultants, and green bond issuers; and secondary validation through BCA Green Mark certification databases, NABERS rating disclosures, Green Star assessment records, and municipal construction permitting records. Bottom-up project pipeline aggregation across Jakarta, Bangkok, Ho Chi Minh City, Singapore, Sydney, Melbourne, Shanghai, Shenzhen, Tokyo, and Osaka triangulated against top-down macroeconomic indicators.
Across the analysis window, the forecasting framework modeled building type segmentation, technology adoption curves, material specification tiers, and certification scheme convergence patterns. CAGRs derived from historical permitting velocity, certified stock accumulation rates, and green financing issuance trajectories. Industry-specific inputs included MEE dual carbon compliance timeline enforcement patterns and METI procurement guideline adoption rates.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of operational energy disclosure would require recalibration. Forecasts reflect assumptions regarding certification scheme interoperability and low-carbon material cost curve trajectories. Practitioners should keep alternative scenarios live as grid infrastructure development pace and green bond market depth evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Green Coatings Market
Green Building Materials
Green Roof Market
Green Building Materials
Green Cement and Concrete Market
Green Building Materials
United States Green Cement Market
Green Building Materials
Sustainable and Green Building Materials Market
Green Building Materials
Artificial Green Wall Market
Green Building Materials
Solar Glass Market
Green Building Materials
Europe Green Cement Market
Green Building Materials
GCC Green Cement Market
Green Building Materials
Energy Efficient Window and Door Market
Green Building Materials
Green Rebar Market
Green Building Materials
Solar Frames Market
Green Building Materials
Sustainable Construction Market
Green Building Materials
Eco-Friendly Bitumen Market
Green Building Materials
Solar Windows Market
Green Building Materials
Global Green Walls Market