
 Green Roof Market | 2026-2036
Green Roof Market Size, Share, and Industry Trends Forecast 2026-2036
Green Roof Market Intelligence
Modular substrate engineering with integrated drainage membranes is reconfiguring installation economics for vegetated roofing assemblies. Bauder leverages vertically integrated waterproofing expertise to control specification channels across Northern Europe. ZinCo anchors its position through deep technical documentation of load-bearing profiles for intensive assemblies. LiveRoof competes via pre-cultivated modular trays that compress establishment timelines for commercial contractors.
Green roofs are engineered vegetative systems comprising growing media, drainage layers, root barriers, and waterproof membranes installed atop building structures to manage stormwater, reduce thermal loads, and extend membrane service life; typical extensive assemblies carry saturated loads of 60-150 kg per square meter with substrate depths of 60-200 millimeters. Extensive green roofs dominate volume due to lower structural requirements and minimal maintenance profiles for large commercial footprints. Intensive green roofs command premium specification in hospitality and institutional segments where amenity value and biodiversity targets justify higher capital outlay. Modular systems are gaining share in retrofit applications where crane access constraints favor prefabricated tray delivery.
Germany's FLL guideline framework shapes product testing and warranty terms across the European supply base, while EPA stormwater regulations and municipal green building codes in US cities drive specification in new commercial construction. REACH compliance on polymer components and growing state-level embodied carbon disclosure rules in California and New York are elevating material traceability requirements. Stakeholders must monitor how evolving energy code metrics treat vegetative surfaces as active thermal insulation layers versus passive accessories.
Market Dynamics
Municipal stormwater ordinances are tightening discharge limits for combined sewer systems, forcing commercial developers to specify vegetated roofing assemblies as active infrastructure rather than aesthetic amenities.
Growth Catalysts
- Combined Sewer Overflow Mandates:US cities with aging infrastructure must reduce untreated discharge volumes. Vegetated assemblies absorb first-flush rainfall, delaying peak flow into municipal treatment systems.
- FLL Guideline Harmonization:Germany's landscape development research society establishes testing protocols for substrate stability and root penetration resistance that warranty providers across Northern Europe now require.
- Polymer Membrane Extension:Vegetative coverage shields waterproofing layers from UV degradation and thermal cycling. Building owners in high-insolation climates specify extensive systems primarily for membrane lifecycle economics.
Market Restraints
- Structural Load Constraints:Saturated extensive assemblies add 100-150 kg per square meter. Older commercial stock in dense urban cores lacks the reserve capacity for retrofit without costly reinforcement.
- Substrate Supply Concentration:Engineered growing media with specified drainage coefficients ships from regional blending facilities. Remote project sites face freight cost penalties that erode system economics.
- Maintenance Skill Scarcity:Vegetated systems require seasonal irrigation management and weed suppression. Facility management contractors with horticultural expertise concentrate in affluent metropolitan markets.
Strategic Opportunities
- Biodiversity Credit Markets:Emerging habitat banking schemes in the United Kingdom assign quantified ecological value to pollinator-friendly planting palettes. Intensive assemblies with native species matrices qualify for offset generation.
- Cool Roof Convergence:Vegetative layers combined with reflective membranes address both urban heat island effects and building energy codes. Southern European markets with severe cooling loads show early specification traction.
- Modular Retrofit Channels:Pre-cultivated tray systems enable crane-limited installations on mid-rise commercial buildings. Distribution partnerships with roofing contractors bypass traditional landscape architecture channels.
Industry Challenges
- Leak Detection Complexity:Vegetative coverage obscures membrane integrity assessment. Infrared thermography and electronic field vector mapping require specialized technician certification that contractor networks lack.
- Establishment Period Risk:Substrate settlement and plant mortality during the first growing season create warranty disputes between waterproofing installers and vegetation contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Roof Market |
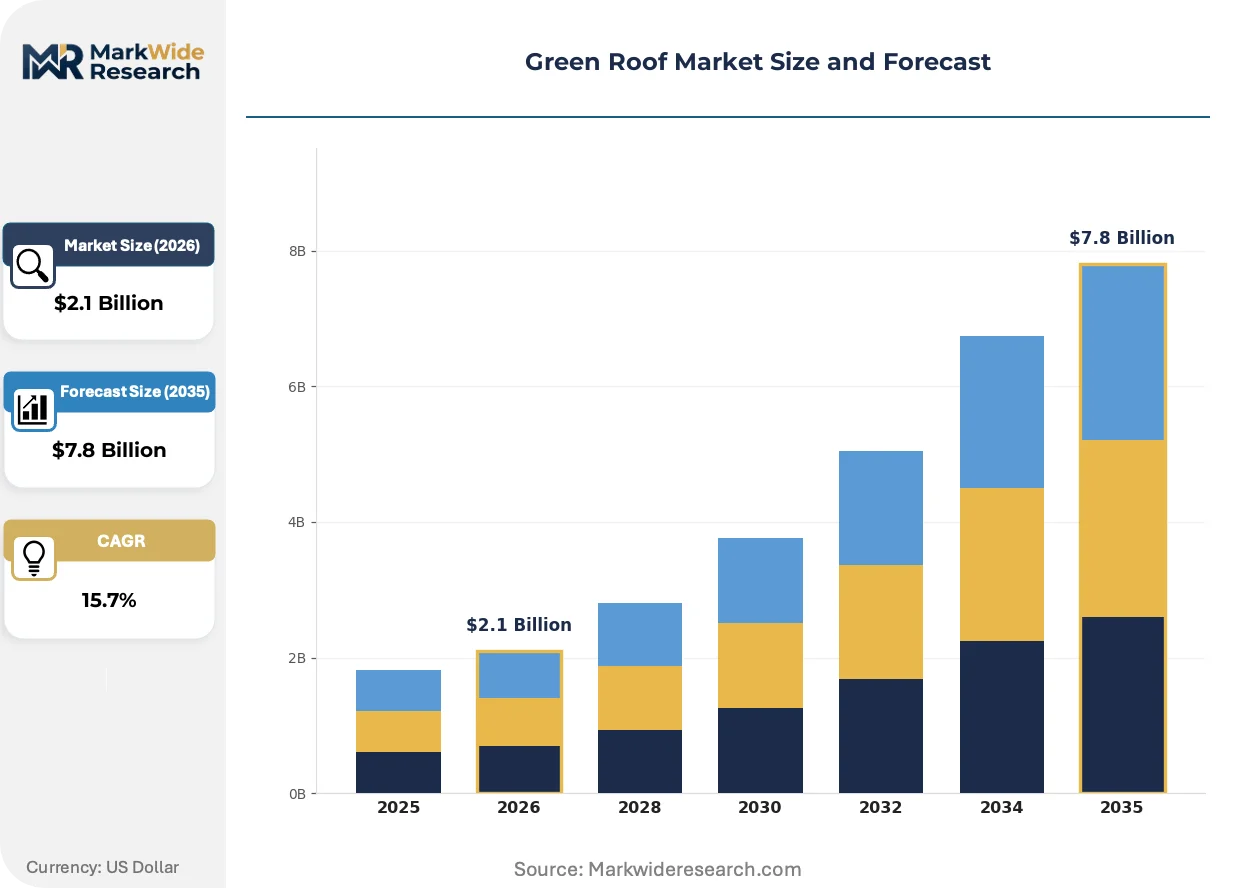
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.8 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Systems, Extensive Green Roofs, Semi-Intensive Green Roofs, Intensive Green Roofs Installation Method: Pre-vegetated Systems, Retrofit Systems, New Construction Systems, Tray Systems End User: Commercial Buildings, Residential Buildings, Educational Institutions, Hotels Vegetation Type: Sedum, Grasses, Wildflowers, Shrubs |
| Companies Covered | Green Roof Blocks, Tournesol Siteworks, Optigreen, Bauder, Xero Flor America, ZinCo, LiveRoof, Soprema, Sempergreen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Roof Market Strategic Shifts & Innovations
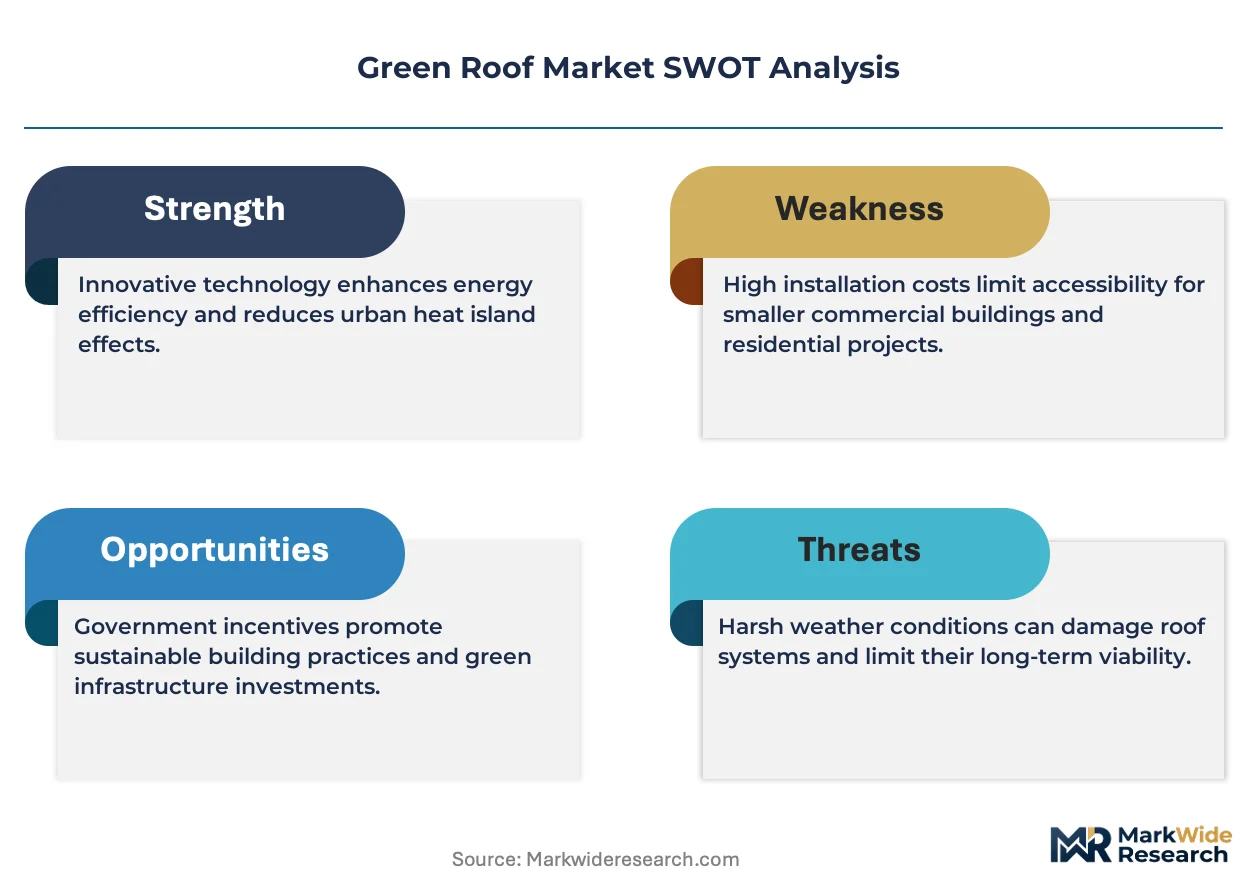
Substrate engineering and membrane chemistry are converging to compress installation timelines and extend performance warranties. Specification patterns increasingly treat vegetative assemblies as active building systems rather than applied finishes.
Mineral wool insulation is hybridizing with engineered growing media to create dual-function substrate boards. Commercial contractors in Scandinavia are adopting these composites for their simultaneous thermal performance and simplified detailing at parapet terminations. The technology is compressing the traditional separation between roofing and landscape trades, enabling single-source warranty structures that reduce owner risk allocation complexity.
REACH compliance documentation on polymer-modified bitumen membranes is reshaping specification eligibility across European commercial construction. ECHA substance restrictions on polycyclic aromatic hydrocarbons in waterproofing layers are forcing reformulation of root-barrier compounds. German and Dutch municipalities with green procurement mandates now require full material disclosure, favoring suppliers with vertically integrated polymer traceability.
Building owners are consolidating vegetative roofing decisions with broader envelope performance contracting. Energy service companies in North American urban cores now bundle vegetative installation with cool roof retrofits and photovoltaic mounting systems. This consolidated procurement pattern is most visible in Chicago and Toronto, where municipal energy disclosure ordinances create audit-driven replacement cycles.
Green Roof Market Segmentation
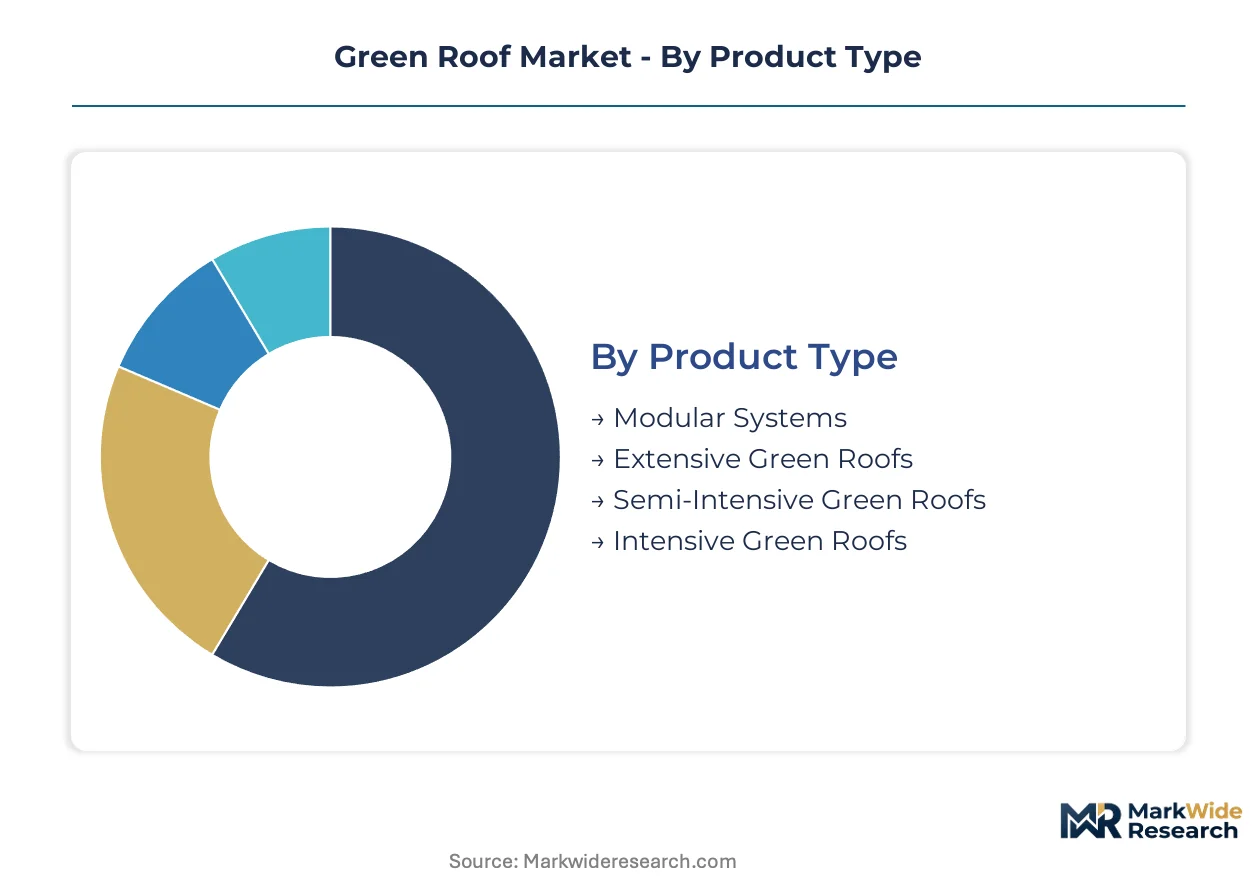
Vegetated roofing assemblies fragment across four structural dimensions that shape procurement economics and technical specification. Product architecture determines load-bearing requirements and warranty complexity. Installation method governs crane access needs and trade coordination intensity.
Product Type:
Cost tier separates the four product architectures, with capital outlay and structural demand scaling directly with substrate depth and plant diversity.
- Extensive Green Roofs:Lightweight assemblies carry 60-150 kg per square meter saturated load with shallow growing media of 60-200 millimeters. Commercial portfolios in German urban cores specify these systems under FLL guideline compliance to satisfy municipal stormwater retention mandates without structural reinforcement.
- Intensive Green Roofs:Deep substrate systems exceeding 200 millimeters support diverse vegetation including shrubs and small trees. Hospitality developers in Toronto and Chicago command premium specification here, leveraging amenity terraces and biodiversity targets to justify higher capital intensity and ongoing horticultural maintenance contracts.
- Modular Systems:Pre-cultivated tray configurations compress installation timelines for retrofit applications with crane constraints.
- Semi-Intensive Green Roofs:Intermediate depth profiles balance structural load with expanded planting palettes for institutional clients.
Extensive systems hold installed capacity across commercial portfolios. Intensive assemblies are rotating up the share rankings in hospitality-led urban regeneration projects.
Installation Method:
Application context—retrofit versus new construction—drives method selection, with access constraints and membrane condition dictating viable technical pathways.
- Tray Systems:Pre-configured modular units arrive site-ready with established vegetation, drainage layers, and root barriers integrated. Contractors in dense US urban cores with limited crane windows favor this method for mid-rise commercial retrofits where traditional built-in-place techniques face logistical barriers.
- New Construction Systems:Integrated waterproofing and vegetative specification proceeds concurrently with structural design. Scandinavian commercial developers specify these to capture single-source warranty coverage across envelope and landscape performance.
- Pre-vegetated Systems:Off-site cultivation accelerates establishment and reduces early-season mortality risk.
- Retrofit Systems:Specialized assemblies accommodate existing membrane conditions and structural reserve capacity limitations.
New construction systems dominate current specification volume. Tray configurations are expanding most quickly as municipal stormwater retrofit mandates accelerate across aging commercial stock.
End User:
Customer type concentrates demand across four verticals with divergent maintenance capabilities and amenity valuation.
- Commercial Buildings:Office and retail portfolios specify extensive systems primarily for stormwater compliance and membrane lifecycle extension. Portfolio owners in combined sewer overflow cities treat vegetative coverage as active infrastructure investment with quantified return through avoided detention tank construction.
- Educational Institutions:Campus sustainability targets and curriculum integration drive intensive system specification with native biodiversity matrices. UK universities qualify these assemblies for emerging habitat banking credit generation under pollinator-friendly planting protocols.
- Residential Buildings:High-rise multifamily developers in premium urban markets specify amenity terraces with intensive profiles.
- Hotels:Experience-driven hospitality operators leverage vegetative rooftops for guest-facing programming and thermal comfort differentiation.
Commercial buildings anchor current specification volume. Educational institutions are climbing the fastest as sustainability-linked procurement mandates expand across public sector construction.
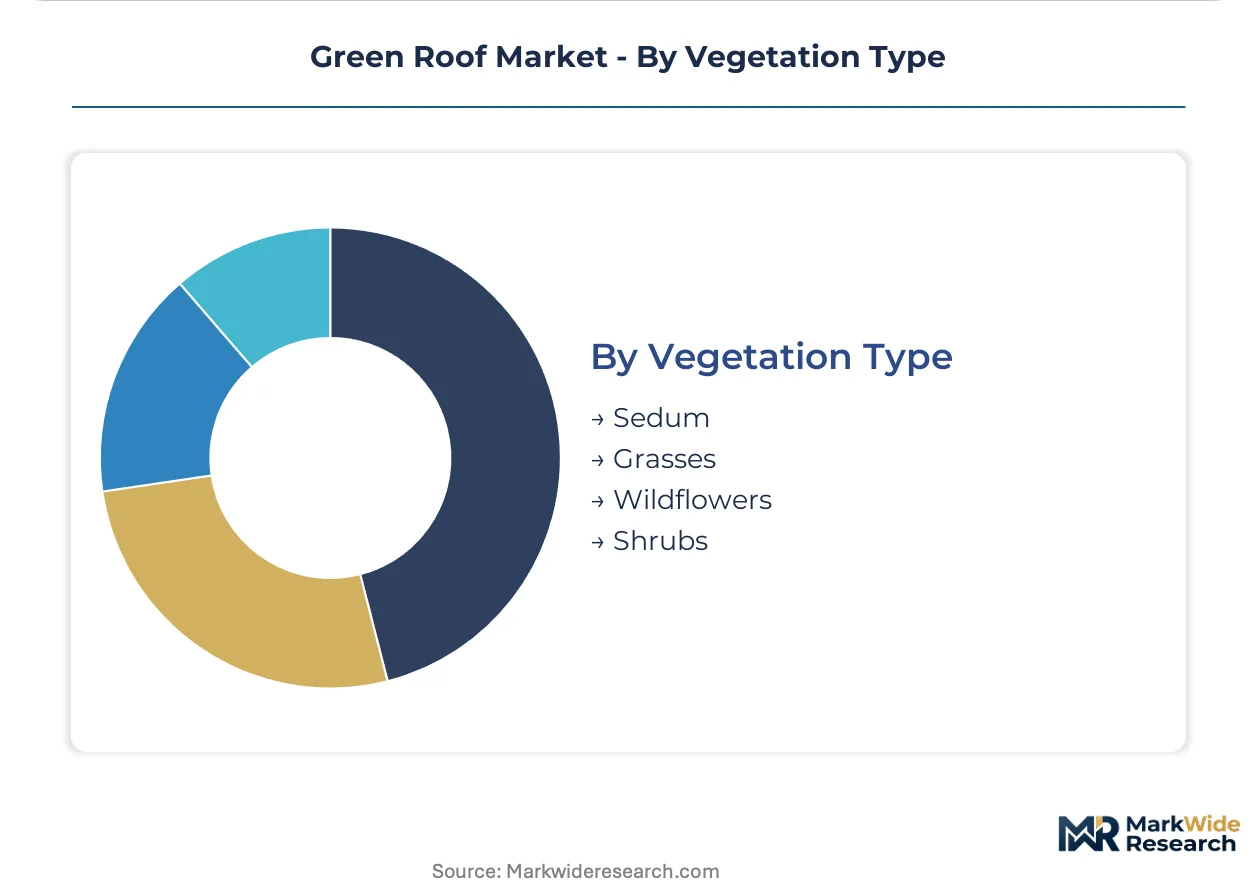
Vegetation Type:
Plant selection determines irrigation demand, establishment risk, and ecological service value delivered per square meter of coverage.
- Sedum:Succulent groundcover species dominate extensive system specification for drought tolerance and minimal substrate depth requirements. German FLL testing protocols certify specific cultivars for wind uplift resistance and substrate stability, creating specification lock-in for warranty-compliant installations.
- Wildflowers:Native pollinator matrices command premium positioning in intensive assemblies targeting biodiversity credit markets. UK habitat banking schemes assign quantified ecological value to these planting palettes, enabling offset generation for commercial developers.
- Grasses:Turf and meadow species suit semi-intensive profiles with moderate maintenance commitment.
- Shrubs:Woody vegetation requires deep substrate and structural load capacity, limiting deployment to intensive systems.
Sedum holds installed capacity across extensive commercial portfolios. Wildflower matrices are rotating up the share rankings as ecological valuation frameworks mature in European regulatory environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a substantial trade surplus in engineered green roof substrates and drainage components, while the United States and United Kingdom remain net importers of specialized waterproofing membranes and pre-cultivated vegetation systems. Export flows from German and Dutch manufacturing clusters supply Northern European retrofit mandates and North American commercial construction.
Germany
Municipal stormwater retention ordinances in Berlin and Hamburg drive specification of FLL-compliant extensive systems across commercial portfolios. The country's landscape development research society (FLL) mandates substrate stability testing that warranty providers across Northern Europe now require. Manufacturing concentration in Bavaria and North Rhine-Westphalia supplies pre-configured drainage boards to Dutch and Scandinavian contractors.
United States
Combined sewer overflow mandates in Chicago, Philadelphia, and Portland force commercial developers to specify vegetated assemblies as active infrastructure. EPA stormwater regulations tighten discharge limits for aging municipal systems. Specification activity clusters in the Great Lakes region and Pacific Northwest where municipal green building codes align with federal compliance timelines.
United Kingdom
Emerging habitat banking schemes assign quantified ecological value to pollinator-friendly intensive assemblies. London's urban heat island mitigation targets and biodiversity net gain requirements drive specification in commercial regeneration projects. Manufacturing and installation expertise concentrates in the Southeast and West Midlands, serving retrofit mandates across Greater Manchester and Birmingham.
Canada
Toronto's green roof bylaw mandates vegetative coverage on commercial buildings exceeding specified floor areas. Municipal stormwater charge systems in Vancouver and Montreal create direct cost avoidance incentives for portfolio owners. Technical documentation and substrate blending facilities cluster in Southern Ontario, supplying Quebec and Prairie province projects.
Netherlands
Rotterdam's water-sensitive urban design program treats vegetated roofing as critical flood resilience infrastructure. National building codes incorporate blue-green roof hybrid specifications for new commercial construction. Distribution and engineering services concentrate in the Randstad, exporting modular system components to Belgian and German border regions.
Green Roof Market Key Industry Players
On the supply side, the industry is moderately consolidated around waterproofing specialists with landscape engineering capabilities and modular system fabricators with regional cultivation networks. Three archetypes dominate competitive positioning: integrated envelope contractors controlling specification channels through single-source warranties, substrate engineering specialists with vertically integrated mineral processing, and modular tray suppliers compressing installation timelines through pre-cultivated delivery. Capacity expansion and distribution partnerships with roofing contractors represent the dominant competitive moves.
Among the waterproofing-integrated specialists, Bauder and Soprema occupy positions where membrane chemistry expertise anchors specification influence across Northern European commercial construction. ZinCo exemplifies the substrate engineering archetype through technical documentation dominance for load-bearing intensive assemblies. LiveRoof and Xero Flor America represent modular system positioning where pre-cultivated tray delivery addresses crane-constrained retrofit applications in dense US urban cores.
| Leading Market Players |
|---|
| Green Roof Blocks |
| Tournesol Siteworks |
| Optigreen |
| Bauder |
| Xero Flor America |
| ZinCo |
| LiveRoof |
| Soprema |
| Sempergreen |
| Others |
Cost & Logistics Intelligence
Bavarian substrate blending facilities anchor European supply capacity, with their kiln-dried mineral processing lines determining downstream pricing power for engineered growing media shipped to Dutch contractors and Scandinavian developers.
Pricing Analysis
Modular tray systems command premium positioning against built-in-place extensive assemblies, while pre-cultivated intensive configurations sit at the top tier. Three-tier pricing structure across premium, standard, and economy levels separates FLL-certified substrate blends from generic regional mixes and basic drainage board configurations. Cost compression in standard-tier extensive systems is intensifying because freight penalties from Bavaria erode margins for remote UK and US projects. Commercial portfolio owners exhibit highest price sensitivity, while hospitality developers seeking amenity terraces show lowest.
Supply Chain Analysis
Extended payment terms from German waterproofing specialists to Dutch distribution partners are stabilizing working capital for modular system fabricators. Supply concentrates in Germany, the Netherlands, and the United States for engineered substrates, polymer membranes, and pre-cultivated vegetation respectively. Raw material dependencies include expanded clay aggregates, bituminous root barriers, and sedum cuttings. Single-source vulnerability around FLL-certified substrate testing laboratories creates specification bottlenecks. Distribution runs through roofing contractor networks rather than traditional landscape architecture channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green roof markets reward service-attach strategies where multi-year horticultural maintenance contracts and membrane lifecycle warranty extensions expand faster than initial installation revenues.
For Market Incumbents: Pre-empt modular retrofit channels by acquiring regional cultivation facilities in Chicago and Toronto, where municipal stormwater mandates accelerate crane-constrained installations. Consolidate specification influence through single-source warranty coverage spanning waterproofing and vegetation performance. Invest in FLL guideline harmonization to lock out non-compliant substrate competitors from Northern European procurement. For New Entrants and Emerging Players: Pursue biodiversity credit generation services for UK educational institutions and London commercial regeneration projects, where emerging habitat banking schemes assign quantified ecological value. Target semi-intensive system specification in institutional segments with moderate structural capacity and expanded planting palette demands. Partner with energy service companies bundling vegetative installation with cool roof retrofits and photovoltaic mounting systems. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among modular tray suppliers with captive maintenance networks and substrate engineering specialists with vertically integrated mineral processing. Long-term viability favors acquisition targets controlling FLL-compliant testing documentation and regional cultivation capacity. Watch municipal green building code adoption velocity as the inflection indicator for retrofit mandate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Processing | Bavarian mineral processing lines secure FLL-compliant supply for Northern European warranty providers. |
| Modular Cultivation Facility Expansion | Pre-cultivated tray capacity in Chicago and Toronto addresses crane-constrained retrofit demand. |
| Single-Source Warranty Consolidation | Combined envelope and landscape coverage reduces owner risk allocation complexity in Scandinavian markets. |
| Biodiversity Credit Service Development | Pollinator-friendly planting protocols qualify UK intensive assemblies for emerging habitat banking schemes. |
| Cool Roof Convergence Partnership | Vegetative-reflective membrane bundles address urban heat island targets in Southern European cooling-load markets. |
Research Approach
Desk research of municipal stormwater ordinances, FLL guideline documentation, and EPA regulatory filings preceded structured interviews with waterproofing specification managers, commercial roofing contractors, landscape architecture principals, and facilities management directors. Primary fieldwork across Germany, the United Kingdom, and the United States validated substrate engineering claims and installation timeline assumptions. Secondary sources included customs records for engineered growing media trade flows, municipal green building code databases, and commercial construction permit filings. Bottom-up project pipeline analysis triangulated against top-down market sizing from envelope contractor revenue disclosures.
Assumptions held municipal stormwater mandate adoption schedules and FLL guideline harmonization timelines fixed, while varying commercial construction starts and retrofit incentive program funding across the analysis window. Segmentation modeling covered product architecture, installation method, end-user vertical, and vegetation type dimensions. CAGRs derived from logistic diffusion curves fitted to historical specification penetration rates. Industry-specific inputs included combined sewer overflow compliance deadlines and embodied carbon disclosure rule adoption trajectories in California and New York.
Macroeconomic conditions sit as an overlay; deviation in commercial real estate investment cycles or municipal infrastructure funding priorities would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and substrate freight cost stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Outdoor Flooring Market
Green Building Materials
Green Silica Market
Green Building Materials
Sustainable and Green Building Materials Market
Green Building Materials
United States Green Cement Market
Green Building Materials
Green Waterproofing Products Market
Green Building Materials
APAC Green Buildings Market
Green Building Materials
Green Cement and Concrete Market
Green Building Materials
Solar Windows Market
Green Building Materials
Solar Glass Market
Green Building Materials
China Green Building Materials Market
Green Building Materials
Green Rebar Market
Green Building Materials
Global Eco-Friendly Green Roofs Market
Green Building Materials
Green Cement Market
Green Building Materials
Green Coatings Market
Green Building Materials
Eco-Friendly Bitumen Market
Green Building Materials
Non-Residential Green Building Market