
 Global Green Walls Market | 2026-2036
Global Green Walls Market Size, Share, and Industry Trends Forecast 2026-2036
Global Green Walls Market Analysis
Market Context
The capital-intensity divergence between integrated system providers and modular assemblers is redrawing competitive boundaries across the green walls sector. Sempergreen leverages its captive nursery network and installation crews to control margin pools from substrate through maintenance. GSky Plant Systems anchors North American commercial contracts through prefabricated panel standardization that reduces on-site labor hours. Naava Inc. differentiates via automated irrigation and air-quality monitoring hardware embedded in its biowall units.
Technical Definition and Segment Structure
Green walls are vertical assemblies of living plants integrated with engineered growing media, irrigation infrastructure, and structural support systems designed to provide thermal insulation, stormwater retention, and biophilic interior environments. Modular systems dominate current installation volume due to faster deployment timelines and lower specialist labor requirements, while biowalls capture premium pricing through integrated air-filtration functionality. The residential application segment shows structural acceleration as prefabricated panel costs decline, though commercial projects still occupy the largest absolute margin pool due to scale economies in maintenance contracts.
Regulatory Frame and Outlook
The EU Green Deal and F-Gas Regulation shape product specifications across European projects, while the EPA's stormwater management guidelines influence substrate and drainage design in United States installations. China's dual carbon goals and MEE building efficiency standards are opening municipal procurement channels for vertical garden systems in tier-one cities. Stakeholders must monitor how evolving green building certification thresholds in multiple jurisdictions alter the specification power of architects relative to contractors.
Market Dynamics
The EU Green Deal's building retrofit mandates are compressing installation timelines and forcing substrate suppliers to certify thermal performance metrics ahead of specification lock-in by major commercial developers.
Growth Catalysts
- EU Green Deal retrofit obligations:Germany's municipal greening ordinances now mandate living wall integration for commercial building renovations exceeding 1,000 square meters.
- Stormwater retention infrastructure:EPA guidelines in the United States require permeable surface ratios that green walls satisfy more cost-effectively than subsurface systems in dense urban cores.
- Biophilic certification premiums:WELL Building Standard and LEED v4.1 award density bonuses that translate directly to rent escalators in Class A office portfolios.
Market Restraints
- Substrate material cost volatility:Expanded clay aggregate and coconut coir prices fluctuate with agricultural commodity indices and freight rates from Southeast Asian processing centers.
- Specialized installation labor scarcity:Certified living wall technicians concentrate in Amsterdam, Berlin, and Singapore, creating 12-16 week lead times for projects outside these hubs.
- Irrigation system technical limitations:Recirculating hydroponic setups face mineral buildup and root-zone oxygenation failures in hard-water municipalities without pretreatment infrastructure.
Strategic Opportunities
- India's tier-one municipal procurement:Smart city missions in Mumbai, Bengaluru, and Delhi mandate vertical gardens for transit-oriented development air quality mitigation.
- Healthcare biowall integration:Hospital HVAC retrofits in Japan and South Korea specify Naava-style air-filtration units to reduce particulate loads in surgical wards and oncology floors.
- Residential prefabrication channels:Direct-to-developer panel sales bypass traditional landscape architecture specification gates in multifamily construction across Australia and Canada.
Industry Challenges
- Horticultural maintenance skill gaps:Building facility managers lack training in integrated pest management and seasonal plant rotation protocols, causing warranty disputes with system providers.
- Fire safety certification timelines:EN 13501-1 and ASTM E84 testing cycles extend 8-14 months for novel substrate-plant combinations, delaying project approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Green Walls Market |
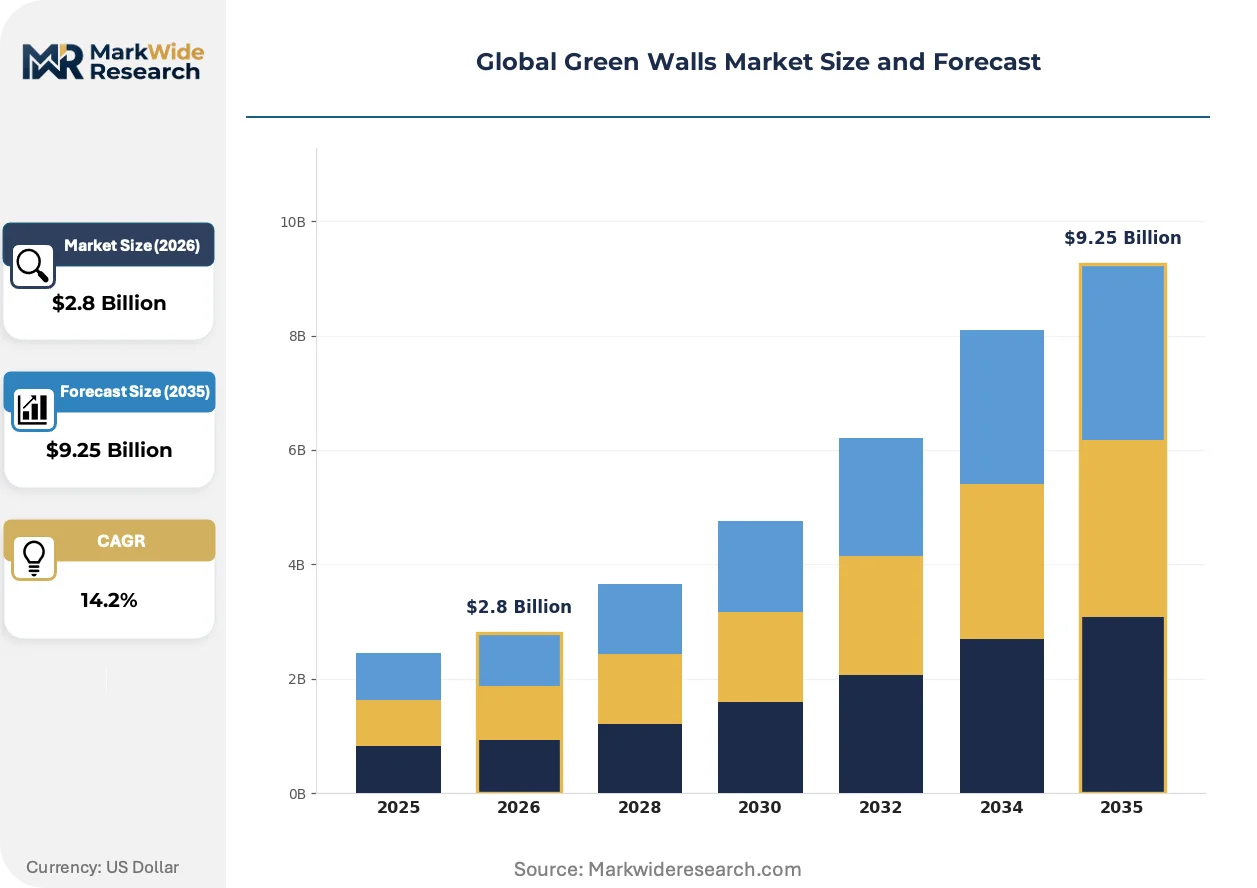
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.25 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetated Panels, Modular Systems, Trellis Systems, Biowalls Application: Residential, Commercial, Institutional, Urban Planning Installation Type: Indoor, Outdoor, Vertical Gardens, Hybrid Systems Maintenance Type: Regular Maintenance, Remedial Maintenance, Automated Systems, Manual Services |
| Companies Covered | Mobilane, Vertiko GmbH, Sempergreen, SageGreenLife, Ecotelhado, GSky Plant Systems, Naava Inc., Ginkgo Sustainability Inc., Green Fortune, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Green Walls Market Emerging Trajectories
Active experimentation with substrate chemistry and sensor-embedded irrigation is compressing the gap between modular system providers and integrated biowall specialists. Three developments merit close tracking.
Sensor-integrated growing media is fragmenting the traditional split between hardware suppliers and horticultural service providers. Large commercial landlords in London and New York now demand real-time moisture, nutrient, and root-health telemetry as a contract precondition. This capability compression forces modular panel manufacturers to either develop proprietary IoT stacks or cede margin to third-party analytics platforms.
REACH substance restrictions and the EU F-Gas Regulation are phasing out certain synthetic rooting hormones and refrigerant-based climate control in enclosed biowall systems. Manufacturers serving European projects must reformulate substrate binders and shift to water-loop thermal management. German specification architects now exclude products lacking EPD certification from shortlists for public-sector contracts.
Subscription-based maintenance contracts are displacing lump-sum warranty structures in commercial real estate procurement. Asset managers in Singapore and Sydney prefer per-square-meter monthly fees covering plant replacement, irrigation servicing, and performance guarantees. This preference shift compresses upfront project margins while extending customer lifetime value for vertically integrated providers with captive nursery networks.
Global Green Walls Market Segmentation
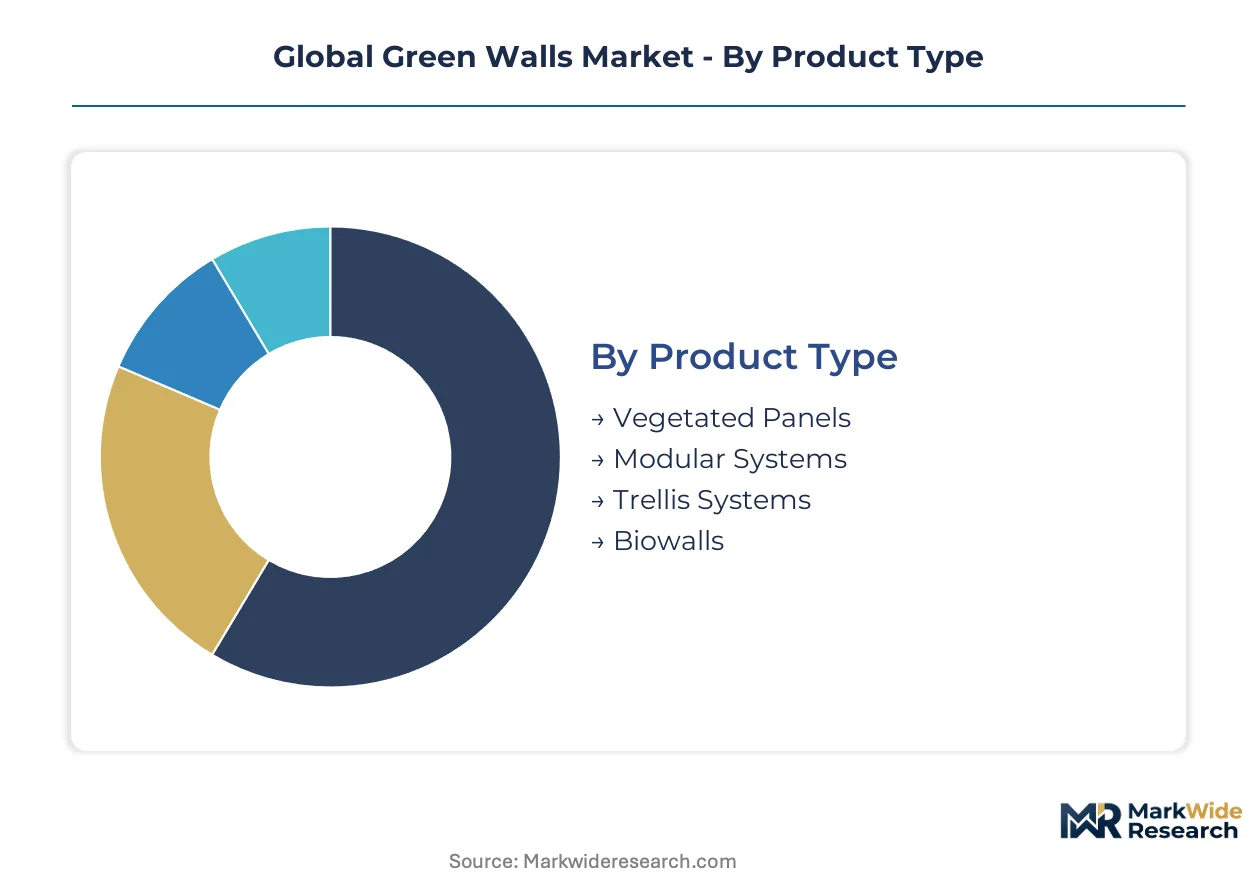
Green walls manufacturers configure product portfolios around installation complexity and ongoing service obligations. Segment boundaries blur as modular hardware providers add maintenance subscriptions and biowall specialists expand into standardized panel formats.
Product Type:
Modular systems dominate export markets due to containerized shipping efficiency, while vegetated panels and biowalls concentrate in domestic European supply chains with captive nursery networks.
- Vegetated Panels:Pre-grown plant mats bonded to flexible backing substrates enable rapid deployment on irregular facades. German municipal retrofit ordinances specify these for heritage building integrations where structural load limits prohibit rigid assemblies.
- Modular Systems:Interchangeable cassette-based designs with standardized dimensions reduce on-site labor hours. Singapore and Sydney commercial developers favor these for 12-16 week installation timelines that satisfy lease commencement deadlines.
- Trellis Systems:Climbing-plant frameworks with integrated irrigation for exterior facade coverage. Australian residential builders specify these for cost-sensitive multifamily projects.
- Biowalls:Active air-filtration units with embedded sensors and hydroponic root zones. Japanese hospital HVAC retrofits drive specification for surgical ward particulate reduction.
Modular systems hold the largest share; momentum sits with biowalls.
Application:
Commercial projects generate the highest absolute margins through scale economies in maintenance contracting, while residential applications show the steepest expansion trajectory as prefabricated panel costs decline.
- Residential:Balcony-integrated and interior partition installations in multifamily construction. Direct-to-developer panel sales in Canada and Australia bypass traditional landscape architecture specification gates.
- Commercial:Class A office portfolios leverage WELL Building Standard and LEED v4.1 density bonuses for rent escalators. London and New York asset managers now demand real-time moisture telemetry as contract precondition.
- Institutional:Healthcare, education, and government facilities with extended ownership horizons. South Korean oncology floors specify Naava-style air-filtration for particulate load management.
- Urban Planning:Transit-oriented development mandates in Mumbai, Bengaluru, and Delhi require vertical gardens for air quality mitigation under smart city missions.
Commercial applications anchor current revenue; residential is gaining share fastest.
Installation Type:
Indoor installations concentrate in high-labor-cost markets where automated irrigation justifies premium hardware expenditure, while outdoor systems dominate volume in climate zones with reliable precipitation patterns.
- Indoor:Climate-controlled environments with supplemental lighting and HVAC integration. New York and London landlords specify these for biophilic certification premiums.
- Outdoor:Rain-fed or minimally irrigated facade systems with weather-resistant substrates. German commercial retrofits under EU Green Deal mandates drive specification.
- Vertical Gardens:Freestanding or attached assemblies with integrated structural support. Singapore municipal procurement favors these for dense urban core stormwater retention.
- Hybrid Systems:Configurable indoor-outdoor transitions with seasonal plant rotation protocols. Sydney asset managers prefer these for subscription-based maintenance contracts.
Outdoor systems command volume leadership; hybrid configurations show strongest pricing power.
Maintenance Type:
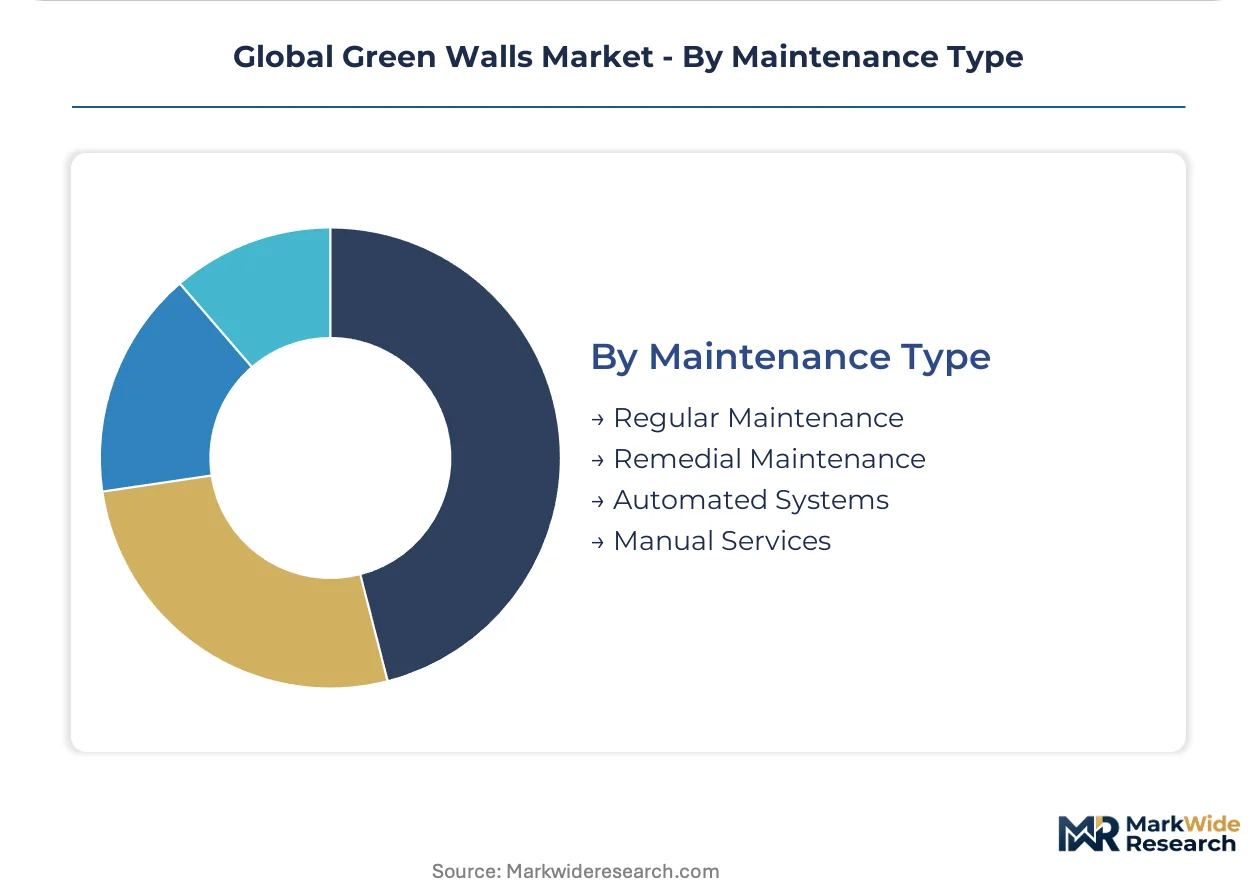
Subscription-based service models are displacing lump-sum warranties in premium commercial markets, while manual services retain dominance in cost-sensitive residential segments.
- Regular Maintenance:Scheduled plant replacement, irrigation servicing, and nutrient monitoring. Singapore and Sydney per-square-meter monthly fees extend customer lifetime value for integrated providers.
- Remedial Maintenance:Reactive interventions for system failures, pest infestations, or plant mortality. Building facility managers lacking horticultural training generate warranty disputes with system providers.
- Automated Systems:Sensor-embedded growing media with IoT-enabled moisture, nutrient, and root-health telemetry. Large London commercial landlords demand these as contract precondition.
- Manual Services:Technician-dependent plant care without integrated monitoring hardware. Concentrates in markets outside Amsterdam, Berlin, and Singapore technician hubs.
Regular maintenance captures the largest contract value; automated systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany exceeds that in India by a factor of three, reflecting divergent regulatory enforcement and labor cost structures. Municipal retrofit mandates in Frankfurt and Berlin compress installation timelines while elevating specification standards. Singapore and Sydney command intermediate premiums through subscription-based maintenance contracting.
Germany
Frankfurt commercial developers face municipal greening ordinances mandating living wall integration for renovations exceeding 1,000 square meters. The EU Green Deal and F-Gas Regulation shape substrate binder formulations and thermal performance certification requirements. Berlin's heritage building retrofit cluster specifies vegetated panels where structural load limits prohibit rigid assemblies.
United States
Class A office portfolios in New York and Chicago leverage WELL Building Standard and LEED v4.1 density bonuses for rent escalators. EPA stormwater management guidelines require permeable surface ratios that green walls satisfy more cost-effectively than subsurface systems. Manhattan asset managers now demand real-time moisture telemetry as a contract precondition for new installations.
Singapore
Municipal procurement for transit-oriented development mandates vertical gardens for dense urban core stormwater retention. The country's building efficiency standards and smart city mission create specification channels for modular systems with 12-16 week installation timelines. Commercial developers in the central business district favor subscription-based maintenance contracts over lump-sum warranties.
Japan
Hospital HVAC retrofits in Tokyo and Osaka specify biowall units for particulate reduction in surgical wards and oncology floors. METI building efficiency standards and healthcare facility modernization programs drive specification of active air-filtration systems. The Kanto region's integrated design-build firms concentrate certified living wall technician capacity.
Australia
Residential prefabrication channels in Sydney and Melbourne bypass traditional landscape architecture specification gates through direct-to-developer panel sales. Building codes in New South Wales and Victoria increasingly reference biophilic design guidelines for multifamily construction. Sydney asset managers prefer hybrid indoor-outdoor configurations with seasonal plant rotation protocols under monthly fee structures.
Global Green Walls Market Vendor Landscape
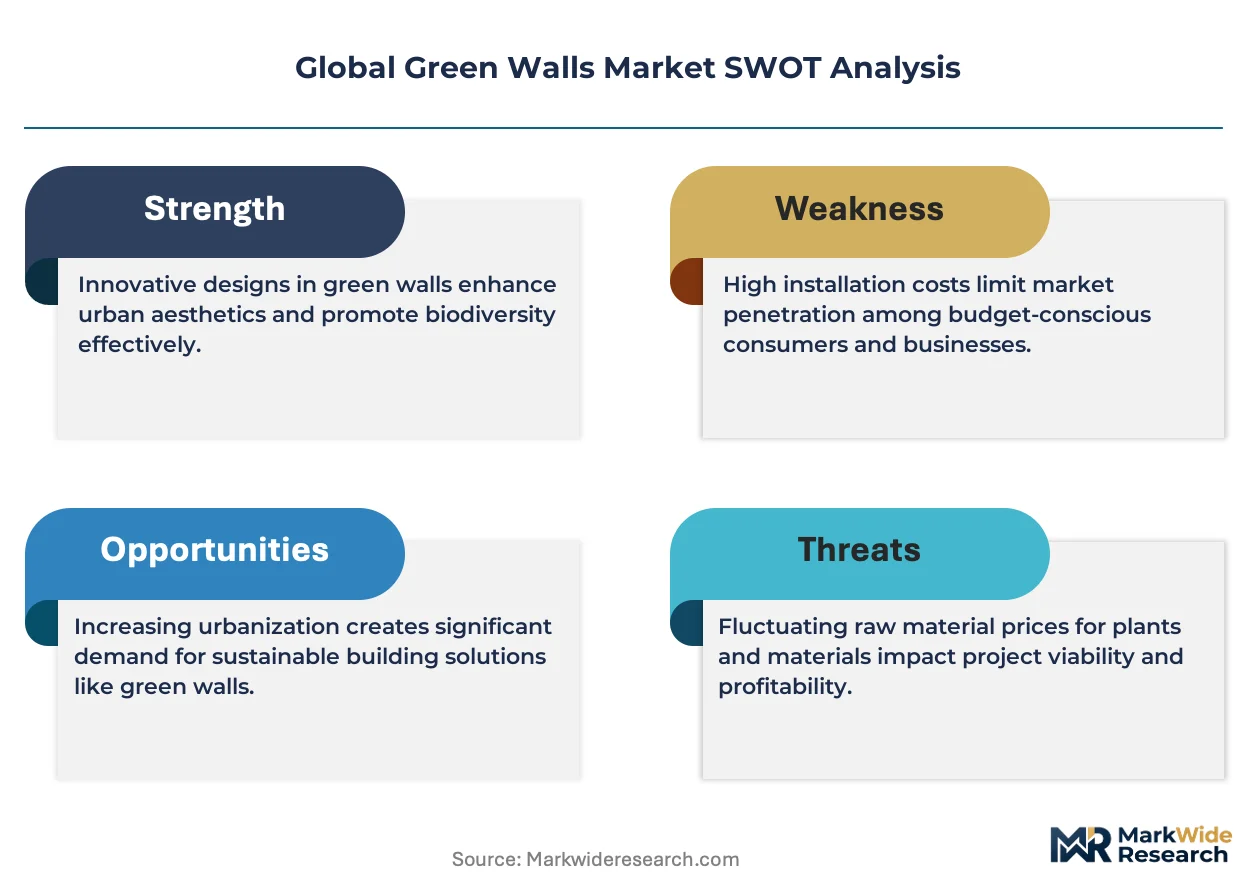
Concentration sits with integrated system providers controlling captive nursery networks and installation crews. The vendor base spans three strategic tiers: modular hardware manufacturers, biowall specialists with embedded sensor technology, and horticultural service providers expanding into panel fabrication. Competitive moves center on backward integration into substrate supply and geographic expansion through specification relationships with commercial real estate developers.
Among European integrated providers, Sempergreen and Vertiko GmbH exemplify the captive nursery archetype, while Naava Inc. represents the biowall specialist tier with embedded air-filtration hardware. GSky Plant Systems anchors North American commercial contracting through prefabricated panel standardization. SageGreenLife occupies a position bridging modular installation efficiency with horticultural maintenance expertise.
| Leading Market Players |
|---|
| Mobilane |
| Vertiko GmbH |
| Sempergreen |
| SageGreenLife |
| Ecotelhado |
| GSky Plant Systems |
| Naava Inc. |
| Ginkgo Sustainability Inc. |
| Green Fortune |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at captive nursery networks in the Netherlands and Germany sets price floors across substrate-integrated systems, compressing margins for modular assemblers lacking upstream biomass control while elevating premium capture for biowall specialists with automated irrigation hardware.
Pricing Analysis
The customization-premium spread separates configured-to-order vegetated panels from standardized modular cassettes, with heritage retrofit specifications in Berlin commanding substantial premiums over Sydney commercial lease-driven installations. Subscription-based maintenance contracts now dominate Class A office procurement, displacing lump-sum warranties and extending customer lifetime value for integrated providers. Price differentiation rests on EPD certification status and real-time telemetry integration, with Singapore asset managers least sensitive to per-square-meter fees and Australian residential developers most responsive to panel unit economics.
Supply Chain Analysis
Inbound logistics costs from Southeast Asian coconut coir processing centers through Rotterdam and Hamburg ports constrain substrate supplier margins, particularly for expanded clay aggregate blends dependent on containerized bulk shipping. Manufacturing concentration clusters in the Netherlands, Germany, and Singapore, with raw material feeds drawing from Indonesian palm fiber processors and German mineral wool producers. Single-source vulnerability concentrates in certified living wall technician pools centered on Amsterdam, Berlin, and Singapore, creating specification bottlenecks for projects outside these hubs. Distribution runs through specification relationships with commercial real estate developers and direct-to-developer channels in residential prefabrication markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Class A office asset managers in London, New York, and Singapore who now mandate real-time telemetry and subscription maintenance as contract preconditions, fragmenting procurement authority away from traditional landscape architecture specification gates.
For Market Incumbents: Shield margin pools by deepening captive nursery network coverage and securing EPD certification ahead of EU Green Deal enforcement tightening. The priority defensive move anchors subscription-based maintenance contracts with telemetry integration, countering modular hardware competitors lacking horticultural service infrastructure. Backward integration into substrate binder formulation mitigates REACH substance restriction compliance costs. For New Entrants and Emerging Players: Certification fast-track through EN 13501-1 fire safety testing opens procurement channels in German municipal retrofit ordinances where heritage building load limits favor vegetated panel configurations. White-space concentration sits with India's tier-one smart city missions and Japanese hospital HVAC retrofit specifications for biowall air-filtration units. A direct-to-developer go-to-market angle bypasses saturated specification relationships in established commercial real estate markets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated providers with captive nursery networks and sensor-embedded hardware capabilities over pure-play modular manufacturers facing telemetry margin compression. Long-term viability across the projection horizon hinges on maintenance contract recurring revenue density and geographic technician hub control. The inflection signal to monitor is subscription-based contract penetration rates in Singapore and Sydney relative to lump-sum warranty retention.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Nursery Network Expansion | Sempergreen-style upstream biomass control secures substrate margin pools and maintenance contract density. |
| Sensor-Embedded Panel Development | Real-time moisture telemetry satisfies London and New York asset manager contract preconditions. |
| EPD Certification Investment | German public-sector procurement exclusion risk elevates environmental product declaration to table stakes. |
| Subscription Maintenance Scaling | Per-square-meter monthly fees extend customer lifetime value and compress competitor upfront pricing power. |
| Fire Safety Testing Acceleration | EN 13501-1 and ASTM E84 certification timelines determine project approval velocity in regulated markets. |
Methodological Framework
The analysis maps modular systems, vegetated panels, biowalls, and trellis configurations, each validated through facility managers at Class A office portfolios, procurement leads at commercial real estate developers, certified living wall technicians, and specification architects at heritage retrofit practices. Primary interview findings triangulate against EU Green Deal regulatory filings, EPA stormwater management guidelines, WELL Building Standard certification databases, and municipal procurement records from Mumbai, Singapore, and Sydney. Secondary sources include customs data on expanded clay aggregate and coconut coir trade flows, SEC filings from integrated building material suppliers, and project development databases tracking installation timelines. Bottom-up segment sizing reconciles with top-down market boundary checks.
Consistency validation against external benchmarks ensures volume and value outputs align with disclosed maintenance contract values and panel shipment records across the analysis window. The analytical framework models product type, application, installation complexity, and service obligation dimensions. CAGRs derive from segment-level growth rate synthesis with cross-validation against regulatory mandate implementation schedules and commercial real estate development pipelines. Forecast inputs incorporate technician hub capacity constraints and substrate material cost index trajectories.
Underlying assumptions cover EU Green Deal retrofit obligation enforcement timelines and EPA guideline permanence, with deviation risk concentrated in fire safety certification delays and Southeast Asian agricultural commodity price volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
North America Green Buildings Market
Green Building Materials
Green Building Market
Green Building Materials
Green Waterproofing Products Market
Green Building Materials
Global Eco-Friendly Green Roofs Market
Green Building Materials
Solar Windows Market
Green Building Materials
Green Cement and Concrete Market
Green Building Materials
Green Roof Market
Green Building Materials
Green Rebar Market
Green Building Materials
Energy Efficient Window and Door Market
Green Building Materials
Sustainable Construction Market
Green Building Materials
Green Cement Market
Green Building Materials
Eco Flooring Market
Green Building Materials
Outdoor Flooring Market
Green Building Materials
Green Concrete Market
Green Building Materials
Green Building Materials Market
Green Building Materials
Asia Pacific Green Cement Market