
 Eco-Friendly Bitumen Market | 2026-2036
Eco-Friendly Bitumen Market Size, Share, and Industry Trends Forecast 2026-2036
Eco-Friendly Bitumen Market Insights
India's expanding refinery-to-road infrastructure pipeline is reshaping competitive dynamics across Asia-Pacific. Bharat Petroleum leverages its integrated downstream network to secure feedstock access for polymer modified grades. Agarwal Industrial Corporation dominates western India through specialized blending facilities near Gujarat's industrial corridor. Jalnidhi Bitumen Specialties differentiates via technical service partnerships with state public works departments.
Eco-friendly bitumen comprises petroleum-derived binder modified with bio-based feedstocks, recycled polymers, or sulfur extenders to reduce production temperatures below conventional hot-mix thresholds of 150–190°C while maintaining penetration grades of 60–70 or 80–100 per ASTM D946. Its primary purpose centers on cutting energy consumption and CO2 emissions during asphalt pavement manufacturing without sacrificing Marshall stability or rutting resistance. Bio-bitumen leads product type revenue due to compatibility with existing hot-mix plants and recognition under green procurement frameworks, while warm mix technology captures the fastest technology adoption as contractors face tightening carbon disclosure requirements. Road construction anchors application demand through national highway programs, though roofing solutions yield superior margins due to specification premiums for UV-resistant modified membranes.
The EU Green Deal and F-Gas Regulation pressure European contractors to document lifecycle emissions across pavement projects, while India's BIS certification mandates performance testing for polymer modified binders in national highway contracts. The US EPA tailpipe and industrial emission standards indirectly steer state departments of transportation toward warm-mix specifications through federal infrastructure funding conditions. Stakeholders must monitor how regulatory carbon accounting expands from production-phase to full pavement lifecycle assessments, as this boundary shift will determine which modification technologies qualify for green procurement preference.
Market Dynamics
Warm-mix bitumen technology is compressing the cost-emissions tradeoff that previously forced contractors to choose between compliance and margins, as production temperature reductions of 30–40°C now align with both EU carbon thresholds and project profitability targets.
Growth Catalysts
- EU Green Deal carbon thresholds:Public infrastructure tenders across Germany, France, and the Netherlands now mandate documented lifecycle emissions, accelerating warm-mix procurement by road construction agencies seeking contract eligibility.
- India's PLI scheme for construction chemicals:Domestic manufacturers receive production-linked incentives for bio-bitumen output, reducing import dependence for national highway programs.
- Recycled polymer feedstock availability:Post-consumer plastic waste streams in Southeast Asia are stabilizing input costs for modified binder producers serving municipal road contracts.
Market Restraints
- Crude-linked base bitumen volatility:Refinery output fluctuations in the Middle East transmit directly to binder input costs, compressing blending margins for specialty grade producers.
- Technical performance validation gaps:Bio-based formulations lack standardized 10-year pavement performance datasets, slowing specification approval by conservative state public works departments.
- REACH registration burdens:Novel bio-additives face multi-year substance evaluation timelines at ECHA, delaying European market entry for innovative modification chemistries.
Strategic Opportunities
- Rooftop solar integration:UV-resistant modified bitumen membranes for commercial building-integrated photovoltaics command specification premiums in Germany's renewable construction sector.
- US federal infrastructure funding conditions:EPA industrial emission standards embedded in IIJA disbursement rules steer state DOTs toward warm-mix specifications for interstate rehabilitation contracts.
- Sulfur extender technology convergence:Refinery byproduct utilization is hybridizing with conventional polymer modification, creating cost-competitive pathways for high-rutting-resistance binders in tropical climates.
Industry Challenges
- Marshall stability testing expertise shortage:Laboratory technicians trained in conventional hot-mix protocols require recertification for warm-mix performance validation, extending project qualification timelines.
- Legacy plant retrofit capex:Foam bitumen injection systems and additive dosing equipment demand capital outlays that strain contractor balance sheets in price-competitive municipal bidding environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eco-Friendly Bitumen Market |
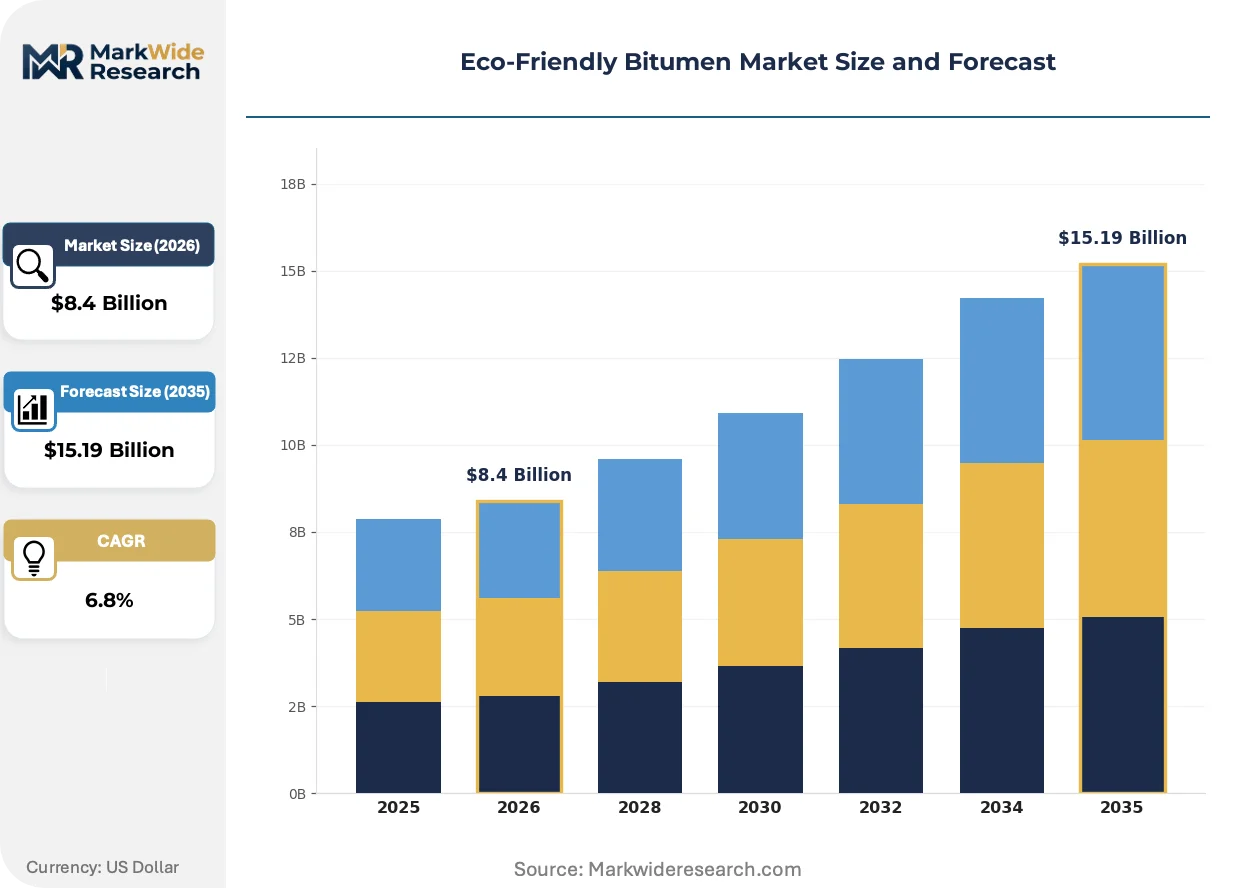
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bio-Bitumen, Polymer Modified Bitumen, Rubberized Bitumen, Sulfur-Extended Bitumen Technology: Warm Mix Technology, Cold Mix Technology, Foamed Bitumen, Hot Mix Technology Application: Road Construction, Airport Runways, Parking Lots, Roofing Solutions End User: Government Agencies, Road Contractors, Construction Firms, Infrastructure Developers |
| Companies Covered | Cosmique, Gilsonite, Agarwal Industrial Corporation, Mamz Asphalt Technologies, Jalnidhi Bitumen Specialties, Avello Bioenergy, Eagle Petrochem, Nikan West Gilsonite, Bharat Petroleum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eco-Friendly Bitumen Market Trends and Innovations
Modification chemistry is converging with carbon accounting infrastructure, as binder producers invest in blockchain-tracked feedstock provenance to satisfy emerging procurement disclosure requirements.
Low-temperature rheology enhancement through bio-oil derived from lignocellulosic waste is hybridizing with conventional styrene-butadiene-styrene modification, enabling German contractors to meet F-Gas Regulation thresholds without sacrificing high-temperature grade performance. State road agencies in Bavaria and Baden-Württemberg have accelerated pilot specifications for these hybrid binders following successful Autobahn trial sections.
CSRD corporate sustainability reporting mandates are forcing construction material suppliers to document Scope 3 emissions across their value chains, with bitumen blenders now required to obtain certified carbon intensity data from refinery feedstock providers. French and Italian infrastructure consortia have responded by consolidating procurement around suppliers with verified Environmental Product Declarations.
Specification-driven supplier consolidation is compressing the vendor base for national highway contracts, as India's BIS certification mandates for polymer modified binders disqualify unregistered blenders from central government-funded projects. State public works departments in Maharashtra and Tamil Nadu have narrowed approved vendor lists to fewer than six certified suppliers, shifting competitive dynamics toward technical service capabilities rather than price alone.
Eco-Friendly Bitumen Market Segmentation
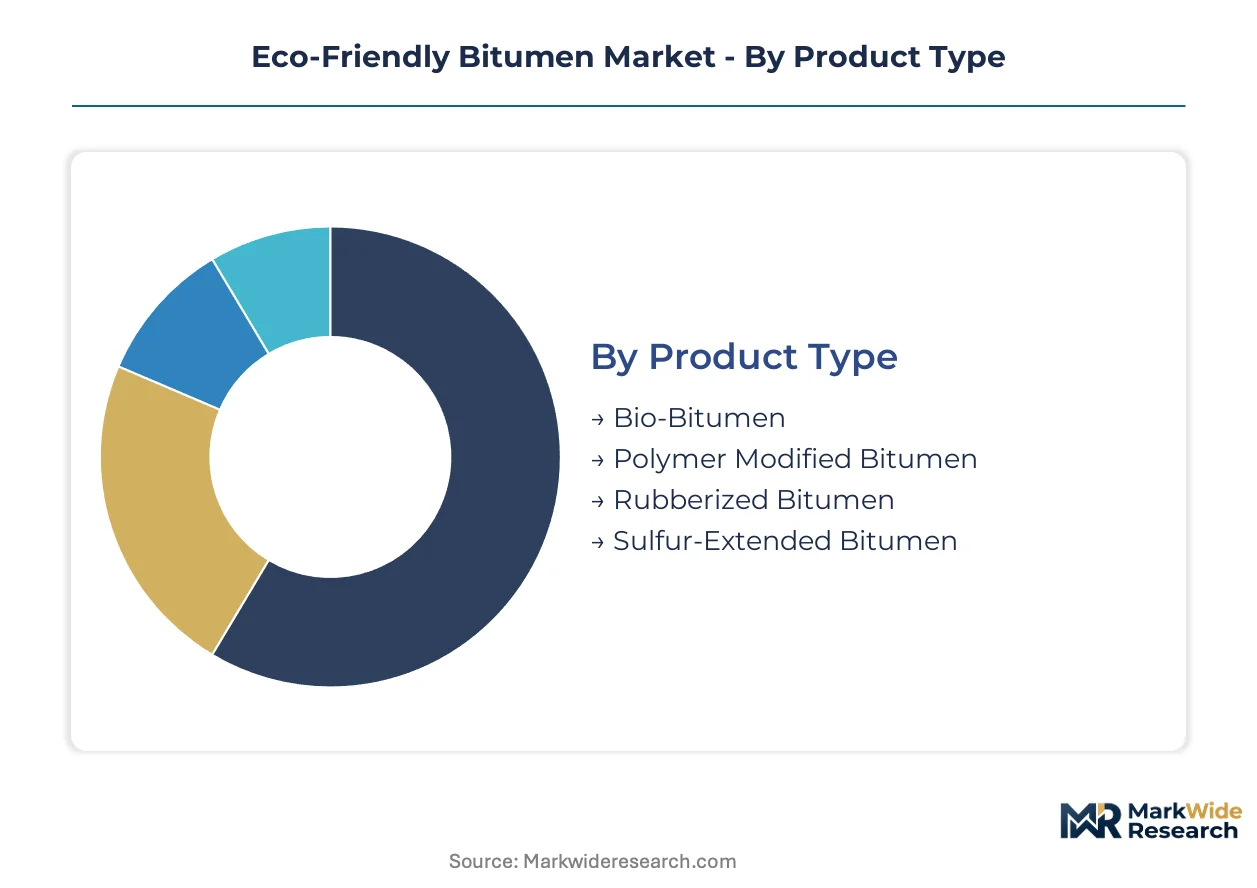
Eco-friendly bitumen markets fragment across modification chemistry, production temperature regimes, and specification intensity. Each dimension carries distinct margin profiles and regulatory exposure that determine competitive positioning.
Product Type:
Cost tier differentiation separates commodity-compatible formulations from premium performance grades requiring specialized feedstock security.
- Bio-Bitumen:Petroleum-derived binder modified with lignocellulosic or agricultural waste feedstocks, compatible with standard hot-mix plant infrastructure. Procurement concentrates in Germany where EU Green Deal tender thresholds mandate documented carbon intensity, and in India where PLI scheme incentives reduce domestic production costs for national highway programs.
- Polymer Modified Bitumen:Styrene-butadiene-styrene or ethylene-vinyl-acetate elastomers blended into base binder to enhance rutting resistance and fatigue life. India's BIS certification requirements for national highway contracts are consolidating demand around certified blenders in Maharashtra and Tamil Nadu, squeezing unregistered suppliers from central government-funded projects.
- Rubberized Bitumen:Crumb rubber from end-of-life tires dispersed into binder for improved elasticity and noise reduction.
- Sulfur-Extended Bitumen:Refinery byproduct sulfur partially replacing bitumen content, creating cost-competitive pathways for high-temperature climate applications.
Bio-bitumen commands the established base. The steepest expansion runs through polymer modified grades as specification mandates tighten.
Technology:
Application temperature determines energy intensity, emissions profile, and retrofit capital requirements for contractor adoption.
- Warm Mix Technology:Chemical additives or foaming processes reduce production temperatures by 30–40°C below conventional 150–190°C thresholds while preserving Marshall stability. German road construction agencies are scaling procurement as EU carbon disclosure requirements harden, aligning compliance margins with project profitability targets.
- Cold Mix Technology:Emulsion-based systems enabling ambient-temperature application for remote or maintenance-focused projects.
- Foamed Bitumen:Water injection creates expanded binder for stabilized base layers in pavement recycling applications.
- Hot Mix Technology:Conventional high-temperature production retains dominance in specification-conservative markets lacking carbon accounting infrastructure.
Warm mix technology is climbing the fastest as carbon disclosure requirements spread from EU Green Deal jurisdictions into federal funding conditions elsewhere.
Application:
Volume scale versus margin intensity splits the market between infrastructure programs and commercial building specifications.
- Road Construction:National highway and municipal street programs consuming bulk volumes with specification-driven procurement. India's refinery-to-road infrastructure pipeline and Germany's Autobahn rehabilitation cycles anchor demand concentration, though margin compression from competitive bidding limits profitability.
- Roofing Solutions:UV-resistant modified bitumen membranes for commercial and industrial building envelopes. German renewable construction sector procurement for building-integrated photovoltaics commands specification premiums unavailable in road applications.
- Airport Runways:High-performance binder specifications for heavy aircraft loading and jet fuel resistance.
- Parking Lots:Light-duty commercial and residential surface applications with lower technical barriers to entry.
Road construction anchors volume throughput. Roofing solutions deliver superior margin capture per ton.
End User:
Procurement authority and technical specification control determine supplier access and contract tenure.
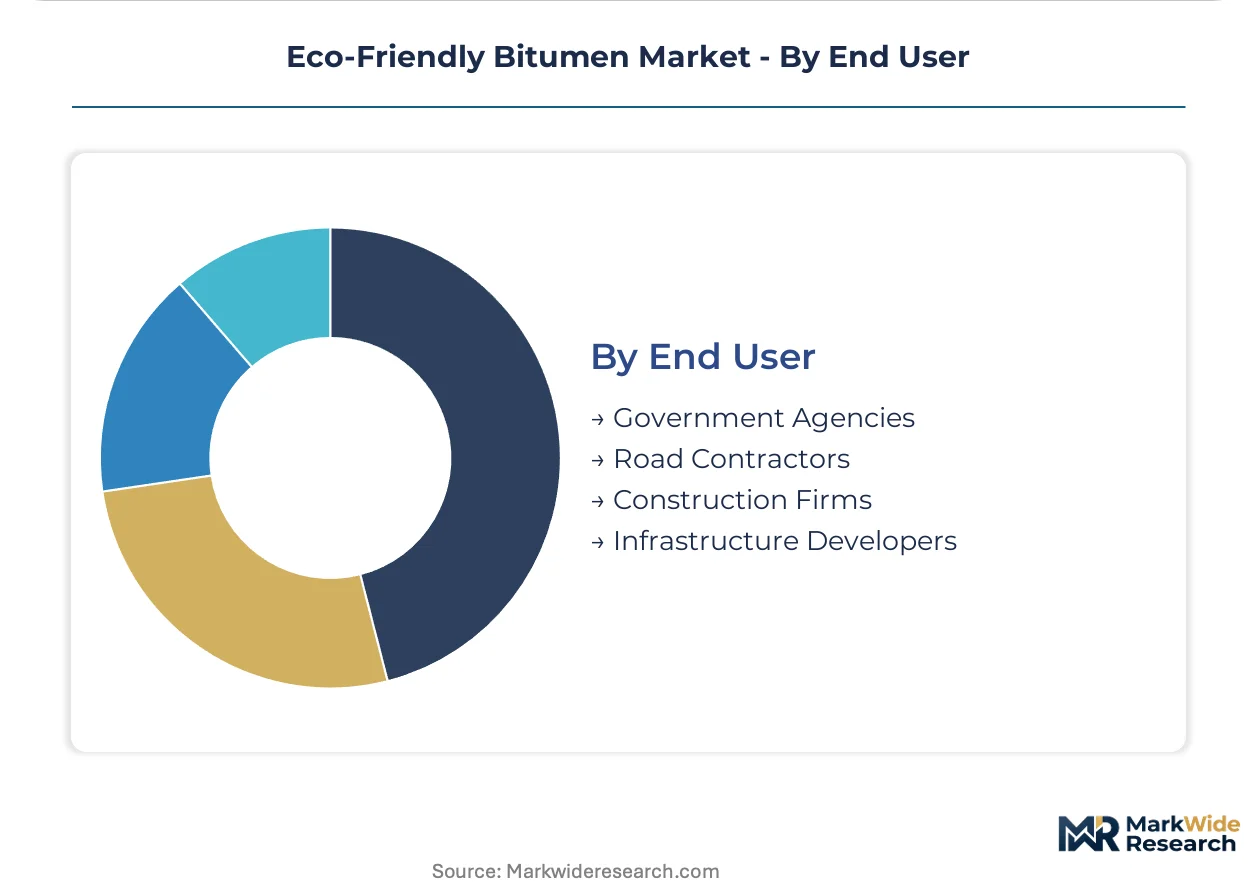
- Government Agencies:State and federal public works departments with mandate-driven purchasing power. EU Green Deal carbon thresholds and India's BIS certification requirements are narrowing approved vendor lists, consolidating procurement around suppliers with verified Environmental Product Declarations and technical service capabilities.
- Infrastructure Developers:Private concession holders and public-private partnership operators with lifecycle cost optimization incentives.
- Road Contractors:Project-execution firms absorbing plant retrofit costs and performance risk.
- Construction Firms:General builders with incidental bitumen demand across diversified project portfolios.
Government agencies control specification gates. Infrastructure developers are gaining share fastest as concession models expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon thresholds anchor procurement mandates across Germany, where road construction agencies now require documented lifecycle emissions for public infrastructure tenders. National highway programs in India and federal infrastructure funding conditions in the United States are accelerating parallel specification shifts.
Germany
Autobahn rehabilitation cycles and municipal street programs drive warm-mix procurement volumes. F-Gas Regulation thresholds pressure contractors to adopt low-temperature rheology enhancements. Bavaria and Baden-Württemberg host pilot specifications for hybrid bio-oil binders following successful trial sections.
India
National highway expansion and refinery-to-road infrastructure pipelines concentrate demand in western and southern states. BIS certification mandates for polymer modified binders disqualify unregistered blenders from central government-funded projects. Maharashtra and Tamil Nadu have narrowed approved vendor lists to fewer than six certified suppliers.
United States
Interstate rehabilitation contracts and state department of transportation procurement steer specifications through federal funding conditions. EPA industrial emission standards embedded in IIJA disbursement rules favor warm-mix formulations. State DOTs in California and Texas are advancing carbon disclosure pilots.
France
Commercial building-integrated photovoltaics and renewable construction sector procurement command specification premiums for UV-resistant modified membranes. CSRD corporate sustainability reporting mandates force construction material suppliers to document Scope 3 emissions. Infrastructure consortia have consolidated procurement around suppliers with verified Environmental Product Declarations.
Netherlands
Public infrastructure tenders mandate documented lifecycle emissions, aligning with EU Green Deal thresholds. Road construction agencies scale warm-mix procurement to maintain contract eligibility. The Randstad region concentrates technical service partnerships between blenders and municipal public works departments.
Eco-Friendly Bitumen Market Competitive Landscape
Integrated refiners and specialized blenders split the market into distinct capability tiers. Consolidation pressures are mounting as certification mandates narrow approved vendor lists for national highway contracts. National oil companies and independent modification specialists represent the dominant strategic archetypes. Capacity expansion near industrial corridors and backward integration into feedstock security constitute the primary competitive moves.
Among India-based suppliers, Bharat Petroleum leverages integrated downstream networks to secure feedstock access, while Agarwal Industrial Corporation dominates western India through specialized blending facilities. Jalnidhi Bitumen Specialties occupies a position differentiated via technical service partnerships with state public works departments.
| Leading Market Players |
|---|
| Cosmique |
| Gilsonite |
| Agarwal Industrial Corporation |
| Mamz Asphalt Technologies |
| Jalnidhi Bitumen Specialties |
| Avello Bioenergy |
| Eagle Petrochem |
| Nikan West Gilsonite |
| Bharat Petroleum |
| Others |
Pricing and Supply Chain Analysis
Crude-linked base bitumen volatility transmits directly from Middle Eastern refinery output fluctuations to binder input costs, compressing blending margins for specialty grade producers while simultaneously widening price spreads between commodity-compatible formulations and certified premium grades across procurement markets.
Pricing Analysis
German warm-mix formulations command measurable premiums over Indian bio-bitumen outputs due to EU Green Deal carbon disclosure requirements and F-Gas Regulation compliance costs. Three-tier pricing structure across premium certified, standard BIS-registered, and economy unmodified grades separates government agency procurement from municipal contractor bidding. Pricing pressure stems from competitive consolidation around Maharashtra and Tamil Nadu approved vendor lists. State public works departments exhibit highest price sensitivity, while German renewable construction sector buyers absorb specification premiums for UV-resistant membranes.
Supply Chain Analysis
REACH registration burdens at ECHA function as de facto export controls, delaying European market entry for innovative bio-additive chemistries and fragmenting modification technology flows. Feedstock security concentrates in India, Germany, and the United States through integrated refinery networks and specialized blending corridors. Raw material dependencies span crude-derived base bitumen, lignocellulosic waste streams, and post-consumer polymer waste. Single-source vulnerability runs through Middle Eastern refinery output fluctuations. Distribution runs through certified blender networks serving state public works departments and infrastructure consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where BIS certification and EU Green Deal carbon thresholds create switching costs that lock government agencies into approved vendor relationships, deepening competitive moats for certified suppliers.
For Market Incumbents: Insulate market position through backward integration into refinery feedstock networks near Gujarat's industrial corridor and accelerated BIS certification investments for polymer modified grades. Unregistered blenders face disqualification from India's central government-funded projects. Technical service capabilities with state public works departments anchor contract tenure against price-only competitors. For New Entrants and Emerging Players: Establish a beachhead in sulfur-extended bitumen for tropical climate applications where refinery byproduct utilization creates cost-competitive pathways without requiring full BIS certification. Municipal road maintenance contracts in Southeast Asia offer lowest barriers. Partner with regional crumb rubber processors for rubberized bitumen formulations targeting noise reduction specifications. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with captive feedstock access and certified EPD documentation. Long-term viability hinges on carbon accounting infrastructure expansion from production-phase to full pavement lifecycle assessments. Watch for CSRD Scope 3 disclosure mandates forcing construction material supplier consolidation as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refinery Feedstock | Bharat Petroleum secures base binder supply for polymer modified grades through captive downstream networks. |
| BIS Certification Investment | Registration mandates disqualify unregistered blenders from Maharashtra and Tamil Nadu approved vendor lists. |
| Technical Service Partnership Expansion | Jalnidhi Bitumen Specialties anchors state public works department relationships beyond price competition. |
| Warm-Mix Technology Retrofit | German contractors align EU Green Deal compliance margins with project profitability through temperature reduction. |
| Environmental Product Declaration Verification | French infrastructure consortia consolidate procurement around suppliers with certified carbon intensity data. |
Research Methodology
Initial hypotheses were tested against primary input from refinery operations managers, state public works department procurement leads, road construction contractors, and technical R&D directors at modification specialists and refined through secondary validation against BIS certification records, EU Green Deal tender documentation, SEC filings from integrated energy companies, customs trade data for bitumen imports, and ECHA REACH registration databases. Bottom-up demand modeling across application segments triangulated with top-down supply capacity assessments.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling spanning modification chemistry, production temperature regime, application intensity, and end-user procurement authority. CAGRs were derived from installed base growth rates and specification mandate diffusion curves. Forecast inputs incorporated PLI scheme incentive trajectories and CSRD corporate sustainability reporting phase-in schedules.
Sensitivities concentrate around crude price volatility, REACH registration timeline extensions, and BIS certification enforcement intensity. Forecasts reflect documented assumptions regarding regulatory carbon accounting boundary expansion. Material shifts in EU Green Deal threshold stringency or Indian central government funding allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Green Cement Market
Green Building Materials
Green Cement and Concrete Market
Green Building Materials
Green Silica Market
Green Building Materials
Solar Glass Market
Green Building Materials
APAC Green Buildings Market
Green Building Materials
United States Green Cement Market
Green Building Materials
Green Building Materials Market
Green Building Materials
Green Waterproofing Products Market
Green Building Materials
Solar Windows Market
Green Building Materials
GCC Green Cement Market
Green Building Materials
North America Green Buildings Market
Green Building Materials
Eco-Friendly Tiles Market
Green Building Materials
Asia Pacific Green Cement Market
Green Building Materials
Green Rebar Market
Green Building Materials
Green Roof Market
Green Building Materials
China Green Building Materials Market