
 North America Bio-Medical Waste Management Market | 2026-2036
North America Bio-Medical Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bio-Medical Waste Management Market Insights
Subscription-based compliance monitoring is pivoting how waste management firms monetize relationships beyond per-pickup fees. Stericycle sustains broad geographic coverage through its North American network of treatment facilities. Republic Services leverages municipal solid waste infrastructure to cross-sell bio-medical services at competitive unit economics. Clean Harbors anchors high-complexity hazardous waste streams with specialized incineration and chemical treatment capabilities.
Bio-medical waste management encompasses the controlled collection, transport, treatment, and disposal of infectious, pathological, and sharps waste generated by healthcare facilities, with autoclaving subjecting materials to steam at 121°C for 15–30 minutes to achieve sterilization before landfill deposition. The primary purpose is preventing disease transmission and environmental contamination from bloodborne pathogens and pharmaceutical residues. Sharps containers dominate product-type procurement volumes due to universal precaution mandates in hospitals and laboratories. Autoclaving leads technology adoption for non-hazardous streams, while plasma pyrolysis captures emerging interest for zero-residue hazardous destruction. Collection services concentrate margin pools through route density and long-term contracts with integrated delivery networks.
US EPA medical waste tracking rules, OSHA bloodborne pathogen standards, and state environmental agency permits collectively shape treatment technology choices and facility siting decisions across the region. Canadian provincial regulators and Mexico's environmental secretariat add cross-border complexity for multinational healthcare systems operating treatment networks. Stakeholders must monitor evolving pharmaceutical waste classification rules and emerging PFAS restrictions that could redefine acceptable disposal pathways.
Market Dynamics
US EPA's medical waste tracking regulations and state-level cradle-to-grave manifest requirements are compressing operational timelines for healthcare facilities while expanding compliance service demand. Long-term care facilities face escalating waste volumes from aging patient demographics, forcing procurement teams toward integrated service contracts.
Growth Catalysts
- Southeastern US hospital construction:New acute care facilities in Florida, Georgia, and North Carolina are issuing bundled waste management RFPs with 10-year terms. These contracts prioritize route density and on-site treatment capacity.
- OSHA bloodborne pathogen standards:Universal precaution mandates require sharps container placement at every point of care, driving recurring container replacement volumes across outpatient clinics and physician practices.
- Plasma pyrolysis adoption:Zero-residue hazardous waste destruction is capturing interest from research hospitals and pharmaceutical manufacturers seeking to eliminate landfill liability for trace chemotherapeutic residues.
Market Restraints
- Specialized incineration capacity concentration:High-complexity hazardous waste treatment infrastructure clusters in Texas, Ohio, and Ontario, creating regional bottlenecks and transport cost premiums for facilities outside these zones.
- PFAS regulatory uncertainty:Emerging restrictions on per- and polyfluoroalkyl substances in medical textiles and protective equipment threaten to reclassify previously non-hazardous waste streams, requiring costly retesting protocols.
- Autoclave energy intensity:Steam sterilization at 121°C for 15–30 minutes consumes substantial natural gas or electricity, exposing service providers to volatile utility rates across deregulated state markets.
Strategic Opportunities
- Mexico healthcare system expansion:The country's environmental secretariat is developing federal bio-medical waste standards that will require foreign treatment partnerships for border-state hospitals lacking domestic incineration capacity.
- Subscription-based compliance monitoring:Real-time manifest tracking and regulatory alert systems are creating recurring revenue streams beyond per-pickup fees, deepening customer switching costs.
- AI-powered route optimization:Machine learning algorithms are converging with telematics to reduce collection vehicle miles by predicting waste accumulation patterns at multi-site integrated delivery networks.
Industry Challenges
- Certified treatment technician scarcity:OSHA 40-hour HAZWOPER training and state-specific operator licenses create 6–12 month hiring pipelines, constraining facility expansion timelines.
- Legacy manifest system integration:Healthcare IT departments struggle to connect EPA-mandated tracking databases with existing ERP platforms, delaying contract start dates and invoice reconciliation.
- Chemical treatment capex cycles:Alkaline hydrolysis and advanced oxidation systems require 7–10 year depreciation schedules, complicating ROI calculations against shorter contract durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bio-Medical Waste Management Market |
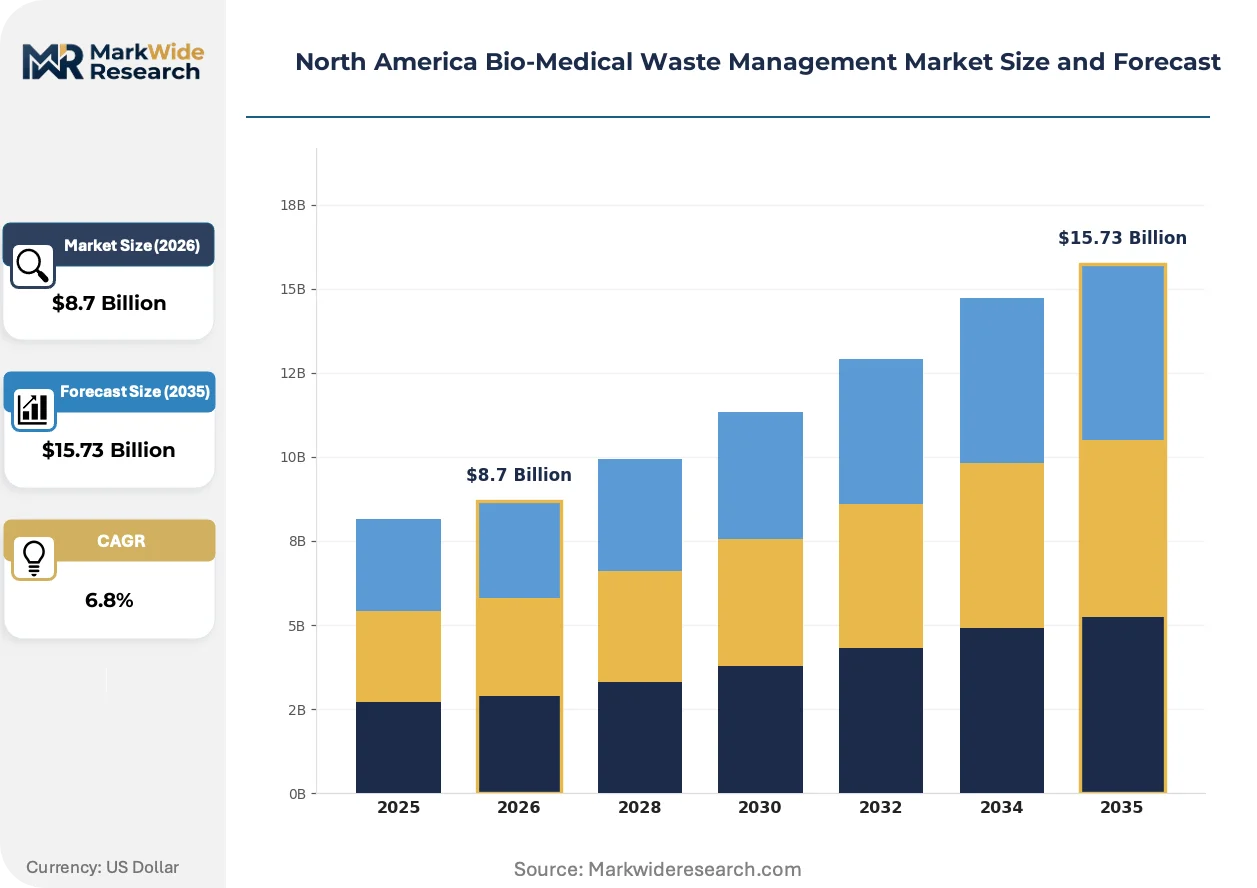
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sharps, Pathological Waste, Non-Hazardous Waste, Hazardous Waste Service Type: Collection, Treatment, Disposal, Recycling End User: Hospitals, Clinics, Laboratories, Long-Term Care Facilities Technology: Incineration, Autoclaving, Plasma Pyrolysis, Chemical Treatment |
| Companies Covered | Veolia Environmental Services, Republic Services, Inc., Stericycle, Inc., BioMedical Waste Solutions, LLC, Daniels Sharpsmart, Inc., Waste Management, Inc., MedPro Disposal, Sharp Compliance, Inc., Clean Harbors, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bio-Medical Waste Management Market Trends and Innovations
Technology convergence and regulatory tightening are compressing traditional service boundaries while elevating data transparency as a competitive differentiator. Treatment providers are repositioning around compliance intelligence rather than commodity disposal.
Mobile sterilization units mounted on truck chassis are modularizing treatment capacity deployment. Rural critical access hospitals and temporary field clinics are adopting these systems to eliminate transport costs for infectious waste. This distributed architecture is compressing the addressable market for centralized incineration facilities in secondary metropolitan areas.
US EPA's pharmaceutical waste classification rules are tightening segregation requirements for hazardous drug listings. Healthcare facilities must now maintain separate streams for P-listed and U-listed chemotherapeutics, doubling container SKUs and staff training burdens. Oncology centers in California and Massachusetts are responding by outsourcing entire pharmacy waste programs to specialized third-party managers.
Integrated delivery networks are consolidating vendor relationships across dozens of affiliated sites. Procurement teams at systems like those spanning Wisconsin-to-Illinois corridors are replacing site-by-site contracts with enterprise-wide agreements that bundle bio-medical, hazardous, and municipal solid waste under unified pricing tiers. This concentration is visible most acutely in the upper Midwest, where Catholic health systems and academic medical centers lead consolidation patterns.
North America Bio-Medical Waste Management Market Segmentation
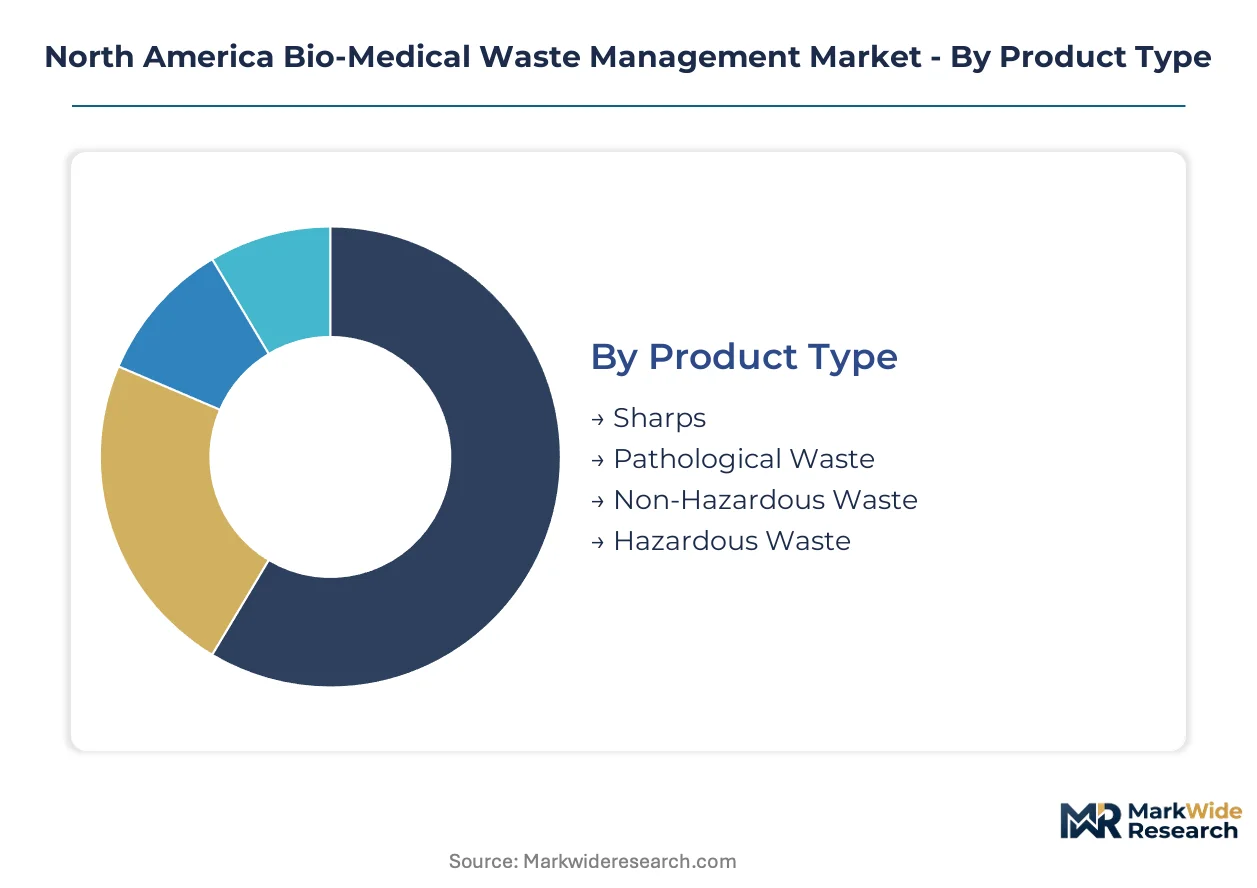
Segmentation in bio-medical waste management reveals how service providers configure operations around waste hazard profiles, treatment physics, and facility scale. Procurement patterns diverge sharply between high-volume hospital systems and distributed outpatient networks, with technology choices locking in decade-long capital commitments.
Product Type:
Customization intensity spans from standardized commodity containers to highly regulated hazardous streams requiring specialized handling protocols.
- Sharps:Puncture-resistant containers constructed from polypropylene or high-density polyethylene withstand needle penetration and autoclave cycles. OSHA bloodborne pathogen mandates require placement at every point of care across Florida, Georgia, and Texas outpatient networks, driving recurring replacement schedules tied to fill-line indicators.
- Hazardous Waste:Chemotherapeutic residues, mercury-containing devices, and bulk pharmaceuticals fall under EPA hazardous waste listings with cradle-to-grave manifest obligations. Research hospitals in Massachusetts and California face the strictest state-level testing protocols for trace residue thresholds.
- Pathological Waste:Human tissues, organs, and anatomical parts require incineration or alkaline hydrolysis under state medical waste regulations.
- Non-Hazardous Waste:General infectious materials excluding sharps and pathological streams, suitable for autoclaving before landfill deposition.
Leading the category by volume: Sharps. Expanding most quickly: Hazardous Waste.
Service Type:
Margin distribution follows the value chain from logistics-intensive collection through capital-heavy treatment to compliance-critical documentation.
- Collection:Route-optimized pickup services using DOT-certified vehicles and refrigerated transport for temperature-sensitive biological materials. Southeastern US hospital construction is bundling 10-year collection contracts with on-site storage system leases.
- Treatment:Steam sterilization, incineration, and emerging plasma pyrolysis systems requiring EPA permits and continuous emissions monitoring. Texas and Ohio treatment clusters capture economies of scale for high-complexity hazardous streams.
- Disposal:Final landfill deposition of treated residues, with RCRA subtitle D facilities accepting autoclaved waste and subtitle C sites handling hazardous ash.
- Recycling:Recovery of sterilized plastics and metals from non-hazardous streams, constrained by FDA concerns over material traceability in medical applications.
Dominant by revenue: Treatment. Steepest expansion trajectory: Collection.
End User:
Facility scale determines contract structure, with integrated delivery networks consolidating vendor relationships across dozens of sites.
- Hospitals:Acute care facilities generating 50-70% of regional bio-medical waste volume through surgical suites, emergency departments, and inpatient units. New construction in North Carolina and Florida is issuing bundled RFPs prioritizing route density.
- Long-Term Care Facilities:Nursing homes and assisted living centers facing escalating waste volumes from aging patient demographics and extended antibiotic therapies. Procurement teams are migrating from per-pickup arrangements to integrated service contracts with compliance monitoring subscriptions.
- Clinics:Outpatient and physician practice settings with lower volume but higher per-pound logistics costs due to dispersed geography.
- Laboratories:Diagnostic and research facilities generating concentrated chemical and biological hazard streams requiring specialized segregation.
Volume leader: Hospitals. Gaining share fastest: Long-Term Care Facilities.
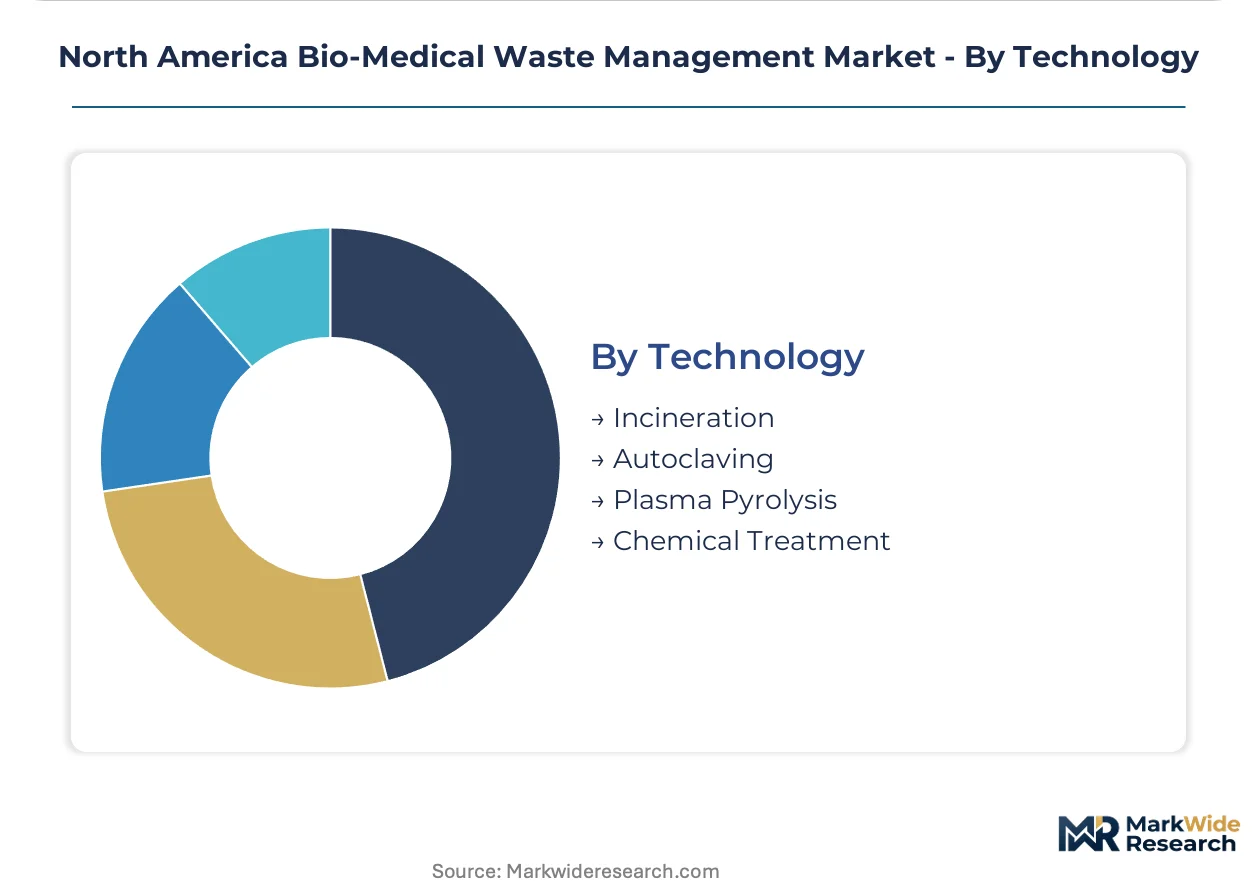
Technology:
Capital intensity and regulatory acceptance create divergent adoption curves across treatment modalities.
- Autoclaving:Steam sterilization at 121°C for 15-30 minutes achieves 4-log pathogen reduction before landfill deposition. Natural gas price volatility in deregulated Texas and California markets is compressing operating margins for high-throughput facilities.
- Plasma Pyrolysis:High-temperature plasma arc destruction achieving zero-residue conversion of hazardous organic compounds to syngas and vitrified slag. Research hospitals in Ontario and pharmaceutical manufacturers are piloting systems to eliminate landfill liability for chemotherapeutic residues.
- Incineration:Controlled combustion with emissions scrubbing for pathological and hazardous waste streams, concentrated in Texas, Ohio, and Ontario due to permitting complexity.
- Chemical Treatment:Alkaline hydrolysis and advanced oxidation for specific pharmaceutical and chemical waste categories, requiring 7-10 year depreciation schedules.
Installed base leader: Autoclaving. Climbing the fastest: Plasma Pyrolysis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American bio-medical waste treatment capacity through its specialized incineration cluster and petrochemical-adjacent hazardous waste infrastructure. The metropolitan area's concentration of EPA-permitted facilities draws waste streams from across the southeastern United States and Mexico border states.
United States
Hospital construction in Florida, Georgia, and North Carolina is generating bundled 10-year service contracts prioritizing route density and on-site treatment capacity. The EPA's medical waste tracking regulations and state-level cradle-to-grave manifest requirements are compressing operational timelines for healthcare facilities. Texas and Ohio treatment clusters capture economies of scale for high-complexity hazardous streams.
Canada
Ontario's research hospitals in Toronto and Ottawa are piloting plasma pyrolysis systems to eliminate landfill liability for chemotherapeutic residues. Provincial regulators enforce stringent testing protocols for trace residue thresholds that exceed federal baselines. The province's incineration capacity concentration creates regional bottlenecks for facilities in Atlantic Canada and the Prairie Provinces.
Mexico
The environmental secretariat is developing federal bio-medical waste standards that will require foreign treatment partnerships for border-state hospitals lacking domestic incineration capacity. Mexico City Metro hospitals currently rely on cross-border transport to Texas facilities. Nuevo León and Baja California are emerging as priority zones for infrastructure investment.
Southeastern United States
Florida's aging demographics are escalating waste volumes at long-term care facilities, forcing procurement teams toward integrated service contracts with compliance monitoring subscriptions. Georgia's outpatient clinic expansion is driving sharps container replacement volumes under OSHA bloodborne pathogen mandates. North Carolina's Research Triangle pharmaceutical manufacturers are outsourcing entire pharmacy waste programs.
North America Bio-Medical Waste Management Market Competitive Landscape
Capital-heavy treatment facility operators compete with asset-light logistics specialists for margin pools across the value chain. The market exhibits tiered consolidation, with national networks spanning collection through disposal alongside regional specialists anchoring single-service dominance. Three archetypes predominate: integrated full-service providers, hazardous waste specialists with incineration depth, and route-optimized collection platforms. M&A activity concentrates on expanding geographic coverage, while technology licensing partnerships accelerate plasma pyrolysis deployment.
Among integrated full-service providers, Stericycle, Inc. and Republic Services, Inc. exemplify the national-network archetype through broad geographic coverage and cross-selling capabilities. Clean Harbors, Inc. occupies a distinct position anchoring high-complexity hazardous waste streams with specialized treatment depth. These three companies represent the competitive spectrum from commodity logistics to technical differentiation.
| Leading Market Players |
|---|
| Veolia Environmental Services |
| Republic Services, Inc. |
| Stericycle, Inc. |
| BioMedical Waste Solutions, LLC |
| Daniels Sharpsmart, Inc. |
| Waste Management, Inc. |
| MedPro Disposal |
| Sharp Compliance, Inc. |
| Clean Harbors, Inc. |
| Others |
Pricing and Supply Chain Analysis
Integrated delivery networks concentrating procurement across southeastern US hospital systems have shifted contract structures toward subscription-based compliance monitoring bundled with per-pickup fees. This buyer concentration rewards route density and long-term contract tenure over spot-market flexibility.
Pricing Analysis
Throughput-based pricing anchors service contracts, with providers charging per-pound rates for infectious waste streams and flat monthly fees for compliance documentation systems. Price differentiation separates hazardous chemotherapeutic residues requiring cradle-to-grave manifest tracking from standard autoclaved materials. Cost compression in the non-hazardous tier stems from natural gas price volatility affecting steam sterilization economics. Long-term care facilities exhibit highest price sensitivity due to thin operating margins, while research hospitals show lowest sensitivity given liability avoidance priorities.
Supply Chain Analysis
Single-source vulnerability sits with Texas, Ohio, and Ontario as the only North American jurisdictions hosting EPA-permitted high-complexity incineration capacity. Treatment infrastructure draws from specialized refractory linings, emissions scrubbing catalysts, and certified technician labor pools. Tariff exposure runs through Canadian cross-border transport corridors serving Michigan and New York healthcare systems. Distribution runs through hub-and-spoke logistics networks radiating from Houston and Toronto treatment clusters to rural critical access hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized incineration capacity bottlenecks in Texas and Ohio prop pricing power for hazardous waste treatment tiers, creating durable margin pools for operators with permitting depth.
For Market Incumbents: Deepen vertical integration into on-site sterilization equipment leasing to capture recurring revenue streams beyond transport fees. Expand plasma pyrolysis pilot programs at research hospitals in Ontario and Massachusetts to preempt landfill liability shifts. Defend against mobile sterilization unit disruptors by locking in 10-year exclusive service contracts with new southeastern hospital construction. For New Entrants and Emerging Players: Begin with AI-powered route optimization software targeting mid-sized integrated delivery networks in the upper Midwest lacking enterprise-scale vendor relationships. Mexico's border-state hospitals lacking domestic incineration capacity offer the most penetrable geography. Pursue foreign treatment partnership structures with Texas facilities as the go-to-market anchor. For Investors and Strategic Acquirers: The window for entry favors asset-light compliance monitoring platforms with recurring SaaS revenue models over capital-intensive treatment infrastructure. Long-term viability rests on regulatory complexity expansion rather than volume growth alone. Watch for PFAS reclassification rules as the signal indicating accelerated hazardous waste stream migration toward specialized treatment.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Pyrolysis Deployment | Eliminates landfill liability for chemotherapeutic residues at research hospitals in Ontario. |
| Subscription Compliance Monitoring | Creates recurring revenue beyond per-pickup fees through real-time EPA manifest tracking. |
| Mobile Sterilization Unit Manufacturing | Modularizes treatment capacity for rural critical access hospitals in secondary markets. |
| Mexico Foreign Partnership Structure | Captures border-state hospital demand lacking domestic incineration infrastructure. |
| AI Route Optimization Platform | Reduces collection vehicle miles through predictive waste accumulation pattern modeling. |
Research Methodology
EPA medical waste tracking databases, state environmental agency permit filings, and hospital procurement contract disclosures formed the secondary backbone. Primary interviews with waste treatment facility operators, healthcare GPO contracts managers, and biomedical engineering directors at integrated delivery networks validated operational assumptions. Bottom-up triangulation across service contract values and top-down cross-checks against treatment capacity utilization rates anchored volume estimates.
Historical trendline analysis of treatment facility permitting timelines and waste stream classification shifts informed the projection framework. Segmentation modeling spanned product type hazard profiles, service tier margin structures, end-user facility scales, and technology adoption curves across the analysis window. CAGRs derived from contracted pricing escalators and capacity expansion announcements rather than extrapolated growth rates. Forecast inputs incorporated OSHA enforcement intensity patterns and pharmaceutical waste listing updates.
Underlying measurement precision varies by segment; sharps container procurement volumes carry tighter precision than emerging plasma pyrolysis adoption rates. Forecasts reflect assumptions about regulatory enforcement continuity and natural gas price stabilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Industrial Solid Waste Management Market
Waste Management & Pollution Control
Africa Waste Management Market
Waste Management & Pollution Control
Metal Recycling Baler Market
Waste Management & Pollution Control
Compostable Straws Market
Waste Management & Pollution Control
North America Trash Bags Market
Waste Management & Pollution Control
Waste Paper Management Market
Waste Management & Pollution Control
UAE Industrial Waste Management Market
Waste Management & Pollution Control
Solid Waste Management Market
Waste Management & Pollution Control
Smart Waste Sorting Bin Market
Waste Management & Pollution Control
GCC Waste Management Market
Waste Management & Pollution Control
Global Waste Disposal Equipment Market
Waste Management & Pollution Control
India Municipal Solid Waste Management Market
Waste Management & Pollution Control
Recycled Waste Management Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market
Waste Management & Pollution Control
India Bio-Medical Waste Management Market
Waste Management & Pollution Control
Global Smart Trash Bin Market