
 Green Cement Market | 2026-2036
Green Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Green Cement Market Analysis
Aftermarket service revenue from clinker substitution consulting is narrowing as manufacturers internalize technical advisory functions. Holcim Ltd leverages its global R&D network to develop low-carbon binders across multiple geographies. Heidelberg Materials anchors European production capacity through integrated slag processing infrastructure. UltraTech Cement Ltd dominates South Asian fly ash blending operations with captive thermal power linkages.
Green cement denotes hydraulic binders manufactured with reduced clinker content through supplementary cementitious materials such as fly ash, ground granulated blast-furnace slag, or metakaolin, achieving CO2 reductions of 30-70% versus ordinary Portland cement while maintaining compressive strength standards for structural applications. Fly ash blends occupy the largest volume share among product types due to established supply chains from coal power generation, while geopolymer formulations represent the fastest-expanding category as alkaline activation chemistry matures for precast concrete applications. Infrastructure projects generate the dominant application demand as public procurement mandates embodied carbon thresholds for bridges, roads, and utility structures.
The EPA enforces greenhouse gas reporting requirements for cement kilns under the Clean Air Act, compelling US producers to document and reduce process emissions. The EU Green Deal's carbon border adjustment mechanism and the F-Gas Regulation collectively reshape import competitiveness for conventional clinker-intensive cement. India's BIS clinker-factor grading standards directly determine product classification and public project eligibility. Stakeholders must monitor regulatory tightening trajectories in their operating jurisdictions to align capital allocation with compliance timelines.
Market Dynamics
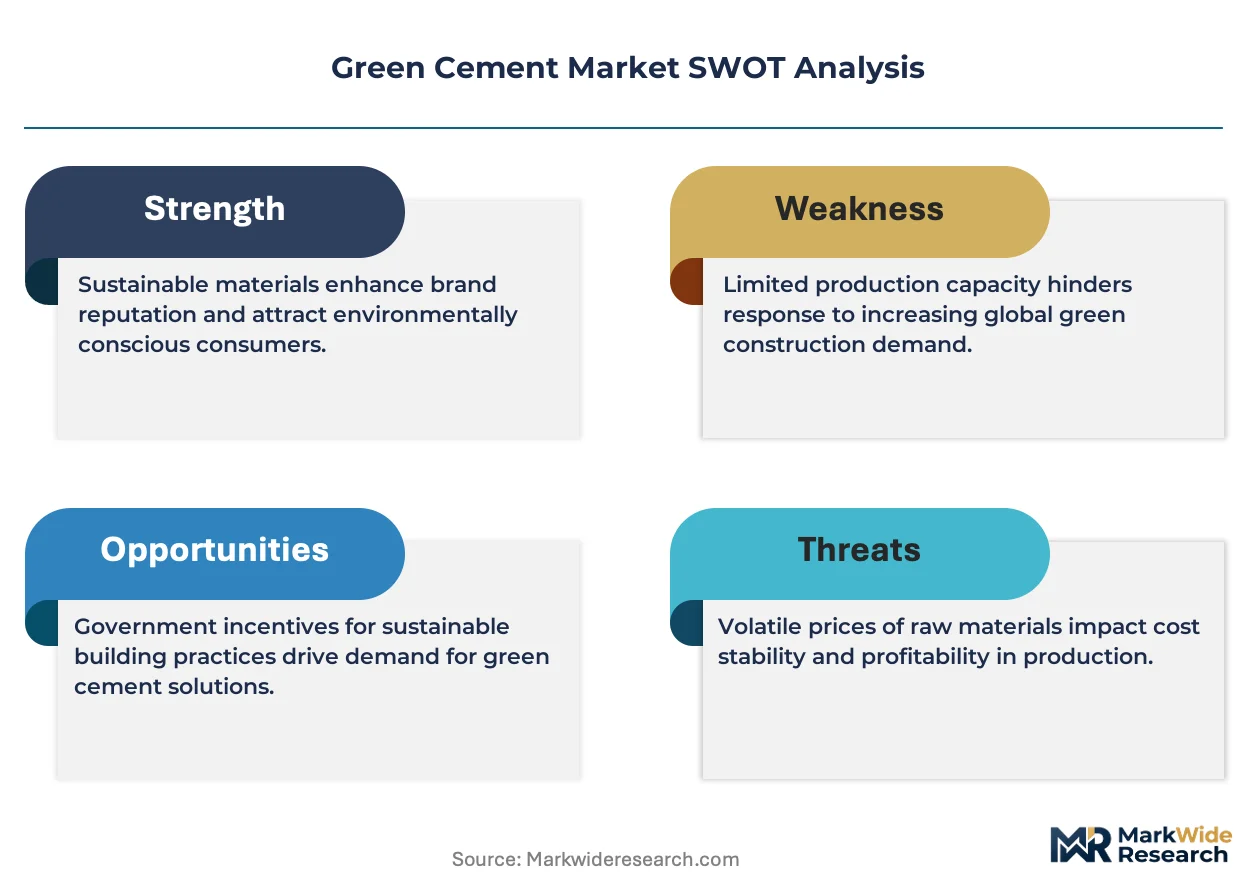
Clinker-factor reduction mandates are compressing conventional Portland cement margins while elevating supplementary cementitious material premiums across procurement contracts.
Growth Catalysts
- EU Green Deal carbon border adjustments:Import tariffs on clinker-intensive cement from non-EU sources are redirecting contractor procurement toward domestic low-carbon blends.
- India BIS grading protocols:Tightened clinker-factor limits for public project eligibility are forcing manufacturers to reformulate products for infrastructure tenders.
- Geopolymer chemistry maturation:Alkaline activation processes for fly ash and slag are achieving compressive strength parity with conventional binders in precast applications.
Market Restraints
- Fly ash supply concentration:Thermal power plant retirements in Germany and Poland are constraining SCM availability for regional blenders.
- Metakaolin cost volatility:Calcined clay production energy intensity creates input price exposure unmatched by slag or ash alternatives.
- CSA cement substitution threat:Calcium sulfoaluminate formulations from specialty producers are capturing niche high-early-strength segments.
Strategic Opportunities
- Carbon capture integration:Post-combustion amine scrubbing at cement kilns creates negative-emission product lines qualifying for EU ETS premium credits.
- Rural India distribution gaps:Untapped district-level markets lack blended cement penetration despite available fly ash from state thermal plants.
- 3D-printed concrete specification:Geopolymer rheology tailored for extrusion-based construction is opening additive manufacturing demand channels.
Industry Challenges
- Alkali-silica reaction testing gaps:Extended durability validation timelines for novel SCM combinations delay commercial rollout.
- Legacy kiln retrofit capex:Converting long-dry kilns to oxyfuel combustion requires capital commitments beyond mid-tier producer balance sheet capacity.
- SCM logistics reconfiguration:Slag grinding infrastructure placement misaligned with emerging demand centers creates supply chain friction.
Report Scope
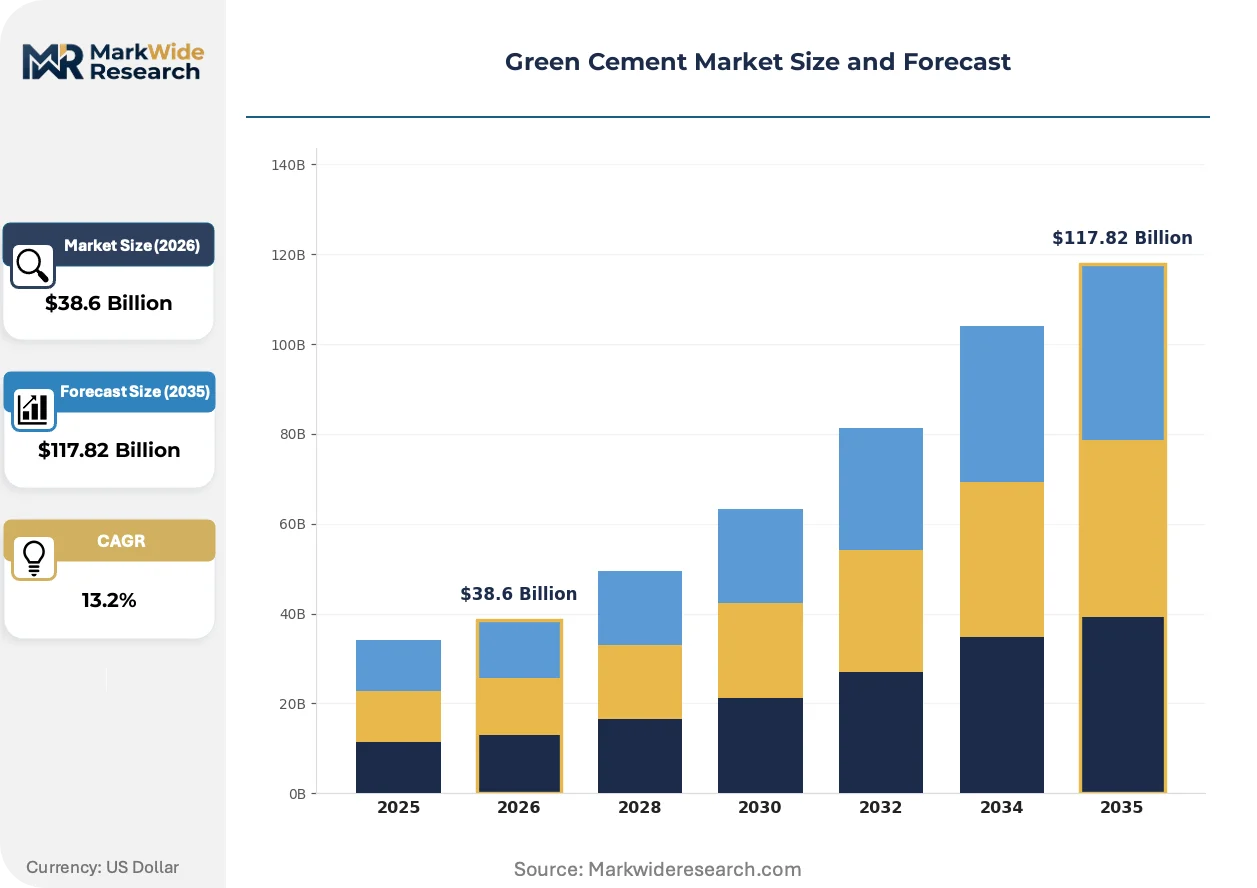
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Cement Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $117.82 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fly Ash, Slag Cement, Geopolymer, Sulfate Resisting Application: Residential Construction, Commercial Construction, Infrastructure, Precast Concrete End User: Contractors, Engineers, Architects, Builders Distribution Channel: Direct Sales, Retail, Online Sales, Wholesale |
| Companies Covered | Holcim Ltd, CEMEX S.A.B. de C.V., Heidelberg Materials, UltraTech Cement Ltd, CRH plc, Anhui Conch Cement, Taiheiyo Cement Corporation, Votorantim Cimentos S.A., ACC Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Cement Market Emerging Trajectories
Digital twin modeling of clinker substitution chemistry is compressing formulation development cycles while regulatory carbon accounting tightens procurement specifications.
Artificial intelligence-driven predictive control is digitizing kiln combustion optimization to maintain burn zone stability with highly variable SCM feedstocks. Heidelberg Materials deploys neural network models across its German integrated plants to manage slag-blend thermal profiles. The technology is digitizing quality assurance workflows that previously required manual sampling and lab testing.
The EU F-Gas Regulation and carbon border adjustment mechanism collectively reshape import competitiveness for conventional clinker-intensive cement. Non-EU producers face compliance documentation burdens that favor domestic low-carbon blenders. Infrastructure contractors in the Netherlands and Belgium are now specifying embodied carbon thresholds that exclude unverified imports.
Buyers are consolidating procurement around certified low-carbon products with third-party EPD verification replacing generic sustainability claims. General contractors on French public works projects now require ISO 14025-compliant declarations for all structural concrete. This specification compression is visible most acutely in Nordic markets where Skanska and NCC have unified their green cement tender requirements.
Green Cement Market Segmentation
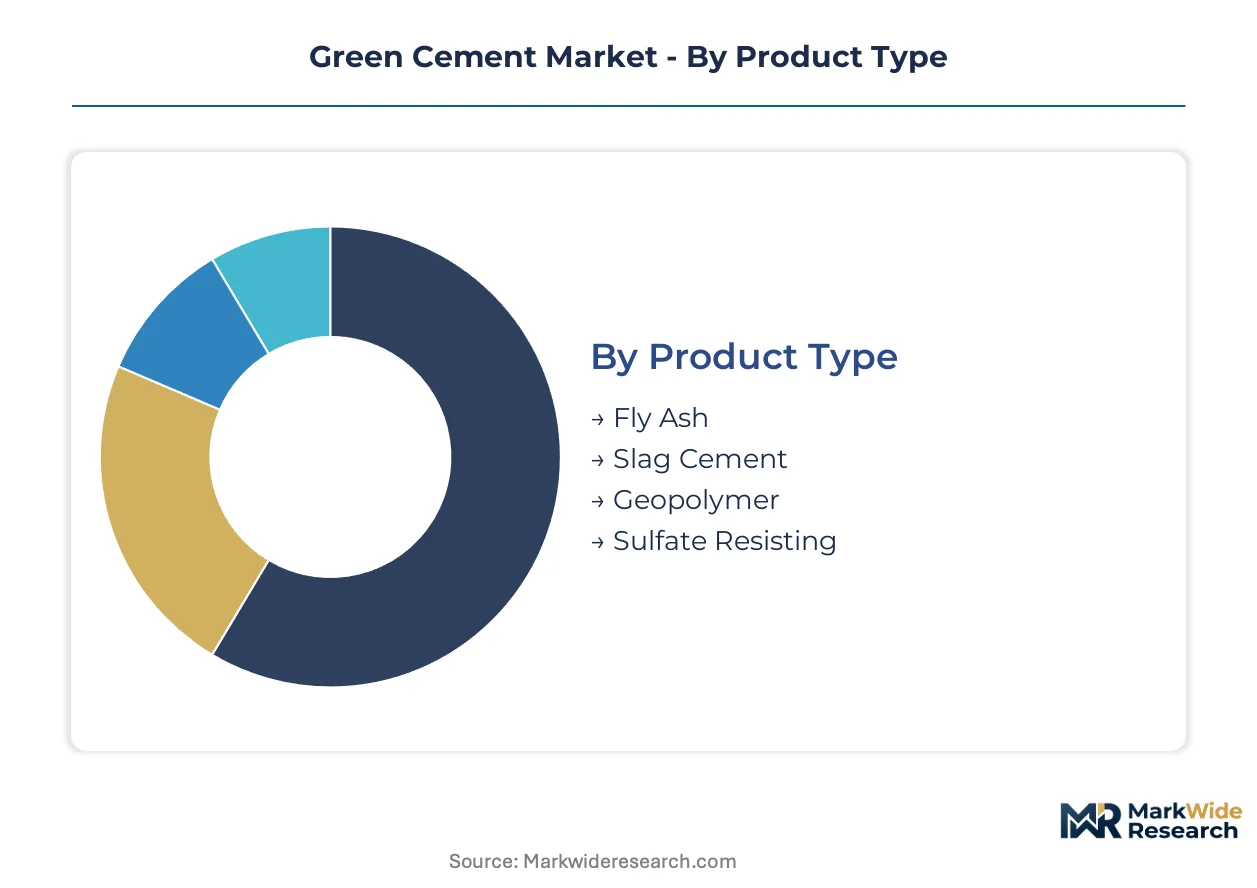
Green cement segmentation reveals how clinker substitution chemistry, procurement specifications, and project delivery methods fragment demand across distinct technical and commercial channels. Manufacturers configure production assets and supply chain investments around these segment boundaries.
Product Type:
Mature formulations anchor current procurement volumes while emerging chemistries reshape R&D allocation and capital deployment priorities.
- Fly Ash:Pulverized coal combustion residue processed as supplementary cementitious material, typically replacing 15-35% of clinker in blended formulations. Indian infrastructure contractors specify this grade most heavily under BIS clinker-factor protocols, though German thermal plant retirements are tightening regional availability. Fly Ash retains volume leadership; Geopolymer holds the steepest expansion curve.
- Slag Cement:Ground granulated blast-furnace slag activated through hydraulic reaction with Portland cement clinker, delivering sulfate resistance and lower heat of hydration. Heidelberg Materials anchors European production through integrated steel mill partnerships, capturing precast concrete demand in the Netherlands and Belgium.
- Geopolymer:Alkaline-activated aluminosilicate binders eliminating Portland clinker entirely, with metakaolin or fly ash feedstocks cured under elevated temperature conditions.
- Sulfate Resisting:Low-C3A clinker formulations or blended alternatives engineered for sewage treatment, marine, and aggressive soil environments.
Formulation chemistry directly determines carbon intensity certification eligibility under procurement mandates in France, India, and the Netherlands.
Application:
Project scale and structural performance requirements create divergent specification thresholds that segment manufacturing and distribution strategies.
- Residential Construction:Single-family and multi-unit housing projects specifying lower-grade blended cements for foundations, slabs, and non-structural elements. Indian state housing boards drive fly ash blend procurement through cost-sensitive tender mechanisms, while German Passivhaus standards elevate performance requirements for thermal mass applications.
- Commercial Construction:Office towers, retail complexes, and institutional buildings requiring certified compressive strength and embodied carbon documentation. French public works mandates now require ISO 14025-compliant EPDs for all structural concrete in this segment, compressing supplier qualification lists.
- Infrastructure:Bridges, highways, dams, and utility structures governed by public agency procurement with clinker-factor limits and durability warranties.
- Precast Concrete:Factory-cast structural and architectural elements demanding controlled curing conditions and rapid strength development.
Infrastructure commands the largest absolute tonnage; Precast Concrete is climbing the fastest as geopolymer rheology matures for extrusion and molding applications.
End User:
Professional role determines whether procurement decisions prioritize first-cost minimization, lifecycle carbon accounting, or aesthetic and structural design flexibility.
- Contractors:Construction firms managing project delivery and material procurement under fixed-price or cost-plus contracts. Indian EPC contractors on National Highway Authority projects face BIS grading compliance as a tender eligibility gate, reshaping supplier relationships.
- Engineers:Structural and materials engineers specifying mix designs and performance standards. Nordic engineering consultancies now embed embodied carbon thresholds in concrete specifications for Skanska and NCC frameworks, eliminating conventional Portland alternatives.
- Architects:Design professionals influencing material selection through sustainability scoring and aesthetic requirements.
- Builders:Small-scale construction operators purchasing through retail and wholesale channels with limited technical specification involvement.
Engineers control specification authority for high-volume projects; Contractors concentrate procurement decision-making for public infrastructure.
Distribution Channel:
Channel selection reflects order scale predictability, geographic proximity to production assets, and documentation requirements for carbon certification.
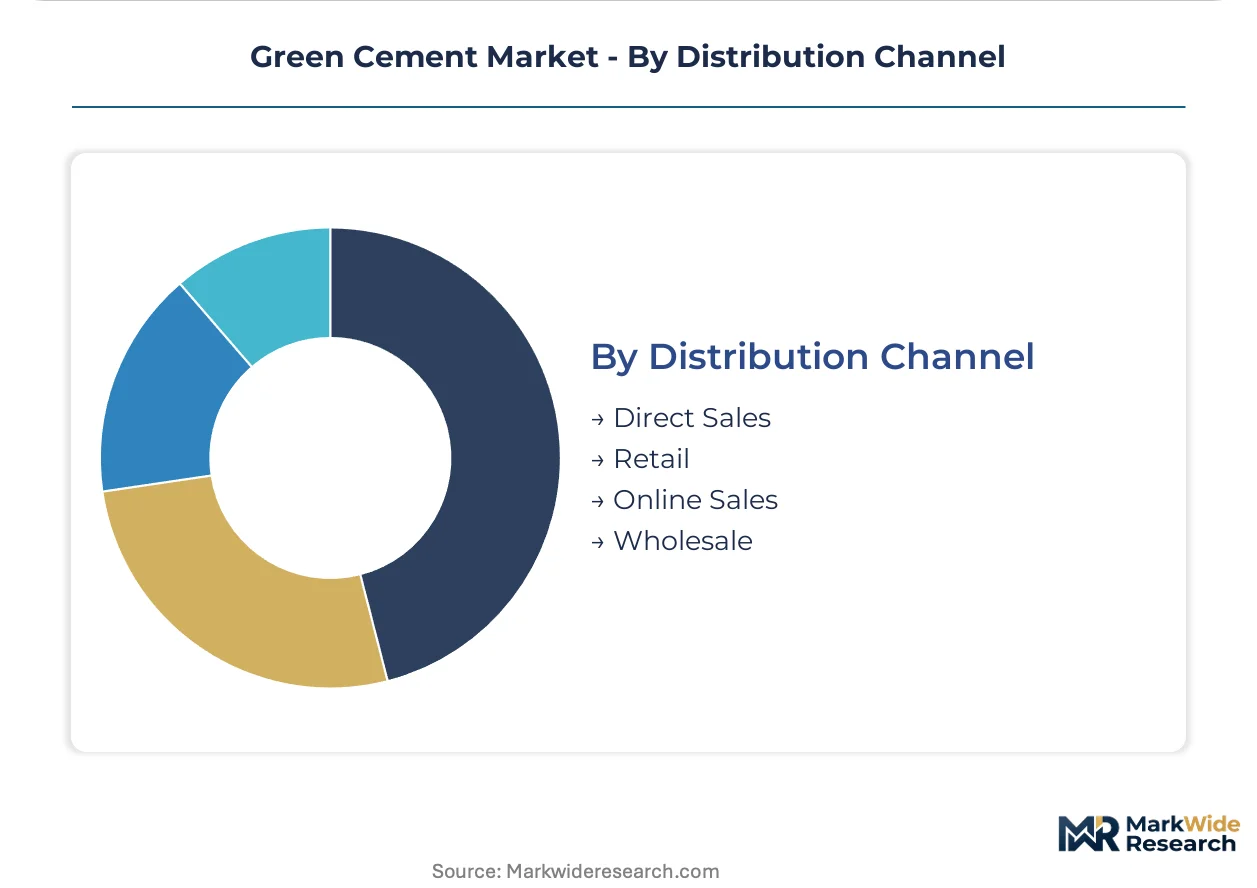
- Direct Sales:Manufacturer-to-contractor relationships for large infrastructure and commercial projects requiring EPD verification and dedicated logistics coordination. Holcim Ltd leverages direct channels for low-carbon binder deployment across multiple geographies, bypassing intermediary margin extraction.
- Wholesale:Regional distributors aggregating demand from multiple contractors and stocking blended cement grades for construction seasonality. UltraTech Cement Ltd dominates South Asian wholesale fly ash distribution through captive thermal power linkages and district-level depot networks.
- Retail:Hardware and building material stores serving residential builders and small contractors with bagged product.
- Online Sales:Digital procurement platforms emerging for standardized grades with documented certification, particularly in European markets with EPD verification requirements.
Wholesale captures the greatest tonnage throughput; Direct Sales is gaining share fastest as carbon documentation requirements concentrate procurement around manufacturer-verified supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian contractors exhibit acute price sensitivity to fly ash blend premiums, while Nordic engineering consultancies absorb higher geopolymer costs to meet embodied carbon thresholds. German buyers face supply-driven volatility as thermal plant retirements tighten SCM availability. UAE infrastructure agencies prioritize rapid strength development over substitution rates.
United States
EPA greenhouse gas reporting requirements under the Clean Air Act compel kiln operators to document process emissions. Infrastructure contractors on federal projects face Buy America compliance layered with carbon disclosure mandates. Texas and California cement terminals are retrofitting for slag grinding to serve Gulf Coast and Pacific megaprojects.
Germany
Heidelberg Materials anchors European production through integrated steel mill slag partnerships. The EU F-Gas Regulation and carbon border adjustment mechanism redirect procurement toward domestic low-carbon blends. The Rhine-Ruhr industrial corridor concentrates precast concrete demand as Dutch and Belgian contractors specify embodied carbon thresholds.
India
National Highway Authority projects drive fly ash blend procurement under BIS clinker-factor grading protocols. State housing boards specify cost-sensitive tender mechanisms for foundations and non-structural elements. Maharashtra and Gujarat cement depots leverage captive thermal power linkages for district-level distribution.
China
Dual carbon goals and GB standards enforcement compress clinker-intensive production margins. Yangtze River Delta infrastructure agencies mandate SCM thresholds for bridge and highway concrete. Anhui province cement clusters are reconfiguring grinding infrastructure around steel mill slag availability.
United Arab Emirates
MOHAP and federal infrastructure procurement prioritize rapid strength development for desert construction timelines. Dubai and Abu Dhabi megaprojects specify sulfate resistance for marine and aggressive soil environments. NEOM construction frameworks are piloting geopolymer formulations for precast element standardization.
Green Cement Market Vendor Landscape
Integrated multinational cement groups and regional blended-material specialists split the market along capital intensity and SCM access lines. The vendor base concentrates around steel mill and thermal power partnerships that secure slag and fly ash feedstock. Three archetypes dominate: captive-utility integrated producers, steel-mill-anchored European operators, and alkaline-activation technology developers. Competitive moves center on slag grinding infrastructure placement and direct sales channel expansion for carbon-verified projects.
Within the multinational integrated tier, Holcim Ltd represents global R&D network deployment across multiple geographies, while Heidelberg Materials exemplifies European slag-processing infrastructure concentration. UltraTech Cement Ltd occupies a position as South Asian fly ash blending capacity anchored to captive thermal power linkages.
| Leading Market Players |
|---|
| Holcim Ltd |
| CEMEX S.A.B. de C.V. |
| Heidelberg Materials |
| UltraTech Cement Ltd |
| CRH plc |
| Anhui Conch Cement |
| Taiheiyo Cement Corporation |
| Votorantim Cimentos S.A. |
| ACC Limited |
| Others |
Supply Flow & Price Mechanics
Rhine-Ruhr slag corridor freight costs compress margins for Dutch precast contractors while amplifying price spreads between certified low-carbon blends and conventional imports. German steel mill partnerships concentrate supply-side leverage, forcing buyers to absorb logistics premiums or shift procurement to domestic geopolymer alternatives with shorter haul distances.
Pricing Analysis
Aftermarket clinker substitution consulting revenue is narrowing as manufacturers internalize technical advisory functions. Three-tier pricing structure across premium EPD-verified, standard blended, and economy Portland-equivalent grades reflects certification investment and carbon disclosure burden. Cost compression in economy tiers intensifies because Indian state housing boards enforce cost-plus tender mechanisms with minimal quality differentiation. Infrastructure contractors exhibit acute price sensitivity, while Nordic engineering consultancies absorb geopolymer premiums to meet embodied carbon thresholds.
Supply Chain Analysis
Extended payment terms from German steel mills anchor slag procurement financing for Heidelberg Materials' integrated grinding operations. Supply concentrates in India, Germany, and China, with each hub drawing from distinct feedstock ecosystems: captive thermal power linkages, steel mill partnerships, and Yangtze River Delta industrial clustering respectively. Raw material dependencies center on fly ash from coal generation, blast-furnace slag from integrated steel production, and calcined clay from kaolin processing. Single-source vulnerability runs through German thermal plant retirements constraining regional SCM availability. Distribution runs through manufacturer-direct channels for carbon-verified projects and wholesale depots for cost-sensitive residential construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green cement procurement is approaching a platform-economics inflection as ISO 14025 EPD verification becomes the interoperability standard for cross-border project eligibility. Ecosystem consolidation around third-party certification infrastructure is compressing supplier qualification lists and amplifying returns to integrated data systems.
For Market Incumbents: Pre-empt CSA cement substitution threats by accelerating geopolymer precast capacity in the Netherlands and Belgium. Anchor slag grinding infrastructure adjacent to Rhine-Ruhr steel mills to defend logistics cost position against emerging alkaline-activation specialists. Certification investment in ISO 14025-compliant EPD infrastructure represents the priority defensive lever as French public works mandates tighten.
For New Entrants and Emerging Players: Establish a beachhead in rural Indian district-level markets where state thermal plants generate surplus fly ash but blended cement penetration remains underdeveloped. Target Maharashtra and Gujarat depot networks with cost-optimized fly ash formulations for state housing board tenders. Go-to-market execution should leverage direct contractor relationships bypassing established wholesale channels with documented BIS grading compliance.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational cement groups divesting non-core regional blending operations lacking integrated SCM access. Long-term viability over the next decade hinges on captive feedstock control and carbon capture retrofit optionality. The signal to watch is EU ETS premium credit pricing for negative-emission product lines, which would revalue oxyfuel-ready kiln assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Slag Grinding Capacity Expansion | Heidelberg Materials anchors European supply security through integrated steel mill partnerships. |
| Carbon Capture Integration | Post-combustion amine scrubbing creates negative-emission product lines qualifying for EU ETS credits. |
| Geopolymer R&D Partnership | Alkaline activation chemistry maturation enables precast concrete applications with clinker elimination. |
| Direct Sales Channel Development | Holcim Ltd bypasses intermediary margin extraction for carbon-verified infrastructure projects. |
| Captive Thermal Power Linkage | UltraTech Cement Ltd secures fly ash feedstock cost advantage through district-level depot networks. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cement plant managers, EPC procurement leads on National Highway Authority projects, structural engineers at Nordic consultancies, and distribution channel partners in Maharashtra and Gujarat. Secondary validation drew from Bureau of Indian Standards grading protocols, EU F-Gas Regulation documentation, EPA Clean Air Act filings, and steel mill slag availability reports. Bottom-up volume modeling triangulated against top-down carbon intensity projections across the analysis window.
Calibration anchored volume and value outputs to documented clinker-factor reduction trajectories under tightening regulatory mandates. Segmentation dimensions modeled include formulation chemistry, project delivery method, professional role in procurement decisions, and distribution channel structure. CAGRs were derived from elasticity-adjusted demand curves incorporating infrastructure spending patterns and public procurement threshold enforcement. Industry-specific forecast inputs centered on thermal power plant retirement schedules and steel mill slag output correlations.
Stress conditions across SCM availability disruptions, EU carbon border adjustment tariff implementation, and geopolymer compressive strength validation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory tightening trajectories and feedstock concentration. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Eco Flooring Market
Green Building Materials
Green Silica Market
Green Building Materials
Eco-Friendly Tiles Market
Green Building Materials
Green Roof Market
Green Building Materials
Sustainable Construction Market
Green Building Materials
China Green Building Materials Market
Green Building Materials
Solar Glass Market
Green Building Materials
Sustainable and Green Building Materials Market
Green Building Materials
Green Coatings Market
Green Building Materials
Global Eco-Friendly Green Roofs Market
Green Building Materials
Eco-Friendly Bitumen Market
Green Building Materials
Green Building Market
Green Building Materials
Green Rebar Market
Green Building Materials
Green Building Materials Market
Green Building Materials
APAC Green Buildings Market
Green Building Materials
North America Green Buildings Market