
 Green Silica Market | 2026-2036
Green Silica Market Size, Share, and Industry Trends Forecast 2026-2036
Green Silica Market Outlook
REACH is recalibrating the cost-of-entry calculus for imported silica into European manufacturing supply chains. Evonik Industries AG leverages its precipitated silica specialization to anchor premium positioning in pharmaceutical-grade applications. Dow Corporate sustains broad geographic coverage through integrated silicate chemistry platforms. Biosilico competes on feedstock circularity, converting agricultural waste streams into high-purity silica for industrial buyers.
Green silica denotes amorphous silicon dioxide produced from bio-based or recycled feedstocks rather than conventional quartz mining, typically achieving surface areas of 150–300 m²/g through controlled precipitation or thermal processing. It functions primarily as a reinforcing filler in rubber compounding, a viscosity modifier in coatings, and an anti-caking agent in food systems. Precipitated silica dominates volume flows due to mature production infrastructure and established tire industry qualification protocols. Spray-dried grades command margin premiums in cosmetics and pharmaceuticals where particle morphology directly impacts formulation stability. Fumed silica occupies a specialized niche in high-performance coatings, though its energy-intensive manufacturing constrains green credentialing.
EPA industrial emissions guidelines and China's MEE dual carbon enforcement are tightening feedstock provenance documentation requirements across export markets. ECHA substance evaluation protocols now require lifecycle carbon disclosures for silica used in consumer-facing applications. Stakeholders must monitor evolving bio-based content certification schemes to preserve market access in regulated jurisdictions.
Market Dynamics
Automotive OEMs in Germany have mandated recycled-content verification for tire suppliers, compressing qualification timelines and forcing precipitated silica producers to reengineer feedstock provenance systems ahead of contract renewals.
Growth Catalysts
- EU REACH carbon thresholds:Tightening lifecycle disclosure requirements for silica in consumer-facing applications are compelling tire manufacturers to source rice husk-derived alternatives.
- Rubber compounding demand:Reinforcing filler specifications for fuel-efficient tire grades are accelerating qualification of bio-based precipitated silica with surface areas of 150–300 m²/g.
- China's MEE dual carbon enforcement:Export documentation requirements for carbon-intensive materials are redirecting domestic silica capacity toward agricultural waste feedstock conversion.
Market Restraints
- Energy input cost volatility:Thermal processing of rice husk ash requires sustained natural gas or biomass energy inputs, exposing margins to feedstock energy price swings.
- Technical purity ceilings:Agricultural silica carries trace metal contaminants that constrain qualification for pharmaceutical-grade spray-dried applications.
- Fumed silica substitution resistance:High-performance coatings segments retain preference for energy-intensive fumed grades where particle morphology requirements exceed precipitation process capabilities.
Strategic Opportunities
- Cosmetics formulation expansion:Spray-dried green silica with controlled particle morphology is penetrating premium skincare and color cosmetic segments previously served by mined quartz derivatives.
- India PLI scheme alignment:Domestic tire manufacturing incentives are creating localized demand for agricultural waste-derived silica within South Asian supply chains.
- Co-processing technology convergence:Integration of pyrolysis and precipitation unit operations is enabling integrated biorefineries to extract silica alongside biochar and energy products.
Industry Challenges
- Feedstock logistics reconfiguration:Seasonal rice husk availability requires multi-source contracting and regional pre-processing infrastructure that strains working capital.
- ECHA substance evaluation timelines:Extended dossier review periods for novel bio-based silica variants are delaying market access for qualified producers.
- Cross-contamination control:Shared equipment between conventional quartz-derived and green silica production lines demands validated cleaning protocols to preserve certification integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Silica Market |
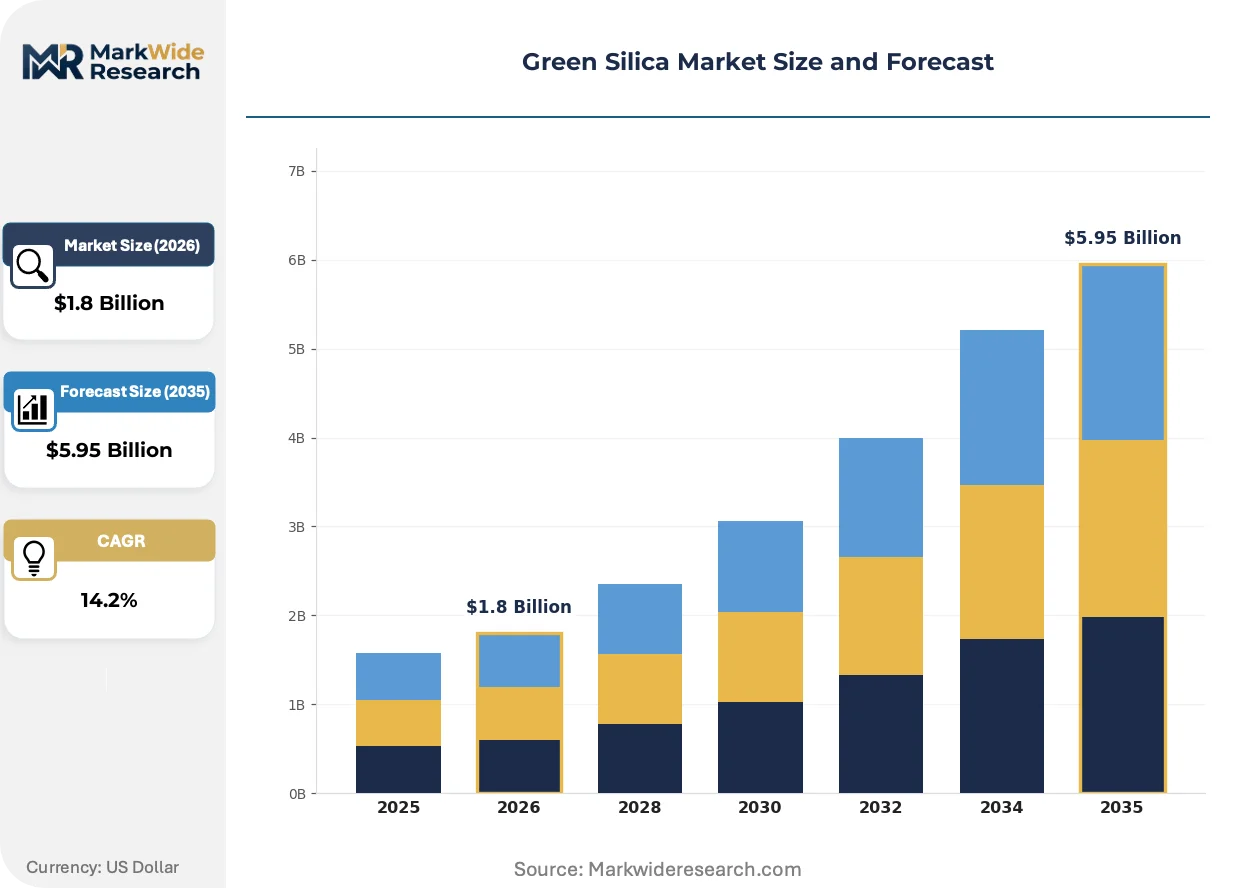
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray-Dried, Fumed, Precipitated, Dried Application: Food & Beverage, Pharmaceuticals, Cosmetics, Paints & Coatings End User: Chemical Industry, Food Industry, Healthcare Sector, Construction Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Biosilico, Brisil, Evonik Industries AG, Katyayani Organic, Green Vision Silica, Dow Corporate, Green Silica, Palamatic Process, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Silica Market Strategic Shifts
Processing technology maturation and regulatory documentation requirements are converging to redefine competitive differentiation around verified carbon intensity rather than traditional performance metrics alone.
Controlled precipitation from rice husk ash leachate is absorbing capital allocation previously directed toward conventional sodium silicate routes. Tire compounders in Germany and Japan are qualifying these grades for rolling-resistance-optimized tread formulations. The technology is absorbing margin pressure from energy-intensive fumed alternatives by offering comparable reinforcement indices at lower documented carbon intensity.
ECHA substance evaluation protocols now require lifecycle carbon disclosures for silica incorporated into consumer-facing products. This documentation burden is filtering supplier bases toward those with integrated feedstock traceability systems. Cosmetics and food-grade applications face the steepest compliance ramps, with spray-dried grades requiring quarterly third-party verification of agricultural waste sourcing.
Automotive OEM procurement teams are consolidating qualified supplier lists around verified recycled-content thresholds. Long-term offtake agreements with fixed-price escalators are displacing spot-market purchasing for tire-grade precipitated silica. Germany's automotive supply chain exhibits the most pronounced concentration, with OEM sustainability scorecards directly weighting silica feedstock circularity in supplier tiering decisions.
Green Silica Market Segmentation
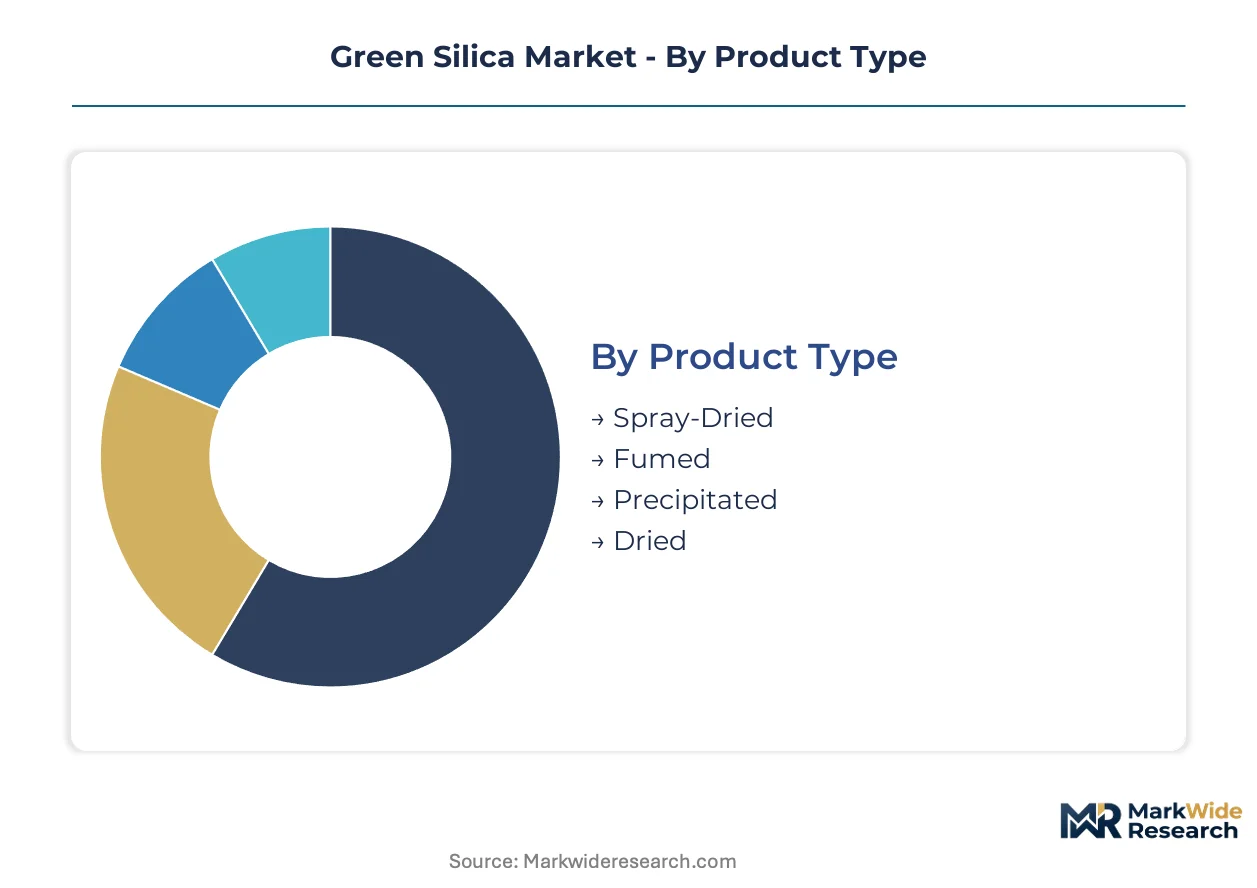
Segmentation in green silica markets tracks how regulatory pressure and end-use qualification requirements split demand across technical grades. Buyers select product types based on surface area specifications and carbon intensity documentation, while application segments diverge around purity thresholds and feedstock provenance systems.
Product Type:
Procurement teams weight surface area performance against verified carbon intensity when selecting among precipitation and thermal processing routes.
- Precipitated:Amorphous silica produced through controlled acid precipitation of sodium silicate or agricultural leachate, achieving surface areas of 150–300 m²/g. Tire manufacturers in Germany have mandated this grade for rolling-resistance-optimized tread formulations, compressing qualification timelines around rice husk feedstock verification.
- Spray-Dried:Atomized silica slurry processed into free-flowing powders with controlled particle morphology. Cosmetics formulators in France and Japan are qualifying these grades for premium skincare applications where particle size distribution directly impacts formulation stability and ECHA lifecycle disclosure requirements apply.
- Fumed:High-purity silica synthesized through flame hydrolysis of silicon tetrachloride, delivering surface areas exceeding 300 m²/g.
- Dried:Conventional silica gel or precipitated products subjected to thermal dehydration without spray atomization.
Volume sits with Precipitated; growth tilts toward Spray-Dried.
Application:
End-use sectors diverge sharply around purity ceilings and documentation burdens, with consumer-facing applications facing steepest compliance ramps.
- Food & Beverage:Anti-caking and free-flow agent applications requiring FSSAI, FDA, and EFSA compliance for direct food contact. India's food processing expansion under PLI scheme alignment is creating localized demand for agricultural waste-derived grades with quarterly third-party sourcing verification.
- Cosmetics:Viscosity modification and texture enhancement in color cosmetics and skincare. Premium brands in France and South Korea are mandating spray-dried green silica with documented bio-based content above threshold levels to satisfy retailer sustainability scorecards.
- Pharmaceuticals:Glidant and disintegrant functions in tablet formulations requiring pharmacopeial compliance.
- Paints & Coatings:Matting agent and rheology control applications spanning architectural and industrial formulations.
Revenue concentrates in Food & Beverage; Cosmetics shows the steepest expansion trajectory.
End User:
Industry buyers vary in technical specification stringency and contract structures, from spot purchasing to multi-year offtake agreements with fixed-price escalators.
- Chemical Industry:Intermediate processing and specialty chemical manufacturing consuming precipitated grades as feedstock for downstream silicate derivatives. German automotive supply chain concentration is driving consolidation of qualified supplier lists around verified recycled-content thresholds.
- Healthcare Sector:Medical device and pharmaceutical manufacturing requiring ISO 13485 traceability and pharmacopeial certification. EMA and FDA documentation requirements for excipient-grade silica are filtering supplier bases toward integrated feedstock traceability systems.
- Food Industry:Direct incorporation into processed food matrices and packaging materials.
- Construction:Concrete admixture and coating additive applications with lower purity requirements.
Contract value peaks with Chemical Industry; qualification velocity favors Healthcare Sector.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and feedstock provenance documentation needs.
- Direct Sales:Manufacturer-to-manufacturer relationships for tire and pharmaceutical compounders requiring dedicated technical service and customized specification development. Automotive OEM procurement teams in Germany and Japan are consolidating volumes through long-term direct agreements with fixed-price escalators displacing spot-market purchasing.
- Distributors:Regional inventory positioning for mid-volume buyers across coatings and cosmetics segments. Seasonal rice husk availability is forcing distributors to maintain multi-source contracting and regional pre-processing infrastructure that strains working capital.
- Online:E-procurement platforms serving research-scale and pilot-batch buyers with standardized grades.
- Retail:Small-package sales to artisan food producers and independent cosmetics formulators.
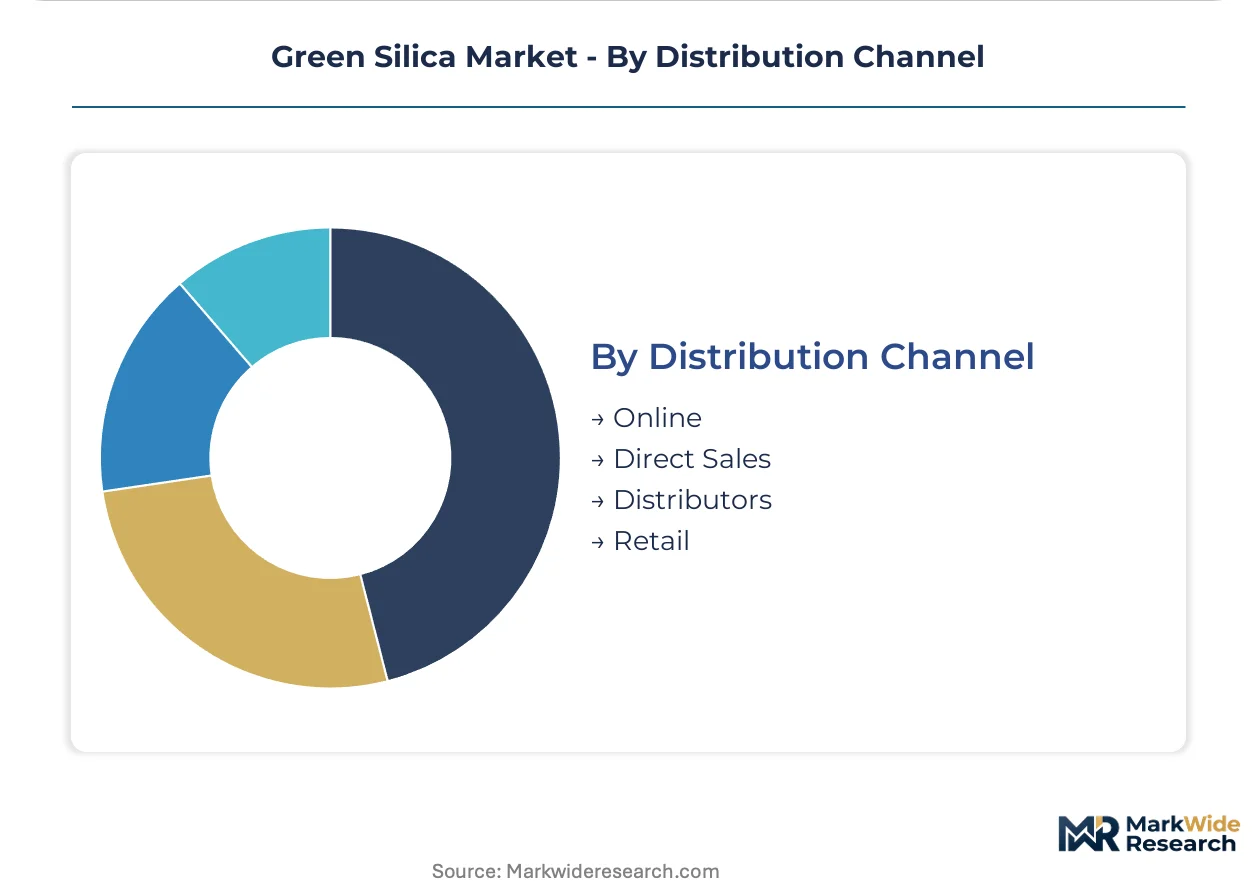
Transaction volume flows through Distributors; margin capture concentrates in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement in Germany and tire manufacturing expansion in India concentrate demand-side momentum for agricultural waste-derived silica, while regulatory enforcement in China and Japan redirects domestic capacity toward bio-based feedstock conversion.
Germany
Volkswagen, BMW, and Mercedes-Benz procurement teams have mandated recycled-content verification thresholds for tire suppliers, compressing qualification timelines for precipitated silica producers. REACH lifecycle disclosure requirements for consumer-facing applications filter supplier bases toward integrated feedstock traceability systems. The Ruhr industrial corridor hosts concentrated rubber compounding operations serving OEM sustainability scorecards.
China
Domestic tire manufacturers are accelerating rice husk silica procurement to meet export documentation requirements for carbon-intensive materials under MEE dual carbon enforcement. GB standards on industrial emissions tighten feedstock provenance verification for silica destined for European markets. The Yangtze River Delta agglomerates precipitated silica capacity alongside agricultural waste preprocessing infrastructure.
India
PLI scheme incentives for domestic tire manufacturing create localized demand pull for agricultural waste-derived silica within South Asian supply chains. FSSAI compliance requirements for food-grade applications necessitate quarterly third-party verification of rice husk sourcing. Gujarat and Maharashtra industrial clusters concentrate spray-dried silica production for cosmetics and food processing segments.
Japan
Bridgestone and Yokohama Rubber procurement specifications prioritize documented carbon intensity reductions in reinforcing filler selections. METI industrial decarbonization guidelines redirect domestic chemical producers toward bio-based silica precipitation routes. The Kansai region maintains specialized compounding facilities qualifying rice husk-derived grades for premium tire formulations.
United States
EPA industrial emissions guidelines tighten documentation requirements for silica imports used in automotive and consumer product applications. Dow Corporate and specialty chemical producers leverage integrated silicate chemistry platforms to sustain broad geographic coverage. The Gulf Coast petrochemical corridor experiments with co-processing pyrolysis and precipitation technologies for integrated biorefinery configurations.
Green Silica Market Competitive Environment
German producers anchor one tier through specialized precipitated silica manufacturing; Indian agricultural waste processors hold feedstock circularity advantages. The vendor base splits between integrated chemical conglomerates with silicate chemistry platforms and dedicated bio-based specialists converting rice husk ash. Three archetypes dominate: diversified multinationals with broad geographic coverage, regional feedstock-integrated specialists, and technology licensors enabling third-party capacity conversion. Competitive moves concentrate on long-term offtake agreements with fixed-price escalators and backward integration into agricultural waste preprocessing infrastructure.
Within the diversified multinational tier, Evonik Industries AG and Dow Corporate exemplify integrated silicate chemistry platforms sustaining premium positioning across pharmaceutical and industrial applications. Among dedicated bio-based specialists, Biosilico occupies a position representing feedstock circularity advantages through agricultural waste stream conversion. These three companies illustrate the competitive tension between established precipitation expertise and emerging bio-based qualification protocols reshaping supplier tiering decisions.
| Leading Market Players |
|---|
| Biosilico |
| Brisil |
| Evonik Industries AG |
| Katyayani Organic |
| Green Vision Silica |
| Dow Corporate |
| Green Silica |
| Palamatic Process |
| Solvay |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between pharmaceutical spray-dried and tire-grade precipitated silica manifests in divergent margin structures and supply chain footprints. ECHA lifecycle disclosure requirements impose documentation cost burdens that stratify pricing across feedstock traceability tiers while compressing spot-market liquidity for unverified grades.
Pricing Analysis
Volume concentrates in contract-based long-term offtake agreements for tire-grade precipitated silica, while margin capture tilts toward spray-dried cosmetics grades commanding premium positioning through quarterly third-party bio-based verification. Price differentiation rests on certification level and volume scale, with automotive OEM procurement teams least sensitive to unit cost given sustainability scorecard weightings. Cost compression in standard precipitated grades is intensifying as rice husk preprocessing capacity expansion outpaces qualified demand growth.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale tire manufacturer demand through dedicated technical service relationships, while regional distributors serve mid-volume cosmetics and coatings buyers. Supply concentrates in Germany, China, and India, with raw material dependencies on seasonal rice husk availability, natural gas or biomass thermal inputs, and acid precipitation reagents. Single-source vulnerability in agricultural waste preprocessing infrastructure poses structural risk given monsoon-dependent harvest cycles. Distribution runs through direct sales for qualified automotive compounders and distributor networks for fragmented cosmetics formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where ECHA substance evaluation protocols erect barrier-to-entry moats favoring incumbents with integrated feedstock traceability systems.
For Market Incumbents: Extend backward integration into regional rice husk preprocessing infrastructure to defend margin position against emerging agricultural waste specialists. Lock automotive OEM procurement teams into multi-year direct agreements with fixed-price escalators before contract renewal windows compress. Prioritize spray-dried capacity expansion for cosmetics applications where ECHA lifecycle disclosure requirements filter competitor bases most aggressively. For New Entrants and Emerging Players: Co-processing technology convergence offers entry leverage through integrated biorefinery configurations extracting silica alongside biochar and energy products. Target India's PLI scheme-aligned tire manufacturing expansion where localized agricultural waste preprocessing infrastructure remains underdeveloped. Pursue distributor partnerships rather than direct sales to avoid working capital strain from seasonal feedstock logistics. For Investors and Strategic Acquirers: Re-rating potential sits with feedstock-integrated specialists given EU REACH carbon threshold tightening and automotive OEM recycled-content mandate acceleration. Five-to-ten-year viability favors producers with validated cross-contamination control protocols and multi-source rice husk contracting. Monitor ECHA dossier review timeline acceleration as inflection signal for market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rice Husk Preprocessing | Captures margin from seasonal availability volatility while satisfying ECHA traceability requirements. |
| Long-term Supply Agreement with Automotive OEMs | Locks volume through sustainability scorecard alignment ahead of supplier list consolidation. |
| Spray-Dried Capacity Expansion for Cosmetics | Penetrates premium skincare segments where particle morphology commands formulation stability premiums. |
| Co-processing Technology Licensing | Enables biorefinery operators to extract silica alongside biochar without greenfield capital deployment. |
| Quarterly Third-Party Verification Program | Satisfies FSSAI and EFSA compliance for food-grade applications under tightening provenance documentation. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with tire compounder procurement leads, cosmetics formulator R&D directors, rice husk preprocessing plant managers, and agricultural waste supply chain coordinators. Bottom-up volume triangulation across precipitation, spray-dried, and fumed product grades converged with top-down demand validation from automotive OEM sustainability scorecards and ECHA substance evaluation dossiers.
Segment-level granularity modeled surface area specifications, feedstock provenance tiers, and end-use qualification requirements across the projection horizon. CAGRs derived from regression analysis of historical capacity expansion patterns and regulatory enforcement trajectory. Industry-specific forecast inputs included seasonal rice husk harvest cycles, natural gas price volatility assumptions, and ECHA review timeline probability distributions.
Several conditions sit outside the modeled scope, including unannounced revisions to EU REACH carbon intensity thresholds, breakthroughs in fumed silica energy efficiency, and geopolitical disruptions to agricultural waste trade flows. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and feedstock logistics infrastructure development. Periodic stress-testing of base assumptions is recommended given energy input cost volatility and evolving bio-based content certification scheme requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Solar Frames Market
Green Building Materials
Eco-Friendly Tiles Market
Green Building Materials
Global Green Walls Market
Green Building Materials
Global Eco-Friendly Green Roofs Market
Green Building Materials
Green Rebar Market
Green Building Materials
GCC Green Cement Market
Green Building Materials
North America Green Cement Market
Green Building Materials
Green Roof Market
Green Building Materials
Eco Flooring Market
Green Building Materials
Green Concrete Market
Green Building Materials
Green Building Materials Market
Green Building Materials
Energy Efficient Window and Door Market
Green Building Materials
Outdoor Flooring Market
Green Building Materials
APAC Green Buildings Market
Green Building Materials
United States Green Cement Market
Green Building Materials
Eco-Friendly Bitumen Market