
 Green Building Materials Market | 2026-2036
Green Building Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Green Building Materials Market Analysis
The specification channel between architects and material distributors is narrowing as large projects consolidate procurement through pre-approved vendor lists. Saint-Gobain S.A. leverages its integrated glass and insulation portfolio to control specification pipelines across European commercial towers. Kingspan Group plc anchors its position through cold-storage and facade system dominance in North American data center construction. Owens Corning competes on fiberglass insulation scale while extending its geographic footprint through regional manufacturing density.
Green building materials encompass engineered products and naturally sourced substances formulated to minimize embodied carbon, energy consumption, and environmental toxicity across a structure's lifecycle. These materials typically incorporate recycled content percentages above 30 percent, achieve Cradle to Cradle or BREEAM certification, and perform to thermal conductivity standards below 0.040 W/mK for insulation applications. Insulation commands the deepest margin pools due to code-mandated R-value escalations and retrofit volume, while wall panels represent the fastest-growing category as mass timber and compressed earth block systems displace conventional framing. Bamboo and hempcrete materials attract capital in residential applications where biogenic carbon sequestration qualifies for green mortgage rate reductions.
The EU Green Deal and REACH frameworks restrict formaldehyde emissions and mandate environmental product declarations for construction materials sold across member states. The EPA's ENERGY STAR and LEED certification systems in the United States create tiered market access where uncertified products face de facto exclusion from institutional procurement. Stakeholders must monitor evolving embodied carbon accounting rules, as regulators in multiple jurisdictions shift from operational to whole-lifecycle emissions metrics.
Market Dynamics
The EU Green Deal's embodied carbon thresholds are compressing specification timelines for commercial developers, forcing material distributors to pre-certify entire product lines before bidding on public infrastructure tenders.
Growth Catalysts
- Near-zero-energy mandates:Germany's federal building code revisions require passive-house-equivalent performance for new construction, pulling demand for triple-glazed facades and mineral wool insulation systems.
- REACH formaldehyde restrictions:ECHA's tightened emission limits for construction adhesives and resins are disqualifying conventional particleboard from institutional procurement across EU member states.
- Data center thermal loads:Hyperscale cloud operators in Northern Virginia and Frankfurt are specifying bio-based insulation with fire ratings above Euroclass B to meet corporate net-zero commitments.
Market Restraints
- Portland cement price volatility:Energy-intensive clinker production faces natural gas cost swings and EU ETS carbon allowance expenses that compress margins for low-carbon concrete alternatives.
- Mass timber supply concentration:Cross-laminated timber production clusters in Austria and Finland, creating lead-time risks for North American developers seeking to displace steel framing.
- Technical limitation in hempcrete:Variable compressive strength and extended curing periods restrict structural load-bearing applications to single-family residential envelopes.
Strategic Opportunities
- Retrofit volume in France:MaPrimeRénov subsidies for building envelope upgrades create certified installation demand for aerogel and vacuum insulation panels in aging Parisian housing stock.
- Green mortgage rate linkages:UK lenders are pricing biogenic material content into residential loan terms, rewarding bamboo flooring and straw bale construction with basis-point reductions.
- Digital product passport mandates:EU CSRD reporting requirements will force environmental product declaration standardization, favoring manufacturers with blockchain-tracked supply chain data.
Industry Challenges
- Embodied carbon accounting skill gaps:Lifecycle assessment expertise remains concentrated among specialized consultancies, slowing contractor adoption of whole-building carbon tools.
- Capex intensity for regional manufacturing:Mineral wool and fiberglass production requires furnace investments exceeding $200 million, limiting geographic diversification for insulation suppliers.
- Multi-certification timeline compression:BREEAM, LEED, and Cradle to Cradle parallel review processes extend product launch cycles by 14-18 months for novel bio-based formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Building Materials Market |
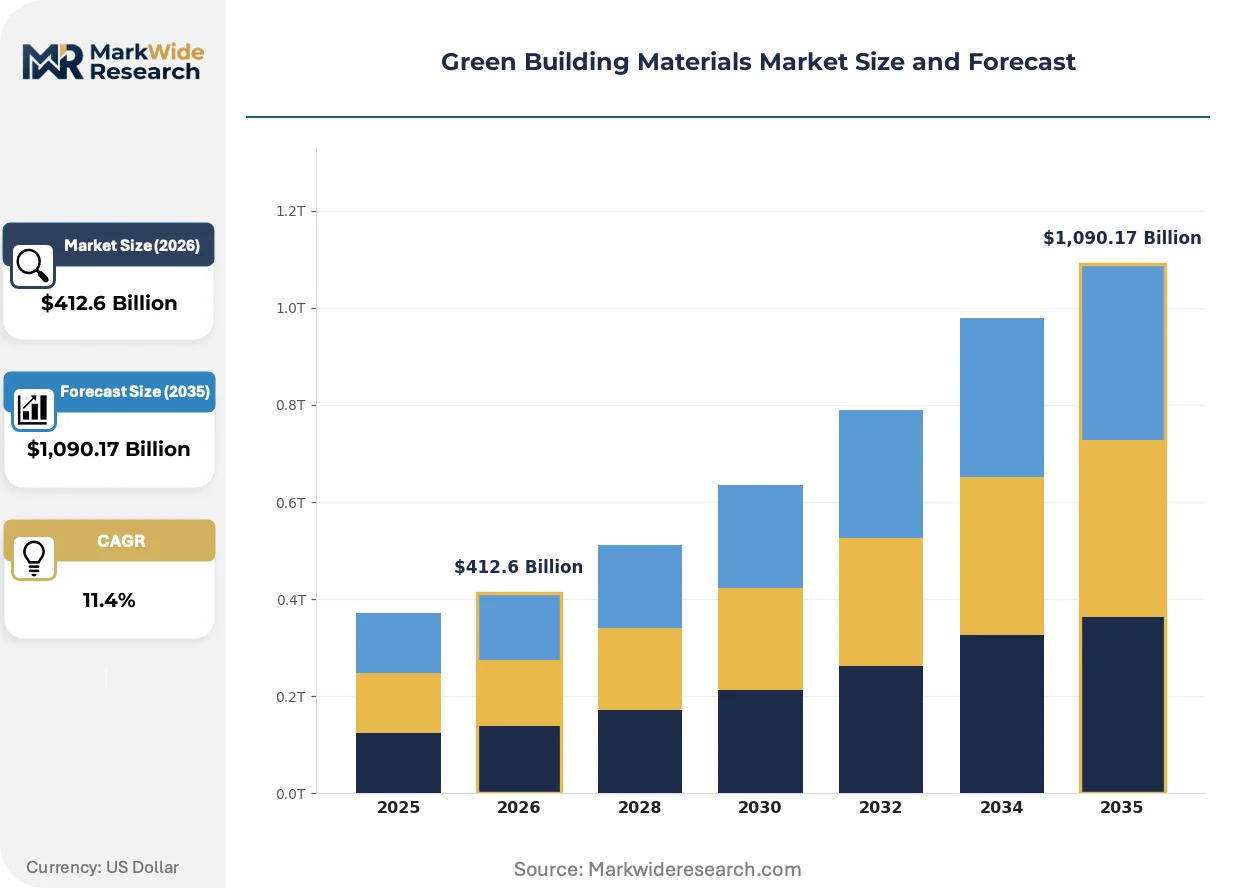
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $1,090.17 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulation, Flooring, Wall Panels, Roofing Material: Bamboo, Recycled Steel, Hempcrete, Glass Application: Residential, Commercial, Infrastructure, Industrial Technology: Passive Solar, Rainwater Harvesting, Energy Monitoring, Green Roof Systems |
| Companies Covered | Saint-Gobain S.A., Kingspan Group plc, Owens Corning, BASF SE, Holcim Ltd, Rockwool International A/S, Armstrong World Industries, Sika AG, Knauf Insulation GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Building Materials Market Emerging Trajectories
Material science convergence is collapsing traditional category boundaries as thermal performance, structural integrity, and carbon sequestration become simultaneous specification requirements rather than trade-offs.
Cross-laminated timber is hybridizing with steel connection systems to create hybrid structural modules that satisfy seismic codes in Japanese commercial towers while maintaining biogenic carbon credits. Mid-rise office developers in Tokyo and Osaka are specifying these systems to meet METI's 2030 decarbonization roadmap. The technology is compressing conventional steel-concrete hybrid timelines by enabling offsite fabrication with reduced crane-time requirements.
EPA's ENERGY STAR Multifamily New Construction protocol now mandates whole-building airtightness testing, forcing insulation contractors to integrate blower-door verification into standard installation workflows. The regulation is elevating spray foam and continuous exterior insulation systems over batt alternatives in US rental housing developments. Affordable housing authorities in California and New York are responding by consolidating procurement through performance-based contractor prequalification.
Specification authority is migrating from individual architects to consolidated owner-operator procurement teams managing multi-asset portfolios. Large European commercial real estate investment trusts are displacing traditional distributor relationships with direct manufacturer contracts tied to embodied carbon benchmarks. This concentration is most visible in German and Dutch logistics warehouse construction, where single-source facade system agreements now span 50,000 square meter minimum commitments.
Green Building Materials Market Segmentation
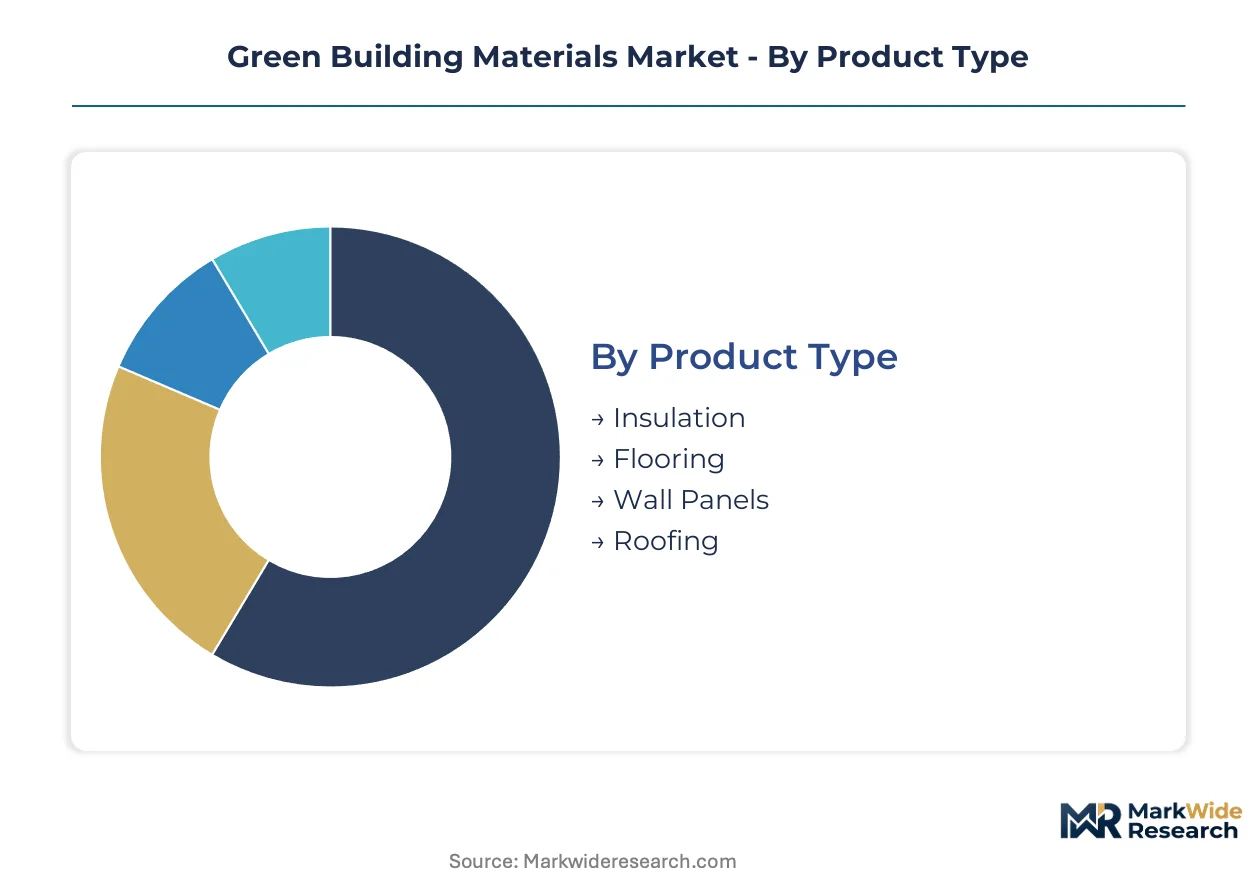
Product configuration in green building materials determines regulatory compliance pathways and margin capture. Material composition governs carbon accounting eligibility and certification tier access. Application context shapes procurement authority and specification timelines across project types.
Product Type:
Cost tier differentiation separates code-mandated thermal performance from premium envelope systems and emerging structural alternatives.
- Insulation:Mineral wool, fiberglass, and bio-based foams achieve thermal conductivity below 0.040 W/mK. German passive-house mandates and Virginia data center construction pull specification volume for mineral wool systems with Euroclass A fire ratings.
- Wall Panels:Cross-laminated timber, compressed earth block, and prefabricated facade modules displace conventional framing. Mass timber hybrids in Tokyo commercial towers satisfy METI seismic codes while capturing biogenic carbon credits.
- Flooring:Bamboo, cork, and reclaimed hardwood systems qualify for UK green mortgage rate reductions based on biogenic content thresholds.
- Roofing:Cool roof membranes, vegetated systems, and solar-integrated tiles manage urban heat island effects.
Insulation commands the established base. The steepest expansion runs through wall panels.
Material:
Supply concentration and carbon sequestration potential create divergent procurement economics across feedstock categories.
- Bamboo:Rapid-growth grass species achieve structural density comparable to hardwood in 3-5 year harvest cycles. UK residential lenders price bamboo flooring content into green mortgage terms, rewarding basis-point reductions for biogenic material share.
- Recycled Steel:Electric arc furnace production slashes embodied carbon versus blast furnace routes. Infrastructure tenders in Germany and the Netherlands specify minimum recycled content for bridge and transit structures.
- Hempcrete:Lime-bound hemp shiv creates carbon-negative masonry with variable compressive strength. Extended curing periods restrict load-bearing applications to single-family residential envelopes in France and Belgium.
- Glass:Low-iron formulations and vacuum glazing advance facade thermal performance. Triple-glazed units satisfy Germany's federal near-zero-energy code for new construction.
Recycled steel anchors industrial procurement. Hempcrete climbs fastest in residential carbon-negative positioning.
Application:
Customer type and project scale determine specification authority consolidation and certification stringency.
- Commercial:Office towers, logistics warehouses, and retail developments consolidate procurement through owner-operator direct contracts. German and Dutch REITs mandate 50,000 square meter minimum facade system commitments tied to embodied carbon benchmarks.
- Residential:Single-family and multifamily construction respond to mortgage-linked green incentives. California and New York affordable housing authorities consolidate insulation procurement through performance-based contractor prequalification.
- Infrastructure:Public tenders impose environmental product declaration requirements under EU Green Deal thresholds.
- Industrial:Manufacturing facilities and cold-storage operations specify bio-based insulation with fire ratings above Euroclass B.
Commercial development concentrates specification authority. Residential applications gain share fastest through financial incentive linkage.
Technology:
Maturity gradients separate proven building-integrated systems from emerging digital and ecological infrastructure.
- Passive Solar:Orientation-optimized glazing and thermal mass design reduce mechanical load. German building code revisions mandate passive-house-equivalent performance, pulling demand for triple-glazed facades.
- Green Roof Systems:Vegetated assemblies manage stormwater and urban heat. Parisian housing stock retrofits under MaPrimeRénov subsidies create certified installation demand for extensive and intensive systems.
- Rainwater Harvesting:Cistern and permeable surface systems reduce municipal water burden.
- Energy Monitoring:Sensor networks and building management software optimize operational performance.
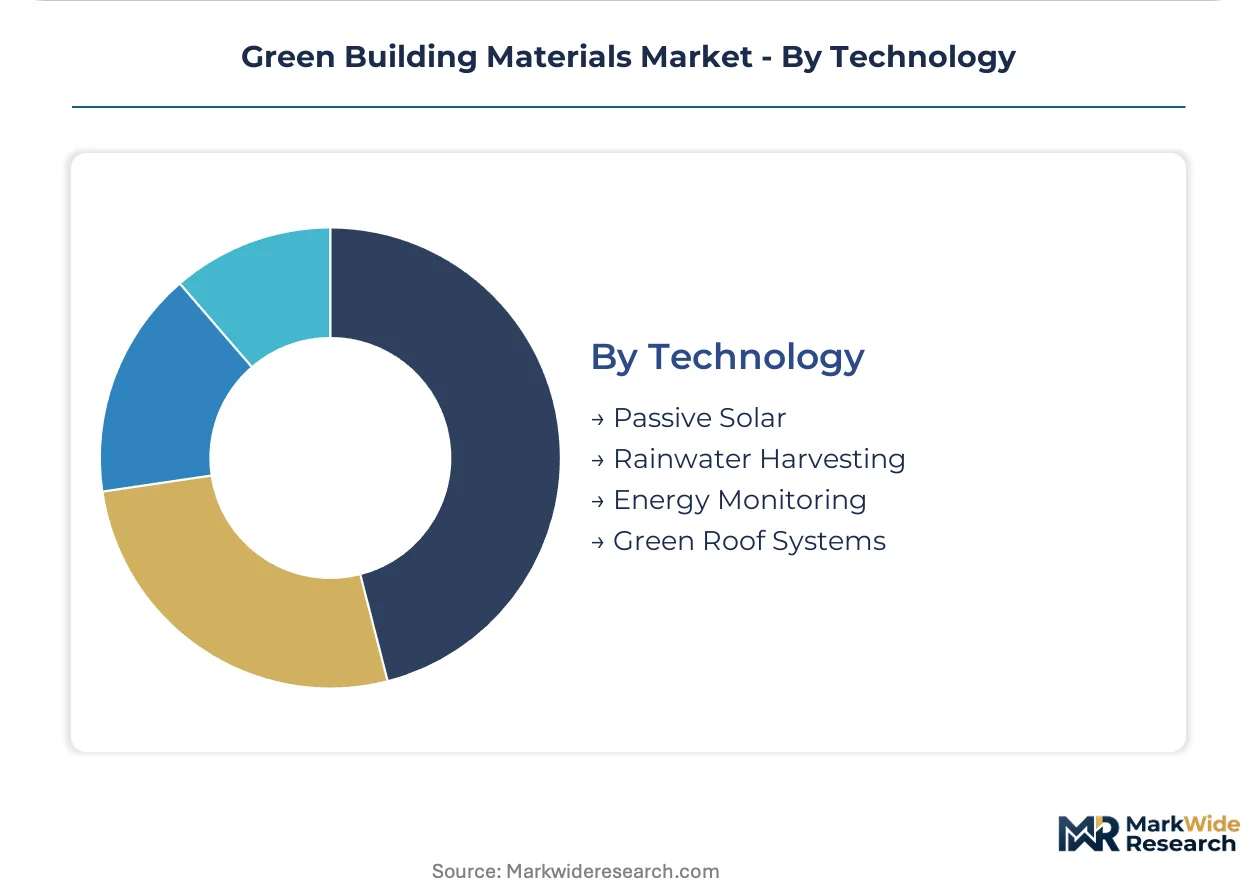
Passive solar commands the established efficiency base. Green roof systems expand most quickly through European retrofit subsidy programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal embodied carbon thresholds anchor procurement specifications across member states, compressing timelines for material distributors seeking public infrastructure access. Germany's federal building code mandates near-zero-energy standards, pulling demand for triple-glazed facades and mineral wool insulation systems. France, the United Kingdom, the United States, and Japan concentrate distinct regulatory incentives and construction clusters that shape regional competitive dynamics.
Germany
Passive-house-equivalent performance requirements under federal building code revisions drive specification of mineral wool systems with Euroclass A fire ratings. The EU Green Deal's embodied carbon thresholds disqualify conventional materials from institutional procurement. Industrial concentration clusters in Bavaria and North Rhine-Westphalia, where REITs consolidate facade system procurement through 50,000 square meter minimum commitments tied to carbon benchmarks.
France
MaPrimeRénov subsidies for building envelope upgrades generate certified installation demand for aerogel and vacuum insulation panels. ECHA's REACH formaldehyde restrictions eliminate conventional particleboard from public tenders. Retrofit activity concentrates in aging Parisian housing stock, where extensive and intensive green roof systems capture stormwater management requirements under municipal climate adaptation plans.
United Kingdom
Green mortgage rate linkages price biogenic material content into residential loan terms, rewarding bamboo flooring and straw bale construction with basis-point reductions. The country's national building regulator enforces tightened energy performance certificates for new construction. Development clusters in London and the Southeast corridor, where owner-operators consolidate procurement authority across multi-asset commercial portfolios.
United States
EPA's ENERGY STAR and LEED certification systems create tiered market access where uncertified products face de facto exclusion from institutional procurement. California and New York affordable housing authorities consolidate insulation procurement through performance-based contractor prequalification. Hyperscale cloud operators in Northern Virginia specify bio-based insulation with fire ratings above Euroclass B to meet corporate net-zero commitments.
Japan
METI's 2030 decarbonization roadmap pulls demand for hybrid structural modules combining cross-laminated timber with steel connection systems. The country's national building standards institute maintains seismic code requirements that shape material specifications. Commercial tower development concentrates in Tokyo and Osaka, where offsite fabrication reduces crane-time requirements and compresses conventional steel-concrete hybrid timelines.
Green Building Materials Market Vendor Landscape
Integrated material conglomerates and specialized insulation manufacturers split the market between specification control and category depth. The vendor base organizes around three strategic archetypes: portfolio-integrated building envelope suppliers, single-category scale producers, and regional bio-based material specialists. Consolidation pressures intensify as owner-operators displace traditional distributor relationships with direct manufacturer contracts. Dominant competitive moves include backward integration into raw material supply and geographic manufacturing density expansion.
Among European-anchored conglomerates, Saint-Gobain S.A. and Kingspan Group plc exemplify divergent archetype positioning within specification pipelines. Saint-Gobain represents the portfolio-integrated model controlling glass and insulation combinations across commercial tower developments. Kingspan occupies a position emphasizing cold-storage and facade system dominance in data center construction. Owens Corning anchors the North American scale-producer tier, competing on fiberglass insulation manufacturing density while extending geographic footprint through regional production networks.
| Leading Market Players |
|---|
| Saint-Gobain S.A. |
| Kingspan Group plc |
| Owens Corning |
| BASF SE |
| Holcim Ltd |
| Rockwool International A/S |
| Armstrong World Industries |
| Sika AG |
| Knauf Insulation GmbH |
| Others |
Supply Flow & Price Mechanics
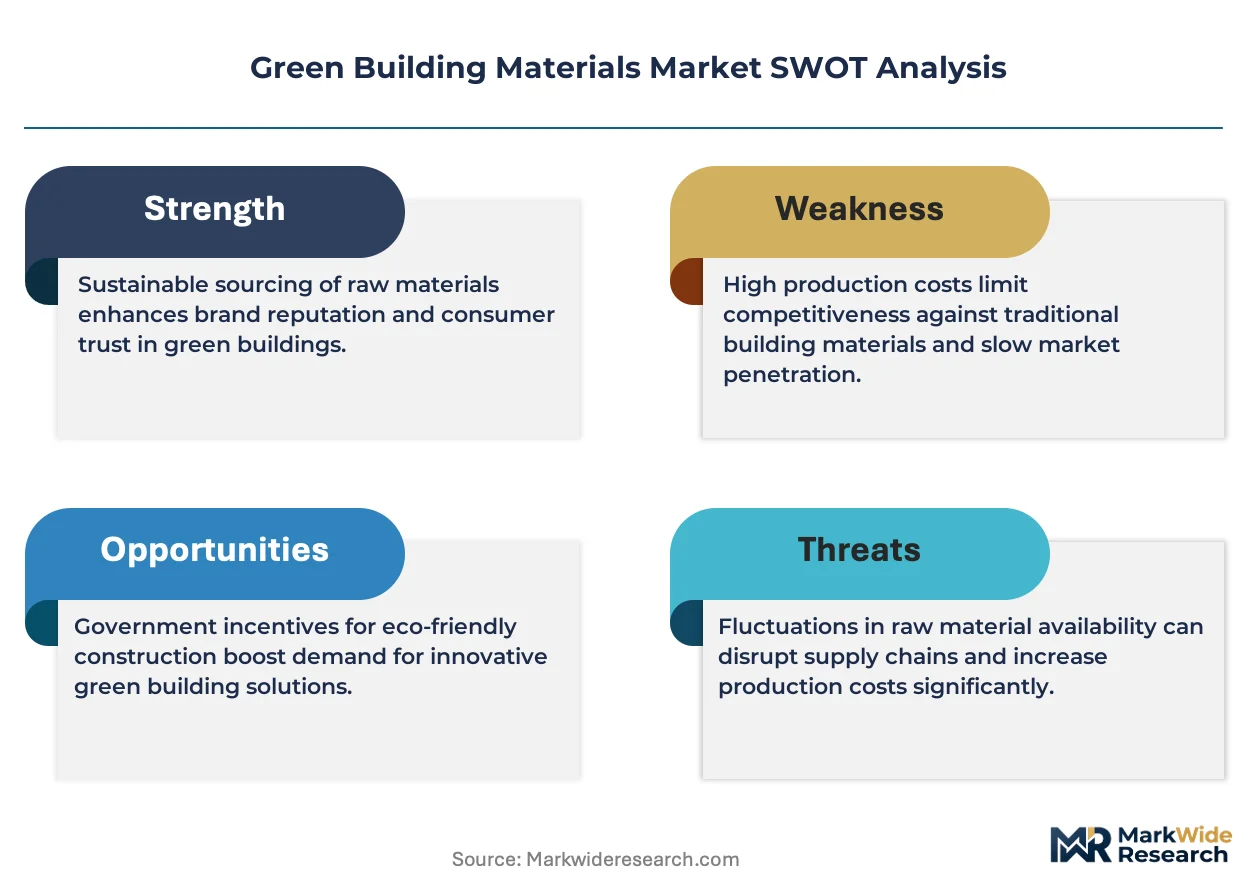
Overcapacity in Chinese fiberglass insulation production is compressing global pricing benchmarks and forcing European manufacturers to defend margin position through carbon-credit differentiation rather than volume scale. This utilization imbalance simultaneously accelerates backward integration into mineral wool feedstocks among incumbent suppliers seeking supply security against energy cost volatility.
Pricing Analysis
Geographic price spreads between German passive-house-certified systems and standard-grade alternatives in Southern Europe exceed 40 percent on a per-square-meter basis. Three-tier pricing structure across premium certified, standard code-compliant, and economy retrofit tiers separates specification authority. Pricing pressure stems from Portland cement cost volatility under EU ETS carbon allowance expenses. Residential retrofit contractors exhibit highest price sensitivity, while data center owner-operators prioritize fire-rated performance over unit cost.
Supply Chain Analysis
Upstream feedstock concentration in Austrian cross-laminated timber and Finnish engineered wood products creates lead-time vulnerability for North American mass timber developers. Raw material dependencies center on industrial hemp cultivation in France, bamboo plantations in China, and recycled steel scrap flows in Germany and the Netherlands. Single-source vulnerability runs through Austrian CLT production clusters. Distribution runs through specification-controlled vendor lists managed by large European REITs and North American data center operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from bio-based insulation formulations capturing green mortgage-linked procurement in UK residential construction. Defense requires building specification moats before certification requirements harden.
For Market Incumbents: Build certification moats by pre-positioning entire product lines for EU Green Deal embodied carbon thresholds before tender deadlines compress. Secure backward integration into low-carbon clinker substitutes to defend margin position against EU ETS cost pass-through. Anchor specification pipelines through direct contracts with German and Dutch logistics REITs.
For New Entrants and Emerging Players: Pursue white-space capture in French MaPrimeRénov retrofit channels where certified installation capacity lags subsidy volume. Target aerogel and vacuum insulation panel segments where incumbent manufacturing scale is weakest. Enter through performance-based contractor prequalification partnerships with affordable housing authorities in California and New York.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mineral wool furnace investments exceeding $200 million per production line. Five-to-ten year viability favors manufacturers with blockchain-tracked supply chain data for EU CSRD digital product passport compliance. Monitor embodied carbon accounting skill gaps as inflection signal—capability scarcity in lifecycle assessment expertise will determine which suppliers capture public infrastructure tenders.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Clinker | Secures margin position against EU ETS carbon allowance cost pass-through. |
| Certification Pre-Positioning for EU Green Deal | Enables bidding on compressed-timeline public infrastructure tenders across member states. |
| Blockchain Supply Chain Tracking | Supports EU CSRD digital product passport mandates for environmental declaration standardization. |
| Direct REIT Contracting | Displaces traditional distributor relationships in German and Dutch logistics warehouse construction. |
| Retrofit Channel Partnership | Captures MaPrimeRénov subsidy volume in aging Parisian housing stock envelope upgrades. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and certification body records across the analysis window. Primary interviews engaged sustainability officers at material conglomerates, specification directors at architectural practices, procurement leads at commercial REITs, and technical directors at insulation contractors. Secondary sources included EU ECHA REACH documentation, EPA ENERGY STAR protocol releases, BREEAM and LEED certification databases, and national building code revisions. Bottom-up project pipeline tracking triangulates against top-down market sizing.
Forecast inputs incorporate product type segmentation by insulation, wall panel, flooring, and roofing categories; material feedstock differentiation across bio-based, recycled, and engineered streams; and application context spanning commercial, residential, infrastructure, and industrial end-uses. CAGRs derive from elasticity modeling against regulatory mandate implementation schedules and retrofit subsidy program allocations. Embodied carbon threshold adoption curves and green mortgage penetration rates inform trajectory assumptions.
Macroeconomic conditions sit as an overlay; deviation in construction output indices, natural gas pricing, and EU ETS allowance auction clearing prices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and certification body capacity expansion. Cross-checking against national building permit databases and REIT capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Solar Windows Market
Green Building Materials
North America Green Buildings Market
Green Building Materials
Eco-Friendly Tiles Market
Green Building Materials
Artificial Green Wall Market
Green Building Materials
Solar Frames Market
Green Building Materials
Non-Residential Green Building Market
Green Building Materials
Sustainable and Green Building Materials Market
Green Building Materials
Global Eco-Friendly Green Roofs Market
Green Building Materials
Green Building Market
Green Building Materials
Sustainable Construction Market
Green Building Materials
Eco Flooring Market
Green Building Materials
Green Concrete Market
Green Building Materials
Eco-Friendly Bitumen Market
Green Building Materials
Global Green Walls Market
Green Building Materials
Outdoor Flooring Market
Green Building Materials
Green Coatings Market