
 Solar Windows Market | 2026-2036
Solar Windows Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Windows Market Outlook
Commercial real estate is expanding as the dominant end-use vertical for solar windows, overtaking early residential pilot programs. Ubiquitous Energy leverages organic photovoltaic coatings to target high-rise retrofits with minimal visual alteration. Onyx Solar Energy anchors the BIPV segment through specialized glazing for airports and stadiums. Physee competes in the Netherlands with smart window systems that combine energy harvesting with climate control.
Solar windows integrate photovoltaic layers into transparent or semi-transparent glazing to generate electricity while maintaining visible light transmission, typically achieving 10-40% efficiency depending on cell chemistry and transparency ratio. Thin-film and perovskite technologies lead product development due to superior flexibility and lower manufacturing temperatures compared to crystalline silicon. The commercial end-user segment captures the largest margin pool, while government installations represent the fastest-growing category driven by public building decarbonization mandates. New construction dominates installation volumes, though retrofit applications are gaining traction as building codes tighten across jurisdictions.
The EU Green Deal and F-Gas Regulation shape product standards by restricting high-global-warming-potential materials in glazing manufacturing, while REACH compliance governs chemical inputs for organic photovoltaic layers. In the United States, the IRA provides investment tax credits that directly improve project economics for commercial solar window deployments. Stakeholders must monitor evolving perovskite stability standards and local building code harmonization to capture retrofit opportunities as regulatory thresholds tighten.
Market Dynamics
Commercial building retrofits now drive solar window demand as EU member states enforce net-zero building codes through the EU Green Deal, creating structural pull for transparent photovoltaic glazing that preserves architectural aesthetics while meeting energy performance mandates.
Growth Catalysts
- EU Green Deal retrofit mandates:Member states must decarbonize existing building stock, forcing commercial landlords to adopt building-integrated photovoltaics that avoid envelope reconstruction costs.
- Perovskite thin-film chemistry:Laboratory-scale efficiency gains above 25% for semi-transparent cells reduce the performance gap with conventional silicon, accelerating pilot-to-production timelines.
- Germany's urban density:High-rise commercial districts in Frankfurt, Berlin, and Munich face space constraints that favor vertical energy harvesting over rooftop-only solar.
Market Restraints
- Silver and indium input volatility:Transparent conductive oxide layers depend on scarce metals whose price swings compress manufacturing margins unpredictably.
- Perovskite degradation rates:Organic-inorganic hybrid cells suffer rapid efficiency loss under UV exposure and thermal cycling, limiting warranty terms to 10-15 years versus 25-year silicon benchmarks.
- REACH chemical compliance:ECHA registration requirements for lead-containing perovskite formulations add 18-24 month approval delays for new product lines targeting European installations.
Strategic Opportunities
- US IRA commercial tax credits:The Inflation Reduction Act's 30% investment tax credit for energy property improves project economics for Class A office retrofits in California and New York.
- Airport terminal glazing:Massive curtain wall expansions at Dubai, Singapore, and Denver International create demand for high-transparency power-generating facades with minimal visual obstruction.
- Smart window convergence:Integration of electrochromic tinting with photovoltaic layers enables dynamic climate control plus energy harvesting in a single glazing unit.
Industry Challenges
- Building envelope engineering talent:Few contractors possess expertise in both curtain wall installation and electrical interconnection, creating bottlenecks for multi-story projects.
- Local jurisdiction code harmonization:Fire safety and structural load standards for photovoltaic glazing vary across German federal states, requiring redundant certification testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Windows Market |
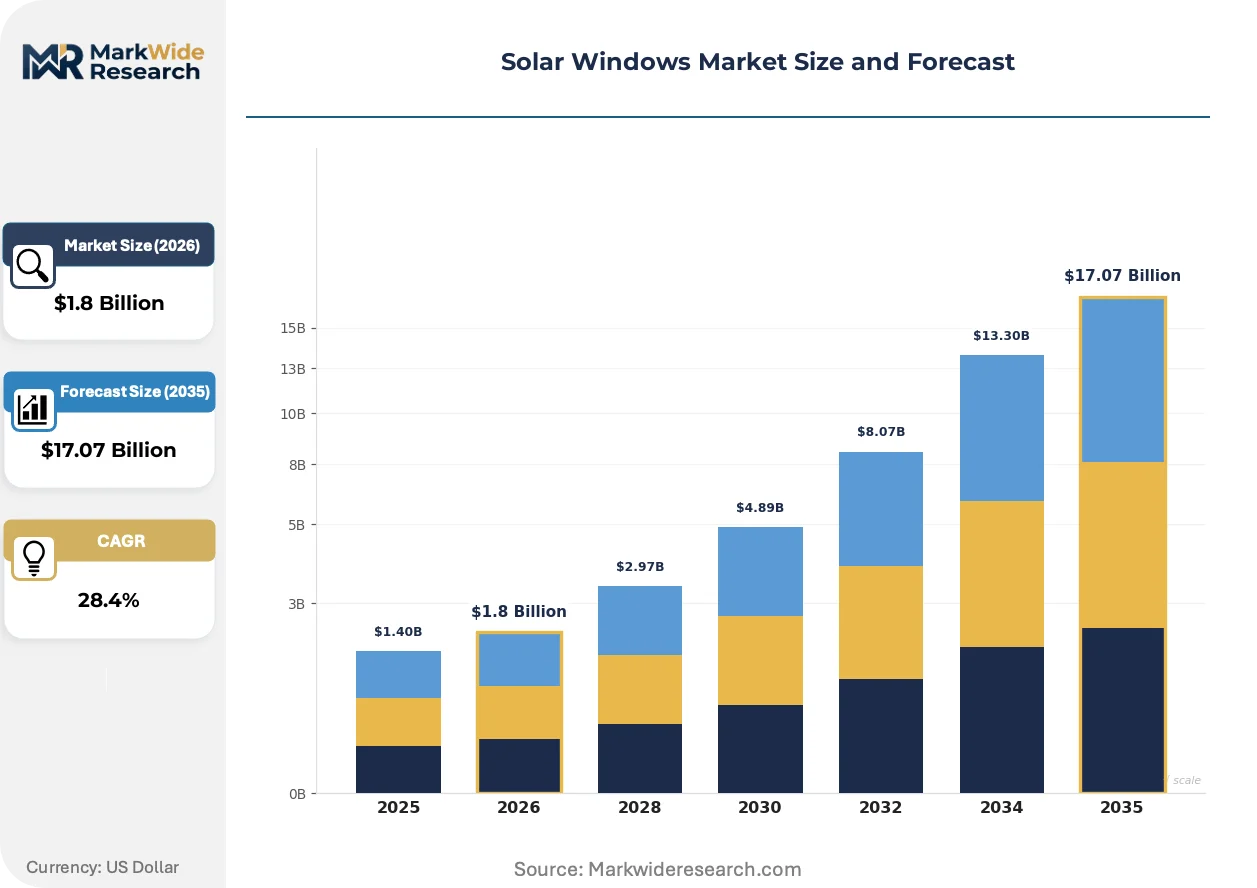
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.07 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Glass, Transparent Solar Cells, BIPV, Energy-Harvesting Windows Technology: Thin-Film, Organic Photovoltaics, Crystalline Silicon, Perovskite End User: Residential, Commercial, Industrial, Government Installation: New Construction, Retrofit, Upgrades, DIY Solutions |
| Companies Covered | Ubiquitous Energy, Brite Solar, Physee, View Inc, SolarWindow Technologies, Onyx Solar Energy, EnergyGlass, Heliotrope Technologies, Solaria Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Windows Market Strategic Shifts
Transparent photovoltaic technology is fragmenting into specialized formulations optimized for specific transparency-to-efficiency tradeoffs, while regulatory pressure and procurement evolution reshape how buyers evaluate lifecycle performance versus upfront capital cost.
Perovskite-on-glass tandem architectures are modularizing the manufacturing stack, allowing separate optimization of absorption and transmission layers. Commercial developers in Germany and the Netherlands now specify 20-40% visible light transmission variants for atrium and lobby applications. This modularization is compressing custom engineering timelines from 18 months to 6 months for standardized high-rise retrofits.
The EU F-Gas Regulation is phasing out hydrofluorocarbon blowing agents in insulating glass units, forcing manufacturers to reformulate spacer systems and edge seals. Industrial consequence includes accelerated R&D spending on thermoplastic spacer alternatives. German and Austrian glazing suppliers are responding fastest, securing early-mover positions in low-carbon building envelope specifications.
Building owners now require performance guarantees covering 20-year energy yield, not just equipment warranties. This behavior shift is displacing traditional equipment-only procurement with energy-as-a-service contracts where glazing suppliers retain operational risk. The model is most visible in Dutch commercial real estate, where Physee and similar integrators guarantee kilowatt-hour output per square meter of installed facade.
Solar Windows Market Segmentation
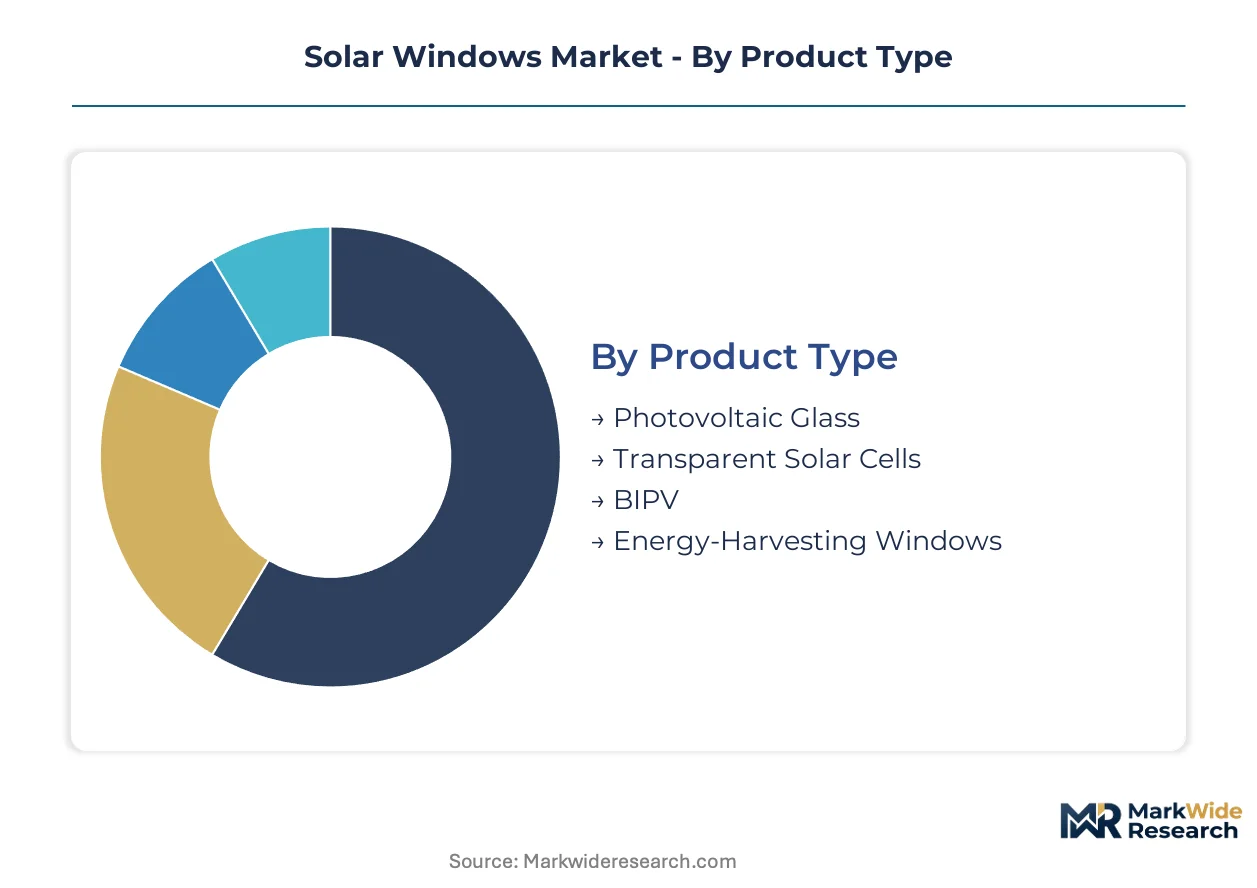
Solar windows fragment across four intersecting axes that determine performance specifications, project economics, and buyer procurement patterns. Each segmentation layer carries distinct margin profiles and regulatory exposure that shape vendor positioning strategies.
Product Type:
Photovoltaic integration depth defines the architectural tradeoff between transparency and power output.
- Photovoltaic Glass:Monolithic glazing with embedded silicon or thin-film layers achieves 10-20% efficiency in fully opaque configurations. Frankfurt high-rises specify this variant for spandrel and vision glass replacement where curtain wall aesthetics must remain unchanged.
- Transparent Solar Cells:Semi-transparent organic and perovskite chemistries transmit 30-60% visible light while generating 20-40 watts per square meter. Dutch atrium projects favor this balance for daylight-dependent spaces.
- BIPV:Building-integrated photovoltaic facades combine structural glazing with electrical generation in factory-assembled curtain wall units.
- Energy-Harvesting Windows:Consumer-grade retrofit films and aftermarket coatings target residential DIY installation with lower efficiency thresholds.
Photovoltaic glass leads on scale; transparent solar cells lead on momentum.
Technology:
Cell chemistry governs manufacturing temperature, substrate flexibility, and degradation curves under thermal cycling.
- Thin-Film:Cadmium telluride and copper indium gallium selenide deposit at 500-600°C onto glass substrates, achieving 15-20% efficiency with proven 25-year warranties. CIGS variants dominate German commercial retrofits where bankability requirements favor established degradation data.
- Perovskite:Solution-processed organic-inorganic hybrids reach 25%+ laboratory efficiency at sub-150°C manufacturing temperatures, enabling plastic substrate compatibility. UV instability and lead content complicate REACH compliance timelines for EU deployment.
- Organic Photovoltaics:Carbon-based donor-acceptor blends enable roll-to-roll printing on flexible films with sub-10% efficiency.
- Crystalline Silicon:Conventional silicon wafers embedded in laminated glass deliver highest efficiency but require opaque or heavily tinted configurations.
Thin-film commands current deployment volumes; perovskite captures R&D investment intensity.
End User:
Buyer sophistication and procurement risk tolerance vary sharply across building ownership structures.
- Commercial:Class A office landlords and institutional investors drive demand for performance-guaranteed facade installations. Energy-as-a-service contracts with guaranteed kilowatt-hour output per square meter are displacing equipment-only procurement in Dutch and German markets.
- Government:Public building decarbonization mandates under the EU Green Deal accelerate procurement for municipal offices, schools, and transit infrastructure. This segment climbs the fastest as member states enforce net-zero retrofit timelines.
- Residential:Single-family and multi-family housing pilot programs concentrate in California and New York where IRA tax credits improve project economics.
- Industrial:Manufacturing facilities and warehouses with large curtain wall areas represent emerging demand as ESG reporting requirements tighten.
Commercial dominates revenue concentration; government expands most quickly.
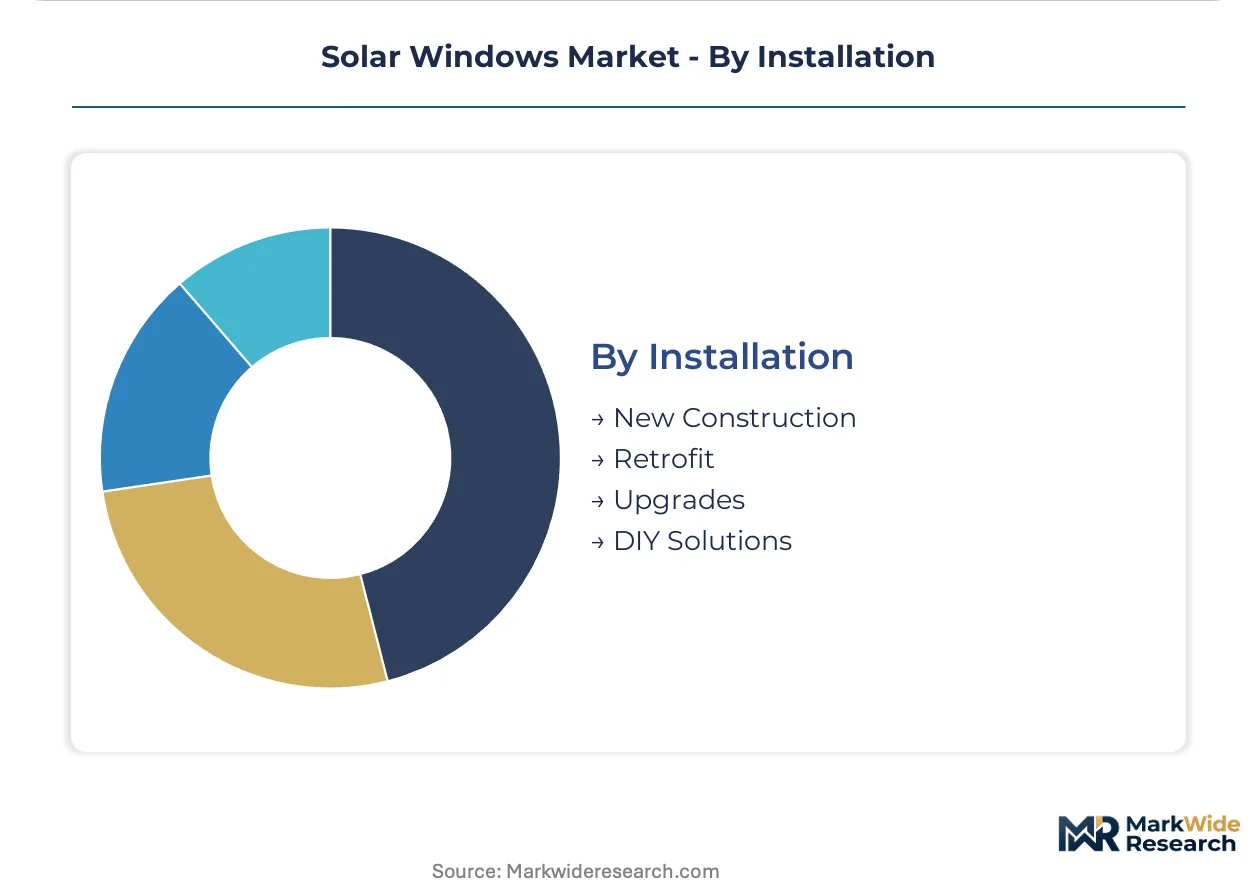
Installation:
Project delivery mode determines engineering complexity, contractor specialization requirements, and margin capture.
- New Construction:Integrated design-build contracts allow photovoltaic glazing specification during architectural programming. Airport terminals in Dubai, Singapore, and Denver specify high-transparency variants for massive curtain wall expansions.
- Retrofit:Existing building envelope replacement demands minimal structural modification and electrical interconnection expertise. EU Green Deal retrofit mandates in Germany, France, and Italy concentrate demand here as building codes tighten.
- Upgrades:Partial facade replacement or supplemental glazing installation targets end-of-life curtain wall systems.
- DIY Solutions:Aftermarket films and plug-and-play window units serve residential consumers through direct-to-channel distribution.
New construction leads on volume; retrofit gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers migrate production toward jurisdictions with streamlined chemical registration pathways, creating cost-of-compliance arbitrage between REACH-governed Europe and emerging Asian regulatory regimes. The EU Green Deal's retrofit mandates pull demand northward while Asian manufacturing clusters capture scale economies.
Germany
Frankfurt, Berlin, and Munich high-rise districts face severe rooftop space constraints that favor vertical photovoltaic harvesting. The Federal Building Energy Act mandates net-zero performance standards for commercial retrofits by 2030. The Rhine-Main metropolitan cluster hosts specialized curtain wall contractors integrating thin-film glazing into Class A office renovations.
United States
California and New York commercial landlords deploy solar windows to meet state-level building decarbonization timelines and capture IRA investment tax credits. The Inflation Reduction Act's 30% credit for energy property improves project economics for office retrofits. The San Francisco Bay Area and Manhattan submarkets concentrate pilot installations for high-transparency atrium glazing.
Netherlands
Dutch commercial real estate investors demand performance-guaranteed facade installations with 20-year energy yield contracts. The national climate agreement accelerates public building retrofits through 2035. The Randstad conurbation anchors smart window development combining electrochromic tinting with photovoltaic layers.
China
Dual carbon goals and provincial green building codes stimulate demand for building-integrated photovoltaics in tier-one cities. The Ministry of Ecology and Environment tightens embodied carbon standards for construction materials. The Yangtze River Delta manufacturing corridor concentrates thin-film deposition capacity serving domestic and export markets.
United Arab Emirates
Massive airport terminal expansions at Dubai International create demand for high-transparency power-generating curtain walls. The Emirates Green Building Council mandates renewable energy integration for new commercial developments. Dubai's sustainable city district specifications prioritize photovoltaic glazing for prestige developments.
Solar Windows Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated technology developers capturing premium positioning in commercial retrofits while glass fabricators supply standardized BIPV units for new construction. The vendor base organizes into three tiers: chemistry innovators controlling core photovoltaic formulations, glazing specialists managing architectural integration, and regional installers handling electrical interconnection. Consolidation pressure concentrates among mid-scale European glazing suppliers facing REACH compliance cost escalation. Dominant competitive moves include technology licensing agreements spanning cell chemistry to facade engineering, and backward integration into transparent conductive oxide deposition capacity.
Among chemistry-specialist developers, Ubiquitous Energy exemplifies the transparent organic photovoltaic archetype targeting aesthetic-sensitive retrofits, while Onyx Solar Energy anchors the building-integrated photovoltaic segment through specialized glazing systems. Physee occupies a position at the convergence of energy harvesting and smart climate control within Dutch commercial real estate. These three represent distinct strategic postures: materials innovation, architectural systems integration, and energy-as-a-service contracting.
| Leading Market Players |
|---|
| Ubiquitous Energy |
| Brite Solar |
| Physee |
| View Inc |
| SolarWindow Technologies |
| Onyx Solar Energy |
| EnergyGlass |
| Heliotrope Technologies |
| Solaria Corporation |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal retrofit mandates gate qualified supply and premium-tier pricing access by restricting photovoltaic glazing procurement to REACH-compliant manufacturers with verified degradation data. Buyers seeking performance-guaranteed installations face supply scarcity that elevates pricing power for certified vendors while marginalizing uncertified competitors.
Pricing Analysis
Project-based contracting dominates commercial solar window procurement, with pricing stratifying across premium, standard, and economy tiers based on transparency ratio and warranty duration. Price differentiation hinges on perovskite stability certification and electrochromic integration depth. Cost compression in the standard tier is intensifying because CIGS thin-film capacity expansion in China feeds oversupply. Government retrofit programs exhibit lowest price sensitivity due to mandate-driven procurement timelines.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale airport terminal demand, while specialized curtain wall contractors manage commercial retrofit installation. Manufacturing concentrates in China, Germany, and the Netherlands, with thin-film deposition capacity anchored in the Yangtze River Delta. Raw material dependencies draw from silver, indium, and lead halide precursors. Single-source vulnerability in transparent conductive oxide supply creates structural risk. Distribution runs through glazing fabricators, regional facade integrators, and energy-as-a-service platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar windows market functions as a stable compounder, with EU building decarbonization mandates providing decade-long demand visibility that supports sustained capacity investment and pricing discipline.
For Market Incumbents: Anticipate perovskite stability standardization by anchoring R&D spend in tandem cell architectures and securing backward integration into transparent conductive oxide deposition capacity. Defend margin position by locking long-term indium supply agreements before thin-film capacity expansion accelerates. Prioritize certification investment for REACH-compliant lead-free formulations to preempt regulatory exclusion from German and Dutch procurement pools. For New Entrants and Emerging Players: Launch via energy-as-a-service contracting models targeting Dutch commercial real estate, where performance guarantees displace equipment-only procurement. White-space opportunities concentrate in US airport terminal retrofits eligible for IRA tax credits and Italian public building mandates under accelerated EU Green Deal timelines. Penetrate through smart window convergence, bundling electrochromic climate control with photovoltaic generation. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale European glazing suppliers facing REACH compliance cost escalation because fragmented regional players lack capital for independent certification and tandem cell R&D. Long-term viability favors targets with established curtain wall contractor relationships and existing thin-film warranty portfolios. Monitor perovskite stability test results from accredited German laboratories as the inflection signal for chemistry-transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into TCO Deposition | Captive indium sourcing insulates margin volatility from commodity exchange swings. |
| REACH-Compliant Lead-Free Certification | ECHA registration unlocks German and Dutch public procurement eligibility. |
| Energy-as-a-Service Platform Launch | Physee-style output guarantees displace equipment-only contracting in Dutch commercial real estate. |
| Smart Window Convergence R&D | Electrochromic-photovoltaic integration commands premium positioning in atrium applications. |
| Airport Terminal Direct Procurement | Dubai and Denver International curtain wall expansions create hyperscale project pipelines. |
Study Parameters
Coverage spans Germany, the Netherlands, the United States, China, and the United Arab Emirates, with primary inputs from each market gathered through interviews with facade engineering directors, commercial real estate asset managers, curtain wall installation contractors, and photovoltaic glazing procurement officers at airport authorities. Secondary validation draws from EU Green Deal implementation reports, ECHA REACH registration databases, FERC interconnection filings, and building code harmonization documents across German federal states. Bottom-up project pipeline tracking triangulates with top-down regulatory mandate sizing.
Rate-of-change decomposition separates retrofit mandate enforcement velocity from new construction permit flows across the analysis window. Segmentation dimensions modeled include transparency-to-efficiency ratio, cell chemistry family, end-user ownership structure, and installation delivery mode. CAGRs derive from building stock turnover rates, code compliance deadlines, and technology cost curves. Industry-specific inputs incorporate perovskite stability test data from Fraunhofer ISE and thin-film warranty claim histories from German commercial installations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under perovskite degradation rate surprises and indium price spike scenarios. Projections reflect assumptions regarding EU member state enforcement consistency and IRA credit continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Green Coatings Market
Green Building Materials
Eco Flooring Market
Green Building Materials
Global Eco-Friendly Green Roofs Market
Green Building Materials
Asia Pacific Green Cement Market
Green Building Materials
Green Waterproofing Products Market
Green Building Materials
Green Concrete Market
Green Building Materials
Artificial Green Wall Market
Green Building Materials
Solar Glass Market
Green Building Materials
Eco-Friendly Tiles Market
Green Building Materials
Green Cement Market
Green Building Materials
Green Cement and Concrete Market
Green Building Materials
Non-Residential Green Building Market
Green Building Materials
Green Rebar Market
Green Building Materials
Europe Green Cement Market
Green Building Materials
Global Green Walls Market
Green Building Materials
Energy Efficient Window and Door Market