
 GCC Green Cement Market | 2026-2036
GCC Green Cement Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Green Cement Market Intelligence
The premium-commodity split in GCC green cement is recalibrating around carbon intensity certification and clinker substitution rates, with spec-grade products commanding procurement preference on giga-projects while generic blended cements face margin compression. Heidelberg Materials leverages its regional clinker network to supply certified low-carbon binders across the UAE and Saudi Arabia. UltraTech Cement Ltd. anchors its GCC position through specialized geopolymer formulations for coastal infrastructure. Raysut Cement Company competes via its Omani manufacturing base serving Dhofar and Salalah port expansions.
Green cement denotes hydraulic binders manufactured with reduced clinker content through supplementary cementitious materials such as fly ash, slag, or calcined clays, achieving CO₂ emissions below 400 kg per tonne while meeting BS EN 197-1 strength classifications. Its primary purpose is to decarbonize structural concrete in desert climates where sulfate resistance and thermal performance are critical. Fly ash cement dominates volume flows on infrastructure megaprojects where procurement pools favor proven supply chains, while geopolymer cement captures the fastest expansion as NEOM and Red Sea Global specify alkali-activated systems for marine environments. Sulfate resisting cement occupies a stable niche in Qatar's coastal and subsurface applications where groundwater salinity demands specialized durability.
Saudi Building Code and UAE's Al Sa'fat green rating system are tightening embodied carbon limits, forcing reformulation across domestic plants. The Gulf Standardization Organization's emerging eco-label criteria will condition market access for imported and locally produced binders alike. Stakeholders must monitor how sovereign wealth project procurement evolves from voluntary green specifications to enforceable carbon accounting in contractor bids.
Market Dynamics
Sovereign wealth procurement mandates across Saudi Arabia and the UAE are compressing specification timelines for low-carbon binders, forcing rapid plant retrofits ahead of embodied carbon enforcement deadlines on giga-projects.
Growth Catalysts
- Al Sa'fat Green Building Rating:The UAE's mandatory embodied carbon thresholds for construction materials are pulling spec-grade low-clinker cement into commercial and residential high-rises across Dubai and Abu Dhabi.
- Calcined clay activation:LC3 (limestone calcined clay cement) formulations are achieving 40% clinker reduction while maintaining sulfate resistance, matching the durability requirements of coastal desert infrastructure.
- NEOM procurement pools:Saudi Arabia's linear city development has centralized sustainable cement sourcing through sovereign-backed contractor pre-qualification, locking in multi-year offtake commitments.
Market Restraints
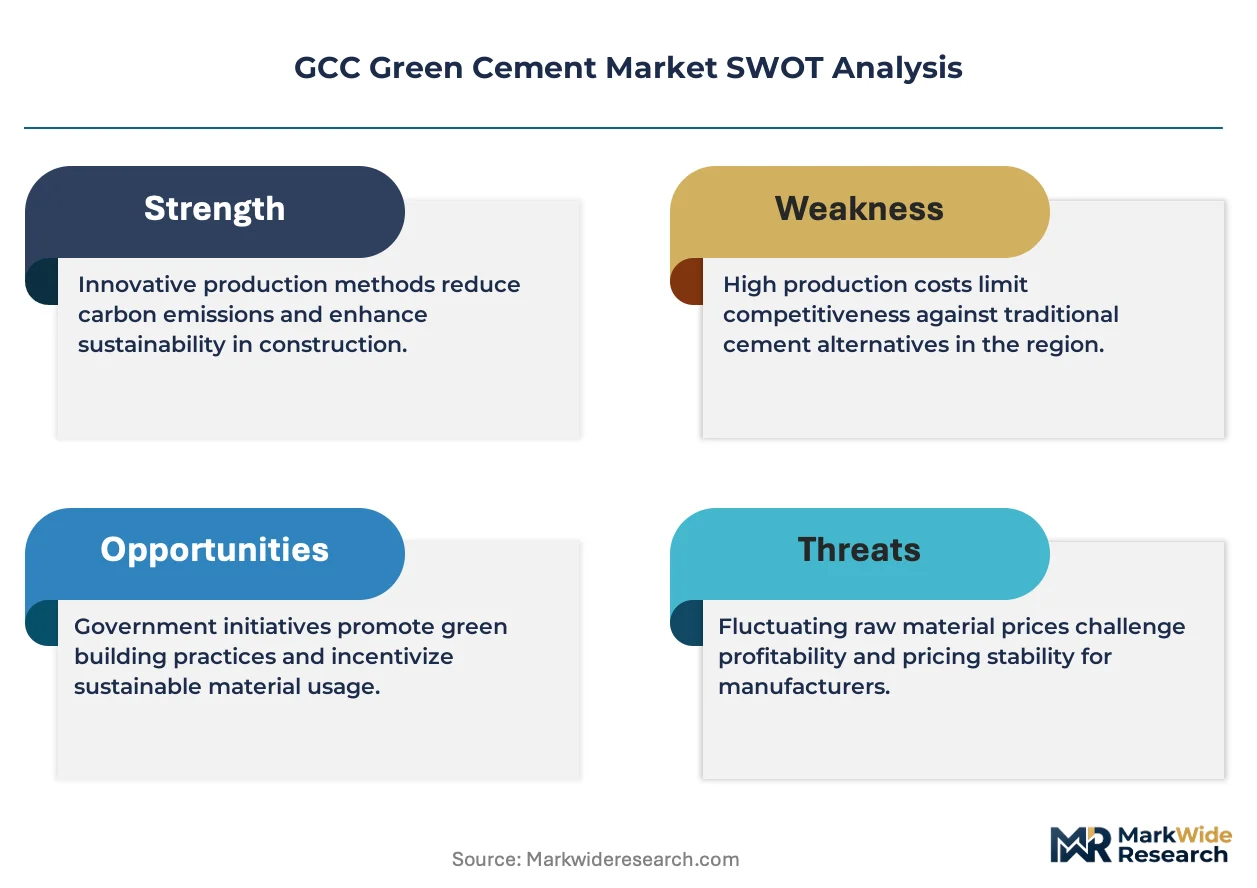
- Fly ash supply concentration:Regional dependence on imported supplementary cementitious materials from Indian and Turkish power generation creates input cost volatility and logistics bottlenecks.
- Clinker substitution ceiling:Current BS EN 197-1 strength classifications limit SCM loading to 35% for structural applications, capping emissions reduction potential on load-bearing concrete.
- Geopolymer curing complexity:Alkali-activated systems require controlled temperature and humidity conditions incompatible with ambient desert construction schedules, restricting deployment scale.
Strategic Opportunities
- Oman downstream integration:Dhofar and Salalah port expansions offer captive demand for sulfate-resisting blended cements with integrated clinker-grinding capacity.
- Carbon credit monetization:Gulf Standardization Organization's emerging eco-label criteria will enable certified producers to capture green premiums in voluntary carbon markets.
- Red Sea Global marine specifications:Coastal tourism and hospitality developments are mandating chloride-resistant geopolymer concrete for submerged foundations and waterfront structures.
Industry Challenges
- Alkali-silica reaction testing:SCM variability from diverse industrial waste sources requires extended aggregate compatibility validation, stretching project qualification timelines.
- Retrofit capex burden:Vertical roller mill installations for calcined clay grinding demand $40-60 million per production line, straining mid-cap producer balance sheets.
- Contractor specification literacy:Site engineers lack training in low-carbon mix design optimization, leading to over-specification of Portland cement for risk aversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Green Cement Market |
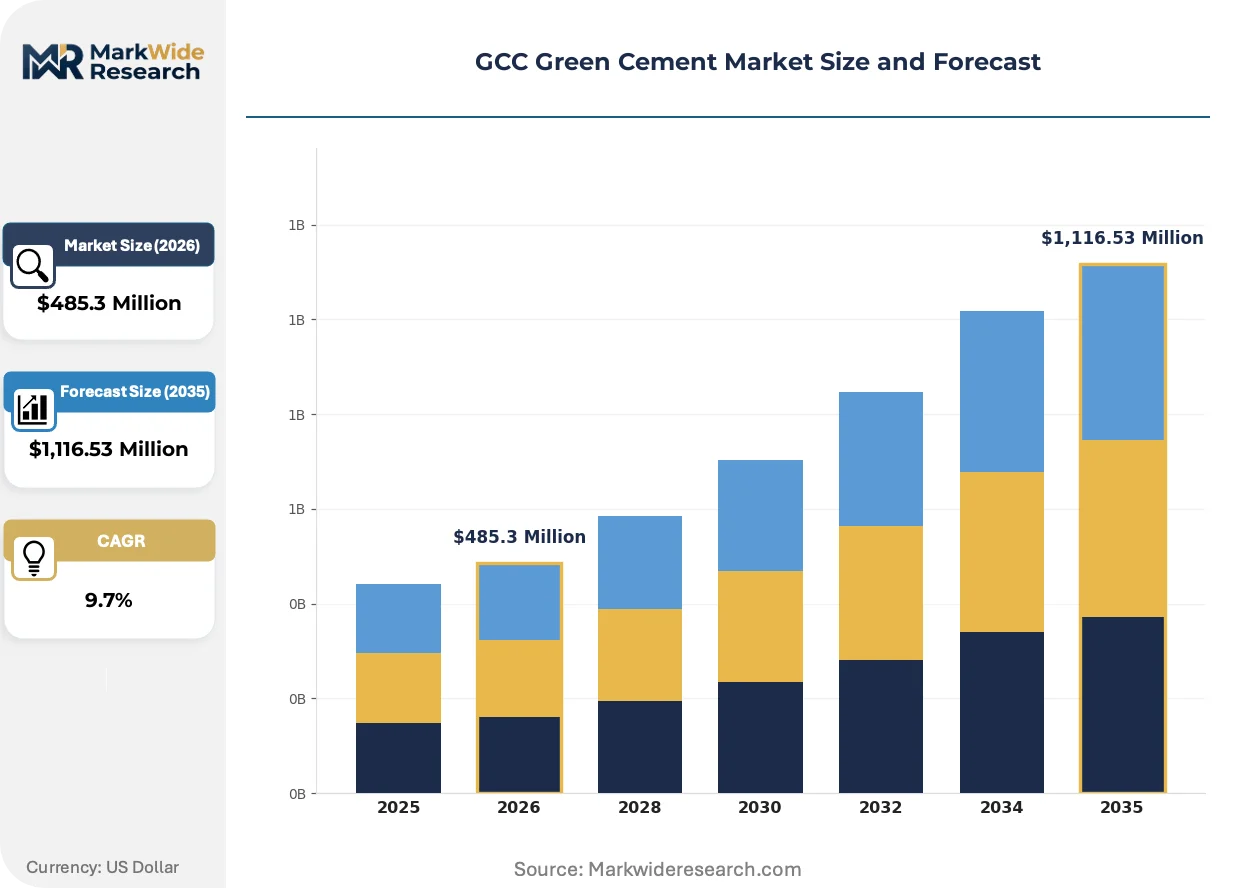
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,116.53 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fly Ash Cement, Geopolymer Cement, Recycled Aggregates, Sulfate Resisting Cement Application: Infrastructure, Residential Construction, Commercial Construction, Road Construction End User: Contractors, Construction Firms, Government Agencies, Architects Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | JSW Cement, Heidelberg Materials, UltraTech Cement Ltd., Green Cement Factory, Sharjah Cement & Industrial Development Co., HOLCIM, Raysut Cement Company, DUCON INDUSTRIES, CEMEX, S.A.B. de C.V., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Green Cement Market Strategic Shifts & Innovations
Carbon accounting transparency is rewiring competitive advantage around verified supply chain emissions data rather than traditional strength-grade positioning, compressing margins for uncertified commodity blends.
Calcined clay processing technology is consolidating around flash calcination systems that reduce fuel intensity by 30% versus rotary kiln methods. Saudi Building Code amendments are accelerating adoption timelines for LC3 binders on government-funded infrastructure. This consolidation is compressing the premium window for early-mover clay suppliers as regional production scales.
The Gulf Standardization Organization's draft eco-label criteria will mandate third-party carbon footprint verification for market access, mirroring EU CBAM alignment pressures. Domestic producers are pre-emptively installing continuous emissions monitoring to secure certification readiness. Saudi Arabia's sovereign project procurement offices are already embedding these standards into tender pre-qualification requirements.
Contractor buying committees are consolidating specification authority away from project-level engineers toward centralized procurement functions with carbon accounting mandates. Bulk purchasing agreements with verified low-carbon suppliers are displacing spot-market cement sourcing on multi-year developments. This concentration is most visible across NEOM and Qiddiya where master developer procurement pools lock in 3-5 year supply contracts with emissions disclosure requirements.
GCC Green Cement Market Segmentation
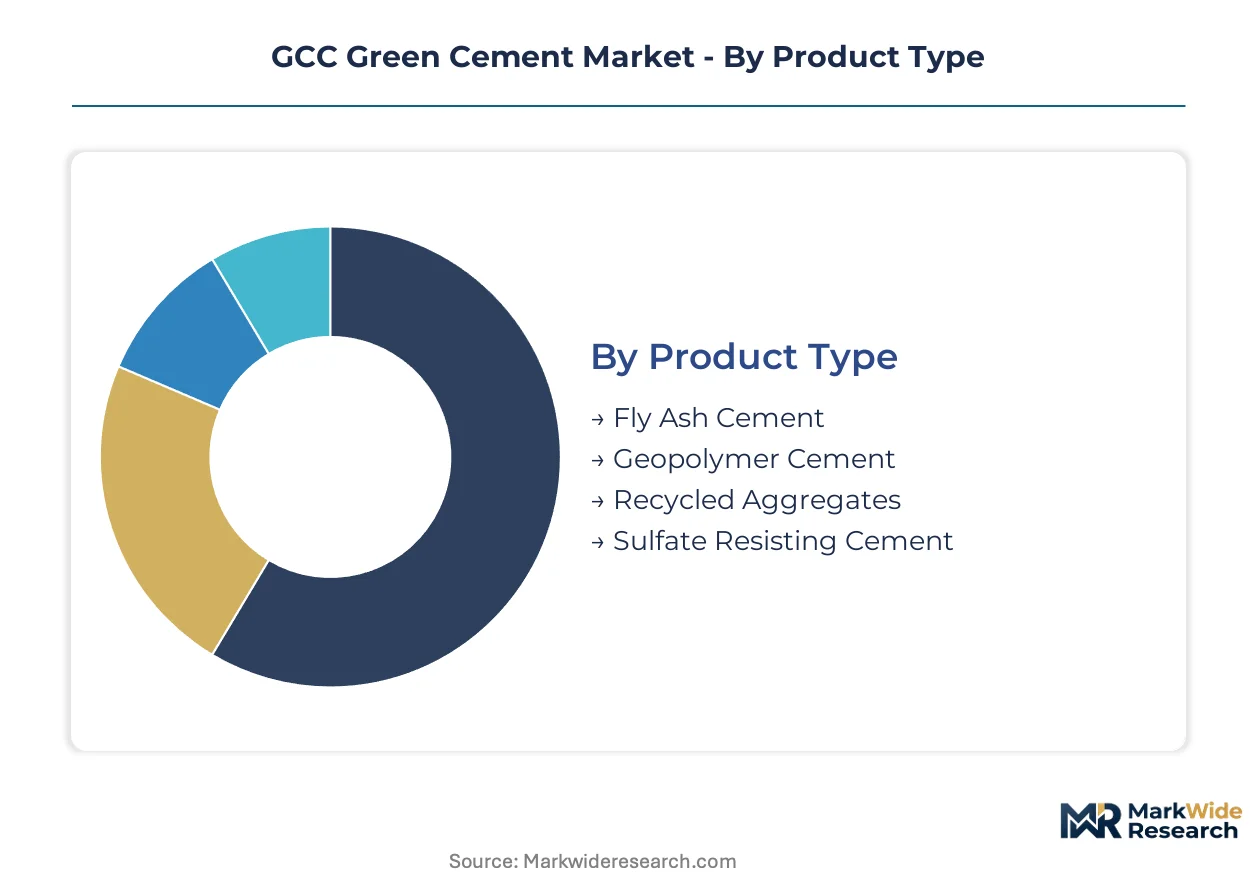
Segmentation in the GCC green cement market reveals how certification requirements and procurement mandates fragment demand across product grades. Sovereign project specifications are compressing the addressable market for uncertified blends while concentrating volume in validated low-carbon categories.
Product Type:
BS EN 197-1 compliance and Saudi Building Code amendments impose differentiated certification burdens across binder formulations, with calcined clay and geopolymer systems facing extended validation timelines.
- Fly Ash Cement:Blended binder incorporating pulverized fuel ash achieves 25-35% clinker substitution while maintaining standard strength grades. Demand concentrates on Saudi Arabia's giga-project corridor where NEOM procurement pools favor established supply chains with proven sulfate resistance documentation.
- Geopolymer Cement:Alkali-activated systems utilizing metakaolin or slag achieve near-zero clinker content but require controlled curing protocols. Red Sea Global marine specifications are pulling this segment into coastal tourism foundations despite ambient desert construction constraints.
- Recycled Aggregates:Processed construction demolition waste substitutes virgin limestone in concrete mixes. UAE Al Sa'fat rating system credits are accelerating specification on Dubai commercial high-rises.
- Sulfate Resisting Cement:Low-C3A Portland or blended formulations withstand groundwater salinity. Qatar's coastal infrastructure and subsurface utilities sustain steady procurement through specialized contractor pre-qualification.
Leading the category by volume: Fly Ash Cement. Growing fastest: Geopolymer Cement.
Application:
Cost tier stratification separates sovereign-funded megaprojects with carbon accounting mandates from private developments where price sensitivity dominates binder selection.
- Infrastructure:Bridges, tunnels, and utilities demand high-durability low-carbon concrete with verified supply chain emissions. Saudi sovereign wealth procurement mandates are locking in multi-year offtake agreements for certified binders.
- Residential Construction:Mid-rise apartments and villa developments favor cost-optimized blended cements meeting minimum green building credits. Dubai's Al Sa'fat enforcement is tightening embodied carbon thresholds for new permits.
- Commercial Construction:Office towers and retail complexes specify performance-grade binders for structural columns and slabs. Abu Dhabi master developers are consolidating procurement through centralized buying committees with carbon disclosure requirements.
- Road Construction:Pavements and highway infrastructure utilize lower-grade blended cements where load-bearing demands permit higher SCM loading. Oman Dhofar port access roads are testing calcined clay formulations.
Highest specification intensity: Infrastructure. Steepest volume expansion: Commercial Construction.
End User:
Customer type determines whether procurement prioritizes certified low-carbon binders or commodity-grade blended cements, with sovereign-backed entities driving premium segment growth.
- Contractors:Site-level engineers execute mix designs specified by master developers, often over-specifying Portland cement for risk aversion despite green procurement mandates.
- Construction Firms:Large integrated builders maintain captive concrete batching with direct low-carbon supplier relationships. NEOM and Qiddiya pre-qualified consortiums lock in 3-5 year supply contracts.
- Government Agencies:Saudi Building Code amendments and UAE federal procurement rules are embedding embodied carbon limits into tender documentation, forcing reformulation across public infrastructure.
- Architects:Design-phase specification authority is shifting toward procurement functions, reducing traditional influence over binder selection despite sustainability preferences.
Contractor volume dominance persists. Government agencies are gaining specification authority fastest.
Distribution Channel:
Supply chain configuration determines price realization and certification integrity, with direct relationships capturing sovereign project premiums while intermediaries serve fragmented private demand.
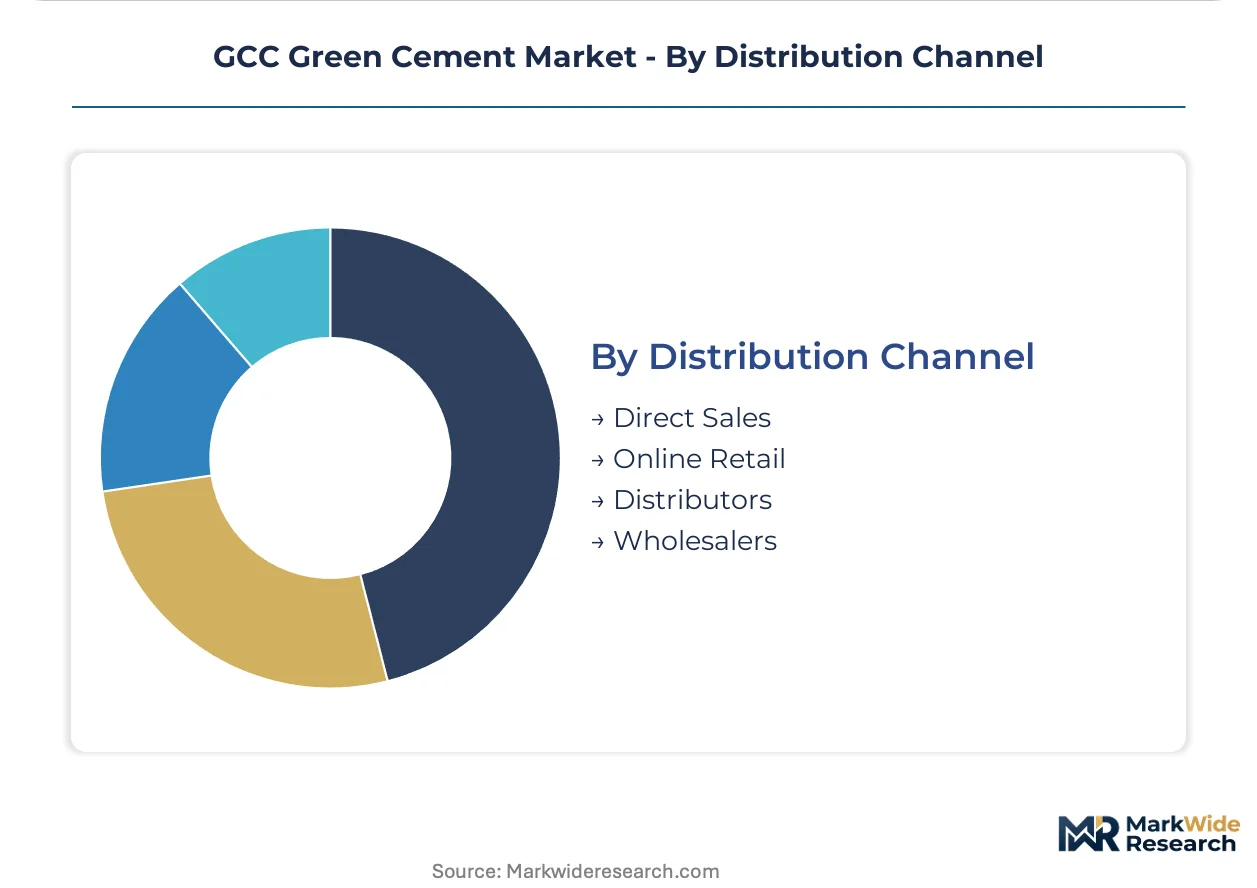
- Direct Sales:Producer-to-developer relationships enable verified carbon accounting and custom formulation for giga-projects. Heidelberg Materials and regional majors leverage clinker network proximity for UAE and Saudi Arabia coverage.
- Online Retail:Digital platforms facilitate small-batch specialty binder procurement for renovation and repair segments. Limited penetration due to bulk logistics constraints.
- Distributors:Regional stockists aggregate demand from mid-cap contractors and independent builders. Inventory carrying costs strain working capital for calcined clay and geopolymer variants.
- Wholesalers:Volume aggregators supply commodity blended cements to price-sensitive segments with minimal certification documentation. Margin compression is accelerating consolidation.
Direct sales command premium positioning. Distributor networks are expanding coverage most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NEOM's linear city corridor dominates sovereign-backed green cement procurement, with Riyadh and Dubai anchoring commercial specification authority across the Arabian Peninsula.
Saudi Arabia
NEOM and Qiddiya developments mandate low-carbon concrete for structural applications through centralized procurement pools. The Saudi Building Code tightens embodied carbon thresholds for government-funded infrastructure. Riyadh's giga-project corridor locks in multi-year offtake agreements with certified binder suppliers.
United Arab Emirates
Dubai and Abu Dhabi commercial high-rises specify performance-grade binders under mandatory Al Sa'fat green building ratings. MOHAP enforcement tightens embodied carbon limits for new construction permits. Abu Dhabi master developers consolidate buying committees with carbon disclosure requirements.
Oman
Dhofar and Salalah port expansions generate captive demand for sulfate-resisting blended cements. The Sultanate's coastal infrastructure program tests calcined clay formulations for marine durability. Salalah's integrated clinker-grinding capacity serves regional export markets.
Qatar
Coastal and subsurface utilities sustain procurement of specialized low-C3A formulations for groundwater salinity resistance. Public infrastructure tenders embed durability certification requirements. Doha's liquefied natural gas expansion corridors specify high-sulfate-resistant binders.
GCC Green Cement Market Key Industry Players
Capital-heavy producers compete with asset-light technology licensors across the GCC green cement landscape. Integrated clinker manufacturers leverage vertical kiln networks for calcined clay activation, while regional grinding specialists import supplementary cementitious materials for blending operations. The market structure consolidates around three archetypes: sovereign-project certifiers, coastal infrastructure specialists, and commodity blenders facing margin compression. Dominant competitive moves include calciner retrofit investments and pre-qualification lock-ins with NEOM procurement pools.
Among European-anchored materials conglomerates, Heidelberg Materials and HOLCIM occupy positions as certifiers serving UAE and Saudi sovereign projects. UltraTech Cement Ltd. represents the India-origin specialist tier with geopolymer formulation capabilities. Raysut Cement Company anchors the Omani manufacturing base for Dhofar port logistics.
| Leading Market Players |
|---|
| JSW Cement |
| Heidelberg Materials |
| UltraTech Cement Ltd. |
| Green Cement Factory |
| Sharjah Cement & Industrial Development Co. |
| HOLCIM |
| Raysut Cement Company |
| DUCON INDUSTRIES |
| CEMEX, S.A.B. de C.V. |
| Others |
Cost & Logistics Intelligence
Al Sa'fat green building ratings and Saudi Building Code amendments gate qualified supply access and premium-tier pricing realization across the GCC green cement landscape. Sovereign project procurement pools restrict multi-year offtake eligibility to certified low-carbon producers, compressing margins for uncertified commodity blenders while calcined clay and geopolymer formulations capture structural premiums.
Pricing Analysis
Value-based pricing anchored to verified carbon intensity certification separates spec-grade low-clinker binders from generic blended cements across the GCC. Price differentiation rests on third-party emissions verification and clinker substitution rates, with certified products commanding procurement preference on NEOM and Qiddiya developments. Cost compression in commodity-grade fly ash blends is intensifying because imported supplementary cementitious material volatility erodes margin buffers. Government agencies and sovereign wealth project offices exhibit lowest price sensitivity, while mid-cap contractors and independent builders in residential construction remain most responsive to per-tonne differentials.
Supply Chain Analysis
Saudi Arabia's local-content mandates and the UAE's Al Sa'fat enforcement are reshaping sourcing patterns toward domestic calcined clay activation and regional clinker network proximity. Geographic supply concentration centers on Saudi Arabia, the UAE, and Oman, with integrated kiln capacity anchoring calciner retrofit investments. Raw material dependencies draw from Indian and Turkish fly ash imports, Omani limestone reserves, and regional metakaolin deposits. Single-source vulnerability in supplementary cementitious material logistics creates input cost volatility during shipping disruptions. Distribution runs through direct producer-to-developer relationships for sovereign projects and regional distributor networks for fragmented private demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC green cement sector sits in a technology-transition phase where LC3 and geopolymer formulations are displacing conventional Portland-limestone blends. Calcined clay activation and alkali-activated systems are capturing specification authority on carbon-accounting megaprojects.
For Market Incumbents: Extend certification coverage across clinker substitution tiers to defend sovereign project pre-qualification status against emerging grinding specialists. Backward integration into calcined clay feedstock through vertical roller mill retrofits secures input cost control. Lock in multi-year offtake agreements with NEOM and Red Sea Global procurement pools before capacity additions by regional competitors dilute premium windows. For New Entrants and Emerging Players: Flash calcination technology for limestone calcined clay cement offers a technology-first wedge into the spec-grade binder segment underserved by legacy rotary kiln producers. Target Oman's Dhofar and Salalah port corridor where captive infrastructure demand meets limited incumbent calciner presence. Lead with marine durability credentials and integrated grinding capacity to bypass distributor margin stacking. For Investors and Strategic Acquirers: Gulf Standardization Organization eco-label enforcement is the leading indicator that certified low-carbon production capacity will command scarcity premiums across the analysis window. Mid-cap grinding specialists with clinker network access and calciner retrofit pipelines represent optimal acquisition archetypes. Monitor sovereign project tender documentation for mandatory carbon accounting clauses as the inflection signal for accelerated specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Calciner Retrofit Investment | Flash calcination systems reduce fuel intensity by 30% versus rotary methods for LC3 production. |
| Long-term Supply Agreement | NEOM procurement pools lock in 3-5 year offtake commitments with emissions disclosure requirements. |
| Green Certification Program | Third-party carbon footprint verification secures access to Al Sa'fat and Saudi Building Code compliant projects. |
| Backward Integration | Captive calcined clay feedstock production insulates margin structures from imported SCM volatility. |
| Joint Venture | Regional grinding partnerships with clinker network proximity expand UAE and Saudi coverage without greenfield capex. |
Research Approach
Document review covered trade customs data, Gulf Standardization Organization draft criteria, SEC filings from listed building materials conglomerates, and project procurement documentation from Saudi sovereign wealth entities, complemented by interviews with plant operations directors at integrated clinker manufacturers, procurement leads from NEOM contractor pre-qualified consortiums, technical specification engineers at Abu Dhabi master developers, and distribution channel managers at regional cement stockists. Bottom-up volume estimates from production capacity utilization and clinker substitution rates were triangulated against top-down demand projections from construction permit data and green building certification trajectories.
Segment-level outputs across product type, application, end user, and distribution channel dimensions were generated through the analytical framework, with calcined clay adoption curves and geopolymer specification penetration modeled as industry-specific forecast inputs. CAGRs were derived from regression analysis of historical clinker-to-cement ratios against embodied carbon threshold tightening schedules, cross-referenced with sovereign project pipeline visibility.
Several conditions sit outside the modeled scope, including abrupt shifts in fly ash import tariffs, unanticipated Saudi Building Code amendment timelines, and breakthroughs in ambient-curing geopolymer chemistry that could relax deployment constraints. Forecasts reflect assumptions around procurement pool centralization and certification enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Global Green Walls Market
Green Building Materials
Eco-Friendly Tiles Market
Green Building Materials
Green Coatings Market
Green Building Materials
Solar Frames Market
Green Building Materials
APAC Green Buildings Market
Green Building Materials
Green Waterproofing Products Market
Green Building Materials
Asia Pacific Green Cement Market
Green Building Materials
North America Green Cement Market
Green Building Materials
Green Cement Market
Green Building Materials
Green Concrete Market
Green Building Materials
Green Building Materials Market
Green Building Materials
United States Green Cement Market
Green Building Materials
Green Silica Market
Green Building Materials
Sustainable and Green Building Materials Market
Green Building Materials
Green Building Market
Green Building Materials
North America Green Buildings Market