
 Carbon Footprint Management Market | 2026-2036
Carbon Footprint Management Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Footprint Management Market Intelligence
The capability gap between capital-intensive platform development and specialized advisory services is unwinding the traditional market structure. Microsoft leverages its Azure cloud infrastructure to offer scalable emission tracking tools. In contrast, Schneider Electric specializes in energy management solutions for industrial clients. IBM competes by integrating AI-driven analytics into its sustainability software suites.
Carbon footprint management encompasses the systematic quantification and monitoring of greenhouse gas emissions generated by an organization, product, or service. These systems often utilize methodologies aligned with the GHG Protocol Corporate Standard to ensure data accuracy and comparability for reporting and reduction planning. Cloud-based deployment models dominate due to scalability and accessibility for global enterprises. Within solution types, carbon accounting and compliance management are foundational, while analytics & insights represent a high-growth area for value creation.
Regulatory frameworks like the EU's Corporate Sustainability Reporting Directive (CSRD) and proposed SEC climate disclosure rules in the United States are creating mandatory demand. These regulations require auditable, investment-grade emissions data, elevating the strategic importance of management platforms. The next critical decision for enterprises will be extending carbon accounting beyond their own operations to encompass complex, multi-tier supply chains.
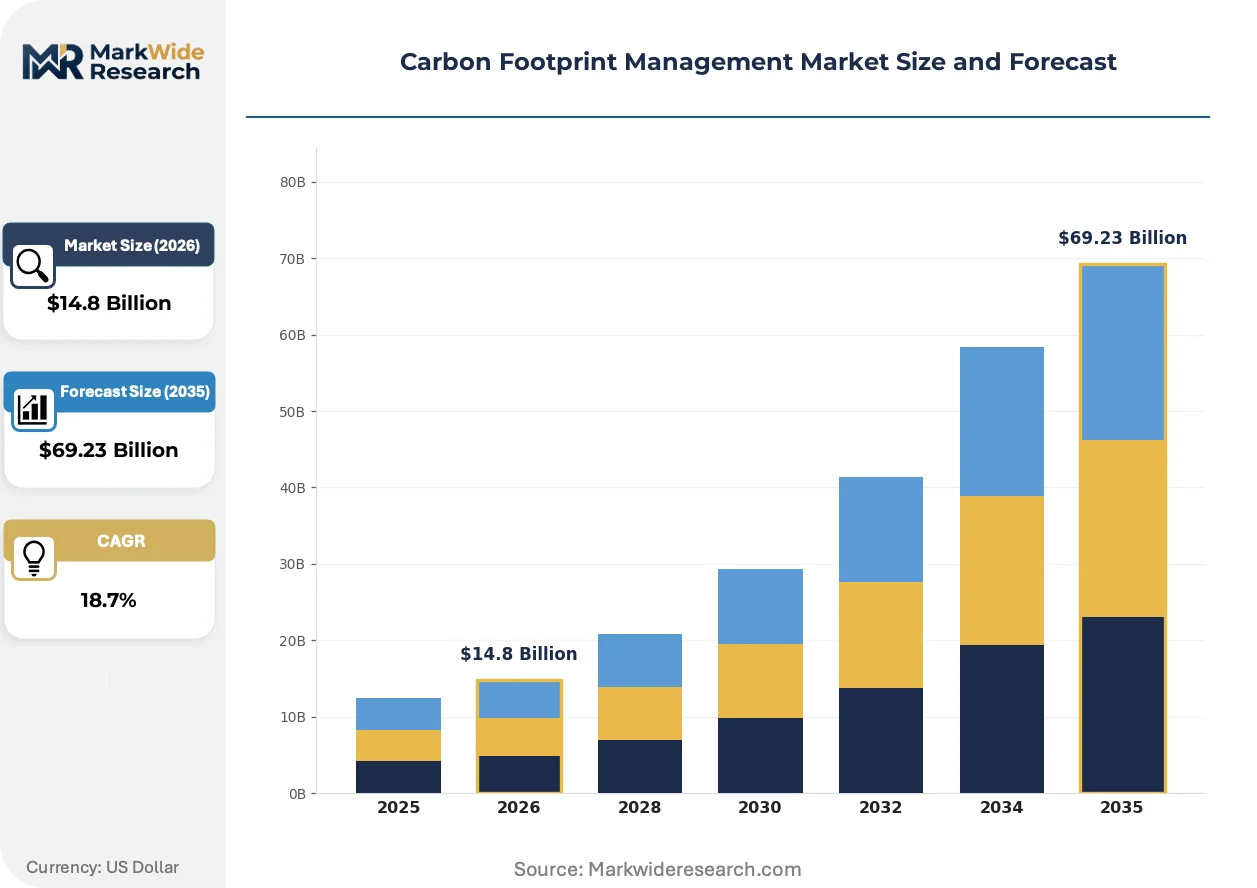
Market Dynamics
The central force shaping the market is the transition from voluntary environmental reporting to mandatory, auditable disclosure. Regulations like the EU's Corporate Sustainability Reporting Directive are elevating carbon accounting from a peripheral activity to a core strategic business function, compelling investment in enterprise-grade platforms.
Growth Catalysts
- Regulatory Mandates:The EU's CSRD and proposed SEC climate rules create non-discretionary demand for auditable emissions data, compelling investment in robust platforms.
- Manufacturing Sector Integration:Industrial firms embed emissions data into operational planning to identify inefficiencies, reduce energy costs, and optimize production.
- Industrial Economy Concentration:Demand is intensifying in economies like Germany and Japan, where complex supply chains require sophisticated tracking solutions.
Market Restraints
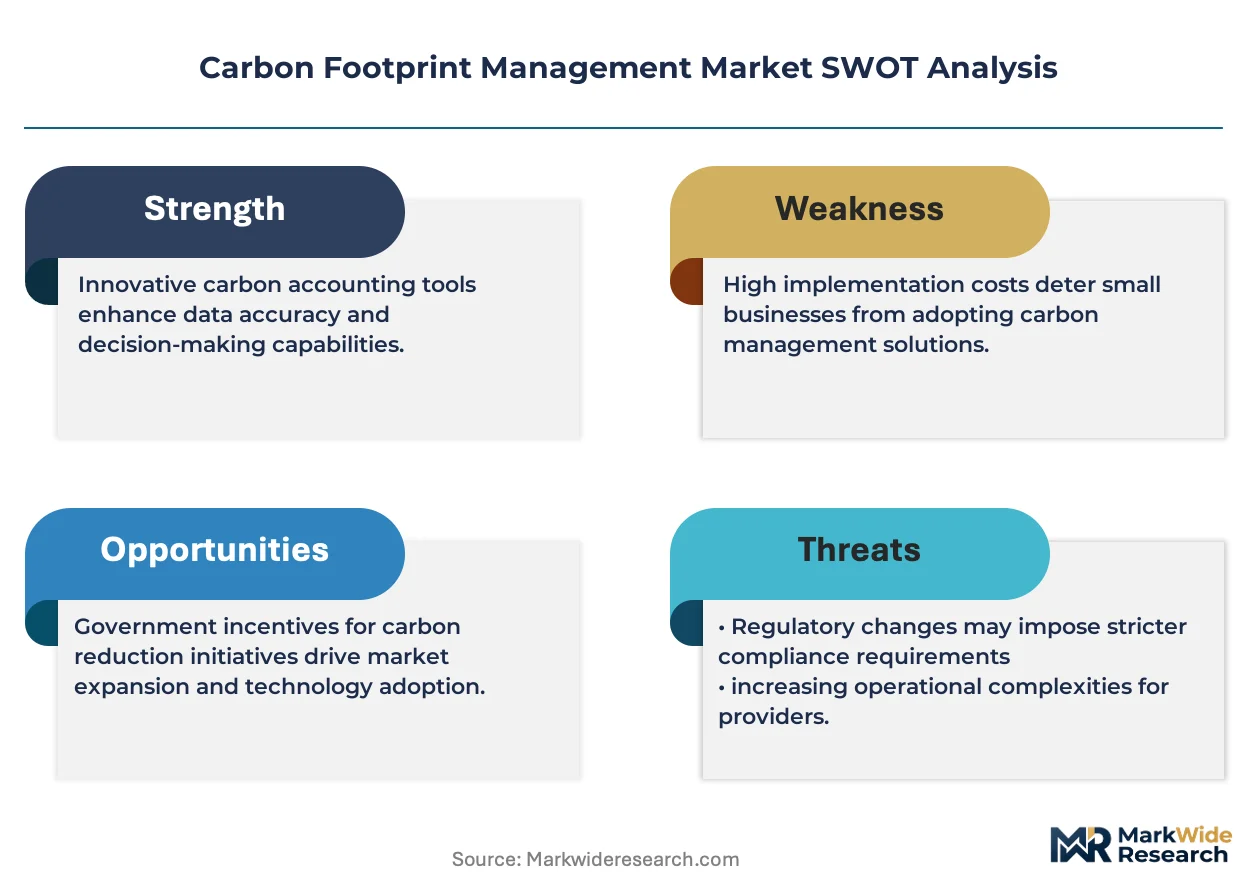
- Scope 3 Data Complexity:Accurately quantifying and verifying emissions across multi-tier global supply chains remains a significant technical barrier.
- High Implementation Costs:The capital outlay for enterprise-grade software and integration with existing ERP systems deters adoption by some firms.
- Simplified Tool Substitution:Organizations may opt for lower-cost estimation tools, which lack the auditability required for regulatory compliance.
Strategic Opportunities
- Product Carbon Footprinting:Specialized modules for product-level emissions tracking can support eco-labeling and sustainable design initiatives.
- Predictive Analytics Integration:Converging AI with carbon platforms enables predictive modeling for decarbonization pathways and investment scenario analysis.
- Emerging Market Expansion:Industrializing economies in Southeast Asia represent a growth frontier as global supply chains and regulatory expectations expand.
Industry Challenges
- Specialized Talent Scarcity:A shortage of professionals with hybrid expertise in sustainability, data science, and specific industry processes hinders effective system implementation and management.
- Data Integration Friction:Consolidating emissions data from disparate sources, including legacy IT systems and diverse supplier formats, into a unified platform is a major operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Footprint Management Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $69.23 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Emission Tracking, Carbon Accounting, Sustainability Reporting, Compliance Management, Analytics & Insights, Risk Assessment Deployment Model: Cloud-Based, On-Premise, Hybrid, SaaS, API Integration Application Area: Supply Chain Monitoring, Energy Management, Waste Reduction, Product Lifecycle Analysis, Corporate Sustainability, Environmental Compliance End User Industry: Manufacturing, Renewable Energy Firms, Transportation Providers, Construction Companies, Agriculture Producers, Financial Services |
| Companies Covered | Klöckner & Co, Patagonia, Microsoft, Unilever, IBM, Schneider Electric, Amazon, Planet FWD, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Footprint Management Market Strategic Shifts & Innovations
The market is shifting from static, compliance-focused data collection toward dynamic, intelligence-driven platforms. Automation and artificial intelligence are transforming carbon management into a tool for proactive operational and strategic decision-making, moving well beyond simple reporting.
AI-powered analytics engines are being integrated into carbon management software to automate data ingestion and analysis from diverse sources. Large enterprises in manufacturing and logistics are adopting these tools to process vast datasets from their operations. This automation is fragmenting the market between basic compliance tools and advanced platforms that offer strategic decision support.
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates detailed and third-party-audited emissions reporting for a wide range of companies. This regulation effectively elevates carbon data to the same level of scrutiny as financial information, requiring investment-grade systems. The directive most affects EU-based firms and their non-EU subsidiaries, forcing rapid adoption of compliant platforms.
A key behavioral shift is the demand for granular, product-level carbon footprint data from suppliers within procurement processes. This disrupts traditional sourcing reliant on industry-average emission factors, replacing it with requests for specific, verifiable data. This trend is most prominent in the automotive and consumer electronics sectors in Europe and Japan.
Carbon Footprint Management Market Segmentation
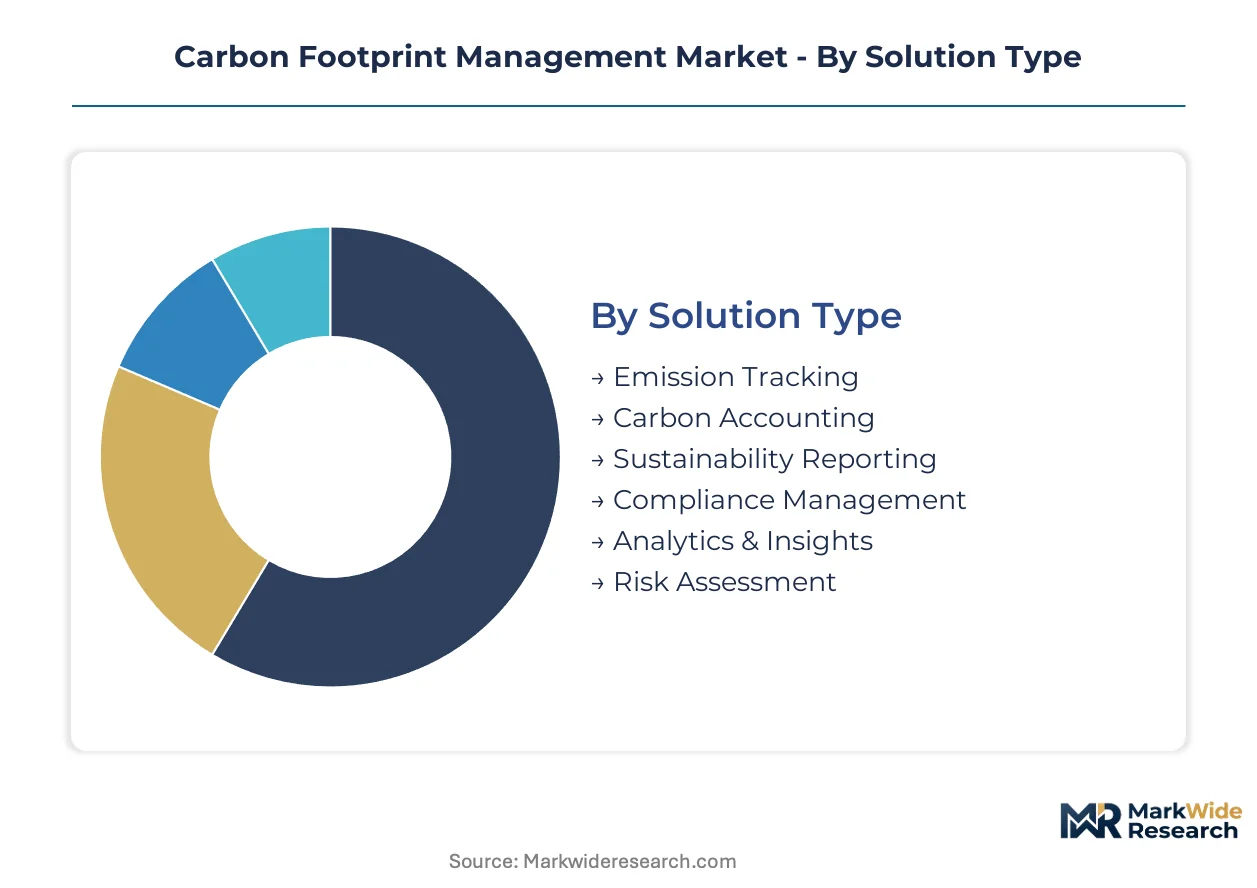
Market segmentation clarifies how different solutions, deployment methods, applications, and end-user industries interact within the carbon footprint management ecosystem. Understanding these distinctions helps identify specific demand drivers and competitive dynamics across the market.
Solution Type:
Substitution pressure significantly impacts the Solution Type segment, as basic compliance tools compete with advanced analytical platforms offering deeper insights and strategic value.
- Carbon Accounting:This foundational solution systematically quantifies greenhouse gas emissions using methodologies like the GHG Protocol Corporate Standard. Demand concentrates in industrial economies like Germany and Japan due to stringent regulatory mandates from bodies like the EU's CSRD.
- Analytics & Insights:These advanced platforms integrate AI-driven analytics to process vast datasets, enabling predictive modeling for decarbonization pathways and investment scenario analysis. Large enterprises in manufacturing and logistics are driving adoption to optimize operations and reduce energy costs.
- Emission Tracking:These tools monitor specific greenhouse gas emissions generated by an organization, product, or service, often forming the basis for broader carbon accounting.
- Sustainability Reporting:Solutions focused on generating standardized reports for stakeholders, adhering to frameworks such as the EU's Corporate Sustainability Reporting Directive.
- Compliance Management:These systems ensure adherence to regulatory mandates and disclosure requirements, elevating auditable emissions data to investment-grade status.
- Risk Assessment:Modules designed to identify and quantify climate-related financial and operational risks, supporting strategic decision-making for enterprises.
Carbon Accounting anchors the volume base while Analytics & Insights gains share at the steepest rate.
Deployment Model:
Supply concentration within deployment models favors highly scalable and accessible infrastructure for global enterprises seeking efficient carbon footprint management.
- Cloud-Based:This model hosts software and data on remote servers, offering scalability, accessibility, and reduced infrastructure costs for enterprises, particularly for multi-national operations. Microsoft Azure provides foundational cloud infrastructure for such tools.
- SaaS:Software-as-a-Service solutions deliver carbon management platforms via a subscription model, providing continuous updates and managed services. This model is preferred for its lower upfront investment and rapid deployment across various industries.
- On-Premise:Software installed and run on a company's own servers, offering maximum control and customization but requiring significant internal IT resources.
- Hybrid:A combination of cloud-based and on-premise components, allowing organizations to balance data control with scalability and remote access.
- API Integration:Solutions that connect carbon management platforms with existing enterprise systems like ERP, enabling seamless data exchange and automation.
Enterprises increasingly prefer cloud-native solutions, driving significant investment in scalable infrastructure.
Application Area:
Application scope dictates the complexity and integration requirements for carbon footprint management systems across diverse operational contexts.
- Supply Chain Monitoring:This application focuses on quantifying and tracking emissions across complex, multi-tier supply chains, addressing the significant technical barrier of Scope 3 data complexity. Procurement processes in the automotive sector demand granular data.
- Corporate Sustainability:This broad application integrates carbon management into overall environmental, social, and governance (ESG) strategies, driven by investor pressure and regulatory mandates from the SEC. IBM offers AI-driven analytics for this area.
- Energy Management:Solutions optimizing energy consumption and identifying inefficiencies within operations, directly contributing to emissions reduction and cost savings for industrial firms.
- Waste Reduction:Applications aimed at minimizing waste generation and its associated emissions, often integrated with broader resource efficiency programs.
- Product Lifecycle Analysis:Modules tracking emissions from raw material extraction through manufacturing, use, and disposal, supporting eco-labeling and sustainable design initiatives.
- Environmental Compliance:Ensuring adherence to specific environmental regulations and reporting standards beyond general carbon disclosure.
Corporate Sustainability initiatives are driving strategic platform adoption across multiple sectors.
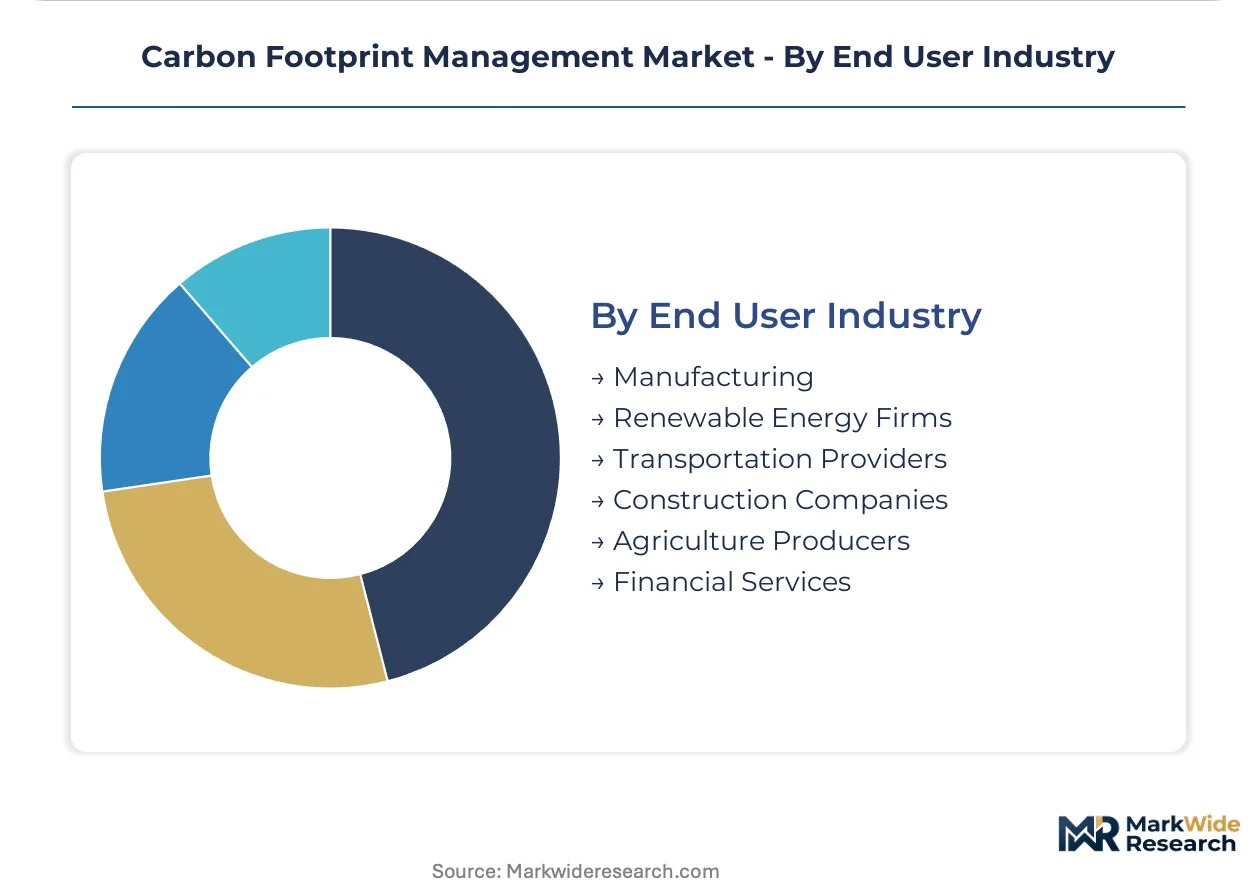
End User Industry:
Customer type influences the specific regulatory compliance needs and operational integration demands for carbon management platforms.
- Manufacturing:This sector embeds emissions data into operational planning to identify inefficiencies, reduce energy costs, and optimize production processes. Industrial firms in Germany are adopting sophisticated tracking solutions due to complex supply chains.
- Financial Services:Firms in this industry require robust platforms for climate-related financial risk assessment, portfolio decarbonization, and compliance with emerging disclosure rules from bodies like the SEC. Investment-grade data is critical for these institutions.
- Renewable Energy Firms:These companies utilize carbon management to track their own operational emissions and to verify the carbon benefits of their energy generation.
- Transportation Providers:Logistics and shipping companies employ these systems to monitor fuel consumption and optimize routes, reducing their significant Scope 1 and 3 emissions.
- Construction Companies:Firms in construction use carbon management to assess the environmental impact of building materials and construction processes.
- Agriculture Producers:This sector uses carbon footprinting to measure emissions from farming practices and to comply with sustainability standards for food production.
Manufacturing firms represent a foundational demand source, while financial services are rapidly expanding their adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global carbon footprint management market reflects a dynamic interplay between nations seeking to balance industrial output with environmental stewardship. Countries with significant export-oriented manufacturing bases are increasingly compelled to adopt robust carbon accounting solutions. This global imperative drives demand across diverse economic landscapes, from established industrial powers to rapidly industrializing regions.
Germany
Demand for advanced carbon accounting platforms intensifies in Germany, driven by its extensive manufacturing sector and stringent regulatory environment. The EU's Corporate Sustainability Reporting Directive (CSRD) compels detailed emissions disclosure from German enterprises. Industrial clusters in Bavaria, particularly around Munich, are adopting sophisticated tracking solutions to manage complex supply chain emissions.
Japan
Japanese companies require granular emissions data to navigate complex, multi-tier supply chains and meet evolving sustainability standards. The Ministry of Economy, Trade and Industry (METI) promotes corporate sustainability initiatives, including carbon footprint management. Major automotive and electronics manufacturers in the Kanto region are integrating these tools into their operational planning.
United States
The United States sees demand for auditable emissions data, particularly from financial services and large corporations. Proposed SEC climate disclosure rules elevate the strategic importance of enterprise-grade carbon platforms for publicly traded companies. Technology hubs in California, such as Silicon Valley, are developing and adopting advanced analytics solutions for environmental reporting.
China
China's vast manufacturing base and ambitious dual carbon goals are accelerating the adoption of carbon management solutions. The Ministry of Ecology and Environment (MEE) implements policies to reduce industrial emissions and promote green development. Enterprises within the Yangtze River Delta economic zone are investing in systems to track and optimize their carbon output.
United Kingdom
Corporate sustainability initiatives and a strong regulatory push define the United Kingdom's carbon footprint management market. The UK Green Finance Strategy encourages businesses to measure and report their environmental impact. London's financial sector and numerous consulting firms are driving the adoption of compliance management and risk assessment tools.
Carbon Footprint Management Market Key Industry Players
Concentration sits with technology giants and specialized software providers, creating a tiered market structure. Large enterprises often leverage established cloud infrastructure providers for scalable solutions. The market segments into foundational compliance tools, advanced analytics platforms, and specialized advisory services for complex industrial applications. Strategic partnerships between technology firms and sustainability consultants represent a dominant competitive move.
Technology providers like Microsoft and IBM occupy a significant position, leveraging their extensive cloud infrastructure and AI capabilities. Schneider Electric exemplifies a specialized industrial player, offering energy management solutions integrated with carbon tracking for operational efficiency. These entities represent different archetypes within the market, from broad platform providers to sector-specific specialists.
| Leading Market Players |
|---|
| Klöckner & Co |
| Patagonia |
| Microsoft |
| Unilever |
| IBM |
| Schneider Electric |
| Amazon |
| Planet FWD |
Cost & Logistics Intelligence
Extended data integration lead times for enterprise-grade platforms directly influence supply chain configuration and pricing power. This dynamic shapes the market for carbon footprint management solutions.
Pricing Analysis
Configured-to-order platform implementations command a significant premium over standard subscription models for carbon accounting software. The dominant pricing model is SaaS-tiered, reflecting feature sets and user volumes. Customization level and bundled after-sales service drive differentiation. Pricing pressure stems from the availability of lower-cost estimation tools lacking auditability. Smaller and mid-sized organizations exhibit higher price sensitivity, while large enterprises prioritize comprehensive, auditable solutions.
Supply Chain Analysis
Specialized talent scarcity for hybrid sustainability and data science expertise represents a critical chokepoint in deployment and integration. Supply concentration for advanced carbon management solutions resides primarily in Germany, Japan, and the United States. The market sources heavily from foundational cloud infrastructure providers and specialized AI/analytics module developers. Data integration friction from legacy IT systems poses a structural risk to efficient implementation. Distribution runs through direct sales channels and strategic partnerships with consulting firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbon footprint management market is undergoing high-growth disruption, driven by mandatory regulatory frameworks like the EU's CSRD. This shift elevates auditable emissions data to investment-grade status, creating new strategic imperatives.
For Market Incumbents:Secure a dominant position by deeply integrating AI-driven analytics into existing platforms, moving beyond basic compliance tools. Form strategic partnerships with sustainability consultants to bridge specialized talent scarcity. The threat of simplified tool substitution requires offering advanced features and auditable data. Leverage extensive cloud infrastructure to provide scalable, accessible solutions for global enterprises.
For New Entrants and Emerging Players:Differentiate on specialized modules for product carbon footprinting, supporting eco-labeling and sustainable design initiatives. Target emerging markets in Southeast Asia, where global supply chains are expanding and regulatory expectations are rising. Predictive analytics for decarbonization pathways represents another white space opportunity. Focus on niche application areas with high data complexity and specific industry needs as a go-to-market angle.
For Investors and Strategic Acquirers:Long-term, this sits as a compliance-driven, data-intensive growth play because mandatory disclosure rules are elevating carbon data to financial-grade status. Acquisition targets should include specialized analytics providers and data integration specialists with proven multi-tier supply chain capabilities. The finalization of SEC climate disclosure rules in the United States is a critical signal to watch as an inflection indicator. Investment in platforms enabling auditable, investment-grade emissions data will yield sustained returns.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Analytics Integration | Automates data ingestion and analysis, providing dynamic decision support for large enterprises in manufacturing. |
| Product Carbon Footprinting Module Development | Supports eco-labeling initiatives and granular data demand from automotive and electronics sectors. |
| Strategic Partnership with ESG Consultancies | Bridges the specialized talent scarcity gap for complex system implementation and management. |
| Expansion into Southeast Asian Markets | Captures growth from industrializing economies as global supply chains expand. |
| Enhanced Supply Chain Data Integration | Addresses Scope 3 data complexity, a significant technical barrier for global enterprises. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during primary research, combining in-depth interviews with rigorous secondary validation. Stakeholders included Sustainability Directors, IT Procurement Managers, Operations Managers in manufacturing, and Financial Services ESG Analysts. Secondary data sources comprised EU CSRD guidelines, SEC climate proposals, GHG Protocol Corporate Standard documents, and corporate sustainability reports. This approach employed both bottom-up and top-down triangulation to ensure data accuracy.
The forecasting boundary extended across the analysis window, utilizing a sophisticated analytical framework to project market evolution. Segmentation dimensions modeled included solution type, deployment model, application area, end-user industry, and regional regulatory intensity. Compound annual growth rates were derived through a comprehensive regression analysis of historical trends and projected market drivers. Key forecast inputs included evolving regulatory compliance deadlines and advancements in Scope 3 data availability.
Material uncertainties — including geopolitical shifts, unforeseen technological breakthroughs, and economic downturns — sit outside the modeled envelope. Forecasts reflect assumptions documented at the time of analysis. Practitioners should keep alternative scenarios live as regulatory enforcement and corporate decarbonization commitments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Carbon Management and Offsetting
Carbon Verification Market
Carbon Management and Offsetting
Asia-Pacific Green Carbon Market
Carbon Management and Offsetting
Emission Trading Schemes Market
Carbon Management and Offsetting
Europe Carbon Dioxide Market
Carbon Management and Offsetting
Carbon Credit Market
Carbon Management and Offsetting
Carbon Credit Trading Platform Market
Carbon Management and Offsetting
Global Voluntary Carbon Credit Trading Market
Carbon Management and Offsetting
Emission Management Market
Carbon Management and Offsetting
Asia-Pacific Carbon Dioxide Market
Carbon Management and Offsetting
Asia-Pacific Carbon Footprint Management Market
Carbon Management and Offsetting
Voluntary Carbon Credits Market
Carbon Management and Offsetting
Carbon Management Software Market
Carbon Management and Offsetting
Track Carbon Footprint App Market
Carbon Management and Offsetting
Smart Carbon Market
Carbon Management and Offsetting
Carbon Dioxide Market
Carbon Management and Offsetting
Europe Green Carbon Market