
 China Green Building Materials Market | 2026-2036
China Green Building Materials Market Size, Share, and Industry Trends Forecast 2026-2036
China Green Building Materials Market Intelligence
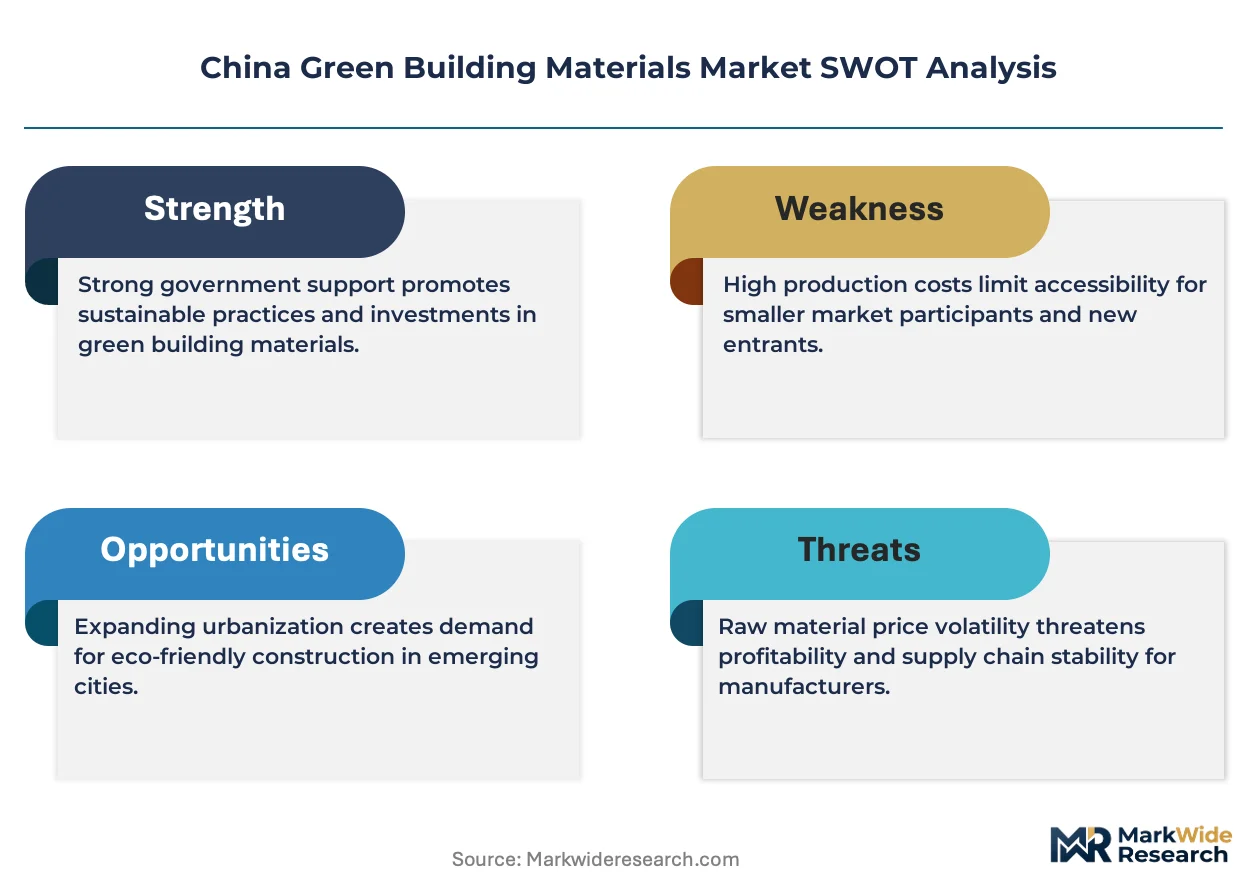
Buyer concentration among state-backed developers and infrastructure consortia is expanding, pulling procurement volume toward vertically integrated suppliers with certified low-carbon product lines. China National Building Material Co Ltd leverages its captive cement and insulation capacity to anchor municipal contracts across eastern provinces. Anhui Conch Cement Company Ltd sustains margin through slag-blend specialization and kiln efficiency upgrades. Basf SE competes on polyurethane insulation chemistry tailored to China's Three-Star Green Building standard.
China green building materials encompass engineered products and systems—insulation batts with thermal conductivity below 0.035 W/m·K, low-emissivity glazing with U-factors under 1.8 W/m²·K, and supplementary cementitious materials reducing clinker factor—that minimize operational and embodied carbon across a structure's lifecycle. Their primary purpose is to satisfy mandatory energy intensity caps while maintaining structural performance under GB standards. The insulation segment leads volume due to enforcement of GB 50189 public building efficiency codes, while bamboo as a material category captures premium residential attention for its sequestration credentials and rapid renewability. Certification under LEED and Green Guard increasingly gates access to commercial developments targeting international tenant standards.
MEE enforces dual carbon trajectory compliance through provincial emissions intensity benchmarks, while SAMR administers GB standard updates that tighten product-level carbon reporting and recyclability thresholds. BIS-equivalent conformity assessment for imported green materials adds procedural friction that favors domestic manufacturers with established testing relationships. Stakeholders must monitor whether forthcoming national carbon accounting rules for construction materials trigger specification shifts before project pipelines lock in supplier selections.
Market Dynamics
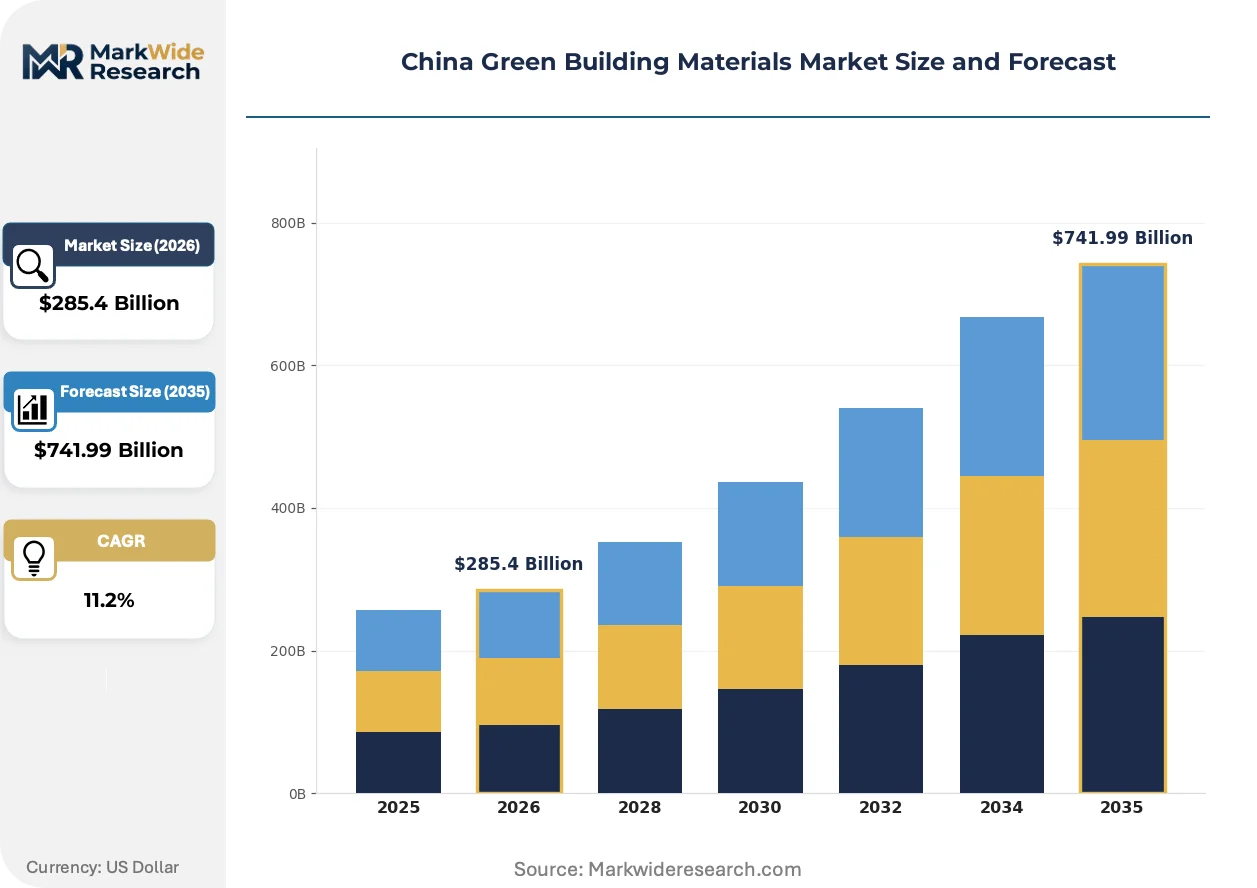
China's dual carbon mandate from MEE is compressing procurement timelines, forcing state-backed developers to lock in low-carbon concrete and certified insulation before provincial emissions intensity benchmarks tighten further. This regulatory velocity is restructuring supplier relationships around pre-certified product lines and vertically integrated manufacturing footprints.
Growth Catalysts
- MEE Dual Carbon Enforcement:Provincial emissions intensity benchmarks are compelling municipal developers to specify fly ash and slag-blend concrete in affordable housing tenders across tier-two cities.
- Shanghai Green Building Codes:Three-Star certification requirements for public buildings are pulling specification volume toward high-performance glazing and sub-0.035 W/m·K insulation batts.
- Yangtze River Delta Clustering:Concentrated infrastructure investment in Jiangsu and Zhejiang provinces is anchoring demand for certified low-carbon materials near manufacturing hubs.
Market Restraints
- Clinker Input Volatility:Cement producers face margin pressure from energy-intensive kiln operations and fluctuating coal prices that resist pass-through in state-tendered contracts.
- Import Certification Friction:SAMR-administered GB standard conformity assessment creates procedural delays for foreign insulation and glazing suppliers without established testing relationships.
- Technical Performance Floors:Bamboo structural materials struggle to satisfy GB load-bearing requirements for mid-rise commercial applications despite sequestration credentials.
Strategic Opportunities
- Western Province Underpenetration:Sichuan and Chongqing construction markets show specification gaps for certified low-carbon materials as MEE benchmarks extend beyond coastal provinces.
- Industrial-Commercial Hybrid Retrofits:Aging manufacturing facility conversions into logistics centers create demand for high-R-value insulation compatible with existing steel frames.
- Digital Procurement Platforms:Municipal tender digitization is enabling direct supplier-buyer matching that bypasses traditional distribution layers in Jiangsu province.
Industry Challenges
- Carbon Accounting Skill Scarcity:Project developers lack personnel trained in embodied carbon lifecycle assessment under forthcoming national construction material accounting rules.
- Certification Timeline Compression:Three-Star Green Building standard documentation requirements are extending project approval cycles beyond developer liquidity windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Green Building Materials Market |
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $741.99 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulation, Windows, Roofing, Flooring Application: Residential, Commercial, Industrial, Institutional Material: Wood, Concrete, Recycled Metal, Bamboo Certification: LEED, BREEAM, Green Guard, Energy Star |
| Companies Covered | Gansu Qilianshan Cement Group Co., PPG Industries Inc, China National Building Material Co Ltd, Binderholz, Basf SE, Anhui Conch Cement Company Ltd, Owens Corning, Alumasc Group plc, Huaxin Cement Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Green Building Materials Market Strategic Shifts & Innovations
Digital fabrication and chemistry optimization are compressing the gap between laboratory performance and field installation, while procurement centralization is rewiring how certified materials reach project sites across eastern China.
Alkali-activated concrete formulations are automating quality control through sensor-embedded batching systems that adjust slag and fly ash ratios in real time. Municipal infrastructure consortia in Jiangsu province are piloting these systems at scale. The technology is automating compliance documentation for MEE emissions reporting, reducing manual testing overhead by embedding verification into production workflows.
GB standard updates administered by SAMR are tightening product-level carbon disclosure thresholds for insulation and glazing imports. Manufacturers without domestic testing partnerships face extended conformity assessment timelines. The regulation is accelerating backward integration among eastern province suppliers seeking captive certification capacity.
Specification decisions are consolidating within state-backed developer procurement centers that bypass traditional distributor networks. Tier-two city affordable housing tenders now route directly to certified suppliers through municipal digital platforms. This channel shift is most visible in Anhui province, where infrastructure consortia are building preferred supplier rosters around pre-verified low-carbon product lines.
China Green Building Materials Market Segmentation
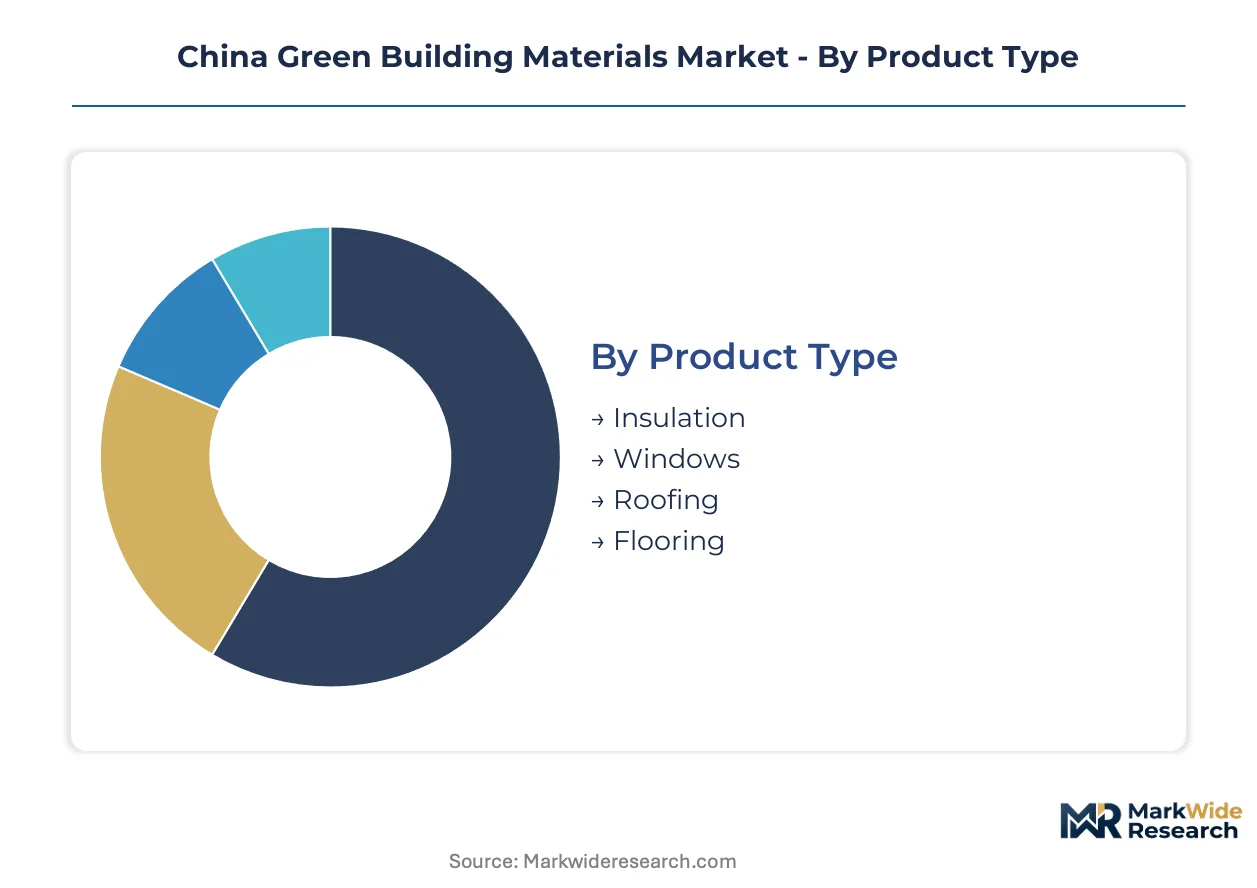
Segmentation in China's green building materials market tracks how certification requirements, thermal performance standards, and dual carbon compliance reshape procurement across product categories and end-use applications. Understanding these divisions reveals where MEE enforcement concentrates specification pressure and which supplier capabilities gate market access.
Product Type:
Certification burden varies sharply across product types, with insulation and glazing facing the most intensive GB standard testing under SAMR-administered conformity assessment protocols.
- Insulation:Mineral wool and polyurethane batts with thermal conductivity below 0.035 W/m·K dominate specification in Shanghai Three-Star public building tenders. Yangtze River Delta infrastructure consortia are locking in multi-year supply contracts for certified batts ahead of provincial emissions benchmark tightening.
- Windows:Low-emissivity glazing with U-factors under 1.8 W/m²·K commands premium positioning in commercial developments targeting international tenant standards. Anhui and Jiangsu province manufacturing clusters anchor domestic supply capacity for high-performance fenestration systems.
- Roofing:Cool roof membranes and vegetated systems reduce urban heat island effects in tier-two city affordable housing programs.
- Flooring:Bamboo and recycled content tiles capture residential attention for sequestration credentials and rapid renewability.
Leading the category by volume: Insulation. Growing fastest: Windows.
Application:
Cost tier stratification separates state-tendered affordable housing from premium commercial developments seeking LEED or Green Guard certification for international tenant compliance.
- Residential:State-backed affordable housing programs in tier-two cities are expanding procurement of fly ash and slag-blend concrete. Municipal digital platforms in Jiangsu province now route tenders directly to certified low-carbon suppliers, bypassing traditional distribution layers.
- Commercial:Three-Star Green Building standard documentation requirements extend project approval cycles for Shanghai office developments. High-performance glazing and sub-0.035 W/m·K insulation specifications concentrate in Yangtze River Delta commercial clusters.
- Industrial:Aging manufacturing facility conversions into logistics centers create demand for high-R-value insulation compatible with existing steel frames.
- Institutional:Public buildings face mandatory GB 50189 energy intensity caps that drive specification of certified materials through state procurement centers.
State-backed residential commands absolute volume. Commercial applications are climbing the fastest as international tenant standards proliferate.
Material:
Supply concentration patterns favor domestic manufacturers with captive raw material access and established SAMR testing relationships.
- Concrete:Alkali-activated formulations with real-time slag and fly ash ratio adjustment are automating MEE emissions compliance documentation. Municipal infrastructure consortia in Jiangsu province pilot these sensor-embedded batching systems at scale.
- Wood:Engineered timber products face import certification friction without BIS-equivalent conformity assessment partnerships.
- Recycled Metal:Steel with post-consumer content satisfies embodied carbon reduction mandates in industrial-commercial hybrid retrofits.
- Bamboo:Rapid renewability and sequestration credentials attract premium residential specification despite GB load-bearing limitations for mid-rise commercial applications.
Concrete dominates by volume. Bamboo is gaining share fastest in premium residential segments.
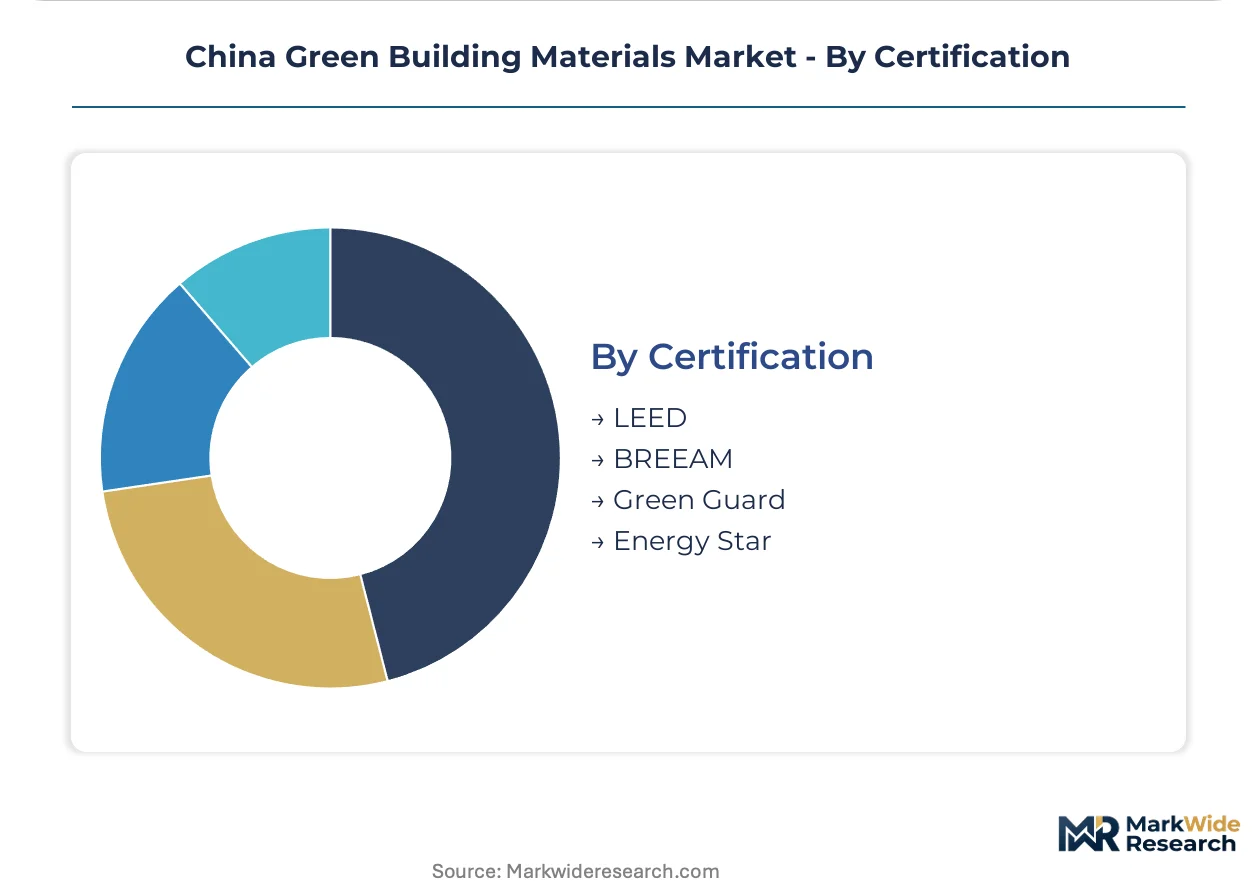
Certification:
Geography of project development determines which certification schemes gate supplier access, with coastal provinces accepting international standards and inland markets defaulting to GB compliance.
- LEED:Commercial developments in Shanghai and Shenzhen seeking international tenant occupancy require LEED documentation that favors suppliers with established Green Guard testing relationships.
- BREEAM:Limited penetration in China compared to LEED, with specification concentrated in joint-venture developments with European capital participation.
- Green Guard:Indoor air quality certification increasingly gates access to premium residential and healthcare institutional projects.
- Energy Star:Fenestration and HVAC-adjacent materials in commercial applications reference this standard for operational energy modeling compliance.
LEED leads by specification volume in coastal commercial developments. Green Guard is expanding most quickly as indoor air quality standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-backed developers concentrate procurement volume in eastern coastal provinces where MEE dual carbon enforcement is tightest. Provincial emissions intensity benchmarks create specification cascades that favor certified suppliers with established SAMR testing relationships.
Yangtze River Delta
Shanghai's Three-Star Green Building codes drive specification of sub-0.035 W/m·K insulation batts and low-emissivity glazing with U-factors under 1.8 W/m²·K. MEE provincial benchmarks compel municipal developers in Jiangsu and Zhejiang to lock in fly ash concrete contracts. Manufacturing clusters in Suzhou and Ningbo anchor domestic supply capacity for high-performance fenestration systems.
Pearl River Delta
Shenzhen commercial developments seeking international tenant occupancy require LEED documentation that favors suppliers with Green Guard testing relationships. SAMR-administered GB standard updates tighten carbon disclosure thresholds for imported materials. Guangzhou infrastructure consortia pilot alkali-activated concrete with sensor-embedded batching systems.
Beijing-Tianjin-Hebei
Capital region institutional buildings face mandatory GB 50189 energy intensity caps that concentrate procurement through state procurement centers. Affordable housing programs in Hebei tier-two cities expand fly ash and slag-blend concrete specification. Tianjin manufacturing hubs supply certified insulation for retrofit applications in aging industrial conversions.
Sichuan-Chongqing
Western province construction markets show specification gaps for certified low-carbon materials as MEE benchmarks extend beyond coastal provinces. Chongqing municipal tenders increasingly route through digital platforms that bypass traditional distribution layers. Chengdu infrastructure investment creates emerging demand for high-R-value insulation in logistics center conversions.
Shandong Peninsula
Qingdao and Yantai manufacturing bases produce mineral wool and polyurethane insulation serving northern province retrofit programs. Provincial emissions intensity targets compress procurement timelines for state-backed developers. Jinan municipal contracts favor vertically integrated suppliers with captive cement and insulation capacity.
China Green Building Materials Market Key Industry Players
Eastern province producers anchor one tier; European and North American specialists hold positioning in premium certification-dependent segments. The supplier base organizes around three archetypes: state-linked cement conglomerates with captive raw material access, chemistry-focused multinationals serving commercial specifications, and regional insulation fabricators with SAMR testing partnerships. Competitive moves concentrate on backward integration into raw material supply and pre-certification of product lines to compress tender response timelines.
Within the state-linked tier, China National Building Material Co Ltd and Anhui Conch Cement Company Ltd exemplify vertically integrated positioning with captive cement and supplementary cementitious material capacity. Among international chemistry suppliers, Basf SE occupies a position tied to polyurethane insulation formulations aligned with Three-Star Green Building standards. Gansu Qilianshan Cement Group Co. and Huaxin Cement Co. represent regional specialists with slag-blend specialization and kiln efficiency positioning.
| Leading Market Players |
|---|
| Gansu Qilianshan Cement Group Co. |
| PPG Industries Inc |
| China National Building Material Co Ltd |
| Binderholz |
| Basf SE |
| Anhui Conch Cement Company Ltd |
| Owens Corning |
| Alumasc Group plc |
| Huaxin Cement Co. |
| Others |
Cost & Logistics Intelligence
Captive cement and insulation capacity anchors pricing power for state-linked conglomerates bidding municipal contracts across eastern provinces. China National Building Material Co Ltd leverages in-house production of slag-blend formulations and certified batts to compress tender response timelines while insulating margins from volatile clinker input costs that resist pass-through in state-tendered affordable housing programs.
Pricing Analysis
Volume concentrates in state-backed residential tenders while margins accrue to premium commercial specifications. Three-tier pricing structure across premium, standard, and economy levels separates LEED-certified glazing for Shanghai office developments from GB-compliant insulation for tier-two city housing projects. Cost compression in economy tiers intensifies because coal price volatility resists full pass-through in municipal contracts. State procurement centers exhibit highest price sensitivity; international tenant-facing commercial developers show lowest.
Supply Chain Analysis
Dual-sourcing requirements from municipal infrastructure consortia mandate multi-supplier qualification for fly ash and slag-blend concrete to mitigate single-source vulnerability. Manufacturing concentrates in China, with raw material draws from domestic limestone deposits and imported supplementary cementitious materials. Supply chain risk centers on SAMR-administered GB standard conformity assessment delays for foreign insulation suppliers. Distribution runs through municipal digital platforms that bypass traditional distributor layers in Jiangsu and Anhui provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEE dual carbon enforcement and SAMR-administered GB standard updates constitute a cost-of-compliance story that erects barrier-to-entry moats around domestic manufacturers with established testing relationships and pre-certified product lines.
For Market Incumbents: To counter margin pressure from energy-intensive kiln operations and fluctuating coal prices, deepen backward integration into captive fly ash supply and accelerate sensor-embedded batching system deployment across Jiangsu province manufacturing footprints. Lock in multi-year municipal contracts before provincial emissions intensity benchmarks tighten further. For New Entrants and Emerging Players: Begin with western province underpenetration in Sichuan and Chongqing, where MEE benchmark extension creates specification gaps for certified low-carbon materials absent established supplier rosters. Target industrial-commercial hybrid retrofit applications in aging manufacturing facility conversions. Route go-to-market through municipal digital procurement platforms that enable direct supplier-buyer matching. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by state-linked cement conglomerates seeking regional capacity expansion and SAMR certification capacity. Long-term viability favors suppliers with vertically integrated manufacturing footprints and pre-certified product lines aligned with Three-Star Green Building standards. Watch for forthcoming national carbon accounting rules for construction materials as inflection indicator triggering specification shifts before project pipelines lock.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fly Ash Supply | Captive supplementary cementitious material access secures MEE compliance documentation for municipal tenders. |
| Sensor-Embedded Batching System Deployment | Real-time slag and fly ash ratio adjustment automates emissions reporting for Jiangsu infrastructure consortia. |
| SAMR Certification Capacity Investment | In-house GB standard testing relationships compress conformity assessment timelines for insulation and glazing imports. |
| Digital Procurement Platform Integration | Direct supplier-buyer matching through municipal tender digitization bypasses traditional distribution layers. |
| Three-Star Green Building Pre-Certification | Pre-verified product lines anchor preferred supplier rosters for Shanghai commercial developments. |
Research Approach
Multi-period observation of provincial emissions intensity benchmarks, municipal tender digitization rates, and GB standard update timelines anchored the trend analysis, supplemented by interviews with cement plant managers, state developer procurement leads, SAMR certification specialists, and polyurethane chemistry R&D directors. Secondary validation drew from MEE policy circulars, SAMR standard drafts, China Customs trade data, and provincial infrastructure investment disclosures. Bottom-up project pipeline tracking triangulated against top-down construction sector output estimates.
Input-output matrices mapped product-type, application, material, and certification dimensions across the projection horizon. Modeled variables included clinker factor reduction rates, thermal conductivity specification thresholds, and provincial dual carbon compliance trajectories. CAGRs derived from segment-level volume builds calibrated to municipal tender award patterns and manufacturing capacity utilization trends. Industry-specific forecast inputs encompassed MEE enforcement velocity and SAMR testing relationship prevalence.
Underlying measurement precision varies by segment; insulation and glazing carry tighter precision than bamboo structural materials given GB load-bearing uncertainty. Forecasts reflect assumptions regarding MEE benchmark implementation timing and SAMR conformity assessment procedural stability. Deviation in national carbon accounting rule promulgation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Eco-Friendly Bitumen Market
Green Building Materials
Global Green Walls Market
Green Building Materials
Eco Flooring Market
Green Building Materials
Solar Glass Market
Green Building Materials
Europe Green Cement Market
Green Building Materials
Green Concrete Market
Green Building Materials
North America Green Cement Market
Green Building Materials
Green Rebar Market
Green Building Materials
Sustainable and Green Building Materials Market
Green Building Materials
Green Silica Market
Green Building Materials
United States Green Cement Market
Green Building Materials
Artificial Green Wall Market
Green Building Materials
Green Roof Market
Green Building Materials
APAC Green Buildings Market
Green Building Materials
Green Cement Market
Green Building Materials
Green Building Materials Market