
 Sustainable and Green Building Materials Market | 2026-2036
Sustainable and Green Building Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable and Green Building Materials Market Insights
Cross-laminated timber and bio-based insulation integration is reconfiguring structural engineering workflows across mid-rise construction. BASF SE leverages its polymer science portfolio to develop low-emission adhesive systems for engineered wood assemblies. Saint-Gobain anchors European supply of recycled-content gypsum and glass wool through vertically integrated mineral sourcing. Owens Corning competes on roofing membrane durability, extending product lifecycles that reduce whole-building embodied carbon.
Sustainable and green building materials encompass engineered and naturally sourced products manufactured to minimize embodied energy, operational carbon, and toxic emissions across a structure's lifecycle; cross-laminated timber achieves structural grades of GL28c with adhesive layers under three millimeters, while cellulose insulation delivers thermal resistance of R-3.7 per inch from 85% recycled paper content. These materials primarily serve to reduce operational energy demand and satisfy third-party environmental certification for commercial and institutional assets. Among product types, recycled steel dominates structural framing for its end-of-life recyclability and established scrap collection infrastructure, yet bamboo grows fastest in interior finishing applications where aesthetic differentiation commands margin premiums. Certification segmentation shows LEED maintains broadest geographic recognition among end users, though BREEAM adoption is deepening in European commercial complexes where regulatory alignment with EU Green Deal targets accelerates specification.
The EPA enforces emissions standards for formaldehyde in composite wood products under TSCA Title VI, compelling domestic manufacturers to certify through third-party testing bodies. ECHA implements REACH restrictions on hazardous substances in construction chemicals, reshaping formulation requirements for European adhesive and sealant suppliers. China's MEE advances dual carbon goals through GB standards for green building evaluation, restricting high-emission materials in public projects. Stakeholders must monitor divergence between regional carbon accounting methodologies, as inconsistency in scope boundaries threatens cross-border material equivalency and project financing eligibility.
Market Dynamics
The EU Green Deal's embodied carbon benchmarks are forcing concrete and insulation manufacturers to reformulate product chemistries, while federal retrofit mandates in Germany concentrate specification demand for bio-based envelope systems across educational and government facilities.
Growth Catalysts
- KfW Green Building Finance:Germany's federal development bank channels low-interest capital toward rammed earth and cellulose insulation in public sector construction, de-risking architect and developer adoption of non-conventional materials.
- Commercial Complex Certification:Asset managers pursuing LEED and BREEAM ratings accelerate procurement of certified low-carbon envelope systems to meet portfolio decarbonization targets and secure green bond eligibility.
- Cross-Laminated Timber Engineering:Structural grades achieving GL28c performance with sub-three-millimeter adhesive layers enable mid-rise construction applications previously reserved for steel and concrete framing.
Market Restraints
- Adhesive Input Volatility:Low-emission adhesive systems depend on petrochemical-derived polymers subject to feedstock price swings, compressing margins for engineered wood manufacturers during crude oil fluctuations.
- Scrap Collection Infrastructure Gaps:End-of-life recyclability of structural steel remains theoretical in markets lacking established demolition waste sorting and regional reprocessing facilities.
- Formaldehyde Testing Bottlenecks:EPA TSCA Title VI third-party certification timelines create months-long delays for composite wood product launches, freezing working capital in inventory.
Strategic Opportunities
- Bamboo Interior Finishing:Aesthetic differentiation in premium residential and hospitality segments commands margin premiums where species certification and supply chain traceability can be guaranteed.
- GB Standards Alignment:China's MEE dual carbon goals restrict high-emission materials in public projects, creating first-mover advantage for suppliers with verified embodied carbon data under national green building evaluation protocols.
- Digital Material Passports:Blockchain-enabled lifecycle tracking converges with ECHA REACH compliance documentation, enabling specification in EU commercial complexes where regulatory alignment accelerates environmental product declaration adoption.
Industry Challenges
- Carbon Accounting Skill Deficits:Lifecycle assessment expertise remains scarce among mid-sized architectural practices, delaying project documentation for BREEAM and LEED submission deadlines.
- Regional Methodology Divergence:Inconsistent scope boundaries between EU, US, and Chinese carbon accounting frameworks threaten cross-border material equivalency and project financing eligibility for multinational developments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable and Green Building Materials Market |
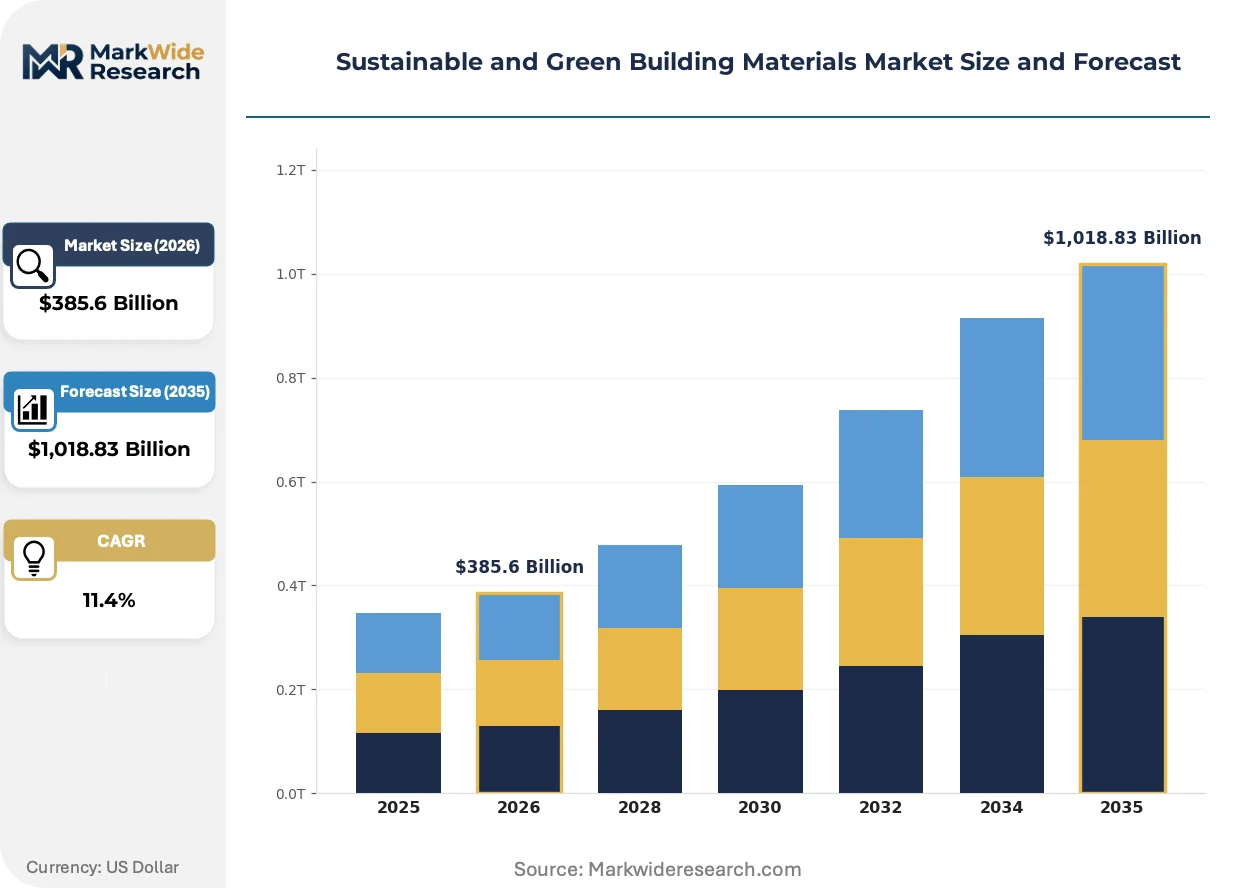
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $1,018.83 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bamboo, Recycled Steel, Rammed Earth, Cork, Cellulose Insulation Application: Building Envelope, Interior Finishing, Foundations, Landscaping, Roofing End Use Industry: Commercial Complexes, Educational Institutes, Government Facilities, Hospitality Venues, Warehousing Certification: LEED, BREEAM, Green Star, WELL Building Standard, Living Building Challenge |
| Companies Covered | Kingspan Group plc, Holcim Ltd, Owens Corning, Saint-Gobain, BASF SE, PPG Industries, DuPont, Sika AG, CertainTeed Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable and Green Building Materials Market Trends and Innovations
Digital fabrication and bio-based chemistry are compressing traditional material procurement cycles while regulatory disclosure requirements reshape specification workflows across commercial and institutional construction.
Building information modeling integrated with embodied carbon databases is virtualizing material selection processes. Architects and structural engineers now simulate whole-building carbon footprints before procurement commitment, compressing traditional specification timelines from months to weeks. Mid-rise commercial developers in Scandinavia and the Pacific Northwest lead adoption, using these platforms to optimize cross-laminated timber and recycled steel ratios against cost and performance constraints.
REACH restrictions on hazardous substances in construction chemicals are reformulating adhesive and sealant supply chains. European manufacturers face mandatory substitution of legacy chemistries with bio-based alternatives, raising raw material qualification costs but opening specification pathways in public sector tenders with mandatory green procurement clauses. German and French commercial complexes show deepest compliance investment, where regulatory alignment with EU Green Deal targets accelerates environmental product declaration integration into technical submittals.
Performance-based material procurement is displacing commodity-grade specification in institutional construction. University and hospital capital projects now contract for thermal and acoustic outcomes rather than product categories, unbundling traditional distribution relationships and rewarding suppliers with verified in-situ performance data. This pattern concentrates in German federal states with active KfW green building finance programs, where outcome verification ties to ongoing energy monitoring requirements.
Sustainable and Green Building Materials Market Segmentation
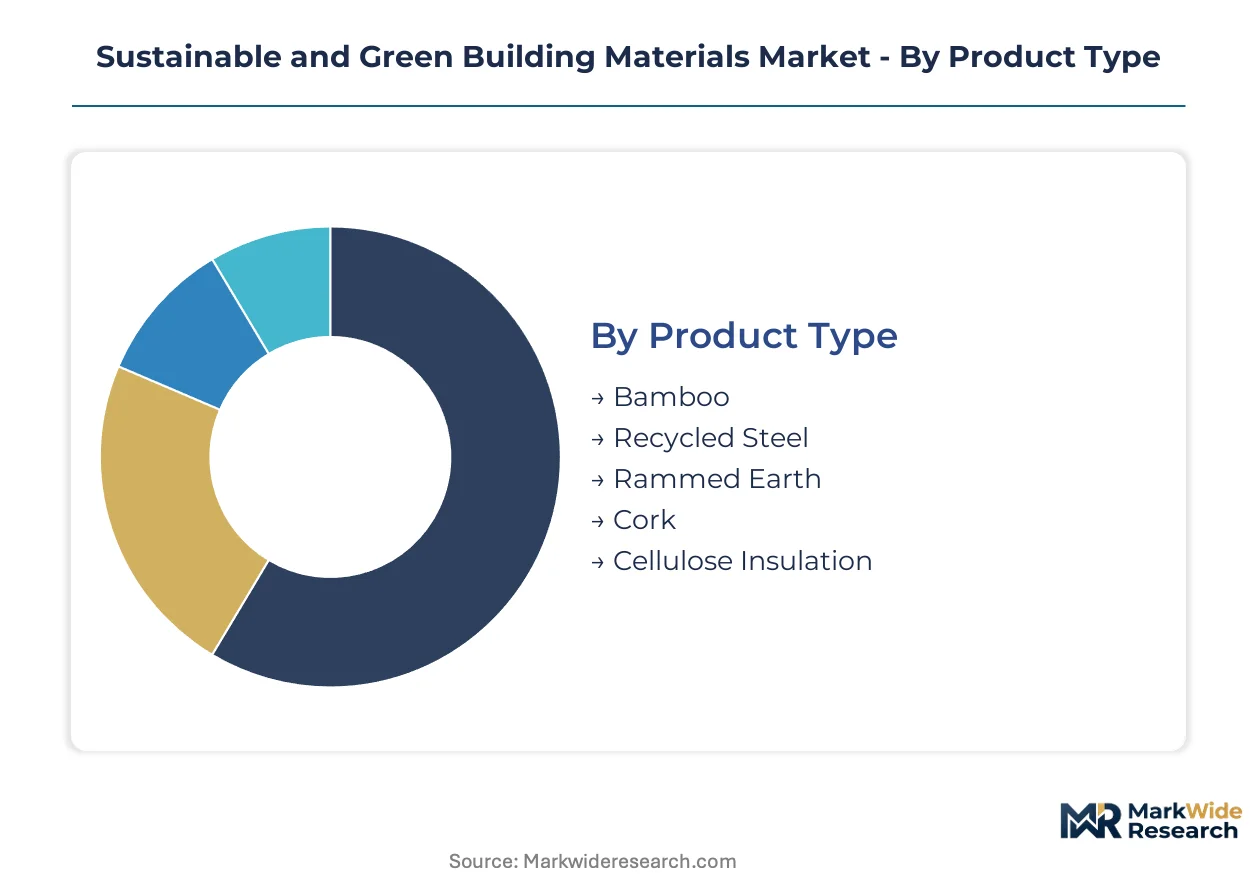
Specification workflows in sustainable construction differ dramatically by material lifecycle and procurement cadence. Architects and developers must match segment characteristics to project timelines, certification requirements, and financing conditions.
Product Type:
Replacement cycles stretch from decades for structural materials to under ten years for interior finishes, reshaping inventory and specification strategies across manufacturer portfolios.
- Recycled Steel:Structural framing fabricated from electric arc furnace production achieves yield strengths of 355 MPa with end-of-life recyclability exceeding 90%. Demand concentrates in German commercial complexes where federal KfW green building finance mandates embodied carbon disclosure for structural systems.
- Cellulose Insulation:Loose-fill and dense-pack formulations deliver thermal resistance of R-3.7 per inch from 85% recycled paper content treated with borate fire retardants. German educational institutes and government facilities drive specification through retrofit mandates requiring bio-based envelope materials.
- Bamboo:Engineered panels and solid stalk products serve interior finishing applications where rapid renewability and aesthetic grain patterns command premium positioning.
- Rammed Earth:Compressed soil-cement mixtures achieve compressive strengths of 2-5 MPa for load-bearing walls in low-rise institutional construction.
- Cork:Expanded bark products provide acoustic and thermal insulation with negative embodied carbon credentials from carbon-sequestering harvest practices.
Recycled steel dominates installed base. Cellulose insulation is where expansion concentrates.
Application:
Cost tiers separate capital-intensive structural systems from discretionary interior treatments, with envelope performance now tied to operational energy guarantees in institutional procurement.
- Building Envelope:Continuous insulation and high-performance glazing assemblies determine whole-building thermal bridging and airtightness metrics. German government facilities mandate envelope upgrades through federal retrofit programs channeling KfW finance toward certified low-carbon systems.
- Interior Finishing:Surface materials, fixtures, and partition systems rotate on shorter replacement cycles aligned with tenant improvement schedules. Hospitality venues in premium European markets specify bamboo and cork for aesthetic differentiation tied to wellness certification narratives.
- Foundations:Low-carbon concrete alternatives and engineered fill materials address subsurface structural requirements with emerging embodied carbon accounting.
- Landscaping:Permeable paving, reclaimed hardscape, and bio-based site furnishings complete site sustainability profiles for commercial complexes pursuing comprehensive certification.
- Roofing:Membrane systems and vegetated assemblies balance durability warranties against thermal performance and stormwater management outcomes.
Building envelope captures the steepest expansion trajectory as operational energy guarantees become standard in institutional contracts. Interior finishing retains the largest addressable surface area across renovation cycles.
End Use Industry:
Customer types diverge by procurement sophistication, with public sector entities embedding environmental criteria into mandatory technical specifications while private developers respond to asset management and financing pressures.
- Commercial Complexes:Multi-tenant office and retail assets pursue LEED and BREEAM ratings to secure green bond eligibility and portfolio decarbonization targets. Asset managers accelerate procurement of certified low-carbon envelope systems to meet disclosure requirements.
- Government Facilities:Federal, state, and municipal construction operates under mandatory green procurement clauses with verified embodied carbon thresholds. German federal retrofit mandates concentrate specification demand for rammed earth and cellulose insulation across educational and administrative buildings.
- Educational Institutes:University and K-12 capital projects contract for thermal and acoustic outcomes rather than product categories, unbundling traditional distribution relationships.
- Hospitality Venues:Premium hotels and resorts leverage material narratives for guest experience differentiation and wellness certification alignment.
- Warehousing:Logistics facilities prioritize rapid enclosure with emerging interest in operational carbon reduction for net-zero distribution commitments.
Government facilities dominate specification volume through procurement mandates. Commercial complexes are climbing the fastest as private capital aligns with environmental disclosure frameworks.
Certification:
Geographic recognition patterns determine specification relevance, with regional regulatory alignment accelerating adoption of specific protocols over others.
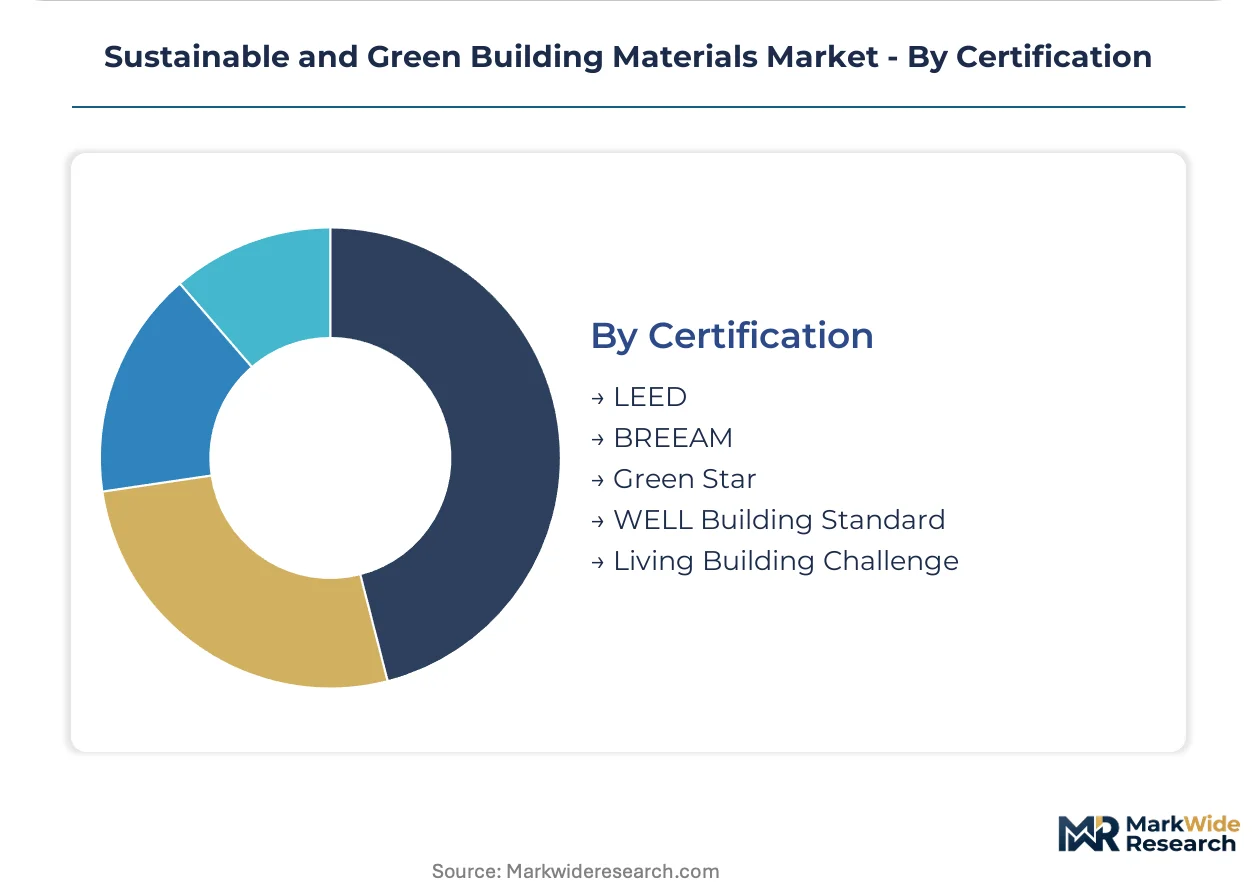
- LEED:The US Green Building Council's rating system maintains broadest geographic recognition among end users across North American commercial and institutional construction. Federal and municipal procurement in multiple countries references LEED equivalency for green building requirements.
- BREEAM:The Building Research Establishment's assessment method deepens adoption in European commercial complexes where EU Green Deal regulatory alignment accelerates specification. German and French projects show deepest compliance investment with mandatory environmental product declaration integration.
- Green Star:The Green Building Council of Australia's protocol serves Australasian markets with climate-specific adaptation criteria.
- WELL Building Standard:The International WELL Building Institute's focus on occupant health and wellness drives specification in premium commercial and hospitality segments.
- Living Building Challenge:The International Living Future Institute's stringent materials red list and net-positive energy requirements attract mission-driven institutional clients with extended capital timelines.
LEED dominates installed base across diverse geographies. BREEAM is where expansion concentrates as EU regulatory alignment deepens commercial complex adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export low-carbon envelope systems to Nordic commercial developers, while Chinese suppliers ship engineered bamboo products to Southeast Asian hospitality contractors.
Germany
Federal retrofit mandates and KfW green building finance accelerate specification of rammed earth and cellulose insulation across educational institutes and government facilities. The EU Green Deal's embodied carbon benchmarks compel domestic manufacturers to reformulate concrete and insulation chemistries. Bavaria concentrates advanced manufacturing of cross-laminated timber assemblies serving mid-rise commercial construction.
United States
Commercial asset managers pursuing LEED certification accelerate procurement of certified low-carbon envelope systems to secure green bond eligibility. EPA TSCA Title VI enforces formaldehyde emissions standards for composite wood products through third-party certification bodies. The Pacific Northwest leads adoption of building information modeling integrated with embodied carbon databases for virtualized material selection.
China
Public project procurement under MEE dual carbon goals restricts high-emission materials while creating first-mover advantage for suppliers with verified embodied carbon data. GB standards for green building evaluation reshape technical specifications for government and institutional construction. The Yangtze River Delta concentrates production capacity for low-carbon concrete alternatives and engineered fill materials.
France
Commercial complexes deepen BREEAM adoption where regulatory alignment with EU Green Deal targets accelerates environmental product declaration integration. ECHA REACH restrictions on hazardous substances in construction chemicals mandate substitution of legacy adhesive and sealant formulations. The Île-de-France region anchors specification demand for bio-based envelope systems in premium office and retail assets.
United Kingdom
Institutional capital projects contract for thermal and acoustic outcomes rather than product categories, unbundling traditional distribution relationships. Building regulations increasingly reference embodied carbon thresholds for structural and envelope materials in public sector tenders. London and the Southeast concentrate performance-based procurement innovation among university and hospital developments.
Sustainable and Green Building Materials Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. BASF SE and Saint-Gobain anchor integrated material portfolios spanning adhesives, insulation, and mineral products, while regional timber engineers and bio-based insulation fabricators occupy niche specification pathways. Three archetypes dominate: multinational chemical conglomerates with polymer science capabilities, vertically integrated building material suppliers with captive mineral sourcing, and specialized engineered wood producers with certified sustainable forestry chains. Competitive moves concentrate on portfolio diversification into low-emission product lines and strategic partnerships with architectural specification platforms.
Among European-based material suppliers, Kingspan Group plc and Holcim Ltd exemplify scale-driven archetypes with building envelope and cement portfolio breadth, while Sika AG occupies a specialist position in construction chemical systems. Owens Corning and Saint-Gobain anchor North American and European supply respectively for roofing and insulation assemblies where product lifecycle extension reduces whole-building embodied carbon. These named entities represent competitive positioning patterns rather than definitive market share claims.
| Leading Market Players |
|---|
| Kingspan Group plc |
| Holcim Ltd |
| Owens Corning |
| Saint-Gobain |
| BASF SE |
| PPG Industries |
| DuPont |
| Sika AG |
| CertainTeed Corporation |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in European cross-laminated timber production drives dual supplier behavior: incumbent chemical conglomerates extend payment terms to lock specification share while regional timber engineers absorb margin compression to secure KfW-financed public sector contracts.
Pricing Analysis
Next-generation bio-based adhesive systems command 15-25% premiums over incumbent petrochemical formulations, while legacy formaldehyde-compliant products face accelerating price erosion. Three-tier pricing structure across certified low-carbon, conventional compliant, and uncertified commodity levels stratifies by BREEAM and LEED tier alignment. Cost compression in cellulose insulation runs through recycled paper feedstock volatility and borate fire retardant sourcing constraints. Government facilities exhibit lowest price sensitivity given mandated green procurement clauses, while speculative commercial developers in secondary markets retain acute cost discipline.
Supply Chain Analysis
Upstream softwood lumber and bamboo pulp feedstock concentration in Germany, Austria, and China shapes raw material availability for engineered wood and bio-based insulation producers. Manufacturing draws from petrochemical-derived isocyanates for low-emission adhesives, recycled steel scrap streams, and mineral wool feedstocks from captive gypsum sourcing. Single-source vulnerability persists in certified sustainable forestry chains where FSC and PEFC audit backlogs constrain volume scaling. Distribution runs through specification-influencing architectural platforms and direct contractor relationships for institutional projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's embodied carbon benchmarks constitute a regulatory inflection compressing material procurement cycles from specification to installation, elevating first-mover advantage for suppliers with verified environmental product declarations.
For Market Incumbents: Insulate specification share by deepening backward integration into certified sustainable forestry chains and captive mineral sourcing for insulation feedstocks. BASF SE and Saint-Gobain demonstrate defensive positioning through polymer science R&D into low-emission adhesive systems that preempt REACH substitution mandates. Capacity addition in Bavaria and the Yangtze River Delta anchors regional supply security against logistics chokepoint exposure. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia and secondary Chinese cities represent the most penetrable entry point given lagging green procurement enforcement and growing asset manager ESG disclosure pressure. Bamboo interior finishing for hospitality venues offers margin premium capture where species certification and blockchain-enabled supply chain traceability can be guaranteed. Digital material passport platforms enable specification bypass of incumbent distributor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory arbitrage play because jurisdictional divergence in carbon accounting methodologies creates acquisition targets with stranded asset risk or undervalued certification infrastructure. Vertically integrated building material suppliers with captive mineral sourcing and established environmental product declaration libraries represent optimal acquisition profiles. The signal to watch is harmonization between EU, US, and Chinese embodied carbon scope boundaries that would trigger rapid revaluation of cross-border material equivalency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Forestry | Captive FSC and PEFC supply secures specification eligibility for KfW-financed German public projects. |
| Environmental Product Declaration Expansion | Verified embodied carbon data unlocks BREEAM and LEED procurement pathways in EU commercial complexes. |
| Digital Material Passport Development | Blockchain-enabled lifecycle tracking converges with ECHA REACH compliance for specification automation. |
| Bio-Based Adhesive Scale-Up | Low-emission polymer systems preempt petrochemical feedstock volatility and regulatory substitution mandates. |
| Performance-Based Procurement Partnerships | Outcome contracting for thermal and acoustic metrics unbundles traditional distribution in institutional construction. |
Research Methodology
Desk research of trade association technical publications, customs and trade flow databases, and regulatory filing repositories preceded structured interviews with architectural specification consultants, structural engineering directors, green building certification auditors, and procurement officers at federal development banks. Primary fieldwork with plant managers at cross-laminated timber facilities and cellulose insulation fabricators validated capacity utilization and feedstock cost assumptions. Secondary sources encompassed EU Green Deal implementation guidance, EPA TSCA Title VI certification timelines, and China MEE GB standards documentation. Bottom-up segment sizing triangulated against top-down construction spending forecasts.
Assumptions held fixed include current EU Green Deal embodied carbon benchmark trajectories and existing KfW green building finance program structures, while variables encompassed crude oil price bands affecting petrochemical adhesive input costs and demolition waste sorting infrastructure development rates. The analytical framework modeled product type, application, end-use industry, and certification segmentation dimensions across the projection horizon. CAGRs derived from regression analysis of historical specification penetration rates against regulatory enforcement intensity and green bond issuance velocity. Industry-specific inputs included electric arc furnace steel production capacity expansion schedules and bamboo plantation maturation cycles.
Practitioners should monitor regulatory harmonization negotiations between EU, US, and Chinese carbon accounting bodies for early signals of cross-border material equivalency shifts. Forecasts reflect assumptions about continued federal retrofit mandate enforcement in Germany and sustained MEE dual carbon goal implementation in Chinese public procurement. Cross-checking against IEA building sector decarbonization roadmaps and national green building council certification volume disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Green Building Market
Green Building Materials
Outdoor Flooring Market
Green Building Materials
United States Green Cement Market
Green Building Materials
Global Green Walls Market
Green Building Materials
Europe Green Cement Market
Green Building Materials
GCC Green Cement Market
Green Building Materials
Green Building Materials Market
Green Building Materials
China Green Building Materials Market
Green Building Materials
Green Cement and Concrete Market
Green Building Materials
Solar Glass Market
Green Building Materials
Green Waterproofing Products Market
Green Building Materials
Solar Frames Market
Green Building Materials
Asia Pacific Green Cement Market
Green Building Materials
APAC Green Buildings Market
Green Building Materials
Solar Windows Market
Green Building Materials
Global Eco-Friendly Green Roofs Market