
 Asia Pacific Green Cement Market | 2026-2036
Asia Pacific Green Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Green Cement Market Insights
Modular specification packages combining fly ash-based and slag-based blends is hardening as the dominant procurement format across large infrastructure tenders. UltraTech Cement Ltd leverages its pan-India manufacturing footprint to anchor blended cement supply for government highway contracts. China National Building Material Company sustains vertical integration from mineral processing to ready-mix distribution, controlling cost structures across multiple provinces. Siam Cement Group differentiates through specialized geopolymer formulations for marine exposure zones in Thai port expansions.
Asia Pacific green cement denotes hydraulic binders manufactured with clinker substitution rates exceeding standard Portland cement, typically incorporating supplementary cementitious materials such as fly ash, ground granulated blast-furnace slag, or metakaolin to achieve embodied carbon reductions. The material serves primarily to decarbonize structural concrete in buildings, roads, and industrial foundations where strength grade and sulfate resistance must meet national construction codes. Fly ash-based products occupy the largest volume share given proximate supply from coal-fired power generation across China and India, though geopolymer segments attract premium positioning for aggressive carbon reduction targets in commercial infrastructure. Slag-based blends compete on durability performance in coastal road construction, where chloride ingress resistance commands specification priority from environmental agencies and government bodies.
China's Ministry of Ecology and Environment enforces dual carbon goals that cap clinker capacity and mandate alternative fuel co-processing, while India's Bureau of Indian Standards revised cement grading to incentivize higher pozzolanic content. The EU Green Deal's carbon border adjustment mechanism, though externally focused, shapes export-facing plant investment decisions across the region. Stakeholders must monitor how national building codes evolve to recognize geopolymer performance equivalency, as this determination will unlock or constrain application scope across residential and industrial segments.
Market Dynamics
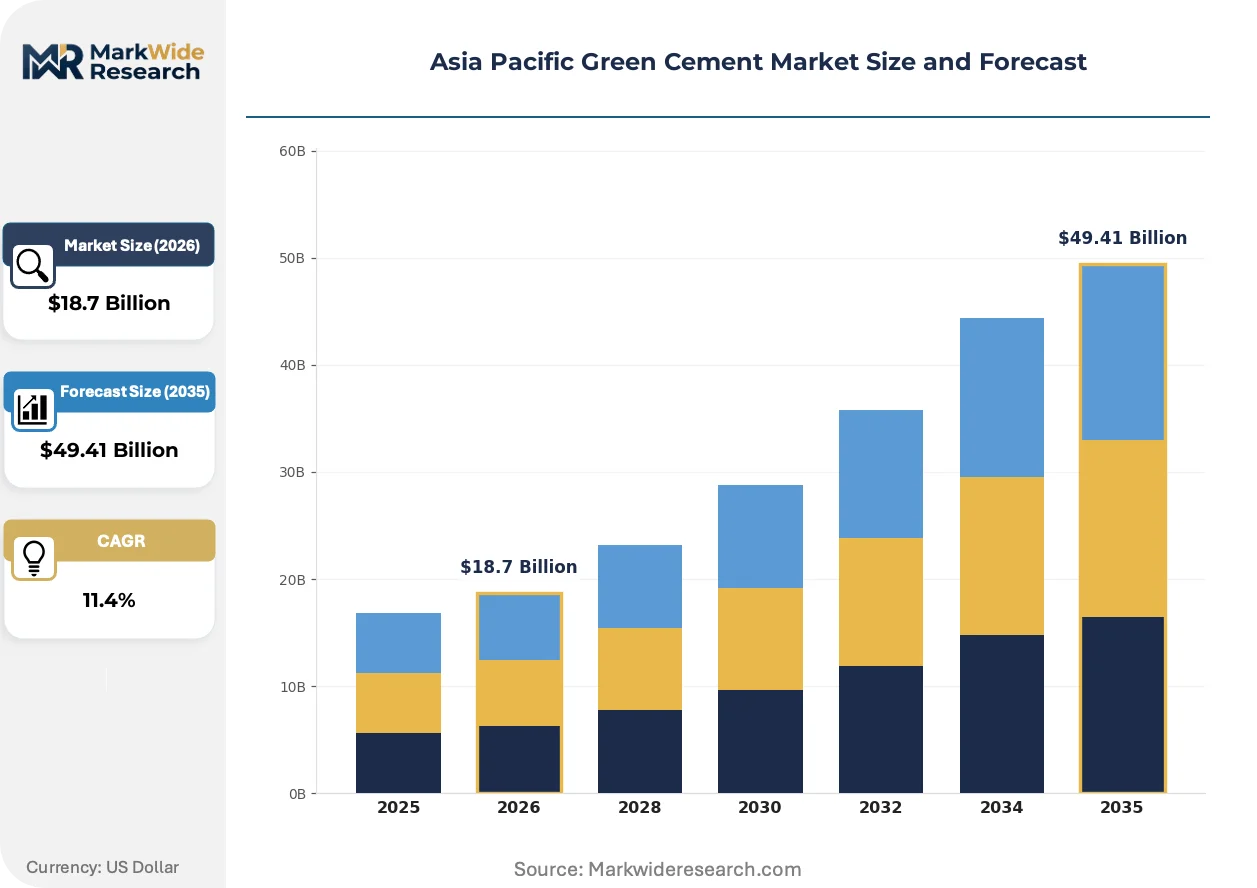
Clinker substitution mandates from China's MEE and India's BIS are compressing traditional Portland cement volumes while rewiring procurement specifications across Southeast Asian infrastructure tenders. These regulatory floors are forcing capital reallocation toward supplementary cementitious material processing capacity.
Growth Catalysts
- India's BIS Green Building Codes:Tightened clinker-to-cement ratios in commercial construction specifications are pulling blended cement volumes into government highway contracts across Maharashtra and Gujarat.
- Mass Transit Infrastructure:Southeast Asian rail and metro expansions in Vietnam, Indonesia, and Thailand are mandating low-carbon binder specifications for tunnel lining and station foundations.
- Fly Ash Proximity Advantage:Coal-fired power generation clusters in China's Shanxi and India's Uttar Pradesh provide captive supplementary cementitious material feedstock for adjacent grinding units.
Market Restraints
- Clinker Capacity Caps:China's dual carbon goals freeze new kiln permits, constraining domestic supply elasticity when regional demand spikes.
- Slag Supply Concentration:Blast furnace slag availability concentrates near integrated steel mills in Japan and South Korea, creating logistics cost penalties for Southeast Asian blenders.
- Geopolymer Performance Uncertainty:India's BIS has not finalized strength equivalency standards for alkali-activated binders, limiting specification in load-bearing structural applications.
Strategic Opportunities
- Vietnam's Port Modernization:Marine exposure specifications for Da Nang and Hai Phong container terminals create pull for sulfate-resistant slag blends and specialized geopolymer formulations.
- Alternative Fuel Co-processing:China's MEE mandates for waste-derived fuels in cement kilns open feedstock arbitrage for municipal solid waste and biomass processors.
- Ready-Mix Channel Integration:Quality-controlled blending at batch plants rather than bagged cement distribution is capturing specification authority from traditional trade channels in Australian commercial construction.
Industry Challenges
- SCM Quality Variability:Fly ash chemistry fluctuates with coal source and combustion conditions, requiring real-time quality control systems at grinding stations.
- Carbon Accounting Verification:Third-party embodied carbon certification for blended cement products lacks harmonized protocols across China's GB standards, India's BIS, and Australia's infrastructure procurement frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Green Cement Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fly Ash-Based, Slag-Based, Geopolymer, Other Blends Application: Residential Construction, Commercial Infrastructure, Road Construction, Industrial Applications End User: Builders, Contractors, Government Bodies, Environmental Agencies Distribution Channel: Direct Sales, Retail, E-Commerce, Wholesalers |
| Companies Covered | Anhui Conch Cement Company, China National Building Material Company, UltraTech Cement Ltd, JSW Cement, TAIHEIYO CEMENT CORPORATION, ACC Limited, Siam Cement Group, Taiwan Cement Corporation, Heidelberg Materials, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Green Cement Market Trends and Innovations
Carbon accounting transparency is becoming a competitive differentiator in infrastructure tenders, with procurement officers demanding disclosed supply chain emissions data alongside traditional performance metrics. This shift is compressing opacity premiums and rewarding early movers in clinker substitution.
Calcined clay activation is overtaking conventional pozzolanic processing as the preferred decarbonization pathway for limestone-rich geographies lacking proximate fly ash or slag sources. Vietnamese and Indonesian producers with access to high-kaolin clays are deploying flash calcination systems to produce metakaolin at industrial scale. This technology is overtaking slag-based blends in markets where steel production is declining or import-dependent, compressing the addressable market for traditional supplementary cementitious materials.
China's MEE enforcement of dual carbon goals is tightening clinker capacity licensing and accelerating alternative fuel substitution mandates in kiln operations. Industrial consequence includes forced consolidation among independent grinding stations unable to secure consistent supplementary cementitious material supply. Coastal provinces facing EU carbon border adjustment mechanism exposure are most affected, with export-oriented plants investing in biomass co-processing and waste heat recovery to document emissions reductions.
Specification packages are consolidating around performance-based blended cement categories rather than prescriptive composition limits, compressing brand loyalty and elevating third-party certification authority. Australian and Singaporean infrastructure authorities now mandate independently verified embodied carbon thresholds for concrete supply contracts. This pattern is most visible in commercial high-rise construction across Melbourne, Sydney, and Singapore, where green building rating systems have hardened from voluntary aspiration to tender disqualification threshold.
Asia Pacific Green Cement Market Segmentation
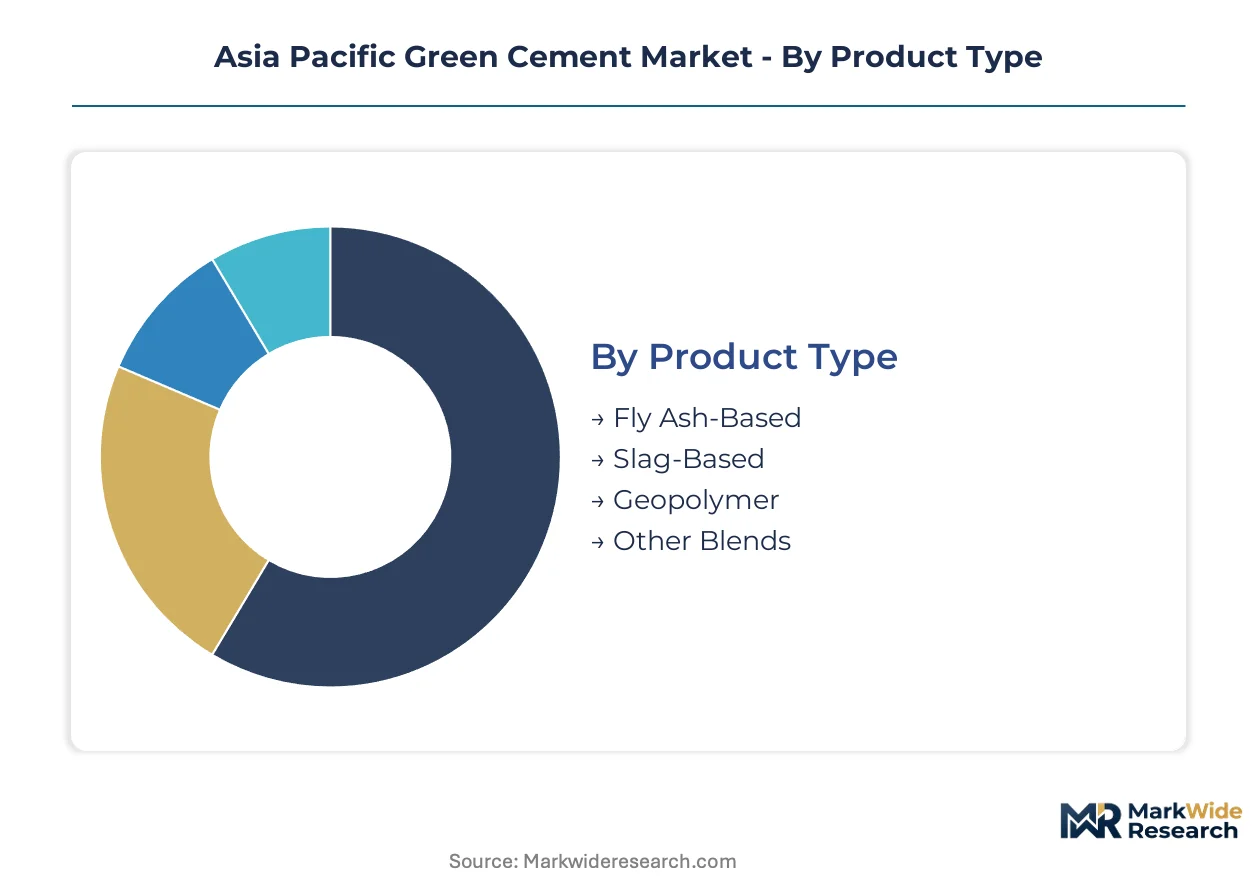
Segmentation in the Asia Pacific green cement market reveals how clinker substitution technologies align with distinct procurement authority patterns across infrastructure value chains. Each dimension exposes different specification pressures, from government tender mandates to contractor blending preferences.
Product Type:
Upgrade cycles in product formulation are compressing as regulatory clinker caps force rapid adoption of supplementary cementitious material blends across regional manufacturing bases.
- Fly Ash-Based:Hydraulic binders incorporating coal combustion byproducts at substitution rates typically exceeding 35 percent, leveraging proximate feedstock from thermal power clusters. Demand concentrates in China's Shanxi province and India's Uttar Pradesh, where captive fly ash supply chains from coal-fired generation anchor grinding unit economics.
- Slag-Based:Ground granulated blast-furnace slag blends offering superior chloride ingress resistance for marine exposure specifications. Procurement pulls strongest from Vietnam's Da Nang port modernization and Thai coastal road tenders, where sulfate resistance commands premium positioning.
- Geopolymer:Alkali-activated binders utilizing metakaolin or fly ash with alkaline activators, positioned for aggressive carbon reduction targets.
- Other Blends:Calcined clay-limestone combinations and hybrid pozzolanic formulations addressing SCM scarcity in import-dependent markets.
Volume placements concentrate in fly ash-based products; the faster expansion belongs to geopolymer formulations as equivalency standards mature.
Application:
Cost tier stratification across application segments separates commodity-grade residential supply from performance-specified infrastructure concrete.
- Residential Construction:Standard-grade blended cements for low-rise housing foundations and masonry mortar, governed by national building code minimums. Demand clusters in India's western states, where Maharashtra's Mumbai-Pune corridor developers mandate BIS-compliant blended specifications for affordable housing schemes.
- Commercial Infrastructure:High-strength green concrete for high-rise structural frames and commercial building envelopes. Australia's Melbourne and Sydney commercial towers drive embodied carbon verification requirements, with procurement officers demanding disclosed supply chain emissions data alongside compressive strength metrics.
- Road Construction:Pavement-grade binders for highway and expressway concrete, subject to government contract specifications.
- Industrial Applications:Specialized formulations for factory floors, containment structures, and process equipment foundations.
Commercial infrastructure commands the steepest price premiums; road construction absorbs the largest absolute tonnage through government highway programs.
End User:
Customer type determines specification authority, with government bodies wielding mandatory blended cement ratios while contractors optimize for logistics cost.
- Government Bodies:Central and state agencies mandating clinker-to-cement ratios in public works tenders. India's NHAI and state PWDs enforce BIS green building codes across Maharashtra and Gujarat highway contracts, pulling blended volumes through procurement floors.
- Contractors:Private construction firms balancing specification compliance with batch plant logistics and working capital constraints. Large contractors in Vietnam's mass transit sector are consolidating ready-mix channel integration to capture quality control authority from bagged cement distributors.
- Builders:Developer-led residential and commercial project owners specifying green cement for building certification compliance.
- Environmental Agencies:Regulatory bodies influencing procurement through embodied carbon thresholds and coastal protection standards.
Government bodies anchor volume commitments through tender mandates; builders are gaining specification influence fastest as green building ratings harden from voluntary to disqualification threshold.
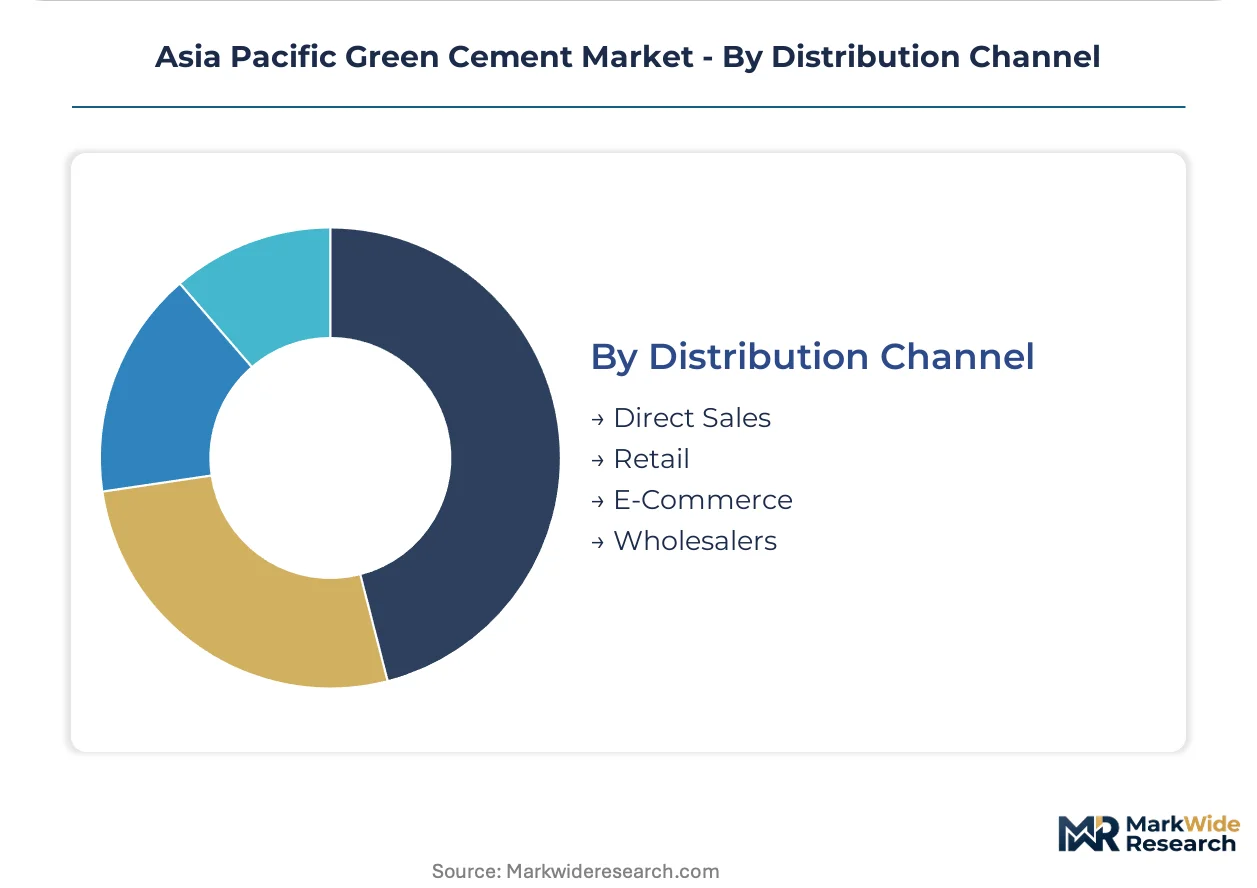
Distribution Channel:
Supply concentration in coastal manufacturing clusters shapes channel economics, with direct sales capturing bulk infrastructure contracts while retail serves fragmented residential demand.
- Direct Sales:Bulk supply contracts from grinding stations to ready-mix batch plants and large project sites. China's coastal provinces facing EU carbon border adjustment mechanism exposure are prioritizing direct sales relationships to document emissions reductions for export-oriented concrete supply.
- Wholesalers:Regional distributors aggregating bagged cement for contractor and retail resale, dominant in secondary city markets.
- Retail:Hardware store and construction material yard sales to small contractors and individual builders.
- E-Commerce:Digital procurement platforms emerging for standardized grade bagged cement in urban markets.
Direct sales capture the largest project-scale volumes; e-commerce channels are climbing the fastest as procurement digitization penetrates tier-one city construction markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal special economic zones and India's dedicated freight corridors are concentrating green cement procurement around export-oriented manufacturing clusters and mass transit construction nodes.
China
Shanxi province's coal-fired power clusters feed captive fly ash supply chains to adjacent grinding units. MEE dual carbon goals freeze new kiln permits while mandating alternative fuel co-processing. Yangtze River Delta manufacturers face EU carbon border adjustment mechanism exposure, forcing biomass co-processing investments.
India
Maharashtra and Gujarat anchor demand through Mumbai-Pune industrial corridor mandates for BIS-compliant blended cement. NHAI and state PWDs enforce green building codes across highway contracts. Western states concentrate grinding capacity near Uttar Pradesh fly ash sources and coastal slag import terminals.
Vietnam
Da Nang and Hai Phong port modernizations specify sulfate-resistant slag blends for marine exposure zones. Mass transit rail expansions in Hanoi and Ho Chi Minh City mandate low-carbon binders for tunnel lining. Northern provinces exploit proximity to Chinese metakaolin feedstock for calcined clay activation.
Thailand
Bangkok metro extensions and Eastern Economic Corridor infrastructure pull specialized geopolymer formulations for coastal road construction. Siam Cement Group anchors domestic supply for marine exposure specifications. Central plains grinding stations blend fly ash from Mae Moh lignite power complex.
Australia
Melbourne and Sydney commercial towers drive embodied carbon verification requirements through independently certified concrete supply. Ready-mix channel integration captures specification authority from bagged distributors. New South Wales and Victoria infrastructure authorities mandate disclosed supply chain emissions data.
Asia Pacific Green Cement Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers defined by scale, vertical integration depth, and formulation specialization. Market structure tilts toward consolidation among integrated building materials groups controlling mineral processing through ready-mix distribution. Three archetypes dominate: pan-regional integrated giants with captive SCM supply, national champions anchored to government contract flows, and technology specialists commanding premium positioning for geopolymer and calcined clay formulations. Competitive moves concentrate on backward integration into supplementary cementitious material processing and strategic partnerships with waste-to-energy operators securing alternative fuel feedstock.
Within the integrated conglomerate tier, China National Building Material Company and Anhui Conch Cement Company represent scale-driven archetypes with multi-province manufacturing footprints. UltraTech Cement Ltd occupies a position exemplifying national-champion dynamics tied to Indian government infrastructure procurement. Siam Cement Group and TAIHEIYO CEMENT CORPORATION sit within the technology-specialist vector, with geographic naming conventions suggesting Thai and Japanese origins respectively. JSW Cement, ACC Limited, and Taiwan Cement Corporation anchor mid-scale competitive positions, their limited-liability structures indicating formalized corporate governance suited to tender participation. Heidelberg Materials represents the multinational integrated archetype, its German-derived name signaling cross-regional technology transfer capabilities.
| Leading Market Players |
|---|
| Anhui Conch Cement Company |
| China National Building Material Company |
| UltraTech Cement Ltd |
| JSW Cement |
| TAIHEIYO CEMENT CORPORATION |
| ACC Limited |
| Siam Cement Group |
| Taiwan Cement Corporation |
| Heidelberg Materials |
| Others |
Pricing and Supply Chain Analysis
Clinker substitution rates feed directly through to grinding unit economics, with supplementary cementitious material proximity separating premium-mid-economy pricing tiers across China's Shanxi province and India's Uttar Pradesh coal clusters. Procurement officers in Vietnam's port authorities and Australia's commercial construction sector now demand embodied carbon disclosure alongside compressive strength metrics, compressing opacity premiums and rewarding documented supply chain transparency.
Pricing Analysis
Margin tightening in standard-grade blended cement reflects regulatory clinker caps forcing rapid formulation shifts across regional manufacturing bases. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with BIS-compliant highway contracts in Maharashtra commanding premiums over residential trade channels. Cost-down pressure on commodity grades accelerates because fly ash chemistry variability requires real-time quality control investments. Government tender participants show least price sensitivity; small contractors in secondary Indian cities demonstrate highest elasticity.
Supply Chain Analysis
Skilled kiln operators and grinding station technicians concentrate in China's coastal special economic zones and India's western industrial corridors, constraining capacity expansion in Vietnam and Indonesia. Manufacturing gravity centers on China, India, and Thailand, with raw material dependencies on coal fly ash, blast furnace slag, and calcined clay feedstock. Single-source vulnerability concentrates in metakaolin supply chains tethered to Chinese clay processing clusters. Distribution runs through direct bulk contracts to ready-mix batch plants for infrastructure scale, with bagged cement wholesalers serving fragmented residential demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcined clay activation is displacing conventional pozzolanic processing as the dominant decarbonization pathway, with flash calcination systems overtaking slag-based blends in limestone-rich geographies lacking proximate fly ash sources.
For Market Incumbents: Anticipate forced consolidation among independent grinding stations unable to secure consistent supplementary cementitious material supply, particularly in China's coastal provinces facing EU carbon border adjustment mechanism exposure. Defensive moves center on backward integration into fly ash processing capacity near Shanxi and Uttar Pradesh power clusters, plus biomass co-processing investments to document emissions reductions for export-oriented concrete supply. For New Entrants and Emerging Players: Capture specification authority in Vietnam's Da Nang and Hai Phong port modernizations where marine exposure standards for sulfate-resistant slag blends remain underserved by incumbent coastal producers. White-space concentrates in specialized geopolymer formulations for Thai coastal road construction and calcined clay activation systems for Indonesian import-dependent markets. Go-to-market leverage rests on third-party embodied carbon certification partnerships with Australian and Singaporean infrastructure authorities. For Investors and Strategic Acquirers: BIS finalization of geopolymer strength equivalency standards is the leading indicator that alkali-activated binder segments will unlock load-bearing structural applications and expand addressable market scope. Long-term viability favors acquisition targets with captive supplementary cementitious material supply chains and ready-mix channel integration controlling quality authority from bagged distributors. Watch for MEE enforcement actions accelerating alternative fuel co-processing mandates as the signal for distressed asset opportunities among clinker-dependent independents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SCM Processing | Captive fly ash supply from Shanxi power clusters secures grinding unit feedstock cost advantage. |
| Alternative Fuel Co-processing Investment | Biomass and municipal waste feedstock arbitrage satisfies China's MEE dual carbon enforcement. |
| Third-party Carbon Certification Partnership | Independent embodied carbon verification unlocks Australian and Singaporean infrastructure tender eligibility. |
| Ready-mix Channel Integration | Quality-controlled blending at batch plants captures specification authority from bagged distributors. |
| Calcined Clay Activation Scale-up | Flash calcination systems in Vietnam and Indonesia address SCM scarcity in import-dependent markets. |
Research Methodology
Document review covered trade flow databases, national building code revisions, and cement industry association filings, complemented by interviews with plant operations directors, government procurement officers at India's NHAI, ready-mix batch plant managers, and technical R&D leads at integrated building materials groups. Secondary validation drew from China's GB standards documentation, India's BIS grading circulars, Australian infrastructure procurement frameworks, and EU carbon border adjustment mechanism guidance. Bottom-up volume modeling triangulated against top-down regulatory impact assessments.
Segment-level projections across product type, application, end user, and distribution channel dimensions were generated through the analysis window, with CAGRs derived from regression against clinker substitution mandate trajectories and infrastructure tender award patterns. Forecast inputs incorporated MEE enforcement intensity indices, BIS equivalency standard development timelines, and mass transit project pipeline visibility across Southeast Asian markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolymer performance standardization, alternative fuel feedstock cost volatility, and EU carbon border adjustment mechanism expansion scope. Material deviation in BIS equivalency finalization or MEE permit enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Outdoor Flooring Market
Green Building Materials
Solar Glass Market
Green Building Materials
Green Roof Market
Green Building Materials
Sustainable Construction Market
Green Building Materials
Artificial Green Wall Market
Green Building Materials
Green Cement Market
Green Building Materials
Global Green Walls Market
Green Building Materials
North America Green Buildings Market
Green Building Materials
APAC Green Buildings Market
Green Building Materials
Green Concrete Market
Green Building Materials
Green Building Market
Green Building Materials
Green Coatings Market
Green Building Materials
Sustainable and Green Building Materials Market
Green Building Materials
Eco-Friendly Tiles Market
Green Building Materials
North America Green Cement Market
Green Building Materials
Energy Efficient Window and Door Market