
 Solar Frames Market | 2026-2036
Solar Frames Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Frames Market Analysis
Direct procurement channels between module manufacturers and extrusion specialists is narrowing as tier-one solar developers seek captive supply security. Alom Group leverages backward integration into billet casting to lock in alloy consistency across high-wind zones. Sunframe Aluminium sustains dominant channel positions across Southeast Asian distribution networks through dedicated logistics infrastructure. Accelor Precision Corporation differentiates via automated anodizing lines that cut lead times for utility-scale racking contractors.
Solar frames are structural perimeter members, typically extruded from 6063-T6 aluminum alloy or hot-dip galvanized steel, that clamp photovoltaic modules and transfer mechanical loads to mounting systems. Wall thicknesses range from 1.2 mm to 2.5 mm depending on wind and snow load ratings, with anodized surfaces providing corrosion resistance in coastal or desert environments. Aluminum segments lead value capture due to extrusion scalability and recycling infrastructure, while steel frames occupy cost-sensitive utility installations where weight penalties matter less. Dual-axis tracking frames represent the fastest-growing design category as concentrated solar power hybrids gain traction in high-direct-normal-irradiance regions.
FERC interconnection standards in the United States, EU Green Deal embodied-carbon thresholds, and China's GB/T 5237 extrusion quality standards collectively reshape material certification requirements and cross-border market access. India's BIS aluminum grade mandates and Saudi SFDA structural safety protocols add further compliance layers for exporters. Stakeholders must monitor evolving alloy traceability rules and regional content requirements that threaten to fragment procurement strategies across major solar installation corridors.
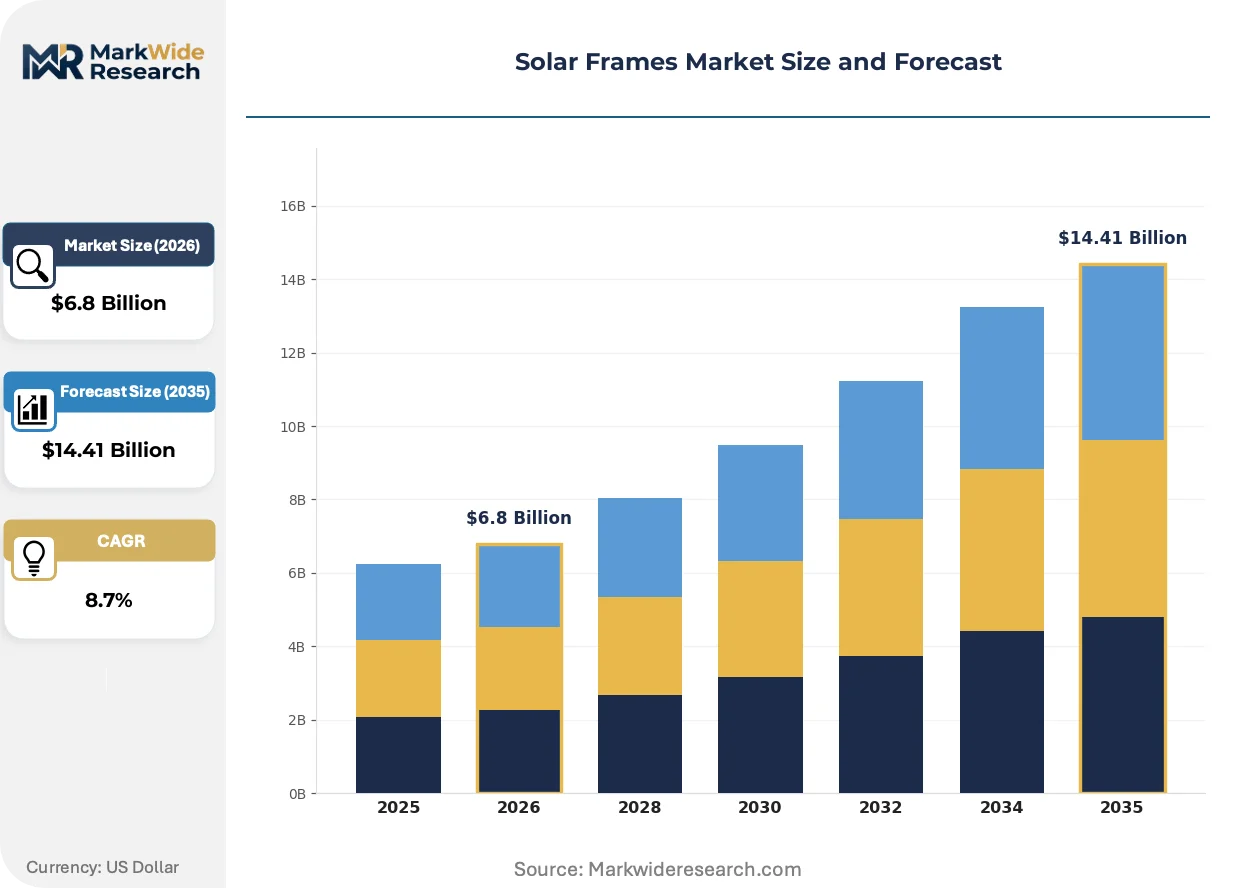
Market Dynamics
Utility-scale solar procurement is consolidating around captive aluminum extrusion supply as developers in India and Saudi Arabia confront alloy traceability mandates and high-wind load engineering requirements.
Growth Catalysts
- EU Green Deal embodied-carbon thresholds:Aluminum frame suppliers are retrofitting smelter power sources and certifying recycled content ratios to maintain access to European utility tenders.
- Dual-axis tracking system proliferation:Concentrated solar power hybrids in high-direct-normal-irradiance zones are driving demand for reinforced perimeter framing with integrated torque tube interfaces.
- Gujarat solar park clustering:India's largest renewable energy zone is concentrating module assembly and frame procurement within a 200-kilometer radius, compressing logistics costs for domestic extruders.
Market Restraints
- Primary aluminum price volatility:LME aluminum fluctuations and Chinese smelter curtailment policies are squeezing margin predictability for frame fabricators locked into fixed-price EPC contracts.
- 6063-T6 alloy supply concentration:Billet casting capacity clusters in Shandong and Henan provinces, creating single-source vulnerability for non-integrated frame manufacturers.
- Steel frame weight penalties:Hot-dip galvanized perimeter members disqualify projects from rooftop distributed solar incentives in Japan and South Korea where structural load limits are binding.
Strategic Opportunities
- Saudi Arabia renewable clusters:NEOM and Red Sea Project gigawatt-scale developments are mandating local content ratios that favor greenfield extrusion joint ventures with European technology partners.
- Anodizing automation convergence:Automated surface treatment lines combined with machine vision inspection are compressing lead times from six weeks to ten days for utility-scale racking contractors.
- India BIS aluminum grade enforcement:Mandatory Bureau of Indian Standards certification for structural aluminum is disqualifying informal recyclers and opening share for organized secondary smelters.
Industry Challenges
- Extrusion die engineering talent scarcity:Complex hollow profile design for dual-axis torque transmission requires specialized tooling expertise concentrated in aging European and Japanese technical institutes.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of FERC interconnection compliance, EU CE marking, and Saudi SFDA structural protocols extends product qualification cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Frames Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Aluminum, Steel, Composite, Plastic Design Type: Fixed, Adjustable, Dual-Axis, Single-Axis End User: Residential, Commercial, Industrial, Utilities Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | Alom Group, Aluminum Shapes LLC, 7 Star Aluminium, Helios Group, American Industrial, Accelor Precision Corporation, Alumec S.r.l., Sunframe Aluminium, Akcome, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Frames Market Emerging Trajectories
Frame manufacturing is digitizing quality assurance and supply chain traceability while regulatory pressure on embodied carbon forces material requalification across major solar corridors.
Machine vision inspection integrated with laser profile measurement is digitizing dimensional tolerance verification in real-time during extrusion line operation. Tier-one module manufacturers in Texas and Gujarat are mandating this capability for frame suppliers to eliminate manual sampling delays. The technology is compressing rejection rates and enabling just-in-time delivery contracts that were previously unfeasible for aluminum perimeter members.
China's GB/T 5237 extrusion quality standards are tightening alloy composition tolerances and mandating batch-level chemical certification for structural solar applications. Domestic frame exporters must now maintain in-house spectroscopy laboratories or third-party testing partnerships to access utility-scale procurement channels. The regulation is displacing informal extruders from state-backed solar farm tenders in Xinjiang and Inner Mongolia.
Direct mill-to-EPC contracting is consolidating procurement channels as developers in Saudi Arabia and the UAE bypass distributors to lock in five-year alloy supply agreements. This behavior is fragmenting the traditional Southeast Asian trading house network that previously intermediated frame logistics. The shift is most visible in Red Sea Project phases where European EPCs are sourcing billet, extrusion, and anodizing as a bundled service from integrated suppliers.
Solar Frames Market Segmentation
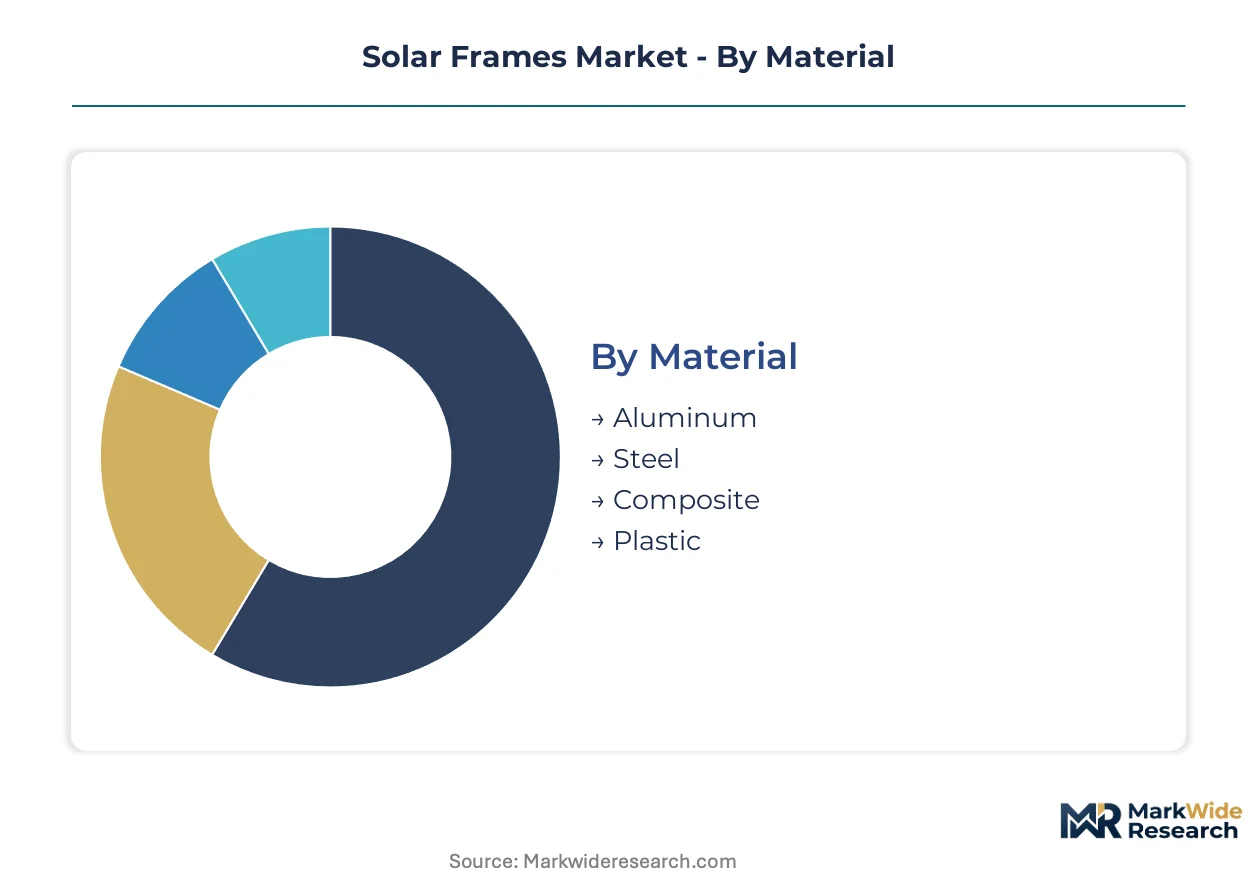
Material composition and design architecture determine procurement cycles for solar framing systems. Aluminum extrusions turn inventory fastest in utility corridors, while composite prototypes linger in certification queues.
Material:
Aluminum billets rotate through smelter-to-extruder channels within days, whereas composite resin batches cure for weeks before structural testing.
- Aluminum:6063-T6 alloy extrusions dominate utility-scale procurement through anodized corrosion resistance and established recycling infrastructure. Demand concentrates in Gujarat solar parks and Texas utility corridors where high-wind load engineering favors wall thicknesses above 1.8 mm.
- Steel:Hot-dip galvanized perimeter members serve cost-sensitive ground-mount installations where weight penalties are acceptable. Procurement cycles stretch longer due to surface treatment batch processing and transportation logistics for heavy coil stock.
- Composite:Fiber-reinforced polymer prototypes face extended qualification timelines for UV degradation and thermal expansion certification.
- Plastic:Injection-molded perimeter options occupy niche distributed solar applications with minimal structural load requirements.
Aluminum anchors the volume base while composite formulations gain share at the steepest rate.
Design Type:
Fixed tilt arrays ship from extrusion lines to installation sites within standard construction windows, but dual-axis tracking frames require integrated torque tube engineering that extends fabrication schedules.
- Fixed:Stationary tilt-angle perimeter members constitute the baseline procurement category with standardized clamp interfaces and minimal mechanical complexity. Deployment concentrates in Saudi Arabia renewable clusters where labor costs favor simple installation protocols over tracking sophistication.
- Dual-Axis:Concentrated solar power hybrids in high-direct-normal-irradiance zones demand reinforced framing with precision-machined torque transmission interfaces. Lead times extend due to hollow profile die engineering and dynamic load testing requirements.
- Adjustable:Seasonal tilt mechanisms add mechanical articulation without full tracking infrastructure.
- Single-Axis:Horizontal tracking systems balance energy yield improvement against structural simplicity in utility corridors.
Fixed configurations retain the largest installed base while dual-axis designs expand most quickly in CSP hybrid installations.
End User:
Residential contractors place fragmented small-batch orders through distribution networks, whereas utilities negotiate multi-year alloy supply agreements with direct mill contracting.
- Utilities:Gigawatt-scale developers in India and the Middle East procure aluminum framing through captive extrusion partnerships with five-year volume commitments. Procurement cycles compress through just-in-tim delivery mandates and machine vision quality verification.
- Residential:Rooftop installers in Japan and South Korea face structural load limits that disqualify steel frames from incentive programs. Order patterns fragment across seasonal construction cycles and regional distributor inventories.
- Commercial:Corporate offtake agreements drive mid-scale ground-mount and rooftop installations.
- Industrial:Manufacturing facility self-consumption projects favor standardized framing for rapid deployment.
Utilities command the procurement volume while residential channels diversify most rapidly across distributed solar incentives.
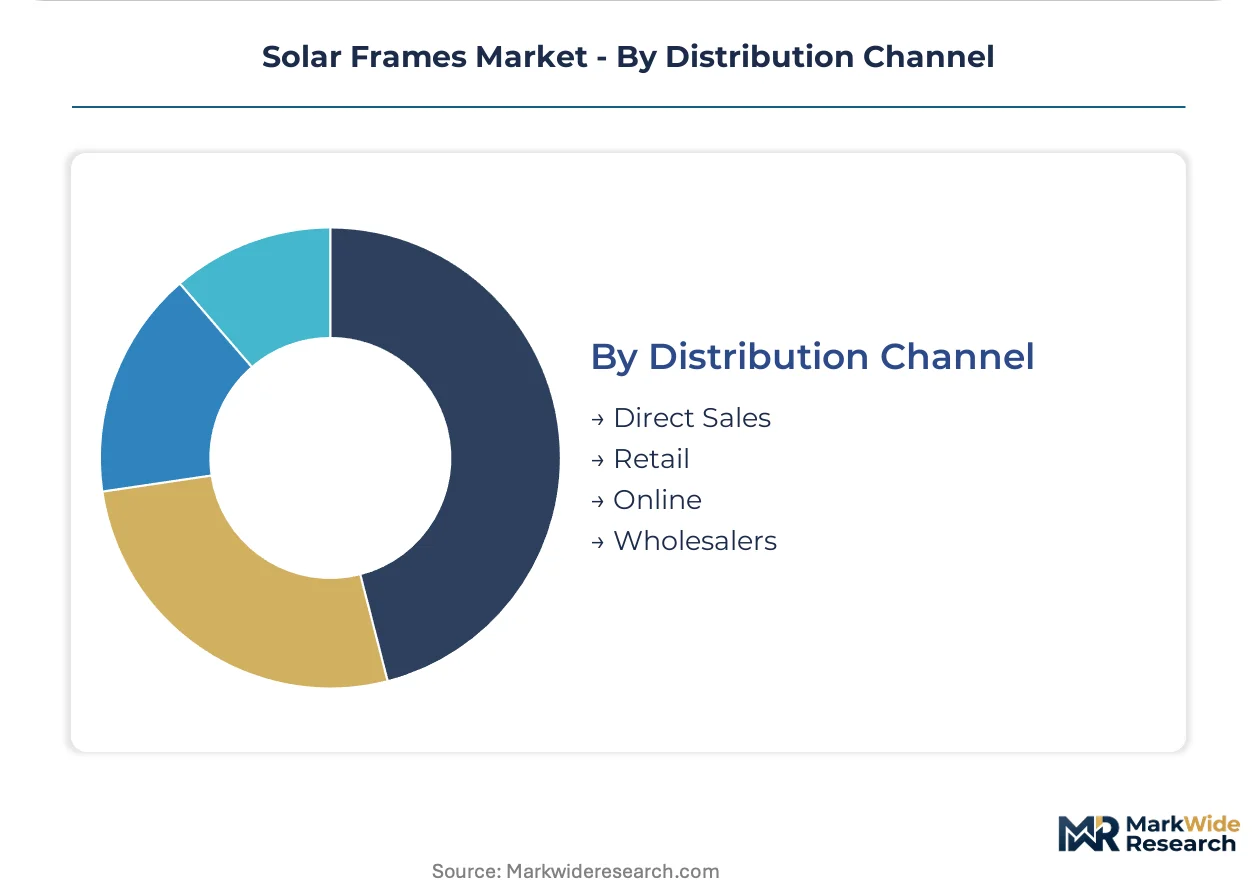
Distribution Channel:
Direct mill-to-EPC contracting accelerates alloy traceability compliance, but wholesale networks retain relevance for smaller developers lacking procurement scale.
- Direct Sales:Tier-one solar developers in Saudi Arabia and the UAE bypass distributors to lock in billet-to-anodizing bundled services. This channel delivers fastest cycle times through eliminated intermediary logistics.
- Wholesalers:Southeast Asian trading houses maintain frame inventories for mid-scale contractors, though their network is fragmenting under direct procurement pressure.
- Retail:Hardware and electrical supply stores serve residential and small commercial installers.
- Online:Digital procurement platforms emerge for standardized aluminum profile specification and price transparency.
Direct sales capture the largest contract value while online channels penetrate fastest among smaller installers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's embodied-carbon thresholds and India's BIS aluminum grade mandates are redirecting procurement flows across major solar installation corridors. Developers in high-direct-normal-irradiance zones are consolidating frame sourcing within tight geographic radii to compress logistics costs and satisfy local content requirements.
India
Gujarat's solar parks concentrate module assembly and frame procurement within a 200-kilometer radius, compressing logistics costs for domestic extruders. The Bureau of Indian Standards enforces mandatory certification for structural aluminum grades, disqualifying informal recyclers and opening share for organized secondary smelters. Domestic frame manufacturers in Mundra and Vadodara industrial zones are retrofitting spectroscopy laboratories to access state-backed solar farm tenders.
China
Dual carbon goals and GB/T 5237 extrusion quality standards are tightening alloy composition tolerances and mandating batch-level chemical certification. Billet casting capacity clusters in Shandong and Henan provinces, creating single-source vulnerability for non-integrated frame manufacturers. Xinjiang and Inner Mongolia solar farm tenders now exclude informal extruders lacking in-house testing capabilities.
Saudi Arabia
NEOM and Red Sea Project gigawatt-scale developments mandate local content ratios that favor greenfield extrusion joint ventures with European technology partners. The Saudi Food and Drug Authority's structural safety protocols add compliance layers for frame exporters seeking access to renewable clusters. Red Sea Project phases show European EPCs sourcing billet, extrusion, and anodizing as bundled services from integrated suppliers.
United States
FERC interconnection standards reshape material certification requirements for utility-scale deployments in Texas corridors. Machine vision inspection mandates from tier-one module manufacturers are digitizing dimensional tolerance verification in real-time. Texas-based developers are locking in five-year alloy supply agreements through direct mill-to-EPC contracting to eliminate intermediary logistics.
Japan
Structural load limits in rooftop distributed solar incentive programs disqualify steel frames, favoring aluminum perimeter members in residential channels. The Ministry of Economy, Trade and Industry oversees compliance frameworks that fragment order patterns across seasonal construction cycles. Osaka and Nagoya industrial zones maintain specialized logistics infrastructure for Southeast Asian frame distribution networks.
Solar Frames Market Vendor Landscape
On the supply side, the industry is consolidating around captive aluminum extrusion supply as developers confront alloy traceability mandates and high-wind load engineering requirements. The vendor base stratifies between integrated billet-to-anodizing suppliers, specialized extrusion houses, and regional trading intermediaries. Three archetypes dominate: backward-integrated conglomerates with smelter assets, automation-focused precision fabricators, and logistics-anchored distribution specialists. Competitive intensity centers on multi-jurisdiction certification timelines and anodizing automation investments that compress lead times.
Among Asia-Pacific fabricators, Alom Group and Sunframe Aluminium exemplify divergent strategic positions. Alom Group represents the backward-integrated archetype through captive billet casting operations that lock in alloy consistency. Sunframe Aluminium occupies a distribution-focused position sustained through dedicated logistics infrastructure across Southeast Asian networks. Accelor Precision Corporation anchors the automation-specialist tier, with its corporate structure suggesting precision manufacturing capabilities. These three entities illustrate how geographic origin and organizational form map onto distinct competitive vectors in a market where certification breadth and lead-time compression determine contract access.
| Leading Market Players |
|---|
| Alom Group |
| Aluminum Shapes LLC |
| 7 Star Aluminium |
| Helios Group |
| American Industrial |
| Accelor Precision Corporation |
| Alumec S.r.l. |
| Sunframe Aluminium |
| Akcome |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Shandong and Henan billet casting zones compresses margins for non-integrated frame fabricators while simultaneously granting pricing leverage to backward-integrated suppliers. This utilization asymmetry shapes procurement negotiations across utility-scale solar corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs aluminum frame procurement. Premium tiers command alloy traceability certification and machine vision quality verification from tier-one module manufacturers. Price differentiation hinges on anodizing automation investment and volume commitment scale. Cost compression in standard tiers intensifies as fixed-price EPC contracts collide with LME aluminum volatility. Residential contractors in Japan and South Korea exhibit highest price sensitivity due to structural load constraints eliminating steel alternatives.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for frame exporters. Primary aluminum production concentrates in China, Saudi Arabia, and the UAE, with billet casting anchored in Shandong and Henan provinces. Raw material flows draw from alumina refineries, anodizing chemical suppliers, and die tooling specialists. Single-source vulnerability in 6063-T6 alloy supply threatens procurement continuity. Distribution runs through direct mill-to-EPC contracting channels that displace traditional Southeast Asian trading house networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar frame manufacturing is accelerating toward a high-growth disruption as dual-axis tracking systems and embodied-carbon mandates reconstitute procurement specifications across major installation corridors.
For Market Incumbents: Build captive billet casting moats through backward integration into alloy production. Secure spectroscopy laboratory accreditation to satisfy India's BIS enforcement and China's GB/T 5237 batch certification. Add extrusion capacity in Gujarat and Saudi Arabia renewable clusters to compress logistics costs and satisfy local content ratios. Neutralize margin pressure from LME volatility through long-term offtake agreements with smelter partners.
For New Entrants and Emerging Players: Mid-market commercial ground-mount installations in India's secondary solar parks represent the most penetrable entry point. Automated anodizing lines with machine vision inspection offer differentiation against legacy fabricators burdened by six-week lead times. Target EPC contractors in Texas utility corridors seeking alternatives to concentrated incumbent supply. Pursue joint venture structures with European technology partners to access Saudi Arabia's NEOM and Red Sea Project tenders.
For Investors and Strategic Acquirers: Capital is best deployed toward automation-specialist fabricators with multi-jurisdiction certification breadth and anodizing line investments. Long-term viability favors suppliers positioned at the intersection of EU Green Deal embodied-carbon compliance and high-wind load engineering capability. Watch for inflection signals in dual-axis tracking frame procurement volumes from concentrated solar power hybrid developers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Billet Casting | Captive alloy supply locks in consistency margins across high-wind zones in Gujarat and Texas. |
| Anodizing Automation Investment | Machine vision lines compress lead times from six weeks to ten days for utility racking contractors. |
| Multi-Jurisdiction Certification Pursuit | Simultaneous FERC, CE marking, and SFDA compliance opens access to gigawatt-scale tender pipelines. |
| Greenfield Extrusion Joint Ventures | European technology partnerships satisfy Saudi local content mandates in NEOM renewable clusters. |
| Spectroscopy Laboratory Accreditation | In-house testing capabilities displace informal extruders from China's Xinjiang solar farm tenders. |
Methodological Framework
A spread of perspectives from extrusion plant managers, EPC procurement leads, module manufacturer supply chain directors, and anodizing line engineers converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC filings, customs trade data, FERC interconnection databases, and Bureau of Indian Standards certification records. Bottom-up project pipeline analysis and top-down smelter capacity assessments were triangulated to anchor volume estimates.
Demand-supply-balance dynamics across material grade, design architecture, end-user scale, and distribution channel shaped the analytical framework. Segmentation modeling incorporated aluminum alloy specification, tracking system complexity, utility versus residential procurement patterns, and direct versus intermediary sales channels. CAGRs were derived from installation volume trajectories and frame intensity per megawatt assumptions. Forecast inputs included BIS enforcement timelines, EU Green Deal threshold implementation, and dual-axis tracking adoption curves.
Practitioners should monitor LME aluminum volatility, Chinese smelter curtailment policies, and alloy traceability rule evolution for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Green Roof Market
Green Building Materials
Solar Glass Market
Green Building Materials
Green Building Market
Green Building Materials
Solar Windows Market
Green Building Materials
APAC Green Buildings Market
Green Building Materials
North America Green Cement Market
Green Building Materials
Global Green Walls Market
Green Building Materials
China Green Building Materials Market
Green Building Materials
Green Waterproofing Products Market
Green Building Materials
Green Rebar Market
Green Building Materials
Global Eco-Friendly Green Roofs Market
Green Building Materials
Green Building Materials Market
Green Building Materials
Green Silica Market
Green Building Materials
Eco-Friendly Tiles Market
Green Building Materials
Green Cement and Concrete Market
Green Building Materials
Asia Pacific Green Cement Market