
 Solar Energy Market | 2026-2036
Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Energy Market Intelligence
The historic reliance on large-scale, utility-led projects is unwinding as commercial enterprises and residential consumers increasingly pursue distributed generation. First Solar, Inc. leverages its thin-film technology to serve utility-scale demand in North America. JinkoSolar Holding Co., Ltd. dominates global module supply through immense manufacturing scale, while Enphase Energy, Inc. specializes in microinverter technology for the distributed residential segment.
Solar energy involves converting sunlight into electricity, either directly using photovoltaics or indirectly using concentrated solar power. Photovoltaic panels employ semiconductor materials, such as silicon, which exhibit the photovoltaic effect to generate a direct current when exposed to photons. Photovoltaic panels represent the dominant product type due to their modularity and falling costs. Within installation types, ground-mounted systems constitute the largest share for utility-scale power generation, while rooftop installations lead in the residential consumer segment.
Government policies are central to market expansion, with frameworks like the US Inflation Reduction Act and the EU Green Deal providing direct subsidies and tax incentives. In parallel, China's dual carbon goals mandate a rapid transition to renewable sources, securing domestic demand for its vast manufacturing base. Stakeholder success will hinge on navigating divergent regional trade policies and securing access to critical materials like polysilicon.
Market Dynamics
The solar energy market's primary dynamic is the tension between extreme supply chain concentration and a global push for energy independence. While manufacturing of polysilicon and wafers is centered in China, policy incentives in the US and EU aim to onshore production and diversify sourcing.
Growth Catalysts
- Policy Frameworks:The US Inflation Reduction Act provides substantial tax credits for domestic manufacturing and new installations, while the EU Green Deal accelerates renewable energy targets for member states.
- Technology Advancement:Continuous improvements in monocrystalline and n-type cell efficiency, coupled with falling production costs, make solar photovoltaics economically competitive with conventional power sources in more regions.
- Corporate Sustainability Goals:A rising number of corporations are adopting stringent ESG criteria, driving demand for on-site rooftop and ground-mounted solar systems to reduce their carbon footprint and secure stable energy costs.
Market Restraints
- Supply Chain Vulnerability:Heavy reliance on China for polysilicon, wafers, and cells creates significant geopolitical and logistical risks, exposing the global market to potential trade disruptions and price volatility.
- Grid Integration Costs:The intermittent nature of solar power necessitates substantial investment in energy storage systems and grid modernization to ensure network stability and manage fluctuating output.
- Material and Land Constraints:Access to critical raw materials like high-purity silicon and silver, along with competition for land suitable for large-scale utility projects, can hinder development timelines and increase project costs.
Strategic Opportunities
- Emerging Geographic Markets:Nations across Southeast Asia and Africa represent significant growth potential as they seek to expand electricity access and reduce reliance on fossil fuel imports, creating demand for distributed and utility-scale solar.
- Technology Convergence:Integrating solar generation with electric vehicle charging infrastructure and building energy management systems creates new value streams for residential and commercial consumers through optimized energy use.
- Product Innovation:The development of next-generation photovoltaic technologies, including perovskite solar cells and transparent solar films, opens possibilities for applications in building-integrated photovoltaics and consumer electronics.
Industry Challenges
- Workforce Development:A persistent shortage of skilled labor, including certified installers, electrical engineers, and maintenance technicians, poses a significant bottleneck to project execution and long-term operational reliability.
- Recycling and End-of-Life Management:Establishing scalable and cost-effective recycling processes for decommissioned solar panels is a critical challenge to ensure the industry's long-term environmental sustainability and create a circular economy for materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Energy Market |
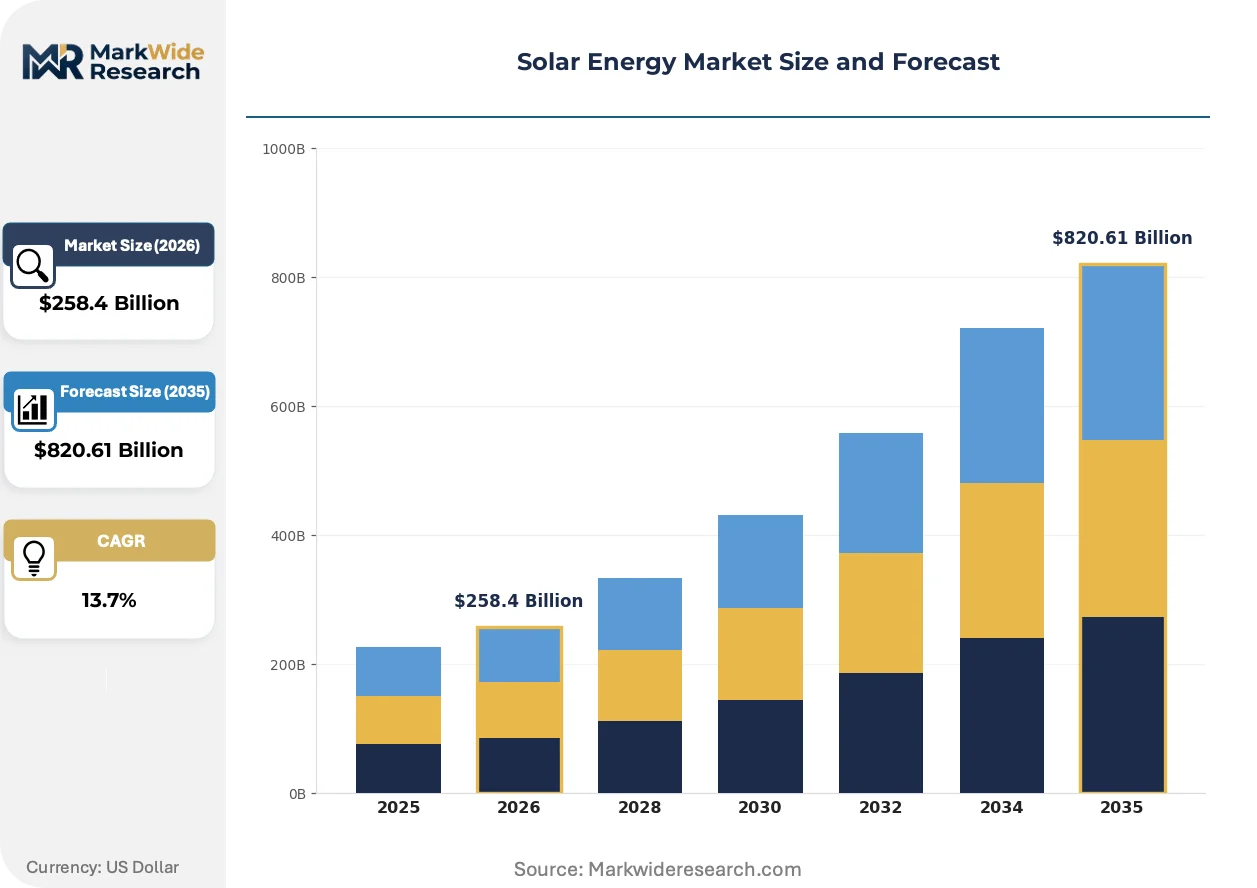
| Market Size in 2026 | $258.4 Billion |
| Market Size in 2035 | $820.61 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Concentrated Solar Power, Solar Water Heaters, Solar Cookers, Solar Lighting Systems Application: Power Generation, Water Pumping, Heating Solutions, Telecommunications, Space Heating Installation Type: Rooftop, Ground-Mounted, Floating, Building-Integrated, Portable Units End User: Residential Consumers, Commercial Enterprises, Agricultural Operations, Government Facilities, Educational Institutions |
| Companies Covered | Enphase Energy, Inc., Canadian Solar Inc., First Solar, Inc., Sungrow Power Supply, SolarEdge Technologies, Inc., Trina Solar Co. Ltd, JinkoSolar Holding Co., Ltd., JA Solar Technology Co., Ltd., Sunrun Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Energy Market Strategic Shifts & Innovations
Technological specialization is reshaping competitive positioning within the solar value chain. As the core photovoltaic module becomes a commodity, differentiation is shifting toward system-level components, software, and manufacturing processes that boost efficiency and reduce lifecycle costs.
Module-level power electronics (MLPE) such as microinverters and power optimizers provide granular control over solar array output. Residential and commercial customers are the primary adopters, seeking to maximize energy harvest from complex or partially shaded rooftops. This technology is fragmenting the traditional dominance of central inverters by enabling panel-level performance monitoring and enhancing system safety.
Regulatory frameworks are increasingly targeting the carbon footprint of the manufacturing supply chain itself. The EU's Carbon Border Adjustment Mechanism (CBAM) will impose levies on imported goods based on their embedded carbon emissions, directly impacting solar components produced using carbon-intensive energy sources. This policy pressures manufacturers, particularly in China, to adopt cleaner production methods and transparently report emissions data.
A notable behavioral shift is the move from standalone component purchases to procurement of integrated energy ecosystems. End-users are increasingly demanding bundled solutions that combine solar panels with battery storage, energy management software, and even electric vehicle chargers. This trend is most pronounced in mature residential markets like Germany and Australia, where grid-feed-in tariffs have declined.
Solar Energy Market Segmentation
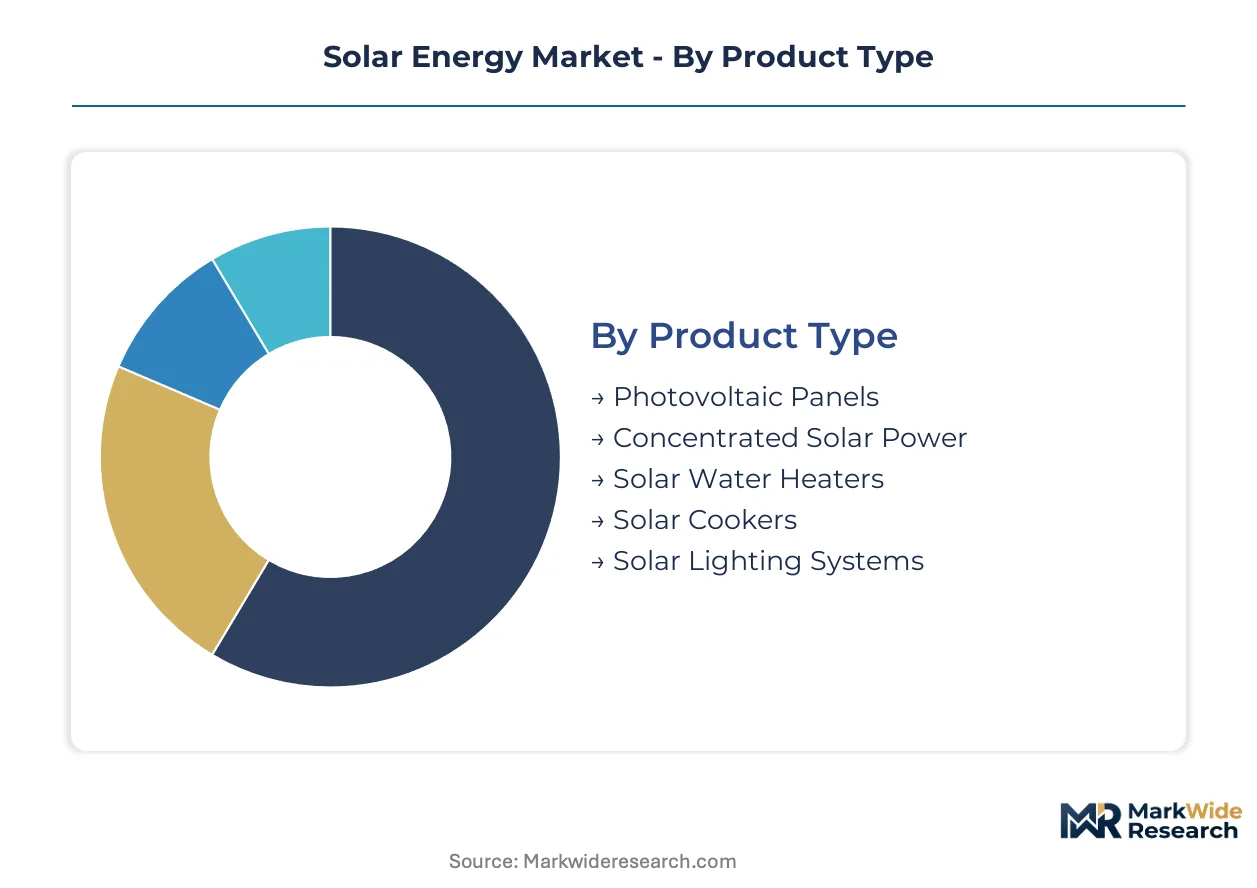
The solar energy market's segmentation reveals diverse technological applications and end-user adoption patterns. Understanding these segments is crucial for stakeholders to tailor product offerings and navigate policy-driven demand shifts. Each segment addresses specific energy needs, influencing investment priorities and regional market development.
Product Type:
The solar energy product landscape faces significant substitution pressure from rapidly advancing photovoltaic technologies.
- Photovoltaic Panels:These devices convert sunlight directly into electricity using semiconductor materials, predominantly silicon. Demand concentrates in both utility-scale projects and distributed residential systems due to their modularity and consistently falling costs.
- Concentrated Solar Power:This technology uses mirrors to focus a large area of sunlight onto a small receiver, generating heat for steam turbines or thermal storage. Utility-scale power generation in arid regions drives demand, offering dispatchable power capabilities.
- Solar Water Heaters:These systems capture solar radiation to heat water for domestic or commercial use. They reduce reliance on conventional heating sources.
- Solar Cookers:Designed for cooking food using solar energy, these devices offer a sustainable alternative in off-grid communities. They reduce fuel wood consumption.
- Solar Lighting Systems:These standalone units integrate photovoltaic panels, batteries, and LED lights for outdoor illumination. They provide energy-efficient lighting solutions in remote areas.
Photovoltaic Panels anchor the volume base while Concentrated Solar Power gains share at the steepest rate.
Application:
Application diversity in solar energy reflects varied end-use requirements across industrial and consumer sectors.
- Power Generation:This application involves converting solar energy into electricity for grid supply or off-grid consumption. Utility-scale solar farms and residential rooftop installations are primary contributors to global energy grids.
- Heating Solutions:Solar energy provides thermal energy for space heating, water heating, and industrial processes. Commercial enterprises adopt these systems to reduce operational energy costs.
- Water Pumping:Solar-powered pumps lift water for irrigation, livestock, and potable water supply in remote areas. Agricultural operations in regions with abundant sunlight benefit significantly from these systems.
- Telecommunications:Solar power provides reliable electricity for remote cellular towers and communication infrastructure. It ensures continuous operation in off-grid locations.
- Space Heating:Solar thermal systems contribute to heating indoor spaces, often integrated with conventional heating systems. This reduces energy consumption in buildings.
Power Generation applications command the largest market share, with Telecommunications exhibiting significant expansion.
Installation Type:
Installation types are differentiated by scalability and integration complexity across diverse environments.
- Ground-Mounted:Large solar arrays installed on open land, typically for utility-scale power generation. These systems benefit from optimal sun exposure and efficient maintenance for large energy output.
- Rooftop:Solar panels installed on the roofs of residential, commercial, and industrial buildings. These systems support distributed generation, reducing electricity bills for property owners.
- Floating:Photovoltaic arrays deployed on bodies of water like reservoirs or lakes. They offer land-saving benefits and improved panel efficiency due to water cooling.
- Building-Integrated:Solar technology seamlessly integrated into building materials such as facades or windows. This provides aesthetic appeal and energy generation for urban structures.
- Portable Units:Compact, movable solar panels designed for temporary power needs, camping, or emergency situations. They offer flexible energy access for individual users.
Ground-Mounted systems account for the highest installed capacity, while Floating installations are expanding rapidly.
End User:
End-user segments are driven by distinct sustainability goals and energy independence imperatives.
- Commercial Enterprises:Businesses adopting solar for their facilities, including rooftop and ground-mounted systems, to reduce operating costs and meet corporate sustainability targets. These entities seek stable energy prices and carbon footprint reduction.
- Residential Consumers:Homeowners installing solar panels for personal electricity consumption and grid-tied energy generation. They aim for energy bill savings and increased energy autonomy.
- Agricultural Operations:Farms and agricultural businesses utilizing solar power for irrigation, cold storage, and other operational needs. This segment benefits from reliable power supply in remote farming regions.
- Government Facilities:Public sector entities deploying solar energy for government buildings, military bases, and public infrastructure. These installations support public policy objectives for renewable energy.
- Educational Institutions:Schools, colleges, and universities installing solar panels to power campuses and educate students on renewable energy technologies. They demonstrate commitment to environmental stewardship.
Commercial Enterprises represent a substantial and growing demand segment, with Agricultural Operations demonstrating increasing uptake for specific applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dominant manufacturing base for polysilicon and wafers supplies a global market increasingly driven by energy independence goals. Policy incentives in the United States and European Union aim to diversify sourcing and onshore production capabilities. This creates a complex trade dynamic for solar components worldwide.
United States
Demand for utility-scale projects and commercial rooftop systems drives US solar deployment. The US Inflation Reduction Act provides substantial tax credits for domestic manufacturing and new installations, stimulating local supply chains. California leads in distributed generation, with robust incentives for residential and commercial solar adoption.
China
China's vast manufacturing base for photovoltaic panels and components anchors global supply, meeting both domestic and international demand. The country's dual carbon goals mandate a rapid transition to renewable sources, securing significant domestic demand. Shandong and Jiangsu provinces host major production clusters for polysilicon and wafer fabrication.
Germany
Residential consumers and commercial enterprises pursue distributed generation across Germany, driven by high electricity prices. The EU Green Deal accelerates renewable energy targets for member states, influencing national policies for solar deployment. Bavaria and Baden-Württemberg demonstrate high adoption rates for rooftop solar and battery storage systems.
India
Energy access and industrial power needs drive solar installations across India, especially in remote regions. The Ministry of New and Renewable Energy promotes schemes like PM-KUSUM for agricultural solar pumps and rooftop solar. Gujarat and Rajasthan are developing large-scale solar parks for utility-scale power generation.
Australia
High electricity prices and abundant sunlight stimulate residential and commercial solar uptake in Australia, particularly for rooftop systems. State-level incentives and feed-in tariffs support distributed generation for property owners. Queensland and New South Wales show significant deployment of rooftop solar and grid-scale battery projects.
Solar Energy Market Key Industry Players
Player mix skews toward large-scale integrated manufacturers and specialized component providers. The market structure exhibits a tiered consolidation, with a few dominant global players controlling significant module production capacity. Strategic archetypes include vertically integrated module suppliers, inverter technology specialists, and project developers. Companies pursue aggressive capacity expansion and technology licensing to secure market share across diverse geographies.
Specialization in manufacturing scale and component technology defines several market participants. JinkoSolar Holding Co., Ltd., a Chinese-based company, represents the large-scale photovoltaic module manufacturing archetype, driving global supply. First Solar, Inc. exemplifies a utility-scale thin-film technology provider, focusing on specific applications in North America. Enphase Energy, Inc., a US-based corporation, occupies a position as a microinverter technology specialist for the distributed residential segment, enhancing system performance. These entities anchor distinct segments of the solar value chain through their technological focus.
| Leading Market Players |
|---|
| Enphase Energy, Inc. |
| Canadian Solar Inc. |
| First Solar, Inc. |
| Sungrow Power Supply |
| SolarEdge Technologies, Inc. |
| Trina Solar Co. Ltd |
| JinkoSolar Holding Co., Ltd. |
| JA Solar Technology Co., Ltd. |
| Sunrun Inc. |
| Others |
Cost & Logistics Intelligence
The US Inflation Reduction Act and the EU Green Deal directly influence solar component qualification and price differentiation. These policy mechanisms drive both domestic manufacturing incentives and global trade dynamics.
Pricing Analysis
Photovoltaic panel technology generations exhibit distinct pricing gaps, with newer, more efficient monocrystalline and n-type cells commanding premiums over older designs. Pricing for solar modules primarily follows a commodity spot model, influenced by immense manufacturing scale in China. Price differentiation stems from module efficiency, brand reputation, and geographic delivery costs. Price softness runs through standard modules due to oversupply, making residential consumers and commercial enterprises highly price-sensitive. Utility-scale developers, however, prioritize long-term levelized cost of energy.
Supply Chain Analysis
Inventory levels and lead times for solar components remain sensitive to manufacturing output in primary hubs, particularly in China. The global solar supply chain draws from China for the vast majority of polysilicon, wafers, and cells. This concentration creates significant geopolitical and logistical risks, exposing the market to potential trade disruptions and price volatility for critical raw materials like high-purity silicon. Distribution runs through large-scale module manufacturers selling directly to project developers, alongside specialized component distributors for smaller integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar energy market represents a high-growth disruption, driven by persistent technological advancements in cell efficiency. Policy frameworks like the US Inflation Reduction Act further accelerate this transition, creating substantial new opportunities.
For Market Incumbents: Secure access to diversified polysilicon and wafer supply chains to mitigate geopolitical risks and single-source vulnerabilities. Invest heavily in R&D for next-generation photovoltaic technologies like perovskite solar cells to counter module commoditization. Expand manufacturing capacity in regions like the US and EU, leveraging incentives from the US Inflation Reduction Act to build resilience. This strategy protects against trade disruptions while maintaining technology leadership.
For New Entrants and Emerging Players: Integrated energy ecosystem solutions represent a service-layer gap where incumbents often under-serve, particularly in residential and commercial distributed generation. New entrants should target emerging geographic markets in Southeast Asia and Africa, focusing on bundled solar-plus-storage offerings. Develop specialized module-level power electronics and energy management software for complex rooftop installations. A go-to-market angle emphasizing optimized energy use and grid independence will resonate with property owners.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across advanced module manufacturing and grid integration infrastructure. Long-term viability remains strong for companies enabling distributed generation and utility-scale projects with integrated storage solutions over the next five to ten years. Investors should seek acquisition targets in specialized component technology, such as microinverter developers or battery energy storage system integrators. Policy stability for domestic manufacturing incentives, particularly in the US and EU, signals continued investment attractiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in US/EU | Reduces supply chain vulnerability and capitalizes on regional incentives. |
| Technology Licensing for Perovskites | Accelerates next-generation cell development and broadens application scope. |
| Vertical Integration into Storage | Offers integrated energy solutions and enhances grid stability for customers. |
| Develop Energy Management Software | Maximizes energy harvest and provides value-added services for end-users. |
| Green Certification Program | Meets regulatory demands like the EU's CBAM and attracts ESG-focused investors. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research. Primary insights came from discussions with utility planning officers, EPC contractors, module manufacturers, and residential installers. Secondary validation drew from EIA data, IEA reports, company financial filings, and trade association publications. This approach ensured robust bottom-up and top-down triangulation of market data.
The forecasting framework projected market dynamics across the analysis window, integrating historical trends with anticipated growth drivers. Segmentation dimensions modeled included product type, application, installation type, end-user, and the regional policy environment. Compound annual growth rates were derived from a blend of historical performance and projected demand shifts. Key forecast inputs included polysilicon pricing and the uptake rate of government incentives.
Underlying assumptions cover policy stability and technology progression, with deviation risk concentrated in geopolitical trade tensions and raw material supply disruptions. These factors could significantly alter market trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Bacteria Powered Solar Cell Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Home Solar System Market
Solar Power Systems
US Solar Carport Market
Solar Power Systems
Solar Collector Panels Market
Solar Power Systems
Flexible Parylene-Based Solar Cells Market
Solar Power Systems
Distributed Solar Power Generation System Market
Solar Power Systems
Asia Pacific Solar Backsheet Market
Solar Power Systems
Solar Photovoltaic Glass Market
Solar Power Systems
Box Solar Cookers Market
Solar Power Systems
Third Generation Solar Cell Sales Market
Solar Power Systems
Organic Solar Cells Market
Solar Power Systems
Photovoltaic (PV) Materials Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Solar Panels Frame Market
Solar Power Systems
Global Photovoltaic Glass Market