
 North America Single Axis Solar Tracker Market | 2026-2036
North America Single Axis Solar Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
North America Single Axis Solar Tracker Market Analytics
Market Context with Strategic Players
Texas and Arizona manufacturing corridors are reshaping domestic tracker supply chains as steel fabrication and assembly capacity expands near project clusters. Nextracker Inc leverages vertical integration in torque tube production to control lead times across southwestern utility installations. Array Technologies Inc anchors its position through distributed manufacturing that reduces freight costs for high-volume solar farm developers. Solar Flexrack competes with lighter-weight designs that cut foundation requirements on rocky or uneven terrain.
Technical Definition and Structural Segments
North America Single Axis Solar Trackers are electromechanical mounting systems that rotate photovoltaic modules along one axis, typically east-west, to maintain optimal sun incidence angles and boost energy harvest by 20-35% over fixed-tilt configurations. Horizontal single-axis trackers dominate utility installations where row spacing and terrain grading permit long continuous tables across flat desert parcels. Smart control systems represent the fastest-expanding segment as embedded sensors and predictive algorithms replace basic astronomical tracking, creating margin pools in software-enabled performance optimization. Ground-mounted installations sustain the volume base while floating and integrated configurations remain nascent sub-sectors with concentrated pilot activity in California reservoir and agrivoltaic projects.
Regulatory Framework and Forward Outlook
The Federal Energy Regulatory Commission and state public utility commissions shape interconnection queues and transmission access that determine tracker project viability across the region. The Inflation Reduction Act's domestic content bonus credits and Buy America provisions redirect procurement toward North American steel and assembly sources. EPA greenhouse gas accounting rules and state renewable portfolio standards in California, Texas, and New Mexico cement tracker economics against fixed-tilt alternatives. Stakeholders must monitor interconnection reform timelines and domestic content threshold adjustments as these regulatory levers determine project returns and supplier qualification criteria.
Market Dynamics
The Inflation Reduction Act's domestic content bonus credits are restructuring procurement patterns across the North American single axis solar tracker supply chain, forcing developers to requalify suppliers and steel sources.
Growth Catalysts
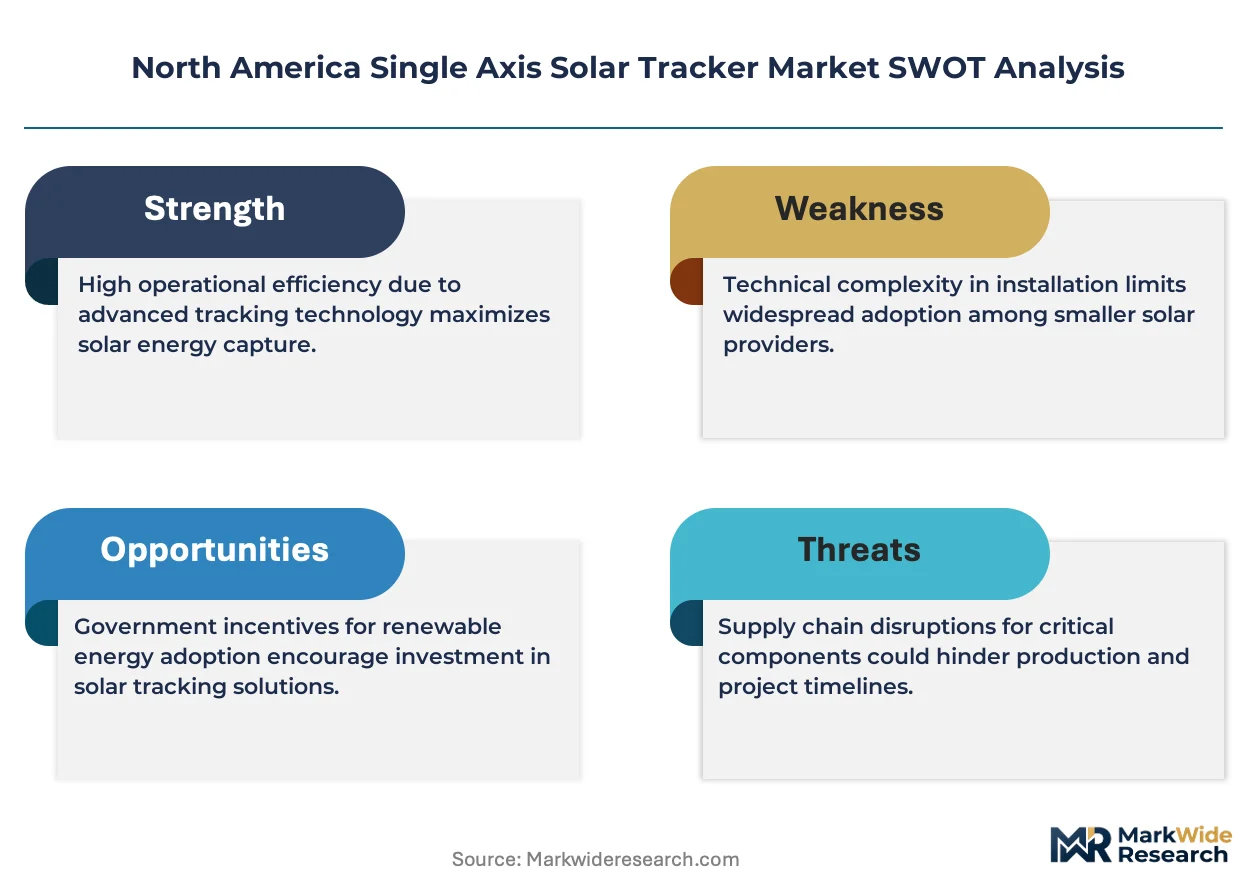
- Investment Tax Credit extension:The IRA's multi-year credit certainty allows utility-scale developers to underwrite tracker economics across 20-year project horizons. Texas and Arizona utility pipelines are expanding tracker deployment percentages.
- Steel fabrication corridors:Domestic torque tube and purlin manufacturing capacity is concentrating near southwestern project clusters, compressing lead times from 26 weeks to 14 weeks for utility EPCs.
- Smart control algorithms:Embedded sensor networks with machine learning-based backtracking are replacing basic astronomical controllers, extracting additional yield from diffuse light conditions.
Market Restraints
- Steel price volatility:Galvanized steel coil input costs fluctuate with scrap metal and zinc markets, squeezing tracker OEM margins when long-dated project contracts fix pricing.
- Interconnection queue congestion:FERC Order 2023 implementation delays at regional transmission organizations are freezing project energization timelines, deferring tracker revenue recognition.
- Fixed-tilt substitution in rocky terrain:Sites with shallow bedrock or steep grading face foundation cost premiums that erase tracker yield advantages, preserving fixed-tilt share in Appalachia and Canadian Shield regions.
Strategic Opportunities
- Agrivoltaic dual-use installations:Elevated tracker architectures that maintain ground clearance for livestock grazing or shade-tolerant crops are opening project sites previously excluded from solar development.
- Floating reservoir deployments:California water districts are piloting pontoon-mounted single-axis systems on irrigation reservoirs, combining evaporation reduction with energy generation.
- Buy America threshold escalation:The domestic content bonus credit's rising steel and manufactured product requirements are advantaging vertically integrated North American tracker producers over imported alternatives.
Industry Challenges
- Electromechanical technician scarcity:Utility-scale solar farms require specialized crews for drive motor replacement and control system troubleshooting, and training pipelines have not kept pace with installation velocity.
- Foundation verification complexity:Geotechnical variability across desert alluvial fans demands site-specific pile depth calculations, adding engineering overhead and schedule risk to EPC contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Single Axis Solar Tracker Market |
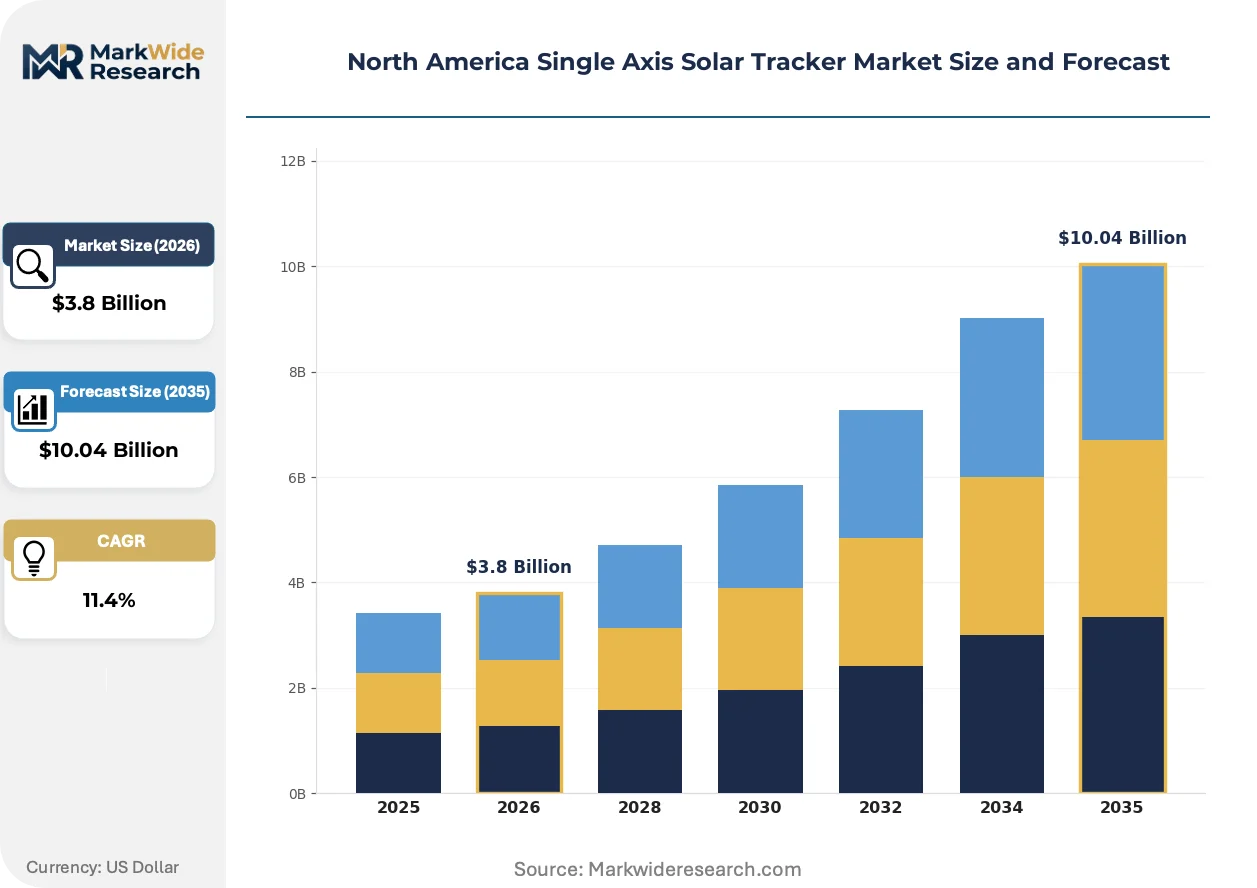
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
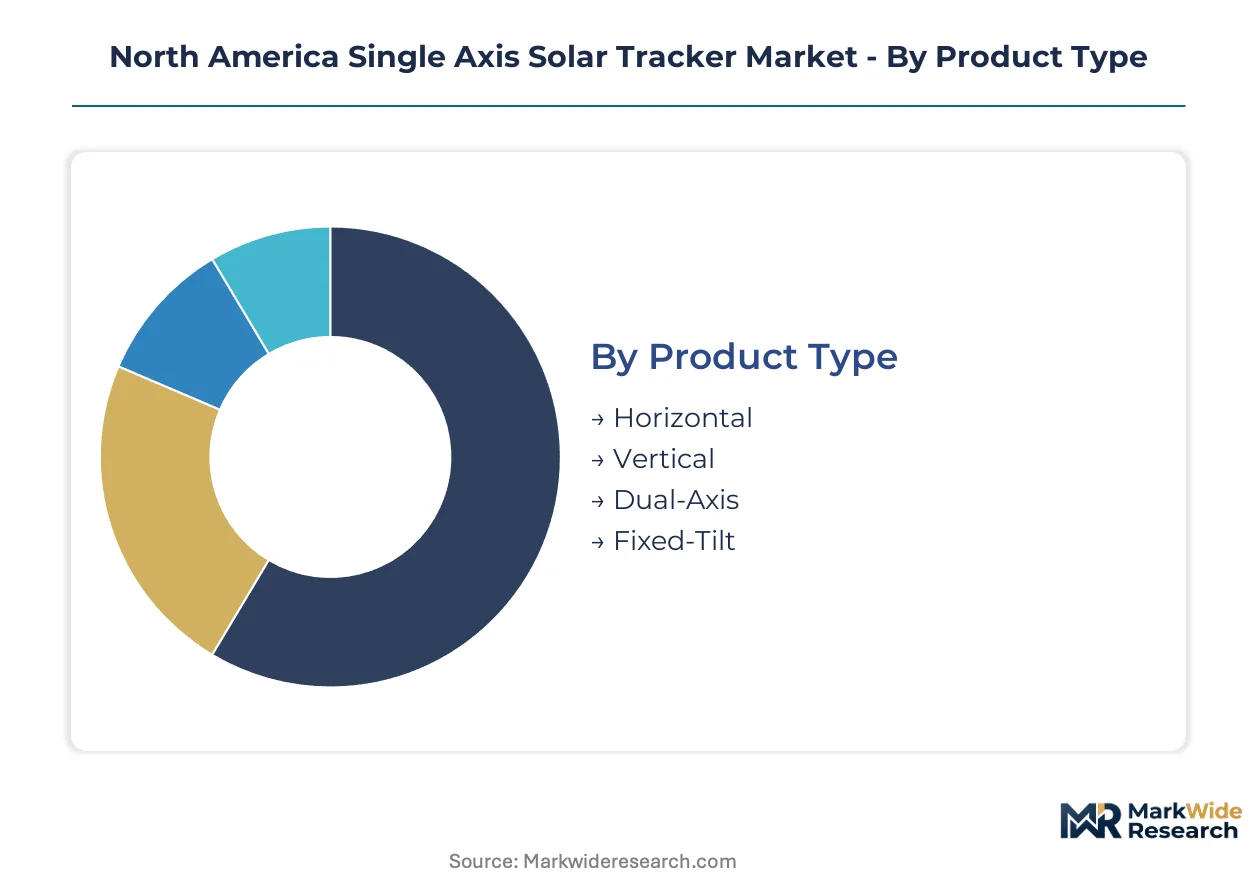
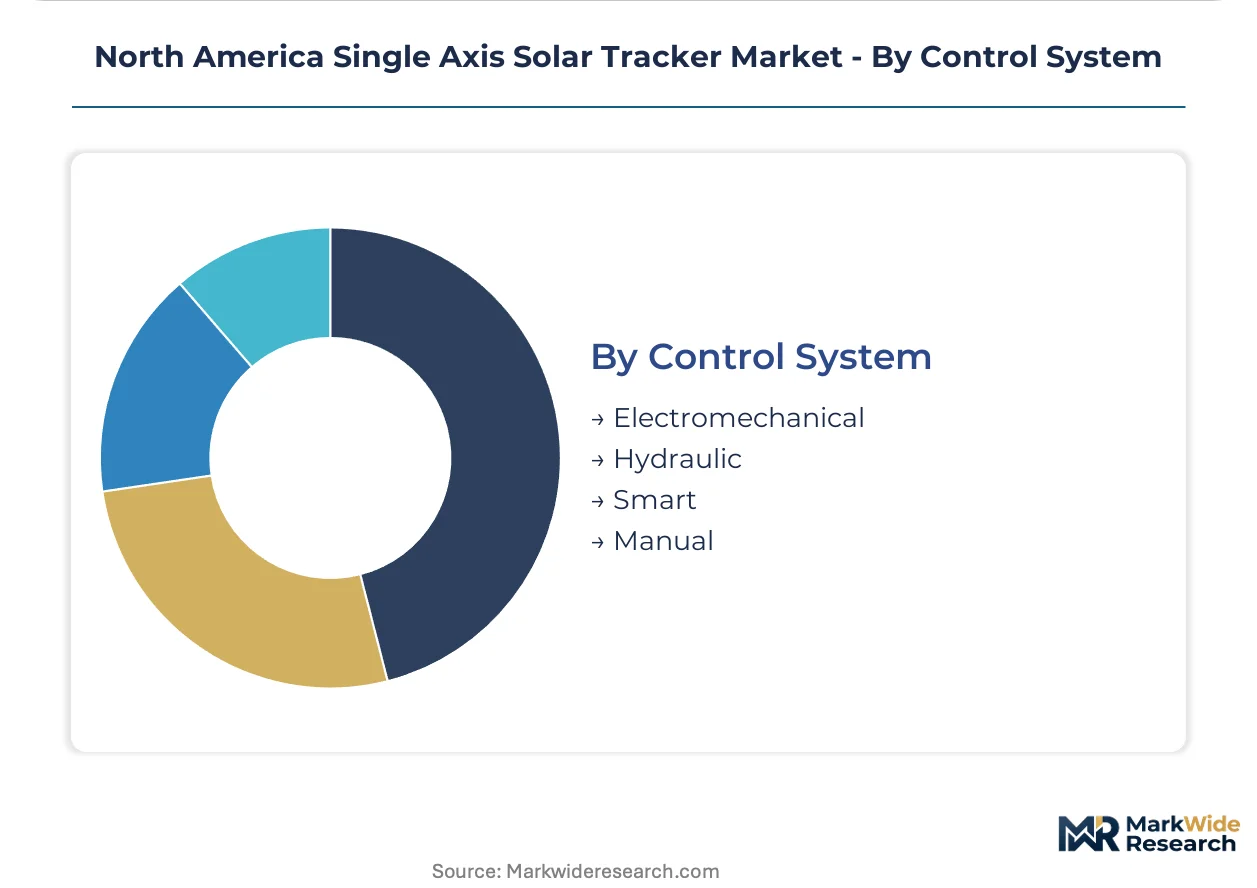
| Segmentation | Product Type: Horizontal, Vertical, Dual-Axis, Fixed-Tilt End User: Utility, Commercial, Residential, Industrial Installation: Ground-mounted, Roof-mounted, Floating, Integrated Control System: Electromechanical, Hydraulic, Smart, Manual |
| Companies Covered | Nextracker Inc, Array Technologies Inc, Solar Flexrack, DCE Solar, Valmont Industries, Inc, FTC Solar, Inc, GameChange Solar, Ideematec, Arctech Solar Holding Co, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Single Axis Solar Tracker Market Evolving Landscape
Control system architectures are converging with predictive weather analytics and module-level power electronics, shifting competitive advantage from mechanical engineering toward software-enabled performance optimization.
Bifacial module compatibility is hybridizing tracker row spacing and height standards. Developers deploying glass-glass bifacial panels in California and Texas are widening inter-row gaps and elevating torque tube heights to capture rear-side albedo gains. This configuration is compressing traditional energy density metrics while boosting specific yield per installed watt.
The IRA's domestic content bonus credit and Buy America provisions are redirecting steel procurement toward North American melt-and-pour sources. Tracker OEMs are requalifying Mexican and Canadian steel mills to meet FERC-adjacent domestic content thresholds. Southwestern project developers are absorbing modest cost premiums to secure bonus credit eligibility.
Utility procurement teams are unbundling tracker supply from EPC wrap contracts, creating direct OEM relationships. Large-scale IPPs in Texas and Arizona are negotiating multi-project framework agreements that lock volume commitments for price transparency. This disintermediation is compressing EPC margin pools while transferring performance risk to tracker manufacturers.
North America Single Axis Solar Tracker Market Segmentation
Single-axis tracker configurations vary sharply by terrain constraints, project scale, and control sophistication. Each segmentation dimension carries distinct procurement patterns and margin structures that shape supplier positioning across southwestern utility corridors.
Product Type:
Tracker architectures span a use-case spectrum from flat desert utility farms to constrained commercial rooftops, with mechanical complexity and yield premiums determining adoption economics.
- Horizontal:East-west rotating tables dominate utility-scale deployments across Texas and Arizona flatlands, delivering 20-35% yield gains over fixed-tilt through continuous sun tracking. Long continuous rows minimize motor count per megawatt, compressing balance-of-system costs for desert solar farms with uniform grading.
- Vertical:North-south axis configurations suit high-latitude sites where summer sun angles favor vertical tracking, with concentrated pilot activity in Canadian prairie provinces and northern US agricultural co-locations. Steeper tilt ranges optimize winter performance but demand heavier torque tubes and foundation loads.
- Dual-Axis:Two-degree-of-freedom systems maximize energy capture through azimuth and elevation adjustment, with niche deployment in concentrated solar-thermal hybrid projects where precision tracking justifies mechanical complexity premiums.
- Fixed-Tilt:Stationary racking retains share in rocky terrain or steep-sloped sites where foundation costs for tracking infrastructure erase yield advantages, preserving presence in Appalachian and Canadian Shield installations.
The dominant share belongs to Horizontal configurations, while Smart control integration is closing the gap fastest through software-enabled performance differentiation.
End User:
Customer scale determines procurement sophistication, with utility buyers driving standardization and smaller segments demanding customization.
- Utility:Multi-hundred-megawatt solar farms in Texas, Arizona, and California anchor volume demand, with developers negotiating multi-project framework agreements that lock steel pricing and compress supplier margins through volume commitments.
- Commercial:Behind-the-meter installations for retail chains and data centers favor shorter row lengths and distributed control architectures, with procurement concentrating through national solar integrators rather than direct OEM relationships.
- Residential:Single-axis tracking remains rare in rooftop applications due to structural load constraints and wind exposure liabilities, with experimental deployments limited to ground-mounted backyard systems in high-irradiance southwestern states.
- Industrial:On-site generation for manufacturing facilities and mining operations pairs elevated trackers with bifacial modules to maximize output per acre where land constraints bind.
Utility procurement commands the revenue base, with Industrial expanding most quickly as corporate renewable targets harden.
Installation:
Mounting topology constrains foundation design and environmental permitting pathways across divergent site conditions.
- Ground-mounted:Standard pile-driven foundations across graded desert terrain sustain the installation base, with geotechnical variability across alluvial fans demanding site-specific engineering that extends EPC timelines.
- Roof-mounted:Ballasted or attached systems on flat commercial rooftops face structural load limits that restrict tracker row lengths and motor placement, preserving fixed-tilt dominance in this topology.
- Floating:Pontoon-mounted single-axis arrays on California irrigation reservoirs combine evaporation reduction with generation, with water district pilots testing corrosion-resistant torque tube coatings and anchoring systems.
- Integrated:Agrivoltaic and building-integrated configurations remain nascent, with elevated tracker architectures maintaining ground clearance for livestock grazing or shade-tolerant crops in pilot southwestern deployments.
Ground-mounted foundations hold the volume majority, though Floating pilots are gaining regulatory traction fastest among alternative topologies.
Control System:
Automation sophistication determines yield extraction and maintenance burden, creating divergent margin pools across mechanical and digital value chains.
- Electromechanical:Motor-driven gearboxes with astronomical position algorithms sustain the installed base across legacy utility fleets, with replacement part demand concentrating around drive motor and bearing failures in desert heat and dust conditions.
- Hydraulic:Fluid-power actuation suits heavy-load vertical trackers and extreme wind-load zones, with maintenance complexity limiting adoption to specialized industrial and high-latitude installations.
- Smart:Embedded sensor networks with machine learning-based backtracking and predictive weather integration represent the steepest expansion trajectory, extracting additional yield from diffuse light and enabling remote diagnostics that reduce site visit frequency.
- Manual:Seasonal adjustment systems retain minimal share in off-grid and developing-world applications, effectively absent from North American commercial deployment.
Electromechanical controllers retain the installed base lead, with Smart systems climbing the fastest as predictive analytics displace basic astronomical tracking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel fabrication corridors have concentrated near southwestern project clusters, compressing lead times and reconfiguring procurement geography across the continent. Texas and Arizona anchor supply-side capacity while demand disperses across irradiance-rich states and provinces.
United States
Utility-scale pipelines in Texas, Arizona, and California drive volume demand as developers underwrite tracker economics against 20-year project horizons. The Inflation Reduction Act's domestic content bonus credits redirect procurement toward North American steel sources. Manufacturing corridors near Phoenix and Dallas-Fort Worth concentrate torque tube fabrication capacity to serve adjacent utility installations.
Canada
High-latitude prairie provinces favor vertical tracker configurations where summer sun angles demand steeper tilt ranges. Provincial renewable portfolio standards in Alberta and Saskatchewan cement tracker deployment against fixed-tilt alternatives. Toronto-based EPCs coordinate cross-border procurement for projects straddling the Great Lakes wind corridors.
Mexico
Sonora and Chihuahua desert zones attract cross-border utility development leveraging irradiance levels comparable to Arizona. Mexican steel mills requalify under FERC-adjacent domestic content thresholds to serve US project demand. Monterrey fabrication clusters supply torque tube assemblies to Texas borderland installations.
North America Single Axis Solar Tracker Market Competitive Landscape
Vertically integrated producers and distributed manufacturers split the market between lead-time control and freight cost minimization. The supplier base concentrates around southwestern fabrication corridors where steel sourcing proximity determines qualification for domestic content bonus credits. Two archetypes dominate: torque tube integrators managing captive steel supply, and modular designers optimizing for rocky terrain adaptability. Competitive moves center on backward integration into steel melt-and-pour sources and multi-project framework agreements that lock volume commitments.
Among southwestern US-based integrators, Nextracker Inc and Array Technologies Inc occupy positions reflecting divergent supply chain philosophies. Nextracker exemplifies the vertically integrated archetype through captive torque tube production, while Array Technologies represents distributed manufacturing models that minimize freight costs for high-volume developers. Solar Flexrack sits within the terrain-specialist tier, competing through lighter-weight structural designs that reduce foundation requirements on uneven sites.
| Leading Market Players |
|---|
| Nextracker Inc |
| Array Technologies Inc |
| Solar Flexrack |
| DCE Solar |
| Valmont Industries, Inc |
| FTC Solar, Inc |
| GameChange Solar |
| Ideematec |
| Arctech Solar Holding Co |
| Others |
Value Network & Pricing Analysis
Torque tube fabrication overcapacity across Arizona and Texas manufacturing corridors compresses supplier pricing power while incentivizing volume commitments from utility-scale developers seeking domestic content bonus credit qualification.
Pricing Analysis
The Inflation Reduction Act's domestic content bonus credit dictates the pricing tier structure across the North American single axis solar tracker market. Three-tier pricing structure across premium, standard, and economy levels separates vertically integrated producers with captive steel supply from modular fabricators and imported alternatives. Price differentiation hinges on domestic melt-and-pour certification and volume scale, with utility EPCs commanding steepest discounts through multi-project framework agreements. Cost compression in standard-tier assemblies is intensifying because Mexican and Canadian steel mills requalify under FERC-adjacent thresholds, eroding margin buffers for non-integrated competitors. Commercial and industrial segments exhibit highest price sensitivity due to smaller project scales and limited bonus credit capture, while utility IPPs prioritize qualification certainty over unit cost minimization.
Supply Chain Analysis
Galvanized steel coil feedstock draws from US, Mexican, and Canadian melt-and-pour sources as tracker OEMs requalify mills to meet domestic content thresholds. Critical inputs span zinc for corrosion protection, high-strength steel alloys for torque tubes, and precision gearboxes for drive assemblies. Supply chain risk centers on single-source vulnerability for specialized drive motors sourced from concentrated electromechanical component manufacturers. Distribution runs through direct OEM relationships with utility developers, disintermediating traditional EPC wrap contracts and transferring performance risk upstream.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as procurement unbundling separates tracker supply from EPC wrap contracts and smart control differentiation displaces commodity mechanical positioning.
For Market Incumbents: Harden domestic content qualification through backward integration into North American steel melt-and-pour sources, locking bonus credit eligibility before threshold escalations tighten. Expand Phoenix and Dallas-Fort Worth fabrication capacity to compress lead times for adjacent utility pipelines, defending share against Mexican cross-border competitors leveraging depreciated peso labor costs. For New Entrants and Emerging Players: Pursue agrivoltaic dual-use architectures where elevated tracker designs open previously excluded agricultural sites, exploiting underpenetrated terrain-specialist demand. Target floating reservoir deployments in California water districts piloting pontoon-mounted systems, partnering with irrigation infrastructure operators for regulatory co-approval and site access. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated tracker producers with captive torque tube supply and qualified domestic steel sourcing, positioned to capture bonus credit premiums across the analysis window. Monitor interconnection queue reform timelines at FERC and regional transmission organizations as the inflection signal determining project energization velocity and tracker revenue recognition cadence.| Strategic Initiative | Industry Significance |
|---|---|
| Steel Mill Requalification Program | Qualifies Mexican and Canadian melt-and-pour sources under IRA domestic content thresholds for bonus credit capture. |
| Smart Control Algorithm Development | Embeds machine learning backtracking to extract yield from diffuse light and enable remote diagnostic capabilities. |
| Agrivoltaic Architecture Pilot | Tests elevated tracker clearance for livestock grazing compatibility, expanding addressable site inventory. |
| Direct OEM Framework Agreements | Locks multi-project volume commitments with Texas and Arizona utility IPPs, disintermediating EPC margin pools. |
| Floating Reservoir Deployment | Combines California irrigation reservoir evaporation reduction with generation, opening water district procurement channels. |
Research Methodology
Initial hypotheses were tested against primary input from utility project developers, EPC procurement directors, tracker OEM engineering leads, and steel fabrication plant managers and refined through secondary validation against EIA generation databases, FERC interconnection filings, IRA domestic content guidance documents, and SEC 10-K disclosures from publicly traded tracker manufacturers. Bottom-up project pipeline aggregation was triangulated against top-down market sizing from component shipment data and steel consumption metrics.
Demand-supply-balance modeling across the projection horizon incorporated tracker deployment percentages by project scale, domestic content qualification rates, and control system sophistication tiers. Segmentation dimensions spanned product architecture, end-user category, installation topology, and automation level. CAGRs were derived from installed base growth trajectories and replacement cycle timing, with forecast inputs including interconnection queue progression, steel price volatility bands, and bonus credit threshold escalation schedules.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories, steel scrap pricing, or transmission investment cycles would shift the trajectory of utility-scale deployment and tracker procurement velocity. Cross-checking against EIA Short-Term Energy Outlook projections and regional transmission organization interconnection reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Egypt Solar Photovoltaic (PV) Market
Solar Power Systems
Concentrated Photovoltaic System Market
Solar Power Systems
DSC Solar Technologies Market
Solar Power Systems
Solar Fuel Market
Solar Power Systems
Floating Solar Panels Market
Solar Power Systems
Flexible Parylene-Based Solar Cells Market
Solar Power Systems
Thailand Solar Energy Market
Solar Power Systems
Solar Cell Films Market
Solar Power Systems
Solar Tracker Installation Market
Solar Power Systems
Middle-East and Africa Distributed Solar Power Generation Market
Solar Power Systems
Distributed Solar Power Generation System Market
Solar Power Systems
Australia Solar Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Roofing Market
Solar Power Systems
High Concentration Photovoltaics Market
Solar Power Systems
Solar PV Mounting Systems Market