
 Solar Collector Panels Market | 2026-2036
Solar Collector Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Collector Panels Market Insights
Heat pump integration with solar thermal systems is reconfiguring collector panel architectures toward hybrid energy platforms. Bosch Thermotechnology leverages its heating-system heritage to anchor European demand for combined solar-thermal and heat-pump installations. Sunrain Group dominates cylindrical evacuated-tube production at scale across Shandong province. GREENoneTEC sustains Austrian manufacturing leadership through selective absorber-coating specialization.
Solar collector panels are heat-absorbing devices, typically comprising copper or aluminum absorber plates with tempered glass glazing and insulated casings, designed to transfer captured solar radiation to fluid circulation loops for water or space heating applications. Evacuated tube collectors capture premium pricing in cold-climate installations where reduced heat loss determines system viability. Flat-plate collectors occupy mature cost-optimized segments across Mediterranean and Middle Eastern residential rooftops. Building-integrated installations are gaining specification share as architects treat collector surfaces as envelope-cladding elements rather than appended mechanical equipment.
China's MIIT enforces GB standards that mandate minimum optical efficiency thresholds for domestically sold collectors. The EU F-Gas Regulation and Ecodesign directives are phasing out refrigerant-dependent backup systems, indirectly elevating pure solar thermal specifications in European procurement. Stakeholders must monitor whether emerging heat-pump coupling mandates in German building codes fragment product standards or consolidate platform-compatible designs.
Market Dynamics
Heat pump integration is restructuring solar collector panel architectures toward hybrid thermal platforms, forcing manufacturers to redesign absorber geometries and fluid loops for dual-source compatibility.
Growth Catalysts
- China's dual carbon goals:The MIIT's updated GB standards for optical efficiency are accelerating replacement cycles among domestic manufacturers and elevating export product specifications.
- Residential water heating:Decentralized renewable thermal systems are gaining specification share as households seek independence from gas-grid price volatility.
- Evacuated tube technology:Premium cold-climate installations in Nordic and Alpine regions are driving demand for reduced heat-loss configurations.
Market Restraints
- Copper and aluminum input costs:Absorber plate materials face commodity price volatility that compresses margin structures for flat-plate collector assemblers.
- Shandong-Zhejiang supply concentration:Component ecosystems and finished panel production cluster in China's eastern coastal provinces, creating geographic risk exposure.
- Refrigerant-dependent backup phase-out:The EU F-Gas Regulation is eliminating conventional auxiliary heating options, forcing costly system redesigns.
Strategic Opportunities
- Building-integrated thermal envelopes:Architects are specifying collector surfaces as cladding elements rather than appended mechanical equipment, opening specification channels.
- German building code evolution:Emerging heat-pump coupling mandates may consolidate platform-compatible collector designs across European markets.
- Austrian absorber-coating specialization:Selective coating technology from Central European suppliers commands premium positioning in high-efficiency segments.
Industry Challenges
- GB standard compliance timelines:Chinese manufacturers face compressed certification windows as MIIT tightens optical efficiency thresholds.
- Heat-pump integration complexity:Legacy solar thermal installers lack training for hybrid system commissioning and control-loop calibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Collector Panels Market |
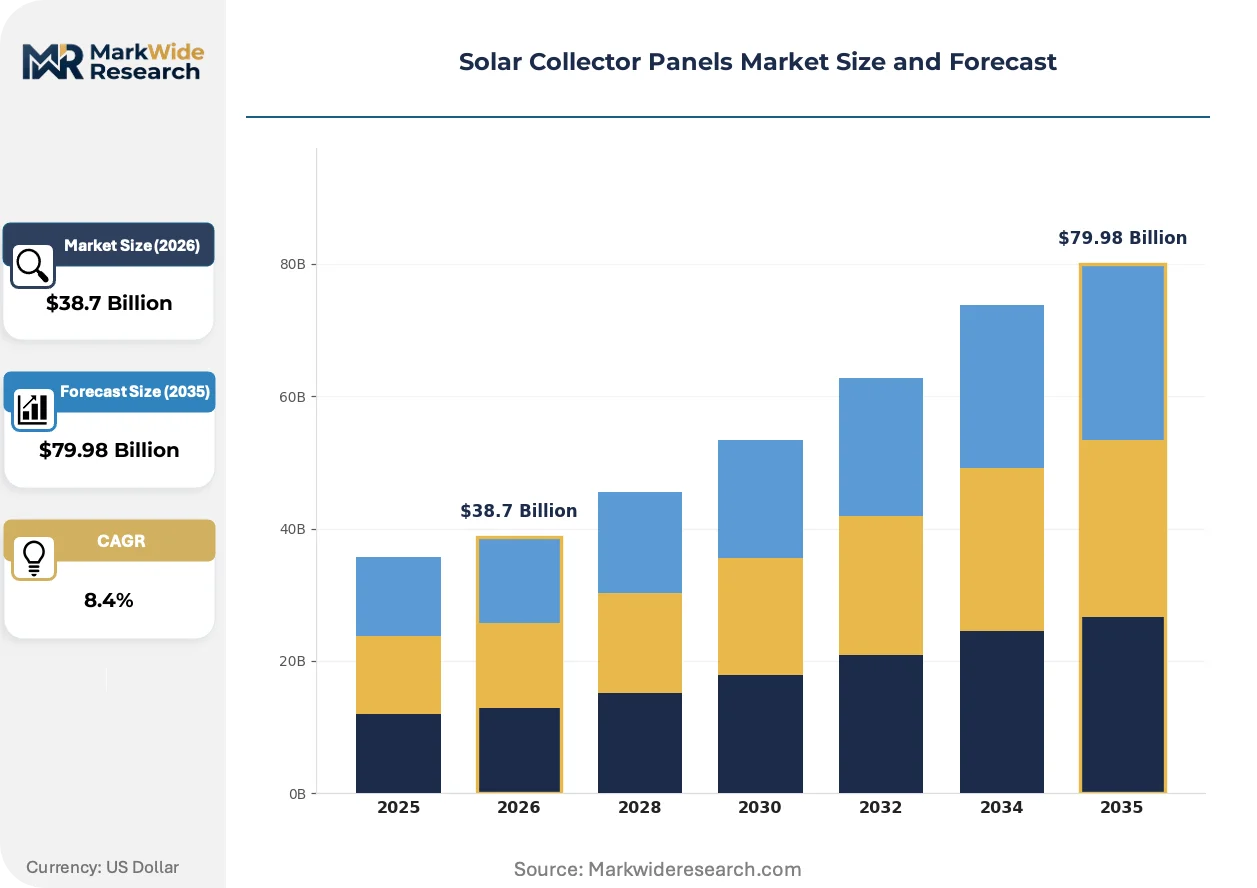
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat-Plate Collectors, Evacuated Tube Collectors, Concentrated Solar Power, Hybrid Collectors Installation Type: Roof-Mounted, Ground-Mounted, Building-Integrated, Portable Systems End User: Residential, Commercial, Industrial, Agricultural Technology: Thermal, Photovoltaic, Micro-Inverter, Smart Controls |
| Companies Covered | Bosch Thermotechnology, GREENoneTEC, Viessmann Werke, Solimpeks, Sunrain Group, Heliodyne, Apricus, Himin Solar, Vaillant Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Collector Panels Market Trends and Innovations
Collector panel architectures are converging with heat pump systems, absorber coatings are advancing optical performance thresholds, and procurement patterns are shifting toward integrated thermal platform sourcing.
Selective surface coatings are migrating from sputtered aluminum-nitride compositions toward advanced titanium-oxide multilayer stacks that achieve higher absorptance-to-emittance ratios. High-altitude and northern-latitude installers are specifying these coatings for premium residential and commercial projects. This migration from conventional coatings is compressing price premiums for standard flat-plate collectors in Mediterranean markets.
The EU F-Gas Regulation and Ecodesign directives are systematically eliminating refrigerant-dependent backup heating from new building specifications. This regulatory pressure is elevating pure solar thermal and hybrid solar-heat-pump configurations in European procurement. German and Austrian building codes are responding with updated technical standards that mandate compatibility testing between collector arrays and heat pump evaporators.
Architects and envelope consultants are bundling collector specification with facade system procurement rather than treating thermal collectors as separate mechanical equipment. This consolidation is displacing traditional HVAC-specifier influence in early design phases. The shift is most visible in Austrian and Swiss commercial building projects where building-integrated solar thermal cladding commands specification priority.
Solar Collector Panels Market Segmentation
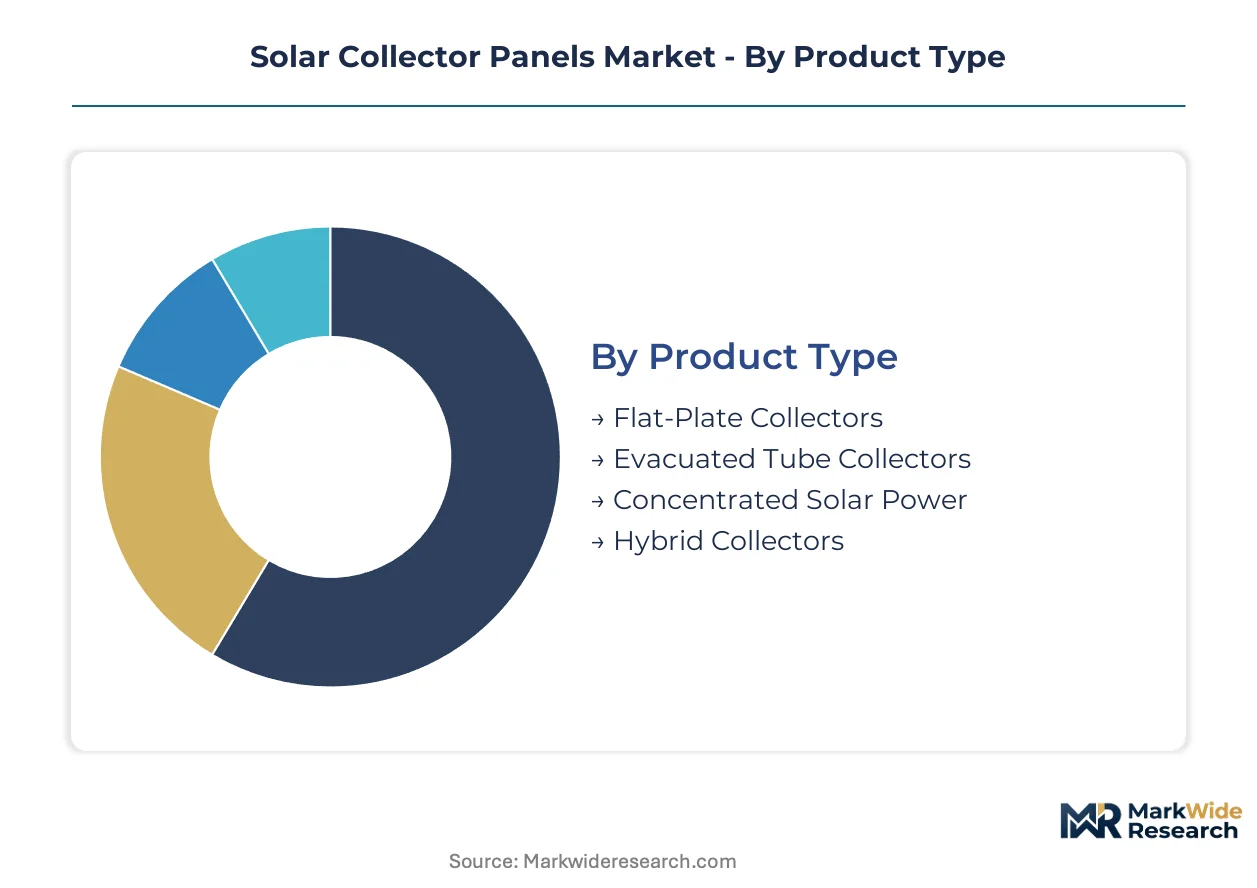
Segmentation in solar collector panels reveals how thermal capture technologies diverge across climate zones, mounting configurations, and energy system architectures. Product and installation categories map directly to regional building codes and end-user procurement patterns.
Product Type:
Mature cost-optimized designs coexist with emerging high-performance architectures across this category.
- Flat-Plate Collectors:Aluminum or copper absorber plates beneath tempered glass glazing dominate Mediterranean and Middle Eastern residential rooftops. Spanish and Italian installers specify these for cost-sensitive retrofits where moderate ambient temperatures reduce heat-loss penalties.
- Evacuated Tube Collectors:Cylindrical borosilicate glass tubes with vacuum insulation capture premium positioning in Nordic and Alpine cold-climate markets. German and Austrian building codes now mandate these configurations for new construction where reduced thermal losses determine system viability.
- Concentrated Solar Power:Parabolic trough and Fresnel lens systems target industrial process heat applications above 150°C.
- Hybrid Collectors:Combined photovoltaic-thermal units extract both electrical and thermal energy from shared aperture areas.
Flat-plate collectors retain volume leadership; evacuated tube configurations hold the steepest expansion curve.
Installation Type:
Mounting strategy selection tracks building stock age and envelope renovation cycles.
- Roof-Mounted:Conventional rack systems on pitched or flat rooftops constitute the baseline deployment mode across European and Chinese residential markets. Shandong province manufacturers optimize export packaging for containerized roof-mount kit delivery.
- Building-Integrated:Collector surfaces specified as facade cladding elements rather than appended mechanical equipment are gaining share in Austrian and Swiss commercial projects. Architects bundle these specifications with envelope system procurement, displacing traditional HVAC specifier influence.
- Ground-Mounted:Free-standing arrays serve agricultural and industrial process heat installations with available land buffers.
- Portable Systems:Mobile collector units address temporary construction site hot water and remote off-grid applications.
Roof-mounted installations retain volume leadership; building-integrated configurations are expanding most quickly.
End User:
Customer type segmentation maps to system scale, temperature requirements, and procurement sophistication.
- Residential:Decentralized water heating systems for single-family and multi-family dwellings represent the foundational demand layer. Chinese households in Shandong and Zhejiang provinces drive replacement cycles as MIIT tightens GB efficiency standards.
- Commercial:Hotels, hospitals, and institutional buildings specify mid-scale arrays for domestic hot water and space heating. German building code evolution toward heat-pump coupling mandates is reshaping commercial procurement specifications.
- Industrial:Process heat applications in food processing and textile manufacturing require higher-temperature collector configurations.
- Agricultural:Greenhouse heating and livestock facility hot water systems deploy ground-mounted arrays with seasonal load profiles.
Residential end users retain volume leadership; commercial segment specifications are climbing the fastest.
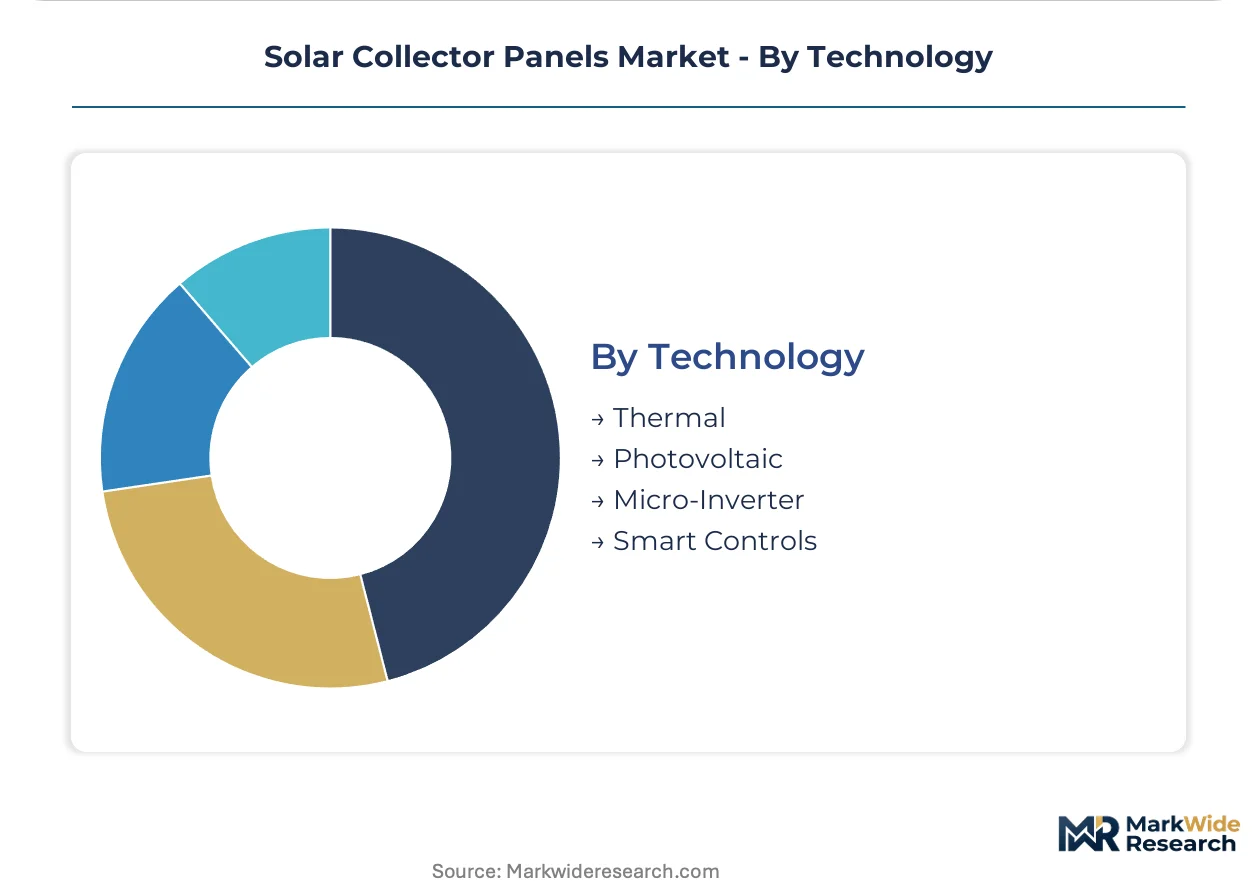
Technology:
Technology layers differentiate between pure thermal capture and integrated energy management architectures.
- Thermal:Direct fluid heating through absorber plate circulation loops remains the dominant technical foundation. Austrian suppliers command premium positioning through selective coating specialization.
- Smart Controls:Sensor networks and predictive algorithms optimize collector array output against heat pump evaporator demand. German and Austrian technical standards now mandate compatibility testing between these control layers.
- Photovoltaic:Electrical generation layers coexist with thermal capture in hybrid collector designs.
- Micro-Inverter:Distributed power electronics manage electrical output from photovoltaic-thermal hybrid units.
Thermal technology retains volume leadership; smart control integration holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial building owners and residential developers drive procurement across distinct regulatory environments. National efficiency mandates and carbon reduction timelines reshape collector specifications. Manufacturing clusters concentrate where component ecosystems and export infrastructure have matured.
China
Shandong and Zhejiang provinces host the dominant manufacturing clusters for evacuated tube and flat-plate collectors. MIIT enforces updated GB standards mandating minimum optical efficiency thresholds for domestically sold products. Sunrain Group anchors cylindrical evacuated-tube production at scale across Shandong province.
Germany
Building code evolution toward heat-pump coupling mandates elevates hybrid system specifications in new construction. The F-Gas Regulation phases out refrigerant-dependent backup heating, indirectly boosting pure solar thermal procurement. Bavarian and Baden-Württemberg installers lead technical integration of collector arrays with heat pump evaporators.
Austria
Architects specify building-integrated solar thermal cladding as envelope elements rather than appended mechanical equipment. Ecodesign directives and technical standards mandate compatibility testing between collector arrays and heat pump systems. GREENoneTEC sustains manufacturing leadership through selective absorber-coating specialization.
United States
California and southwestern states drive residential water heating demand as households seek independence from gas-grid price volatility. State-level renewable thermal incentives complement federal IRA tax credits for clean energy installations. Heliodyne anchors domestic flat-plate collector assembly for commercial and institutional projects.
Spain
Mediterranean climate conditions favor cost-optimized flat-plate collector retrofits on residential rooftops. National building codes incorporate solar thermal obligations for new construction and major renovations. Andalusian and Valencian installers dominate volume deployment for cost-sensitive domestic hot water systems.
Solar Collector Panels Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement channels. The vendor base spans heating-system heritage conglomerates, cylindrical evacuated-tube scale manufacturers, and selective coating specialists. Three archetypes dominate: diversified thermal-platform providers, geography-anchored volume producers, and component-technology specialists. Capacity expansion and strategic technology licensing constitute the primary competitive moves.
Within the diversified thermal-platform tier, Bosch Thermotechnology leverages its heating-system heritage to anchor European demand for combined solar-thermal and heat-pump installations. Among geography-anchored volume producers, Sunrain Group occupies a position exemplifying Shandong province's cylindrical evacuated-tube manufacturing concentration. On the component-specialist vector, GREENoneTEC represents Austrian manufacturing leadership through selective absorber-coating technology.
| Leading Market Players |
|---|
| Bosch Thermotechnology |
| GREENoneTEC |
| Viessmann Werke |
| Solimpeks |
| Sunrain Group |
| Heliodyne |
| Apricus |
| Himin Solar |
| Vaillant Solar |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Shandong province's evacuated-tube manufacturing cluster is compressing export pricing power while forcing Zhejiang flat-plate assemblers into extended payment-term concessions to retain European distributor relationships. This utilization imbalance rewards scale producers with working-capital flexibility and punishes marginal players facing copper absorber plate cost volatility.
Pricing Analysis
Cost-plus contracts indexed to LME copper and aluminum spot prices dominate flat-plate collector procurement between Shandong manufacturers and German distributors. Pricing stratifies across premium selective-coated evacuated tubes, standard aluminum-nitride flat-plate units, and economy-grade uncoated imports for Middle Eastern retrofits. Cost compression in the economy tier is intensifying because Zhejiang exporters are absorbing tariff friction to defend container-volume commitments. Commercial installers in Germany and Austria show the least price sensitivity due to heat-pump coupling mandates, while Spanish residential retrofits exhibit acute cost consciousness.
Supply Chain Analysis
Extended payment terms stretching to 120 days are becoming standard for European distributors sourcing from Shandong and Zhejiang manufacturers, with supply-chain finance facilities bridging the liquidity gap. Component ecosystems draw from Chinese borosilicate glass tube production, Austrian selective coating specialists, and German heat-pump evaporator manufacturers. Single-source vulnerability concentrates in Shandong's cylindrical evacuated-tube capacity, where three producers account for dominant export volume. Distribution runs through HVAC wholesale channels in Germany, building-envelope specifiers in Austria, and municipal procurement frameworks in Spain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among German and Austrian building-envelope specifiers who bundle collector procurement with facade system contracts, marginalizing traditional HVAC distributors. This procurement centralization rewards platform-compatible hybrid designs and punishes standalone thermal-only suppliers.
For Market Incumbents: Pre-empt specification lockout by securing compatibility certification with Viessmann and Bosch heat-pump evaporator lines under emerging German building code technical standards. Add selective coating capacity in Austria or license GREENoneTEC's titanium-oxide multilayer technology to defend premium positioning against Chinese sputtered-aluminum-nitride cost erosion. Absorber plate backward integration into copper rolling mitigates LME price volatility exposure.
For New Entrants and Emerging Players: Establish a beachhead in Spanish residential flat-plate retrofits where cost-optimized uncoated designs face limited incumbent loyalty and municipal solar-thermal obligations create replacement-cycle visibility. Target building-integrated thermal envelope specifications in Swiss commercial projects where architect-led procurement displaces traditional HVAC channels. Lead with facade-cladding aesthetic differentiation and compatibility with Austrian envelope system suppliers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Austrian selective-coating specialists and German smart-control integration providers serving heat-pump coupling mandates. Long-term viability hinges on platform-standardization outcomes across European markets rather than standalone thermal capture scale. Monitor German building code finalization timing as the inflection signal for hybrid system architecture consolidation versus fragmented regional standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Selective Coating Technology Licensing | Austrian titanium-oxide multilayer patents command premium positioning in German cold-climate specifications. |
| Heat-Pump Compatibility Certification | Viessmann and Bosch evaporator integration unlocks specification access under evolving building codes. |
| Building-Integrated Facade Partnerships | Swiss envelope consultants bundle collector specification with cladding procurement, displacing HVAC channels. |
| Copper Absorber Backward Integration | Captive rolling capacity insulates margin structures from LME price volatility in flat-plate assembly. |
| Smart Control Platform Development | Predictive algorithms optimizing collector output against heat-pump demand capture specification premium. |
Research Methodology
Cross-validation between primary interviews with solar thermal system installers, building-envelope specifiers, and HVAC procurement managers and secondary sources including MIIT GB standard filings, EU Ecodesign directive documentation, and Shandong customs export records anchors the qualitative findings. Bottom-up triangulation against top-down manufacturer capacity assessments validates volume estimates across evacuated-tube and flat-plate product categories.
Calibration against historical replacement-cycle data and regulatory implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions span collector architecture, mounting configuration, end-user scale, and technology layer integration. CAGRs derive from fitted growth curves adjusted for heat-pump coupling mandate penetration scenarios and copper price elasticity assumptions in commercial procurement.
Stress conditions across LME metal price bands, German building code implementation pacing, and Chinese export credit availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Roof Tiles Market
Solar Power Systems
Solar Bug Zapper Market
Solar Power Systems
Solar Photovoltaic Glass Market
Solar Power Systems
Commercial Solar Panel Market
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
Malaysia Solar Energy Market
Solar Power Systems
Mexico Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
Rooftop Solar EPC Market
Solar Power Systems
Global Thin Film Solar Cells Market
Solar Power Systems
US Solar Carport Market
Solar Power Systems
Organic Solar Cells Market
Solar Power Systems
UV Solar Simulators Market
Solar Power Systems
Solar Panel Market