
 Photovoltaic (PV) Materials Market | 2026-2036
Photovoltaic (PV) Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Photovoltaic (PV) Materials Market Intelligence
The historical distinction between small-scale residential buyers and large-scale project developers is collapsing as utility-scale procurement becomes the dominant force. This shift favors suppliers with massive production capacity and integrated supply chains. HANGZHOU FIRST APPLIED MATERIAL CO.,LTD. leverages its scale in backsheets and encapsulants to serve this segment. Wacker Chemie AG sustains its position through high-purity polysilicon production, while DuPont differentiates with advanced metallization pastes and polymer materials.
Photovoltaic materials are specialized substances, including semiconductor-grade silicon and polymer encapsulants, engineered for fabricating devices that convert sunlight into electricity. Their core function is to enable efficient energy conversion within solar cells and modules. Crystalline silicon products, especially those using monocrystalline technology, command the market due to proven efficiency and reliability. The utility-scale end-user segment drives the majority of material volume, dictating specifications for large-scale deployments.
Regulatory frameworks create critical market boundaries and incentives. The EU's RoHS and REACH directives restrict the use of hazardous substances like lead and cadmium in PV modules, influencing material selection. In parallel, China's 'dual carbon goals' mandate massive solar capacity additions, directly boosting demand for all PV materials. The central challenge for material suppliers is now balancing improvements in cell efficiency and module longevity with end-of-life recyclability.
Market Dynamics
The central structural force shaping the photovoltaic materials market is the overwhelming demand concentration from utility-scale solar projects. This dynamic favors suppliers with immense production scale and deep supply chain control, reinforcing the manufacturing dominance of established Chinese industrial clusters.
Growth Catalysts
- National Energy Mandates:China's 'dual carbon goals' directly compel massive solar capacity expansion, creating sustained, high-volume demand for foundational materials like polysilicon, solar glass, and encapsulant films to meet installation targets.
- Technology Efficiency Gains:Continuous improvements in monocrystalline silicon cell efficiency and the emergence of perovskite-based tandem cells are creating requirements for advanced metallization pastes and novel transparent electrode materials.
- Utility-Scale Project Pipeline:The global expansion of large-scale solar farms provides a predictable and bankable demand channel for bulk materials, allowing suppliers to optimize production runs for backsheets, frames, and glass.
Market Restraints
- Geographic Supply Concentration:An overwhelming concentration of polysilicon, wafer, and cell production within China exposes the global supply chain to significant geopolitical risk and price manipulation, creating volatility for module assemblers elsewhere.
- Hazardous Substance Regulations:The European Union's RoHS and REACH directives restrict the use of materials like lead and cadmium, forcing costly reformulation of solder ribbons and certain thin-film compounds for suppliers targeting the EU market.
- Material Degradation Limits:The inherent long-term degradation of polymer-based encapsulants and backsheets when exposed to UV radiation and moisture limits the achievable operational lifetime and warranty periods of PV modules.
Strategic Opportunities
- Building-Integrated Photovoltaics (BIPV):The development of specialized materials for BIPV applications, such as colored or semi-transparent modules, opens a high-value architectural market distinct from traditional ground-mount and rooftop segments.
- Domestic Supply Chain Incentives:The US Inflation Reduction Act (IRA) offers significant tax credits for domestic manufacturing of PV components, creating a clear financial opportunity to establish polysilicon and wafer production in North America.
- Tandem Cell Architectures:Combining perovskite thin films with conventional silicon cells creates a pathway to efficiencies beyond the limit of single-junction devices, generating new demand for specialized interlayer and transport materials.
Industry Challenges
- End-of-Life Recyclability:Developing economically viable and scalable processes for separating and recovering high-value materials like silicon and silver from end-of-life composite modules remains a significant operational hurdle for the industry.
- Capital Expenditure Barriers:The immense capital investment and long construction timelines required to build new, world-scale polysilicon production plants act as a formidable barrier to entry for new competitors.
- Bankability of New Materials:Achieving third-party certification and bankability for novel materials, particularly for long-term degradation in perovskite cells, is a slow process that delays widespread commercial adoption by risk-averse project financiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photovoltaic (PV) Materials Market |
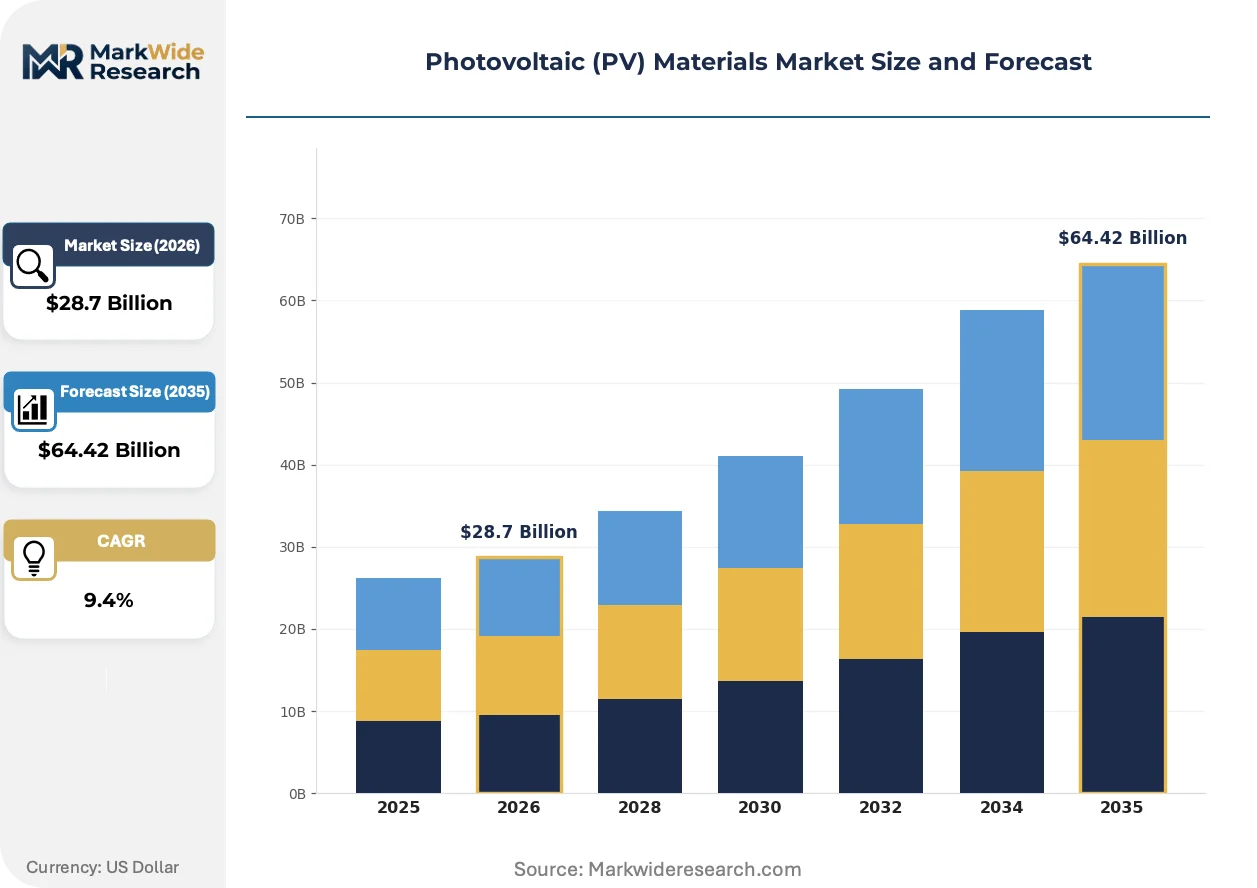
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $64.42 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-Film, Crystalline Silicon, Bifacial, Organic Photovoltaics Technology: CIGS, CdTe, Monocrystalline, Polycrystalline End User: Residential, Commercial, Utility-Scale, Industrial Installation Type: Ground-Mounted, Roof-Mounted, Building-Integrated, Floating |
| Companies Covered | DuPont, Honeywell International Inc., COVEME s.p.a., Mitsubishi Materials Corporation, Targray, HANGZHOU FIRST APPLIED MATERIAL CO.,LTD., Ferrotec Holdings Corporation, Wacker Chemie AG, Applied Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photovoltaic (PV) Materials Market Strategic Shifts & Innovations
Intensifying competition around cell efficiency and module longevity is forcing a holistic re-evaluation of every material in the photovoltaic stack. This pressure creates parallel innovation tracks, driving incremental improvements in mature silicon-based materials while accelerating research into next-generation perovskite and thin-film alternatives.
Perovskite solar cell technology offers the potential for high conversion efficiency using solution-processable methods. Research institutes and specialized startups are pioneering its use in niche applications and tandem cell development. Consequently, perovskite development is fragmenting the material supply base, creating distinct demand for novel hole transport layers, electron transport layers, and specialized encapsulants outside the traditional silicon ecosystem.
The European Union's Corporate Sustainability Reporting Directive (CSRD) imposes stringent new disclosure requirements on supply chain ethics and environmental impact. This forces material suppliers to provide verifiable data on carbon footprint, water usage, and end-of-life recyclability. The directive most directly impacts global producers of polymers, metals, and specialty chemicals, who must now invest in lifecycle assessment capabilities to retain access to European module manufacturers.
Buyer evaluation criteria are evolving from a singular focus on upfront cost-per-watt to a more sophisticated analysis of the Levelized Cost of Energy (LCOE). This shift diminishes the appeal of pure commodity material procurement and elevates the value of high-performance components like advanced anti-reflective coatings and durable, PID-resistant backsheets that boost long-term energy yield. This trend is most prominent among utility-scale asset owners in Germany and the United States.
Photovoltaic (PV) Materials Market Segmentation
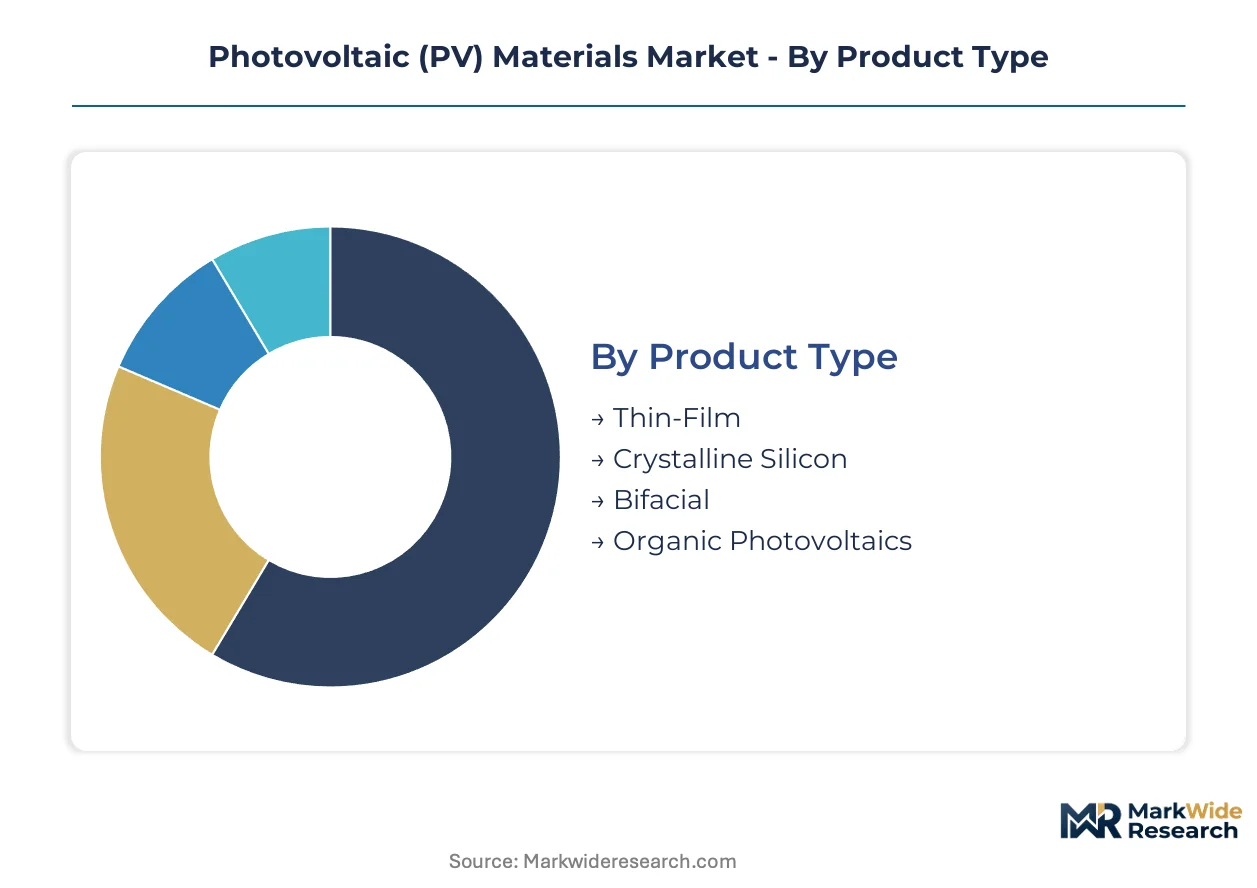
The photovoltaic (PV) materials market segments reflect the diverse requirements of solar energy generation, from foundational semiconductor elements to advanced encapsulants. Understanding these distinctions is critical for suppliers to align production with specific technological demands and end-user applications. This analysis breaks down the market by product type, technology, end user, and installation type, highlighting the unique characteristics and demand drivers within each category.
Product Type:
The geographic spread of PV material consumption often correlates with the maturity and scale of regional solar markets, influencing material specifications for domestic versus export-led module production.
- Crystalline Silicon:Crystalline silicon products, predominantly monocrystalline and polycrystalline, form the backbone of the PV materials market due to their proven efficiency and reliability. Demand for these materials is heavily concentrated in China, driven by the country's massive utility-scale solar capacity additions under its 'dual carbon goals'.
- Bifacial:Bifacial modules incorporate materials designed to capture sunlight from both front and rear surfaces, significantly increasing energy yield in ground-mounted installations. Their adoption is accelerating in arid regions like parts of the United States and India, where high albedo surfaces enhance rear-side power generation.
- Thin-Film:Thin-film materials, including amorphous silicon and cadmium telluride, offer flexibility and aesthetic advantages for specialized applications.
- Organic Photovoltaics:Organic photovoltaics utilize carbon-based compounds for light absorption, enabling lightweight and semi-transparent module designs for niche markets.
Crystalline Silicon commands the established base. The steepest expansion runs through Bifacial.
Technology:
The selection of PV technology dictates the specific material compositions and manufacturing processes, with different applications favoring distinct approaches to energy conversion.
- Monocrystalline:Monocrystalline silicon technology involves highly pure silicon ingots grown as a single crystal, offering superior efficiency and performance in PV modules. This technology is widely deployed in Germany and Japan, where high energy yields from limited land area are prioritized.
- Polycrystalline:Polycrystalline silicon cells are made from multiple silicon crystals, providing a more cost-effective alternative with slightly lower efficiency than monocrystalline. Procurement of these materials remains strong in emerging markets such as Brazil and South Africa, balancing cost and performance.
- CIGS:Copper indium gallium selenide (CIGS) thin-film cells offer high efficiency and flexibility, suitable for specialized architectural and portable power applications.
- CdTe:Cadmium telluride (CdTe) thin-film technology provides a cost-effective solution with a small carbon footprint, primarily used in large-scale utility projects in the United States.
While Polycrystalline maintains its foundational position, Monocrystalline shows the most dynamic expansion.
End User:
The volume requirements of different end-user segments significantly influence the scale of material production and the emphasis on either cost-efficiency or specialized performance attributes.
- Utility-Scale:Utility-scale projects, characterized by vast land areas and centralized power generation, drive the largest material volumes for modules, frames, and mounting structures. Demand from these projects in China and the United States dictates bulk material specifications and procurement cycles.
- Commercial:Commercial installations, typically on large rooftops or industrial sites, require durable materials suitable for diverse building types and often prioritize long-term reliability. European markets, particularly Germany and France, exhibit consistent commercial sector demand.
- Residential:Residential applications involve smaller-scale installations on individual homes, focusing on aesthetics, ease of installation, and consumer-grade durability.
- Industrial:Industrial end users, including off-grid remote power or specialized manufacturing processes, require robust and often customized PV material solutions for demanding environments.
The established demand centers on Residential, with Utility-Scale exhibiting the most rapid uptake.
Installation Type:
The maturity of various installation types shapes material choices, with established methods favoring standardized components and newer approaches demanding innovative, application-specific materials.
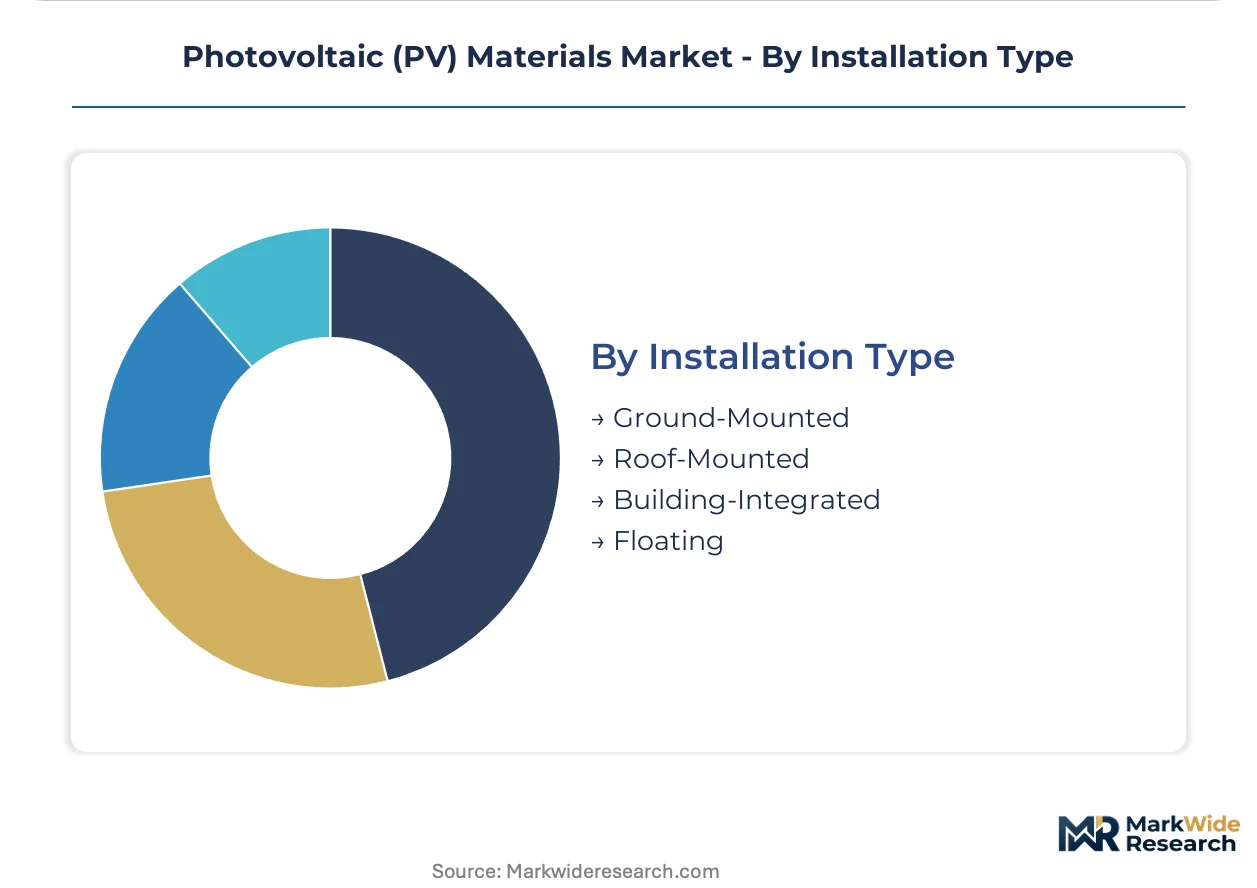
- Ground-Mounted:Ground-mounted installations represent the most mature segment, relying on robust, standardized PV materials for large-scale energy generation. These projects are prevalent in Australia and the Middle East, where land availability supports extensive solar farms.
- Building-Integrated:Building-integrated photovoltaics (BIPV) require specialized materials that serve both energy generation and architectural functions, such as aesthetic integration and structural support. European cities, particularly in Scandinavia, are increasingly adopting BIPV solutions for new constructions.
- Roof-Mounted:Roof-mounted systems, common in both residential and commercial settings, prioritize lightweight and durable materials that can withstand diverse weather conditions without compromising building integrity.
- Floating:Floating PV installations, deployed on bodies of water, necessitate highly corrosion-resistant and waterproof materials for both modules and mounting structures.
Roof-Mounted represents the core market volume, while Building-Integrated is gaining share most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dominant position in photovoltaic material production shapes global supply chains. Its vast manufacturing capacity exports foundational materials to module assemblers worldwide. This concentration influences pricing and availability across diverse international markets.
China
China's 'dual carbon goals' compel massive solar capacity expansion, creating sustained demand for foundational materials like polysilicon and glass. The government mandates directly boost material consumption to meet installation targets. Established solar manufacturing hubs across China, particularly in provinces like Xinjiang and Inner Mongolia, dominate global production and supply.
United States
The United States drives significant demand through its expanding utility-scale project pipeline. The US Inflation Reduction Act (IRA) offers substantial tax credits for domestic manufacturing of PV components. This legislation incentivizes establishing polysilicon and wafer production within North America, aiming to diversify global supply.
Germany
Germany prioritizes high energy yields from limited land area, driving demand for efficient monocrystalline silicon technology. The EU's RoHS and REACH directives restrict hazardous substances, influencing material selection for modules sold there. European markets, especially Germany, exhibit consistent commercial sector demand for durable PV materials.
Japan
Japan's market emphasizes superior efficiency and performance, particularly for monocrystalline silicon modules. National energy policies and quality standards prioritize reliable, long-lifecycle PV materials. Manufacturers in regions like Kansai continue to innovate in advanced material compositions for demanding applications.
India
India's expanding solar capacity, particularly in arid regions, accelerates adoption of bifacial modules. National solar targets and cost-efficiency considerations shape material procurement for large-scale projects. Emerging markets like India maintain strong demand for cost-effective polycrystalline silicon materials.
Photovoltaic (PV) Materials Market Key Industry Players
Player mix skews toward established chemical and materials giants alongside specialized component manufacturers. The market exhibits a tiered structure, with a few large integrated players dominating bulk material supply. Strategic archetypes include high-volume commodity producers, niche technology innovators focused on performance gains, and vertically integrated chemical companies. Firms pursue significant capacity expansion, deep supply chain control, and continuous technology differentiation to secure long-term market share.
Among the established material suppliers, HANGZHOU FIRST APPLIED MATERIAL CO.,LTD. represents a scale-driven entity leveraging its capacity in backsheets and encapsulants. Wacker Chemie AG exemplifies a high-purity specialist, sustaining its position through polysilicon production for critical applications. DuPont occupies a distinct position by differentiating with advanced metallization pastes and polymer materials, serving the high-performance segment. These companies illustrate the diverse strategies employed across the photovoltaic materials value chain.
| Leading Market Players |
|---|
| DuPont |
| Honeywell International Inc. |
| COVEME s.p.a. |
| Mitsubishi Materials Corporation |
| Targray |
| HANGZHOU FIRST APPLIED MATERIAL CO.,LTD. |
| Ferrotec Holdings Corporation |
| Wacker Chemie AG |
| Applied Materials |
| Others |
Cost & Logistics Intelligence
Project-based long-term contracts for bulk photovoltaic materials lock in both supply access and price visibility for large-scale solar developments. This structure mitigates commodity price volatility for utility-scale buyers, ensuring material availability for multi-year installation pipelines.
Pricing Analysis
The pricing gap between current-generation monocrystalline silicon cells and emerging perovskite-based tandem cell materials reflects differing maturity levels. Per-unit transactional pricing dominates for established bulk materials like silicon wafers and encapsulants. Quality grade, such as high-purity polysilicon, and certification level, like CE marking for EU markets, drive significant price differentiation. Pricing pressure stems from the immense production scale of Chinese manufacturers, driving cost compression across all material tiers. Utility-scale project developers exhibit the highest price sensitivity, constantly seeking lower Levelized Cost of Energy (LCOE) components.
Supply Chain Analysis
Inbound logistics costs, particularly for shipping large volumes of solar glass and frames from Asia, influence material delivery prices globally. Geographic supply concentration for polysilicon, wafers, and cells centers heavily in China, encompassing provinces like Xinjiang and Inner Mongolia. Raw material dependencies include high-purity quartz for silicon, specialized polymers for encapsulants, and silver for metallization pastes. Geopolitical risk, specifically related to trade policies and supply disruptions from China, represents a significant structural risk. Distribution typically runs through direct supply agreements between material manufacturers and large module assemblers or project developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The photovoltaic materials market sits at a platform-economics inflection, driven by the emergence of perovskite-silicon tandem architectures creating a new interoperability layer. This shift redefines material requirements across the entire PV stack, from electrodes to specialized encapsulants.
For Market Incumbents:Compound existing scale by investing in next-generation material R&D for tandem cell integration. This defends against the threat of efficiency gains from emerging perovskite technologies. Expand capacity in strategic regions like North America, leveraging incentives such as the US Inflation Reduction Act (IRA) to diversify supply chains. Strengthen channel control through long-term supply agreements with major utility-scale developers, ensuring stable demand for foundational silicon products.
For New Entrants and Emerging Players:Anchor in specialized material solutions for high-value niche applications, such as Building-Integrated Photovoltaics (BIPV) or transparent electrodes. Target the rapidly expanding market for perovskite-specific materials, which currently lacks established suppliers. A go-to-market angle focusing on advanced performance and sustainability credentials, particularly for EU markets under CSRD, can differentiate offerings. Focus on material innovations that address end-of-life recyclability challenges.
For Investors and Strategic Acquirers:The market sits at a growth phase that favors specialized material innovators addressing next-generation PV technologies. Long-term viability rests on material science breakthroughs that push efficiency limits or improve recyclability. Acquisition targets should include firms developing novel transport layers for perovskite cells or scalable recycling processes for composite modules. The signal to watch is the achievement of bankability for new material formulations, indicating readiness for widespread commercial adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in North America | Diversifies global polysilicon supply, reducing geopolitical risk for US module manufacturers. |
| R&D for Perovskite Interlayers | Unlocks higher conversion efficiencies for silicon tandem cells, driving next-gen module performance. |
| Investment in PV Module Recycling | Addresses end-of-life challenges, meeting regulatory demands for circular economy principles in Europe. |
| Long-term Supply Agreements | Secures stable material procurement for utility-scale project developers, ensuring project continuity. |
| Certification for BIPV Materials | Validates aesthetic and performance attributes for architectural integration, opening high-value markets. |
Research Approach
The analysis maps photovoltaic material sub-sectors, including silicon, encapsulants, and transparent electrodes, each validated through extensive primary interviews with material scientists, module manufacturers, and utility-scale project developers. This involved synthesizing insights from procurement managers and regulatory experts, triangulating data across diverse stakeholder perspectives. Secondary validation drew from national energy reports, corporate sustainability disclosures, and trade association publications, ensuring a comprehensive data foundation.
Outputs were consistently checked against external benchmarks, providing a robust forecast framework across the analysis window. Segmentation dimensions modeled included product type, technology, end-user, installation type, and specific material compositions like metallization pastes. Compound annual growth rates were derived from historical trends and projected demand, incorporating key industry-specific inputs such as national solar installation targets (e.g., China's 'dual carbon goals') and material efficiency gain roadmaps.
Material uncertainties — such as geopolitical trade tensions, rapid material science breakthroughs, or global economic downturns — sit outside the modeled envelope. Forecasts reflect assumptions documented through a rigorous validation process. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Module Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
Industrial Solar Water Heaters Market
Solar Power Systems
Residential Solar Market
Solar Power Systems
Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Flower Market
Solar Power Systems
PV Array Combiner Box Sales Market
Solar Power Systems
Solar Interconnect Ribbon Market
Solar Power Systems
Czech Republic Solar Energy Market
Solar Power Systems
Home Solar System Market
Solar Power Systems
Solar Panel Laminator Market
Solar Power Systems
Japan Solar Energy Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Solar Cullet Market
Solar Power Systems
Solar PV Backsheet Market
Solar Power Systems
Indonesia Solar Energy Market