
 Vanadium Redox Batteries Market | 2026-2036
Vanadium Redox Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Vanadium Redox Batteries Market Intelligence
The EU Green Deal is decoupling European utility procurement from fossil-peaking capacity, creating procurement pull for eight-hour-plus storage assets. Invinity Energy Systems leverages its UK-Australian manufacturing footprint to anchor utility tenders in deregulated grids. VRB Energy competes on electrolyte leasing models that reduce upfront capital barriers for renewable developers.
Vanadium redox flow batteries store electrical energy in liquid electrolytes containing vanadium ions in different oxidation states, with power and energy capacity scaled independently through stack size and electrolyte volume. The technology delivers 10,000-plus cycles without capacity fade, serving grid operators requiring four-to-twelve hour discharge duration. Flow batteries occupy the premium tier in product type segmentation where project developers prioritize cycle life over lithium-ion energy density. Energy Storage Systems lead end user demand as utilities in deregulated markets procure standalone storage under capacity payment mechanisms. Grid Storage dominates application segmentation, though Off-Grid Applications in remote mining and island grids sustain higher margin pools due to diesel displacement economics.
Japan's METI long-duration storage subsidies and South Africa's IRP procurement mandates shape product certification requirements and bankability standards for project finance. China's GB standards for flow battery safety and Australia's CEC approved product list create divergent compliance pathways that fragment vendor go-to-market strategy. Stakeholders must monitor electrolyte supply agreements and vanadium pentoxide offtake terms as tightly as cell manufacturing scale, since raw material security determines project delivery timelines and capital cost trajectories.
Market Dynamics
Long-duration storage procurement mandates from grid operators are compressing vendor qualification timelines and forcing electrolyte supply security into front-end project finance due diligence. Stack manufacturing scale and vanadium pentoxide offtake agreements now determine bankability ahead of technology differentiation.
Growth Catalysts
- EU Green Deal capacity mechanisms:European utilities must procure eight-hour-plus storage assets to replace fossil-peaking plants, creating guaranteed offtake pools for flow battery developers.
- Remote mining diesel displacement:Off-grid extraction operations in Australia and South Africa prioritize vanadium redox systems for 24-hour renewable firming over lithium-ion thermal runaway risks.
- China's dual carbon mandates:Grid modernization requirements and domestic electrolyte stack manufacturing subsidies accelerate utility-scale deployment approvals.
Market Restraints
- Vanadium pentoxide price volatility:Steel industry demand fluctuations for vanadium alloying create raw material cost instability that transfers directly to project LCOE calculations.
- Electrolyte supply concentration:High-purity vanadium processing capacity clusters in China, exposing non-Chinese developers to geopolitical supply interruption risk.
- Lithium-ion energy density advantage:Four-hour duration markets favor lithium-iron-phosphate systems where space constraints and capital cost per MWh dominate procurement scoring.
Strategic Opportunities
- Japan METI long-duration subsidies:Procurement mandates exceeding ten hours create premium pricing tiers unavailable to lithium competitors constrained by degradation economics.
- Electrolyte leasing models:Capital-light structures reduce upfront developer exposure to vanadium price swings while securing vendor recurring revenue streams.
- South Africa IRP procurement windows:Integrated Resource Plan storage allocations specify flow battery technology eligibility, bypassing technology-neutral auction competition.
Industry Challenges
- Flow battery engineering talent scarcity:Specialized electrochemical stack design and membrane optimization expertise concentrates among a limited pool of researchers with direct vanadium redox experience.
- Divergent certification pathways:China's GB safety standards, Australia's CEC approved product list, and Japan's METI certification create redundant testing costs for multi-market vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vanadium Redox Batteries Market |
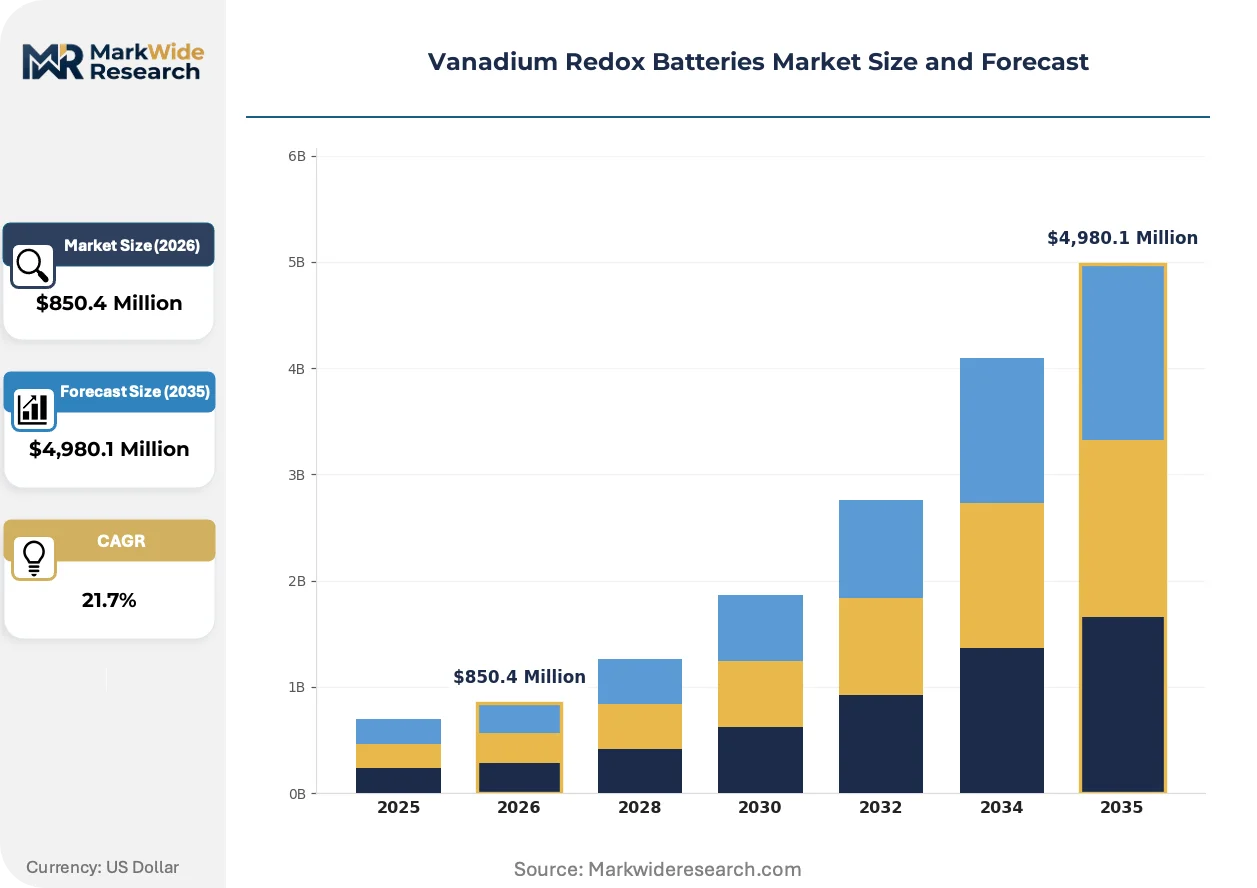
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $4,980.1 Million |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Batteries, Energy Storage Systems, Hybrid Systems, Large-Scale Installations End User: Utilities, Renewable Energy, Industrial Applications, Commercial Sector Technology: Electrolyte Optimization, Stack Design, Energy Management Systems, Control Systems Application: Grid Storage, Peak Shaving, Off-Grid Applications, Regenerative Energy |
| Companies Covered | Invinity Energy Systems, VRB Energy, Sumitomo Electric Industries, Dalian Rongke Power, UniEnergy Technologies, CellCube Energy Storage Systems, Vionx Energy, HydraRedox, StorEn Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vanadium Redox Batteries Market Strategic Shifts & Innovations
Stack architecture improvements and electrolyte formulation advances are compressing system footprint and capital intensity simultaneously. Vendor competition now centers on manufacturing scale and raw material security rather than laboratory performance metrics.
Hybrid ion-exchange membranes with enhanced proton conductivity are expanding into utility-scale deployments previously dominated by perfluorinated sulfonic acid alternatives. European stack manufacturers adopting these materials report reduced crossover rates and extended membrane replacement intervals. The technology is expanding into six-to-eight hour duration tenders where membrane longevity directly determines project IRR.
Australia's CEC approved product list now mandates thermal runaway propagation testing and electrolyte containment validation for grid-connected flow battery systems. The regulation forces non-compliant vendors into eighteen-month recertification cycles that delay project financial close. Utility procurement teams in Queensland and Victoria have integrated these standards into tender evaluation scoring, disadvantaging products certified only to Chinese GB protocols.
Buyers in deregulated markets now unbundle stack supply from electrolyte provision and long-term service agreements, forcing vendors to compete on each component separately. This disaggregation exposes margin compression in hardware manufacturing while creating annuity opportunities in electrolyte refresh and stack refurbishment. The pattern is most visible in Australian and UK utility tenders where independent power producers prioritize operational expenditure flexibility over single-source vendor relationships.
Vanadium Redox Batteries Market Segmentation
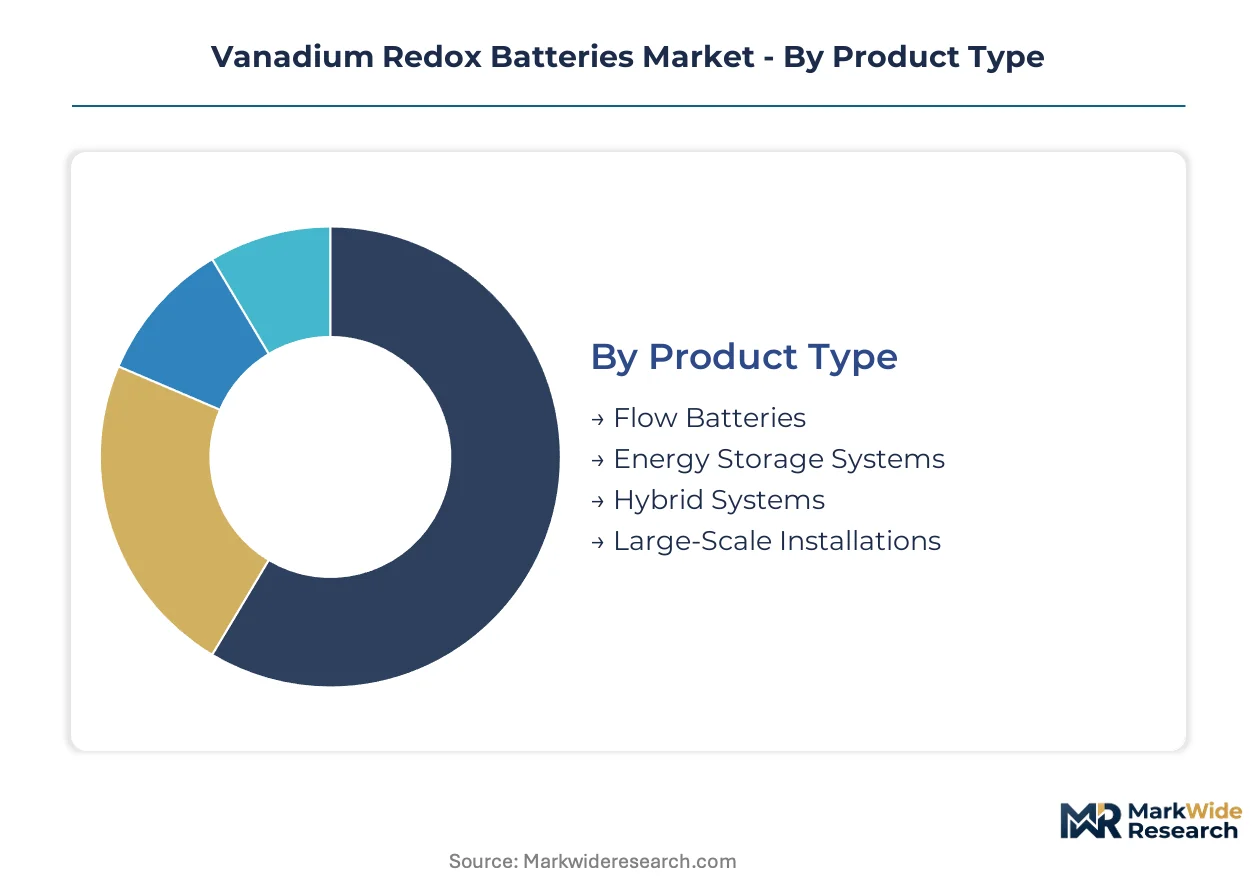
Segmentation in vanadium redox batteries reveals how capital deployment, technical specifications, and procurement channels fragment across divergent use cases. Each dimension carries distinct financing structures, certification requirements, and vendor qualification barriers that shape competitive positioning.
Product Type:
Capital intensity varies sharply across product architectures, with electrolyte volume and stack complexity driving divergent upfront investment profiles.
- Flow Batteries:Core architecture stores energy in liquid electrolytes with vanadium ions cycling between oxidation states. Power and energy scale independently through stack size and tank volume. Demand concentrates in Australian utility tenders where CEC certification and ten-thousand-plus cycle life specifications dominate procurement scoring.
- Energy Storage Systems:Integrated containerized units combine electrolyte storage, power conversion, and thermal management in factory-delivered enclosures. Japanese utilities under METI long-duration subsidies procure these for eight-hour-plus discharge requirements where lithium-ion degradation economics fail.
- Hybrid Systems:Configurations pairing vanadium redox with lithium-ion or mechanical storage for multi-duration optimization.
- Large-Scale Installations:Custom-engineered field-erected systems exceeding 100 MWh with distributed electrolyte tank farms.
Most installed capacity flows through Flow Batteries. Expansion is steepest in Energy Storage Systems.
End User:
Customer procurement sophistication determines contract structures, with utility offtake agreements offering bankable revenue streams unavailable to commercial adopters.
- Utilities:Grid operators in deregulated markets procure standalone storage under capacity payment mechanisms. South Africa's IRP mandates specify flow battery eligibility for renewable firming, bypassing technology-neutral competition.
- Renewable Energy:Solar and wind developers integrate storage to manage intermittency and secure grid connection approvals. China's dual carbon goals accelerate domestic procurement for utility-scale solar pairing.
- Industrial Applications:Mining operations and heavy manufacturing seeking diesel displacement and power quality assurance.
- Commercial Sector:Data centers, hospitals, and retail chains requiring backup power and demand charge management.
Utilities command the largest project pipelines. Renewable Energy developers are gaining share fastest as solar-wind pairing mandates spread.
Technology:
Technical differentiation now centers on manufacturing scale and materials science rather than electrochemical breakthroughs, with membrane and electrolyte advances determining project economics.
- Electrolyte Optimization:High-purity vanadium pentoxide processing and additive formulations that enhance energy density and thermal stability. Chinese GB standards for electrolyte purity create compliance thresholds for export markets.
- Stack Design:Bipolar plate geometry, membrane selection, and sealing systems that determine power density and maintenance intervals. European manufacturers adopting hybrid ion-exchange membranes report reduced vanadium crossover rates.
- Energy Management Systems:Software platforms optimizing charge-discharge cycles against electricity price signals and grid dispatch instructions.
- Control Systems:Hardware and firmware managing electrolyte flow rates, temperature, and state-of-charge balancing.
Stack Design absorbs the majority of R&D expenditure. Electrolyte Optimization is climbing the fastest as raw material security dominates vendor strategy.
Application:
Use case duration requirements and revenue mechanism availability create tiered market access, with longer discharge applications offering premium pricing unavailable to four-hour competitors.
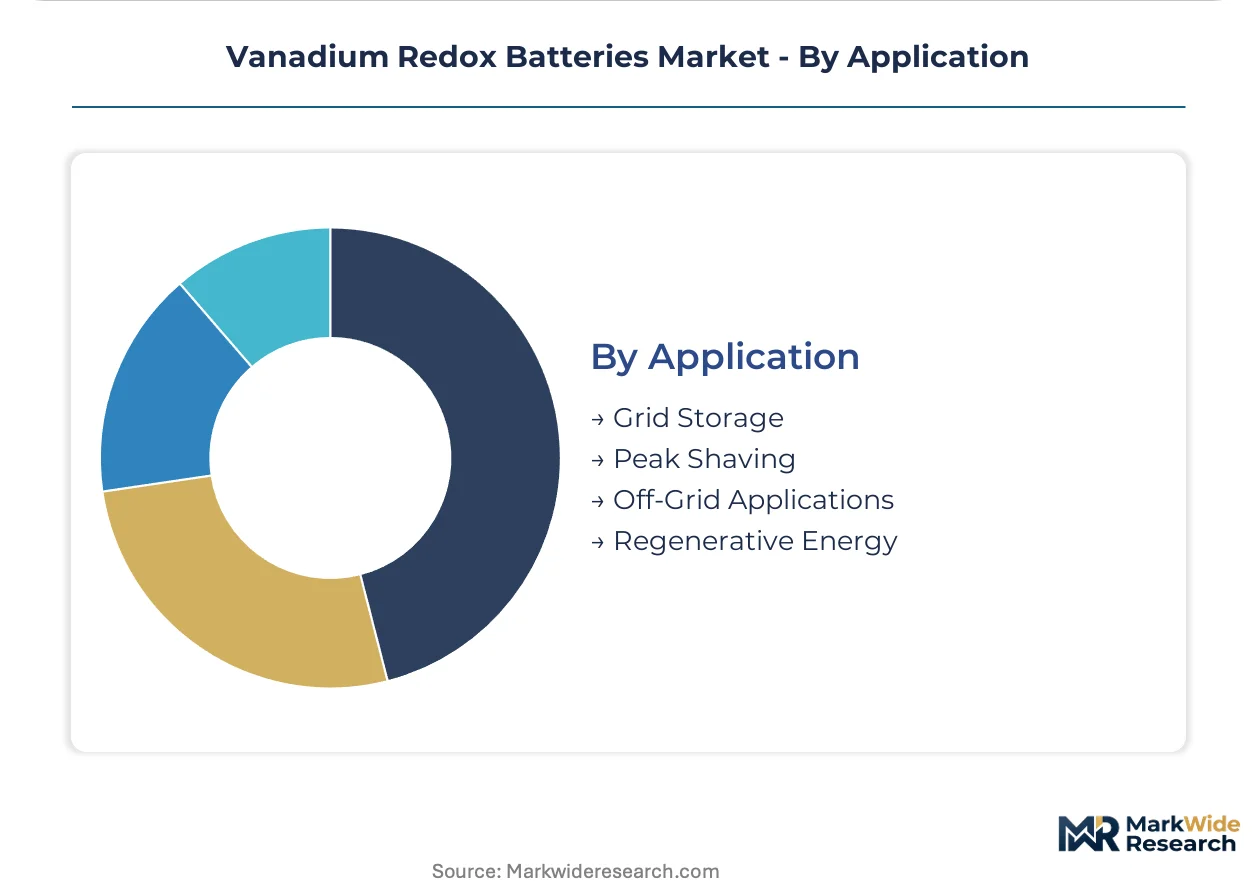
- Grid Storage:Utility-scale frequency regulation, renewable firming, and transmission deferral deployed at substations and renewable generation points. Australia's NEM capacity investment schemes and Japan's capacity market create procurement pull for six-to-twelve hour systems.
- Off-Grid Applications:Remote mining camps, island grids, and military installations where diesel displacement economics justify capital premiums. South African platinum belt operations prioritize flow batteries over lithium-ion thermal runaway risks.
- Peak Shaving:Commercial and industrial demand charge reduction through scheduled discharge during tariff peak periods.
- Regenerative Energy:Capture and reuse of braking energy in rail, port, and heavy industrial settings.
Grid Storage accounts for the dominant share of megawatt-hours deployed. Off-Grid Applications deliver the steepest margin expansion as diesel price volatility intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vanadium redox battery commercialization originated in Japan during the 1980s, with University of Sydney research subsequently scaling electrolyte chemistry for utility deployment. Manufacturing gravity now concentrates where long-duration storage procurement mandates intersect with domestic vanadium processing capacity.
China
Dual carbon mandates from MEE and MIIT accelerate grid modernization procurement across utility-scale solar pairings. GB standards for flow battery safety and electrolyte purity create compliance thresholds that domestic stack manufacturers leverage for export competitiveness. Manufacturing clusters in Dalian and Beijing-Tianjin-Hebei anchor electrolyte production scale for both domestic deployment and international project supply.
Australia
CEC approved product list mandates thermal runaway propagation testing and electrolyte containment validation for grid-connected systems. Queensland and Victoria utility procurement teams integrate these standards into tender evaluation scoring. Remote mining operations in Western Australia's Pilbara region prioritize flow batteries for diesel displacement over lithium-ion thermal risks.
Japan
METI long-duration storage subsidies exceeding ten hours create premium pricing tiers unavailable to lithium competitors constrained by degradation economics. Kanto and Kansai utilities procure integrated containerized systems for eight-hour-plus discharge requirements. Osaka-based industrial conglomerates anchor domestic stack manufacturing and membrane supply chain development.
South Africa
IRP procurement mandates specify flow battery technology eligibility for renewable firming, bypassing technology-neutral auction competition. Platinum belt mining operations in North West and Limpopo provinces prioritize vanadium redox systems for 24-hour renewable firming. Johannesburg-Pretoria industrial corridor hosts project development and engineering service concentration.
United Kingdom
EU Green Deal capacity mechanisms require utilities to procure eight-hour-plus storage assets to replace fossil-peaking plants. Deregulated grid structures in England and Wales create procurement pull for standalone storage under capacity payment mechanisms. Scottish renewable integration projects drive demand for extended-duration systems in transmission-constrained regions.
Vanadium Redox Batteries Market Key Industry Players
Capital-heavy producers compete with asset-light designers across divergent manufacturing strategies in the vanadium redox battery sector. Stack fabricators with captive electrolyte supply chains face project developers leasing vanadium content to reduce upfront capital barriers. Three archetypes dominate: integrated manufacturers controlling raw material through finished system delivery, technology licensors monetizing stack designs through royalty structures, and project developers assembling third-party components under engineering procurement construction contracts. Competitive moves concentrate on electrolyte supply security agreements and manufacturing scale expansion rather than electrochemical differentiation.
Among UK-Australian manufacturing footprint holders, Invinity Energy Systems exemplifies the integrated project developer archetype anchoring utility tenders in deregulated grids. VRB Energy occupies a position representing electrolyte leasing model innovation that reduces upfront capital barriers for renewable developers. Sumitomo Electric Industries anchors the industrial conglomerate tier with historical lineage in vanadium redox commercialization. These three entities represent divergent strategic postures: geographic arbitrage across procurement markets, capital structure innovation, and manufacturing scale depth.
| Leading Market Players |
|---|
| Invinity Energy Systems |
| VRB Energy |
| Sumitomo Electric Industries |
| Dalian Rongke Power |
| UniEnergy Technologies |
| CellCube Energy Storage Systems |
| Vionx Energy |
| HydraRedox |
| StorEn Technologies |
| Others |
Cost & Logistics Intelligence
Captive electrolyte production in China anchors both supply security and pricing power for vanadium redox battery vendors, with domestic GB standards creating compliance moats that export-oriented manufacturers leverage for premium positioning against non-integrated competitors.
Pricing Analysis
Electrolyte leasing structures dominate utility-scale procurement, separating capital expenditure into stack hardware and recurring vanadium content fees. Price differentiation rests on CEC certification tier and membrane replacement guarantee duration. Cost compression in standard-tier systems intensifies as Chinese stack manufacturers scale Dalian-Beijing production corridors. Renewable developers exhibit highest price sensitivity, while remote mining operators accept premiums for thermal runaway immunity.
Supply Chain Analysis
Regional distribution centers in Perth, Johannesburg, and Osaka manage downstream logistics for electrolyte tank farms and stack assemblies. High-purity vanadium pentoxide processing concentrates in China, with secondary refining capacity in South Africa and Russia. The chain draws from steel industry vanadium slag and direct mine output, exposing project timelines to commodity price volatility. Distribution runs through EPC contractor networks rather than direct vendor-to-utility channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in vanadium redox batteries hinges on electrolyte leasing penetration compressing customer capital barriers while securing vendor recurring revenue streams.
For Market Incumbents: Deploy captive vanadium offtake agreements to lock in raw material cost visibility against steel industry demand swings. Add stack manufacturing capacity in Australia to satisfy CEC certification proximity requirements. Lithium-iron-phosphate encroachment into four-hour duration tenders threatens pricing power in standard-tier segments. For New Entrants and Emerging Players: Hybrid ion-exchange membrane advances offer entry wedges into six-to-eight hour duration markets where perfluorinated sulfonic acid incumbents face replacement interval cost pressure. Target South African platinum belt mining operations with diesel displacement economics. Pursue electrolyte formulation partnerships with Chinese refiners to bypass capital-intensive purification infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for project developers with utility offtake pipelines because long-duration storage procurement mandates create contracted revenue visibility. Five-to-ten year viability depends on electrolyte leasing model adoption rates. Watch Japan METI subsidy renewal signals as inflection indicators for premium-tier demand durability.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Leasing Program Launch | Reduces developer capital barriers while securing vendor recurring revenue under METI and IRP tenders. |
| Backward Integration into Vanadium Refining | Captures margin from pentoxide processing and insulates project delivery timelines from steel demand volatility. |
| CEC Certification Investment | Unlocks Queensland and Victoria utility procurement scoring that disadvantages GB-only certified competitors. |
| Hybrid Membrane Manufacturing Scale-Up | Reduces crossover rates and extends replacement intervals for six-to-eight hour duration project IRR. |
| Remote Mining Partnership Expansion | Targets Western Australia Pilbara and South African platinum belt diesel displacement economics. |
Research Approach
Coverage spans China, Australia, Japan, South Africa, and the United Kingdom, with primary inputs from each market's utility planning officers, IPP project developers, EPC contractors, and electrolyte supply specialists. Secondary validation draws from EIA electricity storage databases, IEA long-duration technology roadmaps, FERC interconnection queues, and national regulator procurement disclosures. Bottom-up project pipelines triangulate against top-down capacity installation forecasts.
Segmentation granularity models product architecture, end user procurement sophistication, application duration requirements, and regional regulatory framework clusters across the projection horizon. CAGRs derive from utility tender pipeline analysis and electrolyte supply expansion trajectories. Key inputs include METI subsidy allocation schedules, IRP storage mandate timelines, and CEC certification approval cycles.
The model holds under sustained long-duration storage procurement policy support; deviation in vanadium pentoxide price volatility or lithium-iron-phosphate cost curves would shift deployment trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
US Solar Battery Market
Batteries
18650 And 21700 Battery Market
Batteries
Middle East and Africa Battery Market
Batteries
Global Cylindrical Lithium Battery Pack Market
Batteries
Lithium Starters Market
Batteries
HIT Battery Market
Batteries
Malaysia Battery Market
Batteries
South Asia Battery Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market
Batteries
India SLI Battery Market
Batteries
Li-Ion Pouch Battery Market
Batteries
Flow Battery Market
Batteries
North America NMC Battery Pack Market
Batteries
Japan Battery Market
Batteries
Indonesia and Malaysia Lead Acid Battery Market
Batteries
France Rechargeable Battery Market