
 Home Solar System Market | 2026-2036
Home Solar System Market Size, Share, and Industry Trends Forecast 2026-2036
Home Solar System Market Insights
Suburban homeowners with net-metering access is reorganizing demand away from early-adopter environmentalists. Tesla leverages its integrated energy ecosystem to control the premium installation segment. Enphase Energy sustains technology leadership through microinverter architectures. Jinko Solar anchors global module supply with manufacturing scale across Asia.
Home solar systems convert photovoltaic energy into alternating current for residential consumption, typically comprising silicon-based panels with power ratings from 300W to 700W, inverters, mounting hardware, and battery storage interfaces. Monocrystalline technology dominates efficiency benchmarks while bifacial panels capture incremental yield from rear-side irradiance. Roof-mounted installations occupy the majority of deployed capacity, though off-grid configurations represent the fastest-expanding margin pool in remote and backup-power applications.
The US Inflation Reduction Act directs EPA and Department of Energy frameworks toward residential clean-energy incentives, while California Title 24 mandates solar readiness on new construction. Germany's KBA-adjacent building codes and the EU Green Deal shape European product standards and retrofit demand. Stakeholders must monitor interconnection queue reforms and net-metering tariff revisions as these policy levers determine project economics and buyer conversion rates.
Market Dynamics
The US Inflation Reduction Act's residential tax credit extensions are restructuring buyer economics while net-metering tariff revisions in California and Texas reshape project payback calculations across suburban installations.
Growth Catalysts
- California Title 24 mandates:New construction solar readiness requirements create embedded demand in the largest US state market, locking in pre-installed infrastructure before occupancy.
- Bifacial panel architectures:Rear-side irradiance capture technology boosts yield per square meter, improving rooftop economics for space-constrained suburban homes.
- Texas interconnection reforms:Streamlined utility queue processes accelerate project commissioning timelines, reducing soft costs that previously eroded margins.
Market Restraints
- Polysilicon supply concentration:China's Xinjiang-based ingot and wafer production creates geopolitical and forced-labor compliance exposure for downstream module buyers.
- Net-metering value deflation:California's NEM 3.0 tariff structure slashes export compensation rates, compressing payback periods and buyer conversion rates.
- Permitting fragmentation:Municipal-level inspection variance across US jurisdictions adds 4-8 weeks to project timelines, inflating customer acquisition costs.
Strategic Opportunities
- Florida hurricane resilience bundling:Backup-power configurations pair solar with battery storage to capture disaster-preparedness demand in storm-exposed coastal counties.
- EU Green Deal retrofit mandates:Germany's KBA-adjacent building energy codes create replacement-cycle pull for aging rooftop systems across European housing stock.
- Direct-to-consumer financing platforms:Fintech-enabled loan origination bypasses traditional installer markup structures, capturing margin from disintermediated channel economics.
Industry Challenges
- Electrical contractor licensing bottlenecks:Master electrician certification requirements constrain installation crew scaling in high-growth Sun Belt metros.
- Module-to-inverter compatibility matrices:Rapid product iteration across vendor ecosystems complicates system design standardization and inventory planning.
- Utility interconnection study backlogs:Distribution impact assessments queue for 6-14 months in Texas and Florida, delaying revenue recognition on sold projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Solar System Market |
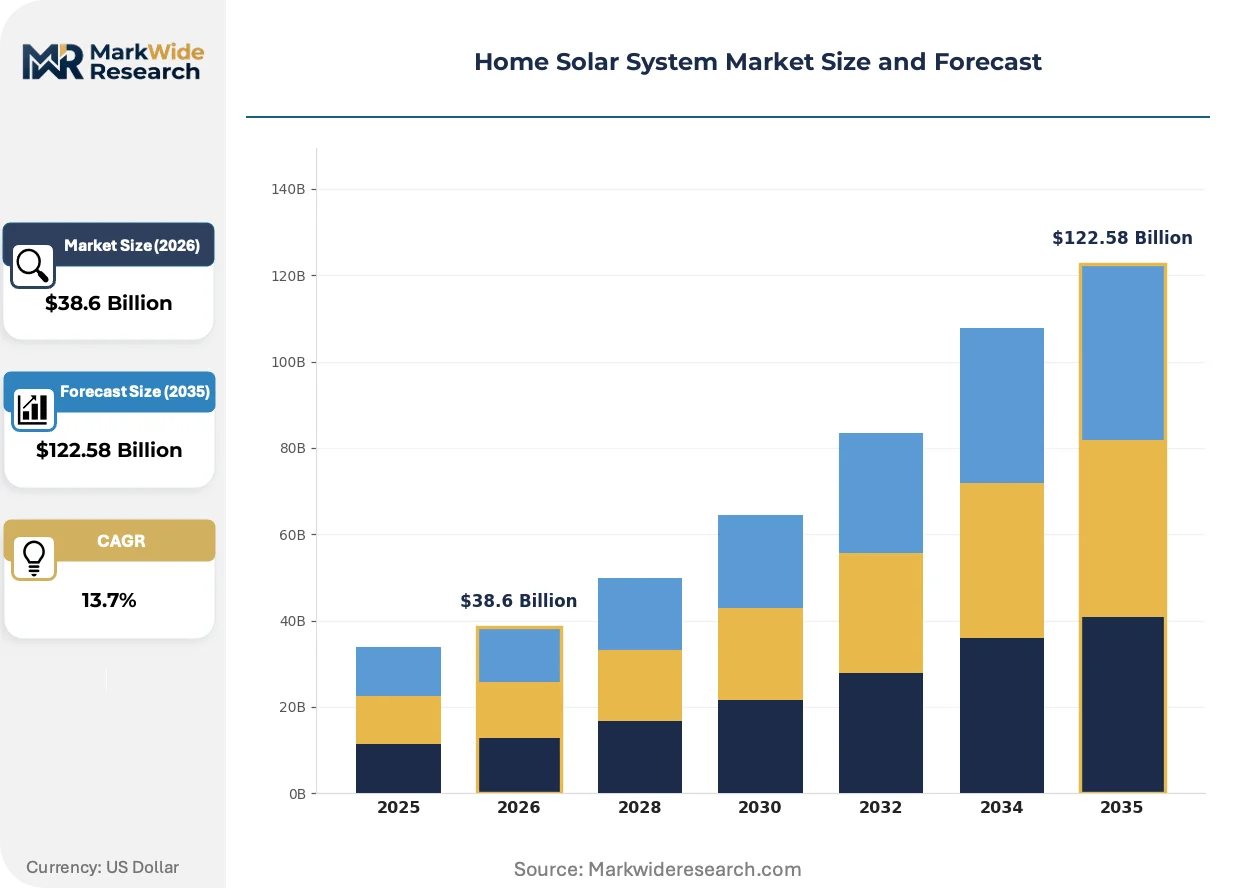
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $122.58 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roof-mounted, Ground-mounted, Hybrid, Off-grid Technology: Monocrystalline, Polycrystalline, Thin-film, Bifacial End User: Residential, Commercial, Industrial, DIY Installation Type: Standard, Custom, Pre-installed, Snap-fit |
| Companies Covered | REC, Qcells, Enphase Energy, Tesla, SolarEdge, Silfab Solar, Panasonic Holdings Corporation, Jinko Solar, Sunrun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Solar System Market Trends and Innovations
Residential solar technology is converging around integrated energy ecosystems where hardware modularity, software optimization, and financing unbundling simultaneously reshape competitive boundaries and customer acquisition economics.
Microinverter electronics are miniaturizing power conversion to the panel level, enabling module-level monitoring and rapid shutdown compliance without string inverter hardware. Suburban homeowners with complex roof geometries or partial shading now specify distributed electronics as default architecture. This shift is miniaturizing the traditional central inverter supply chain while compressing installation labor hours through plug-and-play DC cabling.
The US Inflation Reduction Act's domestic content bonus credit provisions are restructuring module procurement patterns toward North American cell and wafer sourcing. Manufacturers are reconfiguring supply contracts to capture the additional 10 percentage point credit adder for projects meeting domestic assembly thresholds. California and Texas utility-scale developers are most affected, with procurement teams now screening vendor portfolios for qualifying country-of-origin documentation.
Homeowner purchasing behavior is fragmenting across multiple acquisition channels simultaneously. National installer brands face disintermediation from regional electrical contractors offering lower customer acquisition costs and faster permitting relationships. Texas and Florida markets exhibit the most pronounced channel diversification, with online marketplace platforms capturing 15-20% of lead generation in major metros. This behavioral rotation is compressing brand loyalty while elevating price transparency and financing term competition.
Home Solar System Market Segmentation
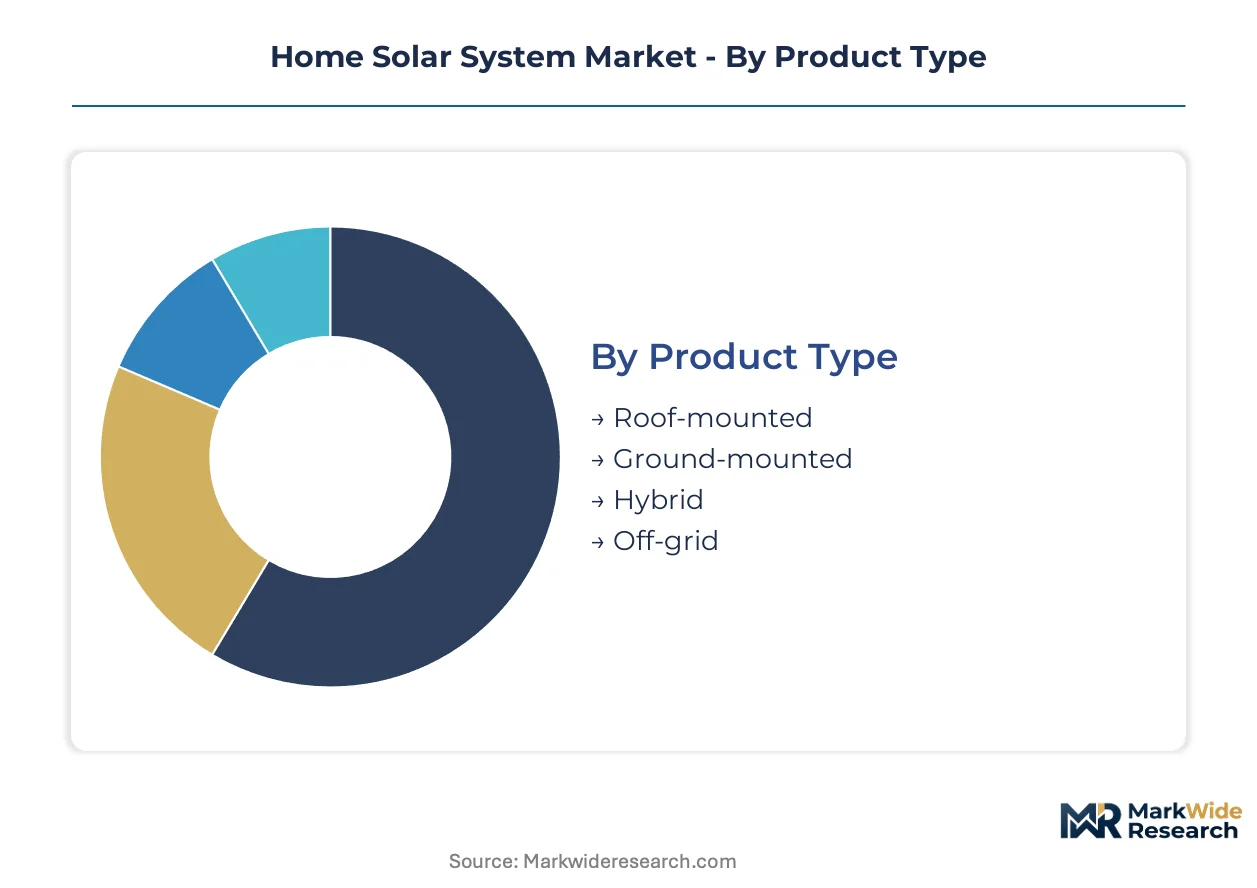
Home solar system segmentation reveals how regulatory frameworks, roof geometries, and buyer sophistication stratify demand across hardware configurations and procurement channels. Understanding these divides exposes where margin concentrates and which technology transitions reshape competitive boundaries.
Product Type:
California Title 24 mandates solar readiness on new construction, embedding infrastructure requirements before occupancy decisions occur. This regulatory architecture privileges certain mounting configurations over others.
- Roof-mounted:Silicon panel arrays affixed to residential roofing structures dominate suburban installations across California, Texas, and Florida. Net-metering access in these states drives conversion among single-family homeowners with suitable roof orientations, though NEM 3.0 tariff compression in California is slowing payback calculations.
- Ground-mounted:Elevated racking systems on dedicated land parcels serve properties with inadequate roof space or shading constraints. Rural Texas counties and Florida exurban developments favor this architecture where acreage permits optimal tilt angles and tracking mechanisms.
- Hybrid:Grid-tied configurations with battery backup interfaces capture disaster-preparedness demand in hurricane-exposed Florida coastal counties where FEMA resilience incentives apply.
- Off-grid:Standalone systems with integrated storage serve remote properties beyond utility distribution networks, climbing fastest in Texas Hill Country and California fire-prone rural zones where PSPS events drive backup power requirements.
Established volume favors roof-mounted; emerging adoption favors off-grid.
Technology:
Module efficiency benchmarks stratify procurement decisions where roof area constraints elevate watt-per-square-meter economics over upfront cost minimization.
- Monocrystalline:Single-crystal silicon ingots deliver the highest commercial conversion efficiencies, now standard in California suburban retrofits where space optimization outweighs module cost premiums. IRA domestic content bonus credits are redirecting procurement toward North American cell sourcing.
- Polycrystalline:Multi-crystal silicon structures trade efficiency for manufacturing cost advantages, retaining share in Texas price-sensitive markets where larger roof areas accommodate lower-density arrays.
- Thin-film:Cadmium telluride and CIGS chemistries enable flexible substrates and low-light performance, finding niche application in building-integrated photovoltaic retrofits subject to EU Green Deal aesthetic requirements.
- Bifacial:Dual-sided irradiance capture boosts yield per installed watt, gaining specification in ground-mounted Texas utility-scale adjacent projects and premium California rooftop designs where rear albedo reflection from light surfaces enhances output.
Monocrystalline commands margin leadership; bifacial specifications are expanding most quickly in space-constrained applications.
End User:
Buyer sophistication and financing access determine channel economics, with procurement authority fragmenting across professional installers and direct-to-consumer platforms.
- Residential:Single-family homeowners with net-metering access represent the core demand pool, concentrated in California Title 24 compliance zones and Texas deregulated retail markets where time-of-use arbitrage improves battery economics.
- Commercial:Small business and multi-tenant property owners pursue accelerated depreciation schedules under IRA commercial provisions, with Florida hospitality and retail sectors leveraging storm resilience marketing.
- Industrial:Behind-the-meter installations for manufacturing and warehousing facilities, typically exceeding residential scale thresholds and triggering utility interconnection study requirements.
- DIY:Self-directed procurement through online marketplaces bypasses installer markups, capturing 15-20% of Texas and Florida lead generation where electrical permitting pathways accommodate homeowner-managed projects.
Professional installation retains revenue concentration; DIY channels are gaining share fastest in deregulated Sun Belt metros.
Installation Type:
Project velocity and soft cost structures differentiate procurement models, with standardization reducing customer acquisition expense in high-volume markets.
- Standard:Pre-engineered system packages with uniform mounting hardware and inverter specifications minimize design labor and permitting variance, dominating California and Texas suburban tract developments.
- Custom:Architecturally integrated designs addressing complex roof geometries, historic preservation requirements, or aesthetic constraints, prevalent in European retrofit markets under KBA-adjacent building energy codes.
- Pre-installed:Builder-integrated solar readiness mandated by California Title 24 on new construction, locking infrastructure before buyer occupancy and reducing retrofit soft costs.
- Snap-fit:Modular racking and plug-and-play DC cabling systems compress installation labor hours, particularly in Texas markets where electrical contractor licensing bottlenecks constrain crew scaling.
Standard packages dominate volume economics; snap-fit configurations are expanding most quickly in labor-constrained installation markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US transmission interconnection queue reforms and Germany's KBA-adjacent building codes anchor regional demand patterns, while solar manufacturing scale concentrates supply-side investment in China and Southeast Asia.
United States
Suburban net-metering access and hurricane resilience bundling drive adoption across Sun Belt metros. The Inflation Reduction Act's residential tax credit extensions restructure buyer economics through EPA and Department of Energy frameworks. California's Title 24 mandates solar readiness on new construction in Los Angeles and San Diego counties, embedding infrastructure before occupancy.
Germany
Retrofit replacement cycles and EU Green Deal building energy standards accelerate aging system upgrades. The KBA-adjacent building codes shape product specifications and aesthetic requirements for rooftop installations. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate installer networks and distribution logistics for European housing stock.
China
Polysilicon ingot and wafer manufacturing scale dominates upstream supply, with Xinjiang-based production creating compliance exposure for downstream buyers. The MIIT dual carbon goals and GB standards shape module efficiency benchmarks and export certification requirements. Yangtze River Delta manufacturing hubs in Jiangsu and Zhejiang provinces anchor cell and module assembly capacity.
Australia
High retail electricity tariffs and abundant solar irradiance compress payback periods for residential installations. The Clean Energy Council accreditation framework and state-level feed-in tariff structures shape installer qualification requirements. Sydney and Melbourne metropolitan markets concentrate demand for premium monocrystalline systems with battery storage interfaces.
India
Rooftop solar targets under the national solar mission and state-level net-metering policies drive urban adoption. The CEA grid interconnection standards and BIS module certification requirements shape product eligibility for subsidy programs. Maharashtra and Gujarat industrial corridors concentrate manufacturing investment and installer network development.
Home Solar System Market Competitive Landscape
Listed leaders compete with private specialists across financing and installation channels, creating a tiered structure where technology vendors, financing platforms, and integrated energy providers occupy distinct competitive positions. The vendor base segments into module manufacturers, inverter electronics specialists, and downstream installation platforms. Three archetypes dominate: silicon-based panel producers with manufacturing scale, microinverter technology licensors with distributed electronics architectures, and vertically integrated energy ecosystem providers with captive financing. Competitive moves concentrate on domestic content bonus credit capture and direct-to-consumer channel expansion.
Among technology-integrated providers, Tesla and Enphase Energy exemplify divergent approaches to residential energy ecosystem control. Tesla occupies a position emphasizing vertical integration across generation, storage, and vehicle charging interfaces. Enphase Energy represents the distributed electronics archetype through panel-level power conversion architectures. Jinko Solar anchors the manufacturing-scale tier among Chinese module producers with global supply contract penetration.
| Leading Market Players |
|---|
| REC |
| Qcells |
| Enphase Energy |
| Tesla |
| SolarEdge |
| Silfab Solar |
| Panasonic Holdings Corporation |
| Jinko Solar |
| Sunrun |
| Others |
Pricing and Supply Chain Analysis
IRA domestic content bonus credit provisions gate both module qualification and price differentiation simultaneously, rewarding North American cell sourcing with additional credit adders while compressing margins on non-qualifying imports. This certification-linked pricing architecture reshapes procurement patterns across California and Texas utility-scale adjacent residential projects.
Pricing Analysis
Volume-discount tiering structures separate premium monocrystalline systems with battery integration from standard rooftop packages and economy-grade polycrystalline configurations. Price differentiation rests on module efficiency ratings and UL certification tiers, with California buyers least sensitive due to Title 24 mandates while Texas price-sensitive markets drive cost compression. Margins are tightening in the standard tier due to installer channel fragmentation and online marketplace price transparency.
Supply Chain Analysis
China and Southeast Asia anchor polysilicon ingot, wafer, and cell manufacturing, with Xinjiang-based production creating forced-labor compliance exposure for downstream buyers. Module assembly draws from silver paste, aluminum framing, and tempered glass inputs. Single-source vulnerability concentrates in Xinjiang polysilicon purification. Distribution runs through national installer networks, regional electrical contractors, and emerging direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid-connected home solar faces substitution pressure from community solar subscriptions and utility-scale green tariff programs that bypass rooftop installation entirely. Incumbents must defend against this bypass threat through ecosystem stickiness.
For Market Incumbents: Fortify customer retention by embedding battery storage and vehicle charging interfaces into integrated energy ecosystems. Deepen backward integration into North American module assembly to capture IRA domestic content bonus credits. Counter community solar substitution with net-metering optimization software that maximizes homeowner arbitrage value.
For New Entrants and Emerging Players: Lead with direct-to-consumer financing platforms that bypass traditional installer markup structures in Texas and Florida deregulated markets. Target DIY-permissive jurisdictions where electrical permitting accommodates homeowner-managed projects. Deploy fintech-enabled loan origination with instant approval algorithms to capture disintermediated channel economics.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across snap-fit modular installation systems that compress labor hours and reduce crew scaling constraints. Long-term viability favors technology-integrated providers with software optimization layers over pure hardware manufacturers. Monitor interconnection queue reform legislation as the inflection signal for project velocity acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into North American Cell Sourcing | Captures IRA domestic content bonus credits qualifying projects for additional incentive adders. |
| Battery Storage Ecosystem Integration | Creates stickiness against community solar substitution through backup power value proposition. |
| Direct-to-Consumer Financing Platform Launch | Bypasses installer markups in Texas and Florida markets with 15-20% online lead generation. |
| Snap-Fit Modular Installation System Deployment | Compresses labor hours where electrical contractor licensing bottlenecks constrain crew scaling. |
| Net-Metering Optimization Software Development | Maximizes homeowner arbitrage value under California NEM 3.0 tariff compression. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across residential installer networks, module procurement teams, utility interconnection planners, and fintech lending platforms. Secondary validation drew from EIA solar deployment data, FERC interconnection filings, IRA implementation guidance from EPA and Department of Energy, and state-level net-metering tariff dockets. Bottom-up project pipeline aggregation triangulated against top-down capacity forecasts.
Across the analysis window, the forecasting framework modeled technology type, installation configuration, end-user segment, and regional regulatory cluster dimensions. CAGRs were derived from installed capacity trajectories and average selling price evolution. Key inputs included interconnection queue reform timelines, net-metering tariff revision schedules, and domestic content bonus credit qualification thresholds.
Forecasts assume regulatory continuity in IRA credit provisions and California Title 24 mandates; material policy shifts would require re-modeling. Module supply disruption from forced-labor enforcement or tariff escalation represents primary forecast revision risk. Recalibration cycles align with material shifts in interconnection reform legislation and net-metering tariff structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Israel Solar Energy Market
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
Solar Backsheet Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
IBC Solar Cells Market
Solar Power Systems
Europe Solar Backsheet Market
Solar Power Systems
South America Solar Tracker Market
Solar Power Systems
Australia Solar Market
Solar Power Systems
Solar Crimp Set Market
Solar Power Systems
Residential Solar Inverter Market
Solar Power Systems
Photovoltaic Mounting System Market
Solar Power Systems
Solar Power Market
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
Boat Solar Panel Market
Solar Power Systems
Malaysia Solar Energy Market
Solar Power Systems
Solar Power Manager Market