
 Global Energy Consumption Market | 2026-2036
Global Energy Consumption Market Size, Share, and Industry Trends Forecast 2026-2036
Global Energy Consumption Market Intelligence
The Paris Agreement's framework for national emissions reduction targets is hardening the imperative for a transition away from fossil fuels. Schneider Electric SE leverages its expertise in digital energy management to help commercial clients optimize consumption. Traditional producers like Saudi Aramco sustain their market position through massive scale in hydrocarbon extraction and refining. Siemens AG competes by developing grid infrastructure technologies essential for integrating renewable energy sources.
Energy consumption refers to the total amount of energy used by an end user, measured in units such as joules or kilowatt-hours (kWh). Its primary function is to power economic activity, from industrial processes and transportation to residential heating and lighting. In the end user sector, industrial applications represent the largest demand, while transportation shows significant shifts in its energy source mix. Consumption modes are diversifying, with electricity gaining share over direct liquid fuels for heating and mechanical power.
Frameworks from the US EPA on emissions and China's MEE, via its dual carbon goals, directly influence the viability of different energy sources. The EU's F-Gas Regulation similarly shapes technology choices for heating and cooling, impacting overall electricity demand. Stakeholders must now decide capital allocation between legacy fossil fuel infrastructure and new investments in renewable capacity and grid modernization.
Market Dynamics
The central dynamic shaping energy consumption is the global policy push for decarbonization clashing with the foundational energy requirements of industrial economies. This creates a powerful tension between transitioning to low-carbon sources and maintaining the energy security needed for manufacturing, transportation, and economic growth.
Growth Catalysts
- Policy Mandates:The EU Green Deal and its associated emissions reduction targets are compelling member states to accelerate investments in renewable energy infrastructure and energy efficiency measures across industrial and residential sectors.
- Technology Advancement:Improvements in battery energy storage systems enhance grid stability, enabling higher penetration of intermittent renewable sources like solar and wind by storing excess power for periods of low generation.
- Industrial Electrification:A demand-side shift toward electrifying industrial processes, such as process heat in manufacturing, is expanding the overall market for electricity as a primary energy vector, replacing direct fossil fuel combustion.
Market Restraints
- Capital Intensity:The immense capital expenditure required for modernizing aging grid infrastructure to accommodate distributed energy resources and handle increased electricity loads acts as a significant barrier to rapid transition.
- Supply Chain Bottlenecks:Geopolitical concentration in the mining and processing of critical minerals like lithium, cobalt, and rare earth elements creates supply chain vulnerabilities and price volatility for renewable energy and battery technologies.
- Technical Intermittency:The inherent variability of solar and wind power generation presents a structural challenge to maintaining grid reliability and requires substantial investment in backup capacity or large-scale energy storage solutions.
Strategic Opportunities
- Green Hydrogen Production:The development of a green hydrogen economy presents a major opportunity, positioning large-scale electrolysis facilities as a significant new category of electricity consumers that can also help balance grid loads.
- Emerging Economies:Electrification initiatives in developing regions, particularly in Southeast Asia and sub-Saharan Africa, offer vast white space for deploying both grid-scale and decentralized renewable energy solutions to power economic development.
- Regulatory Incentives:Policy frameworks like the US Inflation Reduction Act (IRA) create powerful financial incentives for the deployment of clean energy technologies, battery storage, and electric vehicles, stimulating domestic consumption.
Industry Challenges
- Specialized Labor Shortages:A widening skills gap exists for technicians and engineers qualified to design, install, and maintain advanced smart grid systems, utility-scale solar farms, and offshore wind turbines, slowing project execution.
- Grid Integration Complexity:Integrating a high volume of decentralized energy resources, including rooftop solar and electric vehicle charging stations, into legacy grid management systems poses significant technical and operational challenges for utility operators.
- Lengthy Permitting Cycles:Protracted timelines for securing regulatory approvals and permits for major energy infrastructure projects, such as new high-voltage transmission lines, create significant delays and increase project development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Energy Consumption Market |
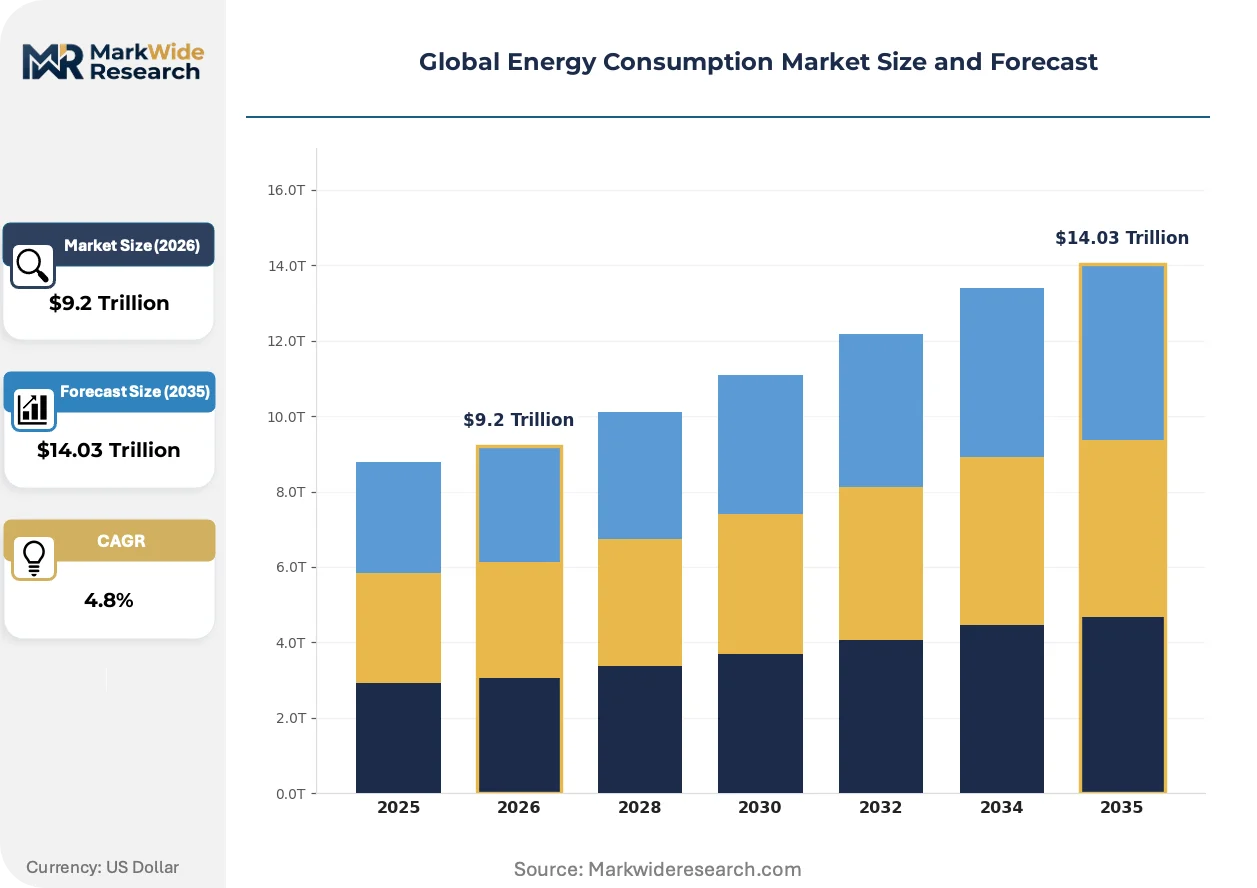
| Market Size in 2026 | $9.2 Trillion |
| Market Size in 2035 | $14.03 Trillion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Coal, Natural Gas, Nuclear, Hydroelectric, Biomass, Geothermal End User Sector: Residential, Commercial, Transportation, Agriculture, Public Services, Mining Consumption Mode: Electricity, Heating, Cooling, Mechanical Power, Lighting, Cooking Distribution Channel: Direct Grid Supply, Liquid Fuels, Compressed Gas, Off-Grid Solutions, Energy Storage, District Heating |
| Companies Covered | Schneider Electric SE, Siemens AG, ABB Ltd., General Electric Company, Honeywell International Inc., Saudi Aramco, ExxonMobil, Chevron Corporation, Shell plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Energy Consumption Market Strategic Shifts & Innovations
Digitalization and decentralization are fundamentally altering the energy landscape. The market is moving away from a unidirectional model of centralized generation toward a more dynamic, multi-directional ecosystem where consumers also act as producers and grid participants, managed by intelligent software platforms.
Artificial intelligence in energy management systems provides the core capability for real-time optimization. Commercial and industrial facilities are the primary adopters, using these platforms to automate responses to price signals and grid conditions. This technology is absorbing the immense complexity of balancing variable renewable energy sources with fluctuating demand, enabling more efficient and resilient power consumption patterns.
China's "dual carbon" policy framework is a powerful regulatory driver for market transformation. This national strategy compels a rapid build-out of renewable generation capacity and mandates stringent energy efficiency upgrades across carbon-intensive sectors. The country's power generation, steel, and cement industries are most directly affected, forcing a strategic pivot toward investments in solar, wind, and nuclear power.
Corporate energy procurement is evolving as large enterprises increasingly sign direct Power Purchase Agreements (PPAs) with renewable energy project developers. This model bypasses traditional utility contracts, creating a direct financial link between clean energy producers and major consumers. This trend is most visible within the data center and technology sectors in North America and Europe, driven by corporate sustainability commitments.
Global Energy Consumption Market Segmentation
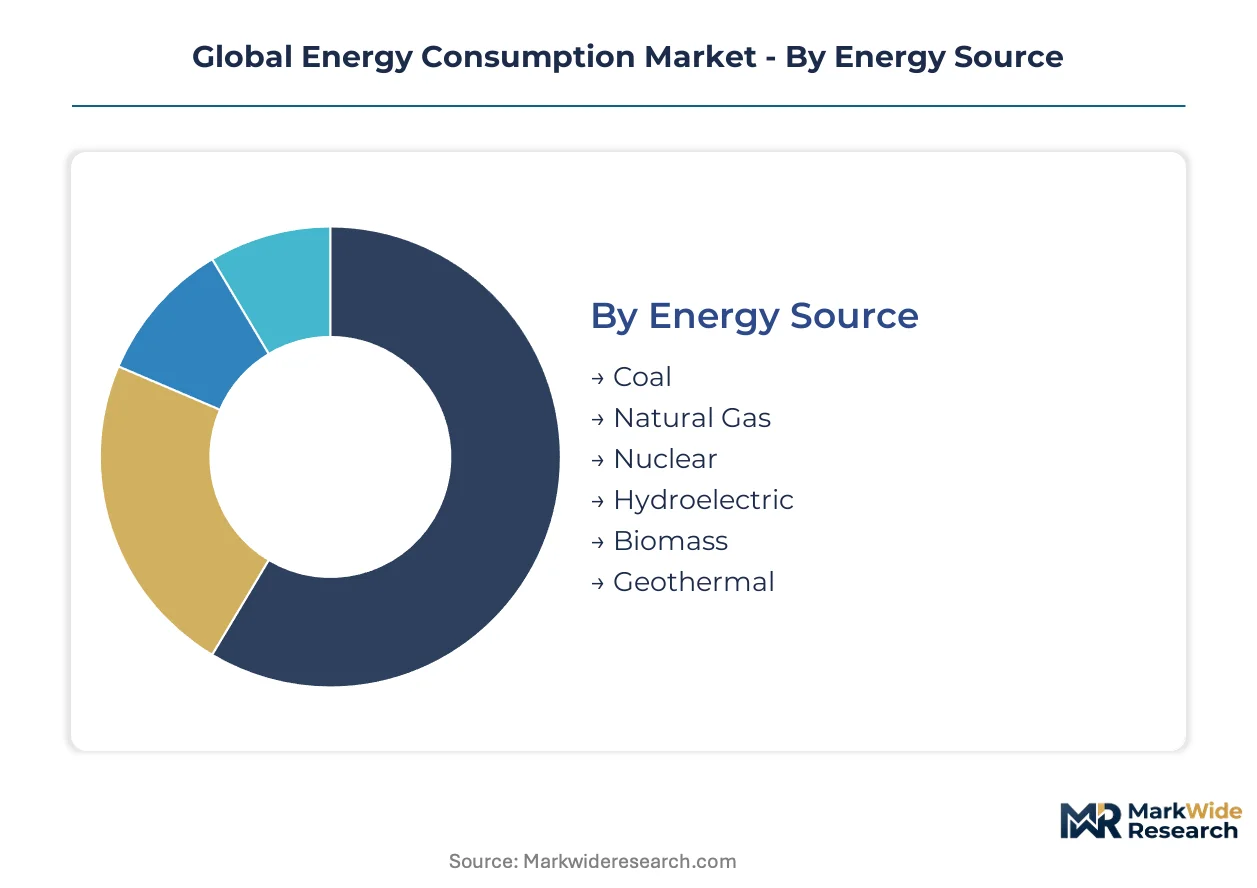
The Global Energy Consumption Market's structure reflects diverse energy sources, varied end-user demands, and evolving consumption patterns. Understanding these segments provides critical insights into capital allocation decisions and strategic investment priorities across the energy value chain. This segmentation highlights where technological advancements and policy directives exert the most influence.
Energy Source:
Energy sources delineate the primary technologies and raw materials used to generate power, each possessing distinct technical characteristics and environmental footprints. This classification is fundamental for assessing resource availability and decarbonization pathways.
- Coal:This fossil fuel remains a dominant energy source globally, primarily due to its abundance and established infrastructure for power generation in industrial economies. Demand concentration is particularly pronounced in China's industrial sector, where it provides massive energy inputs for manufacturing processes.
- Natural Gas:Comprising methane, this hydrocarbon offers a cleaner-burning alternative to coal, often serving as a bridge fuel in the energy transition due to its operational flexibility. Its consumption is concentrated in power generation and industrial heating across Europe, driven by grid stability requirements and emissions targets.
- Nuclear:Fission-based power generation provides stable, low-carbon electricity, offering grid reliability in countries like France.
- Hydroelectric:Utilizing water flow to generate electricity, this renewable source offers significant baseload capacity in regions with abundant water resources, such as Norway.
- Biomass:Organic matter converted into energy, biomass provides dispatchable renewable power, particularly in Scandinavia for heating and electricity.
- Geothermal:Extracting heat from the Earth's interior, geothermal power offers continuous renewable energy, notably in Iceland and New Zealand.
Coal leads on scale; Biomass leads on momentum.
End User Sector:
End-user sectors categorize energy consumption based on the primary application and economic activity where energy is utilized. This segmentation highlights the diverse operational requirements influencing energy demand and infrastructure needs.
- Transportation:This sector consumes significant energy for moving people and goods, undergoing a rapid electrification shift from liquid fuels to electricity for vehicles. Demand concentration is high in urban centers globally, driven by personal mobility needs and commercial logistics requiring efficient energy solutions.
- Mining:Energy consumption in mining operations supports extraction, processing, and transportation of raw materials, requiring substantial mechanical power and heating. Activity is concentrated in resource-rich regions like Australia and South Africa, driven by global commodity demand and large-scale industrial processes.
- Residential:Households consume energy primarily for heating, cooling, lighting, and appliances, influenced by population growth and energy efficiency standards.
- Commercial:Businesses and institutions utilize energy for office buildings, retail spaces, and data centers, with electricity demand growing due to digitalization.
- Agriculture:This sector uses energy for irrigation, machinery, and climate control in farming, often relying on liquid fuels and electricity.
- Public Services:Government facilities, healthcare, and education consume energy for operations, influenced by public infrastructure development and service delivery.
Transportation shows the steepest expansion trajectory, while Residential represents a foundational demand base.
Consumption Mode:
Consumption modes describe the specific forms in which energy is delivered and utilized by end-users, reflecting the functional purpose of energy application. This classification highlights the evolving preferences and technological shifts in how energy powers activities.
- Electricity:This versatile energy vector powers a vast array of devices and processes, increasingly displacing direct fossil fuel combustion in many applications. Its consumption is concentrating in industrial electrification and transportation, driven by decarbonization policies and technological advancements in electric vehicles.
- Heating:Energy for space heating and process heat constitutes a significant portion of global energy demand, undergoing a transition towards electric and renewable sources. Demand remains highest in colder climates like Northern Europe, influenced by building efficiency standards and fuel switching initiatives.
- Cooling:Energy used for air conditioning and refrigeration is expanding, particularly in warmer climates such as Southeast Asia, driven by urbanization.
- Mechanical Power:Direct energy application for industrial motors and machinery represents substantial demand, often powered by electricity or liquid fuels.
- Lighting:Essential for visibility and safety, lighting demand is increasingly met by energy-efficient LED technologies across all sectors.
- Cooking:Energy for food preparation is a fundamental household demand, transitioning from traditional biomass to cleaner fuels and electricity in developing regions.
Electricity is displacing other modes, while Cooling is expanding quickly in specific geographies.
Distribution Channel:
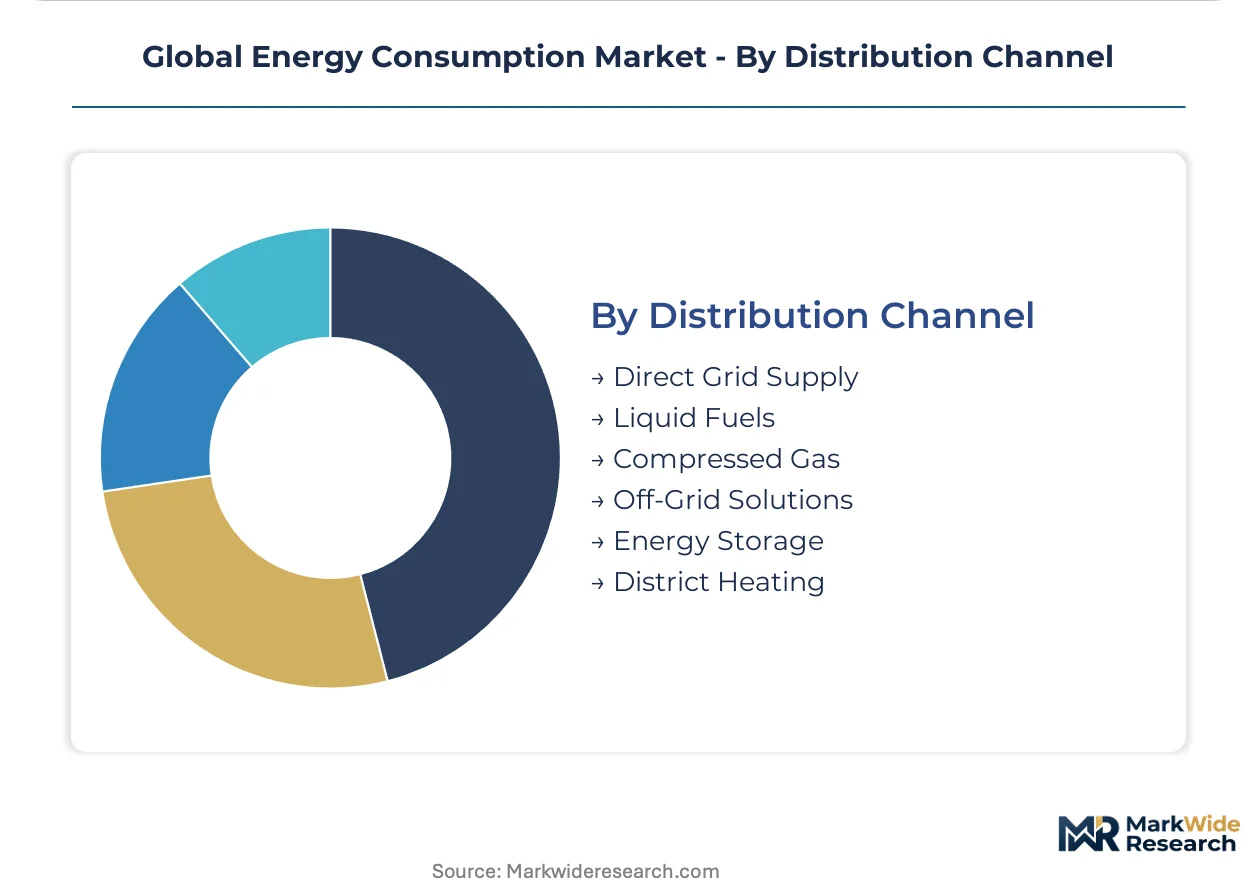
Distribution channels define the primary pathways through which energy reaches end-users, illustrating the infrastructure and logistical frameworks supporting energy delivery. This segmentation reflects the maturity and evolving decentralization of energy systems.
- Direct Grid Supply:Centralized electricity generation transmitted through national and regional grids remains the backbone of modern energy infrastructure, serving most urban and industrial loads. Its reach is concentrated in developed economies like Germany and Japan, where grid modernization efforts integrate diverse generation sources.
- Liquid Fuels:Petroleum products distributed via pipelines, tankers, and retail networks primarily serve the transportation sector and some industrial applications. Distribution is globally ubiquitous, but demand is particularly high in the US and India, supporting vast vehicle fleets and industrial machinery.
- Compressed Gas:Natural gas delivered via pipelines and specialized transport provides energy for heating, power generation, and industrial processes, especially in Europe.
- Off-Grid Solutions:Decentralized energy systems, including standalone solar and battery setups, provide power to remote areas and enhance resilience, particularly in sub-Saharan Africa.
- Energy Storage:Technologies like batteries and pumped hydro enable intermittent renewable energy to be stored and dispatched, crucial for grid stability in Australia.
- District Heating:Centralized heat production distributed through insulated pipe networks serves multiple buildings, common in Scandinavian cities like Copenhagen.
Direct Grid Supply constitutes the largest established channel, while Energy Storage is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A concentration of skilled engineers and energy policy experts anchors the Global Energy Consumption Market. This market expands through significant industrial electrification and robust renewable energy integration. Policy mandates and technological advancements distinctly shape regional energy landscapes and investment priorities.
China
China's vast industrial and manufacturing hubs drive immense energy consumption. The country's MEE, through its dual carbon goals, mandates rapid renewable capacity build-out. Industrial centers like the Yangtze River Delta are pivoting toward solar, wind, and nuclear power investments.
United States
Transportation electrification and expanding industrial processes propel energy demand across the United States. The US Inflation Reduction Act (IRA) creates financial incentives for clean energy technology deployment. States like California and Texas see significant investments in renewable capacity and grid modernization.
Germany
Germany's advanced industrial base demands substantial energy for manufacturing and heating. The EU Green Deal mandates accelerate investments in renewable energy infrastructure and efficiency measures. The Ruhr Valley and Bavaria integrate diverse generation sources and upgrade grid infrastructure.
Saudi Arabia
Saudi Arabia sustains its market position through massive hydrocarbon extraction and refining operations. The nation's energy diversification strategies balance traditional production with new renewable capacity. The Eastern Province remains central to both oil production and emerging solar projects.
India
India's rapid urbanization and industrial growth drive significant energy consumption across diverse sectors. Government policies supporting infrastructure development contribute to rising electricity and fuel demands. Economic hubs like Delhi-NCR and Maharashtra experience shifts in energy source mix for transportation and industrial use.
Global Energy Consumption Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the Global Energy Consumption Market. The market exhibits a tiered structure, from large integrated energy companies controlling vast resources to specialized technology providers. Strategic archetypes include traditional resource holders and digital energy management solution developers. Dominant competitive moves involve portfolio diversification and strategic partnerships to integrate new energy technologies and expand market reach.
Within the traditional resource holder archetype, Saudi Aramco anchors a significant portion of global hydrocarbon extraction and refining capacity. This company exemplifies the scale-driven approach to maintaining energy supply. Digital energy management solution developers like Schneider Electric SE represent a focus on optimizing consumption through advanced software platforms and efficiency solutions for commercial clients. German-based Siemens AG occupies a position in developing grid infrastructure technologies essential for integrating diverse renewable energy sources and managing complex power flows.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Siemens AG |
| ABB Ltd. |
| General Electric Company |
| Honeywell International Inc. |
| Saudi Aramco |
| ExxonMobil |
| Chevron Corporation |
| Shell plc |
| Others |
Cost & Logistics Intelligence
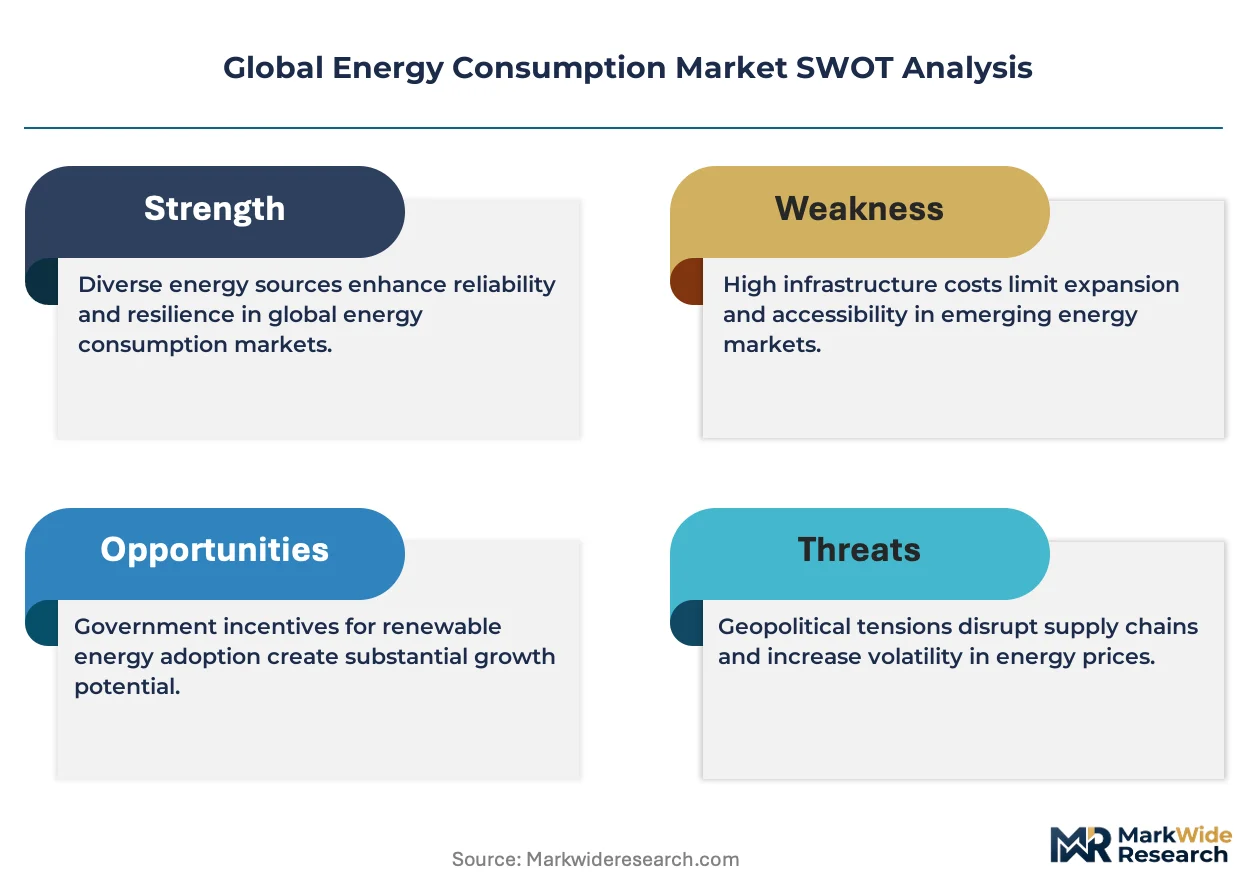
The bifurcation between established fossil fuel infrastructure and nascent renewable energy technologies dictates distinct pricing mechanisms and supply chain structures. This divergence manifests in how energy is valued and the logistical frameworks supporting its delivery to end-users.
Pricing Analysis
Bundled energy management solutions versus unbundled commodity power sales create distinct pricing models. Long-term Power Purchase Agreements (PPAs) dominate renewable energy procurement, while traditional sources often trade on commodity spot markets, with price differentiation stemming from a source's grid stability contribution and its inherent carbon intensity. Cost compression in renewable energy technologies is intensifying due to manufacturing scale. Residential consumers exhibit the highest price sensitivity, whereas large industrial clients prioritize supply reliability over marginal cost.
Supply Chain Analysis
Certification and qualification standards for grid components and energy sources significantly influence supply chain access. Geographic supply concentrates in China for critical minerals and solar components, while Saudi Arabia anchors global hydrocarbon extraction. Raw material dependencies include lithium, cobalt, and rare earth elements for battery technologies. Geopolitical concentration in critical minerals presents a structural risk for renewable energy expansion, while direct grid supply remains the dominant distribution model for electricity, complemented by extensive liquid fuel and gas pipeline networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Energy Consumption Market operates as a regulatory compounder, where policy frameworks like the EU Green Deal consistently accelerate demand for low-carbon solutions. This regulatory impetus drives substantial investment in renewable capacity and energy efficiency across member states.
For Market Incumbents: Extend core competencies into adjacent low-carbon technologies to mitigate fossil fuel asset stranding. Diversify portfolios into green hydrogen production and invest in grid modernization technologies to counter the threat of decarbonization mandates. Form strategic partnerships with technology developers to leverage new energy solutions. Capacity additions in advanced energy storage further reinforce market position.
For New Entrants and Emerging Players: The US Inflation Reduction Act (IRA) in the United States opens a window for specialized clean energy technology providers. Target white space in decentralized renewable solutions for off-grid applications and advanced smart grid integration software. Emerging economies, particularly in sub-Saharan Africa, represent the most penetrable segments for deploying grid-scale and decentralized solutions. Adopt outcome-based service models to demonstrate tangible efficiency gains for commercial clients.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented technology landscapes meet capital-intensive infrastructure requirements. Long-term viability remains strong for entities enabling the energy transition, particularly those with proven grid integration capabilities. Target acquisition archetypes include specialized software platforms for energy management and critical mineral processing companies. The acceleration of Power Purchase Agreement (PPA) volumes in developing regions serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Hydrogen Capacity Buildout | Establishes new electricity demand centers and balances intermittent renewable generation. |
| Digital Energy Management Platform Expansion | Optimizes energy consumption for commercial clients, enhancing grid resilience. |
| Critical Mineral Supply Chain Diversification | Reduces geopolitical risk for battery and renewable technology manufacturing. |
| Grid Modernization Investment | Integrates decentralized energy resources and improves overall network stability. |
| Long-Term Power Purchase Agreements (PPAs) | Secures stable revenue for renewable projects and meets corporate sustainability goals. |
Research Approach
Multiple input streams — primary interviews, secondary research, and proprietary database analytics — were reconciled to construct a comprehensive market view. Primary engagement included utility planning officers, project developers, energy regulators, and industrial procurement leads. Secondary validation drew from IEA reports, EIA data, national energy agency publications, and corporate sustainability reports. A rigorous bottom-up and top-down triangulation approach ensured data consistency and accuracy across all segments.
Historical consumption trends were cross-referenced with expert panel input to project future market trajectories. The analytical framework modeled dynamics across the analysis window, segmenting by energy source, end-user sector, and consumption mode. Compound annual growth rates were derived through regression analysis. Electrification rates and renewable energy penetration targets served as key industry-specific forecast inputs.
Revisions become necessary when significant geopolitical shifts or unforeseen technological breakthroughs materialize. Forecasts reflect assumptions regarding stable regulatory environments and evolving supply chain dynamics. Deviation in global economic growth or major policy changes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Power SCADA Market
Energy Management
APAC Energy Management Systems (EMS) Market
Energy Management
Energy Management Market
Energy Management
Remote Renewable Management Systems Market
Energy Management
Microgrid Control System Market
Energy Management
Brazil Energy Sector Market
Energy Management
APAC Building Energy Management Systems Market
Energy Management
Middle-East and Africa Demand Response Management Systems Market
Energy Management
Energy Harvesting System Market
Energy Management
Smart Energy Solutions Market
Energy Management
European Building Energy Management Systems Market
Energy Management
Residential Demand Response Management Systems Market
Energy Management
Middle East and Africa Energy Management Systems Market
Energy Management
Electric Service Companies (Escos) Market
Energy Management
Europe Energy Management Systems Market
Energy Management
South Korea Residential Heat Pump Market