
 France Electric Vehicle Battery Anode Market | 2026-2036
France Electric Vehicle Battery Anode Market Size, Share, and Industry Trends Forecast 2026-2036
France Electric Vehicle Battery Anode Market Insights
European anode precursor output is realigning toward France's emerging battery valley. BASF SE leverages its Ludwigshafen materials science base to supply tailored graphite formulations for French cell producers. SGL Carbon anchors carbon-based anode supply through its European specialty graphite operations. Verkor competes with vertically integrated cell manufacturing plans that include anode specification control.
France electric vehicle battery anode denotes the negative electrode material—typically graphite or silicon-composite powders with particle sizes of 5–20 microns and specific capacities of 350–420 mAh/g—engineered to intercalate lithium ions during charge cycles in lithium-ion cells. Manufacturing employs sintering for synthetic graphite densification and chemical vapor deposition for silicon encapsulation to suppress volumetric expansion. Graphite dominates material type selection due to established supply chains and cycle stability, while silicon composites represent the fastest-expanding segment as cell makers pursue energy density above 300 Wh/kg. Among product forms, coated anodes capture margin concentration because surface modification with carbon or ceramic layers commands premium pricing from OEMs and tier-1 suppliers seeking enhanced fast-charge tolerance.
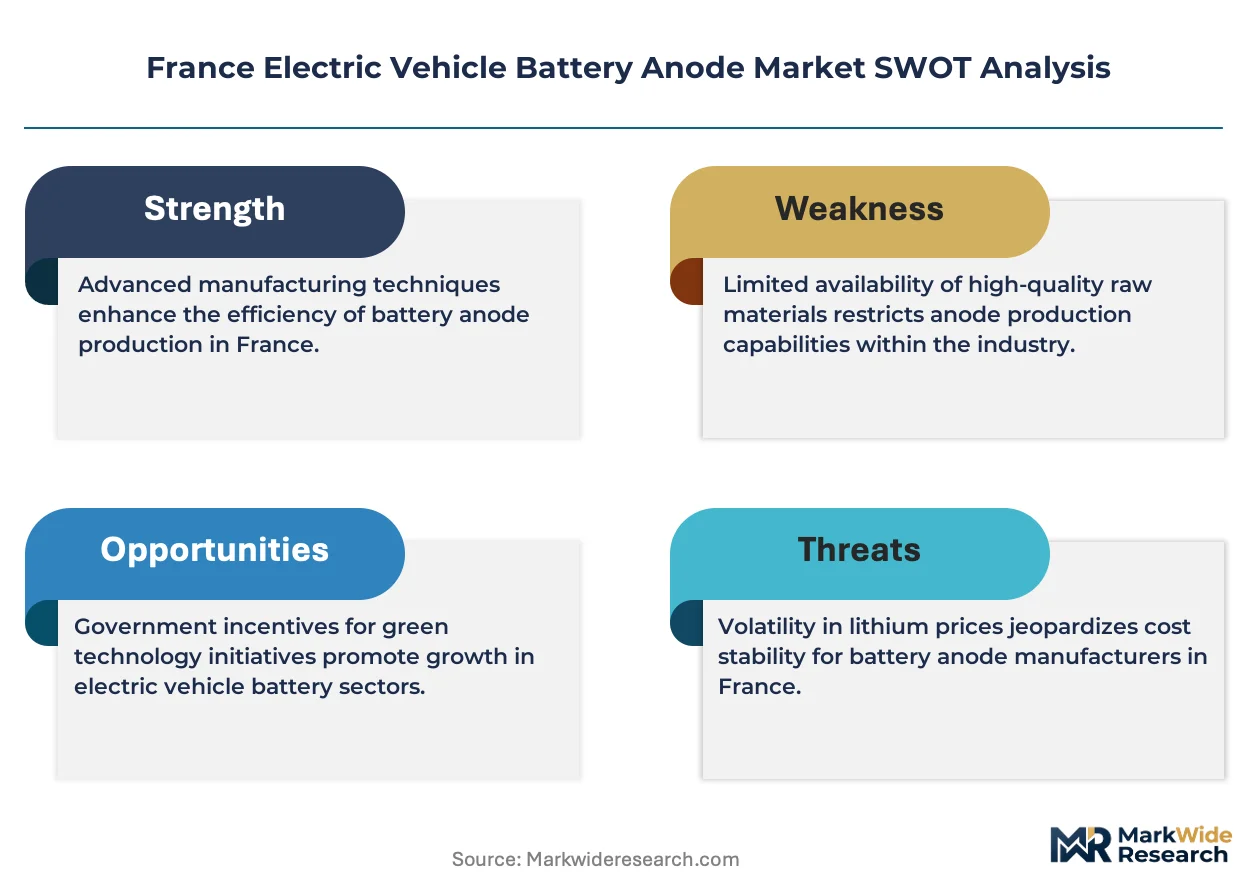
ANSM oversees chemical substance safety in battery materials, while the EU Battery Regulation mandates carbon footprint declarations and minimum recycled lithium recovery rates that reshape anode supply qualification. REACH compliance for graphite and silicon precursor chemicals constrains non-European suppliers seeking market access. Stakeholders must monitor how France's national battery strategy aligns industrial funding with evolving EU performance standards.
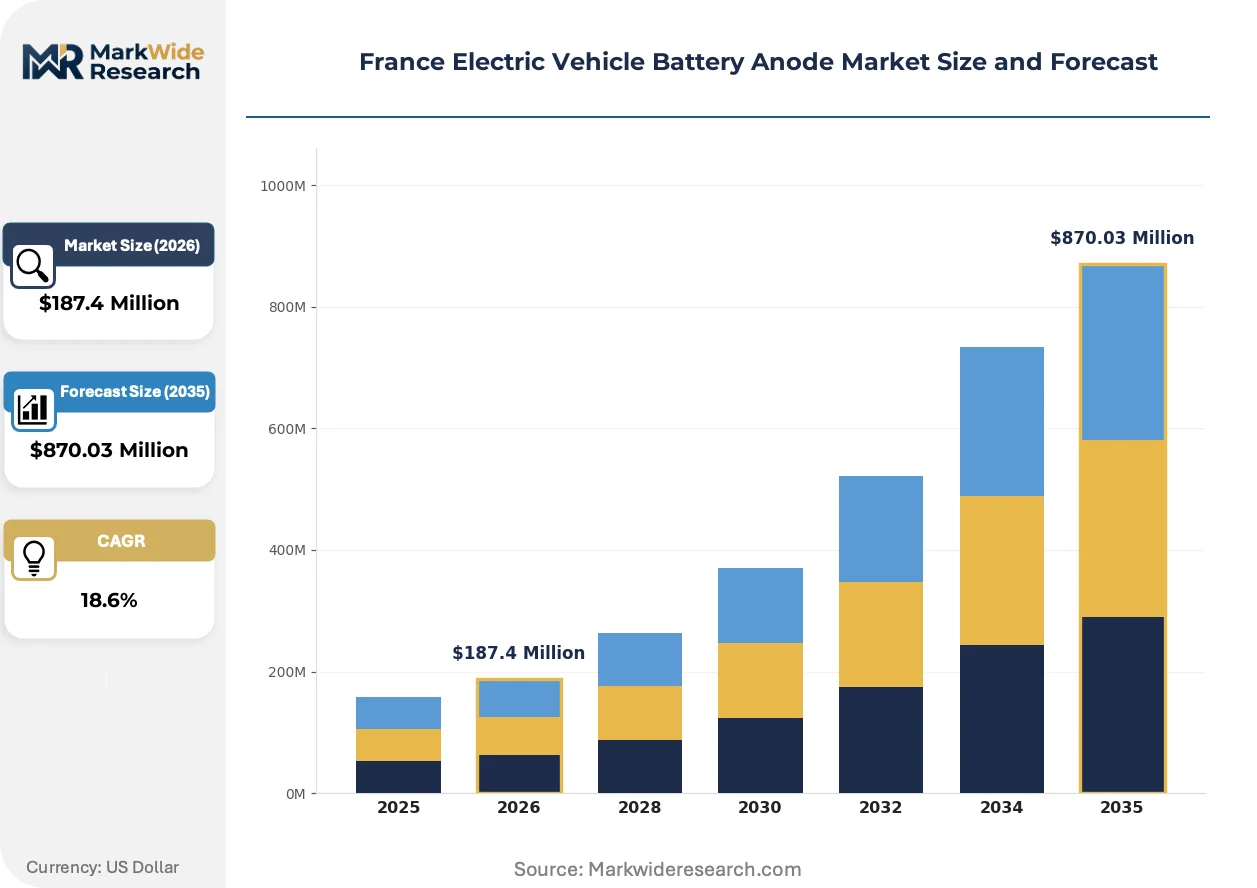
Market Dynamics
The EU Battery Regulation's carbon-footprint thresholds and recycled-content mandates are compressing qualification timelines for anode suppliers while co-locating production around Hauts-de-France and Grand Est industrial corridors.
Growth Catalysts
- EU Battery Regulation mandates:Carbon footprint declarations and minimum recycled lithium recovery rates are forcing cell producers to qualify local anode suppliers, accelerating domestic procurement.
- Silicon-composite anode chemistry:Energy density targets above 300 Wh/kg are pulling investment into silicon encapsulation and chemical vapor deposition capacity.
- Hauts-de-France clustering:Cathode and cell assembly co-location is generating transport-cost savings and just-in-time anode delivery requirements.
Market Restraints
- Graphite supply concentration:Synthetic graphite precursor dependence on Asian feedstock creates exposure to shipping cost volatility and customs processing delays.
- REACH compliance friction:Registration requirements for silicon precursor chemicals constrain non-European suppliers from rapid market entry.
- Silicon volumetric expansion:Particle pulverization during charge cycling limits silicon loading percentages to under 10% in commercial cells.
Strategic Opportunities
- Recycled-content anode streams:The EU Battery Regulation's 2031 recycled cobalt, lithium, and nickel thresholds will create qualified demand for recovered graphite processing.
- Fast-charge surface coatings:Ceramic and carbon layer deposition technologies are opening premium pricing tiers for coated anode products.
- Grand Est corridor expansion:Secondary industrial zones outside Hauts-de-France are attracting anode precursor investments due to lower land and energy costs.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell manufacturers and material suppliers compete for specialists in solid-electrolyte interphase optimization and particle-size distribution control.
- Gigafactory capex synchronization:Anode production capacity must commit to equipment orders 18–24 months ahead of cell line commissioning, creating demand-forecast risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Electric Vehicle Battery Anode Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Graphite, Silicon, Lithium, Composites Product Form: Coated, Uncoated, Flexible Sheets, Standard Sheets Manufacturing Technology: Sintering, Chemical Vapor Deposition, Mechanical Processing, Extrusion End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Research Institutions |
| Companies Covered | BASF SE, Varta AG, Blue Solutions, Arkema S.A., Robert Bosch GmbH, SGL Carbon, Saft Groupe S.A., Verkor, Contemporary Amperex Technology Co. Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Electric Vehicle Battery Anode Market Trends and Innovations
Material science advances and regulatory compression are converging to redefine anode specification standards and supplier qualification protocols across French cell manufacturing.
Silicon-composite anode formulations are expanding into high-energy-density cell designs for premium electric vehicle platforms. Automotive OEMs in the French market are specifying silicon loadings of 5–15% in next-generation cell contracts. This chemistry is expanding into previously graphite-dominated applications as encapsulation techniques suppress capacity fade.
REACH registration requirements for graphite and silicon precursor chemicals are tightening supplier documentation burdens. The regulation is disqualifying non-European material sources that lack established European Chemicals Agency dossiers. French cell producers are responding by dual-sourcing from BASF SE and SGL Carbon to secure compliant feedstock.
Cell producers are consolidating anode procurement around qualified tier-1 material suppliers with integrated coating capabilities. Long-term offtake agreements are replacing spot-market purchasing for synthetic graphite and silicon precursors. This concentration is most visible in the Hauts-de-France corridor, where Verkor and Automotive Cells Company have locked in multi-year supply contracts.
France Electric Vehicle Battery Anode Market Segmentation
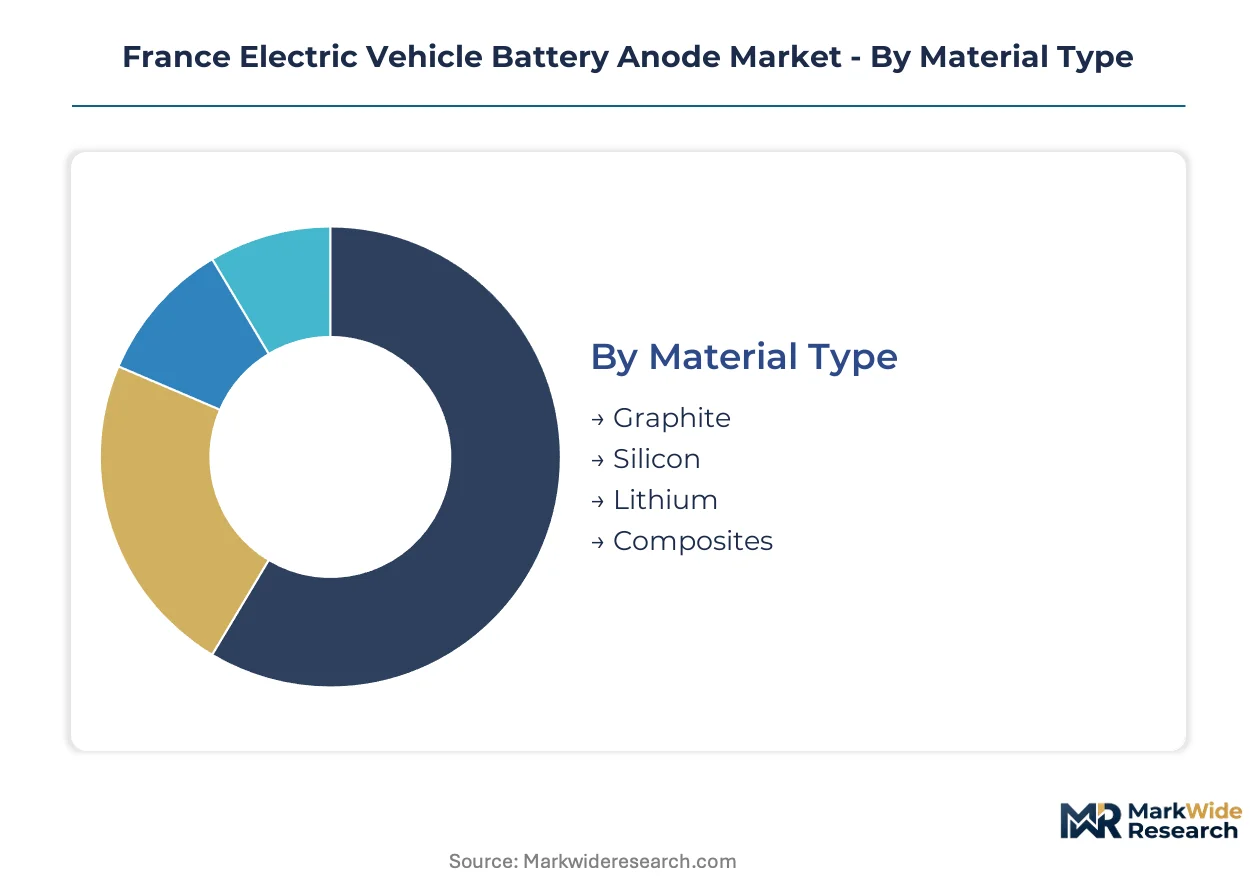
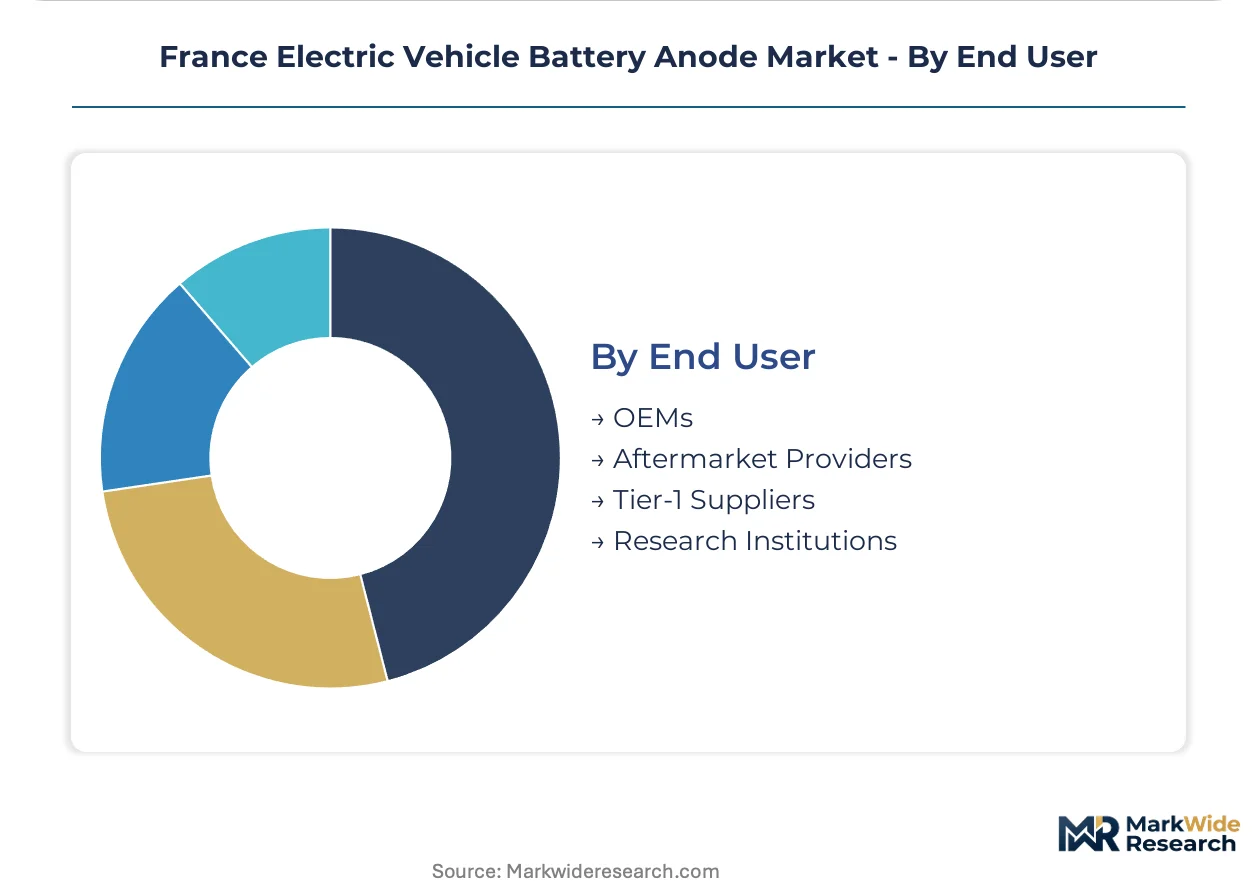
French cell manufacturers segment anode procurement by material chemistry, physical form, production method, and buyer type to align with EU Battery Regulation qualification timelines and gigafactory commissioning schedules. Each dimension carries distinct margin profiles and technical barriers that reshape supplier competitive positioning.
Material Type:
Cell energy density targets drive material selection trade-offs between cycle stability and specific capacity.
- Graphite:Synthetic and natural graphite powders with 350–370 mAh/g capacity dominate French procurement due to established supply chains from SGL Carbon and BASF SE. Hauts-de-France gigafactory projects specify graphite for standard-range vehicle platforms where cycle life exceeds 1,500 charges.
- Silicon:Silicon-composite formulations achieving 420 mAh/g through chemical vapor deposition encapsulation are expanding most quickly. Verkor and Automotive Cells Company qualify silicon loadings of 5–10% for premium electric vehicle contracts targeting above 300 Wh/kg pack density.
- Lithium:Metallic lithium anodes remain experimental in French research corridors, constrained by dendrite formation risks that ANSM safety protocols have not yet cleared for commercial cell deployment.
- Composites:Silicon-graphite hybrid architectures blend the stability of carbon matrices with silicon's capacity advantage, attracting pilot-line investment from Grand Est material startups.
Volume sits with graphite; growth tilts toward silicon.
Product Form:
Surface modification depth separates premium pricing tiers from commodity supply.
- Coated:Ceramic and amorphous carbon surface layers deposited via chemical vapor deposition command premium offtake terms from tier-1 suppliers. Fast-charge tolerance specifications from French OEMs require these coatings to suppress solid-electrolyte interphase degradation.
- Uncoated:Baseline graphite powders without surface modification serve cost-sensitive energy storage applications outside automotive, including stationary grid buffers in Grand Est industrial zones.
- Flexible Sheets:Rolled electrode formats for solid-state cell prototypes are emerging from French research institutions with ANSM pilot-project funding.
- Standard Sheets:Conventional calendered anode foils align with high-volume cylindrical and prismatic cell assembly lines at Hauts-de-France production facilities.
Margin concentration flows to coated formats; standard sheets anchor volume scale.
Manufacturing Technology:
Capital intensity and yield rates determine technology adoption sequencing across French production corridors.
- Sintering:High-temperature densification of synthetic graphite precursor delivers the structural integrity required for automotive cycle-life warranties. SGL Carbon's European operations supply sintered material to Hauts-de-France cell lines under multi-year contracts.
- Chemical Vapor Deposition:Silicon encapsulation and carbon coating deposition are climbing the fastest as energy density specifications harden. Equipment lead times of 18–24 months constrain capacity expansion timing.
- Mechanical Processing:Ball milling and classification of natural graphite feedstock remains cost-competitive for uncooled anode grades serving industrial battery applications.
- Extrusion:Continuous electrode sheet formation is scaling at Automotive Cells Company facilities to match prismatic cell throughput requirements.
Sintering commands installed capacity; chemical vapor deposition attracts capital allocation.
End User:
Procurement authority and technical specification control vary sharply across buyer categories.
- OEMs:Renault, Stellantis, and other French automotive manufacturers issue direct material specifications to anode suppliers, bypassing tier-1 intermediaries for strategic cell chemistry decisions. Their carbon-footprint accounting requirements flow down through supply contracts.
- Tier-1 Suppliers:Cell producers including Verkor and Automotive Cells Company consolidate anode procurement through qualified supplier lists, locking in volume commitments 24 months ahead of line commissioning.
- Aftermarket Providers:Replacement battery pack assemblers source uncooled graphite through spot-market channels with minimal qualification overhead, serving legacy vehicle fleets.
- Research Institutions:CEA and university laboratories pilot silicon-composite architectures and solid-state anode concepts under France's national battery strategy funding envelopes.
Procurement volume concentrates with tier-1 suppliers; specification authority rests with OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Graphite precursor deposits in Lac-des-Iles, Quebec anchor North American feedstock supply for French anode manufacturers seeking supply chain diversification beyond Asian sources.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are accelerating high-energy-density cell procurement, driving cross-border anode demand into Alsace. ECHA enforcement of REACH documentation for silicon precursor chemicals is tightening supplier qualification protocols. BASF SE's Ludwigshafen operations supply synthetic graphite formulations to French gigafactory projects in Hauts-de-France.
Belgium
Port of Antwerp-Bruges logistics hubs are emerging as graphite import gateways for French battery valley supply chains. The EU Battery Regulation's carbon-footprint declaration requirements are reshaping customs documentation for anode materials transiting through Belgian territory. Umicore's Hoboken facility anchors precursor chemical processing serving Grand Est industrial corridors.
Spain
Basque Country automotive suppliers are qualifying French-produced anodes for electric vehicle platform integration. Spain's national recovery plan battery funding aligns with EU performance standards on recycled-content thresholds. Barcelona-Tarragona chemical complexes are developing silicon precursor capacity for cross-border supply to French cell manufacturers.
Italy
Piedmont-based automotive design houses are influencing anode specification standards for premium electric vehicle architectures. Italy's transition plan for automotive supply chains incorporates EU Battery Regulation compliance timelines. Emilia-Romagna industrial zones are piloting graphite recycling streams for recovered anode material qualification.
Netherlands
Randstadt logistics networks are optimizing just-in-time anode delivery schedules to Hauts-de-France production facilities. Dutch national climate agreements on circular battery materials support cross-border recycling infrastructure development. Eindhoven-region equipment suppliers are delivering chemical vapor deposition systems to French silicon-composite anode lines.
France Electric Vehicle Battery Anode Market Competitive Landscape
Global majors compete with regional champions across qualification timelines and carbon-footprint compliance capabilities. The French market exhibits concentrated procurement authority among tier-1 cell producers with vertically integrated material strategies. Three archetypes dominate: diversified chemical conglomerates with battery material portfolios, carbon-specialist manufacturers with synthetic graphite expertise, and emerging cell producers with captive anode specification control. Capacity expansion and strategic partnerships represent the dominant competitive moves as players position for EU Battery Regulation qualification deadlines.
Among Germany-based chemical conglomerates, BASF SE and SGL Carbon exemplify the established supplier archetype with European manufacturing footprints and REACH-compliant documentation systems. SGL Carbon occupies a position within the carbon-specialist tier, leveraging specialty graphite operations for automotive-grade anode supply. French emerging producer Verkor represents the vertically integrated cell manufacturer archetype, exercising direct control over anode material specifications through in-house qualification protocols rather than tier-1 intermediaries.
| Leading Market Players |
|---|
| BASF SE |
| Varta AG |
| Blue Solutions |
| Arkema S.A. |
| Robert Bosch GmbH |
| SGL Carbon |
| Saft Groupe S.A. |
| Verkor |
| Contemporary Amperex Technology Co. Limited |
| Others |
Pricing and Supply Chain Analysis
Coated-uncoated anode divergence separates premium fast-charge formulations from commodity graphite powders, with EU Battery Regulation carbon-footprint declarations forcing tier-1 cell producers to absorb qualification costs while spot-market buyers in aftermarket channels escape documentation burdens. This bifurcation concentrates margin capture among REACH-compliant suppliers with integrated coating capabilities while compressing returns for mechanical-processing operations serving industrial battery applications.
Pricing Analysis
Warranty-backed cycle-life guarantees versus unbundled powder sales define the dominant pricing structure, with coated anodes commanding premium terms based on ceramic-layer certification grades and automotive OEM volume commitments. Price differentiation stems from fast-charge tolerance specifications and geographic proximity to Hauts-de-France assembly corridors. Cost compression in uncoated graphite runs through Asian precursor dependence and shipping volatility. Aftermarket providers exhibit highest price sensitivity; tier-1 cell producers prioritize qualification security over unit cost.
Supply Chain Analysis
EU Battery Regulation qualification gates restrict qualified anode supply to REACH-registered producers with ECHA dossiers, compressing viable supplier lists. Feedstock draws from Chinese synthetic graphite operations, Canadian natural graphite deposits, and German specialty carbon manufacturing. Precursor chemicals, silicon feedstock, and coating deposition equipment constitute critical input dependencies. Single-source vulnerability concentrates in chemical vapor deposition equipment where 18–24 month lead times constrain capacity expansion. Distribution runs through Antwerp-Bruges port logistics into Hauts-de-France and Grand Est industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France electric vehicle battery anode market sits in a technology-transition phase as silicon-composite formulations displace graphite dominance in premium cell architectures. This substitution dynamic rewrites supplier qualification protocols and procurement authority structures.
For Market Incumbents: Anticipate silicon encapsulation technology maturation by securing chemical vapor deposition capacity commitments ahead of equipment lead time bottlenecks. Defensive consolidation should prioritize backward integration into Quebec natural graphite feedstock to reduce Asian precursor exposure. REACH registration maintenance represents the critical lever for preserving tier-1 supplier status against emerging competitors.
For New Entrants and Emerging Players: The EU Battery Regulation in France opens a window for recycled-content anode streams as 2031 recycled lithium thresholds create qualified demand for recovered graphite processing. White-space targets include Grand Est corridor expansion where land and energy costs undercut Hauts-de-France clustering, and fast-charge ceramic coating services for tier-1 suppliers lacking in-house deposition capability. Go-to-market positioning should emphasize carbon-footprint accounting compliance as a service bundled with material supply.
For Investors and Strategic Acquirers: Re-rating potential sits with silicon-composite specialists given energy density specifications hardening above 300 Wh/kg across French OEM platforms. Long-term viability over a 5–10 year window favors producers with captive coating technology and qualified supply relationships with Verkor or Automotive Cells Company. The signal to watch is silicon loading percentage thresholds in next-generation cell contracts as an inflection indicator for chemistry mix shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Encapsulation Capacity Buildout | Chemical vapor deposition investment locks in qualification for Verkor and ACC supply contracts. |
| Quebec Graphite Feedstock Partnership | Lac-des-Iles sourcing diversifies precursor supply beyond Asian concentration risk. |
| Recycled-Content Processing Line | EU Battery Regulation thresholds create qualified demand for recovered anode material streams. |
| Fast-Charge Coating Service Expansion | Ceramic layer deposition commands premium pricing from tier-1 suppliers seeking OEM specification compliance. |
| Grand Est Corridor Manufacturing Footprint | Secondary industrial zones attract investment through lower land and energy costs versus Hauts-de-France clustering. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across cell producer procurement directors, anode material R&D leads, OEM platform engineers, and ECHA regulatory affairs specialists. Secondary validation drew from EU Battery Regulation implementation documents, ANSM chemical safety dossiers, BASF SE and SGL Carbon technical disclosures, and French national battery strategy funding announcements. Bottom-up volume modeling triangulated against top-down market sizing from gigafactory commissioning schedules.
Granularity-level modeling operated at material chemistry, product form, manufacturing technology, and end-user dimensions, with silicon loading percentage and coating thickness treated as continuous variables. CAGRs derived from equipment lead time constraints, qualification timeline compression, and OEM energy density specification trajectories across the analysis window. Forecast inputs incorporated chemical vapor deposition capacity expansion pipelines, REACH registration status by supplier, and Hauts-de-France versus Grand Est corridor investment flows.
The model assumes a particular technology adoption path; alternative pathways for solid-state anode architectures would alter the outlook if ANSM clears metallic lithium designs for commercial deployment. Forecasts reflect assumptions around EU Battery Regulation enforcement timing and silicon encapsulation yield rate improvements. A model refresh is warranted upon material change in OEM energy density specification thresholds or ECHA REACH documentation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
Lithium Nickel Manganese Cobalt Oxide Battery Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Anode Market
Lithium-ion Battery
Li Metal Battery Market
Lithium-ion Battery
Europe Solid State Battery Market
Lithium-ion Battery
Laminated Lithium Ion Secondary Battery Market
Lithium-ion Battery
France SLI Battery Market
Lithium-ion Battery
Automotive Lithium-Ion Battery Cell Market
Lithium-ion Battery
United States Battery Cell Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lifepo4 Battery Market
Lithium-ion Battery
China Electric Vehicle Battery Anode Market
Lithium-ion Battery
Nanobolt Lithium Tungsten Batteries Market
Lithium-ion Battery
Nanotechnology Enabled Battery Market
Lithium-ion Battery
Lithium Iodide Market
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market