
 Global Landing String Equipment Market | 2026-2036
Global Landing String Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Landing String Equipment Market Foresight
Gulf of Mexico capacity build-out is reshaping competitive dynamics in landing string manufacturing. NOV Inc. leverages integrated wellbore construction portfolios to dominate regional supply chains. SLB anchors deepwater technology leadership through proprietary automated landing systems. Expro Group specializes in intervention-focused landing strings for subsea well access.
Landing string equipment comprises high-strength tubular assemblies, typically forged from alloy steel grades meeting 10,000–15,000 psi working pressure ratings, designed to suspend casing and tubing strings within subsea wellheads during drilling and completion operations. The product category breaks into casing hangers and tubing hangers, where margin pools concentrate in premium threaded connections and fatigue-resistant metallurgy. Application demand tilts toward deepwater operations and subsea installations, segments where remote-operated deployment technology commands pricing premiums over mechanical alternatives.
API standards, Norway's PSA regulations, and Brazil's ANP presalt technical requirements shape material traceability and pressure-testing protocols for landing string assemblies. The US BSEE mandates blowout preventer compatibility testing that directly influences landing joint design specifications. Stakeholders must monitor regulatory divergence between presalt jurisdictions and legacy Gulf of Mexico requirements when configuring product portfolios.
Market Dynamics
Deepwater frontier expansion in Brazil's presalt basins and Guyana's Stabroek block is compressing deployment cycles for landing string assemblies, forcing manufacturers to accelerate fatigue-testing protocols and modularize hanger designs for remote-operated installation.
Growth Catalysts
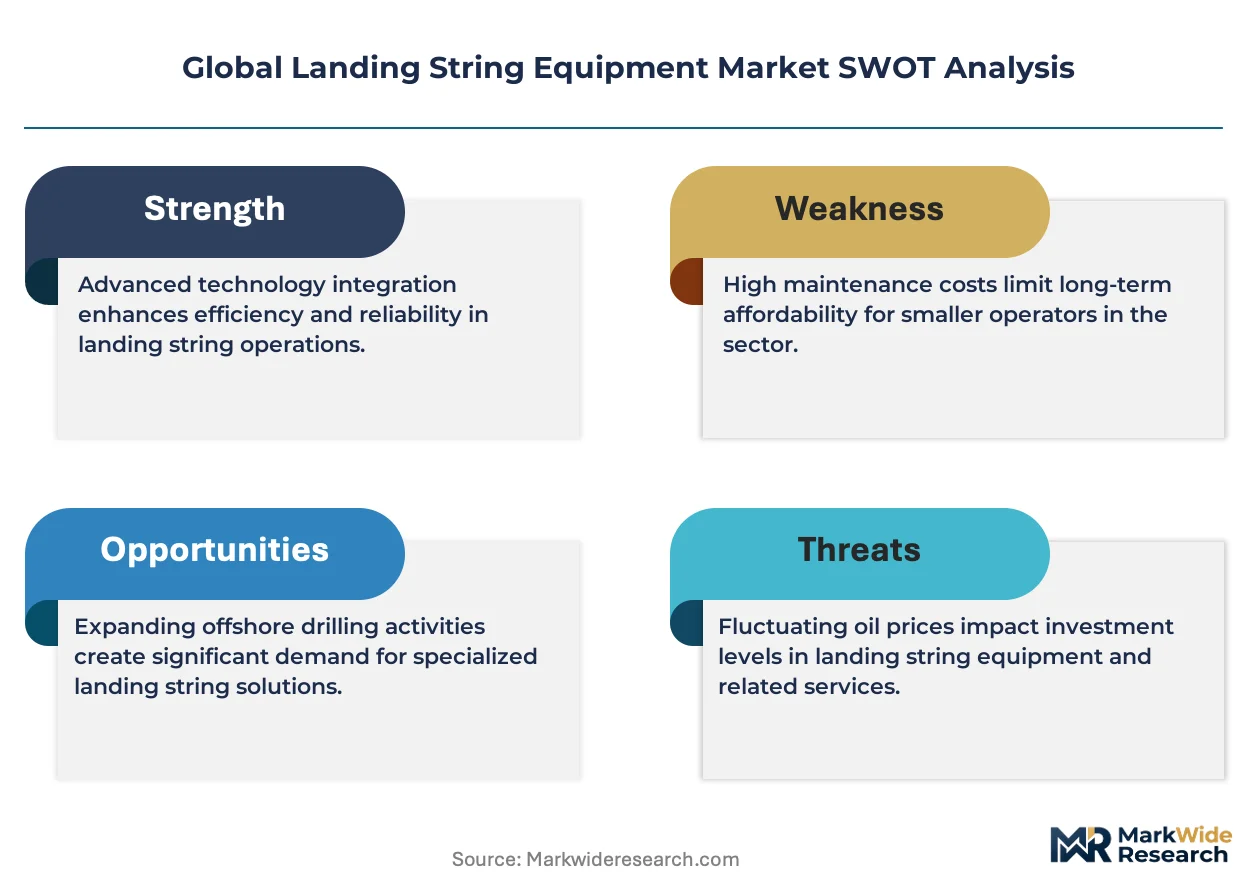
- Presalt regulatory mandates:Brazil's ANP technical requirements for subsea wellhead integrity are mandating redundant landing string configurations, expanding replacement demand for legacy installations.
- Ultra-deepwater metallurgy advances:High-chromium alloy grades rated to 15,000 psi working pressure are extending operational envelopes in Gulf of Mexico Lower Tertiary formations.
- Subsea tieback proliferation:Clustered development architectures off Norway and the UK are standardizing landing string specifications across multi-well templates.
Market Restraints
- Alloy steel input volatility:Nickel and molybdenum price swings in commodity markets are compressing margin visibility for forged hanger manufacturers.
- Supply concentration in forged components:North American and European forging capacity for high-pressure wellhead-grade steel remains bottlenecked at Tier-1 mill suppliers.
- API 6A certification timelines:Extended third-party validation cycles for modified hanger geometries are delaying product commercialization by 12–18 months.
Strategic Opportunities
- Guyana offshore development:ExxonMobil-led Stabroek block expansions are creating fresh demand for standardized landing string fleets optimized for 1,500-meter water depths.
- Electrification convergence:Integration of landing string assemblies with subsea power distribution units is enabling all-electric well intervention capabilities.
- Digital twin adoption:Real-time fatigue monitoring via embedded fiber optic sensors is opening predictive maintenance revenue streams for drilling contractors.
Industry Challenges
- Specialized welding certification scarcity:Qualified orbital welders for high-pressure tubular assemblies remain concentrated at legacy Gulf of Mexico fabrication yards.
- Legacy BOP stack compatibility:Retrofitting automated landing systems to existing subsea blowout preventer configurations requires extensive interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Landing String Equipment Market |
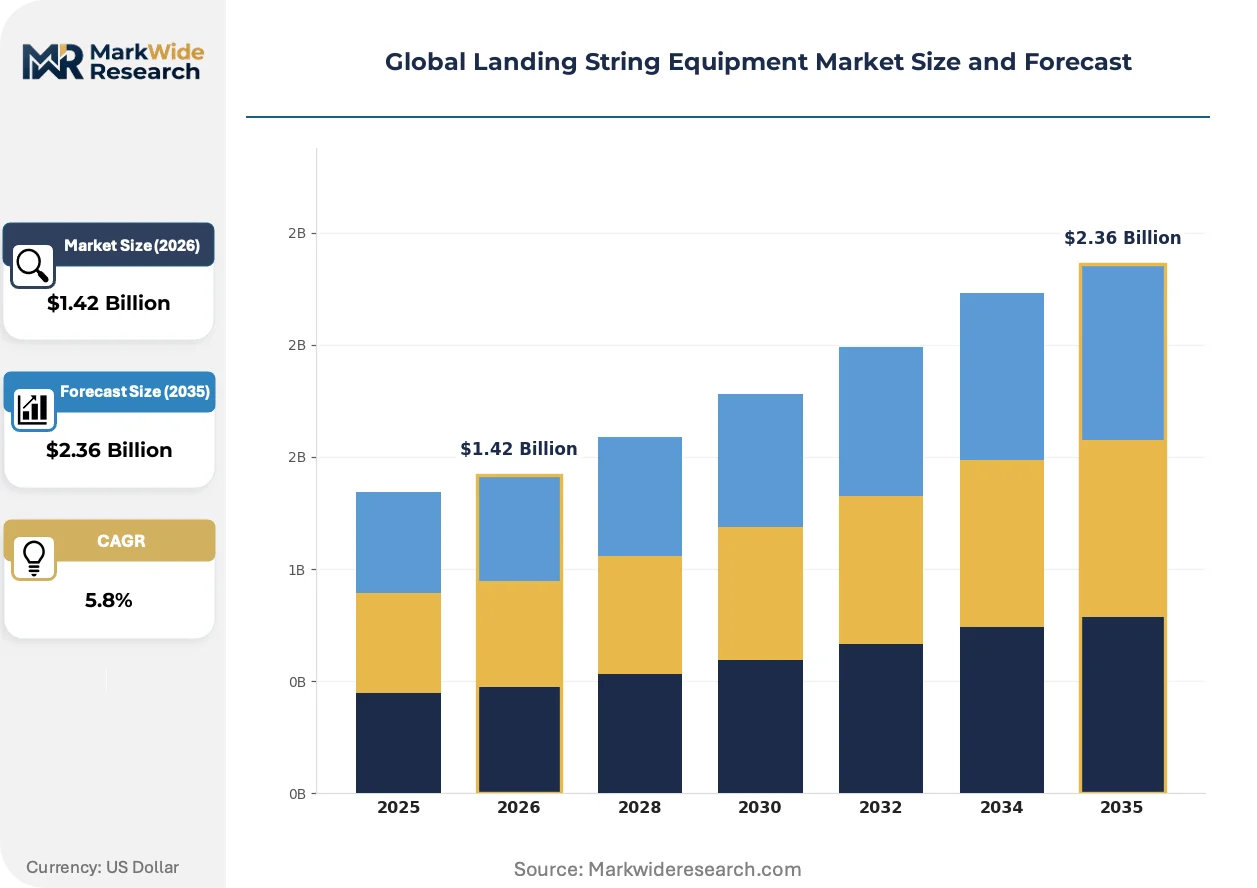
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casing Hangers, Tubing Hangers, Landing Joints, Centralizers, Packers Technology: Mechanical, Hydraulic, Manual, Automated, Remote Operated Application: Offshore Drilling, Onshore Extraction, Deepwater Operations, Subsea Installations End User: Oilfield Service Companies, Exploration Firms, Drilling Contractors, Well Equipment Suppliers |
| Companies Covered | Expro Group, NOV Inc., SLB, TechnipFMC plc, Aker Solutions, Halliburton, Enovate Systems Ltd., Vallourec SA, Quail Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Landing String Equipment Market Shifts & Advancements
Digitalization of subsea deployment workflows is collapsing traditional mechanical-hydraulic boundaries in landing string operations, while material science advances and procurement model evolution are reshaping how operators specify and source critical wellhead components.
Composite-reinforced landing joints are collapsing weight constraints that previously limited water-depth ratings for conventional all-steel assemblies. Deepwater drillship operators in Brazil and West Africa are piloting carbon-fiber hybrid configurations to reduce hookload requirements. This technology is collapsing the capital cost differential between ultra-deepwater and mid-water completions.
ISO 10423:2023 revisions for subsea wellhead equipment are tightening material traceability requirements from melt source through final machining. European operators under Norway's PSA jurisdiction are accelerating compliance investments ahead of certificate renewal cycles. Subsea engineering teams are responding by embedding blockchain-based documentation into supply chain workflows.
Integrated service contracting is displacing component-level procurement for major deepwater projects. Drilling contractors in the Gulf of Mexico are bundling landing string provision with managed pressure drilling packages, compressing vendor negotiation cycles. This consolidation is most pronounced among supermajors executing multi-rig programs off Louisiana and Texas.
Global Landing String Equipment Market Segmentation
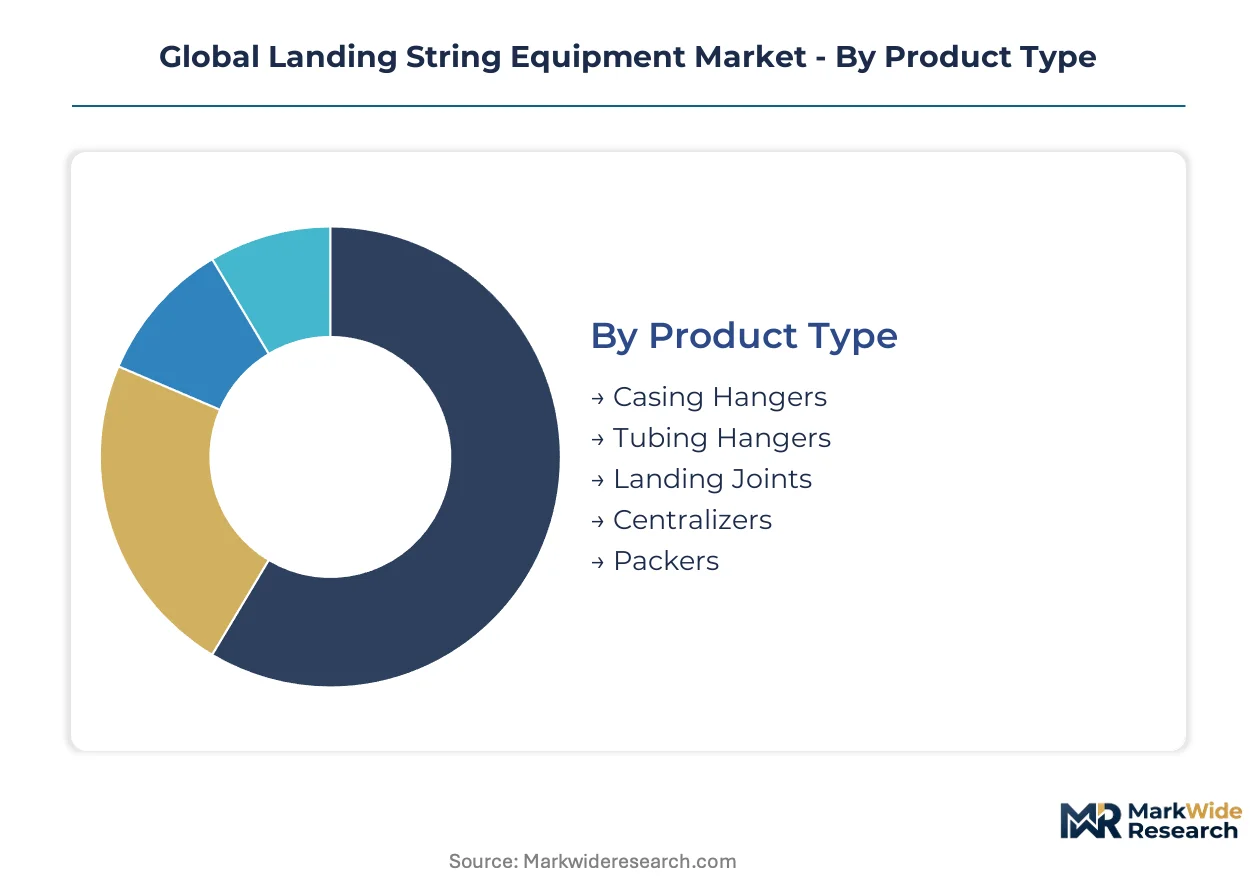
Landing string equipment procurement follows distinct lifecycle patterns across product categories, with pressure-bearing components requiring replacement at intervals measured in well counts rather than calendar years. Understanding segment turnover velocity enables manufacturers to align inventory positioning with contractor maintenance schedules and frontier drilling campaigns.
Product Type:
Casing hangers and tubing hangers turn over fastest due to cyclic fatigue from pressure testing and suspension loads, while centralizers and packers follow extended replacement cycles tied to well integrity management programs.
- Casing Hangers:Forged alloy steel assemblies with premium threaded connections rated to 15,000 psi working pressure. Demand clusters in Brazil's presalt basins and the Gulf of Mexico Lower Tertiary, where ANP and BSEE regulations mandate redundant configurations for ultra-deepwater completions.
- Tubing Hangers:High-strength tubular components designed to suspend production tubing within subsea wellheads during completion and intervention operations. Norway's PSA well integrity requirements are accelerating replacement demand for legacy installations in the North Sea, particularly at clustered subsea tieback developments.
- Landing Joints:Structural transition elements connecting surface BOP stacks to subsea wellhead housings, typically fabricated from chromium-molybdenum steel grades.
- Centralizers:Annular positioning devices ensuring casing string concentricity during cementing operations in deviated wellbores.
- Packers:Sealing elements isolating formation zones within casing strings, with service life extending across multiple well intervention cycles.
Casing hangers dominate installed base. Tubing hangers are where expansion concentrates.
Technology:
Cost tiering separates premium automated systems from mechanical alternatives, with hydraulic and remote-operated configurations commanding 3-4x pricing multiples over manual deployments in shallow-water applications.
- Automated:Self-actuating landing string systems integrating real-time load monitoring and automatic hanger engagement protocols. Guyana's Stabroek block developments are standardizing these configurations for 1,500-meter water depths to minimize ROV dependency and compress deployment cycles.
- Remote Operated:Subsea-deployed landing assemblies actuated via hydraulic flying leads from surface vessels, eliminating diver requirements. West Africa's deepwater frontier off Angola and Nigeria is absorbing these systems as drilling contractors retrofit mid-water rigs for ultra-deepwater capability.
- Hydraulic:Pressure-actuated hanger setting mechanisms requiring surface pump infrastructure for deployment.
- Mechanical:Threaded or cam-actuated engagement systems dependent on drill string rotation for hanger installation.
- Manual:Conventional landing string configurations requiring direct intervention for hanger manipulation.
Mechanical systems anchor legacy installed base. Automated configurations are climbing the fastest as operators prioritize rig-time efficiency.
Application:
Volume concentration tracks water depth ratings, with deepwater and subsea installations generating component-level revenue multiples 5-7x above onshore extraction on a per-well basis.
- Deepwater Operations:Completions in water depths exceeding 400 meters requiring specialized metallurgy and fatigue-resistant landing string geometries. Brazil's Buzios and Mero fields are absorbing premium hanger fleets as Petrobras accelerates presalt production ramp-up.
- Subsea Installations:Seabed wellhead configurations demanding remote-operated deployment capabilities and multi-well template standardization. Norway's Johan Sverdrup and UK Equinor-operated clusters are driving specification convergence across North Sea engineering standards.
- Offshore Drilling:Platform and jackup rig applications in shelf water depths with conventional mechanical landing string requirements.
- Onshore Extraction:Land-based drilling operations utilizing simplified hanger configurations with reduced pressure ratings and manual deployment protocols.
Offshore drilling holds the largest unit volume. Deepwater operations capture the steepest expansion trajectory as frontier basins mature.
End User:
Customer type determines procurement contracting structure, with drilling contractors favoring integrated service bundles while exploration firms retain component-level specification authority.
- Drilling Contractors:Fleet operators managing rig-specific landing string inventories across multi-year drilling programs. Transocean and Seadrill are consolidating vendor relationships through integrated wellbore construction contracts covering managed pressure drilling and landing string provision.
- Oilfield Service Companies:Technical service providers bundling landing string deployment with completion and intervention operations. These firms are embedding digital twin capabilities for predictive maintenance revenue streams in Gulf of Mexico deepwater markets.
- Exploration Firms:Operator companies specifying landing string requirements for prospect-specific drilling campaigns.
- Well Equipment Suppliers:Specialized distributors and aftermarket service providers supporting replacement demand and certification renewal cycles.
Drilling contractors control the largest procurement volume. Oilfield service companies are gaining share fastest through integrated contracting consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Forged alloy steel capacity concentrates in the United States, Norway, and Brazil, with specialized mill suppliers anchoring regional fabrication networks for high-pressure wellhead components.
United States
Gulf of Mexico Lower Tertiary developments drive specification intensity for 15,000 psi landing string assemblies. The US BSEE mandates blowout preventer compatibility testing that shapes landing joint design protocols. Houston-area fabrication yards cluster orbital welding certification for high-pressure tubular assemblies serving ultra-deepwater drillship fleets.
Brazil
Presalt basin expansion at Buzios and Mero fields accelerates demand for redundant landing string configurations. ANP technical requirements for subsea wellhead integrity mandate material traceability from melt source through final machining. Macae and Rio de Janeiro engineering centers standardize automated deployment systems for 1,500-meter water depths.
Norway
North Sea subsea tieback clusters at Johan Sverdrup drive specification convergence across multi-well templates. PSA well integrity regulations accelerate replacement cycles for legacy tubing hanger installations. Stavanger and Bergen engineering hubs specialize in fatigue-resistant metallurgy for remote-operated deployment.
Guyana
Stabroek block development creates fresh demand for standardized landing string fleets optimized for frontier deepwater conditions. The country's petroleum regulator enforces subsea equipment certification aligned with presalt jurisdiction precedents. Georgetown supply bases coordinate ExxonMobil-led drilling campaigns requiring compressed deployment cycles.
United Kingdom
Equinor-operated North Sea clusters absorb remote-operated landing systems for subsea well access. The Health and Safety Executive maintains pressure-equipment integrity standards affecting hanger replacement scheduling. Aberdeen fabrication yards concentrate intervention-focused landing string expertise for mature basin workovers.
Global Landing String Equipment Market Competitive Landscape
Integrated wellbore construction specialists and subsea technology pure-plays split the market between bundled service contracts and component-level supply. Consolidation pressure intensifies as drilling contractors reduce vendor counts through multi-rig procurement programs. Two strategic archetypes dominate: full-service oilfield conglomerates with captive forging capacity, and specialized intervention equipment firms with modular hanger engineering. Competitive moves center on integrated service contracting consolidation and fatigue-testing protocol acceleration.
Among US-based integrated suppliers, NOV Inc. and SLB occupy positions anchoring Gulf of Mexico supply chains through automated landing system portfolios. Expro Group exemplifies the intervention-specialist archetype, sitting within the subsea well access tier with focused landing string configurations. These three firms represent the competitive spectrum from bundled wellbore construction to targeted completion equipment.
| Leading Market Players |
|---|
| Expro Group |
| NOV Inc. |
| SLB |
| TechnipFMC plc |
| Aker Solutions |
| Halliburton |
| Enovate Systems Ltd. |
| Vallourec SA |
| Quail Tools |
| Others |
Supply & Pricing Matrix
Trans-Atlantic heavy-lift shipping corridors connecting Houston to Macae and Stavanger transmit alloy steel price volatility directly into landed cost differentials for forged hanger assemblies, compressing margin pools at fabrication yards while amplifying regional price spreads between Gulf of Mexico and Brazilian presalt procurement.
Pricing Analysis
API 6A certification tiers dictate the pricing tier structure across landing string assemblies, with 15,000 psi premium-mid-economy pricing differentiation separating fatigue-tested configurations from standard-pressure alternatives. Price differentiation hinges on material traceability grade and automated deployment capability, with Norwegian PSA-mandated documentation commanding substantial premiums over legacy mechanical systems. Cost compression in mid-tier hydraulic configurations is intensifying because nickel-molybdenum alloy input volatility feeds through mill pricing. National oil companies in Brazil exhibit lowest price sensitivity due to presalt regulatory mandates, while independent drilling contractors in West Africa remain most exposed to procurement cycle timing.
Supply Chain Analysis
Export-control restrictions on high-strength chromium-molybdenum forging technology limit equipment flows to certain frontier markets, concentrating supply leverage among legacy mill suppliers in the United States, Norway, and Germany. Raw material sourcing draws from nickel mines in Indonesia, molybdenum concentrates from Chile, and specialized alloy scrap recovery networks in the European Union. Single-source vulnerability at Tier-1 forging capacity creates structural exposure for lead-time extensions. Distribution runs through integrated service contractors bundling landing string provision with managed pressure drilling packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification convergence with subsea power distribution units is disrupting traditional mechanical-hydraulic boundaries, creating asymmetric growth windows for vendors with embedded sensor capabilities and all-electric well intervention architectures.
For Market Incumbents: Insulate forging capacity relationships through long-term alloy steel offtake agreements with North American and European mill suppliers, locking in material traceability documentation ahead of ISO 10423:2023 renewal cycles. Backward integration into orbital welding certification programs at legacy Gulf of Mexico fabrication yards defends against qualified technician scarcity threatening deployment timelines.
For New Entrants and Emerging Players: Guyana's Stabroek block development represents the most penetrable frontier, with ExxonMobil-led drilling campaigns standardizing automated landing string specifications that favor modular hanger engineering over integrated wellbore construction bundles. Target intervention-focused service contracting with digital twin capabilities as the primary go-to-market angle, embedding fiber optic fatigue monitoring to differentiate from mechanical-only incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from oilfield service conglomerates divesting non-core subsea equipment divisions to refocus on digital and carbon-transition platforms. Long-term viability centers on vendors with captive forging relationships and ANP-compliant certification infrastructure serving Brazil's presalt expansion. Watch for presalt regulatory harmonization across Guyana, Suriname, and West African frontier basins as the signal indicating accelerated specification standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Landing System Certification | API 6A validation for self-actuating hanger engagement compresses ROV-dependent deployment cycles at Stabroek. |
| Alloy Steel Mill Partnership | Long-term offtake agreements with US and Norwegian forging capacity secure material traceability for ANP compliance. |
| Digital Twin Integration | Embedded fiber optic sensors enable predictive maintenance revenue streams from Transocean and Seadrill fleets. |
| Subsea Electrification Convergence | All-electric well intervention capabilities align with Equinor-operated North Sea cluster power distribution architectures. |
| Orbital Welding Certification Expansion | Qualified technician pipelines at Houston fabrication yards address BSEE-mandated blowout preventer compatibility testing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and equipment certification databases, combining structured interviews with drilling contractors, subsea engineering directors, oilfield procurement leads, and aftermarket service heads with validation through API 6A certification records, ANP technical requirement documents, BSEE safety alerts, and SEC 10-K disclosures from integrated suppliers. Bottom-up segment sizing triangulates against top-down spending estimates from national oil company capital programs.
Forecast inputs include rig fleet deployment schedules, presalt well count trajectories, and water-depth rating migrations across the projection horizon. Segmentation models capture product type pressure ratings, deployment technology tiers, application water-depth bands, and end-user contracting structures. CAGRs derive from elasticity-adjusted spending patterns against frontier basin development timelines, with specific weighting for Lower Tertiary metallurgy advances and subsea tieback proliferation rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pure-play digitalization specialists or carbon-fiber composite entrants would shift outcomes. Material shifts in nickel-molybdenum commodity pricing, presalt regulatory divergence, or major BOP stack redesigns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Air Independent Propulsion Systems for Submarine Market
Military Equipment and Infrastructure
Global Soldier Modernization Market
Military Equipment and Infrastructure
Global Remote Weapon Station Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Deployable Military Shelters Market
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
Man Portable Military Electronics Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market
Military Equipment and Infrastructure
Howitzer Artillery System Market
Military Equipment and Infrastructure
CBRNE Defense Market
Military Equipment and Infrastructure
Global Stealth Warfare Market
Military Equipment and Infrastructure
Military Test Equipment Market
Military Equipment and Infrastructure
Aircraft Carrier Arresting Systems Market
Military Equipment and Infrastructure
Used Serviceable Material (USM) Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market