
 Armoured Personnel Carrier (APC) Market | 2026-2036
Armoured Personnel Carrier (APC) Market Size, Share, and Industry Trends Forecast 2026-2036
Armoured Personnel Carrier (APC) Market Outlook
Steel is restructuring APC hull economics as advanced high-hardness alloys and ceramic composite inserts replace conventional rolled homogeneous armor. Rheinmetall AG leverages its integrated steel-forging and armor-package production to control cost curves across European land-systems programs. BAE Systems sustains long-term sovereign contracts through British Army modernization frameworks. Otokar Otomotiv ve Savunma Sanayi A.Ş. dominates Turkey's export-driven APC sector with wheeled-platform specialization.
An armoured personnel carrier is a protected tactical vehicle engineered to transport infantry squads under ballistic and blast threat, typically featuring V-hull geometries, STANAG 4569 protection levels, and modular mission kits for gunnery, command, or medical evacuation roles. Wheeled configurations lead volume production due to lower lifecycle costs and road mobility, while tracked variants anchor heavy-brigade modernization where terrain crossing and armor mass prove decisive. Active Protection technology segments attract disproportionate R&D allocation as hard-kill interceptors migrate from main battle tanks to medium-weight APCs.
NATO STANAG standards, the EU Green Deal industrial emissions framework, and Turkey's SSB offset requirements collectively shape APC procurement specifications and market access conditions across Europe and adjacent basins. The US Army's NGCV program through PEO Ground Combat Systems imposes modular-open-systems architectures that ripple through allied supplier ecosystems. Stakeholders must monitor how sovereign content rules and emissions compliance timelines interact to determine which production footprints qualify for upcoming multi-billion-dollar vehicle replacement tranches.
Market Dynamics
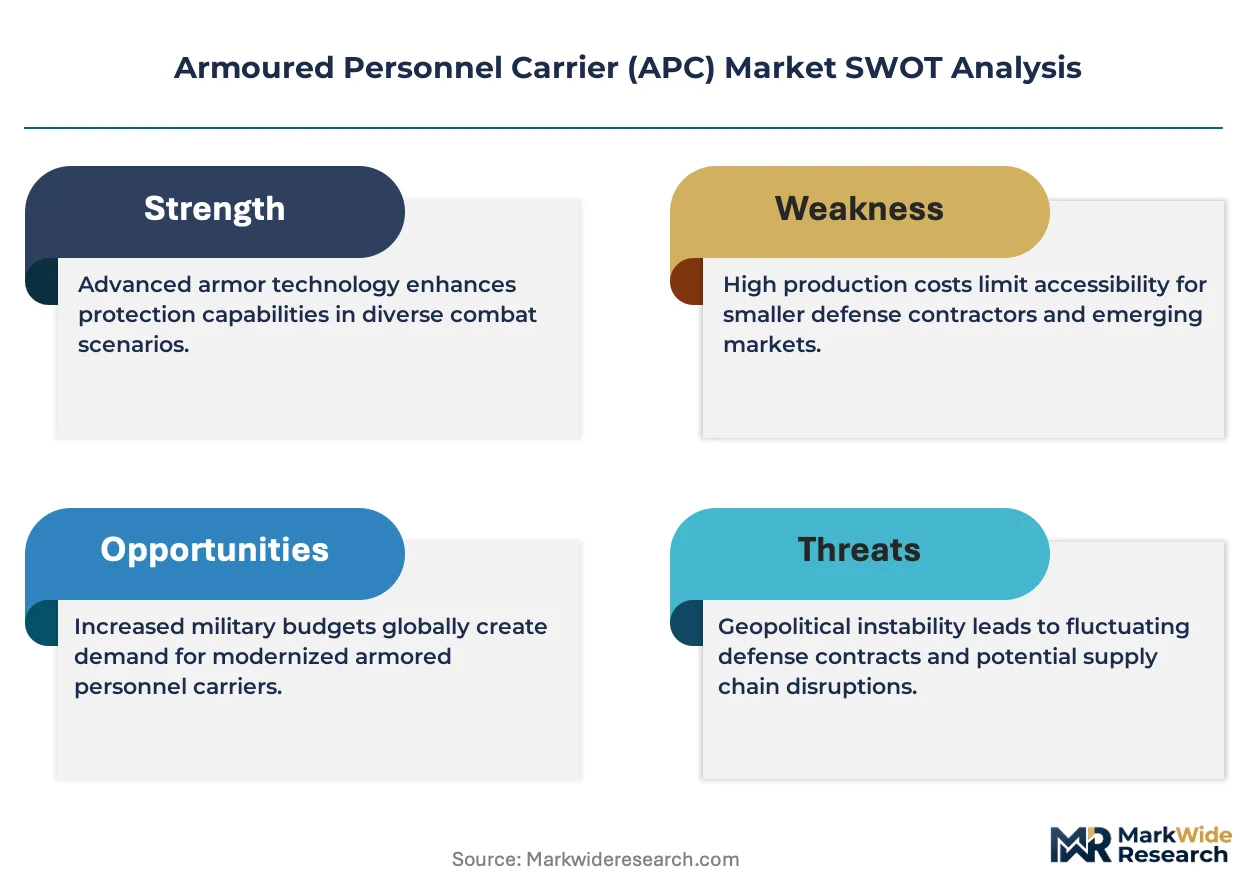
Hybrid-electric drivetrain mandates under the EU Green Deal are forcing rapid powertrain re-engineering across European land-systems suppliers, compressing development timelines and elevating R&D allocation toward battery-thermal management and silent-running capabilities.
Growth Catalysts
- NATO STANAG 4569 modernization:Ballistic protection upgrades across alliance member inventories are accelerating tracked and wheeled platform replacement cycles.
- Turkey:SSB offset requirements and domestic production expansion are creating captive demand for indigenous wheeled APC exports to Central Asian and African operators.
- Active Protection Systems:Hard-kill interceptor miniaturization is migrating from main battle tanks to medium-weight personnel carriers, opening new subsystem procurement categories.
Market Restraints
- Steel alloy volatility:Advanced high-hardness armor plate and ceramic composite insert costs fluctuate with nickel and boron carbide supply constraints.
- Single-source dependence:Tracked suspension component forging capacity concentrates in Central European supplier clusters, exposing programs to geographic disruption risk.
- REACH compliance friction:Ceramic matrix composite manufacturing processes face extended ECHA substance authorization timelines, delaying qualification for EU defense contracts.
Strategic Opportunities
- Poland:Accelerated mechanized brigade expansion under the Homar and Borsuk programs creates near-term volume demand for domestic and licensed production.
- Medical evacuation modular kits:NATO Role 2 field hospital standards are elevating integrated casualty evacuation platforms as a distinct procurement vertical.
- Hybrid-electric + active protection convergence:Silent watch modes paired with radar-based threat detection enable new urban warfare mission profiles previously unattainable with conventional powertrains.
Industry Challenges
- Systems integration engineering:Modular-open-systems architectures under US Army NGCV specifications demand software-defined vehicle expertise scarce among traditional armor manufacturers.
- STANAG certification timelines:Live-fire ballistic and blast testing protocols extend qualification cycles, compressing production windows against fixed delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Armoured Personnel Carrier (APC) Market |
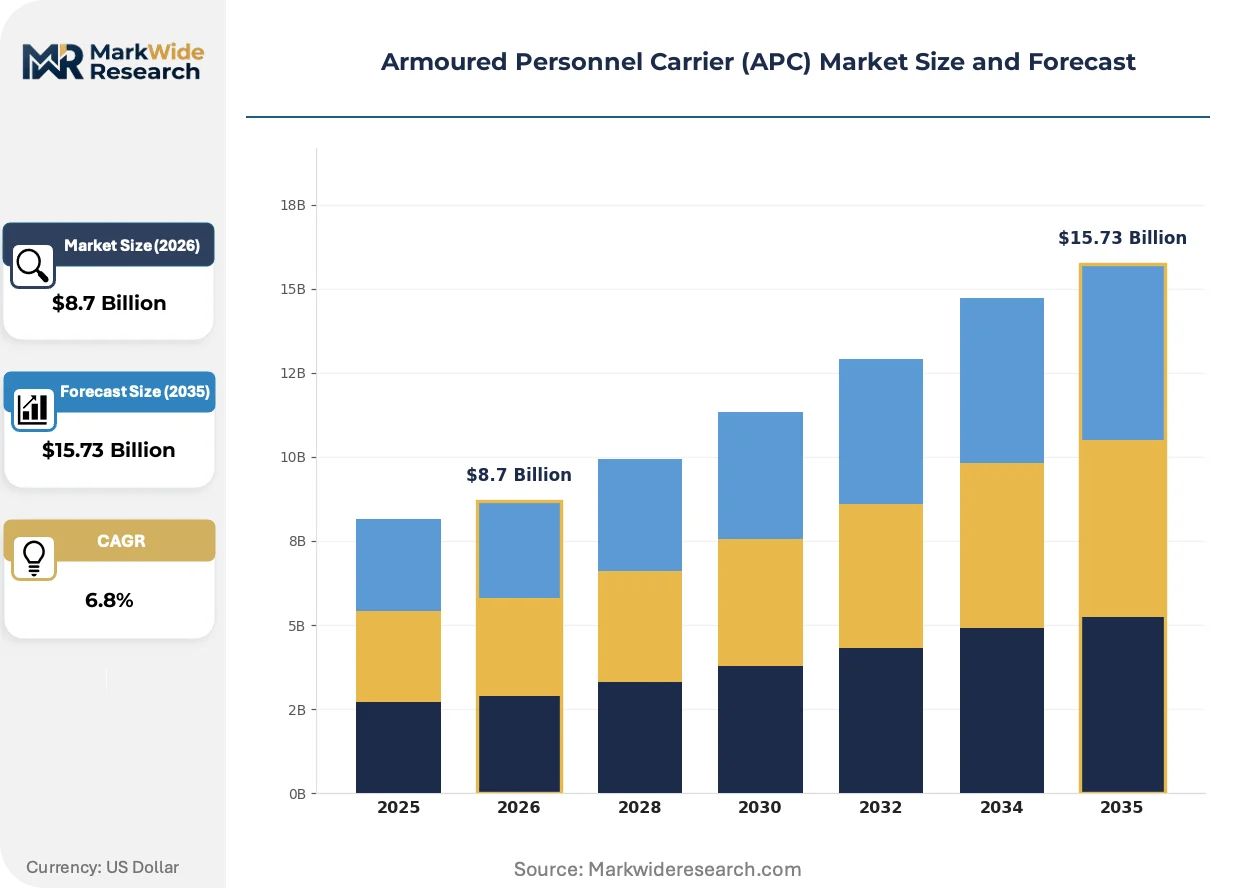
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Fully Amphibious, Wheeled, Tracked, Modular Application: Military Use, Disaster Relief, Law Enforcement, Civic Protection Technology: Passive Armor, Active Protection, Autonomous Systems, Networking End User: Government, Defense Contractors, NGOs, Private Security |
| Companies Covered | General Dynamics Corporation, Rheinmetall AG, BAE Systems, Otokar Otomotiv ve Savunma Sanayi A.Ş., Patria Oyj, KNDS, Oshkosh Corporation, Lockheed Martin Corporation, FNSS Savunma Sistemleri A.Ş., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Armoured Personnel Carrier (APC) Market Strategic Shifts
Powertrain electrification, hardened electronics miniaturization, and sovereign production mandates are simultaneously redefining platform architecture, supplier qualification criteria, and contract award mechanisms across NATO and adjacent procurement basins.
Silicon carbide power electronics are converging with high-density battery pack designs to enable 30-minute silent watch durations without auxiliary generators. Polish and South Korean mechanized units are field-testing these configurations in brigade combat team exercises. This convergence is compressing the performance gap between wheeled and tracked platforms in contested logistics environments.
The EU Green Deal industrial emissions framework is imposing mandatory carbon footprint disclosure on defense industrial base suppliers bidding into European Development Fund vehicle programs. Manufacturers must now document scope 1-3 emissions across steel forging, ceramic sintering, and final assembly stages. German and French land-systems integrators are responding by qualifying domestic green steel sources and captive recycling streams for armor plate production.
Long-term through-life support contracts are displacing traditional transactional spare parts procurement across NATO operator fleets. British Army Boxer and Ajax program offices now require 25-year availability guarantees with contractor logistics support embedded at the platform level. This shift is most visible in UK and Australian acquisition frameworks, where sovereign industrial base participation mandates tie manufacturing workshare to in-country maintenance infrastructure commitments.
Armoured Personnel Carrier (APC) Market Segmentation
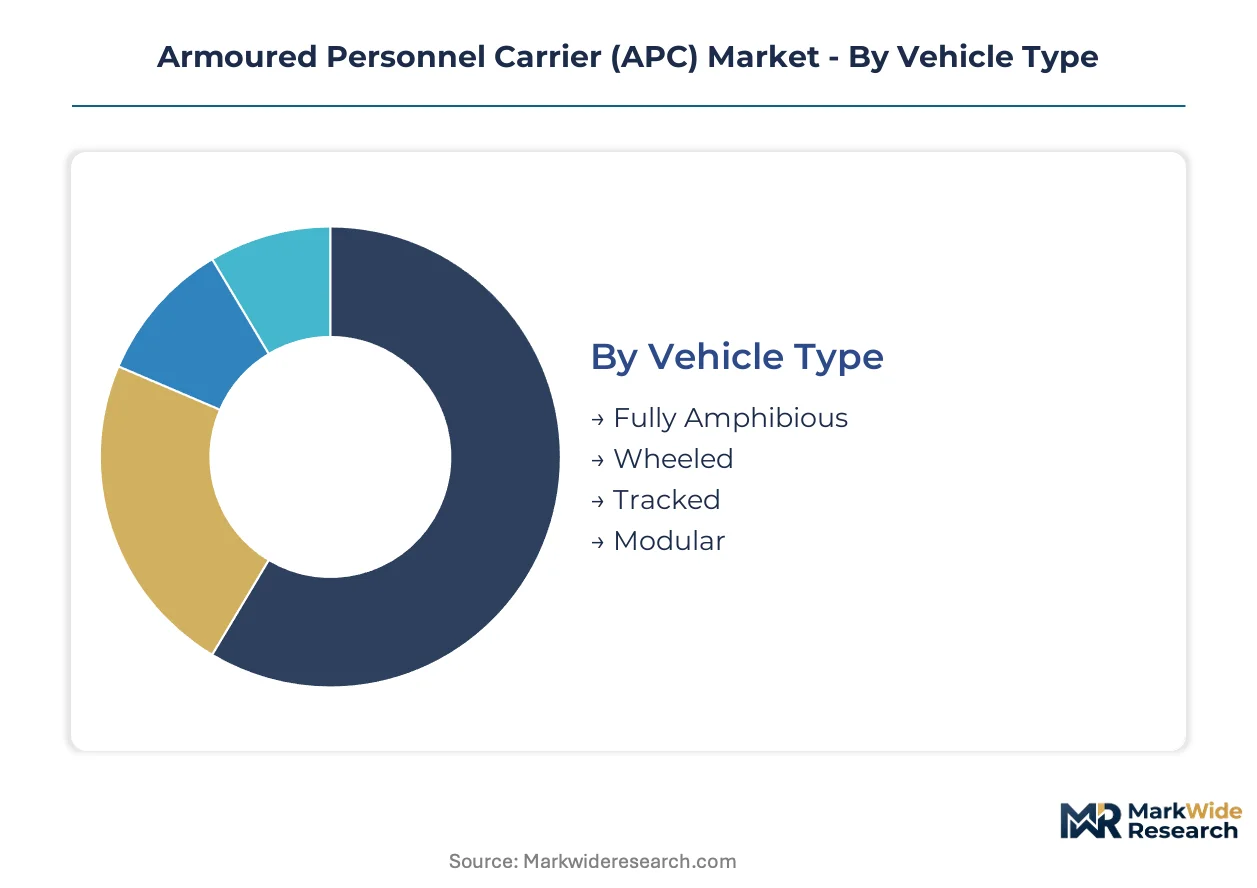
APC procurement specifications fragment across mobility requirements, mission profiles, and protection architectures. Procurement officers weigh lifecycle cost against tactical flexibility when selecting platform configurations for specific threat environments.
Vehicle Type:
Wheeled platforms dominate volume procurement due to lower through-life costs, while tracked variants command premium pricing for heavy brigade applications. The volume-premium split tilts toward wheeled systems in export markets, with tracked configurations concentrated in NATO heavy mechanized units.
- Wheeled:4x4, 6x6, and 8x8 configurations utilize commercial truck powertrain derivatives to reduce maintenance burden. Polish mechanized brigades under the Borsuk program and Turkish SSB-licensed exports to Central Asian operators concentrate demand for 6x6 and 8x8 hulls with STANAG 4569 Level 4 protection.
- Tracked:Continuous band suspensions distribute ground pressure for soft-terrain mobility and support heavier armor packages. German and French heavy brigade modernization programs anchor procurement of tracked personnel carriers with integrated active protection and hybrid-electric silent-running capabilities.
- Fully Amphibious:Sealed hulls with waterjet or track-propelled river crossing capability address littoral and riverine operations.
- Modular:Mission kit architectures enable rapid reconfiguration between infantry transport, command post, and medical evacuation roles.
Today's leader: Wheeled. Tomorrow's challenger: Tracked.
Application:
Mission profile determines protection level, mobility specification, and equipment fit. Cost tiers separate full-spectrum military configurations from lighter variants optimized for constabulary or humanitarian roles.
- Military Use:Infantry squad transport under direct fire and blast threat requires V-hull geometries, STANAG 4569 ballistic certification, and hard-kill active protection integration. NATO STANAG modernization cycles and Poland's Homar mechanized expansion drive procurement concentration.
- Law Enforcement:Wheeled platforms with lower protection levels address urban riot control and counter-terrorism operations. Turkish Otokar and South Korean Hyundai Rotem export wheeled APCs to interior ministry fleets across Southeast Asia and the Middle East.
- Disaster Relief:Unarmored or lightly protected variants with cargo capacity and medical module compatibility support humanitarian logistics.
- Civic Protection:Civil defense and emergency response configurations prioritize crew survivability in CBRN environments over ballistic protection.
Military applications absorb the majority of R&D allocation, yet law enforcement procurement offers faster qualification timelines and lower technical risk for new market entrants.
Technology:
Protection architecture selection separates legacy fleet upgrades from next-generation platform development. Technology tiering reflects the migration from passive steel and ceramic arrays toward software-defined defensive systems.
- Passive Armor:Rolled homogeneous steel, high-hardness alloys, and ceramic composite inserts provide baseline ballistic and blast protection. REACH compliance friction around boron carbide and silicon carbide sintering processes delays ECHA qualification for EU defense contracts.
- Active Protection:Hard-kill interceptors and soft-kill countermeasures are migrating from main battle tanks to medium-weight APCs. Radar-based threat detection paired with hybrid-electric silent watch enables new urban warfare mission profiles.
- Networking:Vehicle-mounted battle management systems and tactical data links integrate APCs into combined arms formations.
- Autonomous Systems:Unmanned ground vehicle technology and optionally manned configurations support route clearance and logistics resupply missions.
Passive armor retains procurement volume leadership. Active protection systems represent the steepest expansion trajectory as miniaturization reduces cost and power penalties.
End User:
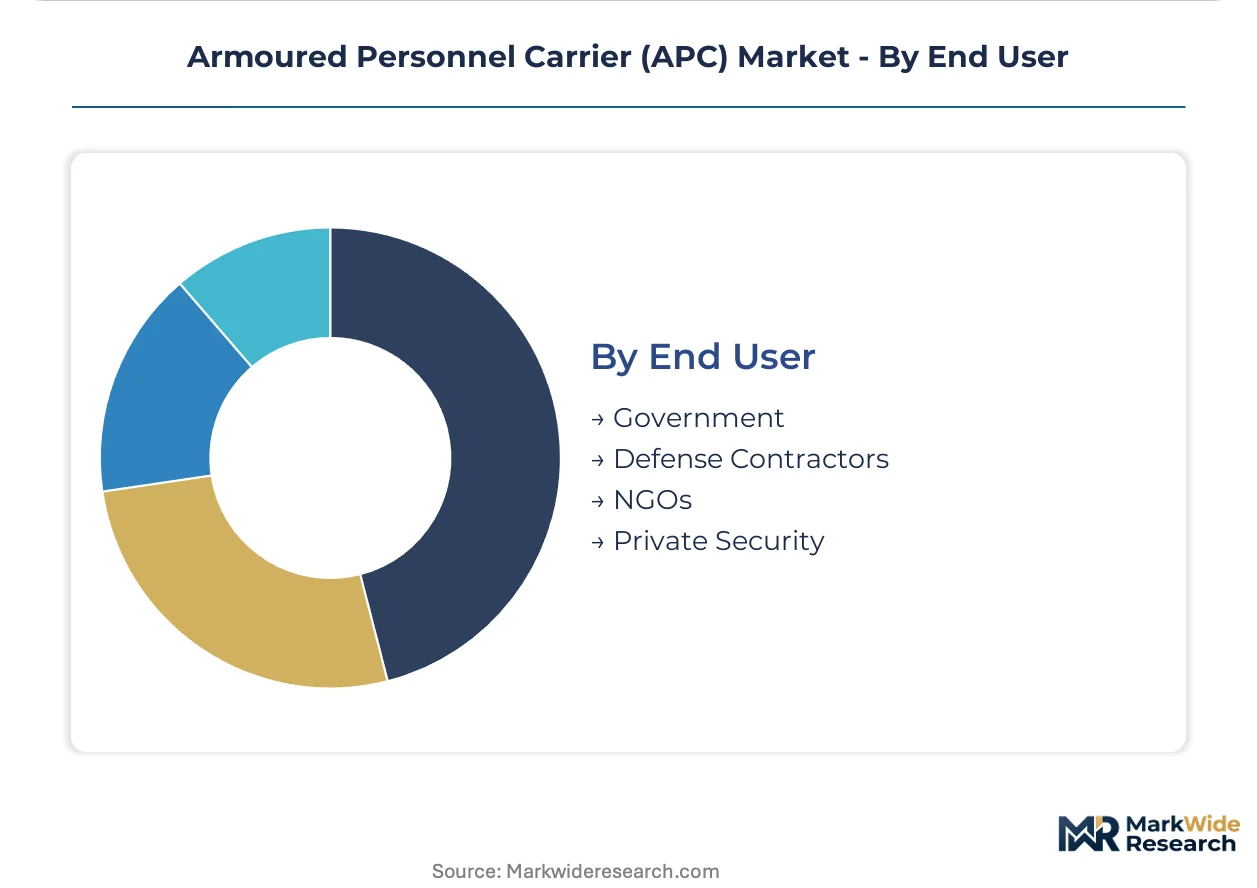
Contracting authority shapes procurement mechanism, offset requirements, and through-life support structure. Customer type tiering separates sovereign defense acquisition from commercial and non-governmental procurement channels.
- Government:National defense ministries and military procurement agencies impose sovereign content rules, offset mandates, and 25-year availability guarantees. British Army Boxer and Ajax programs embed contractor logistics support at the platform level.
- Defense Contractors:Prime integrators and subsystem suppliers purchase hulls and protection packages for integration into national programs. Rheinmetall's integrated steel-forging and armor-package production controls cost curves across European land-systems programs.
- Private Security:Commercial firms operating in high-threat environments procure used military surplus or purpose-built protected mobility vehicles.
- NGOs:Humanitarian organizations acquire unarmored or lightly protected variants for logistics and medical evacuation in conflict zones.
Government end users concentrate premium platform demand. Defense contractors represent the largest volume channel through licensed production and subsystem supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rheinmetall AG's integrated steel-forging complex in Düsseldorf anchors European land-systems production, while Turkey's SSB-licensed export networks and Poland's Homar mechanized expansion reshape procurement basins across NATO's eastern flank and Central Asian operators.
United States
The US Army's NGCV program through PEO Ground Combat Systems drives modular-open-systems architecture demand for next-generation personnel carriers. Pentagon acquisition frameworks impose 25-year availability guarantees with embedded contractor logistics support. Michigan-based Oshkosh Corporation and Virginia-centered General Dynamics facilities concentrate tracked and wheeled platform final assembly capacity.
Germany
KNDS and Rheinmetall AG leverage captive steel-forging and armor-package production to control cost curves across European modernization programs. The EU Green Deal's industrial emissions framework mandates scope 1-3 carbon footprint disclosure for defense industrial base suppliers bidding into European Development Fund vehicle programs. Bavarian and North Rhine-Westphalian industrial clusters host integrated armor plate production and hybrid-electric powertrain development facilities.
Poland
Accelerated mechanized brigade expansion under the Homar and Borsuk programs creates near-term volume demand for domestic and licensed production. NATO STANAG 4569 modernization cycles and sovereign content rules tie manufacturing workshare to in-country maintenance infrastructure commitments. Silesian and Podkarpackie voivodeships concentrate armored vehicle assembly and subsystem supplier networks.
Turkey
SSB offset requirements and domestic production expansion create captive demand for indigenous wheeled APC exports to Central Asian and African operators. Turkish land-systems integrators qualify 6x6 and 8x8 hull configurations for interior ministry fleets across Southeast Asia and the Middle East. Sakarya and Ankara industrial zones anchor Otokar and FNSS Savunma Sistemleri production and export logistics.
South Korea
Hyundai Rotem and domestic suppliers expand mechanized unit modernization for indigenous defense requirements and selective export positioning. The country's national defense procurement agency implicates sovereign production mandates and technology transfer conditions on licensed foreign designs. Changwon and Gyeonggi-do manufacturing complexes concentrate final assembly and active protection system integration capacity.
Armoured Personnel Carrier (APC) Market Competitive Environment
Global majors compete with regional champions across platform architecture and sovereign production mandates, creating a tiered structure where scale-driven integrators coexist with specialization-focused national champions. Consolidation concentrates around steel-forging and armor-package production, while fragmentation persists in active protection subsystem supply. Three archetypes dominate: vertically integrated European land-systems houses, export-driven Turkish wheeled-platform specialists, and US primes anchoring allied supplier ecosystems through NGCV specification alignment. Competitive moves center on hybrid-electric powertrain partnerships and 25-year through-life support contract capture.
Within the European integrated tier, Rheinmetall AG and KNDS exemplify the steel-forging-to-final-assembly model that controls cost curves across NATO modernization programs. BAE Systems occupies a position as a sovereign-contract anchor through British Army Boxer and Ajax program embeddedness. Among export-driven specialists, Otokar Otomotiv ve Savunma Sanayi A.Ş. represents the licensed-production and wheeled-platform archetype serving Central Asian and African operators under Turkish SSB frameworks.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| Rheinmetall AG |
| BAE Systems |
| Otokar Otomotiv ve Savunma Sanayi A.Ş. |
| Patria Oyj |
| KNDS |
| Oshkosh Corporation |
| Lockheed Martin Corporation |
| FNSS Savunma Sistemleri A.Ş. |
| Others |
Value Chain & Pricing Dynamics
Specialized armor-forging technicians in Düsseldorf and Silesia command wage premiums that compress pricing spreads between STANAG-certified premium hulls and lower-tier export configurations. Labor-cost differentials between German integrated producers and Polish licensed-assembly facilities widen the gap between tracked heavy-brigade platforms and wheeled constabulary variants.
Pricing Analysis
Input-cost pass-through from nickel and boron carbide volatility shapes contract structures across armor-package procurement. Three-tier pricing structure across premium, standard, and economy levels separates STANAG 4569 Level 6 tracked platforms from Level 4 wheeled exports and surplus refurbished hulls. Pricing pressure stems from EU Green Deal emissions compliance costs embedded in green steel qualification. Government defense ministries show lowest price sensitivity due to sovereign-content mandates, while private security operators exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with German and Austrian tracked-suspension forging clusters that anchor NATO heavy-mechanized programs. Raw material dependencies center on Ukrainian and Russian-origin steel feedstock, South Korean silicon carbide substrates, and Chinese rare-earth magnet supply for hybrid-electric powertrains. Tariff exposure runs through EU carbon-border adjustment mechanisms on imported armor plate. Distribution runs through prime-integrator direct contracts with national procurement agencies, supplemented by Turkish SSB-licensed export channels to Central Asian operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through captive steel-forging integration and 25-year through-life support contract capture. Hybrid-electric drivetrain standardization creates premium-tier pricing power for silent-running certified platforms.
For Market Incumbents: Deepen captive armor-plate production to offset REACH compliance friction around ceramic matrix composites. Add forging capacity in Poland's Podkarpackie voivodeship to hedge German cluster concentration risk. Lock in 25-year availability guarantees before STANAG 4569 Level 7 certification raises barrier thresholds. For New Entrants and Emerging Players: Begin with medical evacuation modular kits under NATO Role 2 field hospital standards, where qualification timelines compress versus full combat platforms. Target law enforcement wheeled configurations for Southeast Asian interior ministry fleets. Pursue subsystem supply partnerships with Turkish SSB-licensed exporters rather than prime-integrator competition. For Investors and Strategic Acquirers: Defense primes with embedded contractor logistics support are the most active acquirer in this space. Five-to-ten-year viability hinges on hybrid-electric plus active protection convergence patents. Target mid-tier armor-package specialists with ECHA pre-qualification status. Watch for EU Green Deal scope 3 disclosure mandates triggering consolidation among non-compliant forging operations.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Powertrain Partnership | Rheinmetall's silent-running battery-thermal management meets NATO urban warfare requirements. |
| Backward Integration into Steel Forging | KNDS captive green steel sourcing secures EU Green Deal procurement eligibility. |
| 25-Year Through-Life Support Contract | British Army Boxer program embeds contractor logistics at platform level. |
| Active Protection Subsystem Licensing | Hard-kill interceptor miniaturization opens new subsystem categories for medium-weight APCs. |
| SSB-Licensed Export Channel Development | Otokar's Central Asian operator networks bypass NATO prime competition. |
Study Parameters
Coverage spans NATO member states, Turkey, South Korea, and selective Central Asian operators, with primary inputs from each. Defense procurement officers, land-systems program managers, armor-package engineering leads, and SSB export licensing officials provided structured interviews. Secondary validation drew from NATO STANAG documentation, EU ECHA substance authorization databases, national defense white papers, and customs trade records for armored vehicle hull classifications. Bottom-up platform deployment forecasts triangulated against top-down defense budget appropriation analysis.
Rate-of-change decomposition separated vehicle-type mix shifts, protection-level upgrades, and powertrain technology transitions across the modeling period. Segmentation dimensions modeled include mobility configuration, mission application, protection architecture tier, and end-user contracting authority. CAGRs derived from polynomial trend fitting against historical procurement cycles, with industry-specific inputs incorporating NATO STANAG modernization wave timing and EU Green Deal compliance phase-in schedules.
Caveats apply where REACH authorization delays, nickel supply disruptions, or sovereign-content rule changes could materially shift the outlook. Forecasts embed assumptions around STANAG 4569 certification timeline stability and hybrid-electric battery pack cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Armored Vehicles
Armored Vehicle Navigation Systems Market
Armored Vehicles
Global Ceramic Armor Market
Armored Vehicles
Armored Vehicles Upgrade and Retrofit Market
Armored Vehicles
Middle-East and Africa Armored Vehicles Market
Armored Vehicles
Armor Protection Systems Market
Armored Vehicles
Europe Armored Fighting Vehicles Market
Armored Vehicles
Armored Personnel Carrier Market
Armored Vehicles
Armored Vehicles Market
Armored Vehicles
Asia-Pacific Armored Fighting Vehicles Market
Armored Vehicles
Armored Vehicle Fire Suppression Systems Market
Armored Vehicles
Boom Arms Market
Armored Vehicles
North America Armored Fighting Vehicles Market
Armored Vehicles
Armored Fighting Vehicles Market
Armored Vehicles
Military Armored Car Market
Armored Vehicles
US Armored Vehicle Market
Armored Vehicles
Armored Vehicle Procurement and Upgrade Market