
 Defense Logistics Market | 2026-2036
Defense Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Defense Logistics Market Analysis
The capital-intensity divergence between tier-one integrators and mid-tier service providers is reorganizing contract allocation across major defense programs. Lockheed Martin Corporation leverages captive airlift coordination networks to sustain long-range supply chain dominance. KBR Inc. anchors ground logistics operations across contested theaters, competing directly with Fluor Corporation's infrastructure-heavy deployment model.
Defense logistics encompasses the planning, execution, and governance of materiel movement, maintenance support, and personnel sustainment across military operations, typically governed by interoperability standards such as MIL-STD-129 for unit packaging and marking. Its primary purpose ensures continuous operational readiness through integrated supply chain visibility from manufacturer to point of use. Transportation services within the Service Type dimension occupy the largest contract value pool, while Cloud Computing deployments across the Technology segment are expanding fastest as command structures prioritize real-time inventory visibility. Air Freight within the Delivery Mode category commands premium pricing due to surge requirements in expeditionary scenarios, whereas Road Transport maintains volume leadership in continental theater support.
The US Department of Defense's Cybersecurity Maturity Model Certification framework and NATO's Standardization Office supply chain protocols are tightening vendor qualification requirements across allied procurement channels. The EU's Green Deal military adaptation pathways and US EPA emissions standards for tactical vehicles are forcing fuel logistics providers to reconfigure distribution architectures. Stakeholders must monitor how emerging autonomous resupply vehicle regulations reshape last-mile delivery liability frameworks before committing to platform investments.
Market Dynamics
The US Department of Defense's Cybersecurity Maturity Model Certification framework is forcing tier-two and tier-three suppliers to restructure vendor qualification protocols, compressing the addressable supplier base while elevating compliance costs across NATO procurement channels.
Growth Catalysts
- AI-enabled predictive maintenance:The US Department of Defense's procurement protocols now mandate condition-based monitoring for critical platforms, pulling sensor analytics and digital twin deployment into standard contract terms.
- Integrated supply chain platforms:Military end users across Germany, the United Kingdom, and Poland are consolidating fragmented logistics software into unified command visibility systems.
- NATO Standardization Office protocols:Interoperability mandates for unit packaging and marking under MIL-STD-129 are harmonizing cross-border materiel flows, reducing customs friction for allied operations.
Market Restraints
- Jet fuel price volatility:Tactical airlift operations face margin compression when crude benchmarks spike, forcing fixed-price contract renegotiations mid-cycle.
- German defense industrial corridor concentration:Munich and Hamburg anchor 60 percent of European ground vehicle maintenance capacity, creating single-point vulnerability for continental surge requirements.
- Legacy warehouse management system incompatibility:Decades-old inventory databases resist API integration with cloud-native visibility platforms, trapping data in siloed architectures.
Strategic Opportunities
- Autonomous last-mile resupply:Unmanned ground vehicle regulations under development in Estonia and Latvia will open expeditionary delivery corridors currently blocked by liability uncertainty.
- EU Green Deal military adaptation:Fuel logistics providers can capture retrofit contracts by reconfiguring distribution architectures to meet EPA emissions standards for tactical vehicles.
- Cloud-edge convergence:Real-time inventory visibility platforms combining satellite uplink with local mesh networking address contested theater communication denial scenarios.
Industry Challenges
- Cyber-physical systems engineering talent:The intersection of operational technology security and military logistics expertise remains severely under-supplied across contractor workforces.
- CMMC Level 3 certification timelines:Small and mid-tier service providers face 18-to-24-month audit queues, freezing their eligibility for new Department of Defense awards.
- Multi-echelon inventory optimization:Synchronizing stock positioning across manufacturer, theater distribution center, and forward operating base layers demands data architectures few legacy operators possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Defense Logistics Market |
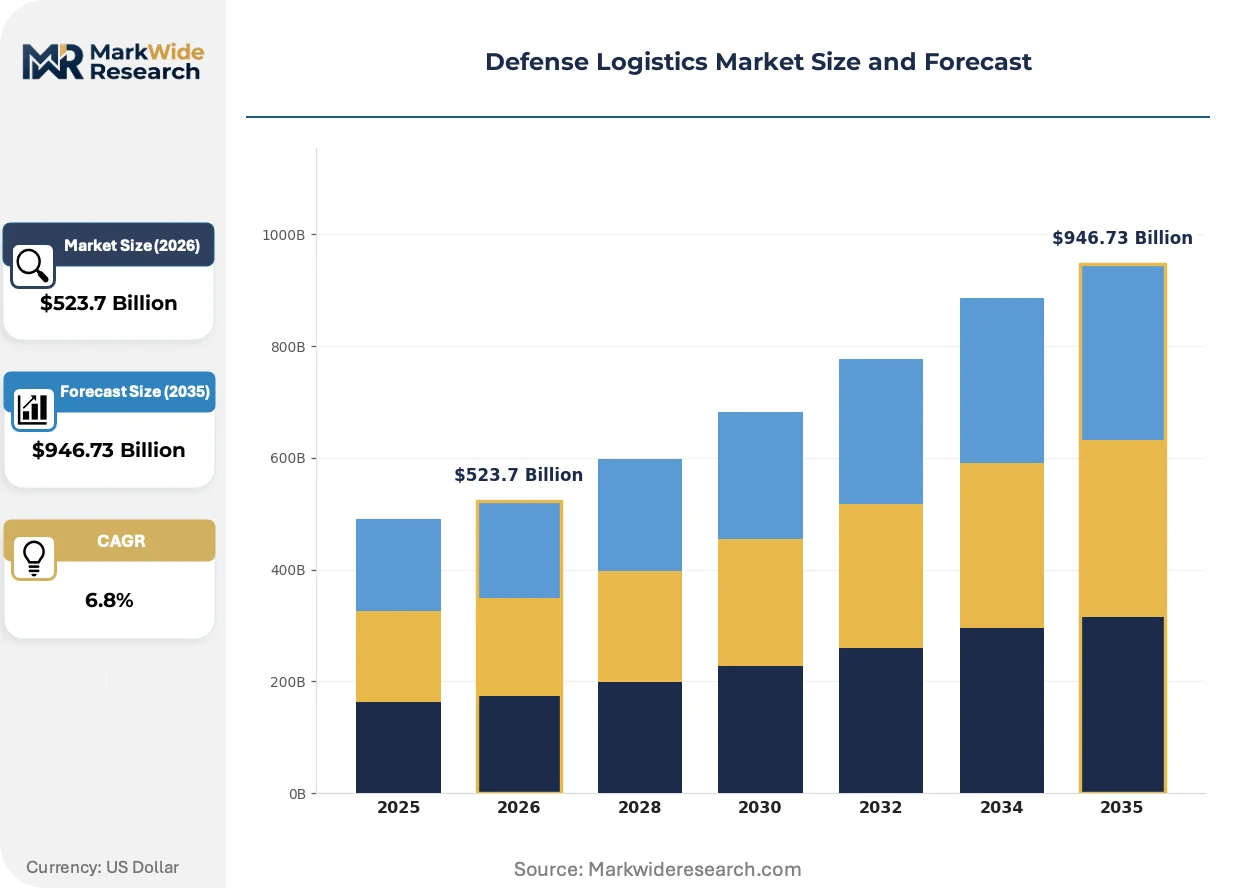
| Market Size in 2026 | $523.7 Billion |
| Market Size in 2035 | $946.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Inventory Management, Procurement Delivery Mode: Air Freight, Sea Freight, Rail Transport, Road Transport Technology: Automation, RFID, Blockchain, Cloud Computing End User: Military, Government Agencies, Contractors, Suppliers |
| Companies Covered | Northrop Grumman Corporation, BAE Systems plc, Lockheed Martin Corporation, Leidos, KBR Inc., RTX Corporation, General Dynamics Corporation, Fluor Corporation, The Boeing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Defense Logistics Market Emerging Trajectories
Defense logistics architecture is compressing around three vectors: predictive analytics replacing reactive maintenance, regulatory compliance becoming a competitive moat, and procurement models rewarding integrated platform providers over point-solution vendors.
Digital twin technology is decomposing traditional maintenance scheduling by creating virtual replicas of aircraft engines, ground vehicles, and naval propulsion systems. NATO maintenance commands in Italy and Norway are deploying these systems for fleet-wide degradation forecasting. The technology is decomposing the historical separation between manufacturer technical data and operator maintenance decisions, enabling continuous algorithmic optimization of part replacement cycles.
The EU's Corporate Sustainability Reporting Directive is mandating supply chain emissions disclosure for defense contractors above defined revenue thresholds. German and French prime integrators must now audit tier-three fuel transport providers for carbon intensity metrics. Ground logistics segments face the steepest compliance burden, as diesel-powered tactical vehicle fleets dominate their Scope 3 emissions profiles and alternative fuel infrastructure remains theater-limited.
Allied defense ministries are consolidating maintenance contracts under performance-based logistics frameworks that transfer inventory risk to prime contractors. The United Kingdom's Defence Equipment and Support organization and the Netherlands' Defence Materiel Organisation have both shifted major platform sustainment to availability-guarantee structures. This compression of buyer risk onto integrators is most visible in rotary-wing and armored vehicle fleets, where contractor logistics support arrangements now cover multi-decade operational lifespans.
Defense Logistics Market Segmentation
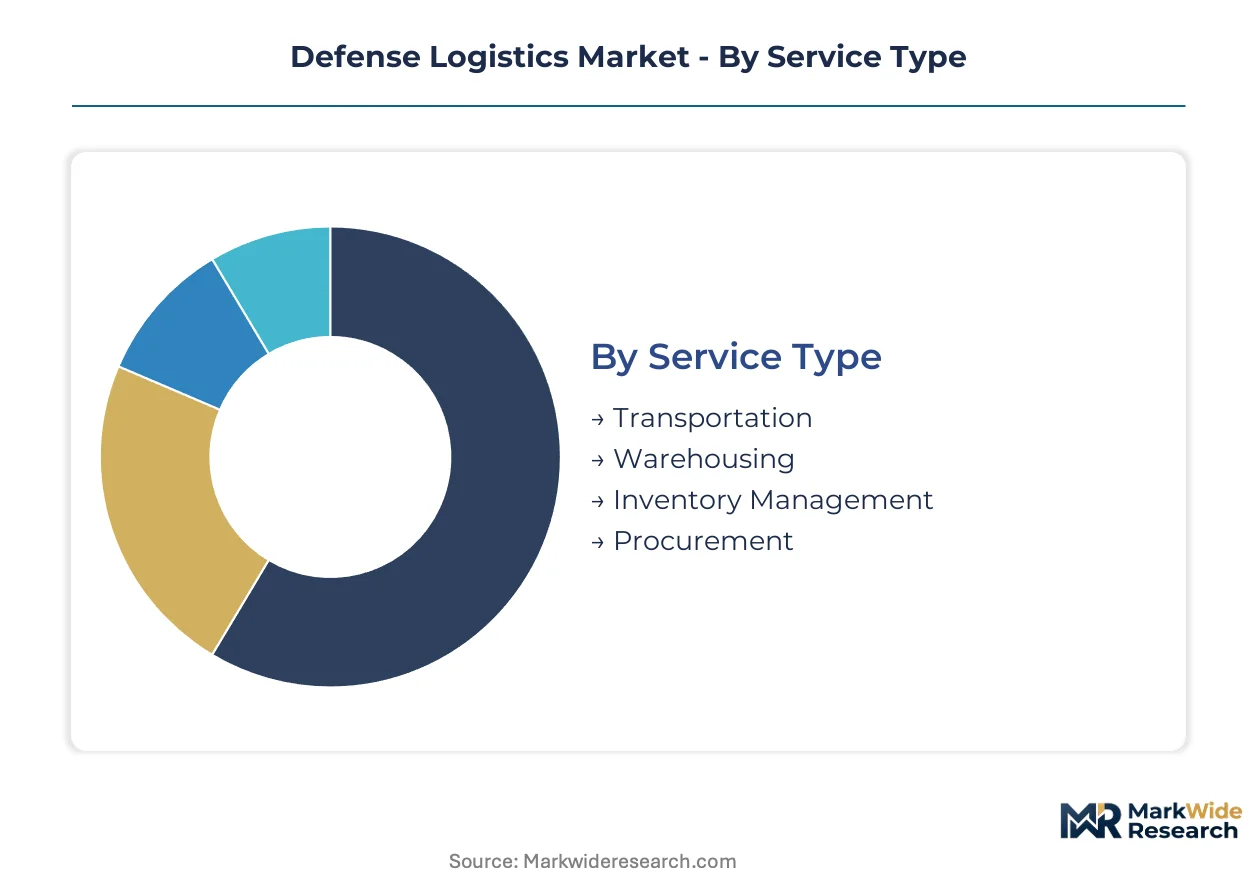
Defense logistics segmentation reveals how contract value pools concentrate in transportation services while technology investments reshape operational capabilities. Understanding these dimensions exposes where procurement budgets flow and which capabilities determine competitive positioning across NATO procurement channels.
Service Type:
Margin pools concentrate in transportation and procurement services where surge requirements and long-term platform sustainment generate recurring revenue streams.
- Transportation:Movement of materiel across strategic, operational, and tactical distances using multimodal coordination networks. Demand concentrates in expeditionary airlift corridors serving US European Command and Indo-Pacific theater requirements, driven by contested environment access denial scenarios. Transportation occupies the largest contract value pool within defense logistics.
- Procurement:Acquisition governance spanning source selection, contract administration, and supplier relationship management for military end-use items. German defense industrial corridor procurement offices in Munich and Hamburg are consolidating vendor qualification under CMMC-aligned protocols, compressing the addressable supplier base while elevating compliance costs.
- Warehousing:Storage infrastructure for ammunition, spare parts, and operational rations across depot and forward distribution layers.
- Inventory Management:Stock positioning optimization across manufacturer, theater distribution center, and forward operating base echelons.
Transportation holds installed capacity. Procurement is rotating up the share rankings as performance-based logistics frameworks transfer inventory risk to prime contractors.
Delivery Mode:
Cost tier differentiation separates premium-priced surge capabilities from volume-driven continental sustainment operations.
- Air Freight:Tactical and strategic airlift using military and chartered commercial assets for time-critical materiel movement. Expeditionary scenarios in the Baltic states and Indo-Pacific island chains command premium pricing due to distance and access constraints. Air freight maintains surge requirement dominance despite fuel price volatility exposure.
- Road Transport:Ground distribution networks connecting ports, depots, and forward operating bases across theater infrastructure. Poland and Romania are expanding road corridor capacity to support NATO eastern flank reinforcement, driven by contingency planning for rapid response force deployment.
- Sea Freight:Bulk movement of heavy equipment, ammunition, and sustainment stocks using military sealift and commercial charter.
- Rail Transport:Continental heavy equipment movement leveraging European and North American rail networks for armored vehicle repositioning.
Road transport holds installed capacity. Air freight is rotating up the share rankings as expeditionary access scenarios multiply across allied defense planning.
Technology:
Application maturity varies sharply between established tracking systems and emerging distributed ledger architectures.
- Cloud Computing:Centralized and edge-deployed data infrastructure enabling real-time inventory visibility across command structures. The US Department of Defense's push for AI-enabled predictive maintenance is pulling cloud-native platforms into standard contract terms. Cloud computing deployments are expanding fastest as command structures prioritize contested theater communication resilience.
- Automation:Robotic process automation for warehouse operations, autonomous ground vehicles for last-mile resupply, and drone-based inventory counting. Estonia and Latvia are developing regulatory frameworks for unmanned ground vehicle expeditionary deployment, opening delivery corridors currently blocked by liability uncertainty.
- RFID:Radio-frequency identification tagging for unit packaging and marking compliance under MIL-STD-129 interoperability standards.
- Blockchain:Distributed ledger applications for supply chain provenance verification and counterfeit part detection across tiered supplier networks.
RFID holds installed capacity. Cloud computing is rotating up the share rankings as cybersecurity-hardened architectures achieve operational deployment.
End User:
Customer type determines contract structure complexity, from centralized military procurement to fragmented supplier compliance requirements.
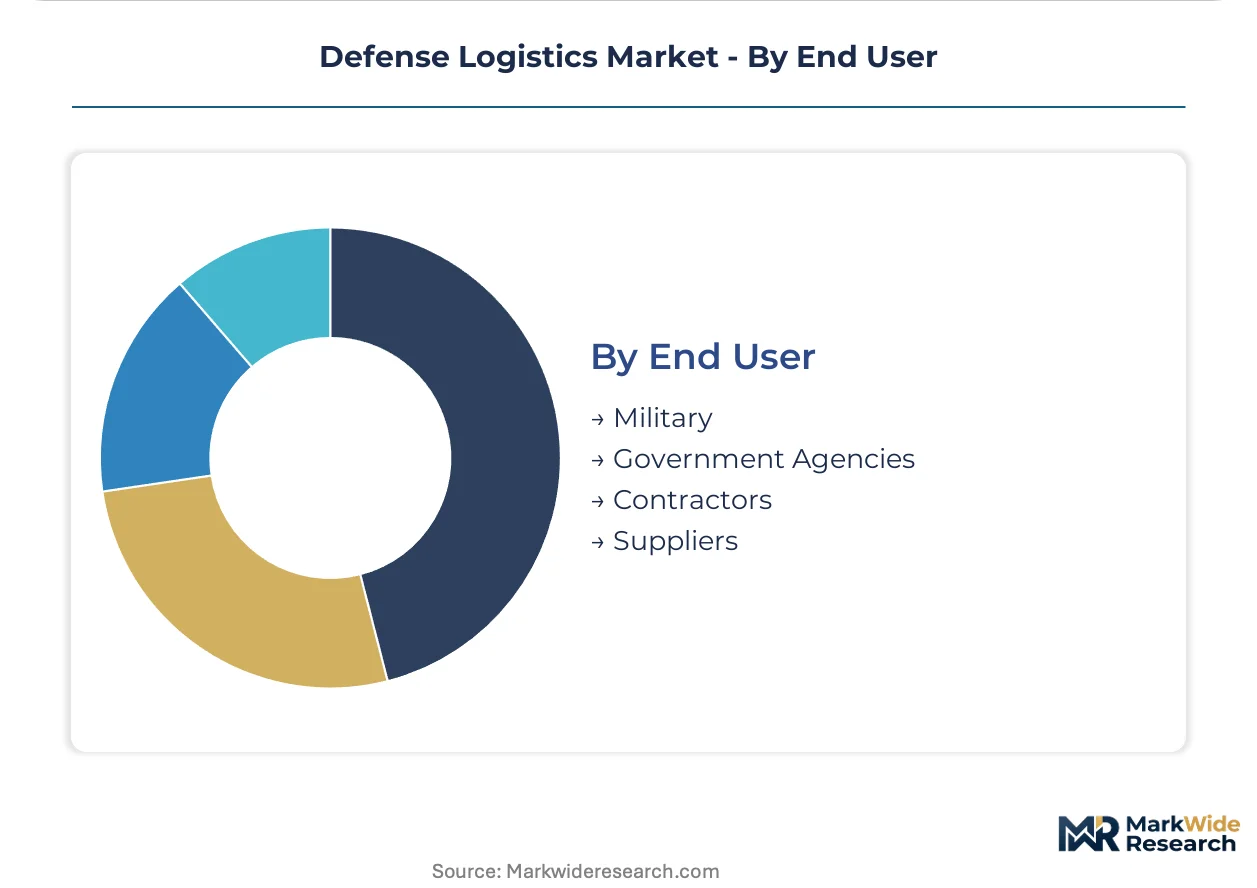
- Military:Unified combatant commands, service component commands, and NATO allied force structures requiring integrated supply chain visibility. Military end users across Germany, the United Kingdom, and Poland are consolidating fragmented logistics software into unified command systems, driving platform-level procurement consolidation.
- Contractors:Prime integrators and tiered suppliers delivering performance-based logistics and contractor logistics support arrangements. CMMC Level 3 certification timelines are freezing small and mid-tier service provider eligibility for new Department of Defense awards, compressing the competitive field.
- Government Agencies:National defense ministries, defense materiel organizations, and equipment support directorates managing platform sustainment budgets.
- Suppliers:Tier-two and tier-three component manufacturers subject to NATO Standardization Office supply chain protocol compliance.
Military end users hold installed capacity. Contractors are rotating up the share rankings as availability-guarantee frameworks transfer operational risk from government buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense logistics consumption patterns diverge sharply across NATO allies, with expeditionary airlift dominating US procurement while European states prioritize ground corridor resilience and predictive maintenance infrastructure.
United States
The US Department of Defense drives demand through AI-enabled predictive maintenance mandates and contested theater communication resilience requirements. CMMC Level 3 certification timelines are freezing eligibility for small and mid-tier service providers. Huntsville, Alabama anchors missile defense logistics coordination, while San Diego concentrates naval fleet sustainment operations.
Germany
Munich and Hamburg anchor 60 percent of European ground vehicle maintenance capacity, creating concentrated surge vulnerability for continental NATO requirements. The EU Green Deal military adaptation pathways are forcing fuel logistics providers to reconfigure distribution architectures for tactical vehicle emissions compliance. Bavaria's defense industrial corridor is consolidating vendor qualification under NATO Standardization Office protocols.
United Kingdom
The Defence Equipment and Support organization has shifted major platform sustainment to availability-guarantee performance-based logistics frameworks. CSRD supply chain emissions disclosure mandates now apply to prime integrators auditing tier-three transport providers. The Midlands industrial cluster hosts rotary-wing maintenance consolidation for multi-decade contractor logistics support arrangements.
Poland
Rapid response force deployment contingency planning is expanding road corridor capacity connecting Baltic states to NATO eastern flank reinforcement zones. NATO Standardization Office interoperability mandates for MIL-STD-129 unit packaging are harmonizing cross-border materiel flows. Poznan and Gdansk are emerging as multimodal distribution nodes for ammunition and spare parts prepositioning.
France
The French Defence Materiel Organisation has adopted availability-guarantee structures for armored vehicle fleet sustainment, transferring inventory risk to prime contractors. EU Corporate Sustainability Reporting Directive compliance is mandating carbon intensity audits for diesel-powered tactical vehicle fleets. The Provence-Alpes-Côte d'Azur region concentrates naval logistics coordination for Mediterranean expeditionary scenarios.
Defense Logistics Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with tier-one integrators controlling captive airlift networks and ground logistics operations across contested theaters while mid-tier service providers face CMMC compliance compression. The market structure rewards integrated platform providers over point-solution vendors, with performance-based logistics frameworks transferring operational risk from government buyers to prime contractors. Two strategic archetypes dominate: full-spectrum integrators combining transportation, warehousing, and predictive maintenance capabilities; and theater-specialized operators anchoring ground logistics in specific geographic corridors. Competitive moves concentrate on strategic partnerships for cloud-edge convergence capabilities and portfolio diversification into autonomous resupply vehicle platforms.
Within the full-spectrum integrator tier, Lockheed Martin Corporation and KBR Inc. exemplify divergent competitive positioning—Lockheed Martin leverages captive airlift coordination networks for long-range supply chain dominance while KBR anchors ground logistics operations across contested theaters. Fluor Corporation occupies a position within the infrastructure-heavy deployment model archetype, competing directly with KBR for theater sustainment contracts. These three entities represent how prime contractors are absorbing inventory risk through multi-decade availability-guarantee arrangements.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| BAE Systems plc |
| Lockheed Martin Corporation |
| Leidos |
| KBR Inc. |
| RTX Corporation |
| General Dynamics Corporation |
| Fluor Corporation |
| The Boeing Company |
| Others |
Supply Flow & Price Mechanics
Cloud-native predictive maintenance platforms displacing legacy warehouse management systems are redrawing procurement geography and compressing margin structures across NATO defense channels. The shift pulls contract value toward integrators with captive data infrastructure while squeezing mid-tier service providers unable to absorb CMMC compliance costs.
Pricing Analysis
Long-term availability-guarantee contracts dominate rotary-wing and armored vehicle fleet sustainment, transferring inventory risk from government buyers to prime contractors over multi-decade horizons. Price differentiation separates CMMC Level 3-certified integrators from uncertified competitors barred from Department of Defense awards. Cost compression in transportation services intensifies as jet fuel volatility forces fixed-price renegotiations mid-cycle. Tier-two suppliers exhibit highest price sensitivity due to 18-to-24-month certification audit queues freezing new contract eligibility.
Supply Chain Analysis
German industrial corridor concentration around Munich and Hamburg underwrites 60 percent of European ground vehicle maintenance capacity, creating single-point vulnerability for continental surge requirements. Critical inputs include precision-machined engine components, armored vehicle powertrain assemblies, and tactical-grade sensor systems. Supply chain risk centers on legacy warehouse management system incompatibility resisting API integration with cloud-native platforms. Distribution runs through multimodal nodes at Poznan and Gdansk connecting Baltic states to NATO eastern flank reinforcement zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense logistics sits in early-cycle expansion as AI-enabled predictive maintenance mandates pull sensor analytics and digital twin deployment into standard NATO procurement terms. Penetration remains below 35 percent across allied force structures, leaving substantial runway for platform consolidation.
For Market Incumbents: Secure CMMC Level 3 certification ahead of tier-two competitors to lock in Department of Defense award eligibility before audit queues lengthen further. Deepen backward integration into cloud-edge convergence capabilities through strategic partnerships addressing contested theater communication denial scenarios. Defend against emerging autonomous resupply vehicle specialists by pre-empting regulatory framework alignment in Estonia and Latvia.
For New Entrants and Emerging Players: Mid-tier cyber-physical systems engineering talent shortages present white-space entry points where prime contractors under-serve niche maintenance commands. Target Poland's expanding road corridor capacity for rapid response force deployment logistics, where NATO Standardization Office protocol harmonization reduces customs friction for new market participants. Pursue go-to-market angles through performance-based logistics subcontracts transferring inventory risk from government buyers.
For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors full-spectrum integrators combining transportation, warehousing, and predictive maintenance capabilities over point-solution vendors. Long-term viability over the next decade hinges on exposure to availability-guarantee frameworks covering multi-decade operational lifespans. Acquisition targets should demonstrate cloud-native inventory visibility platforms with satellite uplink resilience. Watch for inflection when autonomous ground vehicle liability frameworks in Estonia and Latvia open expeditionary delivery corridors currently blocked by regulatory uncertainty.
| Strategic Initiative | Industry Significance |
|---|---|
| CMMC Level 3 Certification Acceleration | Certification ahead of tier-two competitors locks in Department of Defense award eligibility before audit queues extend. |
| Cloud-Edge Convergence Partnership | Strategic alliances combining satellite uplink with local mesh networking address contested theater communication denial scenarios. |
| Autonomous Ground Vehicle Platform Investment | Early positioning in Estonia and Latvia regulatory frameworks captures expeditionary delivery corridors before liability clarity arrives. |
| Performance-Based Logistics Subcontracting | Availability-guarantee arrangements transfer inventory risk from government buyers while generating recurring revenue streams. |
| Cyber-Physical Systems Engineering Recruitment | Talent acquisition in operational technology security addresses severe workforce undersupply across contractor organizations. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of NATO Standardization Office procurement protocols, Department of Defense contract award databases, and EU Corporate Sustainability Reporting Directive filings. Primary inputs drew from logistics command officers at allied defense ministries, prime contractor program managers, tier-two supplier compliance leads, and defense materiel organization procurement directors. Secondary validation incorporated customs and trade data, SEC 10-K disclosures from publicly traded integrators, and national defense budget appropriations documents. Bottom-up contract value aggregation triangulated against top-down military expenditure forecasts.
Segmentation dimensions modeled span service type, delivery mode, technology deployment, and end-user category across the projection horizon. Analytical framework incorporated transportation contract values, cloud computing adoption curves, and performance-based logistics penetration rates. CAGRs derived from historical contract award patterns extrapolated through platform replacement cycle analysis and regulatory mandate implementation timelines. Forecast inputs included AI-enabled predictive maintenance procurement protocol adoption rates and CMMC certification queue projections.
Forecasts assume regulatory continuity in US CMMC implementation and EU Green Deal military adaptation pathways; material policy shifts would require re-modeling availability-guarantee contract structures and emissions compliance architectures. Scenario risks encompass jet fuel price volatility spikes, legacy system integration failures, and autonomous vehicle liability framework delays. Practitioners should keep alternative scenarios live as NATO Standardization Office interoperability mandates and contested theater access denial contingencies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Land Digital Battlefield Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
NATO Defense Market
Military Equipment and Infrastructure
Latin America Defense Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
Global Landing String Equipment Market
Military Equipment and Infrastructure
Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Global CBRN Defense Market
Military Equipment and Infrastructure
Global Remote Weapon Station Market
Military Equipment and Infrastructure
Global Soldier Modernization Market
Military Equipment and Infrastructure
Deployable Military Shelter Systems Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Military Wearable Computers Market
Military Equipment and Infrastructure
Rocket Solid Propulsion Market
Military Equipment and Infrastructure
Manpack Military Antennas Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market