
 Rubber Tracks for Defense and Security Market | 2026-2036
Rubber Tracks for Defense and Security Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Tracks for Defense and Security Market Analysis
Market Context
Maintenance and lifecycle service contracts is rebalancing how defense procurement officials evaluate total cost of ownership for rubber track systems. Soucy International leverages its integrated manufacturing footprint across North America to sustain long-term supply agreements with prime vehicle integrators. Rheinmetall AG anchors European demand through its dominance in tracked combat vehicle platforms and captive track sourcing strategies.
Technical Definition and Segments
Rubber tracks for defense and security are continuous-band propulsion systems comprising steel cable reinforcements embedded in elastomer compounds, engineered to distribute ground pressure below 70 kPa for tactical mobility across soft terrain. Heavy-duty tracks occupy the largest value share due to their specification for main battle tanks and infantry fighting vehicles, while adaptive systems technology is expanding fastest as militaries demand variable stiffness for mixed-terrain deployment. Lightweight tracks concentrate margin pools in special operations and airborne-insertible vehicle segments where weight thresholds dictate procurement decisions.
Regulatory Framework
REACH chemical restrictions in Europe and EPA environmental compliance in the United States are reshaping elastomer formulation requirements for defense track manufacturers. NATO standardization agreements and ISO quality certifications govern interoperability and durability benchmarks that determine market access for component suppliers. Stakeholders must monitor evolving military sustainability mandates that will progressively link procurement eligibility to verified supply chain carbon footprints and recyclability protocols.
Market Dynamics
Vehicle modernization programs across NATO militaries are compressing procurement cycles for rubber track systems, forcing suppliers to align R&D timelines with platform upgrade schedules rather than traditional replacement cycles.
Growth Catalysts
- REACH chemical compliance:European defense procurement rules now mandate verified elastomer formulations, creating technical barriers that favor established compounders with certified supply chains.
- Armored personnel carrier fleets:Militaries in Germany, France, and the United States are retiring legacy wheeled platforms for tracked alternatives that demand higher-durability rubber track specifications.
- Steel-cable reinforcement advances:Embedded cable geometries now enable 40% longer service intervals, reducing lifecycle costs for maintenance-constrained defense budgets.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply disruptions transmit directly to compound costs, compressing margins for non-integrated manufacturers.
- Single-source supply concentration:Germany and the United States host the only qualified steel-cable weavers meeting NATO ballistic protection standards.
- EPF substitution threat:Enhanced polymer foams for wheeled vehicle run-flat systems compete for soft-terrain mobility budgets in light tactical vehicle segments.
Strategic Opportunities
- Special operations vehicle niche:Airborne-insertible platforms in the United States and United Kingdom require sub-500kg track systems where lightweight compound expertise commands premium positioning.
- EU Green Deal circularity mandates:Upcoming defense procurement rules will prioritize recyclable track architectures, rewarding early investment in thermoplastic elastomer alternatives.
- Predictive maintenance integration:Embedded sensor networks converging with IoT telemetry enable condition-based replacement contracts that lock in long-term supplier relationships.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for military-grade elastomers concentrates among retiring specialists, constraining R&D velocity for new entrants.
- ISO 9001 certification timelines:Defense track qualification requires 18-24 month validation cycles that delay revenue recognition for platform-specific contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Tracks for Defense and Security Market |
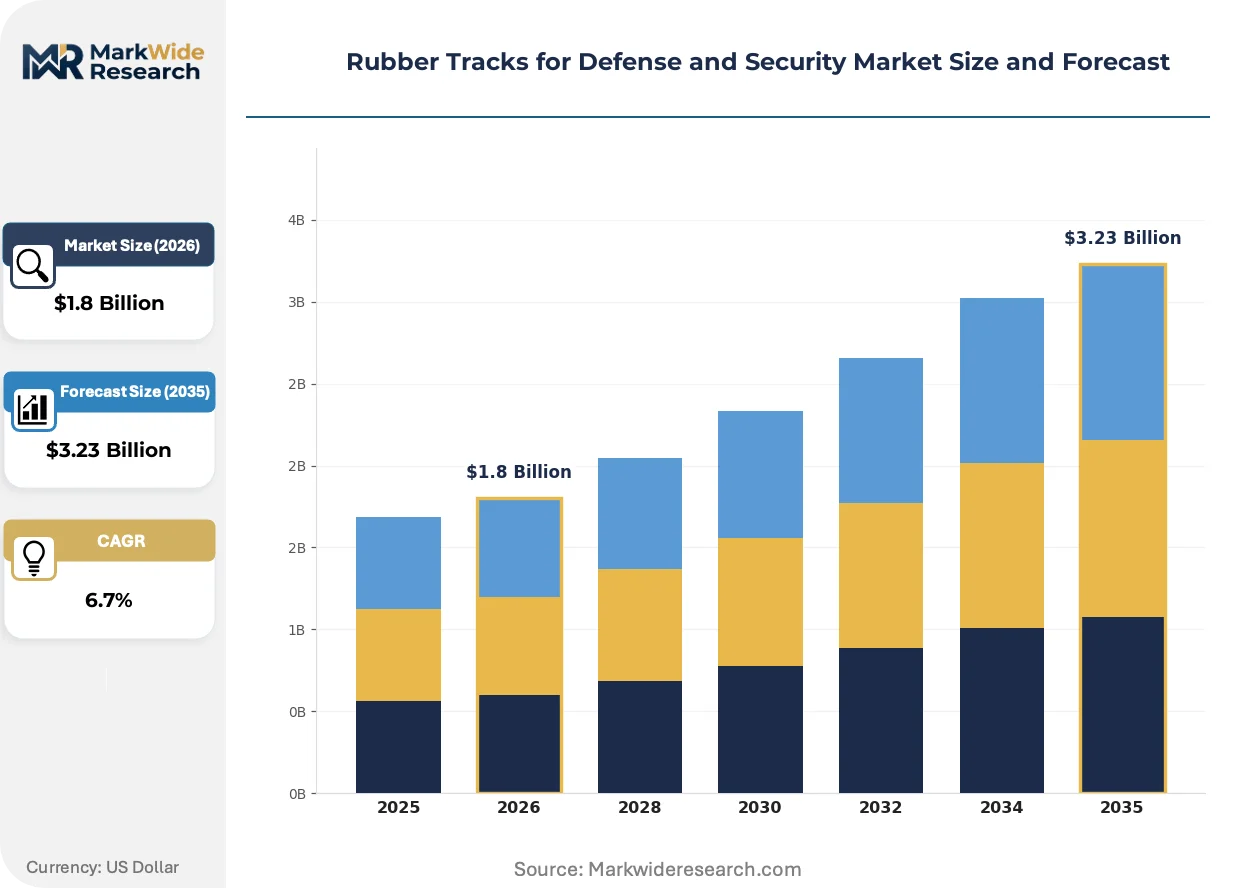
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-duty Tracks, Lightweight Tracks, Specialty Tracks, Agricultural Tracks End User: Military Vehicles, Armored Personnel Carriers, Defense Contractors, Research Institutions Technology: Rubber Composition, Traction Enhancement, Adaptive Systems, Noise Reduction Application: Terrain Navigation, Logistic Support, Surveillance Operations, Tactical Mobility |
| Companies Covered | Diehl Defence, Soucy International, Michelin, Bridgestone Corporation, Continental AG, William Cook Defence Systems, Rheinmetall AG, Camso, Trelleborg AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Tracks for Defense and Security Market Emerging Trajectories
Adaptive stiffness technology is redefining performance benchmarks for multi-terrain deployment, compressing the traditional trade-off between hard-surface speed and soft-ground flotation that has governed track design for decades.
Variable-durometer rubber compounds with embedded shape-memory alloys are consolidating discrete track categories into unified product architectures. Infantry fighting vehicle programs in France and the United States are specifying these systems for mixed-terrain deployment. This consolidation is compressing SKU counts and forcing compounders to prioritize modular manufacturing platforms over purpose-built production lines.
REACH authorization requirements for high-persistence chemicals are tightening elastomer ingredient disclosure rules across European defense supply chains. Compounders must now submit full substance inventories for track formulations used in German and French vehicle programs. Heavy-duty track segments face the steepest compliance costs as legacy formulations rely on restricted plasticizers and stabilizers.
Integrated lifecycle service contracts are displacing component-only procurement in tracked vehicle programs. Prime integrators in the United States now bundle track replacement, inspection, and logistics under multi-year availability agreements. This shift concentrates purchasing authority with vehicle OEMs and marginalizes standalone track suppliers without maintenance network capabilities.
Rubber Tracks for Defense and Security Market Segmentation
Defense procurement officials evaluate rubber track segments through divergent certification burdens and lifecycle cost models. Platform-specific requirements from NATO standardization agreements to national military specifications create tiered barriers that reshape supplier positioning across each category.
Product Type:
ISO 9001 and NATO STANAG certifications impose asymmetric compliance loads across product tiers, with main battle tank specifications demanding the most exhaustive validation protocols.
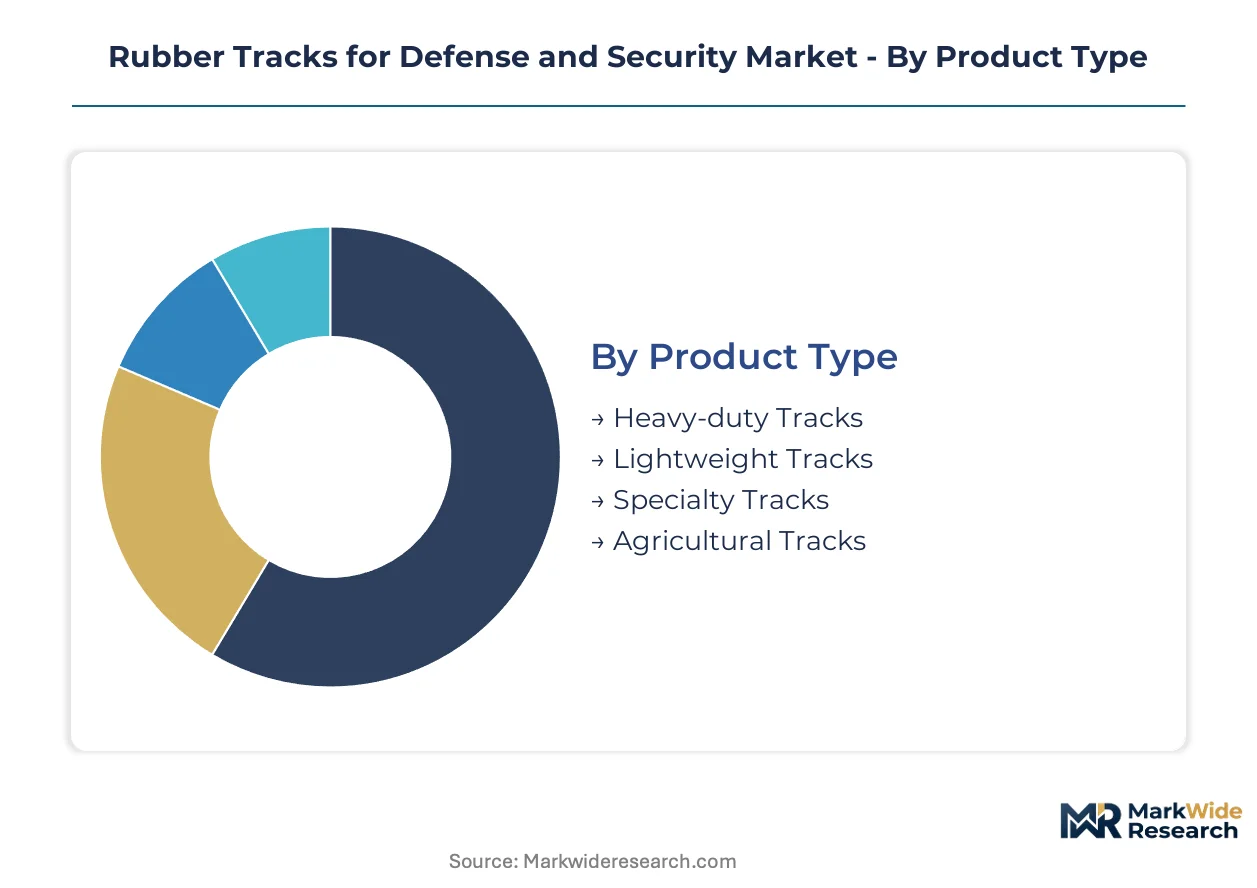
- Heavy-duty Tracks:Steel-cable reinforced elastomer bands rated for ground pressure distribution below 70 kPa on main battle tanks and infantry fighting vehicles. German and French armored vehicle programs concentrate procurement here, driven by platform modernization budgets and extended service interval requirements.
- Lightweight Tracks:Sub-500kg continuous-band systems using high-tensile synthetic reinforcements for airborne-insertible and special operations vehicles. United States and United Kingdom special forces procurement prioritizes these specifications where weight thresholds dictate platform eligibility.
- Specialty Tracks:Mission-configured variants for extreme climate or terrain profiles including arctic-grade compounds and desert-optimized tread geometries.
- Agricultural Tracks:Dual-use elastomer systems meeting both military logistics and civilian farming equipment specifications, common in reserve vehicle fleets.
Heavy-duty tracks sit at the top of the volume ranking, with lightweight tracks climbing the fastest.
End User:
Customer procurement authority concentrates with prime vehicle integrators, marginalizing component-only suppliers lacking integrated maintenance networks.
- Military Vehicles:National defense ministries and armed forces branches operating main battle tanks, infantry fighting vehicles, and self-propelled artillery. United States Army and German Bundeswehr procurement cycles drive specification evolution through platform upgrade schedules.
- Armored Personnel Carriers:Tracked troop transport fleets replacing legacy wheeled platforms across NATO militaries. France and Germany lead vehicle retirement programs, compressing replacement timelines for higher-durability track systems.
- Defense Contractors:Prime integrators and subsystem suppliers bundling track procurement into vehicle availability contracts.
- Research Institutions:National laboratories and military testing facilities evaluating next-generation elastomer formulations and adaptive stiffness architectures.
Armored personnel carriers command the steepest procurement acceleration, while military vehicles retain the largest installed base.
Technology:
REACH authorization requirements and EPA environmental compliance reshape R&D investment priorities across formulation and embedded systems categories.
- Rubber Composition:Elastomer compound engineering incorporating natural rubber, synthetic polybutadiene, and thermoplastic alternatives. ECHA restrictions on high-persistence plasticizers force reformulation investments for European defense suppliers.
- Adaptive Systems:Variable-durometer architectures with embedded shape-memory alloys enabling stiffness modulation across terrain types. Infantry fighting vehicle programs in France and the United States specify these for mixed-terrain deployment.
- Traction Enhancement:Tread pattern optimization and grouser geometry advances for specific soil and surface conditions.
- Noise Reduction:Acoustic signature suppression technologies for reconnaissance and special operations platforms where detectability determines mission success.
Rubber composition absorbs the largest R&D allocation, with adaptive systems gaining share fastest.
Application:
Mission profiles dictate divergent durability and performance specifications, from high-cycle logistics routes to low-probability tactical deployments.
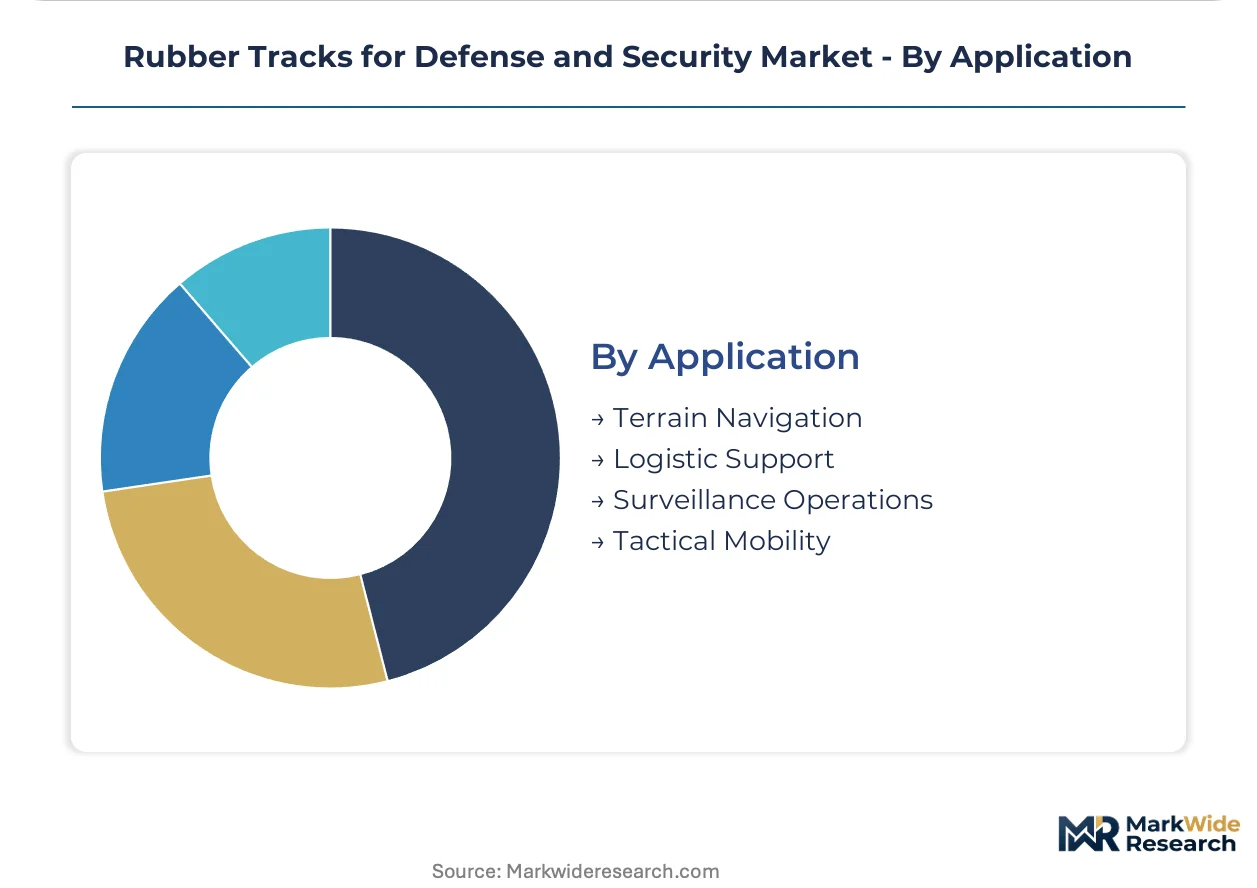
- Terrain Navigation:Soft-ground flotation and obstacle traversal for cross-country mobility. German and United States tracked vehicle procurement prioritizes these specifications for European and Indo-Pacific theater requirements.
- Tactical Mobility:Rapid position displacement and maneuver warfare support for frontline combat formations. NATO readiness initiatives concentrate investment here, linking track replacement to force generation timelines.
- Logistic Support:Supply route sustainment and rear-area transport with extended duty cycles and reduced maintenance windows.
- Surveillance Operations:Low-signature movement for reconnaissance platforms where acoustic and thermal emissions must be minimized.
Terrain navigation holds the broadest platform penetration, with tactical mobility expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States defense procurement cycles run faster than German platform modernization timelines, compressing supplier lead times on opposite sides of the Atlantic. Tracked vehicle demand concentrates where NATO readiness initiatives intersect with domestic manufacturing capabilities.
United States
Army Futures Command drives next-generation combat vehicle specifications through Detroit Arsenal and Redstone Arsenal testing corridors. EPA environmental compliance mandates now govern elastomer ingredient disclosure for defense contractors supplying Aberdeen Proving Ground programs. The Ohio-Michigan industrial corridor hosts steel-cable weavers qualifying for ballistic protection standards.
Germany
Bundeswehr platform retirement schedules accelerate replacement demand for higher-durability track systems on main battle tanks and infantry fighting vehicles. REACH authorization requirements from ECHA force reformulation of legacy plasticizers and stabilizers in heavy-duty compound production. The Bavaria-Rhineland cluster anchors captive track sourcing through Rheinmetall's integrated supply architecture.
France
SCORPION program modernization concentrates procurement authority with prime integrators bundling multi-year availability agreements. EU Green Deal circularity mandates from Brussels progressively link defense procurement eligibility to verified supply chain carbon footprints. The Auvergne-Rhône-Alpes region hosts formulation specialists adapting to thermoplastic elastomer alternatives.
United Kingdom
Special forces procurement for airborne-insertible platforms prioritizes sub-500kg track systems where weight thresholds dictate platform eligibility. NATO STANAG standardization agreements govern interoperability benchmarks for British Army vehicle programs. The Midlands defense manufacturing belt concentrates lightweight compound expertise for rapid deployment requirements.
Japan
Ground Self-Defense Force tracked vehicle modernization aligns with Indo-Pacific theater mobility requirements for mixed-terrain deployment. METI industrial standards shape domestic supplier qualification protocols for military-grade elastomer formulations. The Chubu-Nagoya manufacturing region hosts precision cable reinforcement fabricators serving regional defense supply chains.
Rubber Tracks for Defense and Security Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated vehicle OEMs capturing lifecycle service contract value while standalone compounders compete on formulation certification. The vendor base concentrates among European and North American entities with NATO qualification histories, creating tiered access barriers for new entrants. Three archetypes dominate: captive suppliers owned by prime vehicle integrators, independent compounders with certified supply chains, and dual-use manufacturers leveraging agricultural track expertise. M&A activity targets predictive maintenance capabilities, while capacity expansion concentrates near German and United States military testing facilities.
Among European defense conglomerates, Rheinmetall AG exemplifies the captive supplier archetype through its dominance in tracked combat vehicle platforms, while Diehl Defence occupies a position within the German industrial defense cluster. Soucy International represents the North American independent compounder model with its integrated manufacturing footprint sustaining long-term supply agreements. These three entities anchor competitive positioning across the Atlantic defense procurement axis.
| Leading Market Players |
|---|
| Diehl Defence |
| Soucy International |
| Michelin |
| Bridgestone Corporation |
| Continental AG |
| William Cook Defence Systems |
| Rheinmetall AG |
| Camso |
| Trelleborg AB |
| Others |
Supply Flow & Price Mechanics
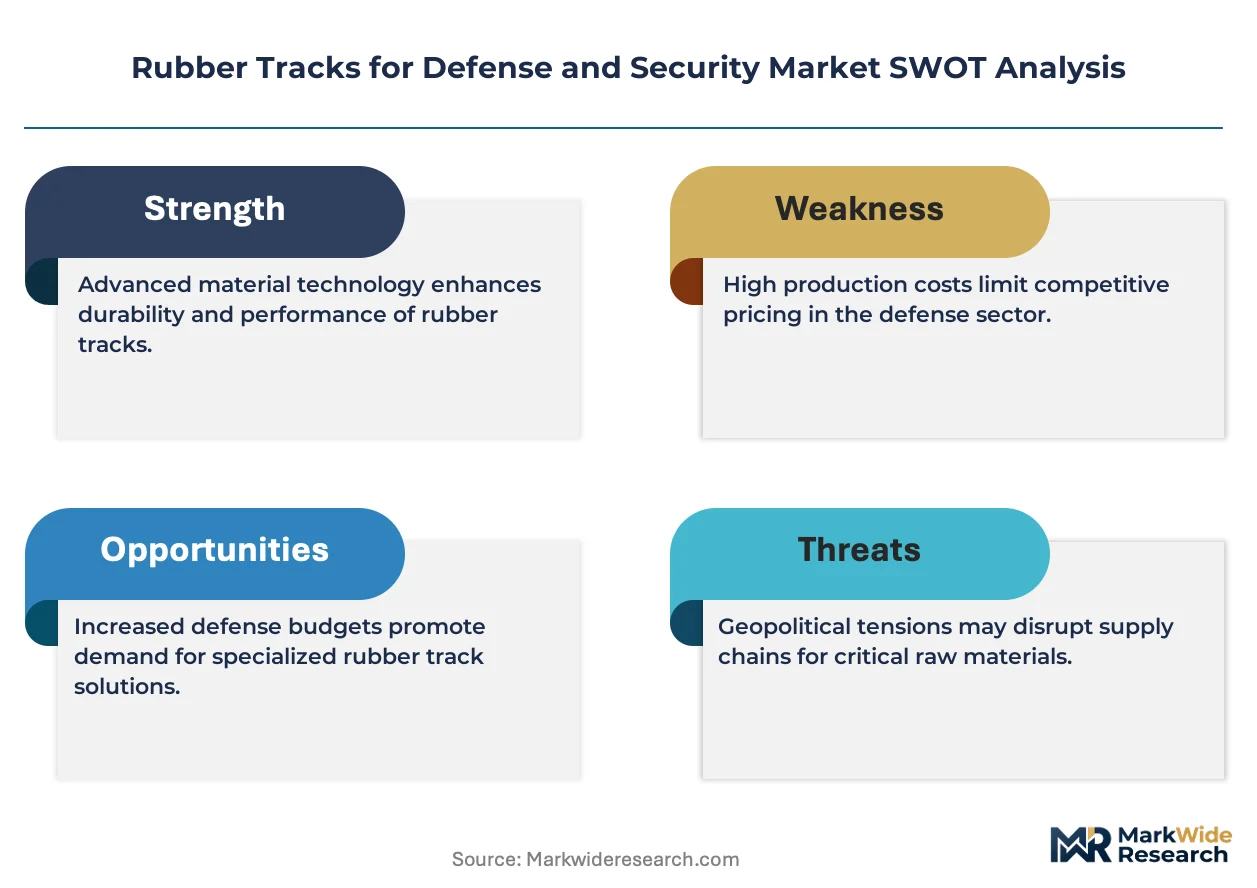
Prime vehicle integrators bundling multi-year availability agreements concentrate procurement authority and compress pricing leverage for standalone compounders. This buyer concentration forces tiered pricing stratification across certification grades, with NATO-qualified suppliers commanding premium positioning over non-certified competitors.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for heavy-duty track segments. Contract-based long-term offtake agreements dominate, with price differentiation hinging on ISO 9001 certification tier and embedded sensor integration level. Cost compression in lightweight compound production is intensifying because specialty polymer suppliers are expanding thermoplastic elastomer capacity. Defense contractors represent the least price-sensitive segment due to lifecycle cost modeling, while reserve vehicle fleet operators exhibit highest sensitivity to unit pricing.
Supply Chain Analysis
Single-source vulnerability sits with German and United States steel-cable weavers meeting NATO ballistic protection standards. Geographic supply concentration centers on Germany, France, and the United States for qualified elastomer compounders. Raw material dependencies rest on Southeast Asian natural rubber, synthetic polybutadiene from petrochemical complexes, and high-tensile steel cable. Tariff exposure on specialty chemicals creates structural risk for European formulators adapting to REACH restrictions. Distribution runs through prime integrator captive networks and authorized defense logistics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in rubber tracks for defense and security rests on predictive maintenance service bundling and premium-tier adaptive system penetration. Thermoplastic elastomer reformulation investments compress material costs while EU Green Deal compliance opens premium positioning.
For Market Incumbents: Cement lifecycle service contract dominance by acquiring predictive maintenance software capabilities and expanding inspection network coverage. Captive steel-cable weaving capacity insulates against NATO qualification bottlenecks. EPF substitution threats from enhanced polymer foam run-flat systems demand accelerated adaptive stiffness R&D to preserve platform relevance. For New Entrants and Emerging Players: Direct-to-defense-contractor digital procurement platforms offer the lowest friction entry path for thermoplastic elastomer specialists lacking legacy NATO relationships. Lightweight track segments for United Kingdom and United States special operations vehicles present the most penetrable white space. Target formulation certification partnerships with established cable weavers to bypass 18-month ISO 9001 validation timelines. For Investors and Strategic Acquirers: Prime vehicle integrators represent the most active acquirer category in this space, seeking predictive maintenance capabilities to bundle availability contracts. Mid-cap compounders with REACH-certified thermoplastic portfolios offer viable acquisition targets over a five-to-ten year defense modernization cycle. Monitor Bundeswehr platform retirement announcements as inflection signals for replacement demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Elastomer Transition | REACH-compliant formulations unlock EU defense procurement eligibility for compounders. |
| Predictive Maintenance Integration | Embedded sensor networks enable condition-based replacement contracts with prime integrators. |
| Steel-Cable Weaving Capacity Expansion | In-house cable production bypasses NATO qualification bottlenecks in Germany and the United States. |
| Special Operations Vehicle Partnership | Sub-500kg track specifications for United Kingdom and United States forces command premium margins. |
| Lifecycle Service Contract Bundling | Multi-year availability agreements concentrate purchasing authority with vehicle OEMs. |
Methodological Framework
Coverage spans North America and Europe, with primary inputs from each defense procurement cluster. The analysis combines structured interviews with platform engineering directors, defense procurement officers, elastomer R&D leads, and aftermarket service heads with secondary validation against NATO standardization agreements, ECHA substance restriction databases, and EPA environmental compliance filings. Bottom-up segment sizing triangulates against top-down military vehicle production forecasts.
Rate-of-change decomposition separates volume effects from mix-shift and pricing dynamics across the projection horizon. Segmentation dimensions modeled include product type tier, end-user procurement authority level, technology formulation category, and regional military modernization cycle stage. CAGRs derive from platform replacement schedule alignment and elastomer reformulation investment trajectories. Bundeswehr and United States Army vehicle retirement timelines serve as primary demand inflection inputs.
The model assumes a particular technology adoption path; alternative pathways for adaptive stiffness architectures would alter the outlook. Forecasts reflect assumptions about REACH authorization timelines and NATO standardization agreement evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Global Armor Materials Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Howitzer Artillery System Market
Military Equipment and Infrastructure
Military Optoelectronic System Market
Military Equipment and Infrastructure
Land Digital Battlefield Market
Military Equipment and Infrastructure
Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Latin America Defense Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market
Military Equipment and Infrastructure
CBRNE Defense Market
Military Equipment and Infrastructure
FLIR and Laser Designator Targeting Pods Market
Military Equipment and Infrastructure
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Europe Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Global Soldier Modernization Market