
 NATO Military Aircraft Modernization and Retrofit Market | 2026-2036
NATO Military Aircraft Modernization and Retrofit Market Size, Share, and Industry Trends Forecast 2026-2036
NATO Military Aircraft Modernization and Retrofit Market Foresight
The gap between full-spectrum platform overhauls and limited-scope avionics refreshes is shifting how defense contractors allocate engineering resources across NATO member states. Lockheed Martin dominates the fighter jet upgrade segment through its F-16 service-life extension programs in Europe. BAE Systems leverages its Eurofighter Typhoon deep-upgrade capabilities to anchor retrofit demand in the United Kingdom and Germany. Leonardo competes on rotorcraft modernization, sustaining its position through AW101 and NH90 avionics retrofit contracts with Italian and British armed forces.
NATO military aircraft modernization and retrofit encompasses the structural, avionic, propulsion, and weapons-system overhaul of existing airframes to extend operational life and restore mission effectiveness against contemporary threats. The process typically involves integrating active electronically scanned array radar, digital cockpit architectures, and NATO-compatible secure communications suites to achieve interoperability with allied command networks. Fighter jets command the largest technology upgrade allocation, with radar systems and avionics representing the fastest-growing retrofit categories as legacy analog systems face obsolescence against peer adversary electronic warfare capabilities. Weapons systems integration trails in growth rate but captures concentrated margin pools where software-defined munitions interfaces require proprietary engineering.
North Atlantic Treaty Organization standardization agreements, U.S. FAA airworthiness directives for military derivative platforms, and national military aviation authorities such as France's DGA and Germany's BAAINBw collectively shape airframe modification approval pathways and cross-border maintenance certifications. These regulatory layers create compliance barriers that favor incumbent prime contractors with established certification relationships over new market entrants. Stakeholders must monitor how NATO's next-generation air dominance requirements will redefine minimum viable capability thresholds for legacy platform retention decisions.
Market Dynamics
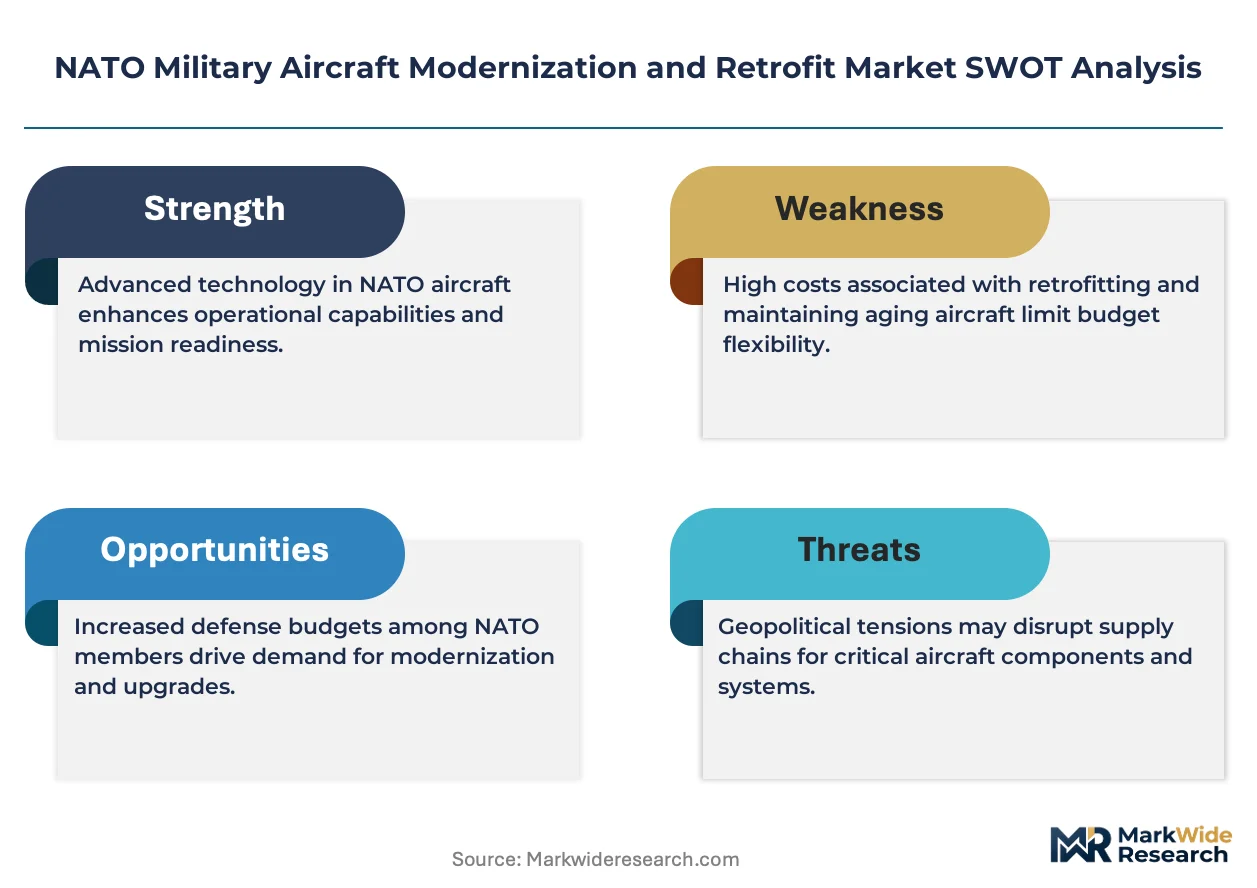
The NATO Military Aircraft Modernization and Retrofit Market faces a structural pivot as peer adversary electronic warfare capabilities force accelerated obsolescence cycles on legacy analog avionics. Fighter jet fleet managers across European member states must now choose between platform retirement and deep structural overhaul.
Growth Catalysts
- STANAG 4170 munitions integration protocols:NATO standardization agreements mandate interoperable weapons interfaces, compelling member states to fund avionics refreshes that enable coalition strike coordination.
- Poland's territorial defense acceleration:Frontline positioning against eastern threats compresses procurement timelines for F-16 service-life extension programs and radar modernization.
- Active electronically scanned array radar:This technology replacement addresses legacy mechanical radar vulnerability to jamming, driving retrofit demand across aging fighter fleets.
Market Restraints
- Titanium and nickel superalloy supply concentration:Structural airframe repairs depend on aerospace-grade materials sourced from limited certified foundries, creating input cost volatility.
- France's DGA certification timelines:National military aviation authority approval pathways for modified airframes extend 18-24 months, delaying revenue recognition for retrofit contractors.
- Platform substitution threat:Sixth-generation fighter development programs in the United States and United Kingdom threaten to truncate demand for legacy platform deep upgrades.
Strategic Opportunities
- Baltic states cluster:Estonia, Latvia, and Lithuania operate Soviet-era rotary wing assets requiring complete avionics replacement to achieve NATO interoperability.
- Software-defined radio convergence:Integration of NATO-compatible secure communications with digital cockpit architectures creates margin-rich upgrade packages.
- Germany's BAAINBw fleet recapitalization wave:The national military aviation authority's Tornado replacement timeline opens bridge modernization contracts for interim capability retention.
Industry Challenges
- Airworthiness engineer scarcity:Military derivative certification expertise concentrates among aging specialists, constraining program execution velocity.
- Legacy analog-digital interface integration:1980s-era airframe wiring harnesses require complete replacement to support modern avionics power and data loads.
- Cross-border maintenance certification friction:Bilateral agreements between national military aviation authorities lack standardization, complicating multi-national fleet support contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NATO Military Aircraft Modernization and Retrofit Market |
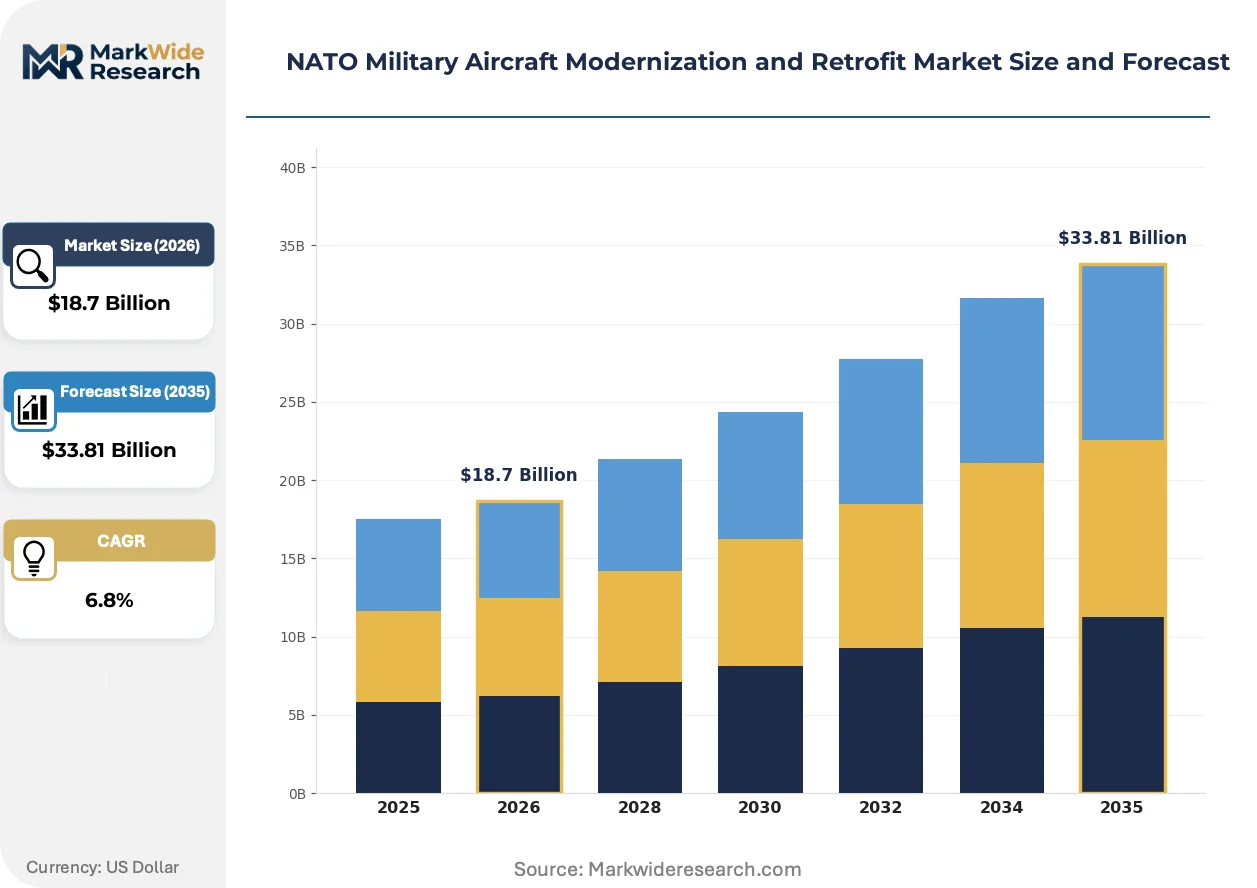
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Fighter Jets, Transport Aircraft, Helicopters, UAVs Technology Upgrade: Avionics, Engines, Weapons Systems, Radar Systems Service Type: Maintenance, Overhaul, Retrofit, Upgrade End User: Military Branches, Defense Contractors, Government Agencies, Private Firms |
| Companies Covered | Airbus, Raytheon Technologies, Lockheed Martin, General Dynamics, Thales Group, Northrop Grumman, Leonardo, L3Harris Technologies, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NATO Military Aircraft Modernization and Retrofit Market Shifts & Advancements
Retrofit engineering priorities are compressing as digital architectures displace federated analog systems across NATO fighter and rotary wing platforms. Contractors must now restructure development workflows to accommodate software-defined capability insertion.
Digital cockpit architecture is electrifying mission system integration by replacing discrete analog instruments with unified glass-panel displays and centralized processing. Polish and Romanian air forces are adopting these configurations at accelerated pace to match NATO alliance network standards. This consolidation is electrifying supplier tier restructuring as specialized display manufacturers capture value previously distributed across multiple analog instrument providers.
REACH and RoHS material compliance mandates in European Union member states are restricting hazardous substance use in aircraft wiring and coatings. Retrofit programs must now substitute legacy lead-based solders and chromate primers with certified alternatives, adding qualification testing to program timelines. German and Italian upgrade contracts face the most acute compliance pressure due to stringent national implementation of EU environmental directives.
Performance-based logistics contracts are displacing traditional time-and-material maintenance arrangements for sustained fleet support. Royal Air Force and Luftwaffe operators now demand availability guarantees rather than component repair services, transferring operational risk to prime contractors. This reconfiguration is most visible in United Kingdom Eurofighter Typhoon deep-upgrade programs where BAE Systems assumes full responsibility for mission-capable rates.
NATO Military Aircraft Modernization and Retrofit Market Segmentation
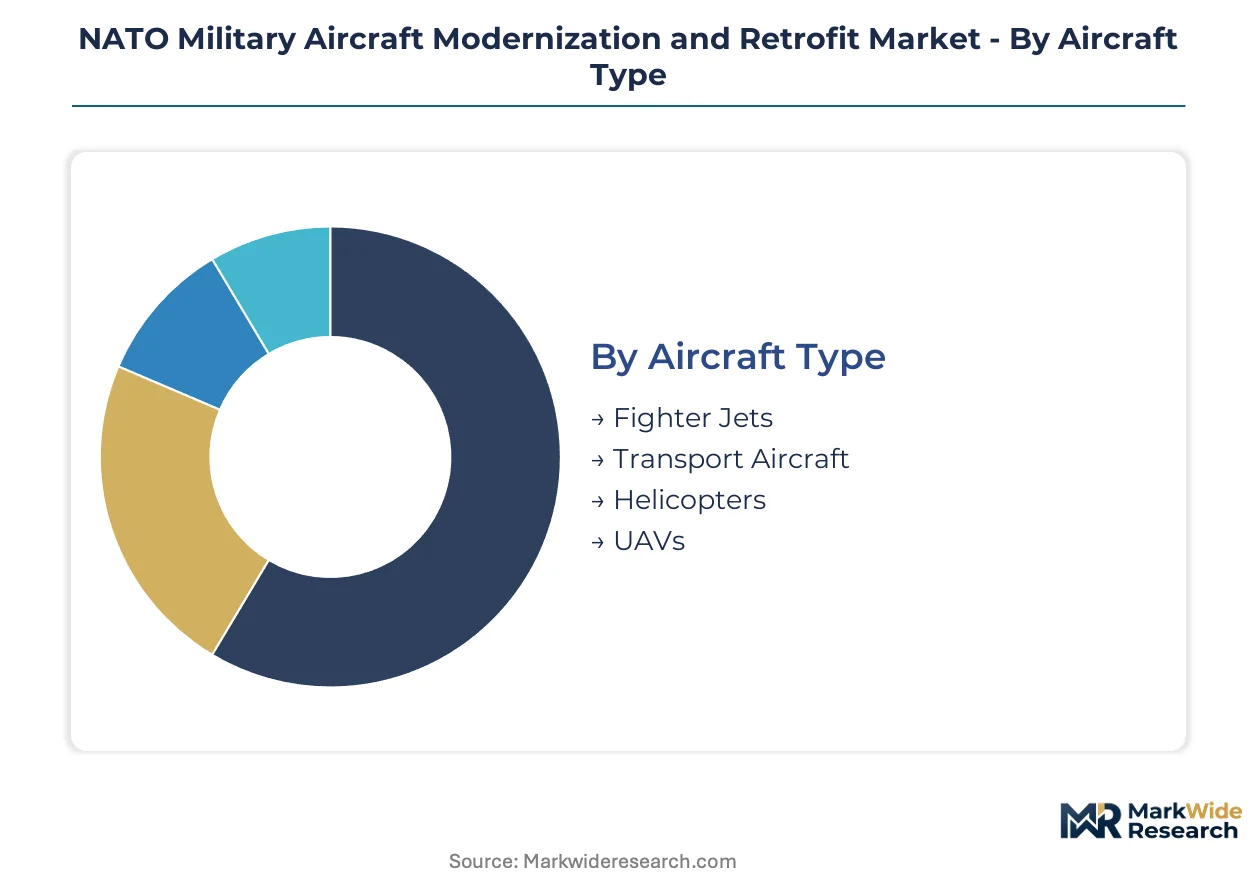
Segmentation in NATO military aircraft modernization reveals how engineering resources and regulatory approvals concentrate around specific airframe categories and technology tiers. Contractors align capability roadmaps with the interoperability mandates that drive procurement decisions across allied defense ministries.
Aircraft Type:
Supply concentration in this category favors platforms with established certification pathways and multi-national fleet footprints that amortize development costs across member states.
- Fighter Jets:Multi-role combat airframes requiring structural life extension, AESA radar integration, and digital cockpit architectures. Poland's territorial defense acceleration and Germany's Tornado replacement timeline are concentrating demand for F-16 and Eurofighter deep-upgrade programs. NATO standardization protocols for munitions interfaces compel avionics refreshes across aging European fleets.
- Helicopters:Rotary wing assets from the AW101, NH90, and legacy Soviet-era fleets demand complete avionics replacement to achieve NATO interoperability. The Baltic states cluster operates Soviet-origin rotary assets requiring NATO-compatible secure communications and digital mission systems to meet coalition operational standards.
- Transport Aircraft:Strategic and tactical airlifters undergo propulsion and avionics modifications to extend service life while maintaining intra-theater mobility.
- UAVs:Unmanned platforms require sensor payload integration and command-link upgrades to satisfy alliance network compatibility requirements.
Today's leader: Fighter Jets. Tomorrow's challenger: Helicopters.
Technology Upgrade:
Cost tier stratification in this category separates software-defined capabilities commanding premium engineering margins from hardware replacements facing commodity pricing pressure.
- Avionics:Digital cockpit architectures replacing federated analog systems with centralized processing and glass-panel displays. Polish and Romanian air forces are adopting these configurations at accelerated pace to match NATO alliance network standards, consolidating supplier tiers around specialized display manufacturers.
- Radar Systems:Active electronically scanned array technology replacing mechanically scanned arrays vulnerable to peer adversary electronic warfare. Frontline NATO members facing eastern threats prioritize this upgrade category for operational survivability against jamming threats.
- Weapons Systems:Software-defined munitions interfaces and NATO STANAG 4170 compliance for coalition strike coordination.
- Engines:Propulsion system overhauls and fuel efficiency modifications extending airframe operational life within existing airworthiness certifications.
Avionics commands current investment priority. Radar Systems is gaining share fastest as electronic warfare threats intensify.
Service Type:
Volume concentration in this category reflects the shift from transactional maintenance arrangements to outcome-based availability contracts transferring operational risk to prime contractors.
- Retrofit:Structural, avionic, and weapons-system modifications integrating contemporary capabilities into legacy airframes. Royal Air Force and Luftwaffe operators now demand availability guarantees rather than component repair services, reconfiguring contract economics toward performance-based logistics.
- Upgrade:Capability insertion programs adding mission systems beyond original design specifications. BAE Systems assumes full responsibility for Eurofighter Typhoon mission-capable rates in United Kingdom deep-upgrade programs.
- Overhaul:Scheduled restoration of airframe, propulsion, and systems to original or modified specifications within approved maintenance intervals.
- Maintenance:Routine servicing and component replacement sustaining fleet availability between major modification events.
Retrofit dominates contract value. Upgrade is expanding most quickly as peer threat evolution compresses capability refresh cycles.
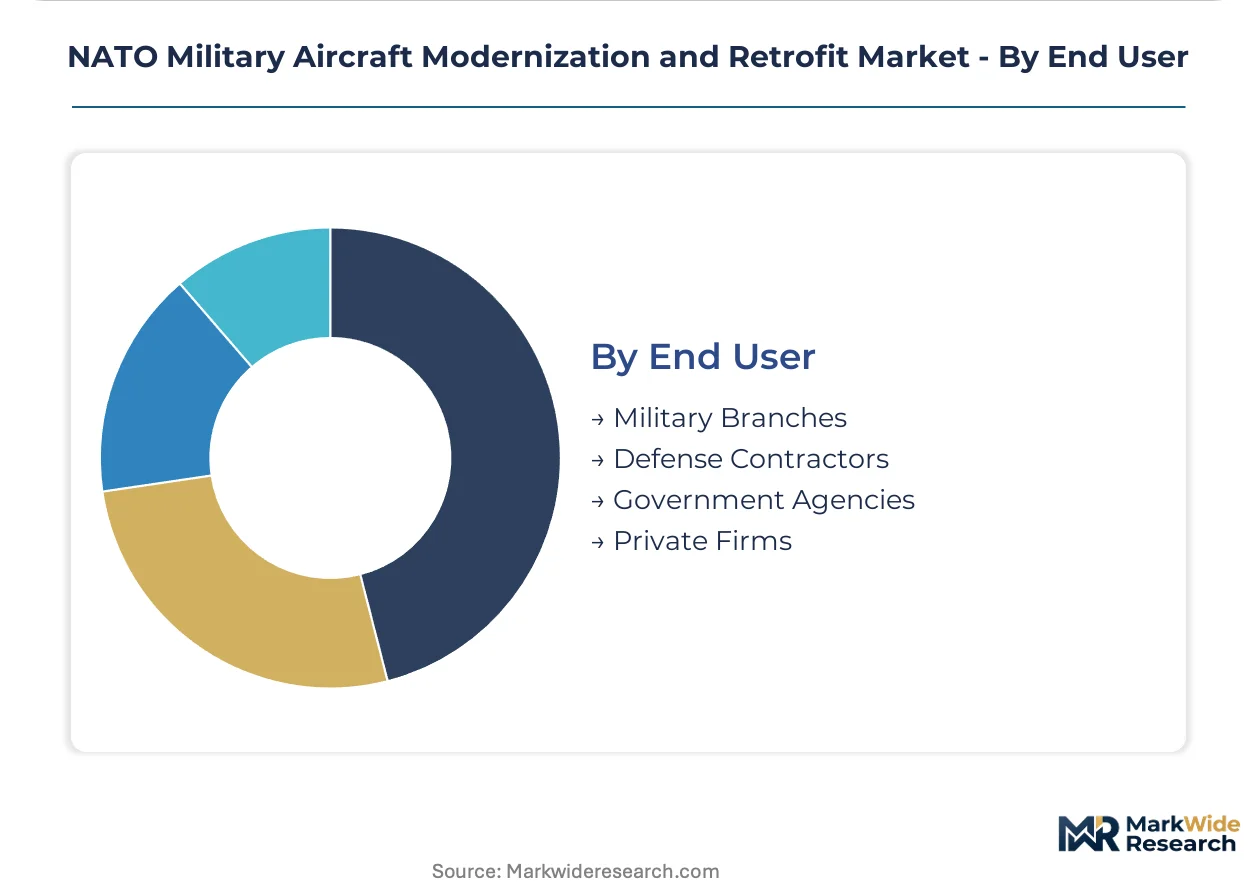
End User:
Customer type differentiation in this category separates sovereign military operators with direct NATO interoperability mandates from contractor intermediaries managing multi-national fleet support.
- Military Branches:National air forces, naval aviation, and army aviation units operating as direct procurement authorities. France's DGA and Germany's BAAINBw shape modification approval pathways through national military aviation authority certification requirements.
- Defense Contractors:Prime contractors and system integrators executing fleet-wide modernization programs under government contract. Cross-border maintenance certification friction complicates multi-national fleet support arrangements due to bilateral agreement gaps between national authorities.
- Government Agencies:Defense ministries and procurement offices establishing technical specifications and funding allocation for modernization priorities.
- Private Firms:Specialized engineering services and component suppliers supporting upgrade program execution under subcontract arrangements.
Military Branches anchor procurement authority. Defense Contractors are capturing expanded scope through performance-based logistics restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European airworthiness engineering talent concentrates in Germany's Bavaria and the United Kingdom's aerospace corridor, anchoring NATO's retrofit certification capacity. Poland's frontline positioning accelerates procurement timelines. Baltic states demand complete Soviet-era fleet replacement.
Poland
Poland's territorial defense priorities compress F-16 service-life extension program schedules against eastern threat vectors. The national military aviation authority accelerates radar modernization approvals for frontline squadrons. Warsaw's defense industrial cluster hosts Lockheed Martin sustainment operations for regional fighter fleet support.
Germany
Germany's Tornado replacement timeline generates bridge modernization contracts through BAAINBw fleet recapitalization authority. REACH and RoHS compliance mandates impose material substitution requirements on wiring harness upgrades. Bavaria's aerospace engineering concentration in Munich anchors Eurofighter deep-upgrade program execution for Luftwaffe operators.
United Kingdom
The Royal Air Force's performance-based logistics restructuring transfers mission-capable rate accountability to prime contractors. BAAINBw certification reciprocity agreements reduce cross-border maintenance friction for multinational Eurofighter fleets. BAE Systems' Lancashire operations anchor Typhoon avionics integration capacity for alliance network compatibility.
Italy
Italy's Leonardo sustains rotorcraft modernization demand through AW101 and NH90 avionics retrofit contracts with national armed forces. EU environmental directives impose hazardous substance restrictions on aircraft coatings and solders. Rome's aerospace district concentrates software-defined radio integration expertise for NATO secure communications convergence.
United States
The United States anchors fighter jet upgrade engineering through F-16 service-life extension program intellectual property concentration. FAA airworthiness directives for military derivative platforms shape modification approval pathways for European operators. Lockheed Martin's Texas operations export retrofit engineering standards across NATO member certification regimes.
NATO Military Aircraft Modernization and Retrofit Market Competitive Landscape
Top-tier vendors anchor platform-original manufacturer tiers, while specialized avionics integrators occupy subsystem retrofit niches. The vendor structure concentrates around fighter jet upgrade specialists with established NATO certification relationships and rotorcraft modernization providers with multi-national fleet footprints. Three archetypes dominate: platform primes controlling airworthiness authority, avionics specialists capturing digital cockpit architecture value, and sustainment contractors assuming operational risk through availability guarantees. Competitive positioning hardens through certification relationship accumulation and performance-based logistics contract capture.
Within the platform prime archetype, Lockheed Martin and BAE Systems exemplify contrasting geographic anchoring strategies. Lockheed Martin represents American engineering standard export across European F-16 fleets. BAE Systems occupies a position as United Kingdom-based Eurofighter deep-upgrade authority. Leonardo sits within the rotorcraft specialization tier, anchoring Italian and British naval aviation modernization demand through vertical lift platform expertise.
| Leading Market Players |
|---|
| Airbus |
| Raytheon Technologies |
| Lockheed Martin |
| General Dynamics |
| Thales Group |
| Northrop Grumman |
| Leonardo |
| L3Harris Technologies |
| BAE Systems |
| Others |
Supply & Pricing Matrix
Airworthiness engineering talent concentration in Germany's Bavaria and the United Kingdom's aerospace corridor creates labor-cost differentials that widen pricing-tier spreads between premium certified upgrades and commodity maintenance services.
Pricing Analysis
The bundled-vs-unbundled service split separates performance-based logistics contracts from transactional component repairs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with NATO STANAG compliance commanding substantial premiums over national-only standards. Cost compression in standard-tier avionics refreshes is intensifying because software-defined radio integration is commoditizing previously proprietary engineering. Defense contractors managing multi-national fleet support exhibit least price sensitivity, while smaller national military aviation authorities face acute budget constraints.
Supply Chain Analysis
Titanium and nickel superalloy supply rests on certified foundries concentrated in the United States, Germany, and Japan. Raw material dependencies center on aerospace-grade alloys, specialized radar components, and NATO-compatible secure communications modules. Single-source vulnerability in mechanical radar component manufacturing creates structural exposure to peer adversary electronic warfare disruption. Distribution runs through prime contractor-led integrated logistics chains rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined capability insertion is expanding margin pools as digital architectures displace analog systems, with premium-tier radar and avionics upgrades capturing value previously distributed across federated suppliers.
For Market Incumbents: Lock in certification relationship accumulation across France's DGA and Germany's BAAINBw approval pathways to defend against emerging avionics specialists. Deepen backward integration into software-defined radio engineering to capture margin-rich NATO secure communications convergence. Prioritize performance-based logistics contract capture with Royal Air Force and Luftwaffe operators transferring operational risk accountability. For New Entrants and Emerging Players: Tier 2 avionics integrators represent the most accessible channel partner type for bypassing prime contractor lock-in. Target the Baltic states cluster of Estonia, Latvia, and Lithuania, where Soviet-era rotary wing assets require complete NATO interoperability retrofits without established incumbent relationships. Pursue software-defined munitions interface development as the primary go-to-market angle, leveraging STANAG 4170 compliance mandates as entry wedge. For Investors and Strategic Acquirers: Defense primes with multi-national fleet footprints are the most active acquirer in this space, consolidating specialized avionics capabilities to anchor platform-original manufacturer tiers. Long-term viability hinges on certification relationship amortization across aging European fighter fleets resisting sixth-generation substitution timelines. Monitor Germany's Tornado replacement bridge modernization contract awards as the critical inflection signal for legacy platform deep-upgrade demand sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| AESA Radar Technology Licensing | Lockheed Martin's F-16 upgrade IP exports across Polish and Romanian certification regimes. |
| Performance-Based Logistics Contracting | BAE Systems assumes full mission-capable rate accountability for Royal Air Force Eurofighter fleets. |
| Software-Defined Radio Platform Integration | Leonardo's Rome operations anchor NATO secure communications convergence for AW101 and NH90 rotorcraft. |
| REACH and RoHS Compliance Certification | German and Italian upgrade contracts face acute material substitution requirements from EU environmental directives. |
| Cross-Border Maintenance Certification Reciprocity | United Kingdom-Germany bilateral agreements reduce friction for multinational Eurofighter fleet support. |
Research Methodology
Coverage spans Poland, Germany, the United Kingdom, Italy, and the United States, with primary inputs from each anchoring regional demand calibration. The analysis combines structured interviews with fleet managers at national military aviation authorities, program directors at prime contractors, airworthiness certification engineers, and defense ministry procurement officers with secondary validation from NATO standardization agreement documentation, national military aviation authority filing records, FAA airworthiness directives for military derivative platforms, and customs data on aerospace-grade material imports. Bottom-up platform-level demand aggregation and top-down defense budget allocation triangulation ensure cross-verified outputs.
Granularity-level modeling extends to individual airframe categories, technology upgrade tiers, service type arrangements, and end-user procurement authorities across the projection horizon. Fighter jet, helicopter, transport aircraft, and UAV segments were modeled separately with technology upgrade splits for avionics, radar systems, weapons systems, and engines. Service type differentiation between retrofit, upgrade, overhaul, and maintenance captures contract economics shifting toward availability guarantees. CAGRs were derived from defense budget trajectory analysis, platform retirement timeline assessment, and threat environment evolution against peer adversary electronic warfare capabilities.
Revisions become necessary when sixth-generation fighter development programs accelerate legacy platform retirement timelines, when REACH and RoHS compliance mandates expand material substitution requirements, or when bilateral cross-border maintenance certification agreements achieve standardization. Forecasts reflect documented assumptions on defense budget continuity, threat environment stability, and certification pathway durations. Material deviation in Germany's Tornado replacement timeline, Poland's territorial defense procurement acceleration, or NATO next-generation air dominance requirement announcements warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market
Military Equipment and Infrastructure
Land Digital Battlefield Market
Military Equipment and Infrastructure
Europe Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Military Displays Market
Military Equipment and Infrastructure
Global Soldier Modernization Market
Military Equipment and Infrastructure
Military Tent and Shelter Market
Military Equipment and Infrastructure
Military Optoelectronic System Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market
Military Equipment and Infrastructure
Military Test Equipment Market
Military Equipment and Infrastructure
CBRNE Defense Market
Military Equipment and Infrastructure
Global Armor Materials Market
Military Equipment and Infrastructure
Howitzer Artillery System Market
Military Equipment and Infrastructure
Global CBRN Defense Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
Europe Digital Battlefield Market