
 FLIR and Laser Designator Targeting Pods Market | 2026-2036
FLIR and Laser Designator Targeting Pods Market Size, Share, and Industry Trends Forecast 2026-2036
FLIR and Laser Designator Targeting Pods Market Foresight
The EU Green Deal's embedded defense industrial sustainability criteria is shifting procurement weights toward suppliers with certified low-carbon manufacturing chains. Lockheed Martin Corporation leverages its captive sapphire window production to control thermal imaging substrate quality. Raytheon Technologies anchors its competitive position through dense vertical integration into cooled infrared detector foundries. Northrop Grumman Corporation dominates the multi-sensor fusion segment with proprietary image stabilization algorithms.
FLIR and laser designator targeting pods integrate stabilized electro-optical sensors, laser rangefinder-designators, and digital video trackers within aerodynamic housings for external aircraft carriage, typically operating across mid-wave infrared (3-5 μm) and long-wave infrared (8-12 μm) spectral bands to enable day-night precision target engagement. Electro-Optical Pods and Multi-Sensor Systems command the largest installed base among product categories, though Infrared Sensors capture disproportionate margin pools due to focal plane array complexity. Thermal Imaging and Target Tracking technologies lead technology segment adoption, with Laser Spot Detection expanding fastest as sovereign laser code interoperability standards proliferate among allied defense forces.
The U.S. Department of Defense's MIL-STD-810 environmental testing requirements and NATO STANAG 3733 laser designator interoperability standards collectively shape product development roadmaps and foreign military sales eligibility. The EU AI Act's emerging risk classification framework for autonomous targeting assistance functions will influence software architecture decisions across Thales Group and Rafael Advanced Defense Systems Ltd product lines. Stakeholders must monitor divergence between U.S. ITAR-controlled technology release policies and European defense procurement autonomy initiatives when structuring cross-border joint development agreements.
Market Dynamics
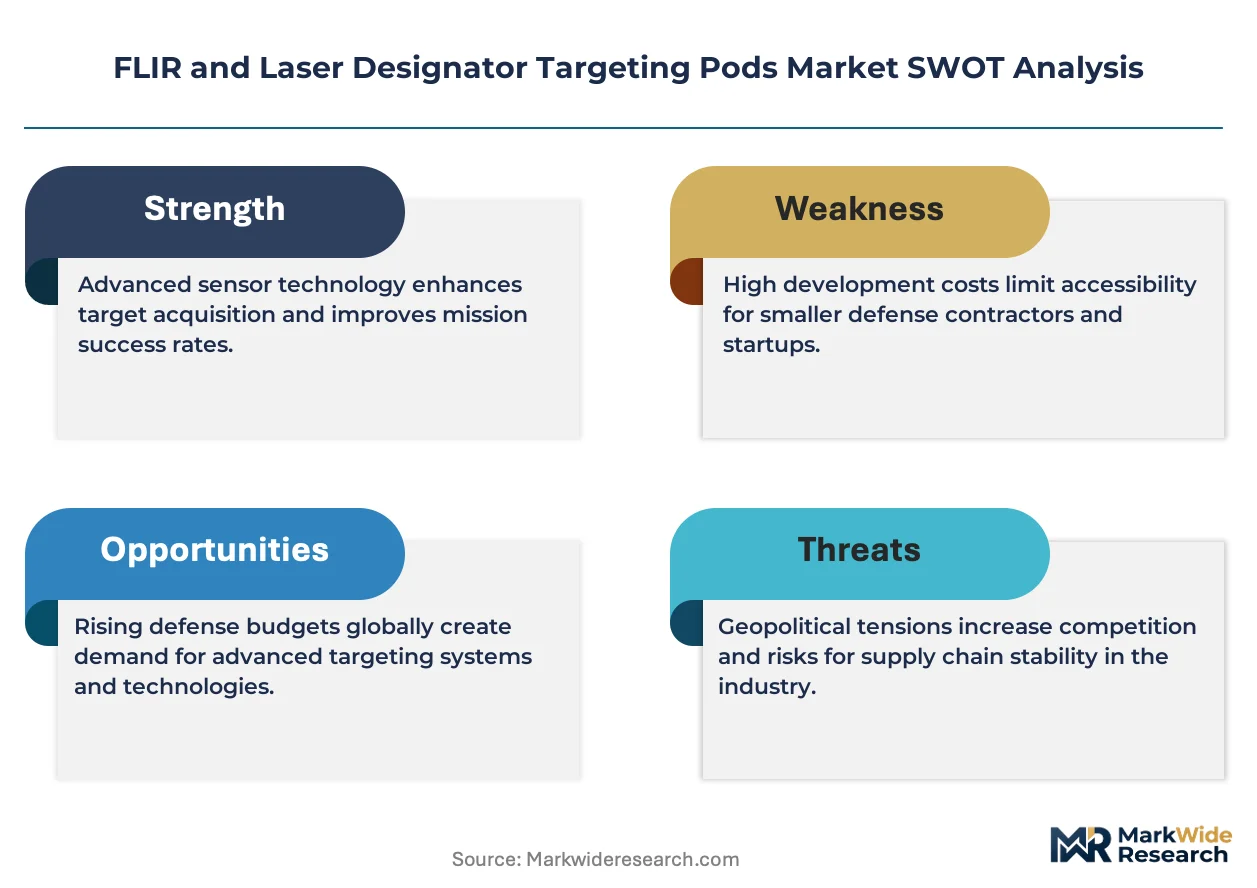
Multi-sensor fusion architectures are compressing development cycles across electro-optical pod manufacturers, as NATO interoperability mandates force simultaneous compliance with multiple sovereign laser code standards and environmental qualification protocols.
Growth Catalysts
- Precision Strike Modernization:The U.S. Department of Defense's prioritization of counter-insurgency and near-peer conflict scenarios drives fighter aircraft retrofit programs with advanced targeting capabilities. Combatant commands demand day-night engagement envelopes.
- EU Green Deal Defense Criteria:Embedded sustainability requirements for defense industrial suppliers create qualification advantages for electro-optical manufacturers with certified low-carbon sapphire substrate production chains.
- Laser Code Interoperability:NATO STANAG 3733 standardization among allied forces enables cross-border mission compatibility, expanding addressable installed bases for multi-code capable designator systems.
Market Restraints
- Indium Antimonide Detector Costs:Cooled MWIR focal plane arrays depend on scarce indium supply concentrated in Chinese refining operations, creating input cost volatility for infrared sensor manufacturers.
- ITAR Technology Release Friction:U.S. State Department export controls on thermal imaging and laser designation subsystems restrict joint development agreements with European defense primes, fragmenting R&D collaboration.
- Uncooled Sensor Performance Gap:Bolometer-based long-wave alternatives lack the sensitivity for extended-range target identification, limiting substitution in high-altitude penetration missions.
Strategic Opportunities
- Autonomous Targeting Assistance:The EU AI Act's emerging risk classification framework creates first-mover advantages for pod manufacturers architecting human-in-the-loop software with explainable decision trails.
- Rotary-Wing Integration:Attack helicopter fleets in Poland and Australia represent underpenetrated demand for compact, vibration-hardened multi-sensor pods with integrated laser spot trackers.
- Dual-Band Sensor Fusion:Convergence of MWIR and SWIR imaging channels with multi-spectral laser designation enables countermeasure-resistant targeting in contested electromagnetic environments.
Industry Challenges
- Cryocooler Reliability Engineering:Stirling-cycle mechanical coolers for cooled detectors require specialized vacuum and precision machining expertise scarce in commercial thermal imaging supply chains.
- MIL-STD-810 Qualification Timelines:Environmental testing for temperature shock, humidity, and gunfire vibration extends product certification cycles, compressing competitive response windows.
- Legacy Platform Integration:Fourth-generation fighter avionics buses lack bandwidth for full-motion multi-spectral video, forcing expensive cockpit display and processor retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FLIR and Laser Designator Targeting Pods Market |
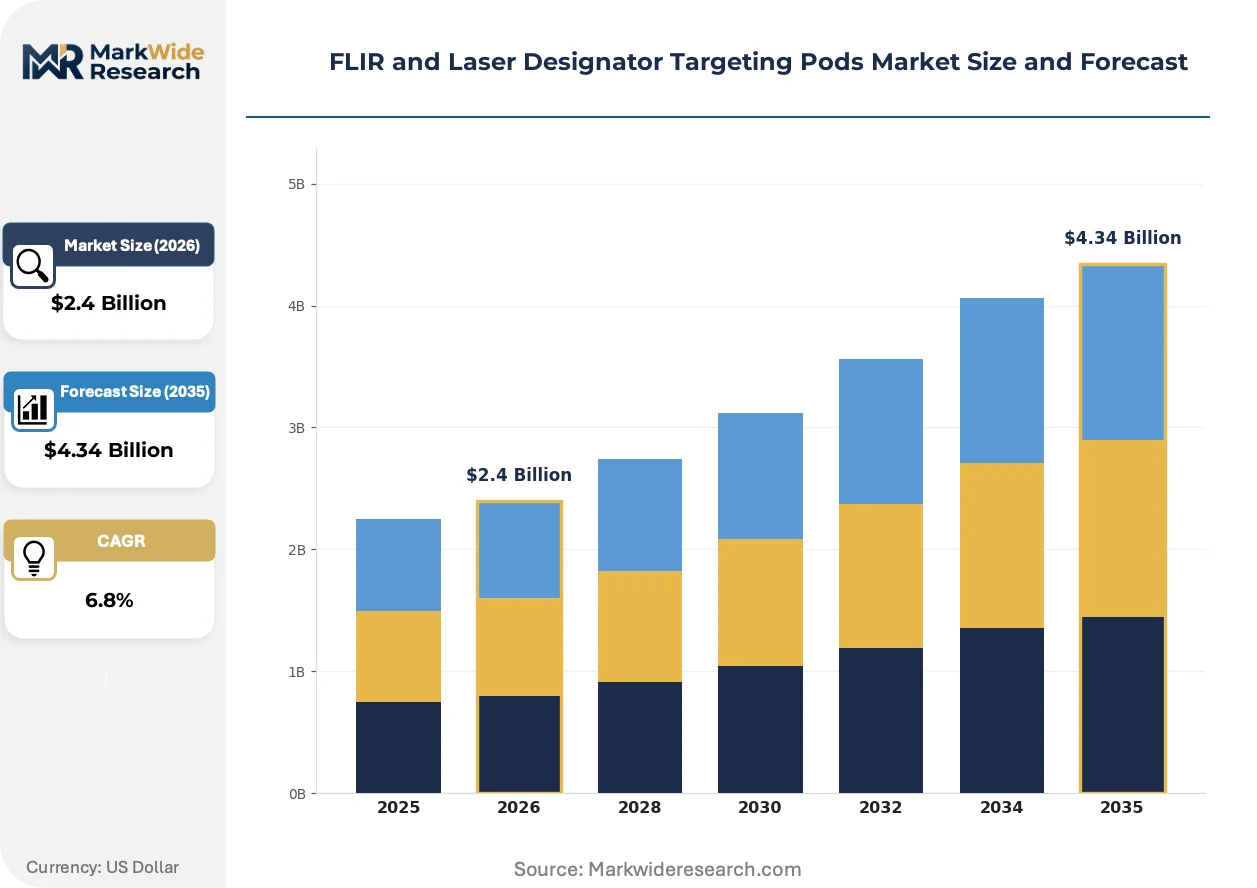
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electro-Optical Pods, Infrared Sensors, Laser Designator Modules, Multi-Sensor Systems Technology: Thermal Imaging, Laser Spot Detection, Target Tracking, Image Stabilization, Night Vision Application: Reconnaissance, Weapon Guidance, Border Surveillance, Maritime Monitoring, Search and Rescue End User: Defense Forces, Security Agencies, Coast Guards, Airborne Units, Law Enforcement |
| Companies Covered | Lockheed Martin Corporation, Raytheon Technologies, Northrop Grumman Corporation, Thales Group, Rafael Advanced Defense Systems Ltd, Teledyne FLIR LLC, Israel Aerospace Industries, MOOG Inc., RTX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FLIR and Laser Designator Targeting Pods Market Shifts & Advancements
Software-defined targeting architectures are displacing hardware-fixed sensor configurations, enabling field-upgradable threat libraries and mission-specific spectral tuning without pod removal.
Two-color split-off focal plane arrays are overtaking single-band MWIR sensors in next-generation pod designs. U.S. Navy and Air Force strike squadrons are specifying these detectors for simultaneous target tracking and countermeasure discrimination. The technology is overtaking legacy indium antimonide alternatives by collapsing size-weight-power constraints while extending identification ranges against low-signature targets.
The EU AI Act's risk-based classification for autonomous weapon system components is forcing architectural decisions across Thales Group and Rafael Advanced Defense Systems product lines. Software modules with assisted target recognition now require conformity assessment procedures and technical documentation trails previously absent from electro-optical procurement. Pod manufacturers serving European defense ministries are reengineering human-machine interface protocols to maintain operator override authority under emerging liability frameworks.
Performance-based logistics contracts are displacing traditional spares-and-repair aftermarket arrangements. Defense procurement offices in the United Kingdom and Germany now specify availability guarantees and mean-time-between-failure metrics rather than component unit pricing. This restructuring concentrates aftermarket revenue with integrated system providers capable of predictive diagnostics and forward-deployed maintenance cells, marginalizing component-only suppliers without field service infrastructure.
FLIR and Laser Designator Targeting Pods Market Segmentation
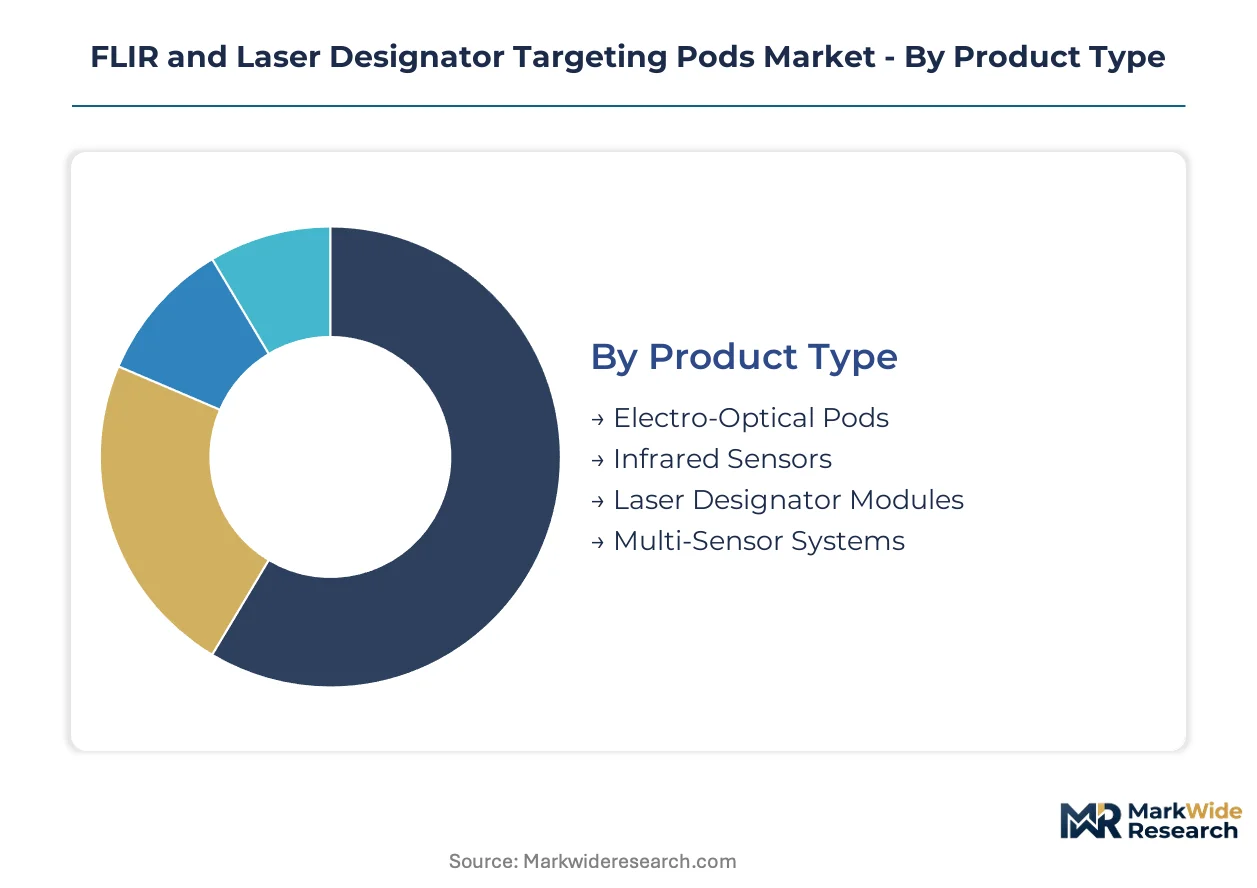
Targeting pod procurement patterns diverge sharply across operational roles and platform integration requirements. Segment-specific technical specifications determine qualification pathways for NATO interoperability standards and national defense procurement frameworks.
Product Type:
Supply concentration in cooled infrared detector foundries and sapphire substrate production chains shapes competitive positioning across product categories.
- Electro-Optical Pods:Stabilized multi-sensor housings integrating MWIR/LWIR imaging with laser designation for external aircraft carriage. U.S. Air Force and Navy fighter modernization programs concentrate demand for day-night precision strike envelopes.
- Multi-Sensor Systems:Fused architectures combining thermal imaging, laser rangefinding, and digital video tracking within unified control interfaces. European defense ministries prioritize these configurations for Eurofighter Typhoon and Rafale fleet upgrades under EU Green Deal sustainability criteria.
- Infrared Sensors:Focal plane arrays and detector assemblies for pod integration.
- Laser Designator Modules:Standalone rangefinder-designator units for platform-agnostic retrofit.
Electro-Optical Pods absorb the bulk of installed capacity; Multi-Sensor Systems are expanding most quickly.
Technology:
Cost tier differentiation separates military-grade cooled detector systems from commercial thermal alternatives with limited target identification range.
- Thermal Imaging:MWIR and LWIR spectral imaging across indium antimonide and mercury cadmium telluride detector technologies. Combatant commands in the United States drive specifications for extended-range target acquisition in contested electromagnetic environments.
- Laser Spot Detection:Receiver systems for identifying and tracking coded laser energy from designator platforms. NATO STANAG 3733 interoperability mandates are accelerating sovereign laser code standardization among allied forces.
- Target Tracking:Digital video processing algorithms for moving target engagement.
- Image Stabilization:Mechanical and electronic compensation for platform vibration and atmospheric distortion.
- Night Vision:Image intensification for low-light operational augmentation.
Thermal Imaging captures the dominant share of defense procurement budgets; Laser Spot Detection is climbing the fastest as multi-code interoperability requirements proliferate.
Application:
Volume concentration in precision strike missions contrasts with emerging demand for maritime domain awareness and border security operations.
- Weapon Guidance:Laser designation and thermal tracking for precision munitions delivery. U.S. Department of Defense counter-insurgency and near-peer conflict planning prioritizes these capabilities across multiple combatant commands.
- Reconnaissance:Passive electro-optical collection for intelligence, surveillance, and target acquisition. Polish and Australian attack helicopter fleets represent underpenetrated demand for compact, vibration-hardened pod configurations.
- Border Surveillance:Persistent wide-area monitoring for territorial security.
- Maritime Monitoring:Naval patrol and littoral domain awareness applications.
- Search and Rescue:Thermal detection for personnel recovery operations.
Weapon Guidance accounts for the majority of program-of-record procurement; Reconnaissance is gaining share fastest as rotary-wing integration accelerates.
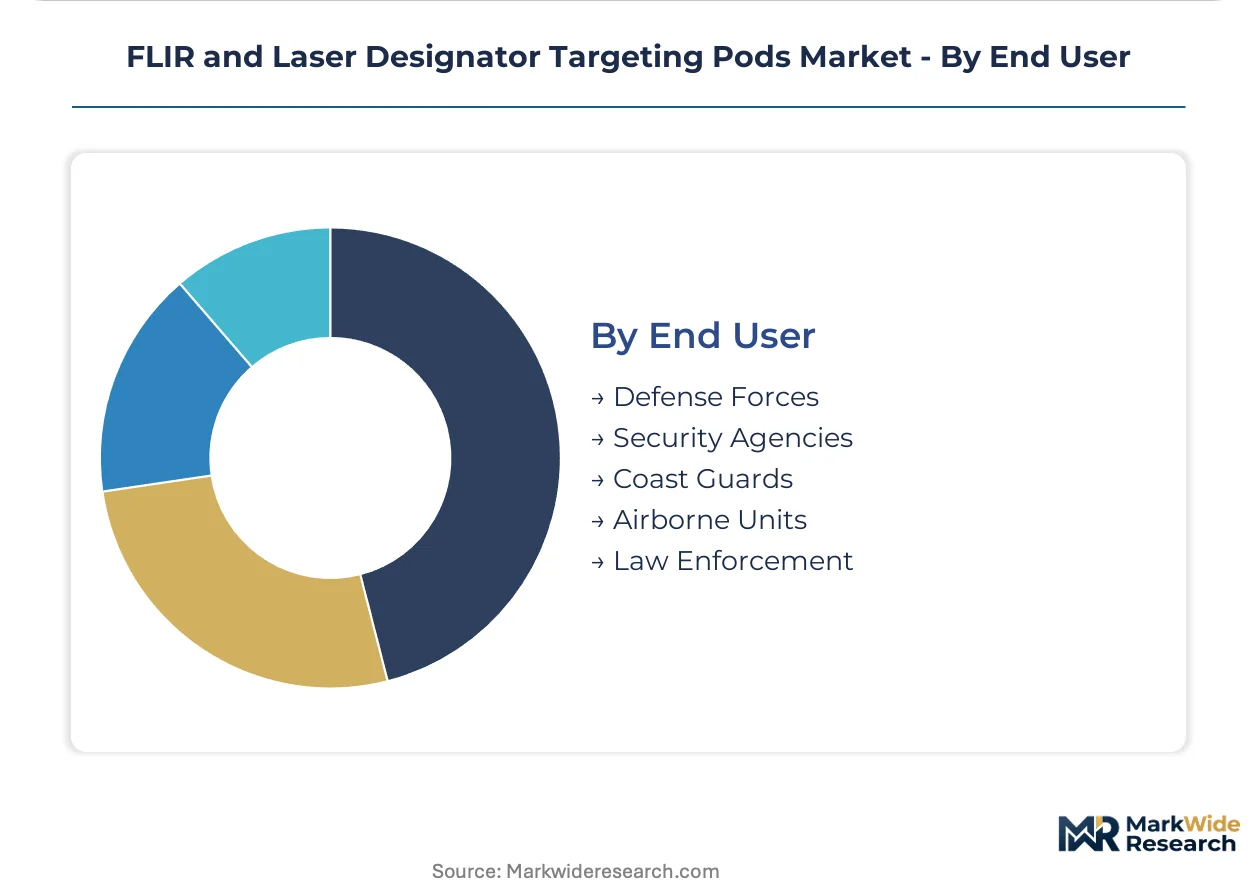
End User:
Customer type segmentation reflects divergent procurement authority structures and operational tempo requirements across institutional buyers.
- Defense Forces:National military services with program-of-record acquisition authority for fighter and helicopter fleets. The U.S. Department of Defense shapes global technical specifications through MIL-STD-810 environmental qualification requirements.
- Airborne Units:Specialized aviation branches with platform-specific integration demands. These formations specify bandwidth-constrained avionics interfaces for fourth-generation fighter cockpit retrofits.
- Security Agencies:Domestic intelligence and counterterrorism organizations with limited procurement scale.
- Coast Guards:Maritime law enforcement with patrol aircraft sensor requirements.
- Law Enforcement:State and local agencies with restricted operational envelopes.
Defense Forces command the preponderance of capital expenditure; Airborne Units are expanding procurement fastest as helicopter fleet modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Washington D.C. anchors defense procurement authority for targeting pod modernization across NATO fighter fleets. The U.S. Department of Defense shapes global technical specifications through MIL-STD-810 environmental qualification requirements and combatant command operational demands.
United States
Fighter aircraft retrofit programs and precision strike modernization drive procurement volumes across Air Force and Navy strike squadrons. The Department of Defense prioritizes counter-insurgency and near-peer conflict scenarios requiring day-night engagement envelopes. Defense industrial corridors in Texas and Arizona concentrate electro-optical subsystem manufacturing and integration facilities.
Germany
Eurofighter Typhoon fleet upgrades and EU Green Deal sustainability criteria reshape supplier qualification requirements. The national defense procurement office specifies performance-based logistics contracts with availability guarantees rather than component unit pricing. Industrial clusters in Bavaria and Baden-Württemberg host precision optics and cooled detector foundry operations.
United Kingdom
Royal Air Force precision strike capabilities and F-35 integration programs sustain demand for multi-sensor fusion architectures. Ministry of Defence procurement frameworks emphasize predictive diagnostics and forward-deployed maintenance cells for aftermarket service. Aerospace manufacturing corridors in Lancashire and the East Midlands concentrate pod integration and test facilities.
Israel
Combat-proven targeting systems and sovereign laser code development sustain export-oriented production. The national defense establishment drives specifications for compact, vibration-hardened configurations suited to attack helicopter integration. Industrial zones around Haifa and the Negev Desert concentrate electro-optical research and multi-sensor system prototyping.
Australia
Attack helicopter fleet modernization and Indo-Pacific operational requirements expand addressable demand for rotary-wing targeting pods. The Department of Defence prioritizes interoperability with allied forces through NATO STANAG 3733 laser code standardization. Defense technology precincts in Victoria and South Australia host subsystem integration and regional maintenance capabilities.
FLIR and Laser Designator Targeting Pods Market Competitive Landscape
The competitive structure tilts toward vertically integrated defense primes with captive supply chains for critical electro-optical components. Market concentration reflects high barriers to entry from ITAR export controls and MIL-STD environmental qualification timelines. Three archetypes dominate: U.S. defense conglomerates with multi-domain portfolios, European system integrators serving NATO interoperability mandates, and Israeli specialists in compact combat-proven configurations. Competitive moves center on backward integration into sapphire substrate and cooled detector production, plus performance-based logistics contracting for aftermarket capture.
Among U.S.-based defense conglomerates, Lockheed Martin Corporation and Raytheon Technologies exemplify the vertically integrated archetype with in-house control over thermal imaging supply chains. Thales Group represents the European system integrator position, while Rafael Advanced Defense Systems Ltd occupies the combat-specialist tier with proven rotary-wing configurations.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Raytheon Technologies |
| Northrop Grumman Corporation |
| Thales Group |
| Rafael Advanced Defense Systems Ltd |
| Teledyne FLIR LLC |
| Israel Aerospace Industries |
| MOOG Inc. |
| RTX Corporation |
| Others |
Supply & Pricing Matrix
Performance-grade certification tiers bifurcate procurement economics between MIL-STD-810 qualified systems and commercial thermal alternatives, concentrating pricing power with U.S. primes holding captive sapphire substrate production while European suppliers absorb EU Green Deal compliance premiums.
Pricing Analysis
Availability-guarantee contracts now anchor defense procurement economics. Performance-based logistics with mean-time-between-failure metrics separate integrated system providers from component-only suppliers. Cost compression in cooled MWIR focal plane arrays intensifies because indium supply volatility from Chinese refining operations feeds through detector foundry pricing. Defense Forces exhibit lowest price sensitivity due to program-of-record authority; Security Agencies face tightest budget constraints.
Supply Chain Analysis
Specialized vacuum and precision machining expertise concentrates in Texas and Arizona defense industrial corridors, with Bavaria and Baden-Württemberg hosting complementary cooled detector foundries. Critical inputs draw from indium antimonide wafer production, mercury cadmium telluride epitaxy, and low-carbon sapphire substrate supply chains. Single-source vulnerability runs through Chinese indium refining concentration. Distribution feeds from prime contractor integration facilities through military logistics channels to combatant command maintenance cells.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as ITAR export controls and MIL-STD qualification timelines squeeze subscale competitors without captive electro-optical component production.
For Market Incumbents: Lock in backward integration into Stirling-cycle cryocooler manufacturing and certified low-carbon sapphire substrate supply chains. Secure performance-based logistics contracts with predictive diagnostics capabilities to capture aftermarket revenue concentration. Counter emerging rotary-wing specialists by accelerating compact pod development for bandwidth-constrained fourth-generation fighter retrofits. For New Entrants and Emerging Players: Capture Polish and Australian attack helicopter fleet modernization demand with vibration-hardened multi-sensor configurations. Laser spot detection modules for NATO STANAG 3733 multi-code interoperability offer the most penetrable entry point. Partner with established primes as subsystem suppliers to bypass ITAR technology release barriers. For Investors and Strategic Acquirers: Re-rating potential sits with Israeli combat-proven specialists given sovereign laser code development capabilities and export-oriented production scale. Long-term viability favors archetypes with software-defined architectures enabling field-upgradable threat libraries. Watch divergence between U.S. ITAR policies and European defense procurement autonomy initiatives as inflection signal for cross-border joint venture structuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cryocooler Production | Captures scarce Stirling-cycle expertise and insulates against vacuum engineering bottlenecks. |
| Performance-Based Logistics Contracting | Aligns revenue with availability guarantees demanded by UK and German defense procurement offices. |
| Dual-Band Sensor Fusion Development | Enables countermeasure-resistant targeting for U.S. Navy and Air Force strike squadron specifications. |
| EU AI Act Compliance Architecture | Positions Thales Group and Rafael product lines for emerging autonomous targeting assistance frameworks. |
| Rotary-Wing Pod Miniaturization | Addresses underpenetrated attack helicopter demand in Poland and Australia with compact configurations. |
Research Methodology
Document review covered defense procurement databases, NATO standardization filings, and EU regulatory frameworks, complemented by interviews with fighter squadron operations officers, electro-optical subsystem procurement leads at defense primes, cooled detector foundry technical directors, and military logistics planners. Secondary sources included U.S. Department of Defense budget justification documents, EU defense industrial strategy publications, and national aerospace trade association reports. Bottom-up platform retrofit demand estimates triangulated against top-down defense expenditure projections.
Historical program-of-record procurement patterns cross-referenced against expert panel inputs on laser code interoperability adoption timelines and AI Act implementation trajectories. Segmentation modeling spanned product type, technology, application, and end user dimensions across the projection horizon. CAGRs derived from fitted adoption curves for software-defined architectures and sovereign laser code standardization. Industry-specific inputs incorporated ITAR technology release friction indices and EU Green Deal supplier qualification timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to indium supply disruptions, ITAR-European procurement autonomy divergence, and autonomous targeting liability framework evolution. Forecasts reflect documented assumptions regarding NATO interoperability mandate adherence and combatant command precision strike prioritization. Material deviation in U.S.-China critical mineral trade flows or EU AI Act enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market
Military Equipment and Infrastructure
Global Landing String Equipment Market
Military Equipment and Infrastructure
Global Stealth Warfare Market
Military Equipment and Infrastructure
Used Serviceable Material (USM) Market
Military Equipment and Infrastructure
Global CBRN Defense Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
Man Portable Military Electronics Market
Military Equipment and Infrastructure
Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Defense Logistics Market
Military Equipment and Infrastructure
Deployable Military Shelters Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market
Military Equipment and Infrastructure
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Manpack Military Antennas Market
Military Equipment and Infrastructure
Europe Military Aircraft Modernization and Retrofit Market