
 Defense Ground Support Equipment Market | 2026-2036
Defense Ground Support Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Defense Ground Support Equipment Market Analysis
European defense industrial capacity is restructuring around electrified ground support architectures. Rheinmetall AG leverages its continental manufacturing footprint to dominate armored vehicle support systems. ITW GSE ApS anchors Nordic and Baltic markets through specialized ground power units for F-35 operations. Tronair Inc. competes on air conditioning and maintenance stand portfolios across U.S. Air Force installations.
Defense ground support equipment encompasses mobile and fixed assets that provide electrical power, environmental control, hydraulic pressure, and structural access for military aircraft and vehicles on tarmac or field conditions. These systems typically operate at 115V/400Hz aircraft electrical standards and must withstand -40°C to +55°C ambient temperatures per MIL-STD-810H environmental testing protocols, with primary purpose being mission readiness sustainment between flight operations. Ground power units lead product type demand as fifth-generation fighter fleets expand, while computerized monitoring technology captures fastest growth due to predictive maintenance mandates. Service type revenue pools concentrate in maintenance management contracts as defense agencies outsource lifecycle accountability.
The U.S. Department of Defense enforces MIL-STD-704F power quality standards and OSHA workplace safety rules for flight line equipment, while EMA and national European regulators coordinate CE marking with military exemption pathways under EU procurement directives. NATO's Standardization Office harmonizes interoperability requirements across member nation ground support fleets. Stakeholders must monitor evolving electromagnetic compatibility thresholds as hybrid-electric propulsion demonstrators enter military test programs.
Market Dynamics
MIL-STD-704F compliance mandates are restructuring supplier qualification frameworks across NATO flight lines, forcing ground power unit manufacturers to redesign electrical architectures for fifth-generation fighter sustainment.
Growth Catalysts
- F-35 fleet expansion:NATO member states are procuring specialized ground power units for stealth fighter operations at bases in Germany, Italy, and the United Kingdom.
- CE marking military exemption pathways:EU procurement directives under EMA coordination are accelerating cross-border equipment standardization across European defense industrial bases.
- Predictive maintenance mandates:Computerized monitoring technology adoption is expanding as defense agencies outsource lifecycle accountability to specialized service contractors.
Market Restraints
- Specialized alloy input volatility:Titanium and high-grade aluminum price swings compress margins for hydraulic system manufacturers dependent on aerospace-grade materials.
- Supplier concentration in Nordic regions:ITW GSE ApS and regional specialists control Baltic ground power unit supply, creating single-source vulnerability for F-35 sustainment programs.
- MIL-STD-810H environmental testing costs:Extended certification cycles for -40°C to +55°C operational validation delay new entrant market access.
Strategic Opportunities
- Baltic states modernization:Estonia, Latvia, and Lithuania are expanding air defense infrastructure with NATO-compatible ground support equipment procurement.
- Hybrid-electric propulsion demonstrators:Electromagnetic compatibility testing for next-generation military aircraft is integrating with existing ground power architectures.
- Performance-based logistics contracts:U.S. Air Force maintenance management outsourcing is creating long-term service revenue pools for integrated support providers.
Industry Challenges
- Aircraft electrical standard certification backlog:115V/400Hz ground power unit validation queues at NATO Standardization Office facilities extend supplier onboarding timelines.
- Legacy 28V DC system integration:Mixed-voltage flight line operations require dual-capability equipment designs that increase engineering complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Defense Ground Support Equipment Market |
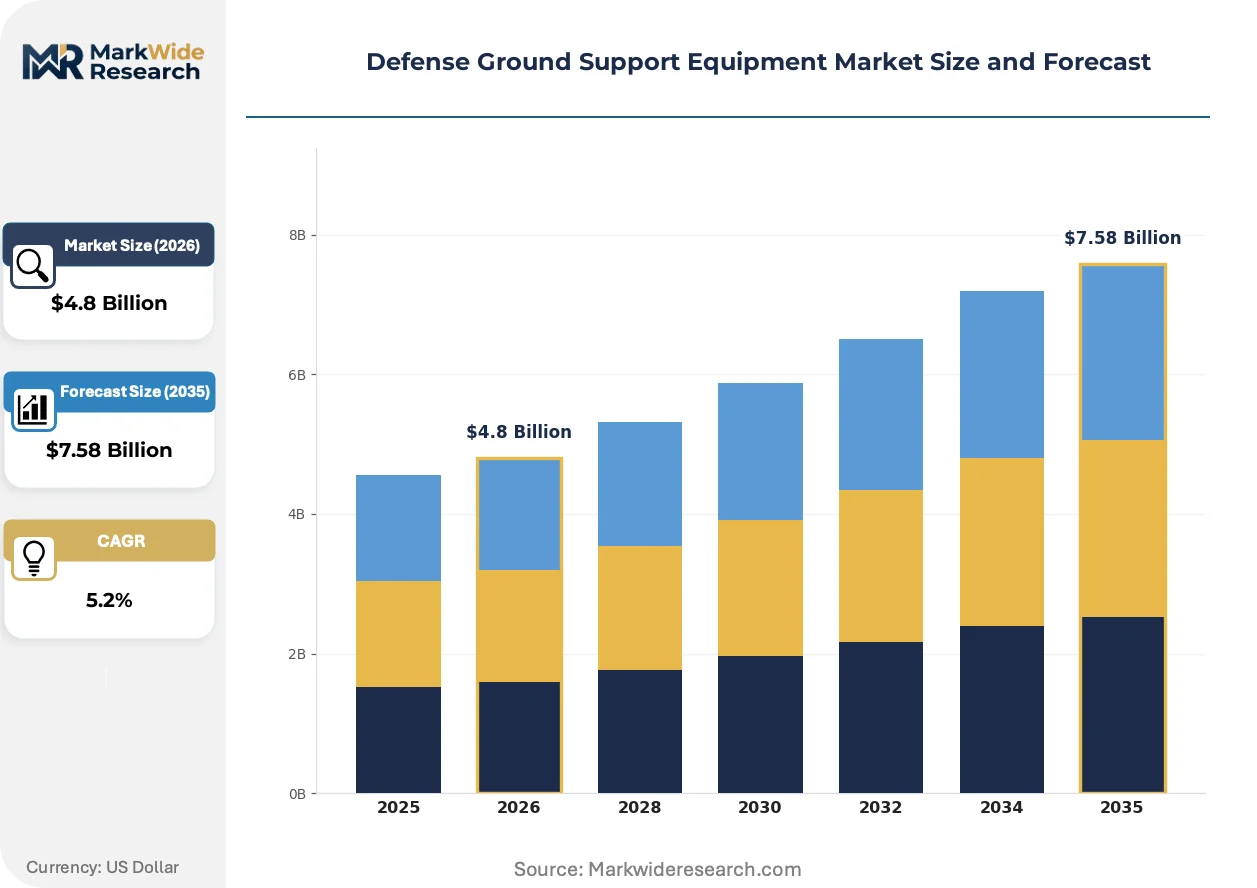
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Conditioning Units, Power Supply Systems, Ground Power Units, Maintenance Stands Technology: Hydraulic Systems, Pneumatic Systems, Electrical Systems, Computerized Monitoring End User: Military Base, Defense Contractor, Government Agency, Aerospace OEM Service Type: Repair Services, Maintenance Management, Training Services, Logistics Support |
| Companies Covered | Tronair Inc., ITW GSE ApS, Rheinmetall AG, Hydraulics International Inc., GATE GSE, Cavotec SA, ATEC, Inc., Air+MAK Industries Inc., JBT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Defense Ground Support Equipment Market Emerging Trajectories
Electrification of ground support architectures is converging with digital monitoring systems to reshape how military bases sustain mission readiness between flight operations.
Silicon carbide power electronics is integrating into next-generation ground power units, enabling higher efficiency conversion for 400Hz aircraft electrical standards. U.S. Air Force installations are adopting these systems for F-22 and F-35 sustainment operations. The technology is integrating predictive load management capabilities that compress generator sizing requirements and reduce fuel consumption during extended ground operations.
REACH chemical substance restrictions are forcing hydraulic fluid formulation changes across European ground support equipment fleets. ECHA compliance deadlines are accelerating R&D investment in bio-based alternatives for armored vehicle maintenance stands. German and French defense contractors are responding with sealed-system designs that minimize fluid exposure and extend service intervals.
Consolidated flight line service contracts are displacing discrete equipment procurement across NATO bases. Defense agencies in the United Kingdom and Norway are bundling ground power, environmental control, and maintenance access systems under single-vendor accountability. This pattern concentrates procurement authority with integrated platform providers and marginalizes standalone equipment specialists.
Defense Ground Support Equipment Market Segmentation
Defense ground support equipment procurement diverges sharply between standardized NATO interoperability requirements and mission-specific custom configurations. Segmentation reveals how electrical architectures, monitoring technologies, and service accountability models allocate capital across flight line operations and armored vehicle sustainment programs.
Product Type:
Standardization dominates power generation and environmental control systems, while maintenance access equipment varies by aircraft platform and base infrastructure.
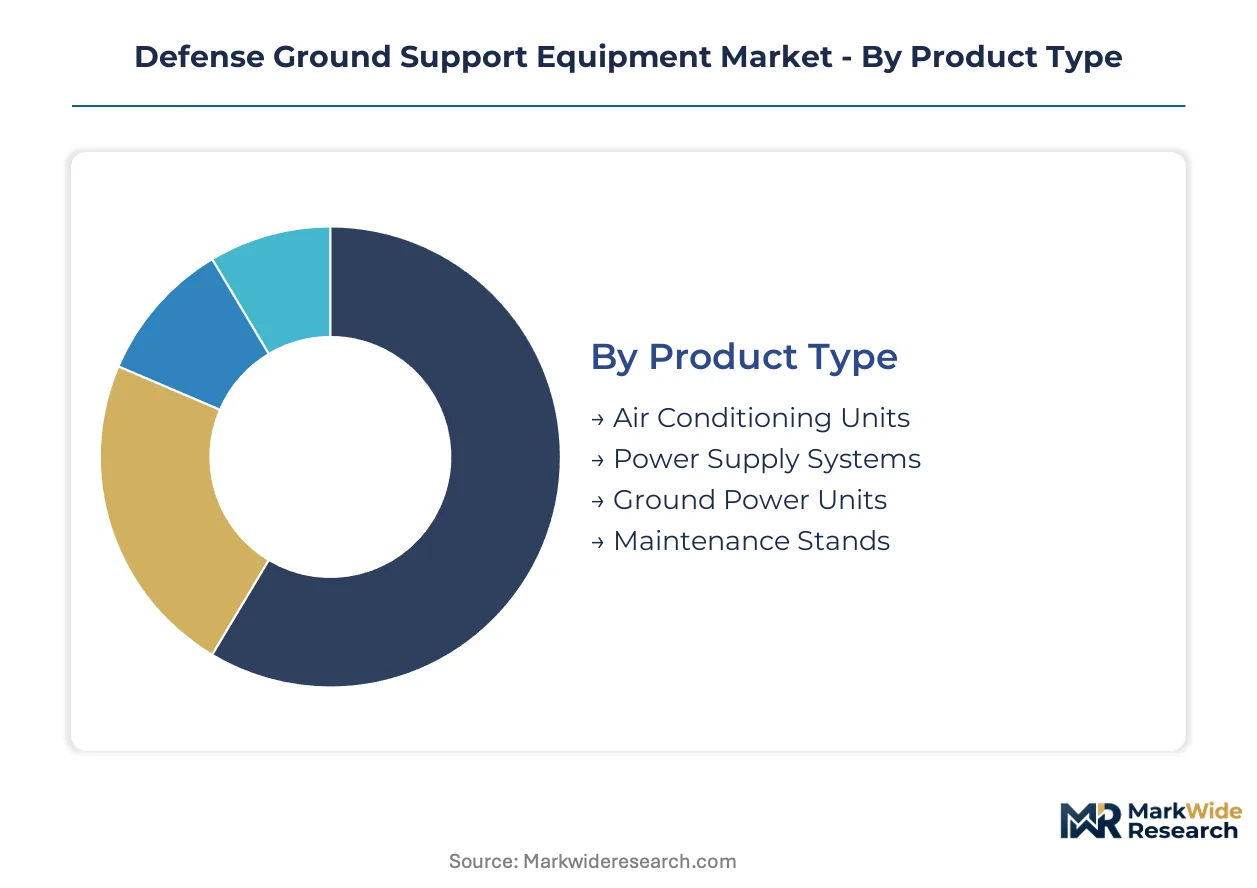
- Ground Power Units:These 115V/400Hz electrical systems provide aircraft power during ground operations and pre-flight sequences. NATO flight lines in Germany and the United Kingdom are concentrating procurement for F-35 sustainment, where MIL-STD-704F compliance mandates are disqualifying legacy suppliers.
- Air Conditioning Units:Environmental control systems regulate cockpit and avionics bay temperatures during extended ground operations. Demand clusters at U.S. Air Force installations in arid climate zones, with ITW GSE ApS and Tronair Inc. competing on portable and fixed-installation variants.
- Power Supply Systems:Fixed-base electrical distribution infrastructure supporting multiple simultaneous aircraft connections.
- Maintenance Stands:Structural access platforms for airframe inspection and component replacement, varying by fighter, transport, and rotary-wing configurations.
Most installed capacity flows through Ground Power Units. Expansion is steepest in Air Conditioning Units as fifth-generation fighter thermal management requirements intensify.
Technology:
Cost tiers separate mature hydraulic and pneumatic architectures from digitally integrated electrical and monitoring systems.
- Computerized Monitoring:Predictive maintenance platforms integrating sensor arrays, load forecasting algorithms, and automated fault detection. U.S. Air Force performance-based logistics contracts are accelerating adoption as contractors assume lifecycle accountability for equipment availability.
- Electrical Systems:Silicon carbide power electronics enabling higher-efficiency 400Hz conversion with reduced fuel consumption. German defense contractors are integrating these architectures into next-generation armored vehicle support equipment.
- Hydraulic Systems:Pressure generation for lifting, positioning, and actuation functions in maintenance stands and cargo loaders.
- Pneumatic Systems:Compressed air delivery for aircraft engine starting and brake systems, prevalent in legacy platform support.
Electrical Systems carry the largest installed base. Computerized Monitoring is climbing the fastest as predictive maintenance mandates spread across NATO procurement frameworks.
End User:
Customer type determines procurement authority concentration and contract structure complexity.
- Military Base:Direct acquisition by air force, army, and naval aviation installations with standardized NATO interoperability requirements. Bases in Italy and Norway are bundling ground power, environmental control, and maintenance systems under consolidated flight line service contracts.
- Defense Contractor:Fleet sustainment outsourcing by primes including Rheinmetall AG and regional specialists managing armored vehicle modernization programs.
- Government Agency:Centralized procurement by defense ministries and national logistics commands.
- Aerospace OEM:Original equipment manufacturers integrating ground support into aircraft delivery packages.
Procurement volume concentrates with Military Base customers. Defense Contractor channels are gaining share fastest as fleet sustainment outsourcing accelerates.
Service Type:
Margin structures favor long-term accountability contracts over discrete repair transactions.
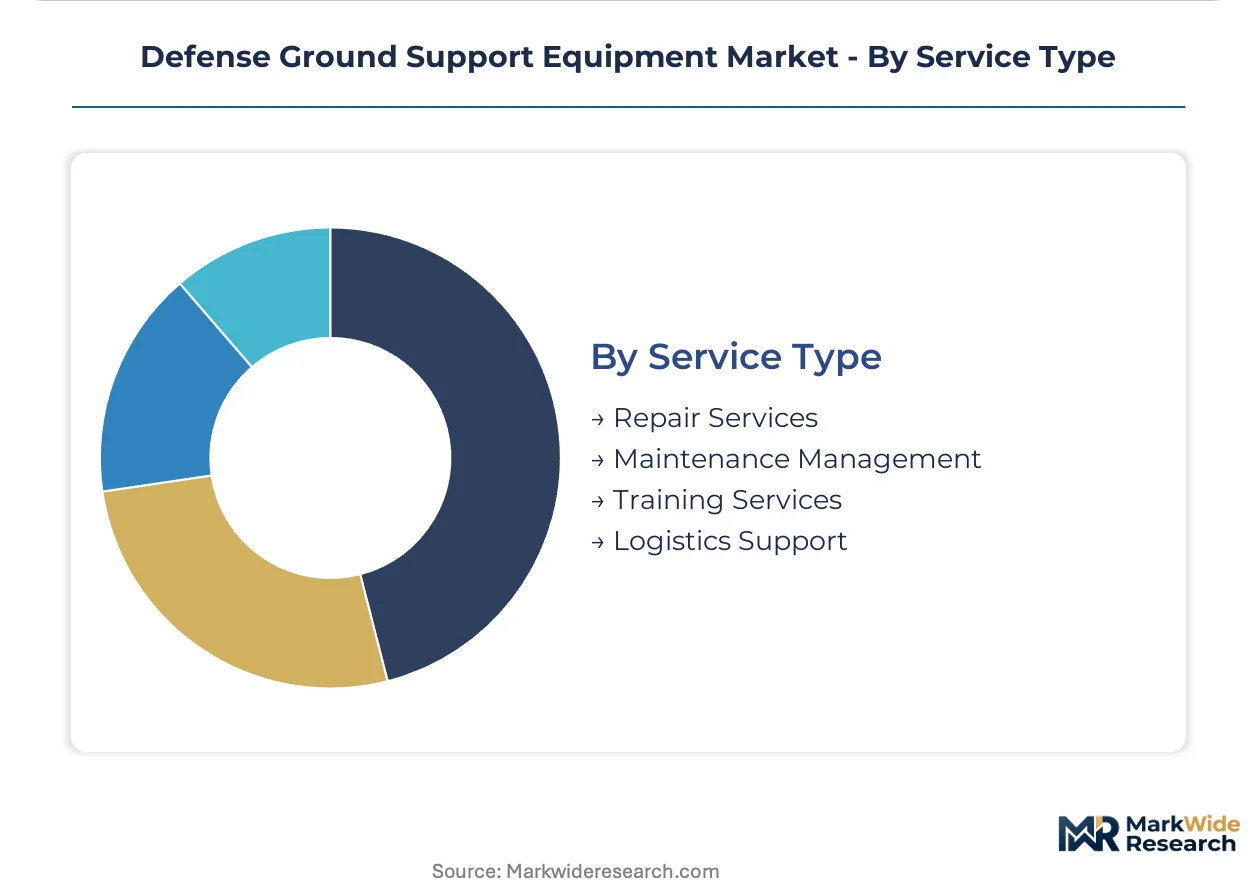
- Maintenance Management:Comprehensive lifecycle accountability encompassing preventive maintenance, spare parts provisioning, and equipment availability guarantees. U.S. Air Force installations are shifting from capital procurement to outcome-based contracts with integrated support providers.
- Logistics Support:Supply chain coordination, transportation, and field deployment services for expeditionary operations.
- Repair Services:Corrective maintenance and component refurbishment on demand.
- Training Services:Operator certification and maintenance technician instruction for specialized equipment.
Revenue pools are deepest in Maintenance Management. Logistics Support is expanding most quickly as expeditionary readiness requirements intensify across Baltic and Nordic defense planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as MIL-STD certification costs diverge across NATO jurisdictions. Production gravitates toward jurisdictions with established defense industrial bases and streamlined military qualification pathways.
United States
The U.S. Department of Defense drives procurement volume through consolidated flight line service contracts at installations across the Sun Belt. OSHA workplace safety rules intersect with MIL-STD-704F power quality mandates to create dual compliance burdens. Greater San Antonio anchors specialized ground power unit manufacturing clusters serving Air Force sustainment operations.
Germany
Rheinmetall AG and regional defense contractors anchor fleet modernization programs with continental manufacturing footprints. EMA-coordinated CE marking with military exemption pathways accelerates cross-border equipment standardization. Bavaria concentrates armored vehicle support system production for NATO interoperability requirements.
United Kingdom
Royal Air Force bases bundle ground power, environmental control, and maintenance access systems under consolidated procurement frameworks. NATO Standardization Office harmonization requirements shape supplier qualification timelines. East Anglia hosts specialized clusters for F-35 ground support equipment integration.
Italy
Aeronautica Militare installations expand fifth-generation fighter sustainment infrastructure across southern bases. EU procurement directives under EMA coordination streamline cross-border defense equipment flows. Campania and Apulia regions concentrate maintenance stand manufacturing for mixed rotary-wing and fixed-wing operations.
Norway
Expeditionary readiness requirements intensify procurement of portable ground power units for Arctic operating conditions. NATO-compatible interoperability mandates dominate specification development for Baltic defense planning support. Bodø and Ørland air stations anchor Nordic ground support equipment modernization programs.
Defense Ground Support Equipment Market Vendor Landscape
German producers anchor one tier of consolidated defense industrial capacity; U.S. and Nordic specialists hold differentiated positions in flight line equipment and Arctic-capable systems. The vendor base structures around three strategic archetypes: integrated platform providers capturing bundled service contracts, specialized electrical system manufacturers, and regional maintenance equipment fabricators. M&A activity concentrates among mid-cap specialists seeking NATO qualification breadth; capacity expansion focuses on silicon carbide power electronics integration.
Within the integrated platform tier, Rheinmetall AG exemplifies continental defense industrial consolidation, while ITW GSE ApS occupies a specialized position in Nordic and Baltic ground power unit supply. Tronair Inc. represents the U.S.-based flight line equipment archetype with air conditioning and maintenance stand portfolios.
| Leading Market Players |
|---|
| Tronair Inc. |
| ITW GSE ApS |
| Rheinmetall AG |
| Hydraulics International Inc. |
| GATE GSE |
| Cavotec SA |
| ATEC, Inc. |
| Air+MAK Industries Inc. |
| JBT Corporation |
| Others |
Supply Flow & Price Mechanics
Aerospace-grade titanium and high-grade aluminum feed through three pricing tiers before reaching hydraulic system manufacturers. Input volatility from Nordic mining operations compresses margins at the standard tier while premium-tier suppliers pass through alloy cost swings via long-term NATO procurement contracts.
Pricing Analysis
Distributor margins for ground power units range from 15% in direct-to-OEM military contracts to 35% through specialized defense equipment dealers. Three-tier pricing structure across MIL-STD-704F certified, CE-marked military exemption, and legacy equipment levels separates procurement pools. Pricing pressure stems from REACH compliance costs forcing hydraulic fluid reformulation. Government agencies exhibit lowest price sensitivity due to performance-based logistics mandates, while regional defense contractors face acute cost compression.
Supply Chain Analysis
Refurbishment flows for 115V/400Hz ground power units concentrate in Germany and the United Kingdom, extending equipment lifecycles for NATO flight lines. Component sourcing draws from titanium suppliers in Norway, aluminum smelters in Iceland, and silicon carbide substrate producers in the United States. Single-source vulnerability pervades Baltic ground power unit supply controlled by Nordic specialists. Distribution runs through Rheinmetall AG's continental network for armored vehicle support systems and ITW GSE ApS's Nordic-Baltic channels for fighter sustainment equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense ground support equipment procurement rewards geographic arbitrage between Germany's streamlined CE marking military exemption pathways and the United States' extended MIL-STD certification queues. Regulatory cost differentials favor continental European manufacturing footprints for NATO interoperability requirements.
For Market Incumbents: Anchor continental manufacturing capacity in Bavaria and Greater San Antonio to exploit divergent certification timelines across NATO jurisdictions. Defend against silicon carbide power electronics disruption by captive supply of semiconductor substrates. Lock in performance-based logistics contracts with U.S. Air Force installations before bundled service consolidation accelerates. For New Entrants and Emerging Players: Capture Baltic states modernization procurement as Estonia, Latvia, and Lithuania expand NATO-compatible air defense infrastructure. Arctic-capable portable ground power units for Norwegian expeditionary operations represent the most penetrable white space. Enter through specialized electromagnetic compatibility testing services for hybrid-electric propulsion demonstrators. For Investors and Strategic Acquirers: Consolidation pressure builds where MIL-STD-704F compliance mandates disqualify legacy suppliers lacking capital for electrical architecture redesign. Long-term viability hinges on integrated platform capabilities spanning power generation, environmental control, and maintenance access. Target mid-cap specialists with NATO Standardization Office pre-qualification. Monitor aircraft electrical standard certification queue lengths at NATO facilities as early inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Electronics Integration | Higher-efficiency 400Hz conversion reduces fuel consumption for F-35 ground operations. |
| Performance-Based Logistics Contract Capture | U.S. Air Force outsourcing creates long-term revenue pools for integrated support providers. |
| CE Marking Military Exemption Pathway Investment | EMA-coordinated compliance accelerates cross-border equipment flows across European defense bases. |
| Arctic-Capable System Development | Norwegian and Baltic expeditionary requirements drive portable ground power unit demand. |
| Predictive Maintenance Platform Deployment | Computerized monitoring adoption spreads across NATO procurement frameworks for lifecycle accountability. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from defense procurement officers at NATO air bases, ground support equipment engineering directors, military logistics command staff, and aftermarket service contract managers. Secondary validation drew from U.S. Department of Defense contract announcements, NATO Standardization Office harmonization documents, EMA regulatory guidance, and national defense ministry budget disclosures. Bottom-up equipment installation counts triangulated against top-down defense expenditure allocations.
Segment-weighting approaches distributed value across product types, technology tiers, end-user categories, and service models. Ground power units, air conditioning systems, maintenance stands, and power supply infrastructure formed the product dimension. Electrical, computerized monitoring, hydraulic, and pneumatic architectures shaped the technology split. Military base direct procurement, defense contractor outsourcing, government agency centralized buying, and aerospace OEM integration defined customer channels. CAGRs derived from equipment replacement cycles, fleet expansion schedules, and regulatory compliance deadlines. Hybrid-electric propulsion testing timelines and REACH chemical restriction phase-ins supplied industry-specific forecast inputs.
Underlying measurement precision varies by segment; ground power unit volumes carry tighter precision than emerging computerized monitoring adoption curves. Forecasts rest on assumptions including sustained NATO defense spending commitments, MIL-STD-704F enforcement continuity, and silicon carbide supply chain scaling. Practitioners should monitor NATO Standardization Office certification queue lengths, titanium spot price volatility, and Baltic air defense infrastructure budget approvals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Global Soldier Modernization Market
Military Equipment and Infrastructure
CBRNE Defense Market
Military Equipment and Infrastructure
Global Mine Countermeasures Market
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
NATO Defense Market
Military Equipment and Infrastructure
Global Landing String Equipment Market
Military Equipment and Infrastructure
Man Portable Military Electronics Market
Military Equipment and Infrastructure
Latin America Defense Market
Military Equipment and Infrastructure
Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Air-Based Remote Weapon Stations Market
Military Equipment and Infrastructure
Howitzer Artillery System Market
Military Equipment and Infrastructure
Military Wearable Computers Market
Military Equipment and Infrastructure
Military Displays Market
Military Equipment and Infrastructure
Global Armor Materials Market
Military Equipment and Infrastructure
Used Serviceable Material (USM) Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market