
 Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market | 2026-2036
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market Size, Share, and Industry Trends Forecast 2026-2036
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market Insights
Asian shipyard clusters is restructuring naval MRO capacity as regional powers expand sovereign maintenance capabilities. Huntington Ingalls Industries dominates nuclear carrier and submarine overhaul work at its Newport News facility. BAE Systems anchors Royal Navy surface fleet support through Portsmouth and Devonport infrastructure. General Dynamics Corporation leverages Electric Boat division expertise to sustain US Navy submarine lifecycle programs.
Naval Vessel Maintenance, Repair, and Overhaul encompasses the technical preservation, defect correction, and capability enhancement of military surface and subsurface platforms through scheduled dry docking, mechanical refurbishment, and systems integration to sustain operational availability and extend service life beyond original design parameters. Hull Maintenance and Propulsion Systems capture the largest share of repair component spending due to saltwater corrosion cycles and powerplant complexity. Predictive Maintenance represents the fastest-expanding maintenance strategy segment as sensor networks and digital twin platforms enable condition-based intervention before critical failure.
US Navy maintenance standards, UK Defence Equipment & Support regulations, and Japan Maritime Self-Defense Force technical directives collectively shape contractor qualification requirements and facility certification protocols across major naval MRO markets. Classification societies including Lloyd's Register and DNV enforce hull integrity and safety system standards that gate market access for repair providers. Stakeholders must monitor sovereign content requirements and cross-border technology transfer restrictions as fleet recapitalization programs accelerate across competing naval powers.
Market Dynamics
Condition-based maintenance protocols are displacing calendar-driven overhaul schedules across NATO naval fleets, compressing dry-docking intervals while extending hull service life through predictive analytics integration.
Growth Catalysts
- US Navy Phased Maintenance Modernization:The program redirects carrier and submarine contracts toward continuous maintenance cycles, creating sustained demand for specialized shipyard infrastructure.
- Indo-Pacific Sovereign Capacity Expansion:Japan, Australia, and South Korea are constructing dedicated naval maintenance facilities to reduce foreign contractor dependence.
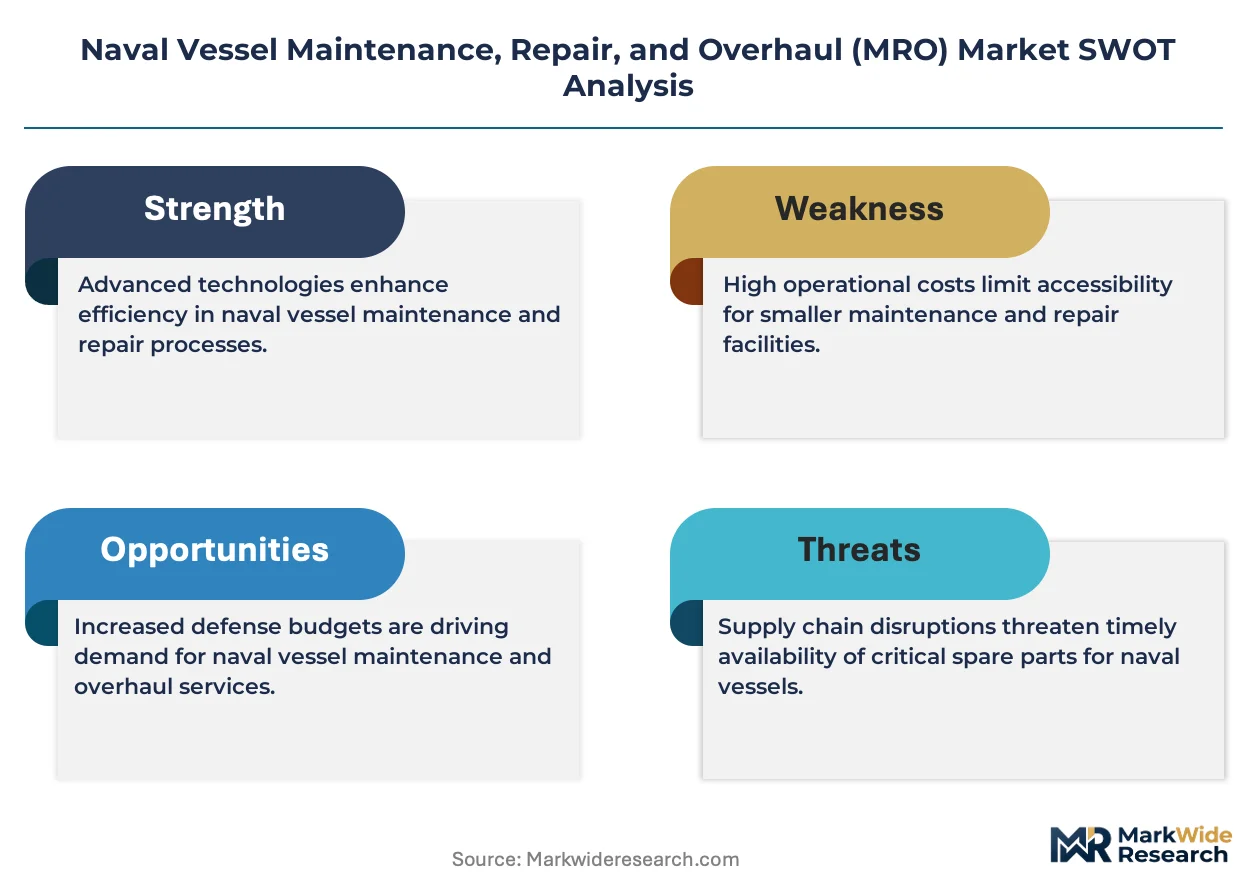
- Predictive Maintenance Technology:Sensor networks and digital twin platforms enable defect detection before critical failure, reducing unplanned downtime.
Market Restraints
- Specialized Labor Scarcity:Nuclear-certified welders and submarine reactor technicians command premium wages, constraining shipyard expansion timelines.
- Steel and Nickel Alloy Volatility:Hull plate and corrosion-resistant piping material costs fluctuate with commodity markets, squeezing fixed-price contract margins.
- Facility Concentration Risk:US nuclear carrier overhaul capacity concentrates at Newport News, creating single-point vulnerability for fleet availability.
Strategic Opportunities
- Underpenetrated Southeast Asian Markets:Vietnam and Indonesia lack indigenous submarine maintenance infrastructure, presenting partnership openings for established yards.
- EU Green Deal Naval Adaptation:Emissions reduction mandates for port operations create demand for shore power integration and hull coating upgrades.
- Autonomous Underwater Vehicle Convergence:Unmanned platform maintenance requires new dry-docking configurations and electronic systems expertise.
Industry Challenges
- Classification Society Certification Bottlenecks:Lloyd's Register and DNV hull integrity verification queues extend project kickoff by months.
- Legacy Combat System Integration:New radar and electronic warfare modules must interface with obsolete shipboard architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market |
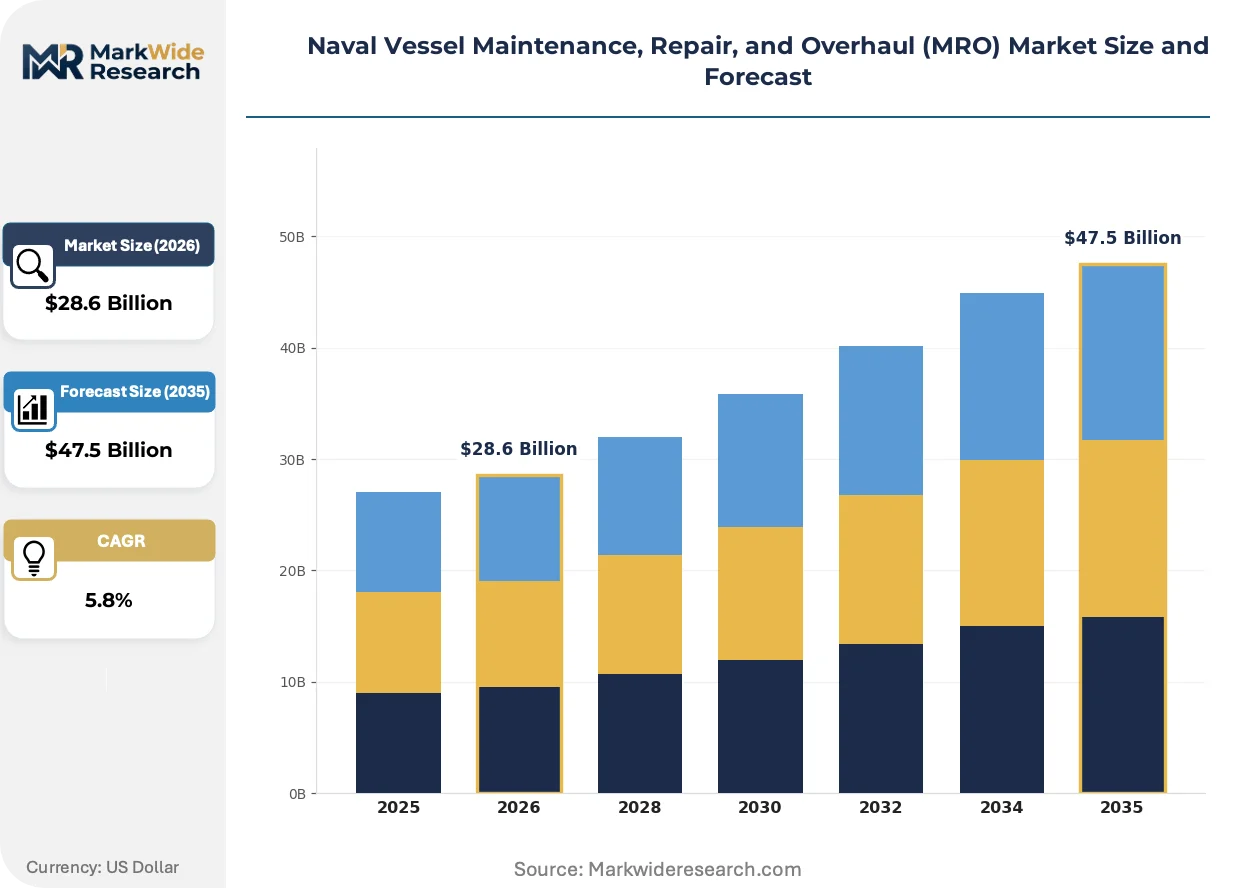
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dry Docking, Routine Maintenance, Emergency Repairs, Upgrades End User: Naval Fleets, Commercial Shipping, Government Agencies, Private Operators Repair Component: Hull Maintenance, Propulsion Systems, Electrical Systems, Communication Equipment Maintenance Strategy: Preventive Maintenance, Predictive Maintenance, Corrective Maintenance, Overhaul |
| Companies Covered | Sembcorp Marine, Navantia, Huntington Ingalls Industries, Damen Shiprepair & Conversion, Samsung Heavy Industries, BAE Systems, Keppel Offshore & Marine, Fincantieri, General Dynamics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market Trends and Innovations
Digitalization is compressing maintenance detection-to-repair cycles while sovereign fleet expansion strains existing yard capacity. Three developments are restructuring competitive positioning.
Digital twin technology is rewriting how surface combatants undergo lifecycle management. The US Navy's Shipyard Infrastructure Optimization Program mandates virtual hull stress modeling before physical dry-docking. This capability is compressing overhaul planning from years to months.
REACH chemical restrictions are forcing coating system reformulation across European naval maintenance. Banned biocides in anti-fouling paints require shipyards to certify alternative surface treatments. Surface fleet operators in the UK and France face extended dry-docking periods during material transition.
Fleet availability contracting is displacing traditional time-and-material arrangements. Sovereign navies now demand guaranteed operational days rather than repair completion milestones. Australian and Japanese defense procurement agencies lead this specification shift.
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market Segmentation
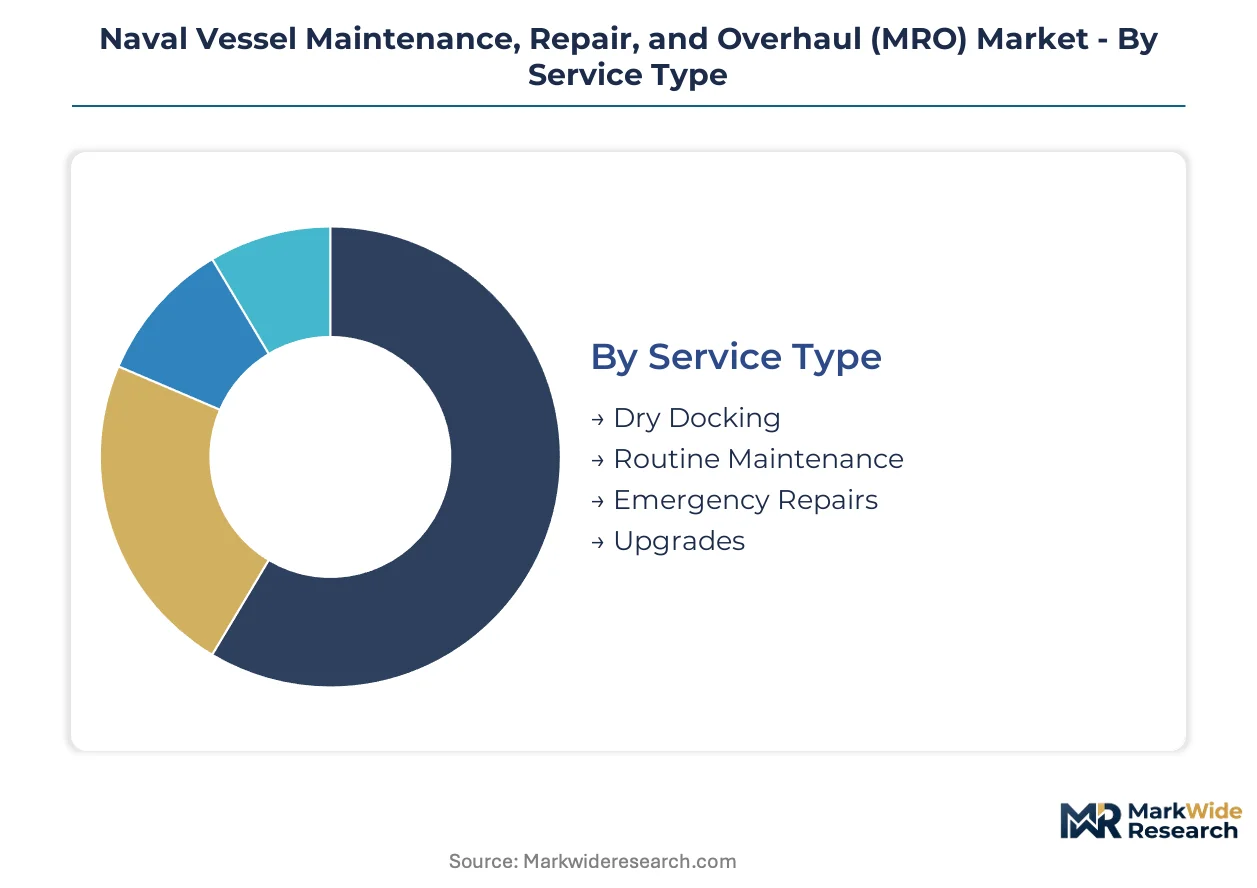
Segmentation of naval vessel MRO services reveals how procurement patterns diverge across vessel lifecycle stages and operational readiness requirements. Contract structures, facility certifications, and technology integration intensity vary materially by service type, end user, and maintenance philosophy.
Service Type:
Dry-docking cycles anchor naval fleet availability schedules, with each service tier demanding distinct yard infrastructure and labor specializations.
- Dry Docking:Scheduled hull inspection and below-waterline repair requiring graving dock or floating dry dock capacity. US Navy carrier overhaul contracts concentrate at Newport News, where nuclear-certified infrastructure limits competitor entry.
- Routine Maintenance:Periodic mechanical servicing and system calibration performed pierside without vessel immobilization. Royal Navy surface fleet contracts through BAE Systems Portsmouth emphasize continuous availability over calendar-based intervals.
- Emergency Repairs:Unplanned damage remediation following collision, grounding, or combat system failure. Demand clusters near Indo-Pacific chokepoints where forward-deployed fleets face elevated operational tempo.
- Upgrades:Capability enhancement through combat system insertion and platform modernization. Japan Maritime Self-Defense Force contracts prioritize electronic warfare and missile defense integration during mid-life refits.
Dry Docking leads on scale; Upgrades leads on momentum.
End User:
Procurement authority shapes contract duration, security clearance requirements, and sovereign content mandates.
- Naval Fleets:Sovereign military operators demanding classified facility access and nuclear certification where applicable. US Navy maintenance modernization program redirects spending toward condition-based contracts with guaranteed availability metrics.
- Commercial Shipping:Container and bulk carrier operators governed by classification society survey schedules. Lloyd's Register and DNV hull integrity verification creates compliance-driven demand spikes at statutory intervals.
- Government Agencies:Coast guard and maritime patrol services with dual-use enforcement missions. Australian Border Force vessel sustainment contracts blend military specification with commercial cost discipline.
- Private Operators:Research vessels and offshore support contractors operating outside naval procurement frameworks. South Korean shipyards target this segment to offset cyclical naval contract volatility.
Naval Fleets command contract value; Government Agencies expand procurement fastest.
Repair Component:
Material degradation patterns and system complexity determine labor skill premiums and spare parts supply chain configurations.
- Hull Maintenance:Steel plate replacement, coating reapplication, and structural reinforcement addressing saltwater corrosion. REACH chemical restrictions in European yards force biocide-free anti-fouling formulation transitions.
- Propulsion Systems:Gas turbine, diesel, and nuclear reactor overhaul requiring OEM technical authorization. US Navy submarine reactor work concentrates at General Dynamics Electric Boat with no qualified domestic competitor.
- Electrical Systems:Power distribution, switchgear, and motor control refurbishment. Shore power integration demand rises under EU Green Deal port emissions mandates.
- Communication Equipment:Radio, satellite, and cryptographic system upgrade. UK Defence Equipment and Support regulations govern classified electronics handling protocols.
Hull Maintenance dominates spending volume; Electrical Systems gains share through platform electrification trends.
Maintenance Strategy:
Technology adoption curves separate early movers with sensor infrastructure from legacy calendar-driven operators.
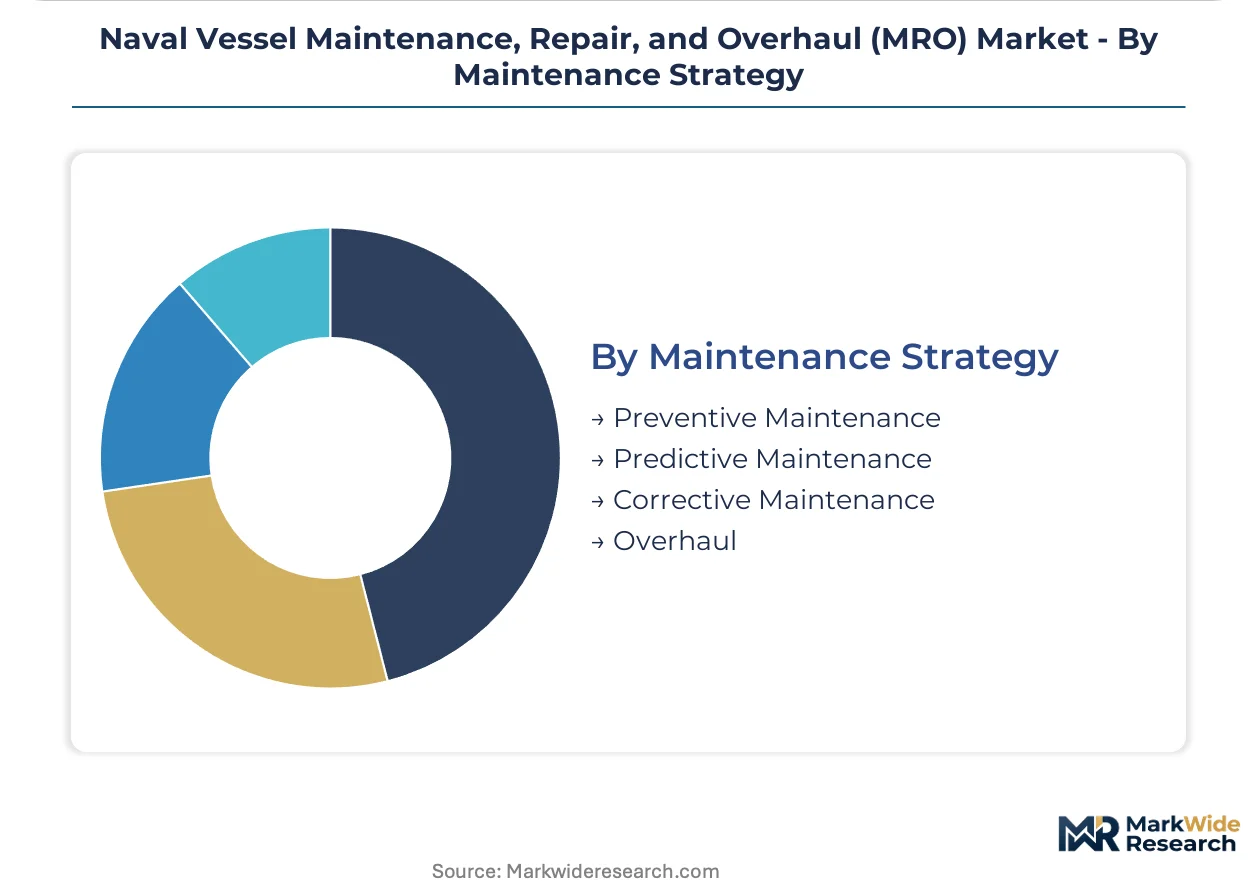
- Preventive Maintenance:Scheduled component replacement based on operating hours or calendar intervals. Royal Navy surface fleet has begun displacing rigid schedules with condition-monitored alternatives.
- Predictive Maintenance:Sensor networks and digital twin platforms enabling failure anticipation. US Navy Shipyard Infrastructure Optimization Program mandates virtual hull stress modeling before physical dry-docking.
- Corrective Maintenance:Reactive repair following detected malfunction or performance degradation. Emergency response contracts carry premium pricing due to fleet availability consequences.
- Overhaul:Comprehensive platform restoration extending service life beyond original design parameters. Japanese defense procurement agencies now specify guaranteed operational days rather than repair completion milestones.
Preventive Maintenance retains installed base; Predictive Maintenance climbs fastest as digital infrastructure deploys.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping naval MRO capacity placement as sovereign content requirements and nuclear certification costs drive facility investment toward jurisdictions with streamlined defense procurement frameworks. Compliance cost differentials between NATO and non-NATO yards are redirecting maintenance contract flows across the Indo-Pacific and Atlantic basins.
United States
The US Navy's phased maintenance modernization program sustains demand for nuclear-certified infrastructure at Newport News and Electric Boat facilities. DOD procurement regulations mandate domestic source requirements for carrier and submarine overhaul work. Huntington Ingalls Industries anchors nuclear surface fleet maintenance at its Virginia shipyard while General Dynamics concentrates submarine reactor work in Connecticut and Rhode Island.
United Kingdom
Royal Navy fleet availability targets are compressing dry-docking intervals through Portsmouth and Devonport infrastructure. UK Defence Equipment & Support regulations govern contractor qualification and classified facility access for surface combatant support. BAE Systems maintains sovereign capacity for destroyer and frigate lifecycle programs across southern England naval bases.
Japan
Japan Maritime Self-Defense Force expansion is driving dedicated submarine maintenance facility construction at Kure and Yokosuka. METI industrial policy supports shipyard modernization grants under defense production base legislation. Mitsubishi Heavy Industries and Kawasaki Heavy Industries are upgrading dry-dock capacity to reduce reliance on US forward-deployment support.
South Korea
DSME and Hyundai Heavy Industries are diversifying from commercial construction into naval MRO through Busan and Geoje yard investments. MFDS defense procurement regulations are tightening sovereign content thresholds for foreign military sales offset programs. Samsung Heavy Industries is retrofitting commercial dry docks for KDX destroyer mid-life refit contracts.
Australia
Hunter-class frigate and AUKUS submarine programs are catalyzing Osborne and Henderson facility expansion under sovereign shipbuilding enterprise frameworks. TGA-equivalent defense certification requirements are mandating Australian-located heavy maintenance for nuclear-powered platforms. BAE Systems Australia and ASC Pty Ltd are developing nuclear-safety infrastructure through technology transfer agreements with UK and US partners.
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent commercial-offshore conversion capabilities to access naval maintenance revenue streams. The market structure concentrates around sovereign-linked defense contractors with nuclear certification and classified facility access, while tier-two players compete for surface fleet availability contracts without reactor work authorization. Strategic archetypes include integrated naval primes with captive shipyard infrastructure, commercial yard operators diversifying into military maintenance, and specialist submarine reactor service providers. Competitive moves center on sovereign partnership formation and digital twin capability acquisition to secure condition-based maintenance contracts.
Within the integrated prime tier, Huntington Ingalls Industries and General Dynamics Corporation exemplify the nuclear-certified infrastructure archetype that gates access to US Navy carrier and submarine overhaul programs. BAE Systems occupies a parallel position in UK and Australian markets through Portsmouth, Devonport, and Osborne facility networks. Among European surface fleet specialists, Navantia and Fincantieri represent the Mediterranean-located alternative for NATO allied navy support contracts. Sembcorp Marine and Keppel Offshore & Marine anchor Southeast Asian commercial-naval crossover capacity, while Damen Shiprepair & Conversion exemplifies the modular repair network approach across Northern European and African ports.
| Leading Market Players |
|---|
| Sembcorp Marine |
| Navantia |
| Huntington Ingalls Industries |
| Damen Shiprepair & Conversion |
| Samsung Heavy Industries |
| BAE Systems |
| Keppel Offshore & Marine |
| Fincantieri |
| General Dynamics Corporation |
| Others |
Pricing and Supply Chain Analysis
Certification-tier divergence between nuclear-qualified and conventional surface fleet contractors splits both pricing power and supplier networks across fundamentally different qualification ladders. US Navy carrier overhaul contracts at Newport News command substantial premiums over commercial dry-docking rates, while non-nuclear surface combatant work at regional yards competes on throughput efficiency and labor arbitrage.
Pricing Analysis
Direct-to-naval-procurement channels capture the dominant contract flow, with prime contractors embedding facility certification costs into long-term availability agreements. Price differentiation centers on nuclear certification grade and sovereign security clearance tier, with US and UK naval contracts carrying 40-60% premiums over NATO allied navy work. Cost compression in conventional hull maintenance is intensifying as South Korean and Japanese yards expand sovereign capacity. Government agencies with dual-use enforcement missions exhibit highest price sensitivity, while nuclear fleet operators demonstrate lowest sensitivity due to single-source infrastructure constraints.
Supply Chain Analysis
Specialty steel and nickel alloy supply rests on Japanese and South Korean metallurgical producers, with US and European mills serving residual NATO demand. Hull plate, corrosion-resistant piping, and reactor-grade forgings constitute the critical input trinity. Single-source vulnerability concentrates in nuclear-certified forging capacity, where Nippon Steel and Doosan Heavy anchor global availability. Distribution runs through defense-procurement frameworks with sovereign content mandates, limiting cross-border contractor mobility despite cost differentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Naval MRO procurement has shifted toward guaranteed fleet availability metrics, elevating contractor performance reliability over unit cost minimization as the dominant selection criterion.
For Market Incumbents: Lock in nuclear certification moats through accelerated Electric Boat and Newport News capacity expansion before Australian AUKUS infrastructure matures. Huntington Ingalls and General Dynamics should deepen reactor technician apprenticeship pipelines to preempt specialized labor scarcity. Counter emerging South Korean sovereign capacity by embedding digital twin capabilities into existing carrier overhaul contracts. For New Entrants and Emerging Players: Southeast Asian government agencies with maritime enforcement missions present the most penetrable buyer archetype, with Vietnam and Indonesia lacking indigenous submarine maintenance infrastructure. Partner with established Japanese or South Korean yards for technology transfer rather than competing on nuclear certification. Target commercial-offshore vessel conversion capabilities as a beachhead for naval patrol craft contracts. For Investors and Strategic Acquirers: Consolidation pressure builds where sovereign content requirements fragment addressable market access across incompatible procurement frameworks. Long-term viability favors vertically integrated primes with captive nuclear infrastructure over regional surface fleet specialists. Watch Australian Osborne facility commissioning timelines as the inflection signal for Indo-Pacific capacity rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | US Navy Shipyard Infrastructure Optimization Program mandates virtual hull modeling before dry-docking. |
| Nuclear Certification Investment | AUKUS submarine programs require Australian-located heavy maintenance infrastructure development. |
| Sovereign Partnership Formation | Japan METI shipyard modernization grants support defense production base legislation compliance. |
| Specialized Labor Pipeline Development | Nuclear-certified welder scarcity at Newport News constrains carrier overhaul expansion timelines. |
| REACH-Compliant Coating Reformulation | EU Green Deal mandates force biocide-free anti-fouling transitions across European naval yards. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region balanced against secondary validation. Shipyard operations directors, naval procurement officers at defense ministries, classification society surveyors, and nuclear certification specialists contributed structured interviews. Secondary sources include US Navy maintenance modernization program disclosures, UK Defence Equipment & Support contract announcements, Japan METI industrial policy filings, Lloyd's Register hull integrity standards, and DNV maritime classification protocols. Bottom-up vessel lifecycle cost modeling and top-down defense budget allocation analysis were triangulated for segment sizing.
Rate-of-change decomposition separates fleet expansion effects from maintenance intensity shifts across the projection horizon. Segmentation dimensions modeled include service type, end user procurement authority, repair component category, and maintenance strategy philosophy. CAGRs were derived from defense budget trajectory analysis and dry-docking cycle compression rates. Forecast inputs incorporate AUKUS submarine delivery schedules and Japan Maritime Self-Defense Force expansion targets.
Inputs from US Navy program offices and UK Ministry of Defence were available through the study window; gaps in classified submarine maintenance cost data introduce uncertainty bands around nuclear fleet segments. Forecasts reflect documented assumptions regarding sovereign content threshold stability and classification society certification queue durations. Regulatory shifts in EU naval emissions mandates and Indo-Pacific technology transfer restrictions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
CBRNE Defense Market
Military Equipment and Infrastructure
Military Displays Market
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market
Military Equipment and Infrastructure
Deployable Military Shelter Systems Market
Military Equipment and Infrastructure
Air Independent Propulsion Systems for Submarine Market
Military Equipment and Infrastructure
Defense Logistics Market
Military Equipment and Infrastructure
Military Test Equipment Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Global Armor Materials Market
Military Equipment and Infrastructure
Global Remote Weapon Station Market
Military Equipment and Infrastructure
CBRN Protection Equipment Market
Military Equipment and Infrastructure
Europe Digital Battlefield Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market
Military Equipment and Infrastructure
Global Stealth Warfare Market
Military Equipment and Infrastructure
Aircraft Carrier Arresting Systems Market