
 CBRNE Defense Market | 2026-2036
CBRNE Defense Market Size, Share, and Industry Trends Forecast 2026-2036
CBRNE Defense Market Analysis
Graphene-based sensing substrates is decoupling legacy semiconductor detector economics from performance trajectories in next-generation threat identification platforms. Thales Group leverages its integrated defense electronics architecture to anchor European military detection programs. Rheinmetall AG competes through armored vehicle-integrated CBRNE reconnaissance systems. Leidos Inc. specializes in analytics-driven planning software for incident response coordination across federal agencies.
CBRNE defense encompasses technologies, equipment, and protocols designed to detect, identify, protect against, and mitigate chemical, biological, radiological, nuclear, and explosive threats, with detection systems typically achieving parts-per-billion sensitivity for nerve agents and biological aerosols through ion mobility spectrometry and PCR-based assays. The primary industrial purpose centers on preserving operational continuity for military units, first responders, and critical infrastructure operators facing asymmetric or terrorist-deployed unconventional weapons. Detection Systems commands the largest revenue share due to persistent military modernization cycles and replacement demand for aging point detectors, while Planning Software represents the fastest-expanding segment as artificial intelligence-enabled consequence modeling gains traction in emergency management agencies. Protective Equipment remains structurally mature with stable replacement demand but thinner margins, whereas Decontamination Solutions concentrates margin pools in mobile platform integrations for military field deployment.
The U.S. FDA and EPA jointly shape product standards for civilian-deployed biological detection kits and decontamination chemistries, while NATO standardization agreements govern interoperability requirements for military equipment across allied procurement programs. The EU AI Act introduces emerging compliance obligations for autonomous threat-classification algorithms embedded in next-generation detection architectures. Stakeholders must monitor how dual-use export control expansions affect cross-border technology transfer for advanced sensor components.
Market Dynamics
Graphene-based sensing substrates are decoupling legacy semiconductor detector economics from performance trajectories, forcing defense procurement agencies to rewrite technical specifications for next-generation threat identification platforms while incumbent suppliers race to retool manufacturing footprints.
Growth Catalysts
- NATO Standardization Agreements:Allied military procurement programs now mandate interoperability requirements for chemical and biological detection equipment, creating synchronized replacement cycles across member state defense ministries.
- Urban Area Security Initiative funding:The United States Department of Homeland Security sustains investment in portable detection systems and advanced protective ensembles for metropolitan first responder networks.
- Artificial intelligence-enabled consequence modeling:Emergency management agencies accelerate software procurement for incident response coordination, pulling analytics capabilities into federal deployment specifications.
Market Restraints
- Dual-use export control expansions:Cross-border technology transfer for advanced sensor components faces tightening restrictions from national security regulators, fragmenting supplier access to critical semiconductor substrates.
- Parts-per-billion sensitivity thresholds:Ion mobility spectrometry and PCR-based assay platforms require calibration infrastructure that concentrates maintenance expertise in specialized military laboratories.
- Mobile platform integration complexity:Armored vehicle-integrated CBRNE reconnaissance systems demand hardened electronics that resist electromagnetic interference, limiting vendor pools to defense-integrated suppliers.
Strategic Opportunities
- Emergency management software unification:Federal agencies seek consolidated analytics platforms that bridge planning, detection, and decontamination workflows, opening white space for system-of-systems architects.
- Autonomous threat-classification algorithms:The EU AI Act introduces compliance obligations that favor vendors with pre-certified machine learning pipelines for biological aerosol identification.
- Field-deployable decontamination chemistries:Military units require mobile platform integrations that reduce logistical burden, creating demand for concentrated decontamination solutions with extended shelf stability.
Industry Challenges
- Legacy point detector interoperability:Aging chemical detection networks in NATO arsenals use proprietary data protocols that resist integration with next-generation graphene-based sensor architectures.
- Biological detection kit certification timelines:Joint FDA and EPA review processes for civilian-deployed assays extend development cycles, compressing competitive windows for novel pathogen identification platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CBRNE Defense Market |
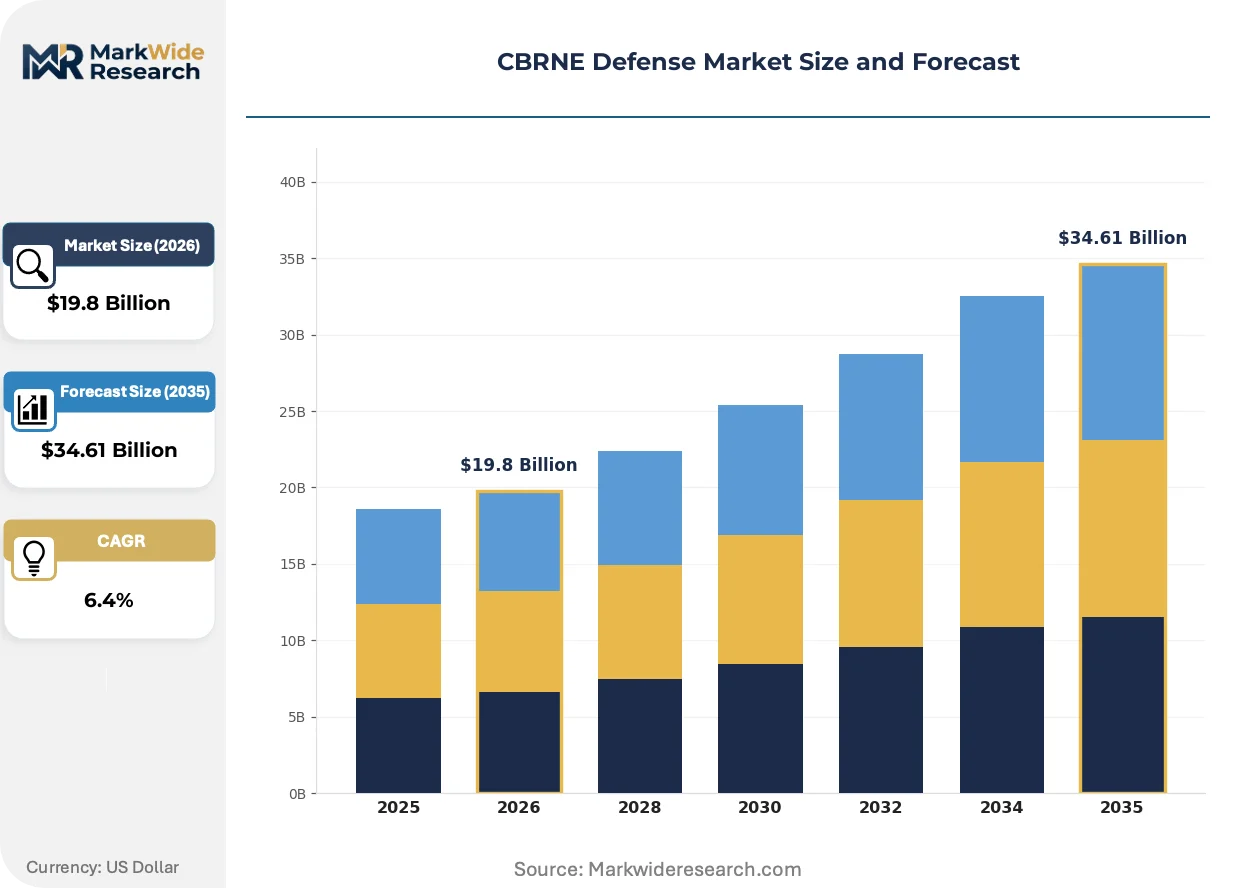
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $34.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Detection Systems, Protective Equipment, Decontamination Solutions, Planning Software End User: Military, Law Enforcement, Emergency Services, Industrial Application: Risk Assessment, Training, Incident Response, Surveillance Component: Sensors, Software, Personal Gear, Support Systems |
| Companies Covered | Thales Group, Smiths Group plc, Teledyne FLIR LLC, Bruker Corporation, Rheinmetall AG, Argon Electronics Ltd, Avon Protection, Battelle, Leidos Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CBRNE Defense Market Emerging Trajectories
Threat detection architectures are converging around materials science breakthroughs and algorithmic classification methods that compress response timelines from minutes to seconds while regulatory frameworks scramble to keep pace with autonomous system deployment.
Graphene-based sensing substrates is integrating molecular capture layers with semiconductor fabrication techniques to achieve sub-parts-per-billion sensitivity for nerve agent vapor detection. Military procurement agencies in NATO member states are adopting these platforms for next-generation point detectors, replacing legacy ion mobility spectrometry units that require heated drift tubes and carrier gas logistics. The technology is integrating threat identification workflows with reduced power budgets and form factors, enabling wearable deployment for individual warfighter protection.
The EU AI Act imposes conformity assessment requirements on autonomous threat-classification algorithms embedded in detection systems, forcing vendors to document training data provenance and decision transparency. Equipment manufacturers serving European defense ministries must now segregate machine learning pipelines into certifiable modules distinct from hardware platforms. Biological detection kit suppliers face the steepest compliance burden, as aerosol identification algorithms require revalidation under the Act's risk-based classification framework.
First responder agencies are consolidating procurement authority under regional homeland security grant administrators, compressing vendor access from municipal fire departments to centralized state-level acquisition offices. This concentration shifts competitive emphasis from product specifications to program-level service contracts encompassing training, maintenance, and consumable resupply. The pattern is most visible in United States urban area security initiatives, where Department of Homeland Security funding flows through designated metropolitan statistical areas rather than individual agency budgets.
CBRNE Defense Market Segmentation
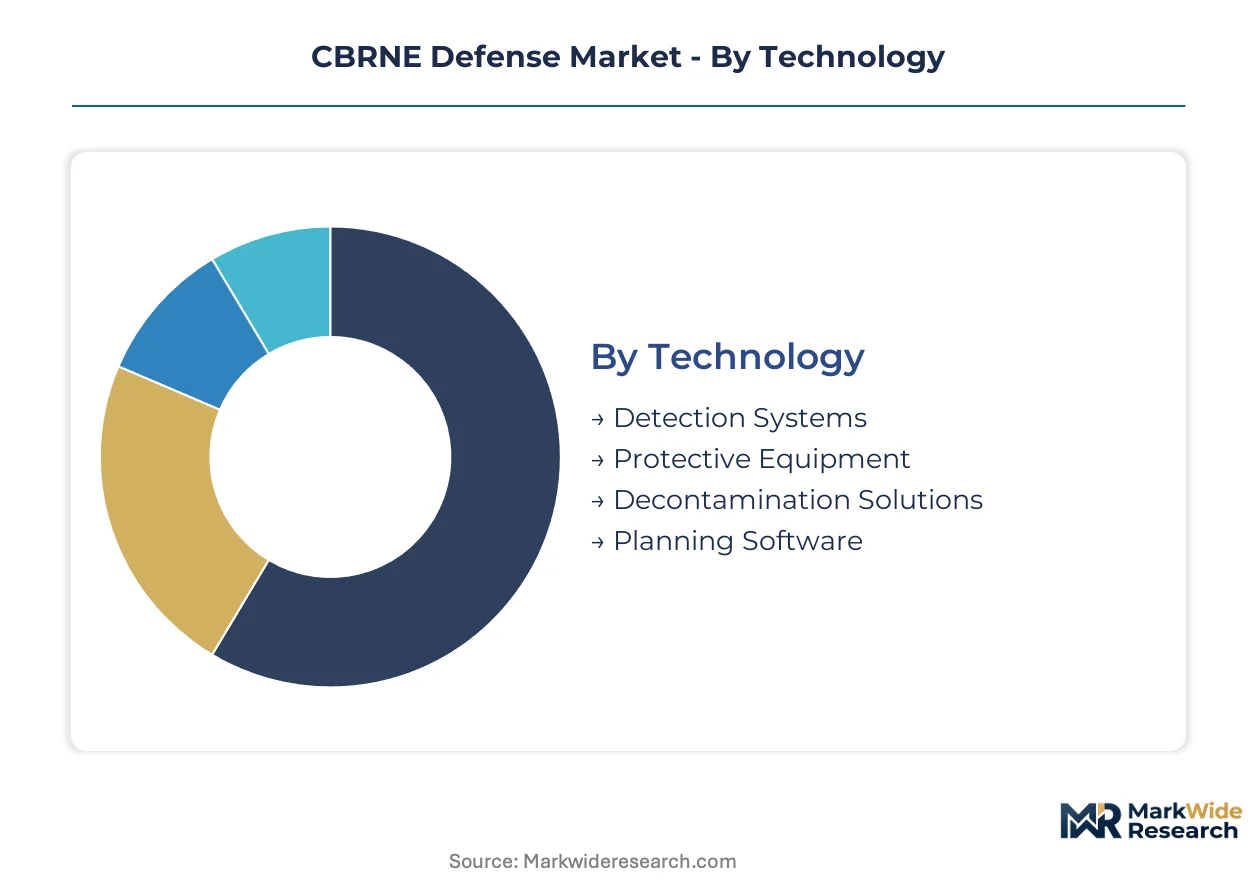
CBRNE defense procurement diverges sharply across operational contexts, with military specifications demanding hardened platform integration while civilian agencies prioritize portability and interoperability. Technology choices cascade through end-user requirements, application workflows, and component architectures in ways that concentrate vendor specialization.
Technology:
Ion mobility spectrometry and PCR-based assay platforms anchor current military specifications, though graphene-based substrates are rewriting sensitivity thresholds.
- Detection Systems:Ion mobility spectrometry and PCR-based assay platforms achieve parts-per-billion sensitivity for nerve agents and biological aerosols. NATO standardization agreements drive synchronized replacement cycles across allied defense ministries, with heated drift tube units facing obsolescence from solid-state alternatives.
- Planning Software:Artificial intelligence-enabled consequence modeling compresses incident response timelines from minutes to seconds. Federal emergency management agencies in the United States pull analytics capabilities into deployment specifications, expanding procurement fastest among technology categories.
- Protective Equipment:Advanced protective ensembles for individual warfighters and first responders concentrate margin pressure from commoditized garment manufacturing.
- Decontamination Solutions:Mobile platform integrations for military field deployment concentrate margin pools in concentrated chemistries with extended shelf stability.
Mature deployment sits with Detection Systems. Newer deployment is concentrated in Planning Software.
End User:
Procurement authority concentrates under distinct funding mechanisms that reshape vendor access patterns.
- Military:Armored vehicle-integrated CBRNE reconnaissance systems demand hardened electronics resistant to electromagnetic interference. Defense procurement agencies across NATO member states expand chemical and biological detection capabilities under updated readiness mandates.
- Law Enforcement:Metropolitan police departments acquire portable detection systems through consolidated state-level grant administrators rather than municipal budgets.
- Emergency Services:Urban Area Security Initiative funding flows through designated metropolitan statistical areas, compressing vendor relationships from individual fire departments to regional coordinators.
- Industrial:Critical infrastructure operators face asymmetric threat profiles with thinner procurement budgets and longer replacement cycles.
Volume concentrates with Military. Margin pressure concentrates with Industrial.
Application:
Workflow integration determines whether procurement emphasizes hardware platforms or service-intensive training ecosystems.
- Incident Response:Real-time coordination across detection, protection, and decontamination workflows demands system-of-systems architectures. Federal agencies seek consolidated analytics platforms bridging these functions.
- Training:Simulation-based exercise programs require consumable resupply contracts and certification maintenance that extend vendor relationships beyond initial equipment sales.
- Risk Assessment:Pre-incident modeling software faces compressed competitive windows from novel pathogen identification platforms awaiting regulatory certification.
- Surveillance:Persistent monitoring networks for biological aerosols grapple with legacy point detector interoperability constraints.
Service revenue concentrates with Training. Technology refresh concentrates with Incident Response.
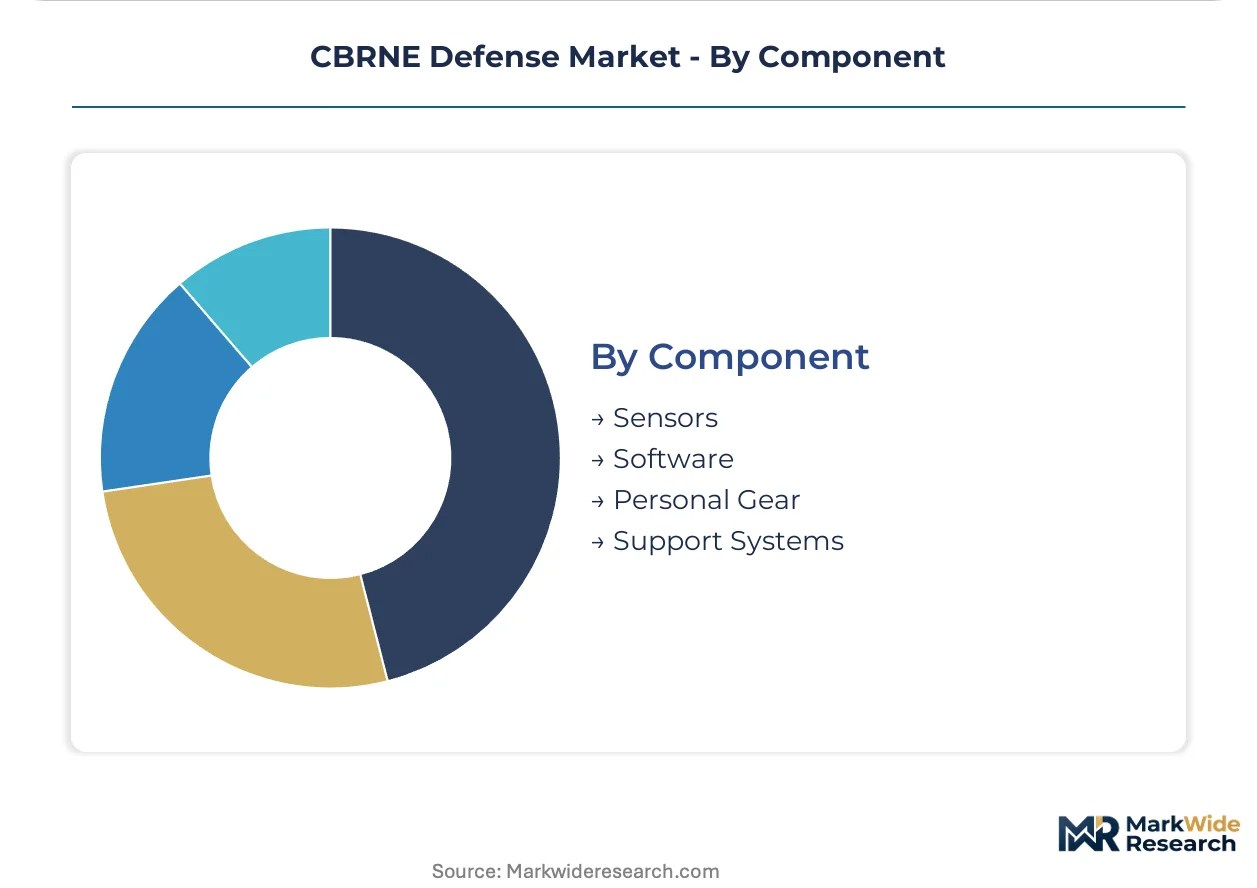
Component:
Supply chain fragmentation across semiconductor substrates and specialized textiles creates divergent sourcing strategies.
- Sensors:Graphene-based sensing substrates decouple legacy semiconductor detector economics from performance trajectories. Dual-use export control expansions fragment supplier access to critical semiconductor materials.
- Software:Autonomous threat-classification algorithms face EU AI Act conformity assessment requirements that favor vendors with pre-certified machine learning pipelines.
- Personal Gear:Wearable deployment for individual warfighter protection reduces power budgets and form factors, stretching textile engineering capabilities.
- Support Systems:Calibration infrastructure for ion mobility spectrometry concentrates maintenance expertise in specialized military laboratories.
Import dependency concentrates with Sensors. Regulatory exposure concentrates with Software.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense innovation zones in the United States concentrate graphene sensor development through DARPA-funded research parks. Allied procurement synchronization under NATO standardization agreements redistributes manufacturing investment across member state territories.
United States
Urban Area Security Initiative grants channel Department of Homeland Security funding into metropolitan statistical areas for portable detection systems. The FDA and EPA jointly certify biological detection kits for civilian deployment, extending development timelines. Boston-Cambridge research clusters host next-generation ion mobility spectrometry startups spun from MIT Lincoln Laboratory programs.
Germany
Rheinmetall AG anchors armored vehicle-integrated CBRNE reconnaissance production for Bundeswehr modernization. The EU AI Act imposes conformity assessment requirements on autonomous threat-classification algorithms exported to allied defense ministries. Bavarian defense electronics corridors around Munich concentrate NATO-standardized chemical detector manufacturing.
United Kingdom
Smiths Group plc maintains ion mobility spectrometry production for British Army point detection networks. The UK Ministry of Defence's updated CBRNE readiness mandates drive replacement cycles for aging heated drift tube units. Porton Down science park clusters biological assay development alongside DSTL threat evaluation facilities.
France
Thales Group leverages integrated defense electronics architecture to anchor European military detection procurement. ANSM and CNIL oversight extends to dual-use sensor exports under EU dual-use regulation expansions. Paris-Saclay technology clusters concentrate AI-enabled consequence modeling software for emergency management agencies.
Israel
Specialized textile engineering capabilities support wearable graphene-based sensor deployment for individual warfighter protection. National security regulators enforce strict dual-use export controls on advanced semiconductor substrates. Tel Aviv metropolitan R&D corridors host autonomous threat-classification algorithm development for European defense certification.
CBRNE Defense Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense-integrated electronics suppliers commanding platform integration contracts while component specialists capture sensor substrate supply. The vendor base organizes around three archetypes: systems integrators with NATO certification authority, materials science specialists controlling graphene fabrication, and software vendors with pre-certified machine learning pipelines. Dominant competitive moves include strategic partnerships for EU AI Act compliance and capacity expansion in armored vehicle-integrated reconnaissance platforms.
Within the defense electronics tier, Thales Group and Rheinmetall AG exemplify systems integrators leveraging NATO standardization agreements to anchor national procurement programs. Leidos Inc. occupies a position among analytics specialists pulling AI-enabled consequence modeling into federal deployment specifications. Smiths Group plc represents the incumbent detector manufacturers facing displacement pressure from solid-state alternatives.
| Leading Market Players |
|---|
| Thales Group |
| Smiths Group plc |
| Teledyne FLIR LLC |
| Bruker Corporation |
| Rheinmetall AG |
| Argon Electronics Ltd |
| Avon Protection |
| Battelle |
| Leidos Inc. |
| Others |
Supply Flow & Price Mechanics
Captive semiconductor fabrication for graphene-based sensing substrates anchors both supply security and pricing power for defense-integrated electronics suppliers serving NATO procurement programs. This backward integration into molecular capture layer production insulates tier-one vendors from dual-use export control volatility while supporting premium positioning against commodity detector manufacturers.
Pricing Analysis
Volume concentrates in standardized ion mobility spectrometry replacements for aging NATO arsenals, while margin pools accrue to graphene-enabled point detectors with sub-parts-per-billion sensitivity. Three-tier pricing structure across military-certified, first-responder, and industrial-grade detection systems reflects FDA-EPA joint certification burdens and NATO interoperability testing. Pricing pressure stems from consolidated state-level grant administration compressing vendor access to Urban Area Security Initiative funding. Military procurement agencies exhibit lowest price sensitivity due to readiness mandate urgency, whereas industrial critical infrastructure operators face thinnest procurement budgets.
Supply Chain Analysis
Domestic-content mandates in U.S. defense procurement and EU strategic autonomy frameworks are reshaping sourcing patterns for advanced sensor substrates. Graphene fabrication concentrates in United States DARPA-funded research parks, German Bavarian electronics corridors, and Israeli Tel Aviv metropolitan R&D clusters. Critical inputs span specialized semiconductor wafers, molecular capture layer chemistries, and electromagnetic-hardened electronics. Single-source vulnerability runs through Taiwanese advanced node foundries subject to dual-use export restrictions. Distribution runs through defense-integrated systems contractors with NATO certification authority rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into graphene substrate fabrication and AI-enabled software stacks defines competitive survival as procurement specifications harden around autonomous threat-classification capabilities.
For Market Incumbents: Extend NATO certification authority into graphene-based detector architectures before solid-state platforms displace heated drift tube inventories. Lock in armored vehicle-integrated reconnaissance contracts through Rheinmetall-style platform partnerships. Prioritize EU AI Act pre-certification for biological aerosol algorithms to exclude software-only entrants from European defense ministries. For New Entrants and Emerging Players: Capture emergency management software unification opportunities as federal agencies consolidate analytics platforms bridging detection, protection, and decontamination workflows. Target state-level homeland security grant administrators with service-intensive training and consumable resupply contracts. Lead with field-deployable decontamination chemistries offering extended shelf stability for mobile military platforms. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by defense-integrated electronics suppliers seeking graphene fabrication capabilities and pre-certified machine learning pipelines. Long-term viability hinges on dual-use technology transfer licenses and NATO standardization agreement alignment. Watch for EU AI Act enforcement actions against non-compliant biological detection kit suppliers as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification | Segregates machine learning pipelines into certifiable modules for European defense procurement compliance. |
| Graphene Substrate Backward Integration | Captures molecular capture layer production to insulate from dual-use export control fragmentation. |
| State-Level Grant Administrator Partnerships | Compresses vendor relationships from municipal fire departments to centralized Urban Area Security Initiative funding flows. |
| Armored Vehicle Platform Integration | Demands electromagnetic-hardened electronics resistant to battlefield interference, limiting vendor pools. |
| Field-Deployable Decontamination Chemistry Development | Reduces logistical burden through concentrated solutions with extended shelf stability for military units. |
Methodological Framework
Independent corroboration across defense procurement officers, graphene materials scientists, and emergency management software architects underwrites the qualitative findings. Primary fieldwork encompassed program managers at NATO standardization offices, federal grant administrators overseeing Urban Area Security Initiative funding, and biomedical engineers at Porton Down threat evaluation facilities. Secondary validation drew from FDA biological detection kit filings, EPA decontamination chemistry registrations, EU dual-use regulation expansions, and SEC disclosures from defense electronics suppliers. Bottom-up segment sizing triangulated against top-down NATO military modernization budget allocations.
Rate-of-change decomposition across technology substitution curves, regulatory compliance timelines, and procurement cycle synchronization generated segment-specific growth trajectories. The analytical framework modeled detection systems, planning software, protective equipment, and decontamination solutions across military, law enforcement, emergency services, and industrial end users. CAGRs derived from replacement cycle analysis for aging ion mobility spectrometry units and penetration forecasting for AI-enabled consequence modeling platforms. Forecast inputs incorporated DARPA graphene sensor program advancement rates and EU AI Act implementation enforcement patterns.
The model holds under sustained NATO readiness mandate funding and stable dual-use export control frameworks; deviation in transatlantic defense budget prioritization or semiconductor substrate trade restrictions would shift replacement cycle timing and vendor competitive positioning. Forecasts reflect documented procurement specifications, regulatory certification timelines, and technology readiness levels without speculative scenario weighting. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Air-Based Remote Weapon Stations Market
Military Equipment and Infrastructure
Aircraft Carrier Arresting Systems Market
Military Equipment and Infrastructure
Used Serviceable Material (USM) Market
Military Equipment and Infrastructure
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Land Digital Battlefield Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Military Optoelectronic System Market
Military Equipment and Infrastructure
Global Armor Materials Market
Military Equipment and Infrastructure
Europe Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market
Military Equipment and Infrastructure
Rocket Solid Propulsion Market
Military Equipment and Infrastructure
Military Test Equipment Market
Military Equipment and Infrastructure
Defense Logistics Market
Military Equipment and Infrastructure
Deployable Military Shelter Systems Market
Military Equipment and Infrastructure
Soft Wall Military Shelter Market