
 Military Infrastructure and Logistics Market | 2026-2036
Military Infrastructure and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Military Infrastructure and Logistics Market Outlook
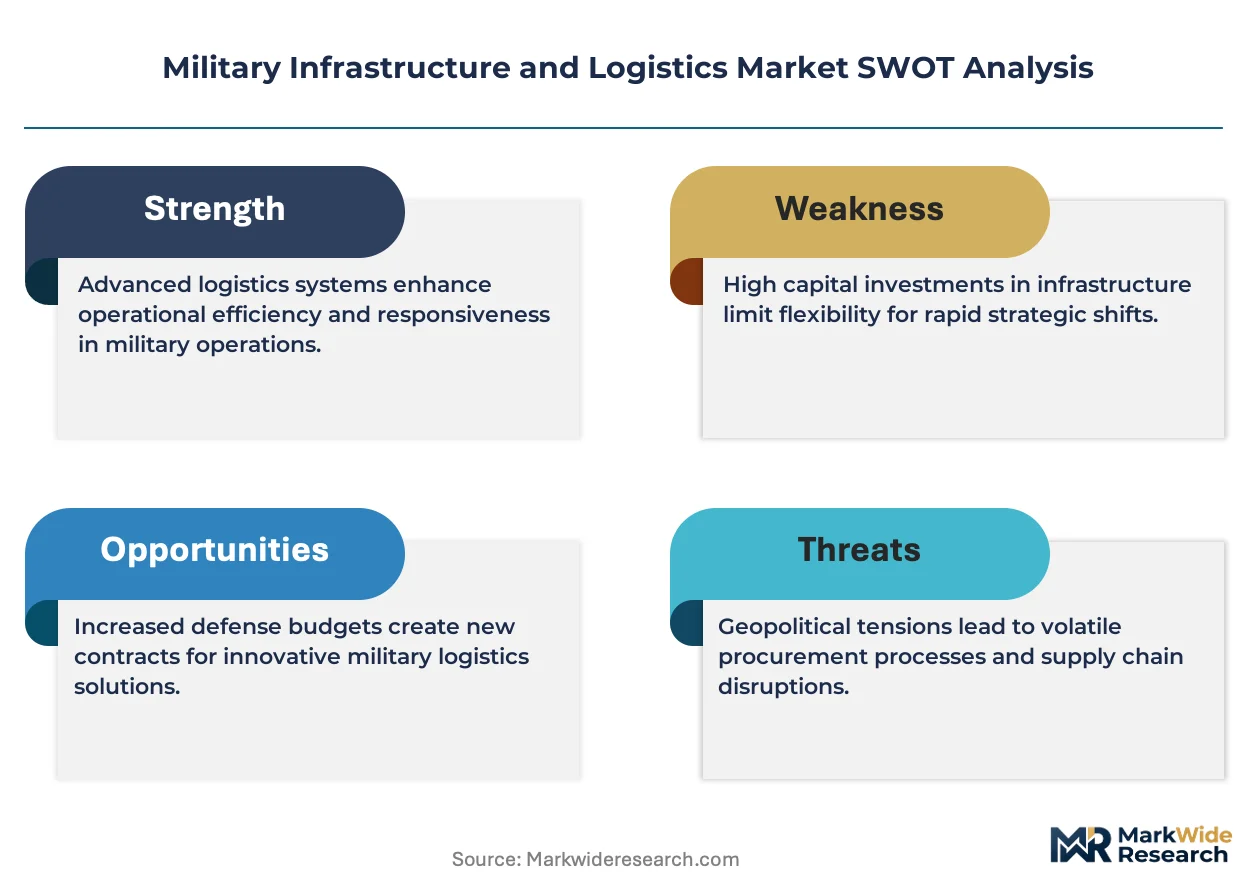
The military infrastructure and logistics sector is pivoting on a widening capability gap between premium integrated systems and commodity support services. Lockheed Martin leverages its vertically integrated defense portfolio to capture high-margin command-and-control infrastructure contracts. KBR anchors its position through persistent presence in contingency logistics and base operations support across multiple theaters. Fluor Corporation differentiates via engineering-intensive military construction programs requiring security-cleared workforces.
Military infrastructure and logistics encompasses the physical assets, supply networks, and operational services that enable force projection, sustainment, and readiness across terrestrial, maritime, and aerial domains. The field integrates hardened facilities with predictive maintenance algorithms and multi-modal distribution architectures designed to function under contested conditions. Transportation and supply chain management segments lead investment flows as peer-adversary scenarios stress-test legacy distribution models. Military bases and repair facilities command disproportionate capital allocation due to their extended asset lifecycles and strategic location requirements. Ground vehicles and aircraft sustainment within the vehicle type category generates recurring revenue through depot-level maintenance and fleet modernization cycles.
The US Department of Defense, NATO Standardization Office, and Australia's Defence Strategic Review framework collectively shape procurement priorities, mandating interoperability standards and supply chain resilience certifications that filter vendor eligibility. The EU's developing Permanent Structured Cooperation (PESCO) infrastructure initiatives and Japan's Acquisition, Technology and Logistics Agency guidelines further tighten compliance requirements for cross-border military logistics operations. Stakeholders must monitor how allied defense industrial base consolidation affects subcontractor access to classified infrastructure programs.
Market Dynamics
The US Department of Defense's supply chain resilience mandate is compressing vendor qualification timelines while redirecting procurement toward dual-use logistics platforms capable of operating across contested theaters.
Growth Catalysts
- NATO Standardization Office interoperability mandates:Common technical standards for fuel distribution and communications infrastructure accelerate cross-border logistics integration among member states.
- Indo-Pacific forward operating site expansion:Australia's Defence Strategic Review drives hardened facility construction and pre-positioned equipment stocks across northern bases.
- Predictive maintenance algorithms:Machine learning platforms embedded in depot operations reduce aircraft downtime and extend fleet availability for sustained operations.
Market Restraints
- Security-cleared workforce scarcity:Engineering and construction trades requiring top-secret clearances face recruitment bottlenecks that extend program timelines.
- Specialized steel and alloy supply concentration:Armor-grade materials and hardened concrete additives source predominantly from limited domestic suppliers subject to quota restrictions.
- EU PESCO infrastructure initiative compliance costs:Cross-border certification requirements for military mobility corridors impose documentation burdens that filter smaller contractors.
Strategic Opportunities
- Japan's Acquisition, Technology and Logistics Agency guidelines:Revised defense equipment transfer protocols open subcontractor access to integrated logistics support contracts previously restricted to domestic primes.
- Maritime pre-positioning ship modernization:Conversion of commercial roll-on/roll-off vessels to military sealift platforms creates demand for hybrid civilian-military outfitting capabilities.
- Contested environment distribution networks:Development of low-signature multi-modal nodes that disaggregate supply concentration across dispersed geographic footprints.
Industry Challenges
- Depot-level maintenance technician pipeline gaps:Specialized airframe and powerplant certifications for military variants lack sufficient training program throughput to match fleet modernization cycles.
- Legacy logistics information system integration:Migration from stovepiped command-and-control architectures to federated data environments encounters protocol incompatibility and cybersecurity recertification delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Infrastructure and Logistics Market |
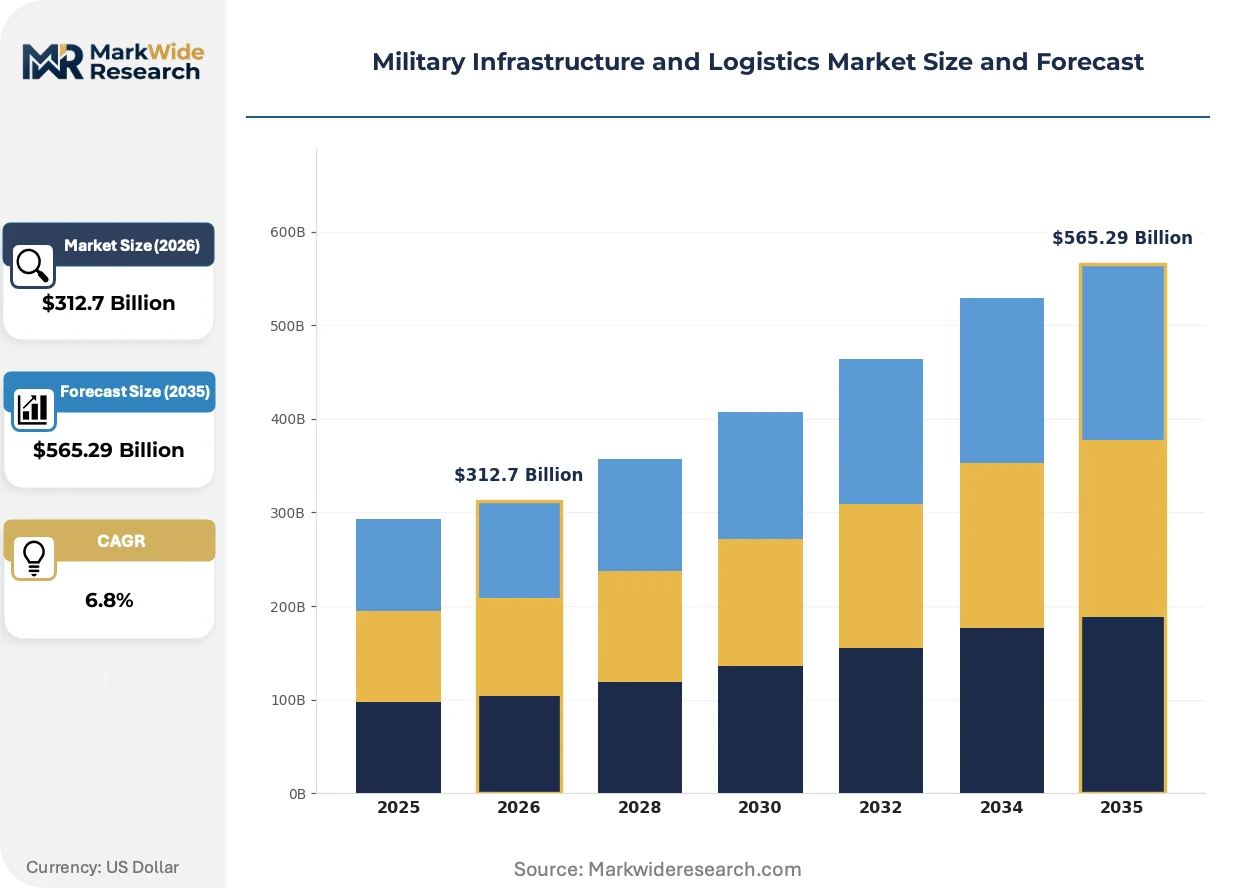
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Logistics Type: Transportation, Supply Chain Management, Warehousing, Distribution Infrastructure Type: Airports, Ports, Military Bases, Repair Facilities Vehicle Type: Ground Vehicles, Aircraft, Naval Vessels, Drones Support Services: Maintenance, Procurement, Technical Support, Training |
| Companies Covered | Lockheed Martin, KBR, Fluor Corporation, BAE Systems, Northrop Grumman, AECOM, ANHAM, Claxton Logistics Services, General Dynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Infrastructure and Logistics Market Strategic Shifts
Autonomous systems and resilient network architectures are compressing the decision loop between threat detection and logistics response, reshaping how military sustainment operates under electromagnetic contested conditions.
Autonomous ground resupply vehicles are automating last-mile distribution to forward positions. The US Marine Corps and Australian Army are field-testing unmanned logistics platforms for ammunition and medical supply delivery in denied environments. This technology is automating route planning and reducing human exposure in high-threat zones while forcing revisions to convoy protection doctrine and vehicle procurement specifications.
The EU's CSRD sustainability disclosure requirements now extend to defense industrial base suppliers with cross-border contracts. Mandatory emissions reporting and circular economy targets for construction materials affect military base modernization programs across member states. German and French defense procurement agencies are revising tender evaluation criteria to weight environmental performance alongside operational specifications.
Defense buyers are consolidating vendor relationships around integrated performance-based logistics contracts. The UK Ministry of Defence and Japan's ATLA are replacing transactional spare parts purchasing with availability-guarantee arrangements that transfer inventory risk to contractors. This reconfiguration is most advanced in rotorcraft and maritime platform sustainment, where primes now manage entire supply chains against mission-capable rate targets.
Military Infrastructure and Logistics Market Segmentation
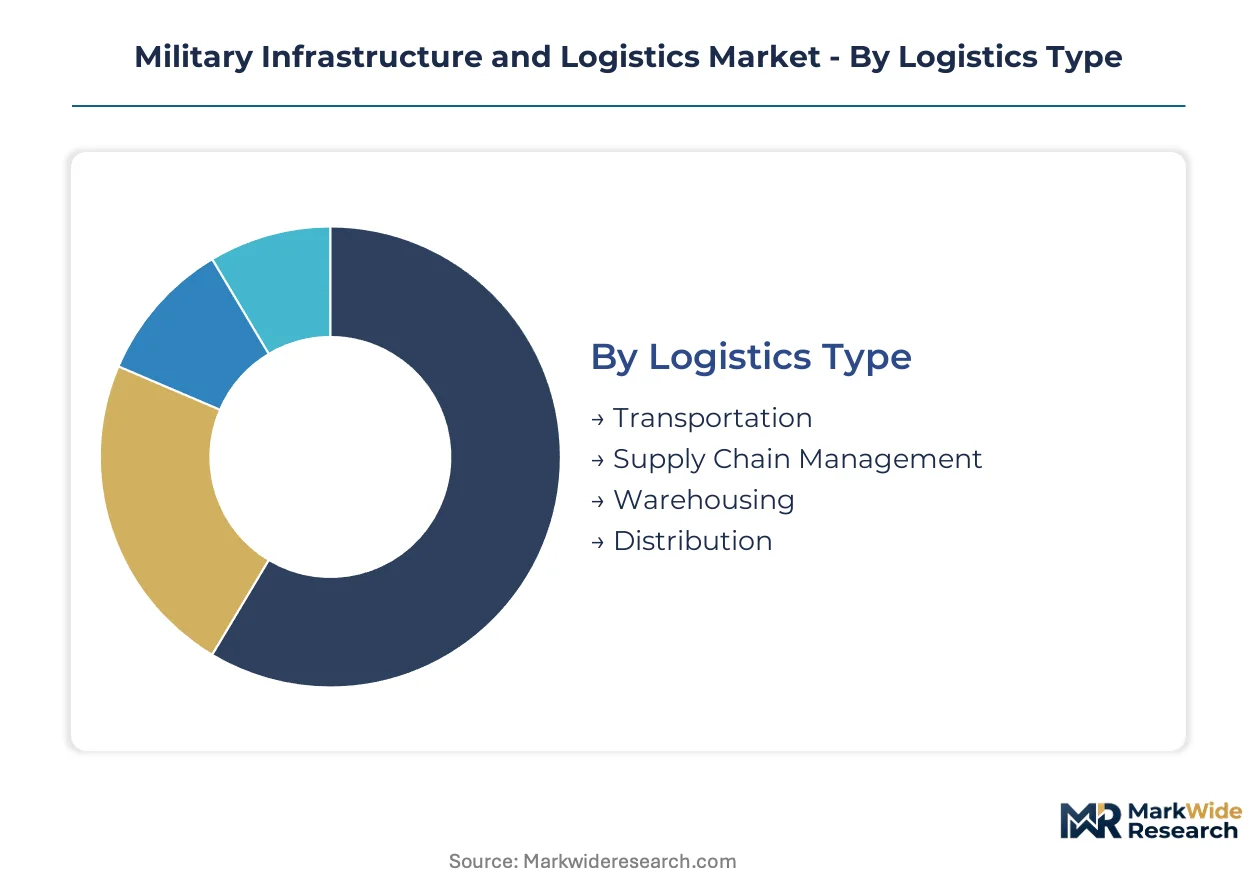
Segmentation in military infrastructure and logistics reveals how procurement budgets fragment across operational domains. Defense agencies allocate capital differently for kinetic sustainment versus static infrastructure, creating distinct competitive arenas with divergent margin profiles and vendor qualification barriers.
Logistics Type:
Defense procurement officers prioritize resilience metrics and contested-environment performance when selecting logistics modalities.
- Transportation:Multi-modal distribution architectures integrate sealift, airlift, and ground conveyance under unified command systems. The US Indo-Pacific Command pre-positions equipment across Australian and Japanese facilities, driving demand for interoperable lift platforms certified to NATO Standardization Office fuel and communications protocols.
- Supply Chain Management:Predictive analytics platforms forecast demand across dispersed operational theaters. Australia's Defence Strategic Review mandates resilient supply networks for northern base complexes, compressing vendor qualification timelines while elevating dual-use platform requirements.
- Warehousing:Hardened storage facilities with climate-controlled environments preserve sensitive munitions and electronics. EU PESCO infrastructure initiatives impose cross-border certification burdens that filter smaller contractors from military mobility corridor contracts.
- Distribution:Last-mile resupply systems employ autonomous ground vehicles for ammunition and medical delivery in denied environments. The US Marine Corps fields unmanned logistics platforms that automate route planning and reduce human exposure.
Transportation leads on scale; Supply Chain Management leads on momentum.
Infrastructure Type:
Capital intensity and asset lifecycle duration shape how defense ministries prioritize facility investments across terrestrial and maritime domains.
- Military Bases:Hardened facilities with extended lifecycles anchor force projection capabilities. Australia's northern base expansion programs and Japan's southwestern island installations command disproportionate capital allocation due to strategic location requirements and forward operating site mandates.
- Repair Facilities:Depot-level maintenance infrastructure extends fleet availability through predictive maintenance algorithms. Specialized airframe and powerplant certifications for military variants face technician pipeline gaps that constrain throughput.
- Airports:Runway reinforcement and hangar construction support rapid deployment requirements. Security-cleared workforce scarcity extends program timelines for engineering-intensive military construction.
- Ports:Maritime pre-positioning infrastructure accommodates roll-on/roll-off vessel conversions for military sealift. Hybrid civilian-military outfitting capabilities create subcontractor opportunities previously restricted to domestic primes.
Military Bases dominate capital deployment; Repair Facilities face the steepest expansion trajectory from fleet modernization cycles.
Vehicle Type:
Platform complexity and maintenance burden determine recurring revenue potential across air, land, and sea domains.
- Aircraft:Rotorcraft and fixed-wing platforms generate sustained depot-level maintenance demand. The UK Ministry of Defence and Japan's ATLA consolidate vendor relationships around availability-guarantee contracts that transfer inventory risk to primes.
- Ground Vehicles:Armored fleet sustainment requires armor-grade materials and hardened components. Specialized steel and alloy supply concentration from limited domestic suppliers subjects programs to quota restrictions.
- Naval Vessels:Maritime platform sustainment operates under performance-based logistics arrangements with mission-capable rate targets. Shipyard capacity constraints and security-cleared welding specialist shortages extend dry-dock schedules.
- Drones:Unmanned systems demand modular maintenance architectures for rapid component replacement. Low-signature distribution networks disaggregate supply concentration across dispersed geographic footprints.
Aircraft anchor recurring revenue; Drones gain share fastest from contested-environment operational requirements.
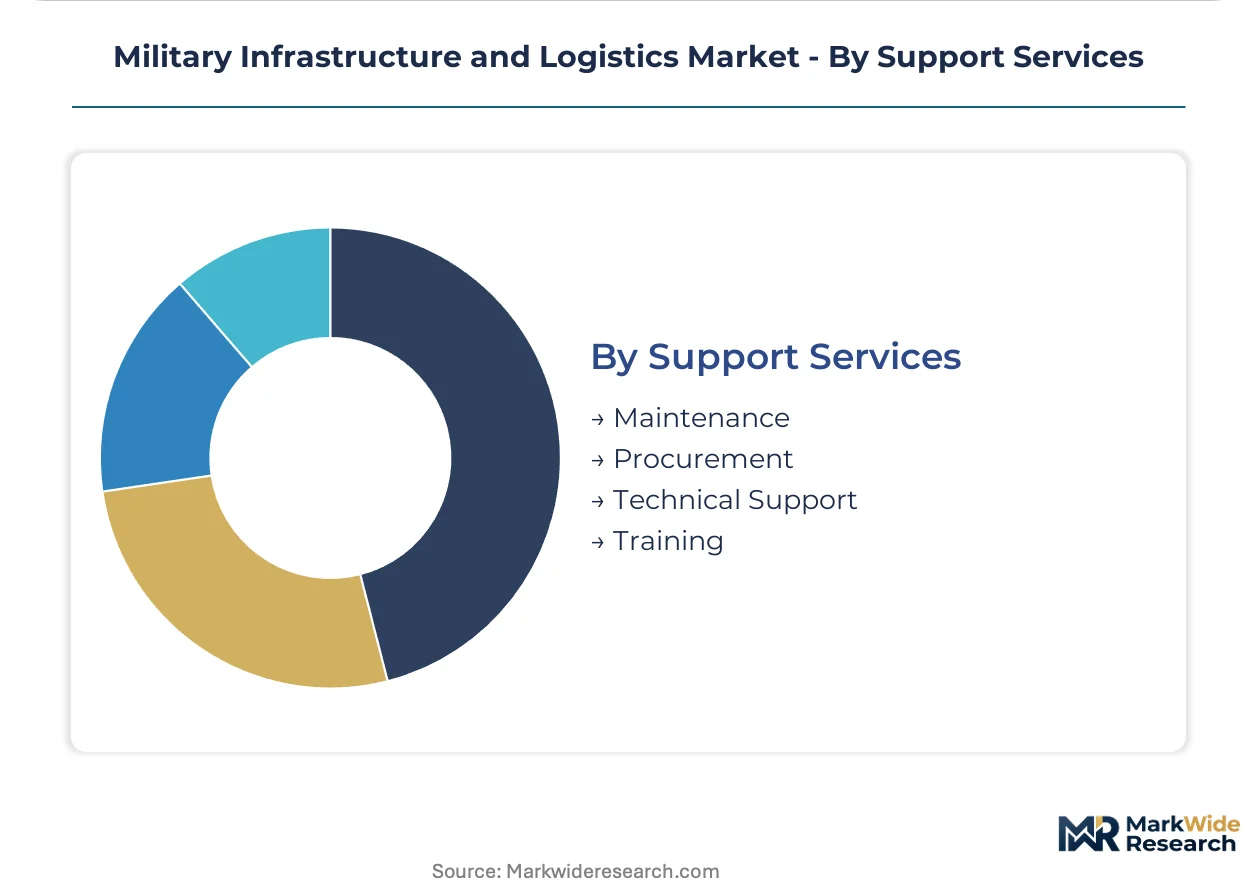
Support Services:
Service delivery models shift from transactional purchasing to outcome-based performance contracts across the sustainment spectrum.
- Maintenance:Predictive algorithms embedded in depot operations reduce downtime and extend availability. Legacy logistics information system integration encounters protocol incompatibility and cybersecurity recertification delays.
- Procurement:Strategic sourcing functions consolidate supplier bases around certified defense industrial base participants. The EU's CSRD sustainability disclosure requirements now extend to cross-border contract suppliers with mandatory emissions reporting.
- Technical Support:Field engineering services require security clearances and platform-specific expertise. Engineering and construction trades face recruitment bottlenecks that compress program timelines.
- Training:Simulation-based instruction reduces live-platform wear while accelerating technician certification throughput. Depot-level maintenance pipeline gaps persist for specialized military variant qualifications.
Maintenance captures the largest contract value; Technical Support encounters the tightest labor market constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Security-cleared engineering talent clusters around defense procurement hubs in the United States, Australia, Japan, Germany, and the United Kingdom, anchoring regional capability concentrations for military infrastructure programs.
United States
The US Department of Defense's supply chain resilience mandate drives dual-use logistics platform procurement across contested theaters. The Pentagon's Defense Industrial Base Consortium coordinates vendor qualification timelines for hardened facility construction. Virginia's Hampton Roads cluster hosts maritime pre-positioning infrastructure modernization programs converting commercial roll-on/roll-off vessels.
Australia
Canberra's Defence Strategic Review mandates northern base expansion with pre-positioned equipment stocks across forward operating sites. The country's Defence Industry Security Program regulates security-cleared workforce access to classified infrastructure contracts. Darwin and Townsville anchor hardened facility construction programs with extended asset lifecycle requirements.
Japan
Tokyo's Acquisition, Technology and Logistics Agency revised defense equipment transfer protocols to open subcontractor access for integrated logistics support. The Ministry of Defense's southwestern island installation programs command disproportionate capital allocation. Okinawa and Kyushu host rapid deployment runway reinforcement and hangar construction projects.
Germany
Berlin's participation in EU PESCO infrastructure initiatives imposes cross-border certification requirements for military mobility corridors. The country's Federal Office for Bundeswehr Equipment mandates interoperability standards for fuel distribution and communications infrastructure. Bavaria's defense industrial base concentrates depot-level maintenance infrastructure for NATO-standardized platforms.
United Kingdom
London's Ministry of Defence consolidates vendor relationships around availability-guarantee contracts for rotorcraft sustainment. The UK Defence and Security Industrial Strategy mandates supply chain resilience certifications filtering vendor eligibility. Scotland's shipyard capacity supports maritime platform performance-based logistics arrangements with mission-capable rate targets.
Military Infrastructure and Logistics Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a bifurcated vendor base where integrated system houses capture premium command-and-control infrastructure while specialized logistics contractors anchor contingency support services. The market structure concentrates around three strategic archetypes: vertically integrated defense primes, engineering-intensive construction specialists, and persistent-presence logistics operators. Competitive positioning depends on security clearance depth and theater-specific operational footprints. M&A activity targets predictive maintenance algorithm capabilities and autonomous resupply platform technologies.
Among US-based integrated defense primes, Lockheed Martin, KBR, and Fluor Corporation exemplify distinct competitive positioning archetypes. Lockheed Martin occupies the vertically integrated system house tier leveraging command-and-control infrastructure portfolios. KBR anchors the persistent-presence logistics segment across multiple operational theaters. Fluor Corporation represents the engineering-intensive construction specialist model requiring security-cleared workforces for hardened facility programs.
| Leading Market Players |
|---|
| Lockheed Martin |
| KBR |
| Fluor Corporation |
| BAE Systems |
| Northrop Grumman |
| AECOM |
| ANHAM |
| Claxton Logistics Services |
| General Dynamics |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up logistics specialists dominate the middle tier of military sustainment contracts, compressing margins through asset-light operating models while sovereign-backed primes preserve pricing power via classified infrastructure access. This ownership split creates divergent supply behaviors: financial sponsors prioritize working capital velocity and subcontractor substitution, whereas state-aligned contractors absorb longer payback periods for security-cleared workforce retention.
Pricing Analysis
Bundled performance-based logistics contracts command premium positioning against unbundled transactional spare parts purchasing. Three-tier pricing structure across premium, standard, and economy levels separates availability-guarantee arrangements from depot-level maintenance call-offs and commodity consumables. Cost compression in standard-tier base operations support is intensifying because private-equity-rolled-up contractors undercut incumbents on labor-loaded rates. Government procurement officers exhibit lowest price sensitivity for command-and-control infrastructure requiring top-secret clearances, while contingency logistics buyers negotiate aggressively on per-unit transport costs.
Supply Chain Analysis
Security clearance qualification gates filter vendor eligibility more stringently than manufacturing capability, concentrating certified production capacity in the United States, United Kingdom, and Australia. Armor-grade steel alloys, hardened concrete additives, and cryptographic communications modules draw from domestic suppliers subject to quota restrictions under defense industrial base regulations. Single-source vulnerability runs through specialized airframe and powerplant certification programs with limited training throughput. Distribution runs through prime contractor-led consortia that subcontract to cleared specialty firms for classified installation work.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage opportunities between Australia's accelerated northern base expansion timeline and Japan's extended vendor qualification protocols reward contractors with dual-country security clearance infrastructure. The cost differential in cleared engineering labor—lower effective rates in Australian regional centers versus Japanese metropolitan clusters—creates margin expansion potential for integrated cross-theater operators.
For Market Incumbents: Hedge against private-equity-rolled-up competitors by deepening captive supply of security-cleared technical labor through apprenticeship pipeline investments in Australian Defence Industry Security Program jurisdictions. Anchor long-term pricing power through backward integration into predictive maintenance algorithm development, displacing asset-light vendors lacking R&D capitalization capacity.
For New Entrants and Emerging Players: Systems integrators with existing commercial logistics footprints represent the most viable channel partner type for penetrating Japan's ATLA-guided subcontractor access reforms. Target maritime pre-positioning ship modernization as the most penetrable segment, where hybrid civilian-military outfitting requirements favor commercial vessel conversion specialists over traditional defense primes. Lead with autonomous ground resupply platform demonstrations to bypass incumbent relationships in contested-environment distribution networks.
For Investors and Strategic Acquirers: Valuations sit cheapest among engineering-intensive construction specialists with security-cleared workforces and enduring presence in Australian northern base complexes. Long-term viability centers on contractors positioned for recurring revenue under performance-based logistics contract structures rather than transactional construction awards. Watch for inflection when the US Department of Defense accelerates dual-use logistics platform procurement timelines, signaling vendor consolidation toward integrated system houses.
| Strategic Initiative | Industry Significance |
|---|---|
| Security-Cleared Workforce Pipeline Investment | Australian Defence Industry Security Program registration enables access to classified infrastructure contracts at Darwin and Townsville. |
| Predictive Maintenance Algorithm Acquisition | Machine learning platforms embedded in depot operations reduce aircraft downtime for UK Ministry of Defence availability-guarantee contracts. |
| Maritime Pre-Positioning Conversion Capability | Hybrid civilian-military outfitting of roll-on/roll-off vessels captures US Indo-Pacific Command equipment pre-positioning demand. |
| Cross-Border Certification Compliance | EU PESCO infrastructure initiative alignment filters smaller competitors from military mobility corridor opportunities in Germany. |
| Autonomous Resupply Platform Development | Unmanned ground vehicles for last-mile distribution address US Marine Corps requirements for denied environment logistics. |
Study Parameters
Bottom-up defense procurement modeling reconciled against top-down defense industrial base tracking forms the analytical core of this study. Primary interviews with base operations commanders, defense procurement officers, security-cleared engineering contractors, and logistics program managers combined with secondary validation from NATO Standardization Office technical documentation, US Department of Defense contract award databases, Australia's Defence Strategic Review policy filings, and EU PESCO infrastructure initiative progress reports. Triangulation between facility construction spend tracking and sustainment contract flow analysis ensures coverage of both capital-intensive and recurring revenue segments.
Historical trendline analysis of defense infrastructure budget allocations across logistics type, infrastructure type, vehicle type, and support service categories established baseline growth patterns. Segmentation dimensions modeled include transportation modality, facility lifecycle phase, platform complexity tier, and service delivery model across the projection horizon. CAGRs were derived from weighted scenario analysis incorporating peer-adversary contingency planning intensity, allied defense industrial base consolidation trajectories, and autonomous systems adoption curves in contested distribution networks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to security-cleared workforce pipeline constraints and specialized material supply quota adjustments. Forecasts reflect documented assumptions regarding NATO interoperability mandate implementation pace and Indo-Pacific forward operating site expansion timelines. A model refresh is warranted upon material change in US Department of Defense dual-use logistics platform procurement acceleration or EU PESCO cross-border certification requirement enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
Deployable Military Shelters Market
Military Equipment and Infrastructure
CBRN Protection Equipment Market
Military Equipment and Infrastructure
Latin America Defense Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market
Military Equipment and Infrastructure
Man Portable Military Electronics Market
Military Equipment and Infrastructure
Global Stealth Warfare Market
Military Equipment and Infrastructure
Military Displays Market
Military Equipment and Infrastructure
Manpack Military Antennas Market
Military Equipment and Infrastructure
Howitzer Artillery System Market
Military Equipment and Infrastructure
Military Optoelectronic System Market
Military Equipment and Infrastructure
Used Serviceable Material (USM) Market
Military Equipment and Infrastructure
Rocket Solid Propulsion Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Military Tent and Shelter Market