
 Military Tent and Shelter Market | 2026-2036
Military Tent and Shelter Market Size, Share, and Industry Trends Forecast 2026-2036
Military Tent and Shelter Market Analysis
Lifecycle maintenance and field upgrade subscriptions is recalibrating how defense buyers evaluate total ownership cost rather than upfront capital expenditure alone. AAR Corp. leverages its integrated logistics network to sustain long-term service contracts across multiple NATO member inventories. HDT Global anchors its competitive position through specialized engineering for extreme-climate expeditionary platforms. Weatherhaven Global Resources differentiates via modular software-configurable environmental control systems embedded within shelter architectures.
Military tents and shelters are engineered deployable structures combining high-tenacity synthetic fabric membranes with lightweight aluminum or composite frame systems, designed to achieve rapid assembly under tactical conditions while providing ballistic protection, climate stabilization, and electromagnetic shielding. Their primary purpose is to establish functional infrastructure for personnel, equipment, and operations in expeditionary or contingency environments lacking permanent facilities. Frame tents and soft-sided shelters command the dominant share of procurement budgets due to their balance of transportability and mission configurability, while hybrid tent architectures represent the fastest-expanding category as militaries demand multi-threat protection in single platforms. Composite materials are capturing margin concentration as ballistic-grade and thermally insulative fabric technologies command premium pricing over conventional polyester or canvas substrates.
The U.S. Department of Defense's Unified Facilities Criteria and NATO's Standardization Office establish baseline performance requirements for shelter portability, interoperability, and environmental resilience that vendors must satisfy for contract eligibility. The U.S. Federal Acquisition Regulation and Defense Federal Acquisition Regulation Supplement govern procurement protocols, while the EPA's restrictions on per- and polyfluoroalkyl substances in textiles are forcing material reformulation across supplier bases. Stakeholders must monitor how evolving electromagnetic spectrum warfare requirements reshape shielding specifications and whether domestic content mandates under the Buy American Act intensify supply chain regionalization pressures.
Market Dynamics
The U.S. Department of Defense's Operational Energy Strategy is compressing procurement timelines for thermally efficient shelter systems while NATO standardization mandates force cross-border interoperability investments. Defense buyers now weight lifecycle service subscriptions against upfront capital outlays, restructuring vendor selection criteria across expeditionary medical and force protection applications.
Growth Catalysts
- Expeditionary Medical Infrastructure:Armed forces are fielding rapidly deployable field hospitals with integrated climate control and electromagnetic shielding, driving procurement of modular soft-sided shelters.
- REACH Chemical Restrictions:ECHA's evolving substance restrictions on per- and polyfluoroalkyl compounds are accelerating supplier investment in alternative ballistic fabric coatings that maintain protective performance.
- Indo-Pacific Force Posture Adjustments:U.S. base realignment initiatives sustain procurement volumes for lightweight frame systems optimized for tropical and maritime environments.
Market Restraints
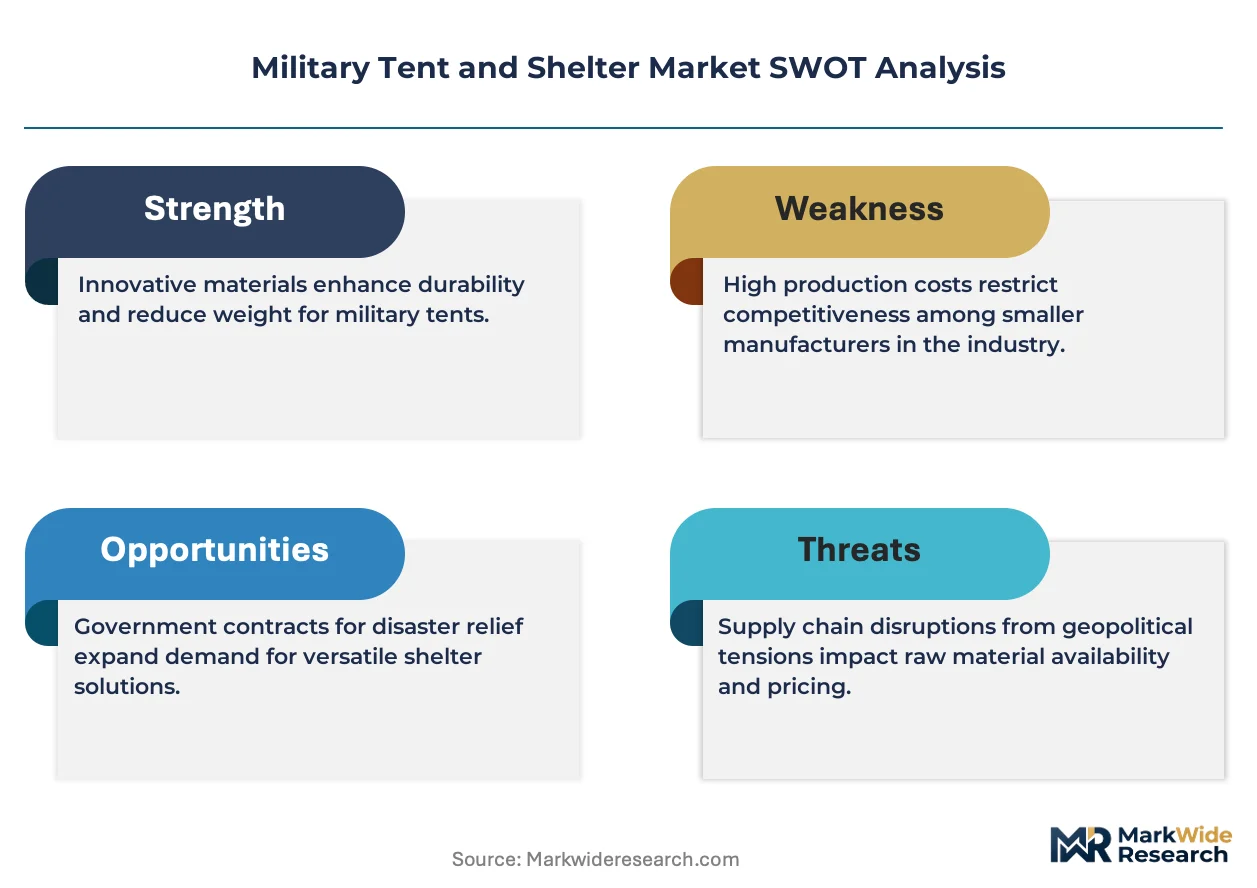
- Aramid Fiber Cost Volatility:Ballistic-grade synthetic substrate prices fluctuate with aerospace and automotive demand, compressing margin predictability for shelter manufacturers.
- Aluminum Extrusion Concentration:Lightweight frame component supply concentrates among East Asian rolling mills, exposing procurement to logistics disruption and tariff exposure.
- Per- and Polyfluoroalkyl Substitution Limits:EPA restrictions on durable water repellent chemistries constrain material options without fully mature replacements, extending qualification timelines.
Strategic Opportunities
- Electromagnetic Spectrum Warfare Requirements:Evolving shielding specifications for command-and-control shelters create white space for vendors with radio-frequency attenuation engineering capabilities.
- Buy American Act Regionalization:Domestic content mandates intensify supply chain regionalization pressures, advantaging vendors with captive U.S. textile and composite manufacturing.
- Hybrid Architecture Convergence:Integration of soft-sided deployability with hard-wall ballistic protection is capturing procurement preference for multi-threat single platforms.
Industry Challenges
- Electromagnetic Compatibility Certification:MIL-STD-285 and NSA 94-106 shielding validation requires specialized testing infrastructure, extending product qualification cycles.
- Legacy Shelter Interoperability:NATO STANAG 4425 compliance demands backward compatibility with existing frame and fabric inventories, constraining design freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Tent and Shelter Market |
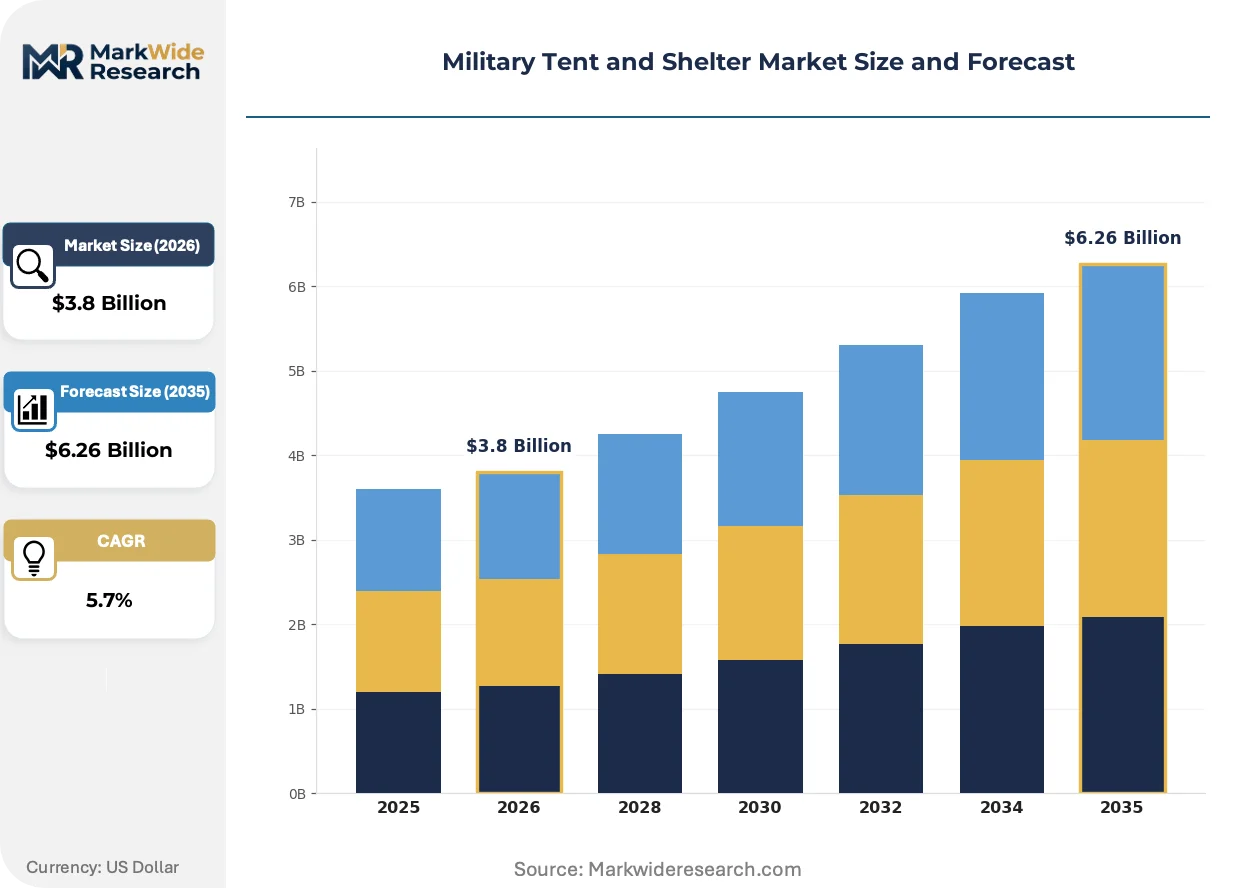
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frame Tents, Pole Tents, Hybrid Tents, Soft-Sided Shelters Application: Field Hospitals, Command Centers, Sleeping Quarters, Supply Depots End User: Military Organizations, Defense Contractors, Government Agencies, Humanitarian Groups Material: Fabric, Aluminum, Steel, Composite Materials |
| Companies Covered | AAR Corp., HTS tentiQ, HDT Global, Rekord Structures, Outdoor Venture Corporation, General Dynamics Mission Systems, Weatherhaven Global Resources, Gichner Shelter Systems, Marshall Aerospace and Defence Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Tent and Shelter Market Emerging Trajectories
Active camouflage and signature management technologies are penetrating expeditionary shelter specifications, while software-configurable environmental control systems embed intelligence directly into fabric architectures. Defense procurement offices now mandate modular upgrade pathways rather than fixed-configuration platforms.
Phase-change material liners are absorbing thermal management burdens previously handled by auxiliary power units, reducing fuel logistics for forward operating bases. U.S. Marine Corps expeditionary units are fielding these substrates at accelerated pace for temperate and arid climate deployments. The technology is absorbing capital previously allocated to standalone climate machinery, compressing total platform weight and generator dependency.
EPA restrictions on per- and polyfluoroalkyl substances in textiles are forcing wholesale material reformulation across supplier bases. Shelter manufacturers must requalify ballistic and water-repellent fabric coatings under compressed timelines to maintain Defense Federal Acquisition Regulation Supplement contract eligibility. European vendors face parallel ECHA regulatory pressure, creating transatlantic alignment on fluorine-free chemistry investment.
Service-based contracting models are displacing traditional capital procurement for shelter fleets. NATO member defense ministries now subscribe to lifecycle maintenance and field upgrade programs, transferring obsolescence risk to vendors. This pattern concentrates most visibly in Nordic countries, where long-term framework agreements cover Arctic-capable expeditionary platforms with embedded logistics support.
Military Tent and Shelter Market Segmentation
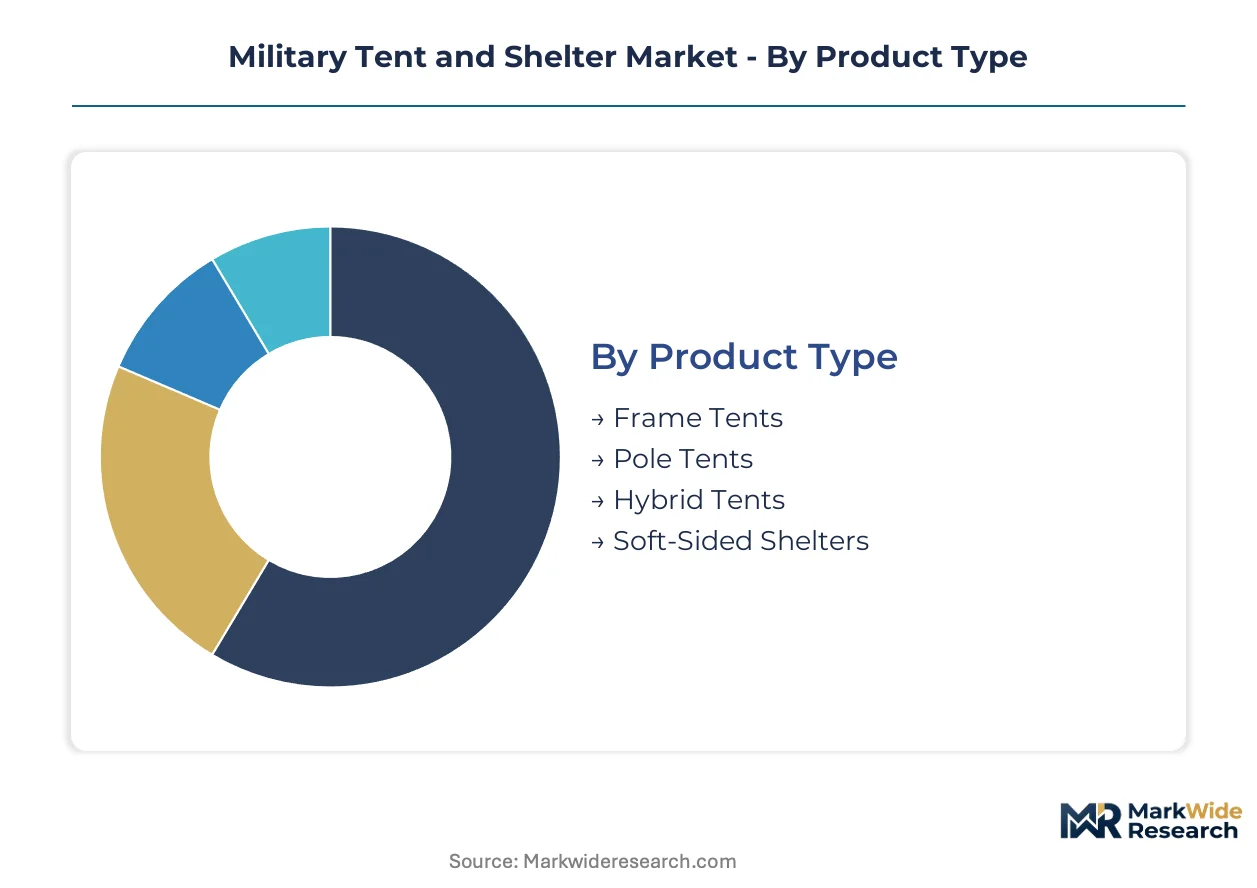
Military tent and shelter procurement divides sharply between capital-intensive hard-wall systems and rapidly deployable soft-sided platforms. Segmentation reveals where defense budgets concentrate infrastructure investment versus expeditionary flexibility.
Product Type:
Capital intensity escalates dramatically from fabric membrane systems through integrated ballistic-composite architectures.
- Frame Tents:Aluminum or composite pole skeletons support high-tenacity synthetic membranes, achieving assembly under tactical time constraints. U.S. Indo-Pacific force posture adjustments sustain procurement volumes for lightweight variants optimized to tropical maritime logistics.
- Hybrid Tents:Soft-sided deployability converges with hard-wall ballistic protection in single-platform configurations. NATO standardization mandates for multi-threat interoperability are accelerating qualification timelines for these integrated systems.
- Pole Tents:Traditional tensioned-fabric structures with collapsible support poles serve secondary logistics and garrison applications where rapid mobility is secondary to cost minimization.
- Soft-Sided Shelters:Membrane-only enclosures without rigid frames prioritize packability for airborne and special operations forces; climate stabilization depends on auxiliary environmental control units.
Frame tents absorb the bulk of installed capacity; hybrid tents are expanding most quickly.
Application:
Medical and command infrastructure command premium pricing versus personnel accommodation due to electromagnetic shielding and climate precision requirements.
- Field Hospitals:Modular soft-sided shelters integrate surgical suites, patient wards, and sterilization corridors with embedded HVAC and electromagnetic protection. U.S. Department of Defense Operational Energy Strategy procurement timelines are compressing for thermally efficient expeditionary medical platforms.
- Command Centers:Shielded enclosures for tactical operations centers demand MIL-STD-285 validated radio-frequency attenuation and NSA 94-106 certification, extending qualification cycles and concentrating supply among specialized vendors.
- Sleeping Quarters:Personnel accommodation prioritizes transport density over protective performance, with procurement driven by force rotation cycles rather than threat environment upgrades.
- Supply Depots:Storage-focused shelters emphasize volume capacity and environmental sealing for ammunition, fuel, and provisions; climate control requirements vary by commodity sensitivity.
Field hospitals concentrate the steepest investment trajectory; sleeping quarters dominate physical unit volumes.
End User:
Contractual risk allocation distinguishes sovereign procurement from outsourced fleet management.
- Military Organizations:National armed forces directly procure shelter systems through defense acquisition regulations, with lifecycle service subscriptions displacing capital-heavy ownership models across NATO inventories.
- Defense Contractors:Private military service providers and base operations contractors lease shelter fleets under performance-based agreements, transferring obsolescence risk to vendors.
- Government Agencies:Non-defense federal entities including disaster response and border security organizations procure through civilian acquisition channels with simplified technical specifications.
- Humanitarian Groups:International relief organizations prioritize cost minimization and rapid donor-funded deployment over military-grade protective performance.
Military organizations anchor procurement value; defense contractors are gaining share fastest through service-based contracting expansion.
Material:
Raw material selection determines ballistic rating, thermal performance, and compliance with evolving chemical restrictions.
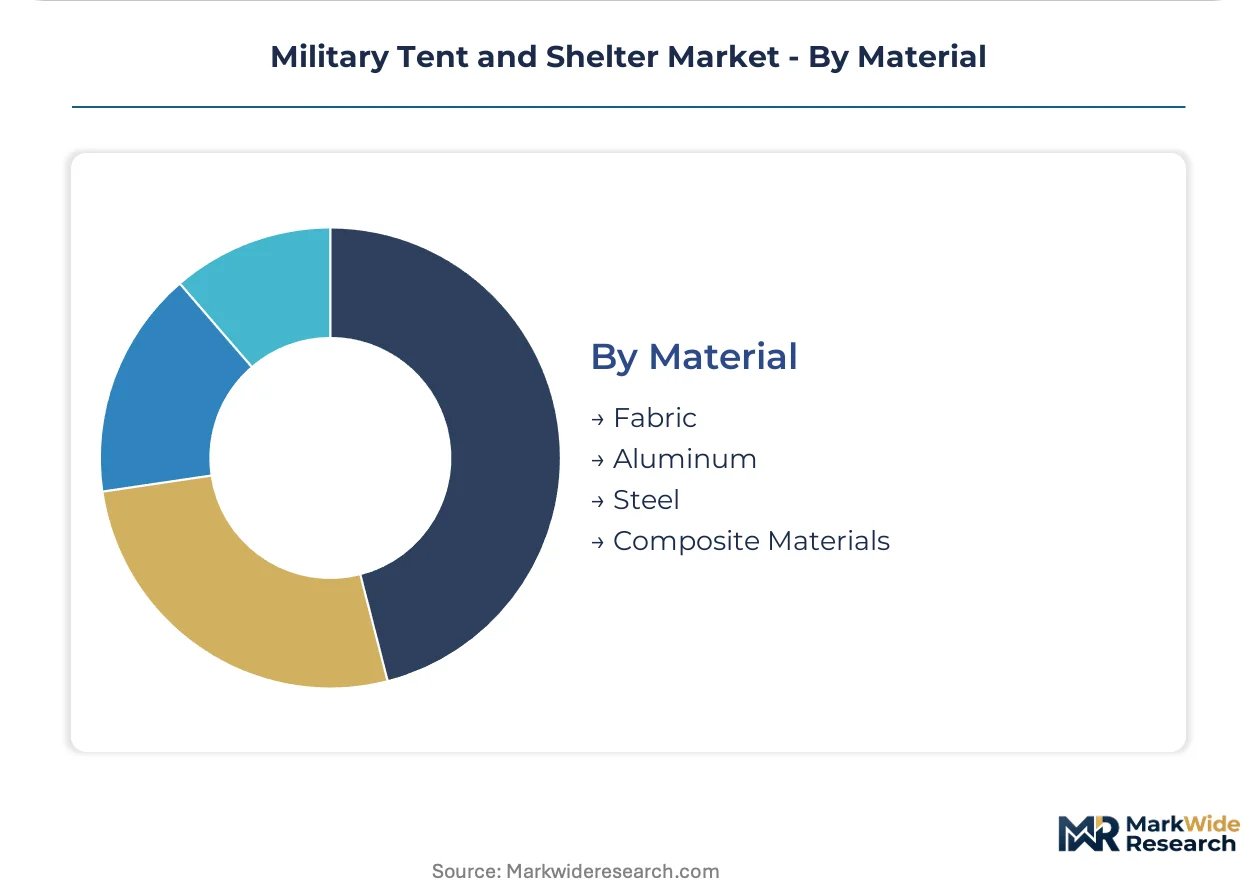
- Fabric:High-tenacity synthetic membranes—aramid, polyester, and emerging fluorine-free coatings—provide the primary weather and signature management barrier; EPA per- and polyfluoroalkyl substance restrictions are forcing wholesale coating reformulation.
- Composite Materials:Ballistic-grade fiber-reinforced polymers integrate thermal insulation with projectile resistance, commanding substantial price premiums over conventional substrates.
- Aluminum:Extruded frame components concentrate supply among East Asian rolling mills, exposing procurement to logistics disruption and tariff exposure per defense trade policy shifts.
- Steel:Heavy-gauge structural elements persist in semi-permanent installations where transport weight constraints are secondary to blast protection and equipment mounting requirements.
Fabric substrates absorb the bulk of installed capacity; composite materials are climbing the fastest as multi-threat protection requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Washington DC's defense procurement corridor concentrates military shelter demand through Pentagon acquisition offices and Army Corps of Engineers facilities. Base realignment initiatives and Indo-Pacific force posture adjustments sustain procurement volumes across multiple theater commands.
United States
U.S. Marine Corps expeditionary units accelerate field hospital deployments with phase-change thermal liners. The Defense Federal Acquisition Regulation Supplement governs contract eligibility and lifecycle service subscription models. Huntsville, Alabama's Army Materiel Command anchors shelter qualification and testing infrastructure for extreme-climate platforms.
Germany
Bundeswehr modernization drives demand for NATO STANAG 4425 interoperable hybrid tent systems. ECHA REACH chemical restrictions force fluorine-free ballistic fabric coating reformulation across supplier bases. Bavaria's aerospace and defense cluster around Munich hosts specialized electromagnetic shielding engineering capabilities for command center shelters.
United Kingdom
British Army expeditionary medical infrastructure investments prioritize rapidly deployable soft-sided shelters with integrated climate control. Ministry of Defence procurement follows the Defence and Security Equipment International framework for cross-border interoperability. Bristol's aerospace corridor concentrates Marshall Aerospace and Defence Group operations for shelter system integration.
France
French Armed Forces emphasize multi-threat protection in single-platform configurations for Sahel and Indo-Pacific deployments. ANSM and CNIL data protection requirements influence command shelter electromagnetic spectrum specifications. The Île-de-France defense industrial base around Paris hosts prime contractors for NATO expeditionary infrastructure programs.
Canada
Canadian Armed Forces Arctic capability investments sustain demand for extreme-climate expeditionary platforms with thermal efficiency mandates. Health Canada and PMRA regulate material safety for personnel accommodation shelters. Ontario's manufacturing corridor around Toronto concentrates fabric membrane production and aluminum frame component fabrication.
Military Tent and Shelter Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the military shelter value chain. Integrated logistics networks and specialized engineering capabilities define tier differentiation. Three archetypes dominate: full-service contractors with lifecycle subscription models, extreme-climate engineering specialists, and modular environmental control system innovators. Consolidation pressures intensify through strategic partnerships and captive manufacturing investments.
Within the full-service tier, AAR Corp. and Marshall Aerospace and Defence Group represent integrated logistics network operators. HDT Global occupies a position among extreme-climate engineering specialists. Weatherhaven Global Resources exemplifies the modular environmental control system archetype with software-configurable shelter architectures.
| Leading Market Players |
|---|
| AAR Corp. |
| HTS tentiQ |
| HDT Global |
| Rekord Structures |
| Outdoor Venture Corporation |
| General Dynamics Mission Systems |
| Weatherhaven Global Resources |
| Gichner Shelter Systems |
| Marshall Aerospace and Defence Group |
| Others |
Supply Flow & Price Mechanics
Aramid fiber and ballistic-grade fabric coatings cascade through three distinct pricing tiers before reaching defense procurement offices, with East Asian rolling mill concentration for aluminum extrusions amplifying cost volatility at the frame component level.
Pricing Analysis
Mission-availability guarantees anchor value-based pricing for expeditionary shelter fleets, with NATO defense ministries subscribing to lifecycle uptime contracts rather than capital purchase. Price differentiation stratifies across MIL-STD-285 certification grade, electromagnetic shielding performance tier, and bundled field logistics support. Cost compression in standard personnel accommodation runs through polyester membrane commoditization, while command center shelters with NSA 94-106 validation command substantial premiums. Humanitarian procurement channels exhibit highest price sensitivity; special operations forces demonstrate lowest sensitivity due to packability and rapid-deployment imperatives.
Supply Chain Analysis
Ballistic fabric substrate supply rests on South Korean and Japanese specialty fiber producers, with Chinese rolling mills dominating aluminum frame extrusion. Raw material dependencies span aramid pulp, fluorine-free coating chemistries, and phase-change thermal liner compounds. Single-source vulnerability concentrates in East Asian aluminum supply, exposing procurement to tariff disruption and maritime logistics chokepoints. Distribution runs through prime contractor integration facilities in Huntsville, Alabama and Bavaria, Germany before military logistics networks deliver to theater commands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with captive U.S. textile manufacturing and in-house electromagnetic shielding engineering emerging as decisive margin-control levers.
For Market Incumbents: Acquire specialized electromagnetic compatibility testing infrastructure to compress NSA 94-106 qualification cycles. Secure long-term offtake agreements with domestic aramid fiber producers ahead of Buy American Act enforcement tightening. Consolidation of fluorine-free coating formulation capabilities counters ECHA REACH regulatory pressure.
For New Entrants and Emerging Players: Capture Arctic-capable expeditionary platform demand from Canadian Armed Forces and Nordic defense ministries, where extreme-climate engineering scarcity limits incumbent saturation. Penetrate electromagnetic spectrum warfare shelter specifications through radio-frequency attenuation specialization. Partner with Army Materiel Command qualification facilities to accelerate STANAG 4425 compliance.
For Investors and Strategic Acquirers: Distressed-cycle entries favor modular environmental control system specialists with software-configurable architectures in the U.S. Midwest manufacturing corridor. Long-term viability hinges on service-based contract backlog depth and captive composite material production. Watch for EPA enforcement acceleration on per- and polyfluoroalkyl substances as inflection trigger for coating chemistry replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Fiber Production | Captive supply of ballistic-grade substrate insulates margin from aerospace demand competition. |
| Electromagnetic Shielding Certification Investment | MIL-STD-285 validation infrastructure concentrates supply among qualified vendors. |
| Lifecycle Service Subscription Expansion | NATO framework agreements transfer obsolescence risk and stabilize recurring revenue. |
| Fluorine-Free Coating Chemistry Development | ECHA REACH compliance enables continued European defense contract eligibility. |
| Hybrid Architecture R&D Partnership | Integration of soft-sided deployability with hard-wall protection captures multi-threat procurement preference. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with Army Materiel Command procurement officers, shelter system integration engineers, defense logistics network managers, and electromagnetic compatibility testing laboratory directors. Defense Federal Acquisition Regulation Supplement contract award databases, EPA chemical restriction notices, ECHA REACH substance candidate lists, and NATO standardization office technical documentation provided validation triangulation. Bottom-up segment sizing across product type, application, and material categories reconciled against top-down defense budget allocation analysis.
Segment-level modeling addressed frame tent, hybrid tent, pole tent, and soft-sided shelter configurations alongside field hospital, command center, sleeping quarter, and supply depot applications across the projection horizon. Fabric substrate, composite material, aluminum, and steel material tiers were modeled with end-user distinctions between military organizations, defense contractors, government agencies, and humanitarian groups. CAGR derivation incorporated defense procurement cycle timing, base realignment initiative schedules, and regulatory compliance deadline clustering. Phase-change thermal liner adoption curves and electromagnetic spectrum warfare specification evolution served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aluminum tariff policy shifts, aramid fiber capacity expansion timing, and electromagnetic shielding standard revision schedules. Assumptions reflect documented defense budget trajectories, standardization mandate adoption patterns, and chemical substitution technology readiness levels. A small set of triggers—EPA enforcement acceleration, NATO STANAG amendment cycles, and Indo-Pacific force posture implementation pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Manpack Military Antennas Market
Military Equipment and Infrastructure
Global Stealth Warfare Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Defense Logistics Market
Military Equipment and Infrastructure
Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
NATO Defense Market
Military Equipment and Infrastructure
FLIR and Laser Designator Targeting Pods Market
Military Equipment and Infrastructure
Deployable Military Shelter Systems Market
Military Equipment and Infrastructure
Global Remote Weapon Station Market
Military Equipment and Infrastructure
Global Soldier Modernization Market
Military Equipment and Infrastructure
Global Armor Materials Market
Military Equipment and Infrastructure
Rocket Solid Propulsion Market
Military Equipment and Infrastructure
Used Serviceable Material (USM) Market
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market