
 Military Image Intensifier Tube Market | 2026-2036
Military Image Intensifier Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Military Image Intensifier Tube Market Foresight
Multi-source procurement for image intensifier tubes is restructuring how defense agencies secure night vision capabilities. L3Harris Technologies leverages captive gallium arsenide photocathode production to dominate domestic U.S. military contracts. Elbit Systems anchors Israeli and allied nation supply through vertically integrated tube-to-system manufacturing. Photonis competes across European NATO channels with specialized Gen 2+ and digital intensifier architectures.
A military image intensifier tube is a vacuum electronic device that amplifies ambient light through a photocathode, microchannel plate, and phosphor screen assembly, typically achieving luminous gains exceeding 50,000 for detection below 10^-6 lux. It enables operators to conduct surveillance, target acquisition, and navigation in near-total darkness without active illumination. Gen 3 tubes containing gallium arsenide photocathodes command the largest revenue share due to their extended infrared sensitivity and service life in aviation and special operations headsets. Digital intensifier segments incorporating CMOS sensor hybrids are gaining traction in law enforcement and drone-mounted reconnaissance where image fusion and data portability outweigh pure low-light performance. Silicon-based microchannel plate alternatives remain niche but attract R&D investment for radiation-hardened space and satellite applications.
ITAR regulations administered by the U.S. Department of State constrain technology transfer and limit non-U.S. entities from accessing Gen 3 manufacturing know-how, fragmenting global supply into classified and non-classified tiers. The EU Green Deal and REACH chemical frameworks are pressuring European manufacturers to reformulate phosphor chemistries and eliminate hazardous substances from tube assembly processes. Stakeholders must monitor how export control expansion and environmental compliance deadlines will reshape manufacturing location decisions and customer eligibility pools.
Market Dynamics
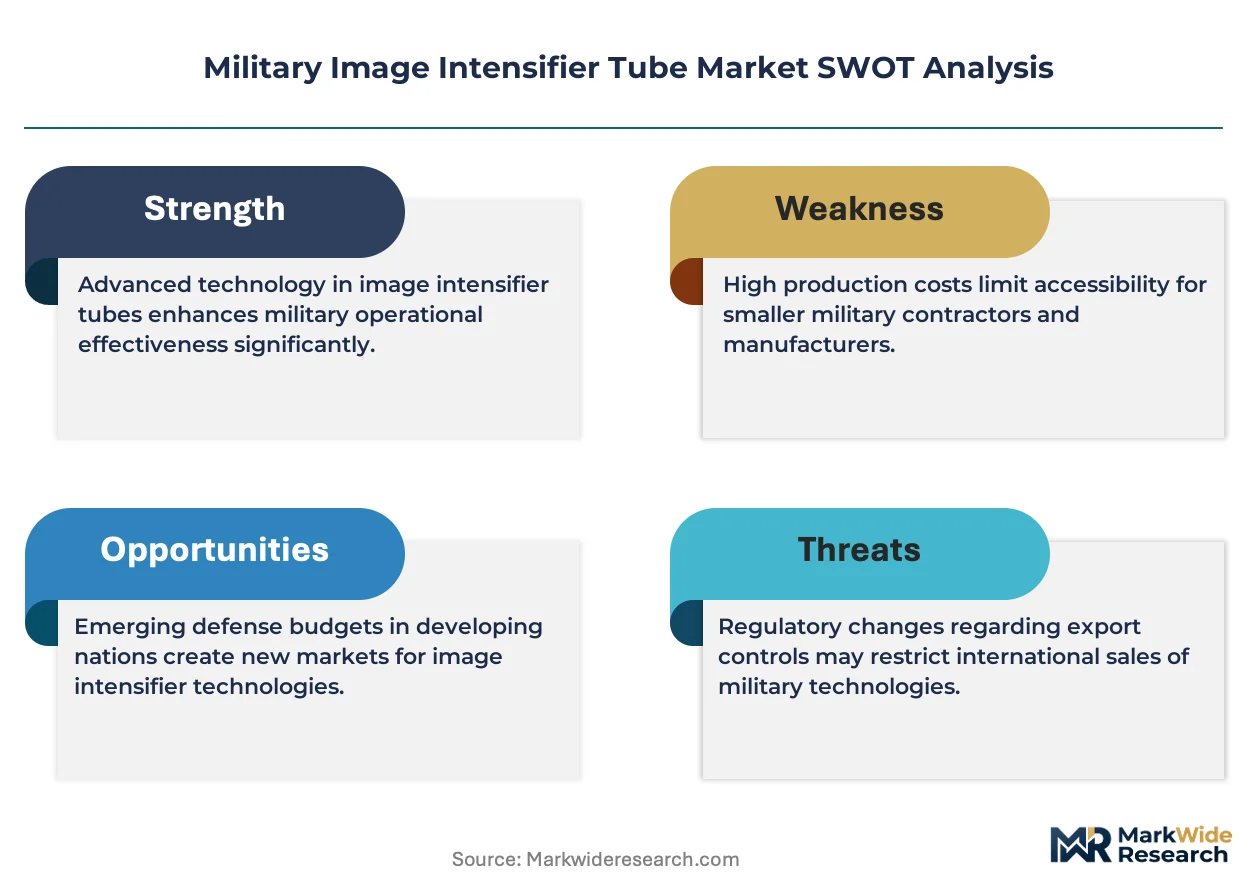
ITAR-controlled gallium arsenide photocathode technology is concentrating domestic U.S. supply chains while fragmenting allied access to Gen 3 night vision capabilities. Export licensing delays and domestic sourcing mandates are restructuring procurement eligibility pools.
Growth Catalysts
- Special Operations Procurement:U.S. SOCOM modernization programs are accelerating tube replacement cycles for helmet-mounted and weapon-sight applications.
- REACH Compliance Reformulation:EU Green Deal phosphor chemistry mandates are driving R&D investment in reduced-hazard europium-doped alternatives.
- Aviation Night Vision:Rotary-wing pilot training expansion across NATO allies is sustaining demand for aviation-grade intensifier configurations.
Market Restraints
- ITAR Fragmentation:U.S. State Department export controls block non-U.S. entities from accessing Gen 3 manufacturing know-how, bifurcating supply tiers.
- Raw Material Concentration:Gallium and arsenic refining capacity clusters in China, creating input vulnerability for Western photocathode production.
- Digital Sensor Substitution:Uncooled thermal imagers and low-light CMOS sensors are capturing law enforcement and perimeter security applications.
Strategic Opportunities
- Drone-Mounted Fusion:Hybrid intensifier-thermal payloads for unmanned reconnaissance require compact, low-power tube architectures.
- Space Radiation Hardening:Silicon microchannel plate variants offer satellite imaging resilience against particle bombardment.
- India Defense Indigenization:PLI scheme incentives and BIS standardization are opening procurement channels for non-ITAR Gen 2+ suppliers.
Industry Challenges
- Photocathode Fabrication Talent:Thin-film gallium arsenide deposition expertise resides with a narrow cohort of vacuum electronics specialists.
- Dual-Use Classification Complexity:ITAR and EU dual-use regulation overlap creates licensing uncertainty for components with civilian security applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Image Intensifier Tube Market |
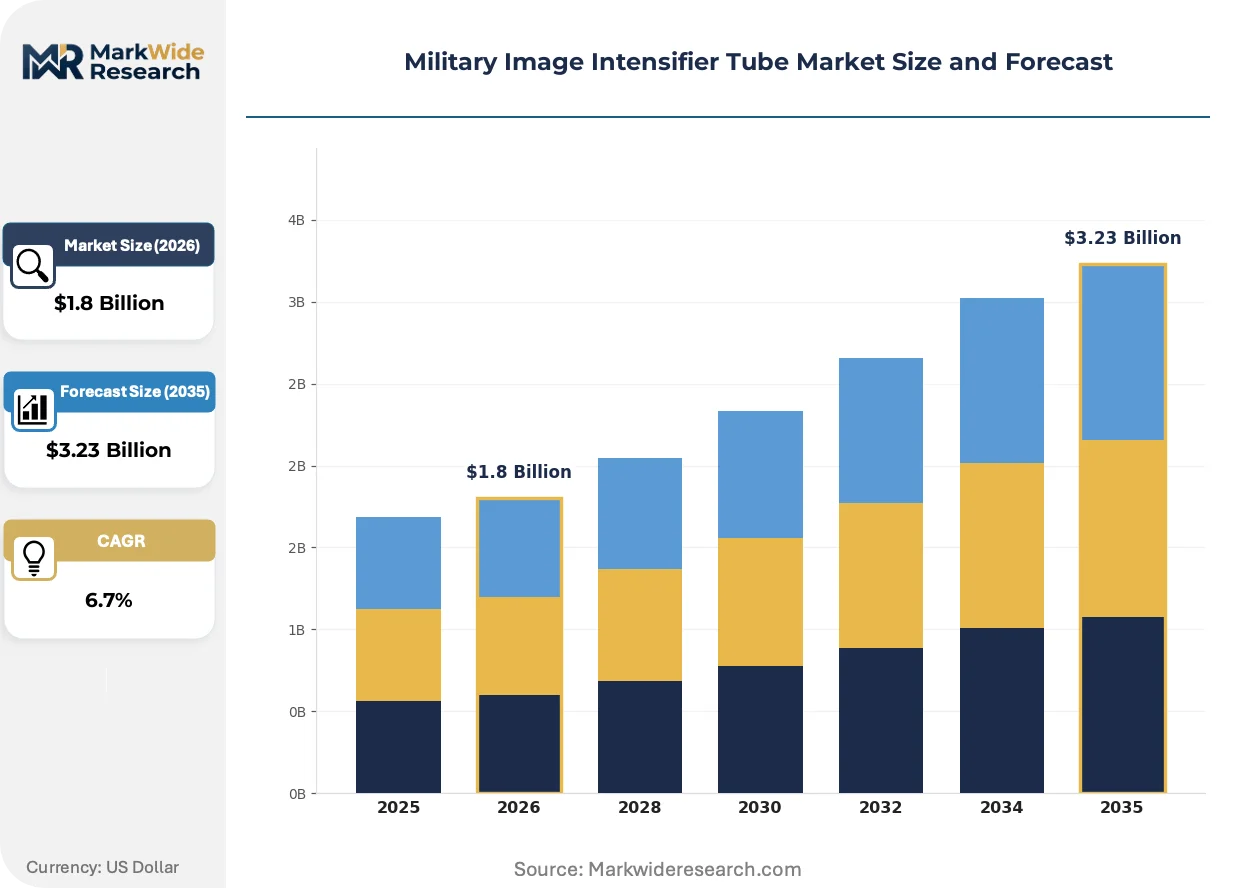
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gen 1, Gen 2, Gen 3, Digital Technology: Photonics, Microchannel Plate, Silicon, CMOS Application: Surveillance, Reconnaissance, Target Acquisition, Night Vision End User: Defense, Law Enforcement, Aerospace, Marine |
| Companies Covered | L3Harris Technologies, Elbit Systems, Thales Group, Photonis, Hensoldt AG, BAE Systems, Exosens, FLIR Systems, Aselsan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Image Intensifier Tube Market Shifts & Advancements
Digital fusion architectures and environmental compliance mandates are compressing traditional tube performance advantages while opening new application vectors. Technology trajectories favor hybrid sensing over pure intensification.
White phosphor P-45 output is consolidating aviation and special operations preferences through improved target discrimination and reduced eye fatigue. U.S. Army Aviation and SOCOM units have standardized on this spectral output for helmet-mounted displays. The shift is consolidating procurement specifications around a single phosphor chemistry, marginalizing legacy green P-43 configurations.
EU REACH Annex XVII restrictions on hazardous substances are forcing phosphor reformulation across European NATO supply chains. ECHA registration requirements for europium and terbium compounds are extending qualification timelines for new tube designs. German and French manufacturers are accelerating in-house phosphor synthesis to control substance compliance.
Multi-year system-of-systems contracts are displacing discrete tube procurement across major defense ministries. End-users now specify performance at the goggle or sight level rather than at the component tier. This pattern concentrates specification authority with prime contractors in the United States and Israel, compressing direct tube manufacturer visibility into end-demand.
Military Image Intensifier Tube Market Segmentation
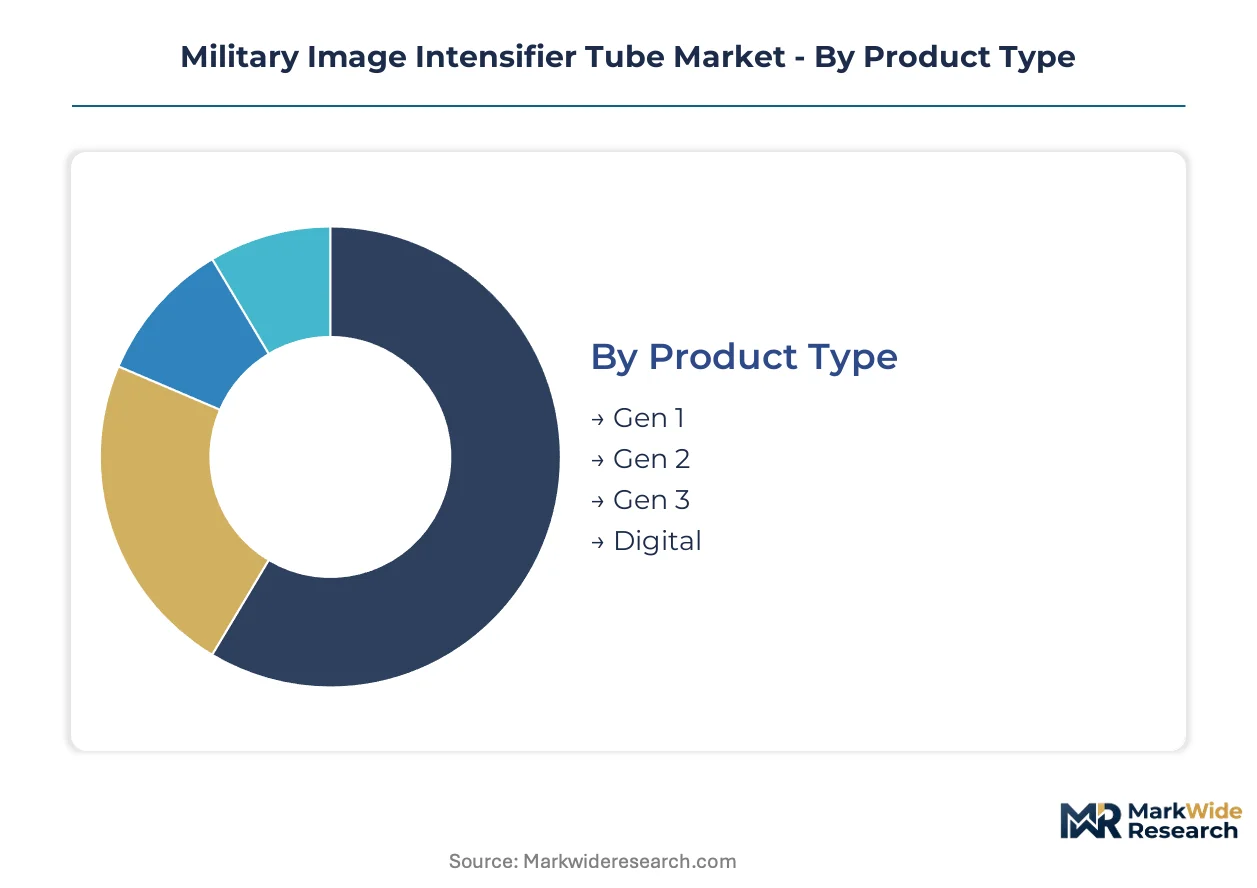
Military image intensifier tube procurement patterns diverge sharply across performance tiers and end-use environments. Upgrade cycles for aviation and special operations units concentrate demand in premium configurations, while perimeter security and training applications sustain volume in legacy generations.
Product Type:
Replacement timelines stretch from 3-5 years for aviation-grade tubes to 10+ years for static surveillance installations, creating tiered procurement rhythms across defense budgets.
- Gen 3:Gallium arsenide photocathodes deliver luminous gains exceeding 50,000 with near-infrared sensitivity to 900nm. U.S. SOCOM and Army Aviation standardize on these tubes for helmet-mounted displays, though ITAR restrictions block non-U.S. entities from accessing this tier.
- Digital:CMOS sensor hybrids fuse intensified imagery with data recording and wireless transmission. Law enforcement drone units and perimeter security operators in Germany and France adopt these for evidence capture and remote monitoring where pure low-light performance is secondary.
- Gen 2:Multi-alkali photocathodes serve NATO allies without ITAR access and emerging defense markets. Israeli and Indian forces deploy these in vehicle-mounted sights and training goggles.
- Gen 1:S-20 photocathode technology persists in cost-constrained training and reserve unit applications. African and Southeast Asian procurement channels sustain residual manufacturing capacity.
Volume placements concentrate in Gen 3; the faster expansion belongs to Digital.
Technology:
Core amplification architectures determine radiation tolerance, power consumption, and integration complexity with downstream optical systems.
- Microchannel Plate:Glass capillary arrays with 6-12 micron pore diameters multiply electron cascades across 10,000:1 gain ratios. U.S. and Israeli manufacturers dominate this segment through captive fiber drawing and hydrogen reduction furnaces.
- Photonics:Vacuum tube assemblies integrating photocathode, MCP, and phosphor screen in hermetic housings. German and French suppliers optimize these for aviation NVG form factors requiring sub-300g mass.
- Silicon:Solid-state alternatives resist particle bombardment in satellite imaging payloads. European Space Agency and NASA research contracts fund development of silicon MCP variants for orbital surveillance.
- CMOS:Sensor fusion layers enable image overlay, edge detection, and digital zoom. South Korean and Japanese electronics houses supply these for hybrid intensifier-thermal systems.
Procurement gravity sits with Microchannel Plate; Silicon is climbing the fastest for non-terrestrial applications.
Application:
Operational tempo and threat environment dictate whether tubes serve dismounted infantry, vehicle platforms, or fixed installations.
- Night Vision:Helmet-mounted and weapon-sight configurations demand compact, shock-resistant tubes with rapid automatic gain control. U.S. Army ground forces and British Army infantry units drive replacement cycles here.
- Target Acquisition:Designated marksman and sniper systems require high-resolution tubes with minimal distortion at field edges. Israeli Defense Forces and Indian Army special units specify these for precision engagement.
- Surveillance:Tripod-mounted and tower installations prioritize extended MTTF and passive operation. Border security agencies in Poland and Romania deploy these along eastern NATO frontiers.
- Reconnaissance:Handheld and vehicle-mounted systems balance magnification with portability. French Foreign Legion and German KSK special forces procure modular tube assemblies for rapid reconfiguration.
Contract awards cluster in Night Vision; Reconnaissance is gaining share fastest as unmanned platforms proliferate.
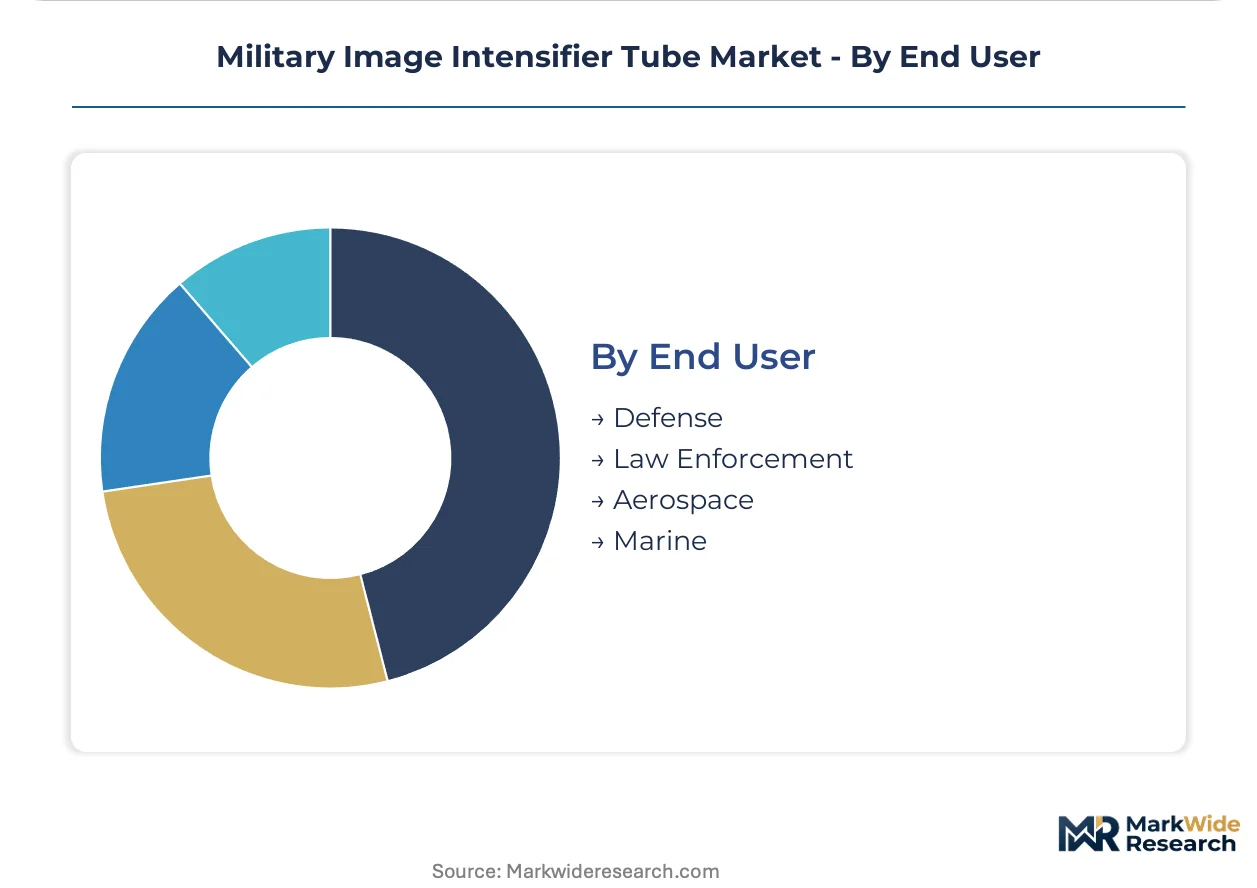
End User:
Budget authority and operational classification determine whether procurement flows through defense ministries, interior departments, or civilian aviation regulators.
- Defense:National military establishments account for the dominant revenue share, with procurement concentrated in special operations, aviation, and armored vehicle modernization lines. U.S. DoD, UK MoD, and Israeli MoD direct specification authority.
- Law Enforcement:Police tactical units and border patrol agencies adopt commercial-off-the-shelf and exportable configurations. German Federal Police and French Gendarmerie sustain European demand in this tier.
- Aerospace:Rotary-wing pilot training and fixed-wing special missions require aviation-certified tubes with electromagnetic interference shielding. NATO flight training centers in the United States, Germany, and Italy standardize these.
- Marine:Naval surface vessels and submarine periscopes specify salt-fog resistant housings and extended depth ratings. Royal Navy and U.S. Navy surface warfare programs maintain niche demand.
Funding authorization concentrates in Defense; Law Enforcement shows the steepest expansion trajectory as urban counterterrorism budgets rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for military image intensifier tubes concentrates in defense procurement channels across five major national markets, each shaped by distinct regulatory frameworks and operational modernization priorities.
United States
U.S. Army Aviation and SOCOM programs drive premium tube procurement for helmet-mounted displays and precision targeting systems. ITAR regulations administered by the U.S. State Department restrict Gen 3 technology transfer, fortifying domestic supply chains. Rochester, New York anchors concentrated manufacturing for gallium arsenide photocathode production serving classified defense contracts.
Germany
Federal Police tactical units and Bundeswehr special forces sustain demand for exportable Gen 2+ configurations and aviation-certified tubes. ECHA REACH Annex XVII mandates phosphor chemistry reformulation, extending qualification timelines for new designs. Oberkochen and Wetzlar host precision optics clusters where manufacturers accelerate in-house phosphor synthesis to control compliance.
Israel
Israel Defense Forces modernization programs and precision engagement requirements anchor regional demand for high-resolution target acquisition tubes. Israeli Ministry of Defense procurement prioritizes vertically integrated tube-to-system manufacturing. Haifa and the Central District concentrate defense electronics production serving domestic and allied nation exports.
United Kingdom
British Army infantry replacement cycles and Royal Navy surface warfare programs sustain procurement for helmet-mounted and marine-grade configurations. UK MoD specification authority increasingly flows through prime contractors rather than direct tube manufacturers. Southampton and Glasgow harbor defense electronics clusters adapting to system-level contracting patterns.
India
Indian Army special units and vehicle-mounted sight programs generate procurement for non-ITAR Gen 2+ tubes as indigenization accelerates. PLI scheme incentives and BIS standardization open channels for foreign suppliers meeting local content thresholds. Hyderabad and Bengaluru concentrate defense electronics manufacturing under Make in India frameworks.
Military Image Intensifier Tube Market Competitive Landscape
Domestic sourcing mandates dominate the current landscape as defense agencies consolidate procurement around nationally controlled supply chains. The vendor structure organizes into three tiers: ITAR-cleared U.S. specialists with captive photocathode production, European NATO suppliers navigating REACH compliance, and emerging non-aligned producers serving markets outside classification regimes. Capacity expansion and strategic partnerships represent the principal competitive vectors as manufacturers seek eligibility for restricted procurement pools.
Among U.S.-based defense primes, L3Harris Technologies exemplifies the vertically integrated archetype through in-house gallium arsenide photocathode production. Elbit Systems occupies a position representing Israeli and allied nation supply through integrated tube-to-system manufacturing. Photonis anchors the European specialist tier, competing across NATO channels with reformulated phosphor architectures compliant with ECHA frameworks.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Elbit Systems |
| Thales Group |
| Photonis |
| Hensoldt AG |
| BAE Systems |
| Exosens |
| FLIR Systems |
| Aselsan |
| Others |
Supply & Pricing Matrix
Gen 3 gallium arsenide photocathode certification against non-ITAR Gen 2+ alternatives bifurcates both cost structures and supplier eligibility pools. U.S. SOCOM and Army Aviation contracts command substantial premiums for ITAR-cleared domestic production, while European and allied nation procurement channels navigate export licensing delays and REACH compliance costs that reshape total delivered economics.
Pricing Analysis
Volume placements concentrate in mid-tier Gen 2+ configurations where NATO allies and emerging defense markets optimize unit economics, while margins accrue to ITAR-restricted Gen 3 suppliers serving U.S. special operations and aviation programs. Price differentiation hinges on photocathode material certification and phosphor chemistry compliance tier, with white phosphor P-45 output commanding aviation-grade premiums over legacy green P-43 alternatives. Cost compression in European supply chains is intensifying as ECHA registration requirements extend qualification timelines for europium-doped reformulations. Law enforcement and perimeter security buyers exhibit highest price sensitivity, prioritizing digital intensifier hybrids with data portability over pure low-light performance.
Supply Chain Analysis
Gallium and arsenic refining capacity rests on Chinese specialty metal producers, creating input vulnerability for Western photocathode fabrication. Microchannel plate glass drawing and hydrogen reduction furnace capacity clusters in the United States and Israel, while phosphor synthesis capabilities concentrate in Germany and France. Single-source vulnerability runs through gallium arsenide substrate supply for ITAR-cleared production. Distribution runs through prime contractors and system integrators rather than direct tube manufacturers, compressing component-tier visibility into end-demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital intensifier-thermal fusion architectures are displacing pure vacuum tube procurement across reconnaissance and drone-mounted applications, compressing traditional performance advantages while opening new specification channels.
For Market Incumbents: Deploy captive photocathode production as a certification barrier against non-ITAR competitors. L3Harris Technologies exemplifies this through in-house gallium arsenide deposition serving classified U.S. contracts. Backward integration into phosphor synthesis mitigates REACH compliance timeline risk for European manufacturing footprints. Digital sensor substitution from uncooled thermal imagers and low-light CMOS arrays threatens perimeter security and law enforcement volume. For New Entrants and Emerging Players: Indian defense electronics procurement under PLI scheme incentives represents the most penetrable non-ITAR channel for Gen 2+ tube suppliers meeting BIS localization thresholds. Drone-mounted fusion payloads for unmanned reconnaissance offer white-space entry where compact, low-power architectures outweigh legacy performance specifications. Partner with Israeli or South Korean system integrators to bypass direct U.S. prime contractor qualification barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in defense prime acquisition of specialty photocathode and microchannel plate producers for ITAR-cleared supply chain control. Long-term viability favors suppliers with demonstrated gallium arsenide deposition expertise and established SOCOM or Army Aviation program office relationships. Watch silicon microchannel plate radiation-hardening progress as an inflection signal for satellite imaging payload substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Photocathode Production Capacity Expansion | Captive gallium arsenide deposition secures ITAR-cleared eligibility for U.S. SOCOM and Army Aviation contracts. |
| Phosphor Chemistry Reformulation Program | Europium-doped alternatives meeting ECHA REACH Annex XVII requirements sustain European NATO supply chain access. |
| Digital-Intensifier Fusion Platform Development | CMOS hybrid architectures address law enforcement drone and perimeter security demand shifts away from pure vacuum tubes. |
| Silicon Microchannel Plate R&D Investment | Radiation-hardened variants target European Space Agency and NASA satellite imaging contracts outside terrestrial defense procurement. |
| India Localization Partnership Structure | PLI scheme-compliant manufacturing in Hyderabad or Bengaluru opens non-ITAR Gen 2+ procurement channels for Indian Army programs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this military image intensifier tube analysis. Primary interviews with vacuum electronics manufacturing directors, defense procurement officers at national ministries, night vision system integrators, and phosphor chemistry specialists combined with U.S. State Department ITAR licensing databases, ECHA substance registration records, and Indian BIS standardization documents. Bottom-up tube shipment estimates by generation tier and top-down defense budget allocation analysis provided cross-validation across the modeling period.
Data-stream reconciliation integrated production capacity assessments, program office budget justification documents, and prime contractor supply chain disclosures. Segmentation modeling spanned product generation, core amplification architecture, end-use application, and national procurement channel across the projection horizon. CAGRs derived from fitted trend analysis of historical program funding cycles and announced modernization timelines. Forecast inputs incorporated SOCOM tube replacement velocity and NATO aviation training expansion commitments.
Revisions become necessary when ITAR regulatory scope expansion, REACH substance restriction amendments, or digital sensor performance breakthroughs materially alter procurement specifications. Forecasts reflect documented assumptions regarding program funding continuity and qualification timeline stability. Export licensing backlog accumulation, gallium supply disruption, or prime contractor consolidation represent specific risk factors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Aircraft Carrier Arresting Systems Market
Military Equipment and Infrastructure
Military Optoelectronic System Market
Military Equipment and Infrastructure
Europe Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Military Test Equipment Market
Military Equipment and Infrastructure
Global Stealth Warfare Market
Military Equipment and Infrastructure
Military Tent and Shelter Market
Military Equipment and Infrastructure
Military Wearable Computers Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Manpack Military Antennas Market
Military Equipment and Infrastructure
Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Global Landing String Equipment Market
Military Equipment and Infrastructure
Global Soldier Modernization Market
Military Equipment and Infrastructure
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Next Generation Military Power Supply Market
Military Equipment and Infrastructure
Deployable Military Shelter Systems Market
Military Equipment and Infrastructure
Howitzer Artillery System Market