
 Smart Wine Cellar Market | 2026-2036
Smart Wine Cellar Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Wine Cellar Market Intelligence
Connected-hvac technician shortages in North America is rotating toward smart appliance certification programs, expanding install capacity for premium climate systems. Breezaire leverages its decades in wine-specific cooling to sustain brand authority among high-end collectors. WhisperKOOL anchors the aftermarket retrofit segment with compressor-based units that compete on decibel ratings and remote monitoring reliability.
Smart wine cellars are precision climate enclosures that integrate temperature control, humidity management, and IoT connectivity to preserve wine chemistry across decades, typically maintaining conditions between 45-65°F and 50-70% relative humidity. Their primary commercial purpose is to eliminate storage risk for inventories where single-bottle values can exceed installation costs. Wine refrigerators dominate product-type revenue due to standardized form factors and shorter replacement cycles, while sensor technologies within the technology dimension command margin premiums through predictive maintenance algorithms. Built-in installations lead the installation category among luxury new construction, though portable units are gaining traction in urban rental markets where permanent modification is restricted.
The U.S. Department of Energy enforces efficiency standards under ENERGY STAR that shape compressor selection and insulation specifications for connected cooling equipment. California Title 24 building codes extend these requirements to smart home integrations, affecting control system power budgets. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants, forcing redesigns of cooling circuits in units sold across Europe. Stakeholders must monitor refrigerant transition timelines and regional efficiency tier upgrades to avoid stranded inventory in compliant markets.
Market Dynamics
Connected-hvac technician shortages in North America are rotating toward smart appliance certification programs, expanding install capacity for premium climate systems and reshaping how cooling expertise distributes across residential and commercial channels.
Growth Catalysts
- EU F-Gas Regulation:Phasedown mandates for hydrofluorocarbon refrigerants are accelerating cooling circuit redesigns, creating replacement demand for compliant smart cellar units across European markets.
- Luxury residential development:California's Napa Valley and Sonoma County wine corridor exhibit collector density that supports premium smart rack deployments as standard amenity installations.
- Sensor fusion:Predictive maintenance algorithms embedded in IoT-enabled humidity and temperature monitoring systems are extending equipment lifecycles and reducing insurance premiums for high-value inventories.
Market Restraints
- Copper and aluminum input volatility:Compressor manufacturing and heat exchanger fabrication face raw material cost swings that compress margin structures for mid-tier manufacturers.
- Technician certification bottlenecks:EPA Section 608 certification requirements for refrigerant handling create supply-side constraints on qualified installation labor pools.
- Substitution by passive cellars:Underground construction and natural geothermal cooling in temperate zones displace active cooling demand for bulk storage applications.
Strategic Opportunities
- Urban rental markets:Portable smart cellar units address permanent modification restrictions in dense metropolitan housing stock where wine collecting participation is rising.
- California Title 24 integration:Smart home control system power budgets create specification pathways for connected cooling equipment in new construction.
- Blockchain provenance convergence:Integration of bottle authentication and storage condition logging addresses secondary market verification needs for investment-grade collections.
Industry Challenges
- Connected-hvac skill gaps:Shortages of technicians cross-trained in refrigeration mechanics and IoT network configuration delay installation timelines and elevate service costs.
- Interoperability fragmentation:Proprietary smart home protocols create integration friction with existing building automation systems, complicating retrofit specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Wine Cellar Market |
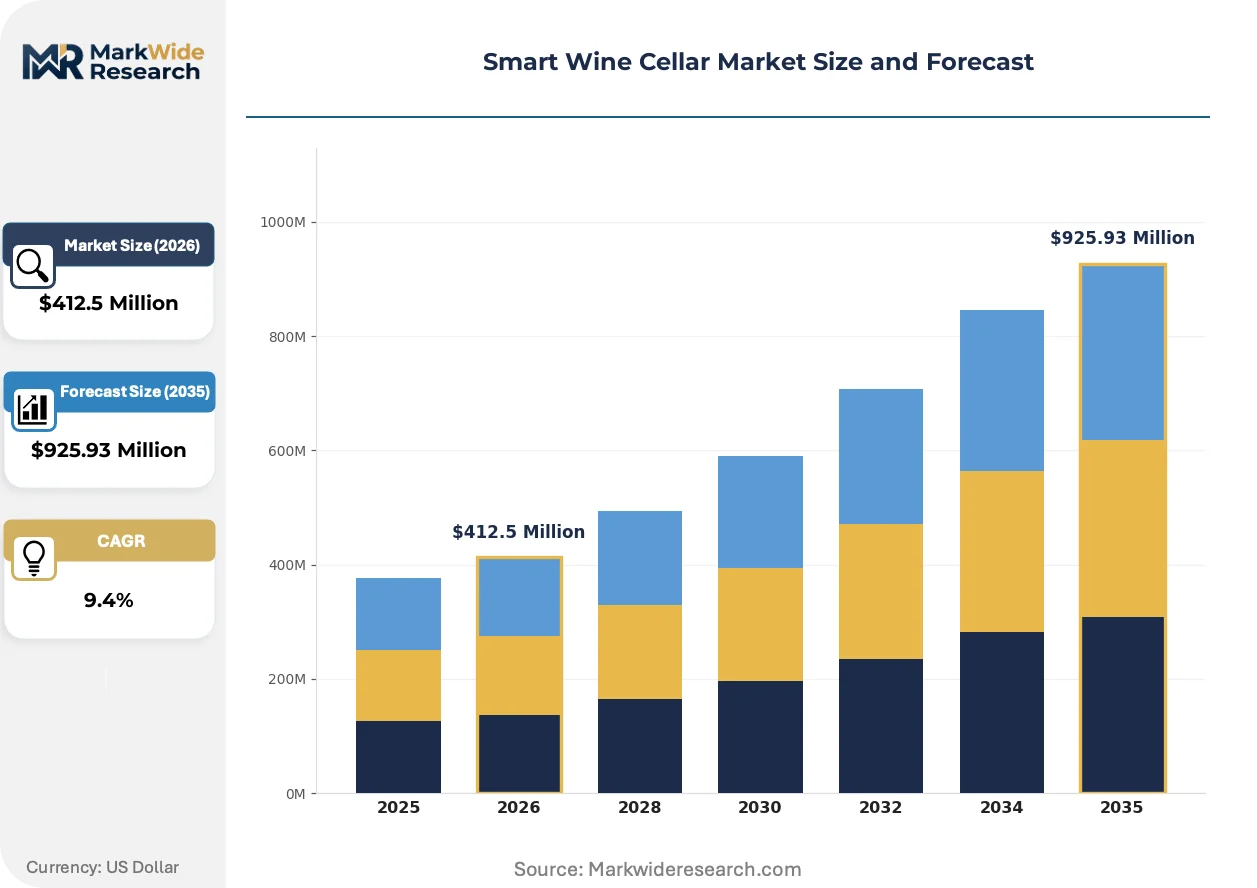
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $925.93 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wine Refrigerators, Temperature Controllers, Humidity Monitors, Smart Racks Technology: IoT Integration, Mobile App Control, Sensor Technologies, Data Analytics End User: Homeowners, Restaurants, Wine Distributors, Collectors Installation: Built-in, Standalone, Wall-mounted, Portable |
| Companies Covered | Breezaire, Le Cache, Wine Guardian, KoolR, Goguette, WhisperKOOL, Transtherm, KoolMore, CellarPro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Wine Cellar Market Strategic Shifts & Innovations
Active cooling architectures are fragmenting into modular, software-defined components that separate thermal management from physical enclosure design, enabling faster product iteration cycles and supplier specialization.
Thermoelectric cooling is decomposing the traditional compressor-centric product hierarchy in sub-500 bottle capacity segments. Boutique collectors and urban apartment dwellers are adopting solid-state units for silent operation and vibration elimination. This technology is decomposing the aftermarket service revenue model by eliminating compressor failure modes and extending maintenance-free operational windows.
The EU Ecodesign for Energy-related Products Directive is tightening minimum efficiency requirements for connected cooling appliances sold across member states. Manufacturers must redesign insulation specifications and control system power budgets to maintain market access. Built-in installation segments face the steepest compliance redesign costs due to fixed form factor constraints.
Collector procurement preferences are pivoting toward outcome-based preservation guarantees rather than equipment ownership. High-net-worth individuals in California's wine corridors now specify temperature and humidity performance contracts with penalty clauses for excursion events. This shift compresses capital equipment margins while expanding recurring monitoring and insurance-adjacent service revenues.
Smart Wine Cellar Market Segmentation
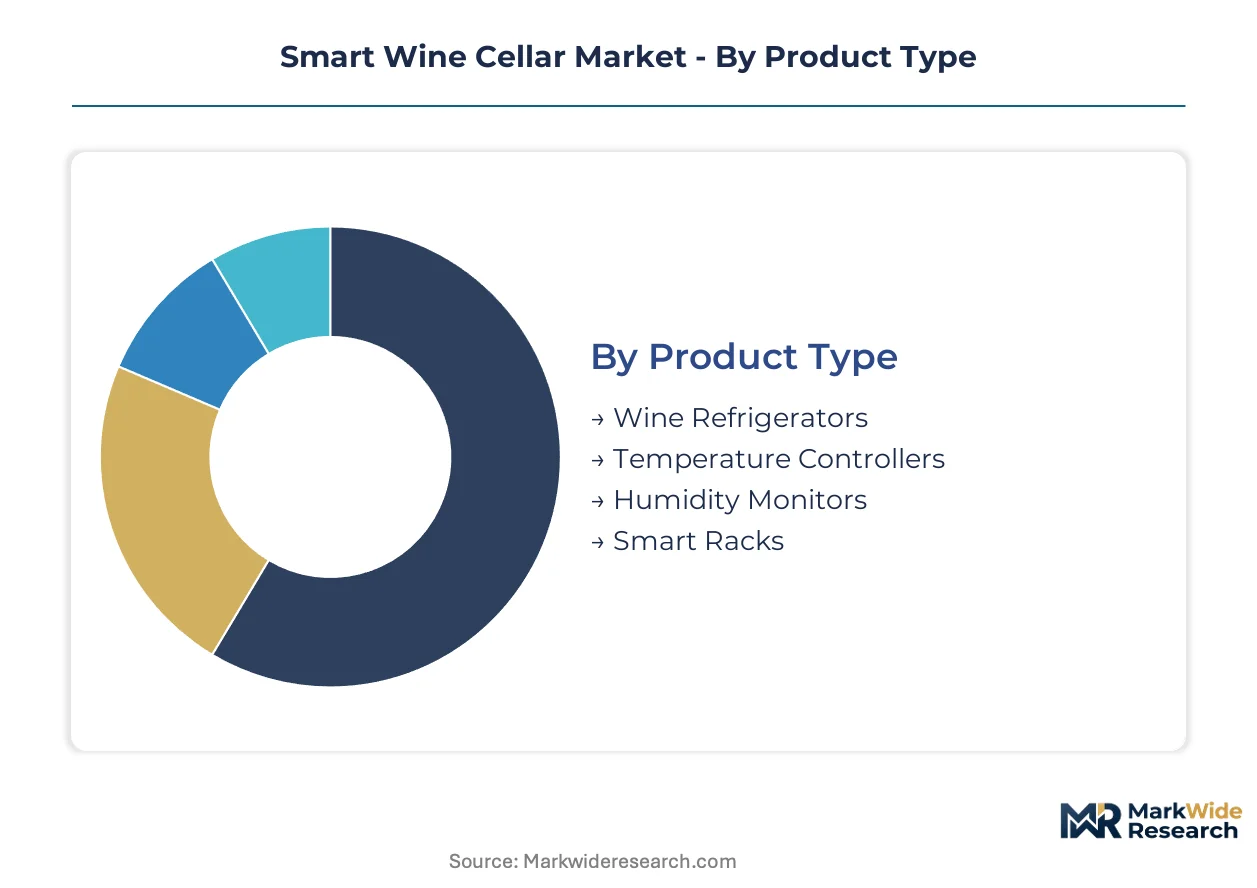
Wine cellar purchasing decisions split across preservation technology, integration complexity, and inventory scale. Segmentation reveals where capital concentrates versus where replacement cycles accelerate.
Product Type:
Domestic demand in the United States concentrates in self-contained cooling systems, while European procurement favors distributed sensor networks for retrofit installations.
- Wine Refrigerators:Standardized form factors with compressor or thermoelectric cooling cores dominate residential procurement. California's Napa Valley and Sonoma County collector density supports premium unit deployments with extended warranties.
- Temperature Controllers:Precision cooling modules designed for integration with passive cellar structures. Demand clusters in temperate zones where geothermal cooling supplements active regulation, particularly in France and Italy.
- Humidity Monitors:Standalone sensor units with wireless data transmission for existing storage infrastructure. Restaurants and small distributors adopt these for compliance documentation without full system replacement.
- Smart Racks:RFID-enabled bottle positioning systems with inventory management software. High-net-worth collectors in the United States specify these for investment-grade collections requiring provenance tracking.
Wine refrigerators command the established base. The steepest expansion runs through smart racks.
Technology:
Cost tiers separate basic connectivity from predictive systems, with margin concentration in algorithm-driven maintenance platforms.
- IoT Integration:Networked device architectures enabling remote monitoring and automated alert systems. California Title 24 building codes shape power budget specifications for new construction deployments.
- Mobile App Control:Smartphone interfaces for temperature adjustment and inventory visualization. Urban rental markets favor these for portable units where permanent modification is restricted.
- Sensor Technologies:Multi-parameter environmental monitoring with predictive maintenance algorithms. These command margin premiums through insurance premium reductions for high-value inventories.
- Data Analytics:Consumption pattern analysis and market valuation tools for secondary market timing. Collector procurement is shifting toward outcome-based preservation guarantees leveraging these capabilities.
Sensor technologies anchor the premium tier. The fastest share gains are emerging through data analytics.
End User:
Application requirements diverge sharply between preservation duration, access frequency, and compliance documentation needs.
- Homeowners:Residential collectors prioritizing long-term bottle chemistry preservation. United States luxury residential developers are expanding built-in installations as standard amenities in high-end construction.
- Restaurants:Commercial operators requiring rapid access and service temperature staging. These users drive demand for dual-zone cooling systems with quick-recovery compressors.
- Wine Distributors:Inventory holders managing provenance documentation and condition verification for secondary market sales. Blockchain integration addresses their authentication requirements.
- Collectors:Investment-focused individuals with collections where single-bottle values exceed installation costs. This segment specifies performance contracts with penalty clauses for excursion events.
Homeowners represent the volume base. The steepest expansion trajectory is concentrating among collectors.
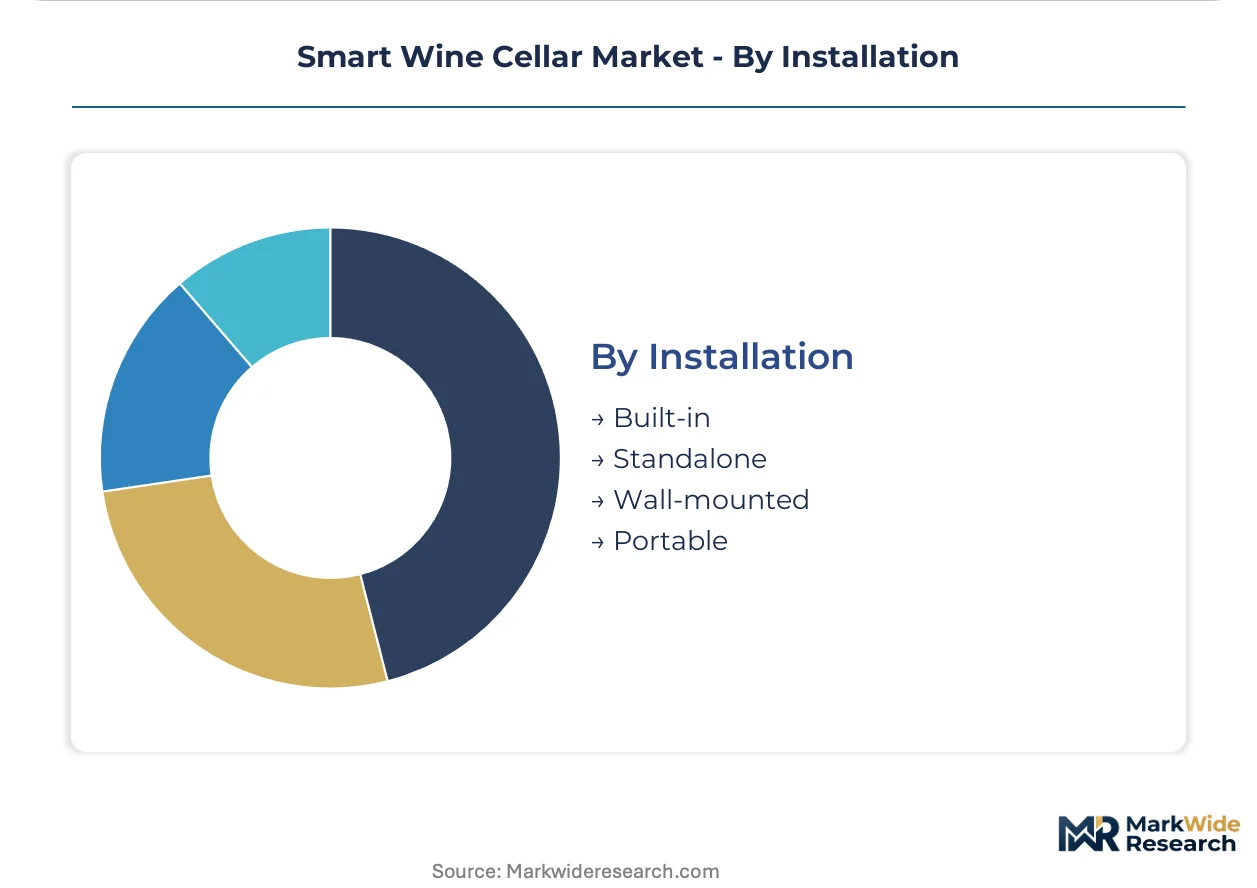
Installation:
Maturity gradients separate legacy construction compatibility from smart home integration requirements.
- Built-in:Custom-fitted enclosures integrated during construction or major renovation. The EU Ecodesign for Energy-related Products Directive forces the steepest compliance redesign costs due to fixed form factor constraints.
- Standalone:Self-contained units requiring only electrical connection and ventilation clearance. These dominate aftermarket retrofit activity with shorter replacement cycles.
- Wall-mounted:Space-efficient configurations for urban apartments with limited floor area. European markets show particular concentration given housing density patterns.
- Portable:Relocatable units addressing permanent modification restrictions in dense metropolitan rental markets. Thermoelectric cooling eliminates compressor noise and vibration for these applications.
Built-in installations hold the established revenue base. Portable configurations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA efficiency standards under ENERGY STAR anchor North American procurement specifications, while the EU F-Gas Regulation and Ecodesign Directive reshape cooling circuit architectures across European markets. California Title 24 building codes extend these requirements to smart home integrations, creating compliance spillover effects.
United States
Luxury residential developers in California's Napa Valley and Sonoma County wine corridor are expanding built-in smart cellar installations as standard amenities. The Department of Energy enforces ENERGY STAR efficiency standards that shape compressor selection and insulation specifications. Collector density in these Northern California clusters supports premium smart rack deployments with extended warranty specifications.
Germany
The EU Ecodesign for Energy-related Products Directive tightens minimum efficiency requirements for connected cooling appliances sold across member states. Germany's Federal Environment Agency enforces the F-Gas Regulation phasedown of hydrofluorocarbon refrigerants, forcing cooling circuit redesigns. Industrial procurement in Baden-Württemberg favors distributed sensor networks for retrofit installations in existing wine storage infrastructure.
France
Temperature controller demand clusters in temperate zones where geothermal cooling supplements active regulation, particularly in Burgundy and Bordeaux wine regions. ANSM and CNIL oversight extends to connected device data handling for inventory management systems. Paris-based collectors are specifying outcome-based preservation guarantees with penalty clauses for excursion events.
Italy
Passive cellar construction and natural geothermal cooling in Tuscany and Piedmont displace active cooling demand for bulk storage applications. The national environmental regulator enforces EU Ecodesign compliance timelines for imported connected appliances. Milan's luxury residential sector shows emerging demand for wall-mounted configurations addressing space constraints in dense urban housing.
Japan
METI efficiency standards and JIS certification requirements shape product specifications for thermoelectric cooling units in sub-500 bottle capacity segments. Tokyo's urban apartment dwellers adopt solid-state units for silent operation and vibration elimination. Osaka-based distributors are integrating blockchain provenance systems for secondary market verification needs.
Smart Wine Cellar Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier that fragments across cooling technology and installation complexity vectors. The upper tier commands specification authority in luxury new construction through bundled climate-control offerings. The specialist tier competes on decibel ratings, remote monitoring reliability, and aftermarket retrofit compatibility. Consolidation pressure runs through refrigerant compliance redesigns that favor engineering depth. Dominant competitive moves include M&A to capture installation service networks and strategic partnerships with luxury residential developers for pre-specification positioning.
Within the cooling-system specialist tier, Breezaire and WhisperKOOL exemplify contrasting archetypes. Breezaire leverages decades in wine-specific cooling to sustain brand authority among high-end collectors requiring precision climate management. WhisperKOOL anchors the aftermarket retrofit segment with compressor-based units competing on decibel ratings and remote monitoring reliability. CellarPro occupies a position between these poles, representing the mid-tier fabricators adapting thermoelectric architectures for urban rental market constraints. These three companies collectively illustrate how brand heritage, noise engineering, and form-factor flexibility distribute competitive position across collector segments.
| Leading Market Players |
|---|
| Breezaire |
| Le Cache |
| Wine Guardian |
| KoolR |
| Goguette |
| WhisperKOOL |
| Transtherm |
| KoolMore |
| CellarPro |
| Others |
Cost & Logistics Intelligence
Thermoelectric cooling modules substituting compressor-based architectures in sub-500 bottle segments are redrawing supply geography toward semiconductor fabrication centers while compressing price premiums previously commanded by vibration-free operation. This substitution dynamic simultaneously elevates inbound electronics costs and erodes the traditional three-tier pricing structure anchored in mechanical complexity differentials.
Pricing Analysis
Long-term performance contracts with penalty clauses for temperature excursion events are displacing transactional equipment sales among California collectors and European investment-grade buyers. Price differentiation rests on sensor fusion density and predictive algorithm sophistication rather than raw cooling capacity. Cost compression in mid-tier thermoelectric units is intensifying because Chinese semiconductor packaging capacity has expanded. Restaurants and small distributors exhibit highest price sensitivity, while collectors with bottle values exceeding installation costs show minimal elasticity.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes are elevating landed costs for thermoelectric substrates and IoT sensor modules sourced from Taiwan and South Korea. Compressor manufacturing draws from Chinese aluminum extrusion and Japanese precision motor winding. Single-source vulnerability concentrates in peltier element substrates from specialized German and Austrian metallurgical suppliers. Distribution runs through HVAC wholesaler networks for built-in installations and direct-to-consumer e-commerce for portable configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among luxury residential developers specifying smart cellars as standard amenities, fragmenting procurement authority away from individual collectors and toward project-level volume contracting.
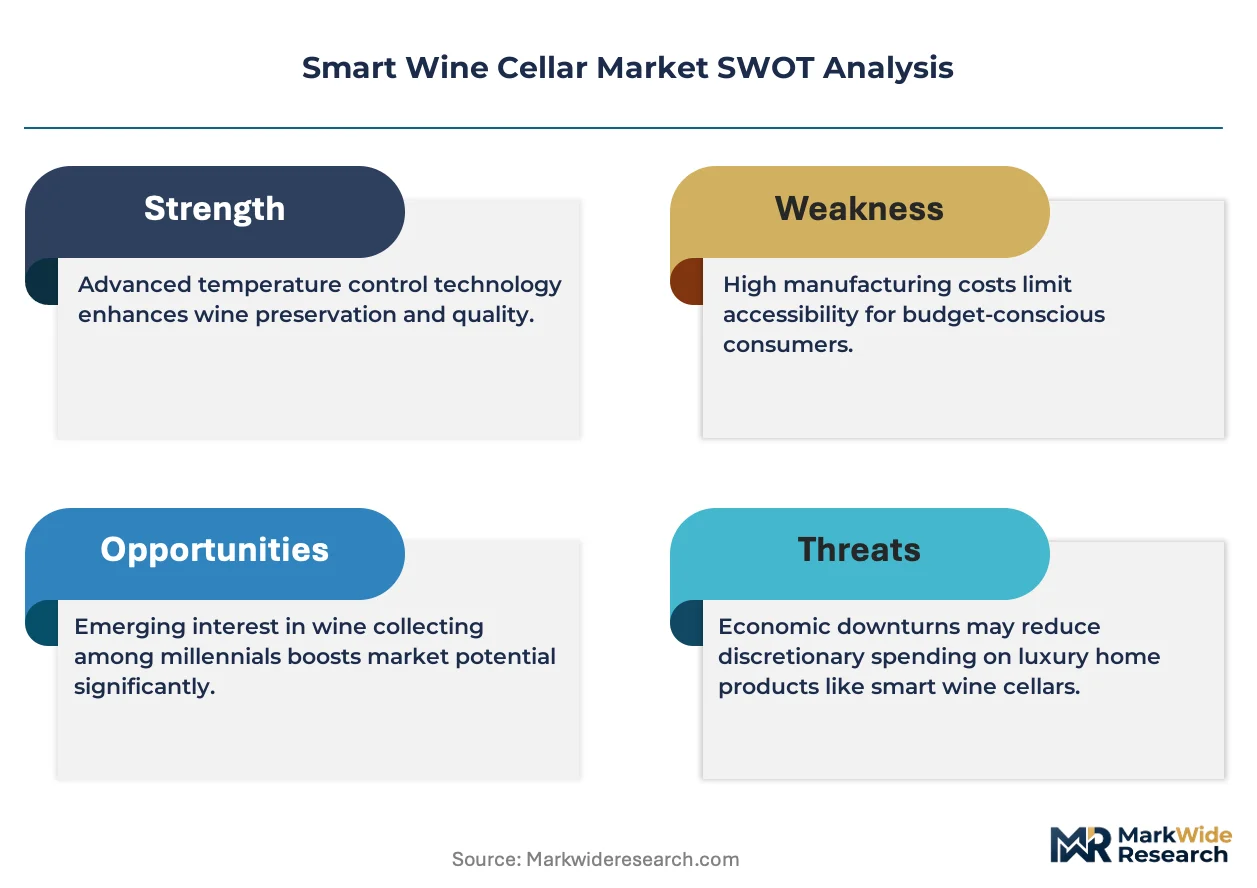
For Market Incumbents: Fortify installation service network density in California's wine corridor and Germany's Baden-Württemberg region to defend against emerging thermoelectric specialists lacking EPA Section 608 certification depth. Deepen backward integration into refrigerant reclamation infrastructure ahead of EU F-Gas phasedown deadlines. Prioritize sensor fusion R&D to maintain algorithm-driven service revenue streams as hardware margins compress. For New Entrants and Emerging Players: Aftermarket retrofit compliance documentation for restaurants and small distributors represents an underserved service layer where incumbents under-invest. Target wall-mounted thermoelectric configurations in Tokyo and Milan apartment markets where space constraints and rental restrictions block traditional built-in competition. Pursue white-label partnerships with luxury residential developers for pre-specification positioning before ground breaks. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier fabricators with thermoelectric engineering depth and existing California Title 24 compliance pathways. Long-term viability across the analysis window hinges on refrigerant transition readiness and IoT platform interoperability rather than brand heritage alone. Monitor EU Ecodesign implementation enforcement intensity as the inflection indicator for stranded inventory risk in European distribution channels.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition R&D | EU F-Gas Regulation mandates hydrofluorocarbon phasedown, forcing cooling circuit redesigns for market access. |
| Smart Home Platform Integration | California Title 24 power budget requirements create specification pathways for connected cooling in new construction. |
| Installation Service Network Expansion | EPA Section 608 certification bottlenecks make qualified technician pools a scarce competitive resource. |
| Blockchain Provenance Partnership | Secondary market verification needs for investment-grade collections drive authentication technology convergence. |
| Thermoelectric Product Line Extension | Urban rental market constraints favor silent, vibration-free solid-state cooling for sub-500 bottle capacities. |
Research Approach
Desk research of regulatory filings from EPA and EU ECHA, trade databases tracking compressor and thermoelectric component flows, and luxury residential development permit records preceded structured interviews with HVAC contractor operations managers, smart home integration specialists, wine cellar installation technicians, and procurement leads at high-end residential developers. Primary fieldwork with collectors in Napa Valley and Bordeaux supplemented secondary validation. Bottom-up unit shipment estimates triangulated against top-down construction spending allocations for climate-controlled storage infrastructure.
Variance decomposition across product type, cooling technology, installation complexity, and regional regulatory clusters shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers including residential construction permits and wine auction volume trends. Modeled inputs incorporated ENERGY STAR efficiency tier adoption curves and EU F-Gas compliance timeline assumptions without year-specific anchoring.
Forecasts assume regulatory continuity in EPA efficiency standards and EU Ecodesign implementation; material policy shifts including accelerated refrigerant bans or altered building code integration requirements would demand re-modeling. Practitioners should keep alternative scenarios live as connected-hvac technician certification throughput and semiconductor substrate supply conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
France Alcohol E-Commerce Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Wine Filtering Machine Market
Alcoholic Beverages
UK Tequila Market
Alcoholic Beverages
US Wine Market
Alcoholic Beverages
Rum Market
Alcoholic Beverages
Liquor Flavored Ice Cream Market
Alcoholic Beverages
Nitro Cocktails Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
Russia Tequila Market
Alcoholic Beverages
Australia Alcohol E-Commerce Market
Alcoholic Beverages
Alcohol Enzymes Market
Alcoholic Beverages
Digital Shaker Market
Alcoholic Beverages
North America Soju Market
Alcoholic Beverages
Cannabis-Based Alcoholic Beverages Market
Alcoholic Beverages
Tequila Market