
 Global Portable Coffee Makers Market | 2026-2036
Global Portable Coffee Makers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Portable Coffee Makers Market Foresight
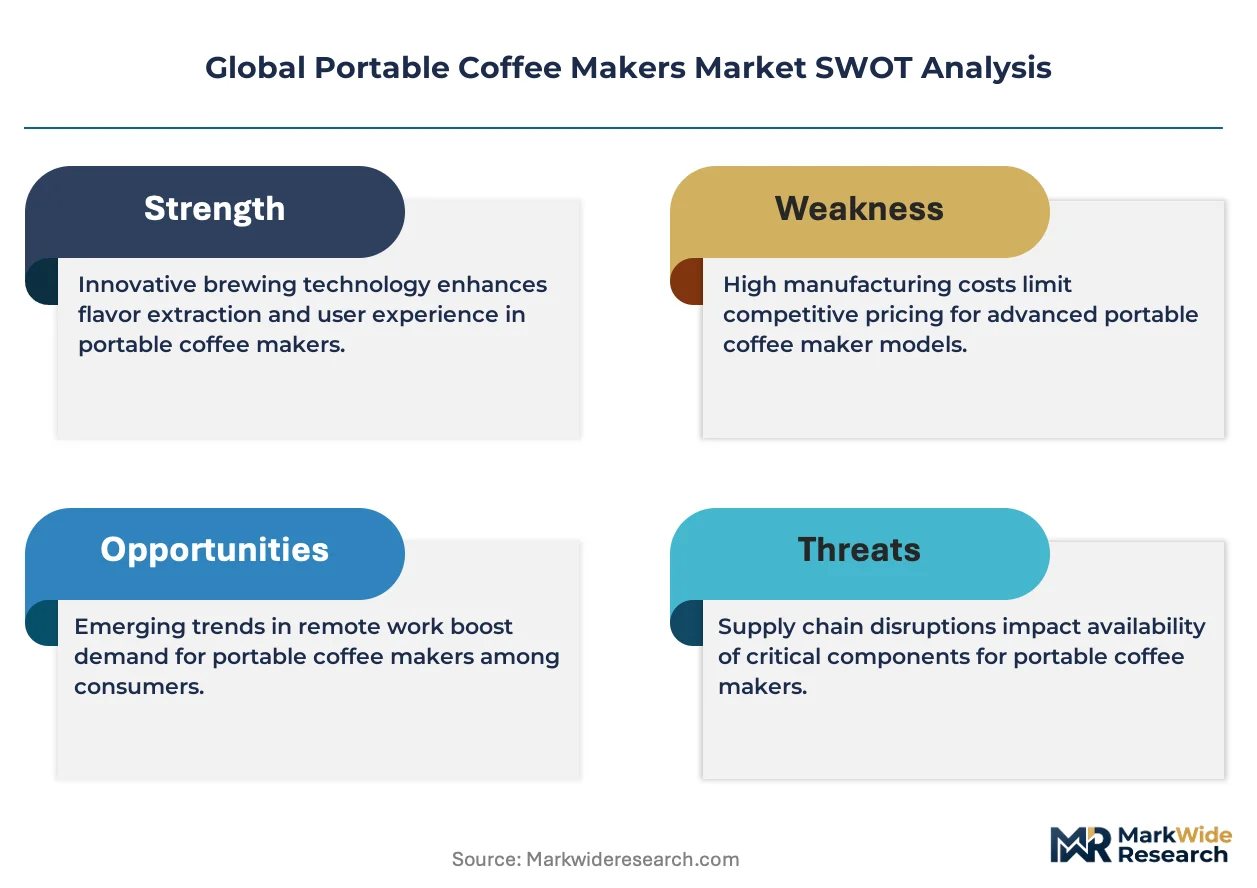
CE marking for electrical appliances is reorganizing competitive entry into the European portable coffee maker channel. Wacaco Company Limited leverages its manual press specialization to dominate ultralight outdoor segments. Nestlé S.A. sustains capsule system compatibility across multiple portable formats. Breville Group Limited anchors premium battery-operated espresso units through controlled retail distribution.
Portable coffee makers are compact, self-contained brewing devices engineered to operate without fixed electrical infrastructure, typically incorporating pressure systems between 8-15 bar, thermal insulation layers, and power sources ranging from manual kinetic energy to lithium-ion cells. These units serve consumers requiring quality coffee extraction during transit, fieldwork, or temporary lodging without access to conventional kitchen equipment. The battery-operated segment leads value generation as mobile workers and commuters prioritize one-touch espresso extraction, while manual press variants occupy the fastest-growing tier among backpackers and alpine enthusiasts seeking zero-dependency brewing. Capsule-compatible portable systems concentrate margin pools through recurring consumable attachment, though French press and pour-over technologies retain durable share among purist coffee enthusiasts rejecting proprietary pod ecosystems.
FDA food-contact material standards govern plastic and stainless steel components in US-bound portable brewers, while EU REACH restrictions on bisphenol derivatives and phthalates are forcing resin reformulation across Asian supply bases. Japan's Electrical Appliance and Material Safety Law imposes additional PSE certification burdens on battery-integrated models entering that market. Stakeholders must monitor evolving lithium-ion transport regulations from IATA and national aviation authorities, as these rules directly constrain product distribution through air freight channels and e-commerce fulfillment networks serving remote outdoor destinations.
Market Dynamics
EU F-Gas Regulation and REACH chemical compliance are forcing resin reformulation and thermal system redesign across Asian supply bases serving European-bound portable coffee makers, compressing margins while accelerating certification differentiation among battery-operated and manual press manufacturers.
Growth Catalysts
- Commuter Culture Density:Mobile workers in the United States, Germany, and Japan prioritize one-touch espresso extraction during transit, sustaining premium adoption of lithium-ion powered units.
- REACH Chemical Reformulation:Bisphenol and phthalate restrictions are accelerating BPA-free resin migration across stainless steel and plastic component supply chains.
- Alpine Outdoor Participation:Backpackers and camping enthusiasts across Japan and Germany are scaling purchases of zero-dependency manual press systems for backcountry brewing.
Market Restraints
- Lithium-Ion Transport Friction:IATA and national aviation authority restrictions constrain air freight distribution to remote outdoor destinations, elevating logistics costs for battery-integrated models.
- Resin Input Volatility:BPA-free polymer reformulation under REACH compliance is elevating material costs for Asian molders serving EU-bound production.
- Capsule Ecosystem Lock-In:Proprietary pod compatibility requirements create switching costs that disadvantage open-format French press and pour-over alternatives.
Strategic Opportunities
- PSE Certification Arbitrage:Battery-integrated models meeting Japan's Electrical Appliance and Material Safety Law can capture underserved premium segments in Tokyo and Osaka commuter corridors.
- CE Marking Channel Access:Electrical appliance compliance reorganization creates entry windows for certified manufacturers into European retail and e-commerce channels.
- Pour-Over Purist White Space:Open-format brewing systems rejecting proprietary pods retain durable share among specialty coffee enthusiasts in Germany and the United States.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA food-contact, REACH chemical, and PSE electrical compliance extends product launch cycles by 8-14 months.
- Thermal System Integration Complexity:Pressure system engineering between 8-15 bar demands specialized mechanical design talent scarce in consumer appliance development pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Portable Coffee Makers Market |
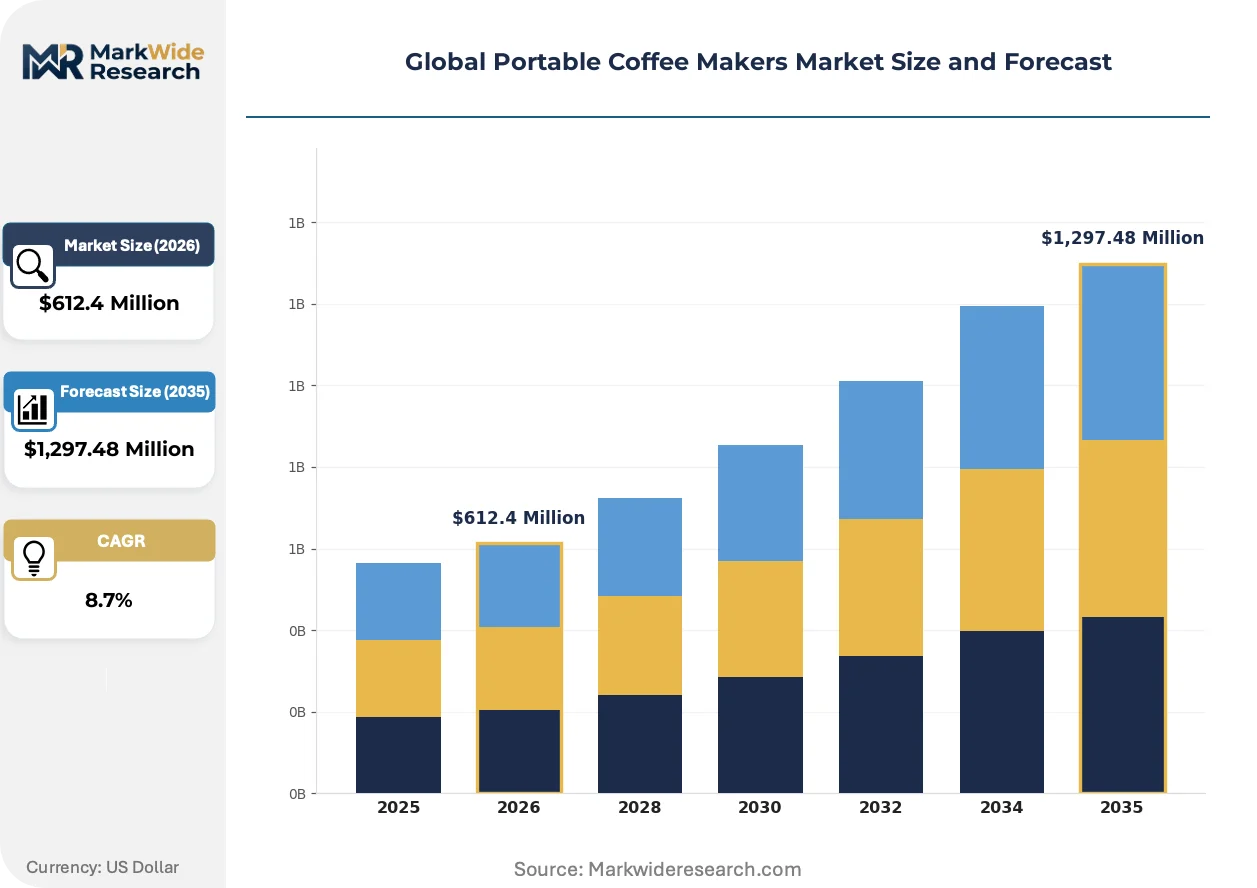
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Press, Capsule, Battery Operated, Thermal Mug, Espresso Portable, Compact Brewer Technology: Cold Brew, Single Serve, French Press, Vacuum Brewing, Instant Coffee, Pour Over Application: Outdoor Recreation, Office Use, Travel, Camping, Commuting, Study Areas End User: Individual Consumers, Coffee Enthusiasts, Mobile Workers, Boutique Cafes, Event Organizers, Students |
| Companies Covered | Keurig Dr Pepper Inc, Nestlé S.A., De’Longhi S.p.A., Hamilton Beach Brands Holding Company, Newell Brands, Electrolux AB, Koninklijke Philips N.V., Breville Group Limited, Wacaco Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Portable Coffee Makers Market Shifts & Advancements
Pressure system miniaturization and thermal insulation layering are actively compressing form factors while preserving extraction quality, enabling new use cases in ultralight outdoor and dense urban transit environments.
Solid-state battery chemistry is decomposing the thermal management constraints that previously limited heating element integration in sub-500 gram portable units. Alpine enthusiasts and bike commuters are adopting these systems at accelerating rates. The technology is decomposing the weight-performance tradeoff that historically forced buyers to choose between battery convenience and manual reliability.
F-Gas Regulation phase-down schedules are forcing hydrocarbon and CO2-based thermal system adoption in European-bound products. Compressor and heating element suppliers are reconfiguring component portfolios to eliminate HFC refrigerants. Battery-operated espresso units with integrated heating face the steepest redesign burdens in Germany and France.
Direct-to-consumer channel migration is fragmenting traditional retail gatekeeper control over portable coffee maker distribution. Specialty outdoor and coffee enthusiast communities are shifting discovery and purchase toward brand-owned digital storefronts and subscription models. This pattern concentrates in the United States and Germany where premium commuter and camping segments overlap.
Global Portable Coffee Makers Market Segmentation
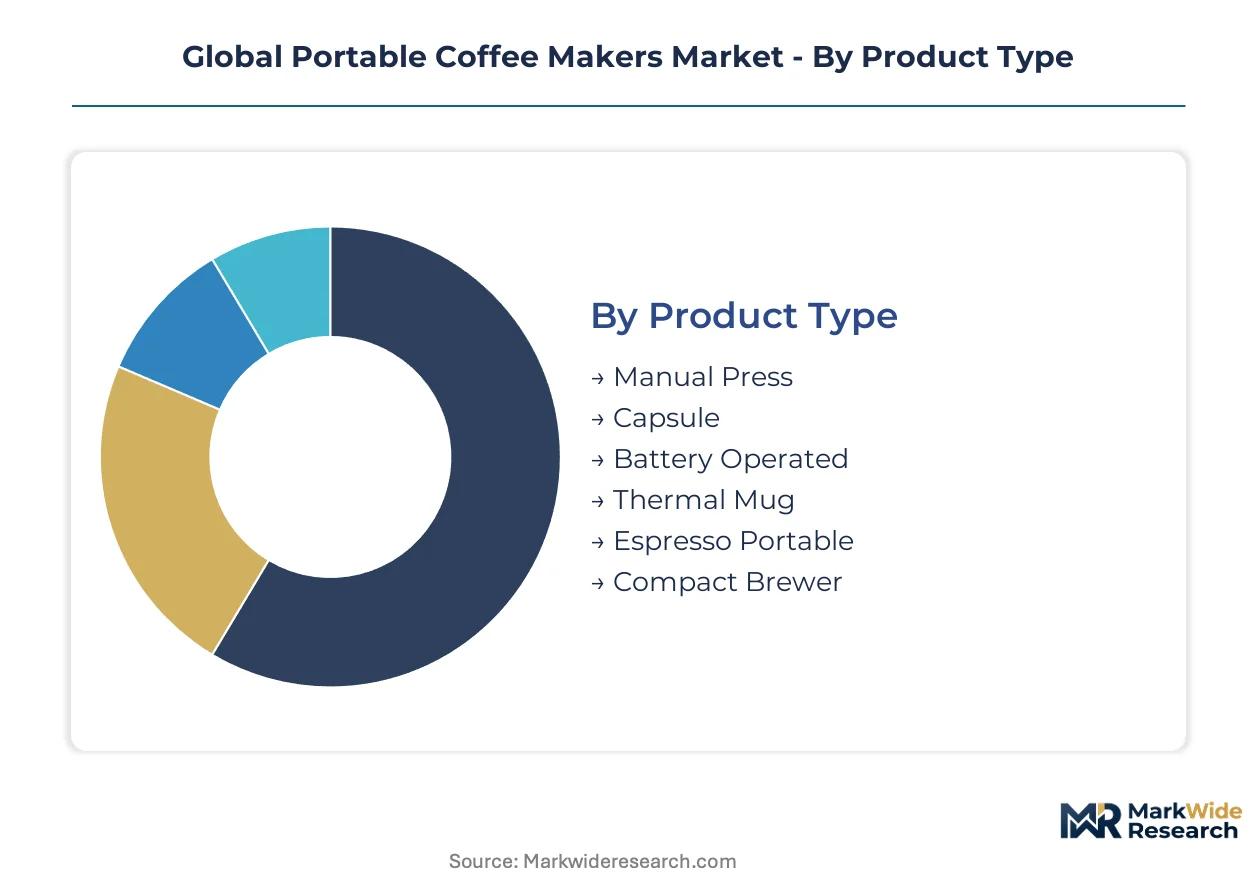
Portable coffee maker purchasing patterns diverge sharply between convenience-seeking commuters and experience-oriented outdoor enthusiasts. Segmentation reveals how pressure system design, power dependency, and brewing ritual preferences partition the addressable market into distinct competitive arenas with varying margin profiles.
Product Type:
Manual press and battery-operated units face divergent substitution pressures from complementary beverage systems and fixed-location alternatives.
- Battery Operated:Lithium-ion powered units integrate heating elements and electric pumps achieving 8-15 bar extraction pressure without external power infrastructure. Mobile workers in the United States and Germany sustain premium adoption for one-touch espresso during transit, though IATA shipping restrictions elevate fulfillment costs to remote destinations.
- Manual Press:Kinetic energy systems leverage mechanical leverage and pre-heated water reservoirs to generate brewing pressure through human force alone. Alpine enthusiasts across Japan and Germany prioritize these units for zero-dependency backcountry use where battery weight and charging logistics impose unacceptable constraints.
- Capsule:Proprietary pod-compatible formats lock users into recurring consumable purchases through standardized extraction chambers.
- Thermal Mug:Insulated vessels with integrated brewing mechanisms prioritize temperature retention over pressure extraction.
- Espresso Portable:Specialized high-pressure variants targeting crema-quality output in sub-kilogram form factors.
- Compact Brewer:Reduced-footprint alternatives emphasizing packability for air travel and ultralight packing.
Battery operated models anchor the volume base while manual press variants gain share at the steepest rate.
Technology:
Cost tier stratification separates premium pressure-based systems from accessible immersion methods with minimal component complexity.
- Single Serve:Pod-based or pre-portioned brewing systems optimize convenience through standardized dose and extraction parameters. Commuter corridors in Tokyo and Osaka concentrate demand for sub-60-second preparation cycles that eliminate measurement variability during rushed morning departures.
- Pour Over:Gravity-fed manual brewing through paper or metal filters rewards technique refinement with clarity of flavor extraction. Specialty coffee enthusiasts in Germany and the United States reject proprietary pod ecosystems, sustaining durable share for open-format alternatives that permit bean selection flexibility.
- Cold Brew:Extended steeping at ambient temperatures produces low-acidity concentrate requiring no heating element.
- French Press:Immersion brewing through metal mesh filtration retains oils and sediment for fuller body.
- Vacuum Brewing:Siphon-based methods using vapor pressure and vacuum draw for theatrical preparation.
- Instant Coffee:Soluble powder or crystallized formats prioritizing weight minimization above extraction quality.
Single serve technology commands the broadest installed base while pour over methods expand most quickly among purist segments.
Application:
Customer type concentration varies dramatically between transient use cases and semi-permanent installation contexts.
- Outdoor Recreation:Backcountry and trail-adjacent brewing demands prioritize weight minimization, mechanical reliability, and independence from electrical grids. Camping participation rates across Japan and Germany directly correlate with manual press unit sales through specialty outdoor retail channels.
- Commuting:Daily transit-oriented use requires rapid preparation, spill containment, and compatibility with vehicle cup holders or bag compartments. Dense commuter rail networks in Germany sustain demand for battery-operated units that function without access to workplace kitchen facilities.
- Office Use:Workplace desktop brewing substitutes for shared coffee station access or addresses preference divergence from bulk brew offerings.
- Travel:Air travel and hotel accommodation use cases emphasize TSA compliance and adaptability to variable international voltage standards.
- Camping:Vehicle-supported outdoor stays with greater weight tolerance than backpacking applications.
- Study Areas:Library and co-working space use requiring minimal noise and odor dispersion.
Commuting applications generate the highest transaction frequency while outdoor recreation drives the steepest premium pricing acceptance.
End User:
Margin structure diverges between price-sensitive volume purchasers and enthusiasts tolerating substantial premiums for performance differentiation.
- Mobile Workers:Consultants, field technicians, and traveling professionals requiring consistent quality coffee across variable accommodation quality. This segment in the United States demonstrates highest willingness-to-pay for battery-operated espresso units that replicate café extraction without location dependency.
- Coffee Enthusiasts:Hobbyist brewers prioritizing origin transparency, extraction control, and ritual participation over convenience optimization. German enthusiasts sustain specialty retailer relationships and direct-to-consumer brand engagement that bypasses mass-market distribution economics.
- Individual Consumers:Generalist purchasers with undifferentiated quality requirements and high price elasticity.
- Boutique Cafes:Small-format food service operations seeking catering or pop-up brewing capabilities.
- Event Organizers:Temporary gathering coordinators requiring scalable beverage service without fixed infrastructure.
- Students:Budget-constrained dormitory and shared housing residents prioritizing acquisition cost above durability or performance specifications.
Individual consumers provide the volume foundation while coffee enthusiasts deliver the highest per-unit profitability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation phase-down schedules and Japan's PSE certification requirements are reorganizing competitive entry patterns across major demand centers. National regulatory differentiation now shapes where battery-operated and manual press variants achieve channel access.
United States
Dense commuter rail networks and mobile worker populations sustain premium adoption of lithium-ion powered espresso units. FDA food-contact material standards govern plastic and stainless steel components in domestic-bound production. Greater Boston and Pacific Northwest clusters concentrate specialty outdoor retail distribution for ultralight manual press systems.
Germany
REACH chemical restrictions on bisphenol derivatives and phthalates are forcing resin reformulation across Asian supply bases serving EU-bound products. F-Gas Regulation compliance is accelerating hydrocarbon-based thermal system adoption in battery-operated models. Bavaria's precision manufacturing corridor anchors component supplier relationships for pressure system engineering.
Japan
Alpine outdoor participation rates and dense urban transit culture create overlapping demand for both zero-dependency manual presses and one-touch battery units. METI-administered PSE certification imposes additional compliance burdens on battery-integrated models entering Tokyo and Osaka commuter corridors. Kanto region specialty retailers sustain direct-to-consumer brand engagement bypassing mass-market economics.
China
Domestic supply base concentration for BPA-free polymer components and lithium-ion cell integration supports cost-competitive manufacturing for export markets. Dual carbon goals and evolving national standards are reshaping thermal system supplier portfolios. Yangtze River Delta industrial clusters dominate mold fabrication and pressure system component output for European and North American-bound finished goods.
South Korea
Seoul Capital Area commuter density and specialty coffee culture expansion sustain niche demand for premium portable brewing formats. MFDS food-contact regulations align with export-market compliance requirements for regional manufacturers. Busan-Ulsan logistics corridors facilitate air freight distribution subject to IATA lithium-ion transport restrictions.
Global Portable Coffee Makers Market Competitive Landscape
Player mix skews toward diversified appliance conglomerates with portable coffee maker as a portfolio extension, supplemented by specialist outdoor equipment fabricators and emerging direct-to-consumer brands. The structure exhibits moderate consolidation around established kitchen appliance names with fragmented长尾 competition from camping-specialist entrants. Two strategic archetypes dominate: capsule ecosystem incumbents leveraging consumable attachment, and pressure-system specialists commanding premium positioning through mechanical engineering differentiation. Competitive moves concentrate on CE marking channel access for European entry and PSE certification arbitrage for Japanese market penetration.
Within the diversified conglomerate tier, Nestlé S.A. and De'Longhi S.p.A. exemplify players sustaining capsule system compatibility across multiple portable formats. Among specialist fabricators, Wacaco Company Limited occupies a position representing manual press engineering focus for ultralight outdoor segments. Breville Group Limited anchors premium battery-operated positioning through controlled retail distribution architecture. Keurig Dr Pepper Inc represents the pod-ecosystem incumbent archetype with cross-format brewing system integration. These named entities collectively illustrate how geographic origin and corporate structure map to divergent strategic positioning within the competitive terrain.
| Leading Market Players |
|---|
| Keurig Dr Pepper Inc |
| Nestlé S.A. |
| De'Longhi S.p.A. |
| Hamilton Beach Brands Holding Company |
| Newell Brands |
| Electrolux AB |
| Koninklijke Philips N.V. |
| Breville Group Limited |
| Wacaco Company Limited |
| Others |
Supply & Pricing Matrix
Capacity utilization at Yangtze River Delta molding clusters shapes both resin input pricing floors and the concentration of BPA-free polymer supply serving EU-bound manufacturers. Scale advantages at these facilities compress unit economics for manual press components while REACH compliance costs elevate price thresholds for battery-integrated models entering European channels.
Pricing Analysis
Certification level creates the primary spread between premium CE-marked battery units and economy-tier manual alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects FDA food-contact grade, PSE electrical compliance, and after-sales service bundling. Cost compression in standard-tier battery models is intensifying because lithium-ion cell sourcing competition from electric vehicle supply chains constrains availability. Individual consumers demonstrate highest price sensitivity, while mobile workers in the United States tolerate substantial premiums for one-touch espresso extraction reliability.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes elevate inbound logistics costs for pressure system components manufactured in China. Component sourcing draws from China for lithium-ion cells and mold fabrication, Germany for precision pressure valves, and Japan for thermal insulation materials. Single-source vulnerability concentrates in rare-earth magnet supply for electric pump motors. Distribution runs through direct-to-consumer brand storefronts and specialty outdoor retail channels, bypassing traditional appliance mass-market gatekeepers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable coffee maker economics increasingly hinge on recurring consumable attachment and subscription-based capsule replenishment, with service-layer revenue expanding faster than hardware transaction value. After-sales calibration services and thermal system maintenance contracts represent underexploited margin pools for vendors with installed base scale.
For Market Incumbents: Shield market position by deepening backward integration into BPA-free resin compounding to offset REACH-driven input volatility. Nestlé S.A.-style capsule ecosystem lock-in remains defensible against open-format pour-over alternatives only through continuous pod format innovation. Capacity addition in Yangtze River Delta clusters secures cost position for manual press volume leaders.
For New Entrants and Emerging Players: CE marking fast-track programs create channel entry windows for battery-operated models targeting underserved commuter corridors in Germany. PSE certification arbitrage in Japan's Kanto region offers the most penetrable geography for premium positioning. Direct-to-consumer launch with specialty coffee enthusiast community engagement bypasses retail gatekeeper economics.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among capsule-ecosystem incumbents with proprietary pod attachment. Long-term viability over the next decade favors pressure-system engineering specialists with thermal management IP. Watch for solid-state battery chemistry maturation as inflection signal for heating-integrated model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Channel Access | REACH and F-Gas compliance unlocks European retail distribution for certified battery-operated entrants. |
| Backward Integration into Resin Compounding | Captive BPA-free polymer supply hedges REACH reformulation cost volatility for Asian manufacturers. |
| PSE Certification Arbitrage | METI electrical compliance captures premium commuter segments in Tokyo and Osaka corridors. |
| Direct-to-Consumer Migration | Brand-owned storefronts fragment traditional retail gatekeeper control over discovery and purchase. |
| Solid-State Battery Integration | Thermal management decomposition enables sub-500 gram heating-integrated espresso units for alpine use. |
Research Methodology
A standing panel of product development leads at portable appliance manufacturers, specialty outdoor retail buyers, lithium-ion cell procurement managers, and pressure system component engineers provided ongoing calibration against secondary validation. Primary interviews combined with customs trade data, FDA food-contact material filings, ECHA REACH substance registrations, and IATA lithium transport guidance documents enabled bottom-up and top-down triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, power dependency, brewing technology, end-user archetype, and regional regulatory cluster dimensions. CAGRs derived from historical trajectory analysis and elasticity-adjusted demand projections incorporated camping participation rates, commuter rail network density, and certification timeline lags as industry-specific inputs.
Decision-makers should treat outputs as directional under assumptions of stable REACH enforcement intensity and continued IATA lithium-ion transport restrictions; material deviation would warrant model refresh. Forecasts reflect base-case regulatory and technology adoption assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Europe Coffee Pods and Capsules Market
Coffee
Ground Coffee Market
Coffee
Coffee Cherry Market
Coffee
Coffee Premixes Market
Coffee
South America Coffee Market
Coffee
Organic Coffee Market
Coffee
Brazil Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Bottle Market
Coffee
Europe Coffee Market
Coffee
Africa Ready-To-Drink (RTD) Coffee Market
Coffee
Decaf Coffee Market
Coffee
GCC Instant Coffee Market
Coffee
Asia-Pacific Ready to Drink (RTD) Coffee Market
Coffee
UK Coffee Roaster Market
Coffee
Coffee Decoction Maker Market
Coffee
Cafix Market